
 Global Pelvic Floor Diagnostic Testing Market | 2026-2036
Global Pelvic Floor Diagnostic Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pelvic Floor Diagnostic Testing Market Intelligence
The shift from hospital-centric procurement to specialized urology and gynecology centers is reshaping distribution strategies. Laborie Medical Technologies leverages its extensive portfolio in urodynamics to capture share in these specialized settings. Medtronic plc competes through its established network in electrophysiology and neuromodulation. CooperSurgical differentiates with its focus on women's health diagnostics, targeting gynecology centers.
Pelvic floor diagnostic testing involves the objective, quantitative measurement of pelvic floor muscle function, tone, and coordination. These procedures often utilize manometry systems to quantify intra-abdominal pressure changes or electromyography to record muscle electrical activity during contraction and rest. Manometry systems and electromyography devices constitute the core product segments, driven by their established clinical utility. Urinary incontinence evaluation represents the largest application, while postpartum dysfunction screening is a rapidly emerging area of focus.
Market access is governed by stringent medical device regulations from bodies like the US FDA, the European Union's MDR framework, and Japan's PMDA. These frameworks mandate rigorous clinical data for product approval, influencing design specifications and post-market surveillance requirements. Future success will depend on navigating varied national reimbursement policies and demonstrating clear clinical efficacy to both regulators and healthcare providers.
Market Dynamics
The convergence of stricter medical device regulations and a clinical shift toward specialized care centers is the central force shaping the pelvic floor diagnostic testing market. This dynamic elevates product quality standards while simultaneously fragmenting procurement away from large, centralized hospital systems toward focused urology and gynecology clinics.
Growth Catalysts
- Aging Demographics:An expanding geriatric population in countries like Germany and Japan increases the prevalence of conditions such as urinary incontinence, directly stimulating demand for objective diagnostic assessments.
- Reimbursement Frameworks:Favorable reimbursement policies for urodynamic and EMG procedures in developed healthcare systems, including parts of Western Europe, incentivize adoption by clinics by ensuring financial viability.
- Non-Invasive Technology Adoption:The clinical preference for non-invasive diagnostic modalities like surface electromyography over more invasive procedures is expanding the addressable patient population by lowering barriers to testing.
Market Restraints
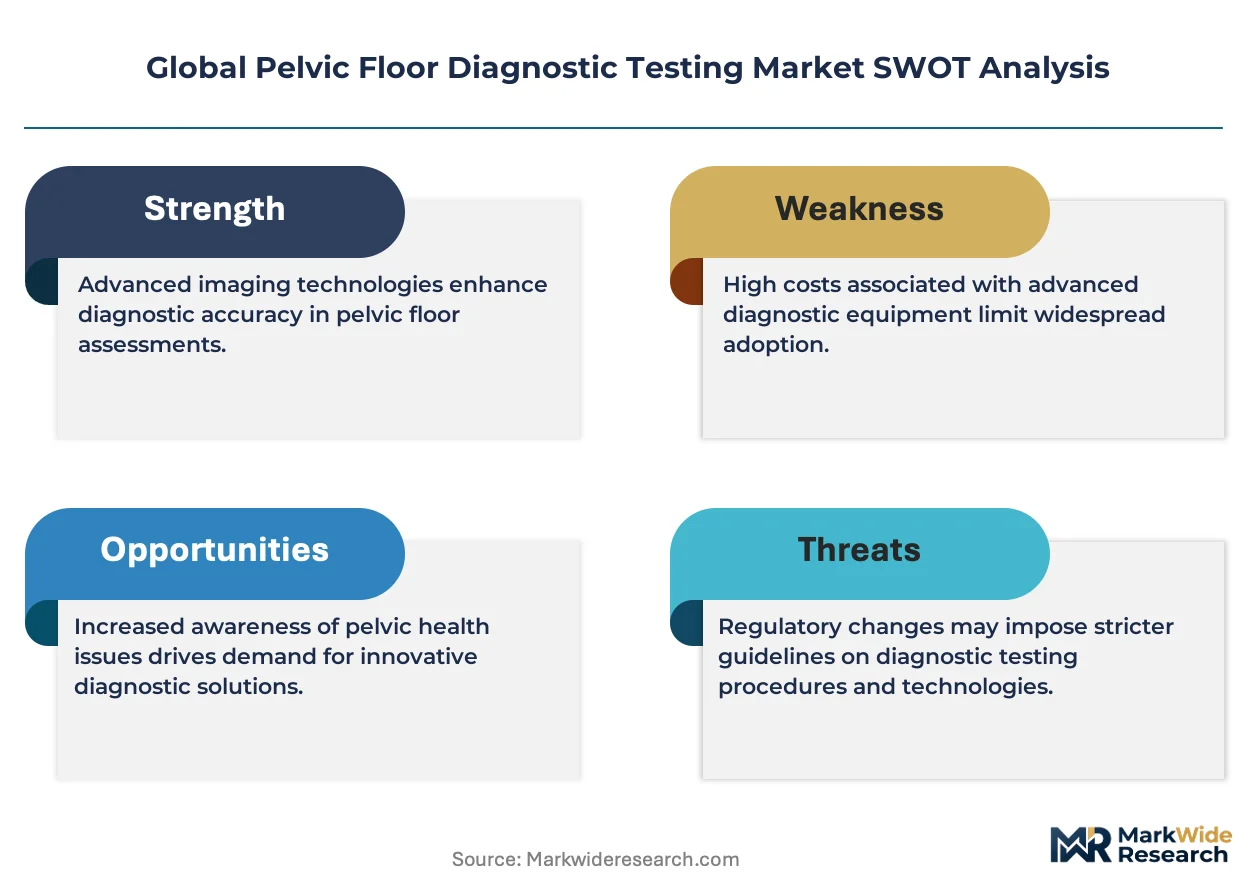
- High Capital Outlay:The significant upfront investment required for advanced manometry and electromyography systems creates a substantial barrier to entry for smaller clinics and practices, limiting market penetration.
- Specialized Skill Scarcity:A shortage of clinicians with specialized training in performing and interpreting complex urodynamic studies acts as a bottleneck, constraining the capacity for testing in many regions.
- Stringent Regulatory Hurdles:Navigating the complex and lengthy device approval processes mandated by bodies like the US FDA and the EU's MDR framework delays product launches and increases development costs.
Strategic Opportunities
- Postpartum Dysfunction Screening:Developing targeted diagnostic protocols for postpartum pelvic floor dysfunction represents a significant growth vector, addressing a large and currently underserved patient group.
- Emerging Market Expansion:Penetrating healthcare markets in countries like Brazil and India, where awareness of pelvic health is growing, offers substantial long-term growth potential for device manufacturers.
- Software and AI Integration:Integrating diagnostic hardware with AI-powered analytical software to automate interpretation and improve diagnostic accuracy presents a key opportunity for product differentiation and value creation.
Industry Challenges
- Data Interoperability:Ensuring seamless integration of diagnostic device data with disparate Electronic Health Record (EHR) systems remains a persistent technical and operational challenge for providers and vendors.
- Inconsistent Reimbursement Policies:The wide variation in reimbursement codes and payment levels for diagnostic procedures across different national and private payers complicates market access and revenue cycle management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pelvic Floor Diagnostic Testing Market |
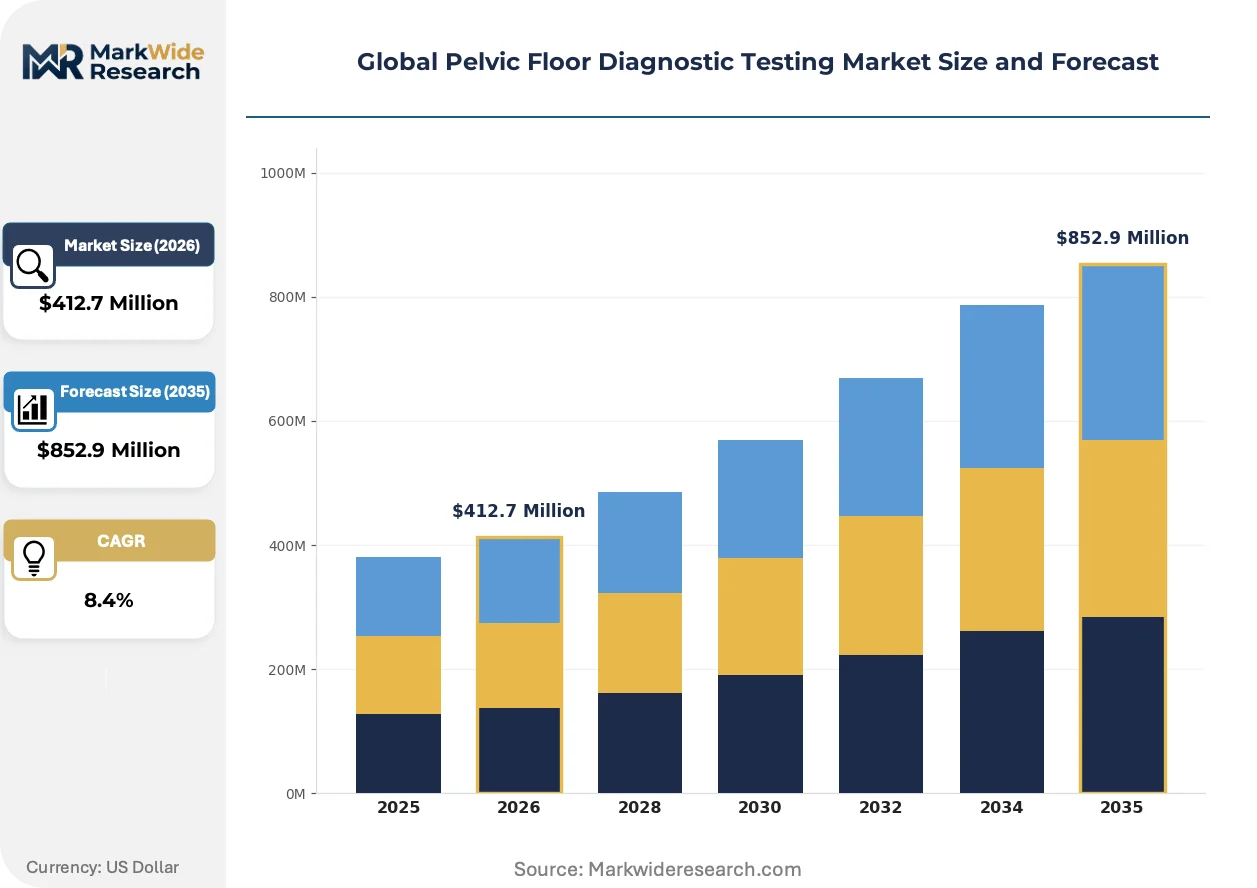
| Market Size in 2026 | $412.7 Million |
| Market Size in 2035 | $852.9 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manometry Systems, Electromyography Devices, Ultrasound Scanners, Imaging Technologies, Pressure Sensors Application: Urinary Incontinence Evaluation, Fecal Incontinence Assessment, Pelvic Organ Prolapse Analysis, Chronic Pelvic Pain Diagnosis, Postpartum Dysfunction Screening End User: Urology Clinics, Gynecology Centers, Diagnostic Laboratories, Physiotherapy Facilities, Specialized Hospitals Technology: Biofeedback, Electrophysiology, Imaging Techniques, Sensor-Based Monitoring, Digital Data Acquisition |
| Companies Covered | Verathon Inc., Diversatek, Laborie Medical Technologies, CooperSurgical, Olympus Corporation, Medtronic plc, Itronix Medical Ltd., Stryker, The Prometheus Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pelvic Floor Diagnostic Testing Market Strategic Shifts & Innovations
A fundamental shift towards quantitative, objective measurement is redefining clinical workflows in pelvic floor diagnostics. This evolution prioritizes data-rich, less invasive technologies and patient-specific care pathways over generalized assessments, influencing both product design and clinical practice.
High-resolution manometry systems provide detailed spatiotemporal plots of pressure within the pelvic region, offering greater diagnostic clarity than conventional methods. Specialized urology and gynecology centers are rapidly adopting this technology to enhance diagnostic precision for complex cases. The diagnostic approach is migrating from simple pressure readings to dynamic, multi-dimensional functional mapping of the pelvic floor.
Japan's PMDA is enforcing more rigorous post-market surveillance requirements for medical devices, including those used in pelvic floor diagnostics. This mandate compels manufacturers to collect and analyze real-world performance data throughout a product's lifecycle, increasing long-term operational costs. The urodynamics segment is most affected, prompting vendors to invest in more robust data tracking and reporting systems.
Purchasing decisions are decentralizing from large hospital capital budget committees to individual clinical directors at specialized urology and gynecology centers. This shift disrupts traditional sales models that relied on hospital-wide contracts, favoring vendors with direct clinical outreach and application-specific expertise. The trend is most prominent in Germany and the United States, where the growth of private specialized clinics is most advanced.
Global Pelvic Floor Diagnostic Testing Market Segmentation
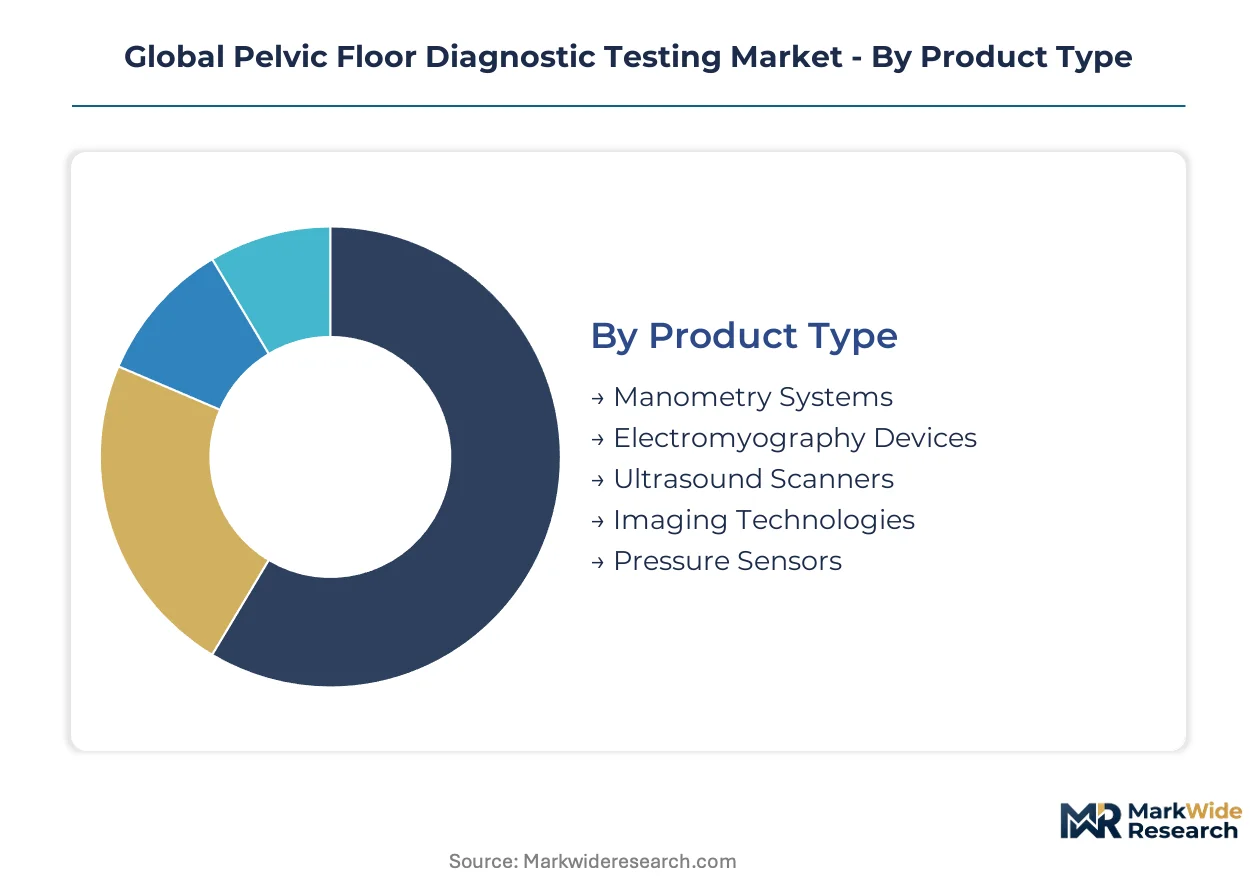
The Global Pelvic Floor Diagnostic Testing Market is precisely segmented to reflect the diverse product offerings, clinical applications, end-user profiles, and underlying technological frameworks. This granular analysis provides a clear understanding of where value is created and how demand patterns are evolving across the diagnostic landscape.
Product Type:
The functional characteristics of diagnostic tools define the Product Type segmentation, grouping devices by their primary operational mechanism.
- Manometry Systems:These devices objectively measure intra-abdominal and pelvic pressure changes, providing quantitative data on muscle function and coordination. Demand concentrates in specialized urology clinics, driven by the need for precise assessment of conditions like urinary incontinence.
- Electromyography Devices:Electromyography systems record the electrical activity of pelvic floor muscles, offering insights into muscle tone, strength, and neurological integrity. Gynecology centers widely adopt these devices for postpartum dysfunction screening due to their non-invasive nature.
- Ultrasound Scanners:These imaging tools provide real-time visualization of pelvic floor anatomy and muscle movement. Clinicians use ultrasound scanners for initial assessments and biofeedback training.
- Imaging Technologies:This segment includes advanced techniques like MRI and CT scans that offer detailed structural views of the pelvic region. Specialized hospitals utilize these for complex diagnostic cases.
- Pressure Sensors:These compact devices measure localized pressure within the pelvic area, often integrated into larger systems or used for biofeedback. Physiotherapy facilities employ pressure sensors for patient training.
Manometry Systems hold significant installed capacity. Electromyography Devices are rotating up the share rankings.
Application:
Patient conditions requiring assessment delineate the Application segments, highlighting the specific clinical needs addressed by diagnostic testing.
- Urinary Incontinence Evaluation:This application involves comprehensive testing to identify the type and severity of urinary leakage, guiding appropriate treatment strategies. Demand for these evaluations is highest in countries with aging demographics, such as Germany and Japan.
- Postpartum Dysfunction Screening:This emerging application focuses on early detection and assessment of pelvic floor weaknesses or injuries following childbirth. Specialized women's health centers are increasingly adopting screening protocols to improve long-term maternal health outcomes.
- Fecal Incontinence Assessment:Diagnostic tests in this category evaluate the integrity and function of the anal sphincter and pelvic floor muscles. Urology and gastroenterology clinics perform these assessments for diagnostic clarity.
- Pelvic Organ Prolapse Analysis:This application involves assessing the descent of pelvic organs due to weakened support structures. Gynecology centers utilize various diagnostic tools for accurate staging and management planning.
- Chronic Pelvic Pain Diagnosis:Diagnostic testing helps identify the underlying causes of persistent pelvic pain, which can involve muscular, neurological, or structural issues. Diagnostic laboratories support these complex investigations.
Urinary Incontinence Evaluation remains the largest application. Postpartum Dysfunction Screening shows the steepest expansion trajectory.
End User:
The primary healthcare settings utilizing pelvic floor diagnostics form the End User categories, reflecting the changing landscape of healthcare delivery.
- Urology Clinics:These specialized clinics focus on urinary tract conditions and male reproductive health, serving as a primary point of care for pelvic floor diagnostics. Procurement decisions are increasingly decentralized at these facilities.
- Gynecology Centers:Dedicated to women's health, these centers provide comprehensive diagnostic services for pelvic floor disorders, including postpartum care. CooperSurgical targets these centers with its diagnostic offerings.
- Diagnostic Laboratories:These facilities perform a range of tests, often supporting referrals from primary care or specialized clinics for complex analyses. Data interoperability with EHR systems remains a challenge for these labs.
- Physiotherapy Facilities:Physical therapists use diagnostic tools for assessment, biofeedback, and guiding rehabilitation exercises for pelvic floor dysfunction. Non-invasive technology adoption is high in these settings.
- Specialized Hospitals:Large hospital systems with dedicated departments for urology, gynecology, and rehabilitation utilize advanced diagnostic equipment. These hospitals often handle more complex or inpatient cases.
Specialized Urology Clinics drive significant procurement volume. Gynecology Centers are expanding their diagnostic capabilities.
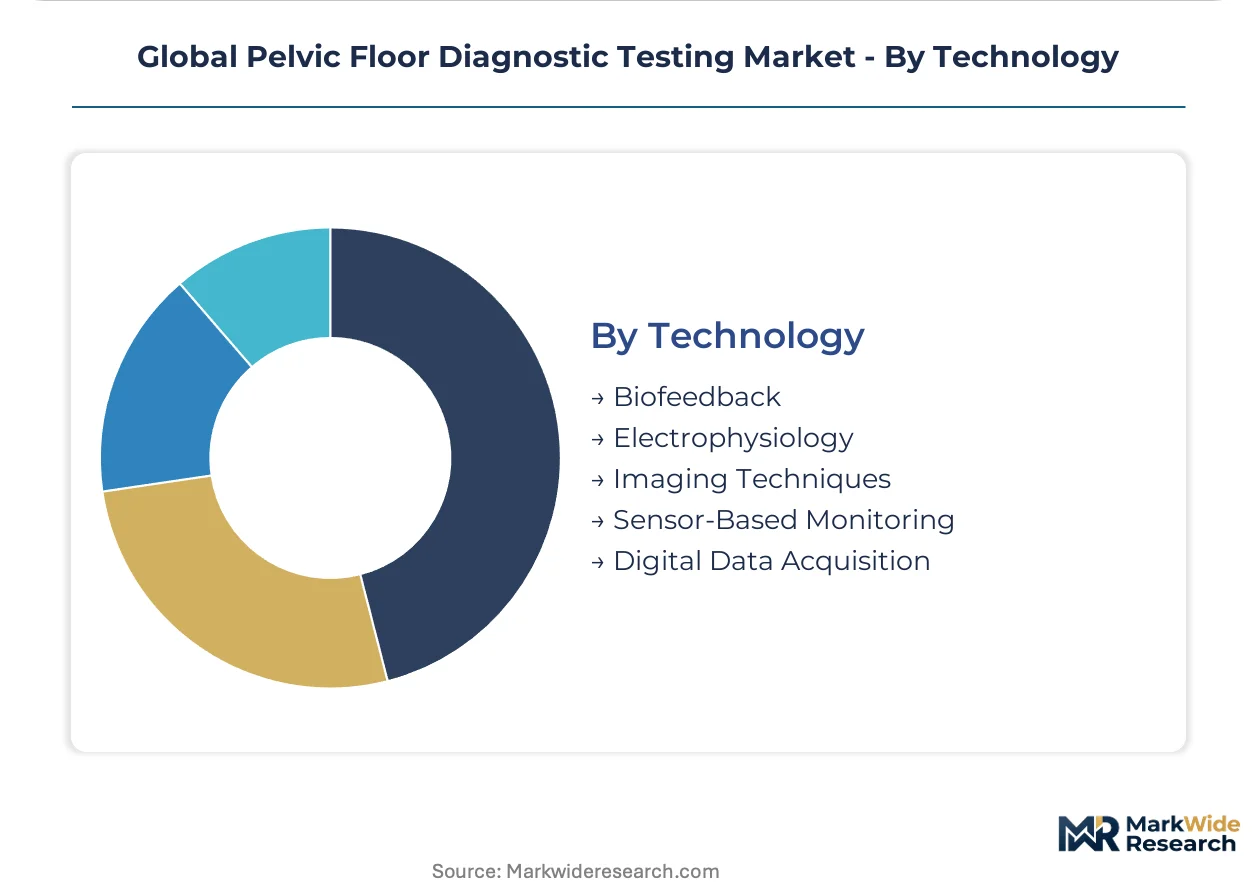
Technology:
Underlying scientific principles and mechanisms classify the Technology segments, showcasing the innovation driving diagnostic advancements.
- Biofeedback:This technology provides real-time feedback on physiological processes, enabling patients to learn to control pelvic floor muscle activity. Physiotherapy facilities widely employ biofeedback for rehabilitation.
- Electrophysiology:This segment encompasses methods like electromyography that measure electrical impulses in muscles and nerves, assessing their function. Medtronic plc competes through its established network in neuromodulation.
- Imaging Techniques:This category includes various modalities such as ultrasound, MRI, and CT that visualize pelvic anatomy and function. High-resolution manometry systems are enhancing diagnostic clarity.
- Sensor-Based Monitoring:This technology utilizes small, often wearable, sensors to collect data on pelvic floor activity and pressure over time. Non-invasive technology adoption expands the addressable patient population.
- Digital Data Acquisition:This involves the electronic capture, storage, and processing of diagnostic data from various devices. Software and AI integration presents a key opportunity for product differentiation.
Electrophysiology provides foundational diagnostic insights. Digital Data Acquisition capabilities are enhancing analytical depth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's favorable reimbursement policies create a distinct market access environment compared to Japan's rigorous post-market surveillance requirements. This disparity influences pricing power and investment strategies for pelvic floor diagnostic technologies. Manufacturers adapt product development to meet varied national regulatory and economic landscapes.
Germany
Germany's aging population and robust healthcare reimbursement system stimulate demand for objective diagnostic assessments. The EU's Medical Device Regulation (MDR) elevates product quality standards for devices sold within its borders. Specialized urology clinics in major urban centers like Munich are rapidly adopting high-resolution manometry systems.
Japan
Japan's expanding geriatric population directly increases the prevalence of conditions such as urinary incontinence, driving diagnostic demand. Japan's PMDA enforces more rigorous post-market surveillance requirements for medical devices. Tokyo-based medical device manufacturers invest in robust data tracking and reporting systems to comply with these mandates.
United States
The United States market benefits from the growth of private specialized clinics and a clinical preference for non-invasive diagnostic modalities. The US FDA mandates rigorous clinical data for product approval, influencing design specifications. Specialized gynecology centers across the Northeast Corridor prioritize adoption of advanced electromyography devices.
France
France's established healthcare infrastructure and increasing awareness of pelvic health contribute to demand for diagnostic testing. The European Union's MDR framework influences device design specifications and post-market surveillance requirements. Urology and gynecology centers in Paris are integrating software and AI with diagnostic hardware for enhanced accuracy.
Brazil
In Brazil, growing awareness of pelvic health and an expanding private healthcare sector offer significant long-term growth potential. Brazil's ANVISA oversees medical device approval processes, requiring local market authorization. São Paulo's emerging private clinic network presents a strategic opportunity for device manufacturers to expand their presence.
Global Pelvic Floor Diagnostic Testing Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying critical elements. The pelvic floor diagnostic market exhibits a tiered structure, with a few large diversified medical technology firms alongside numerous specialized diagnostic providers. Strategic archetypes include comprehensive solution providers offering broad portfolios, niche diagnostic innovators focusing on specific conditions, and imaging technology specialists. Firms pursue portfolio diversification to address varied clinical needs and geographic expansion into emerging markets.
Specialization in diagnostic systems defines many market participants. Laborie Medical Technologies exemplifies a comprehensive solution provider, leveraging its extensive portfolio in urodynamics to capture share in specialized urology clinics. Medtronic plc, with its established network, represents a diversified medical technology firm with capabilities spanning electrophysiology and neuromodulation. CooperSurgical anchors the women's health diagnostics segment, targeting gynecology centers with focused offerings. These companies collectively drive product differentiation through advanced technology integration and targeted distribution strategies, responding to evolving clinical needs and regulatory demands.
| Leading Market Players |
|---|
| Verathon Inc. |
| Diversatek |
| Laborie Medical Technologies |
| CooperSurgical |
| Olympus Corporation |
| Medtronic plc |
| Itronix Medical Ltd. |
| Stryker |
| The Prometheus Group |
| Others |
Cost & Logistics Intelligence
Regulatory chokepoints, such as the EU's Medical Device Regulation, significantly determine pricing tier spreads and shape the pelvic floor diagnostic testing supply chain. Strict approval processes elevate development costs, influencing market entry and product availability.
Pricing Analysis
Configured-to-order pricing for integrated diagnostic systems commands a premium over standard, off-the-shelf devices. The market operates on a hybrid model, combining per-unit transactional pricing for hardware with value-based pricing for integrated software and AI analytics. Price differentiation stems from customization levels for high-resolution manometry systems and bundled after-sales service. Pricing softness reflects the growing demand for cost-effective non-invasive technologies, particularly impacting smaller physiotherapy facilities. Specialized hospitals exhibit lower price sensitivity for advanced imaging systems.
Supply Chain Analysis
Extended payment terms often characterize component procurement for pelvic floor diagnostic device manufacturers, influencing cash flow for smaller suppliers. Supply for precision medical device components concentrates in Germany, the United States, and Japan. The industry draws from specialized microprocessors and high-resolution sensors as critical inputs. Single-source vulnerability for advanced sensor components poses a structural supply chain risk. Distribution runs through direct sales teams targeting specialized urology and gynecology centers, supplemented by regional value-added distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pelvic floor diagnostic market is at a platform-economics inflection, driven by the critical need for seamless Electronic Health Record (EHR) interoperability. This shift demands integrated solutions that connect diagnostic hardware with patient data systems.
For Market Incumbents:Entrench existing market positions by deepening vertical integration into AI-powered analytical software development. Invest heavily in generating robust clinical data to meet stringent regulatory hurdles like the EU's MDR framework, countering emerging AI-powered diagnostic startups. Expand training programs for specialized clinicians, reinforcing brand loyalty and addressing the specialized skill scarcity. Acquire niche technology firms specializing in data interoperability to secure platform dominance.
For New Entrants and Emerging Players:Geographic underpenetration in emerging markets like Brazil and India offers significant growth opportunities for new entrants. Target the rapidly expanding postpartum dysfunction screening application with non-invasive, user-friendly electromyography devices. Focus on physiotherapy facilities and smaller gynecology centers by offering solutions with lower capital outlay and integrated training modules. Develop AI-driven interpretation software to reduce reliance on specialized skill scarcity.
For Investors and Strategic Acquirers:This market sits at a growth phase that favors specialized diagnostic innovators with strong intellectual property in non-invasive technologies. Long-term viability remains strong, propelled by aging demographics and the increasing focus on women's health. Prioritize acquisition targets with proven software and AI integration capabilities that address data interoperability challenges. The signal to watch is the adoption rate of AI-powered analytical software in specialized urology and gynecology centers.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: AI-Integrated Diagnostic System | Enhances diagnostic accuracy and reduces interpretation burden for clinicians in specialized urology clinics. |
| Strategic Partnership: With EHR Vendors | Improves data interoperability, streamlining clinical workflows for diagnostic laboratories and specialized clinics. |
| CE Marking Pathway: For Advanced Manometry Systems | Ensures market access and regulatory compliance within the European Union, particularly Germany and France. |
| Geographic Expansion: Into Brazil and India | Captures growth potential in emerging markets with rising awareness of pelvic health and expanding private sectors. |
| Software Companion Development: For Existing Hardware | Differentiates product offerings and adds value by automating data analysis for gynecology centers and physiotherapy facilities. |
Research Approach
Cross-validation between primary interviews with clinicians and secondary validation from regulatory filings anchors the qualitative findings of this study. Primary insights derive from discussions with urologists, gynecologists, biomedical engineers, and hospital procurement managers. Secondary data sources include US FDA filings, EU MDR documentation, Japan PMDA reports, and medical journal databases. This approach employs both bottom-up and top-down triangulation.
The calibration approach integrates a quantitative modeling framework to project market dynamics across the analysis window. Segmentation dimensions include product type, application, end-user, technology, and regional regulatory frameworks. Compound annual growth rates are derived from historical growth trends and projected market dynamics. Key forecast inputs encompass aging population demographics and evolving healthcare reimbursement policies.
Practitioners should monitor new device approvals, shifts in reimbursement policies, and major technological breakthroughs for early signals of market change. Forecasts reflect assumptions documented at the time of publication. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Infectious Respiratory Disease Diagnostics Market
Diagnostics
Global Veterinary POC Diagnostic Market
Diagnostics
Glucose Biosensors Market
Diagnostics
Global Alzheimers Disease Diagnostic Market
Diagnostics
US in Vitro Diagnostics Market
Diagnostics
Hepatitis E Diagnostic Tests Market
Diagnostics
Semen Analysis Systems Market
Diagnostics
Global Meningitis Diagnostic Testing Market
Diagnostics
Global Blood Transfusion Diagnostics Market
Diagnostics
Blood Grouping Reagents Market
Diagnostics
Diagnostic Testing of Stds Market
Diagnostics
In Vitro Diagnostic Antibodies Market
Diagnostics
Global Antinuclear Antibody Test Market
Diagnostics
Rapid Influenza Diagnostic Tests (RIDT) Market
Diagnostics
North America Molecular Diagnostics Market
Diagnostics
Mexico in-Vitro Diagnostics Market