
 Semen Analysis Systems Market | 2026-2036
Semen Analysis Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Semen Analysis Systems Market Analytics
The gap between premium automated semen analyzers and commodity manual microscopy is expanding across fertility service networks. Hamilton Thorne leverages proprietary CASA algorithms to dominate high-throughput laboratory segments in North America. Medical Electronic Systems anchors its position through integrated sperm processing units that streamline clinic workflows. CooperSurgical competes on brand strength across European hospital procurement channels.
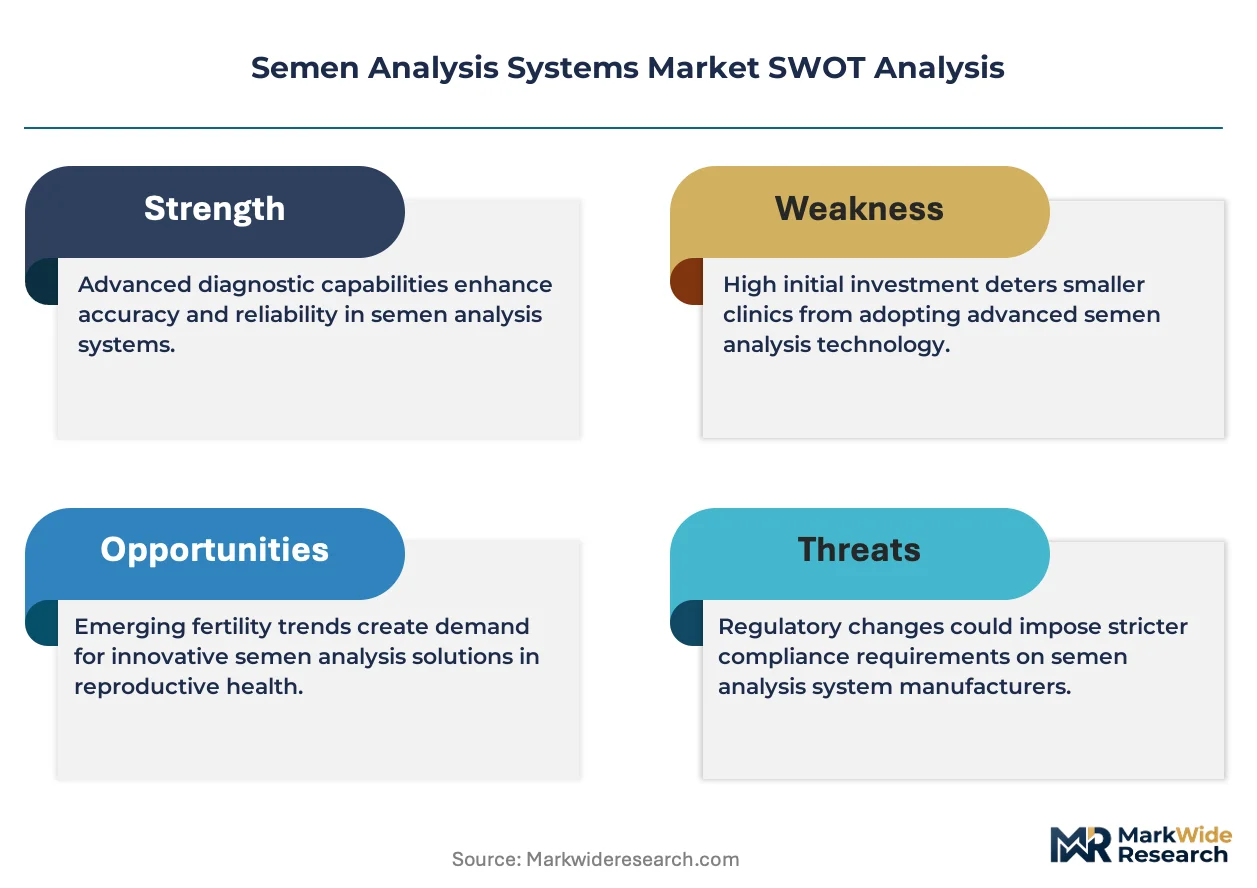
Semen analysis systems comprise hardware and software platforms that evaluate sperm concentration, motility, morphology, and DNA fragmentation using computer-assisted semen analysis or direct visual microscopy, typically operating at 37°C with phase-contrast optics to preserve sample viability for clinical fertility assessment. Automated analysis systems now lead product type demand as laboratories prioritize throughput and reproducibility over manual methods. Image analysis technology captures the fastest growth trajectory within the technology dimension, driven by machine-learning classification of sperm morphology. Fertility evaluation applications concentrate margin pools where clinics require diagnostic-grade reporting for treatment decisions.
FDA 510(k) clearance pathways shape product entry timelines for US manufacturers, while EU MDR technical documentation requirements extend certification cycles for European market access. WHO laboratory manual standards for human semen examination establish baseline performance expectations that regulators in India and China reference for domestic device registration. Stakeholders must weigh regulatory capital requirements against the shift toward software-integrated platforms that blur traditional hardware boundaries.
Market Dynamics
Automated computer-assisted semen analysis (CASA) is compressing the installed base of manual microscopy systems as fertility clinics face reimbursement pressure to demonstrate diagnostic reproducibility. This technology shift is redistributing margin pools from consumables toward software licensing and service contracts.
Growth Catalysts
- EU MDR compliance timelines:German fertility clinics must replace legacy manual systems with validated automated analyzers by certification deadlines, accelerating replacement cycles in Europe's largest diagnostic market.
- WHO laboratory manual standards:India's CDSCO references WHO semen examination protocols for domestic device registration, creating regulatory harmonization that smooths import pathways for CASA manufacturers.
- Hospital laboratory consolidation:United States health system mergers are centralizing andrology services into high-throughput reference labs that demand automated platforms over manual methods.
Market Restraints
- Optical component supply concentration:Phase-contrast microscope objectives rely on German and Japanese precision optics suppliers, exposing manufacturers to lead time volatility and single-source risk.
- FDA 510(k) pathway friction:Substantial equivalence determinations for novel morphology algorithms extend review timelines, delaying product launches and compressing effective patent life.
- Manual microscopy substitution persistence:Low-cost conventional microscopes remain adequate for basic fertility screening in resource-limited settings, capping price elasticity in emerging markets.
Strategic Opportunities
- At-home collection kits with telemedicine integration:Post-collection video analysis apps paired with mail-in semen assessment services are opening direct-to-consumer channels outside traditional clinic procurement.
- DNA fragmentation testing convergence:Sperm chromatin structure assay (SCSA) integration with standard CASA workflows creates premium tier positioning for integrated fertility workup platforms.
- China's NMPA fast-track pathway:Innovative device designation for AI-assisted morphology classification accelerates market entry for foreign manufacturers in the world's largest fertility treatment market.
Industry Challenges
- Embryologist-to-technologist skill translation:Automated systems reduce manual scoring expertise requirements but create demand for IT-integrated laboratory information system (LIS) specialists that training pipelines have not addressed.
- Legacy LIS integration complexity:Proprietary data formats from incumbent CASA vendors fragment connectivity, forcing clinics into expensive middleware development or single-vendor lock-in.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semen Analysis Systems Market |
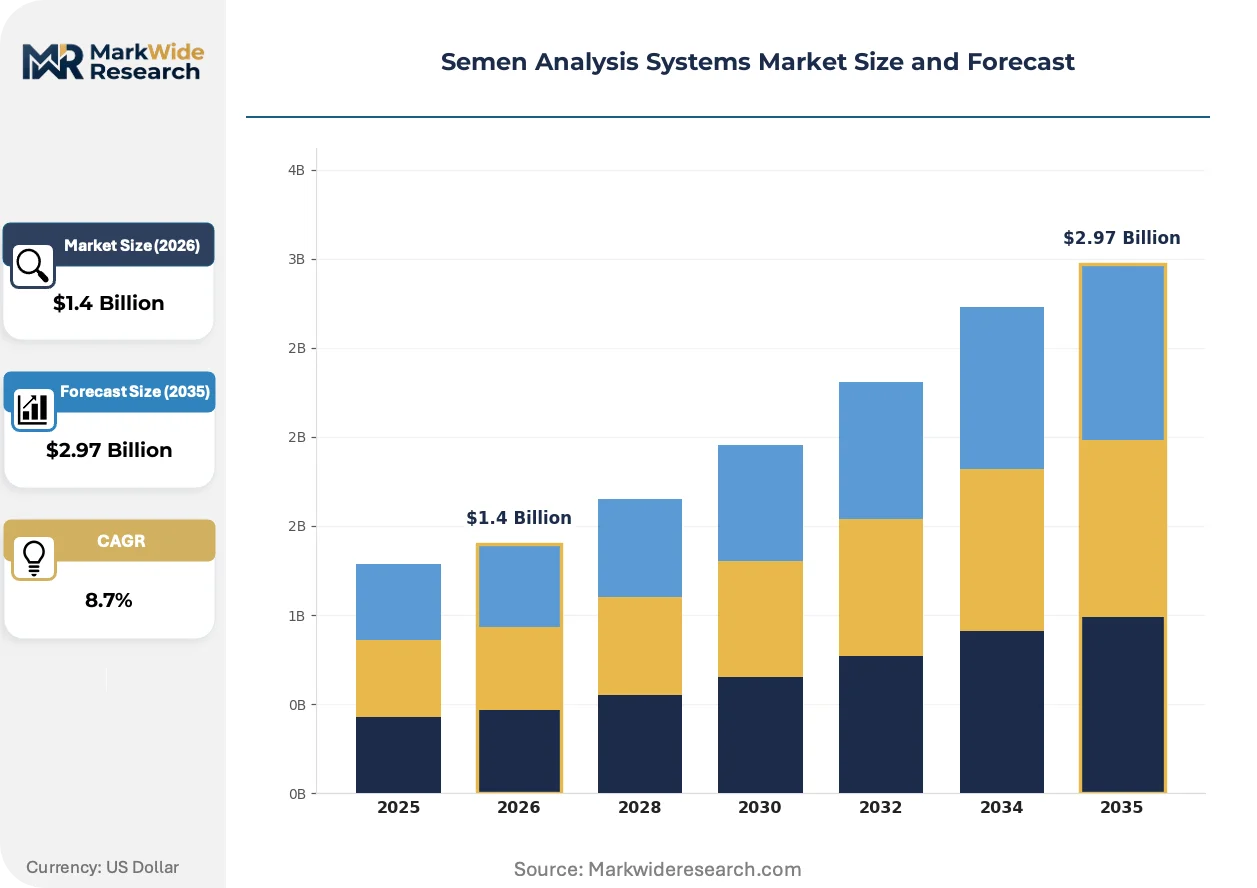
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Semen Analyzer, Software Solutions, Microscopes, Sperm Processing Units End User: Clinics, Hospitals, Laboratories, Research Institutions Technology: Manual Analysis, Automated Analysis, Image Analysis, Software Analytics Application: Fertility Evaluation, Semen Quality Assessment, Research Studies, Health Screening |
| Companies Covered | Hamilton Thorne, Medical Electronic Systems, Bioline Technologies, Microptic, Sperm Processor, LabIVF Asia, Vitrolife, CooperSurgical, Proiser, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semen Analysis Systems Market Evolving Landscape
Machine-learning classification of sperm morphology is compressing the gap between automated and expert human assessment accuracy. This capability leap is restructuring competitive advantage around algorithm training data scale rather than optical hardware refinement alone.
Deep convolutional neural networks trained on annotated morphology datasets are overtaking rule-based image analysis in high-volume fertility networks. Large hospital chains in the United States are deploying these systems to standardize reporting across geographically dispersed laboratory sites. The technology is overtaking the traditional competitive moat of experienced embryologist staffing levels.
EU MDR technical documentation requirements for in-vitro diagnostic device classification are extending certification cycles for European market access. Manufacturers must now compile clinical performance studies and post-market surveillance protocols that the previous directive did not mandate. Small and mid-sized CASA vendors are responding by partnering with notified bodies early and prioritizing their highest-revenue member states for initial submissions.
Subscription-based software licensing is displacing perpetual license sales in North American fertility clinic procurement. Hospital procurement departments favor operational expenditure models that align diagnostic platform costs with patient volume fluctuations. This shift is most visible in United States metropolitan markets where private equity-backed fertility roll-ups standardize technology stacks across acquired practices.
Semen Analysis Systems Market Segmentation
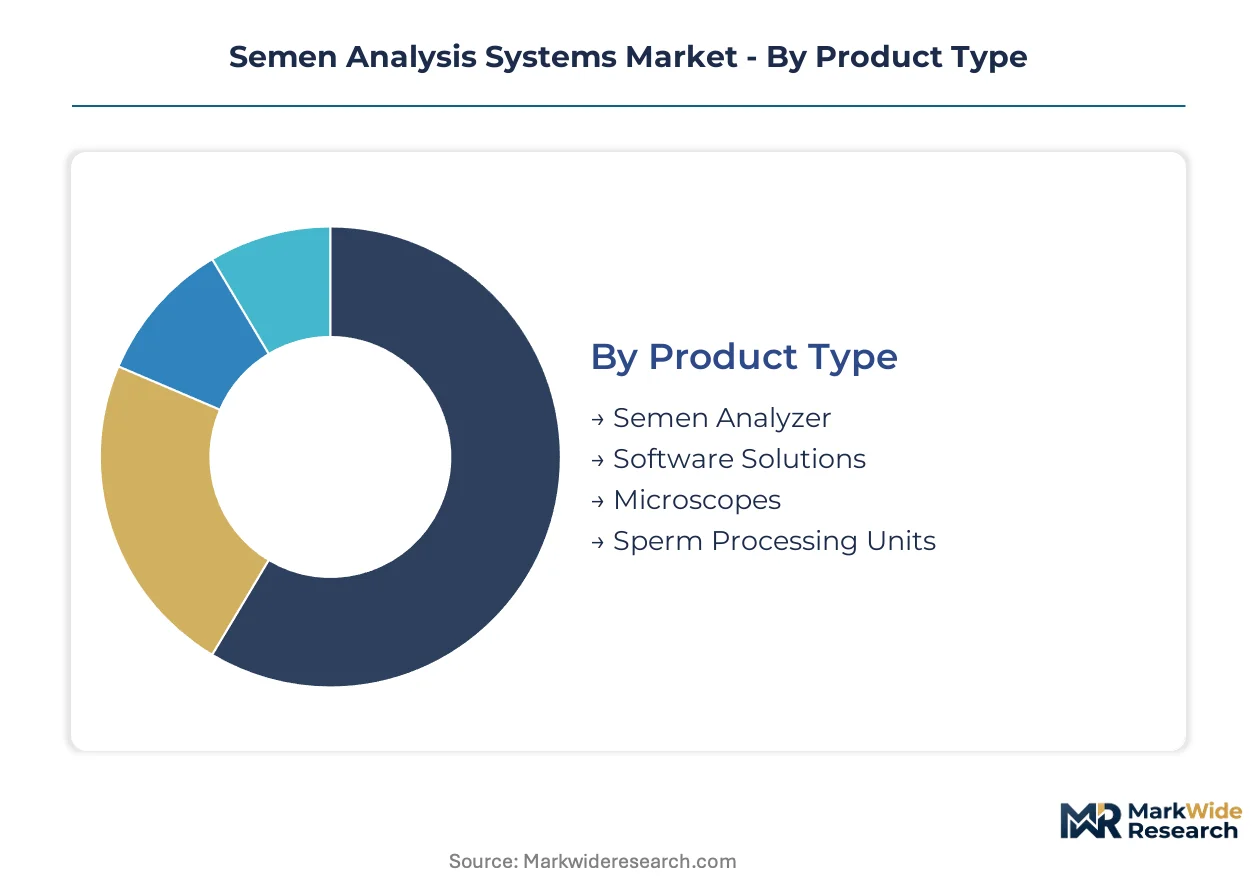
Procurement patterns in semen analysis systems diverge sharply between high-throughput fertility networks seeking automation and resource-constrained settings prioritizing capital efficiency. Understanding these segment boundaries reveals where margin pools concentrate and which technology transitions command pricing power.
Product Type:
Capital allocation decisions separate clinics investing in integrated platforms from those assembling modular component systems.
- Semen Analyzer:Hardware platforms integrate phase-contrast optics, heated stages, and digital imaging sensors to capture sperm concentration and motility metrics at 37°C. Demand clusters in United States hospital laboratories consolidating andrology services into centralized reference facilities.
- Software Solutions:CASA algorithms process video sequences to classify sperm trajectories and morphology classifications, typically licensed through subscription models that align costs with patient volume fluctuations. Fertility clinic roll-ups in metropolitan markets favor operational expenditure structures over perpetual licenses.
- Microscopes:Manual phase-contrast systems serve basic screening functions where automated platforms remain cost-prohibitive.
- Sperm Processing Units:Integrated centrifugation and gradient preparation modules streamline clinic workflows.
Semen analyzers lead on scale; software solutions lead on momentum.
End User:
Reimbursement structures and regulatory compliance timelines reshape purchasing authority across care settings.
- Clinics:Fertility specialty practices face EU MDR compliance deadlines in Germany and other member states, accelerating replacement of legacy manual systems with validated automated analyzers. Private equity-backed clinic networks standardize technology stacks across acquired practices to reduce training overhead.
- Hospitals:Health system mergers in the United States centralize andrology into high-throughput laboratories that demand automated platforms with LIS connectivity.
- Laboratories:Independent diagnostic chains in India adopt CASA technology to displace manual microscopy as CDSCO registration pathways harmonize with WHO standards.
- Research Institutions:Academic centers drive algorithm development for morphology classification using annotated training datasets.
Hospitals lead on scale; clinics lead on momentum.
Technology:
Performance validation requirements and workforce skill availability determine technology selection thresholds.
- Automated Analysis:CASA platforms deliver reproducible concentration and motility measurements that satisfy diagnostic-grade reporting requirements for treatment decisions. Laboratories prioritize these systems where reimbursement pressure demands demonstrated analytical precision.
- Image Analysis:Deep convolutional neural networks trained on morphology datasets compress the accuracy gap between automated and expert human assessment. Large hospital chains deploy these systems to standardize reporting across geographically dispersed sites.
- Manual Analysis:Conventional microscopy persists in resource-limited settings where capital constraints outweigh throughput requirements.
- Software Analytics:Cloud-based platforms enable remote morphology review and telemedicine-integrated semen assessment services.
Automated analysis leads on scale; image analysis leads on momentum.
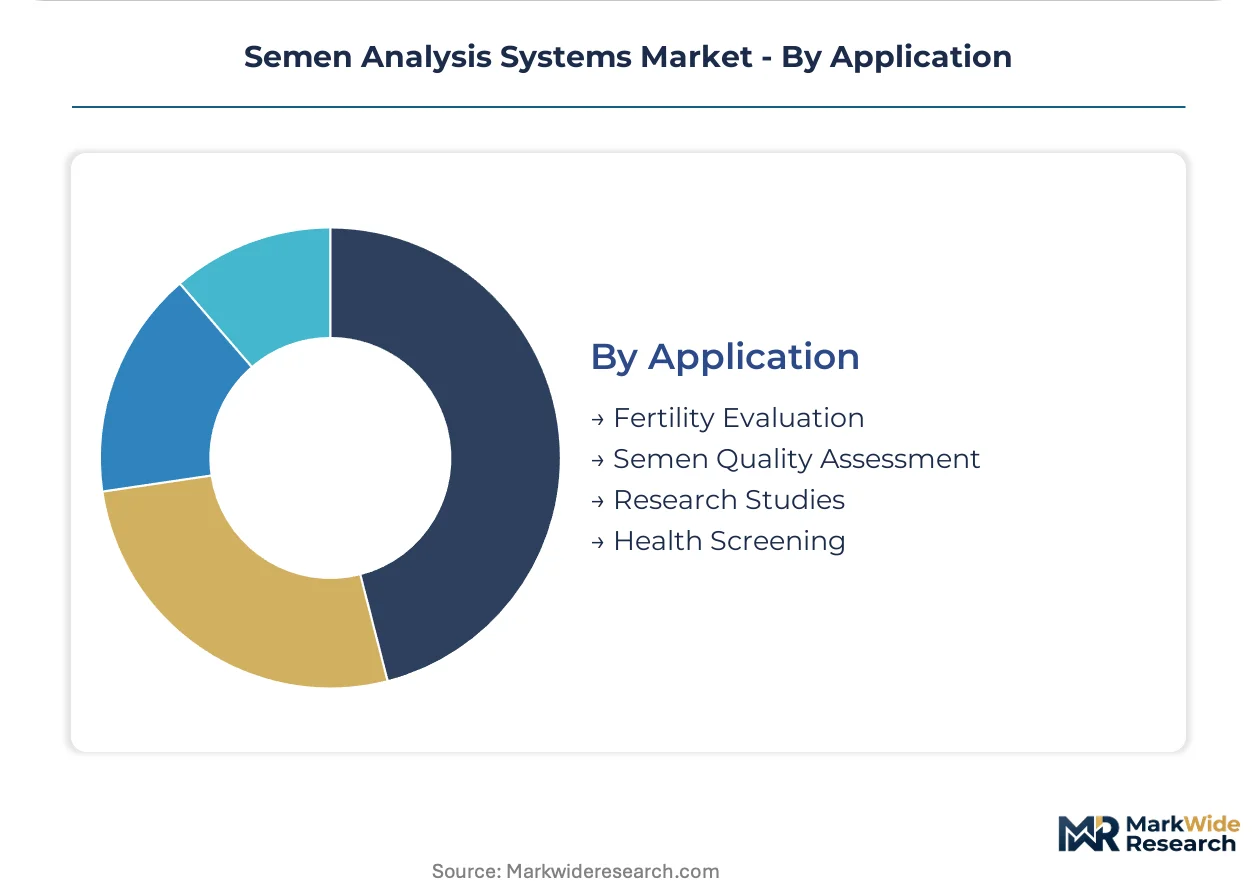
Application:
Clinical utility and reimbursement coding separate diagnostic-grade applications from screening and research uses.
- Fertility Evaluation:Diagnostic-grade semen analysis supports treatment decisions including intrauterine insemination and in-vitro fertilization, commanding premium platform specifications and comprehensive reporting capabilities.
- Semen Quality Assessment:Pre-treatment baseline testing and post-vasectomy confirmation drive recurring volume in hospital-based andrology services.
- Research Studies:Toxicology and environmental health investigations require standardized methodologies that reference WHO laboratory manual protocols.
- Health Screening:Occupational health and military recruitment programs utilize basic semen parameters for fitness determination.
Fertility evaluation leads on scale; semen quality assessment leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's fertility clinics face accelerated replacement cycles under EU MDR deadlines, while India's diagnostic chains adopt CASA technology to displace manual microscopy at a faster pace than anticipated.
United States
Hospital laboratory consolidation is centralizing andrology services into high-throughput reference facilities that demand automated platforms with LIS connectivity. FDA 510(k) clearance pathways shape product entry timelines for domestic manufacturers. The Greater Boston and Pacific Northwest clusters host academic centers driving algorithm development for morphology classification.
Germany
Fertility clinics must replace legacy manual systems with validated automated analyzers by EU MDR certification deadlines. The national pharmaceutical regulator enforces technical documentation requirements that extend certification cycles for European market access. Bavaria and North Rhine-Westphalia concentrate the largest diagnostic laboratory networks undergoing compliance-driven upgrades.
India
Diagnostic chains adopt CASA technology to displace manual microscopy as patient volumes expand across fertility service networks. CDSCO references WHO laboratory manual standards for domestic device registration, creating regulatory harmonization that smooths import pathways. Maharashtra and Karnataka host the fastest-growing clinic networks standardizing on automated platforms.
China
The world's largest fertility treatment market is opening to foreign manufacturers through NMPA fast-track pathways for AI-assisted morphology classification. National medical products administration innovative device designation accelerates market entry for algorithm-integrated platforms. The Yangtze River Delta and Pearl River Delta clusters concentrate premium fertility clinic networks demanding diagnostic-grade reporting capabilities.
Japan
Academic medical centers drive adoption of deep learning-based morphology assessment to standardize reporting across geographically dispersed laboratory sites. PMDA review timelines for software-as-medical-device classification shape product launch strategies for international vendors. The Kanto and Kansai regions anchor demand from consolidated hospital systems prioritizing reproducibility over manual expertise.
Semen Analysis Systems Market Competitive Landscape
Top-tier vendors anchor the premium automated analyzer segment, while mid-tier specialists compete on integrated workflow solutions and regional service proximity. The market structure concentrates around proprietary CASA algorithm developers, optical hardware fabricators, and sperm processing unit integrators. Two dominant competitive moves are reshaping positioning: technology licensing partnerships that accelerate AI morphology capabilities, and subscription-based software licensing that converts capital expenditure into recurring revenue streams.
Within the algorithm-centric tier, Hamilton Thorne and Medical Electronic Systems exemplify divergent strategic positioning—one leveraging North American laboratory relationships, the other anchoring integrated processing workflows. CooperSurgical occupies a position bridging premium hardware and European hospital procurement channels. These three entities represent the archetype spectrum from pure software licensing through bundled platform sales to brand-driven institutional contracting.
| Leading Market Players |
|---|
| Hamilton Thorne |
| Medical Electronic Systems |
| Bioline Technologies |
| Microptic |
| Sperm Processor |
| LabIVF Asia |
| Vitrolife |
| CooperSurgical |
| Proiser |
| Others |
Value Network & Pricing Analysis
Hospital laboratory procurement committees in the United States concentrate purchasing authority for high-throughput CASA platforms, anchoring market-wide pricing around subscription-based software licensing rather than perpetual hardware sales. This buyer archetype consolidation feeds back into manufacturer supply chain decisions, favoring regional service hubs over distributed fabrication networks to support recurring revenue relationships.
Pricing Analysis
Bundled platform-plus-service contracts dominate premium tier transactions while unbundled hardware-only sales persist in economy segments. Pricing stratifies across diagnostic-grade certification, throughput capacity, and AI morphology classification capability. Cost compression in manual microscopy tiers is intensifying because Indian diagnostic chains negotiate volume discounts for CASA displacement. Fertility clinic roll-ups show least price sensitivity; independent laboratories in emerging markets show most.
Supply Chain Analysis
Dual-sourcing requirements from German and Japanese precision optics suppliers are now standard for phase-contrast microscope objectives, forcing manufacturers to qualify secondary vendors for heated stages and digital imaging sensors. Supply draws from Germany, Japan, and China for optical components, with semiconductor sensors sourced from Taiwan and South Korea. Single-source vulnerability concentrates in precision optics fabrication. Distribution runs through authorized service distributors with regional calibration capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU MDR compliance deadlines in Germany accelerate replacement cycles and compress vendor selection timelines. The regulatory milestone creates demand visibility that favors early-mover certification investments.
For Market Incumbents: Lock in proprietary CASA algorithm advantages through expanded training datasets for morphology classification. Defend against emerging AI-first entrants by deepening backward integration into sperm processing unit fabrication. Prioritize LIS connectivity standardization to reduce clinic middleware development costs and reinforce single-vendor retention. For New Entrants and Emerging Players: Cloud-native morphology analysis platforms offer a technology-first wedge into telemedicine-integrated semen assessment services. Target direct-to-consumer channels in metropolitan United States markets where fertility clinic roll-ups standardize technology stacks. Pursue China's NMPA fast-track pathway for AI-assisted classification to establish regulatory beachhead in the world's largest fertility treatment market. For Investors and Strategic Acquirers: Private equity-backed fertility clinic networks are the most active acquirer in this space, driving platform standardization demand that rewards scalable software vendors. Long-term viability hinges on algorithm differentiation moats rather than optical hardware refinement. Watch for FDA 510(k) clearance acceleration for novel morphology algorithms as inflection signal for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Investment | Accelerates market access for automated analyzers in Germany's fertility clinic networks. |
| AI Morphology Algorithm Development | Compresses accuracy gap between automated and expert human assessment in hospital laboratories. |
| LIS Integration Standardization | Reduces clinic middleware costs and reinforces vendor retention across fertility networks. |
| Telemedicine Platform Partnership | Opens direct-to-consumer channels outside traditional clinic procurement structures. |
| China NMPA Fast-Track Filing | Accelerates market entry for foreign manufacturers in premium fertility clinic clusters. |
Research Methodology
Direct dialogue with fertility clinic laboratory directors, hospital andrology service managers, biomedical engineers, and GPO contracts managers grounded qualitative insights. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, CDSCO registration records, and hospital procurement contract repositories. Bottom-up installation base modeling and top-down fertility service network revenue triangulation converged on segment-level estimates.
Segmented outputs across product type, end user, technology, and application dimensions were generated across the analysis window. CAGRs were derived from fitted growth curves calibrated to regulatory milestone impacts and technology substitution rates. Modeled inputs included EU MDR compliance deadline effects, WHO laboratory manual standard adoption timelines, and AI morphology classification accuracy improvement trajectories.
The model holds under stable regulatory enforcement timelines and continued reimbursement pressure for diagnostic reproducibility; deviation in FDA 510(k) review acceleration or EU MDR deadline extensions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Tuberculosis (TB) Diagnostics Market
Diagnostics
Malaria Diagnostics Market
Diagnostics
Mexico in-Vitro Diagnostics Market
Diagnostics
Global Veterinary POC Diagnostic Market
Diagnostics
Sweden in-Vitro Diagnostics Market
Diagnostics
Middle East and Africa Ovarian Cancer Diagnostics Market
Diagnostics
Septicemia Diagnostic Testing Market
Diagnostics
In-Vitro Diagnostics (IVD) Instruments Market
Diagnostics
Global HIV/AIDS Diagnostics Market
Diagnostics
North America Thyroid Cancer Diagnostics Market
Diagnostics
Europe Kidney Cancer Diagnostics Market
Diagnostics
Cellular Health Screening Market
Diagnostics
Italy in Vitro Diagnostics Market
Diagnostics
Europe Colorectal Cancer Diagnostics Market
Diagnostics
Melioidosis Diagnostic Market
Diagnostics
Blood Culture Media Market