
 North America Molecular Diagnostics Market | 2026-2036
North America Molecular Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Molecular Diagnostics Market Outlook
The capital-intensity divergence between platform developers and reagent suppliers is bifurcating competitive dynamics across North America. Abbott Laboratories leverages integrated instrument-and-consumable architectures to sustain installed-base loyalty in high-throughput hospital laboratories. Thermo Fisher Scientific anchors its position through captive supply chains for PCR and NGS chemistries. Illumina dominates sequencing instrument placements while navigating pricing pressure from emerging benchtop competitors.
Molecular diagnostics encompasses nucleic acid amplification, hybridization, and sequencing techniques used to detect genetic mutations, pathogen nucleic acids, and gene expression profiles in clinical specimens. These methods employ polymerase chain reaction thermal cyclers operating at 95°C denaturation and 50-72°C annealing temperatures, real-time fluorescence detection, and massively parallel sequencing to deliver diagnostic sensitivity reaching single-copy detection limits. Reagents and assays generate recurring revenue streams that outpace instrumentation growth, with oncology applications commanding premium pricing due to companion diagnostic requirements. Point-of-care testing represents the fastest-expanding end-user channel, though hospital laboratories retain the deepest margin pools through centralized batch processing and managed care contracting leverage.
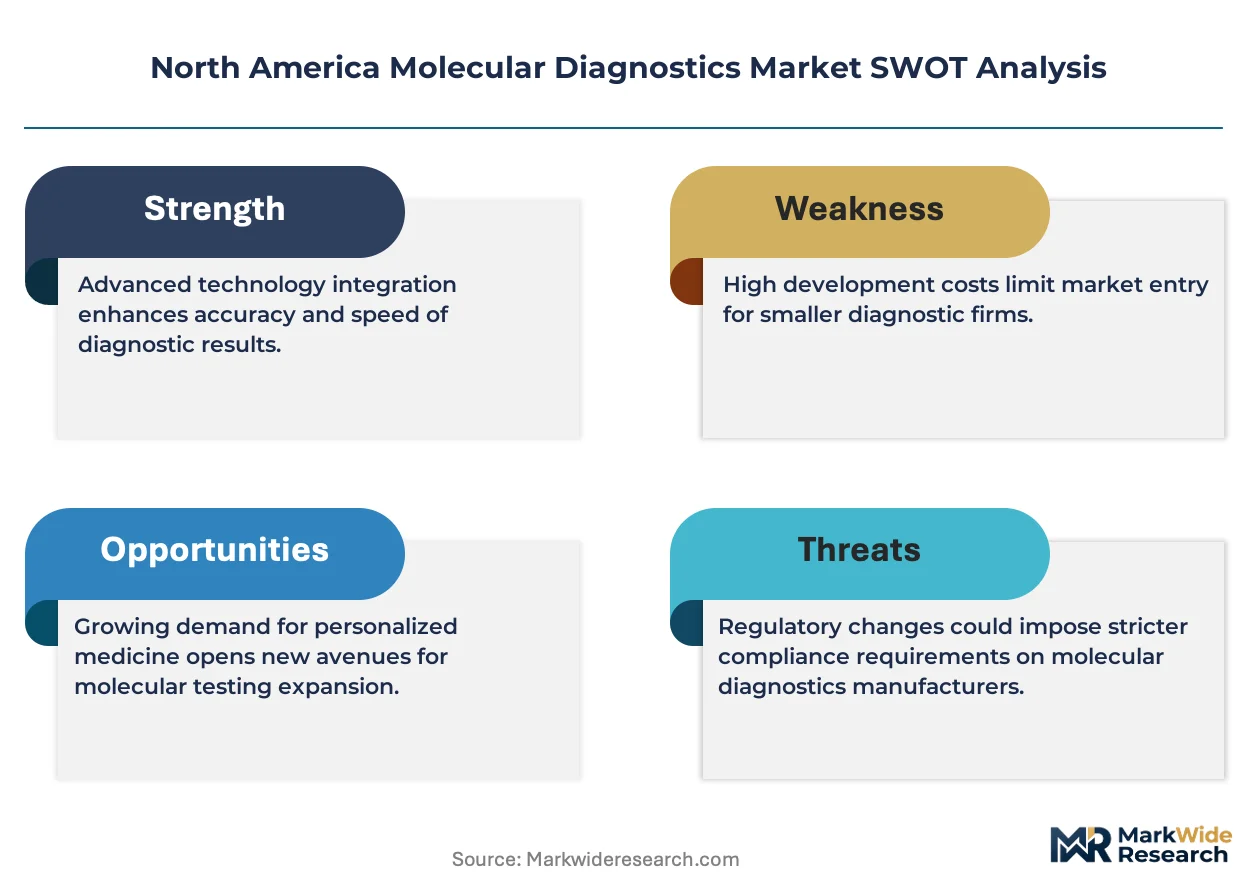
FDA oversight of laboratory-developed tests and CLIA complexity categorization shape market access timelines and validation burdens for new entrants. Health Canada and the FDA coordinate on harmonized nucleic acid test standards, while CAP accreditation requirements drive quality system investments across U.S. reference laboratories. Stakeholders must monitor reimbursement determinations from Medicare contractors and private payers for multi-gene panel tests, as coverage policy shifts will determine which technology platforms achieve sustainable clinical adoption.
Market Dynamics
Automated sample-to-answer platforms are compressing turnaround times for sepsis and respiratory panels, forcing hospital laboratories to consolidate vendor relationships around integrated instrument-consumable ecosystems.
Growth Catalysts
- FDA's evolving NGS oncology guidance:Streamlined companion diagnostic pathways accelerate assay validation timelines for manufacturers targeting solid tumor profiling.
- Academic medical center clustering:Boston, Houston, and San Diego anchor multi-site clinical trial networks that generate reference laboratory volume and technology validation data.
- Point-of-care molecular testing:CLIA-waived PCR platforms expand access beyond centralized labs into urgent care and retail clinic settings.
Market Restraints
- Reagent supply concentration:Captive chemistries from dominant platform manufacturers lock laboratories into proprietary consumable ecosystems with limited substitution options.
- CMS reimbursement uncertainty:Medicare contractor coverage determinations for multi-gene panel tests create unpredictable revenue recognition for assay developers.
- Capital intensity of NGS infrastructure:High-throughput sequencing installations require substantial facility investment that constrains mid-tier hospital laboratory adoption.
Strategic Opportunities
- Health Canada-FDA harmonization:Coordinated nucleic acid test standards enable single validation studies for simultaneous U.S. and Canadian market entry.
- Home-based respiratory surveillance:Consumer-accessible molecular testing for influenza and SARS-CoV-2 opens direct-to-patient channels outside traditional laboratory networks.
- AI-augmented variant interpretation:Machine learning integration with NGS pipelines addresses pathogenicity classification bottlenecks in hereditary cancer screening.
Industry Challenges
- Bioinformatics talent scarcity:Shortage of computational biologists trained in clinical-grade pipeline development constrains laboratory service expansion.
- Legacy LIS integration complexity:Middleware requirements for connecting new molecular platforms to established laboratory information systems extend implementation timelines.
- CAP accreditation burden:Quality system documentation requirements for next-generation sequencing proficiency testing consume substantial operational resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Molecular Diagnostics Market |
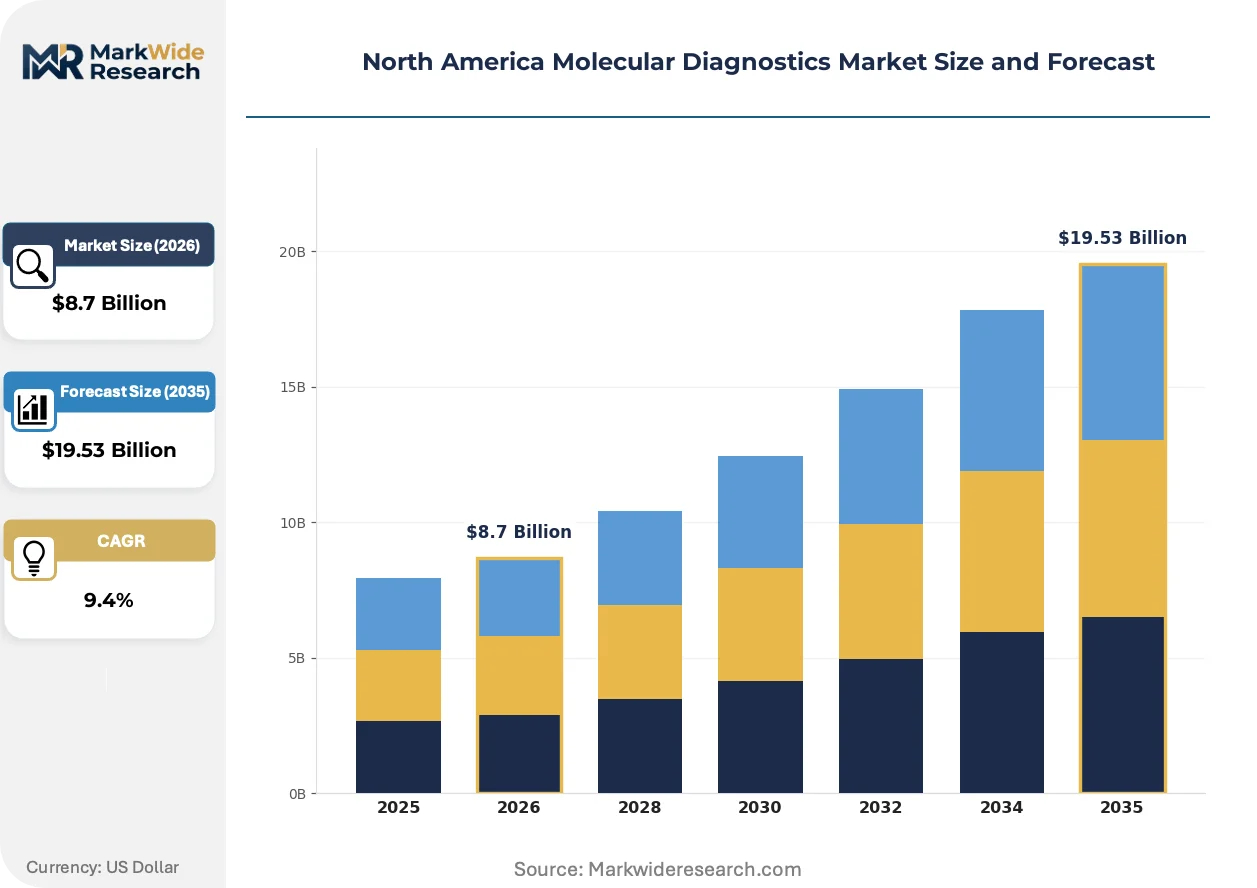
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Assays, Instrumentation, Software Application: Oncology, Infectious Diseases, Genetic Testing, Infectious Disease Screening End User: Hospitals, Laboratories, Clinics, Point-of-Care Testing Technology: PCR, NGS, Microarray, Sanger Sequencing |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche Ltd, Danaher Corporation, Hologic Corporation, Illumina Inc., Agilent Technologies, Becton, Dickinson and Company, Thermo Fisher Scientific Inc., QIAGEN N.V., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Molecular Diagnostics Market Strategic Shifts
Digital PCR platforms are fragmenting the quantitative nucleic acid testing landscape, while regulatory pressure on laboratory-developed tests intensifies compliance investment requirements across the vendor base.
CRISPR-based diagnostic detection is displacing conventional probe hybridization for infectious disease identification. Hospital microbiology laboratories in the United States are piloting SHERLOCK and DETECTR platforms for rapid antimicrobial resistance profiling. This enzymatic approach compresses assay development timelines from months to weeks, is displacing fluorescence resonance energy transfer probes in multiplexed respiratory panels.
FDA's phased enforcement discretion withdrawal for laboratory-developed tests imposes premarket submission requirements on academic medical center assays. Manufacturers must now navigate 510(k) or PMA pathways previously exempted under enforcement discretion. High-complexity molecular pathology laboratories in California and Massachusetts are responding by outsourcing validation to centralized reference facilities.
Consolidated service contracts now bundle instrument placement, reagent supply, and bioinformatics support into per-test pricing structures. Integrated delivery networks negotiate multi-year agreements that cap total molecular testing expenditure. This procurement transformation is most visible in Texas and Florida health systems where managed care contracting leverage concentrates purchasing authority at the IDN level.
North America Molecular Diagnostics Market Segmentation
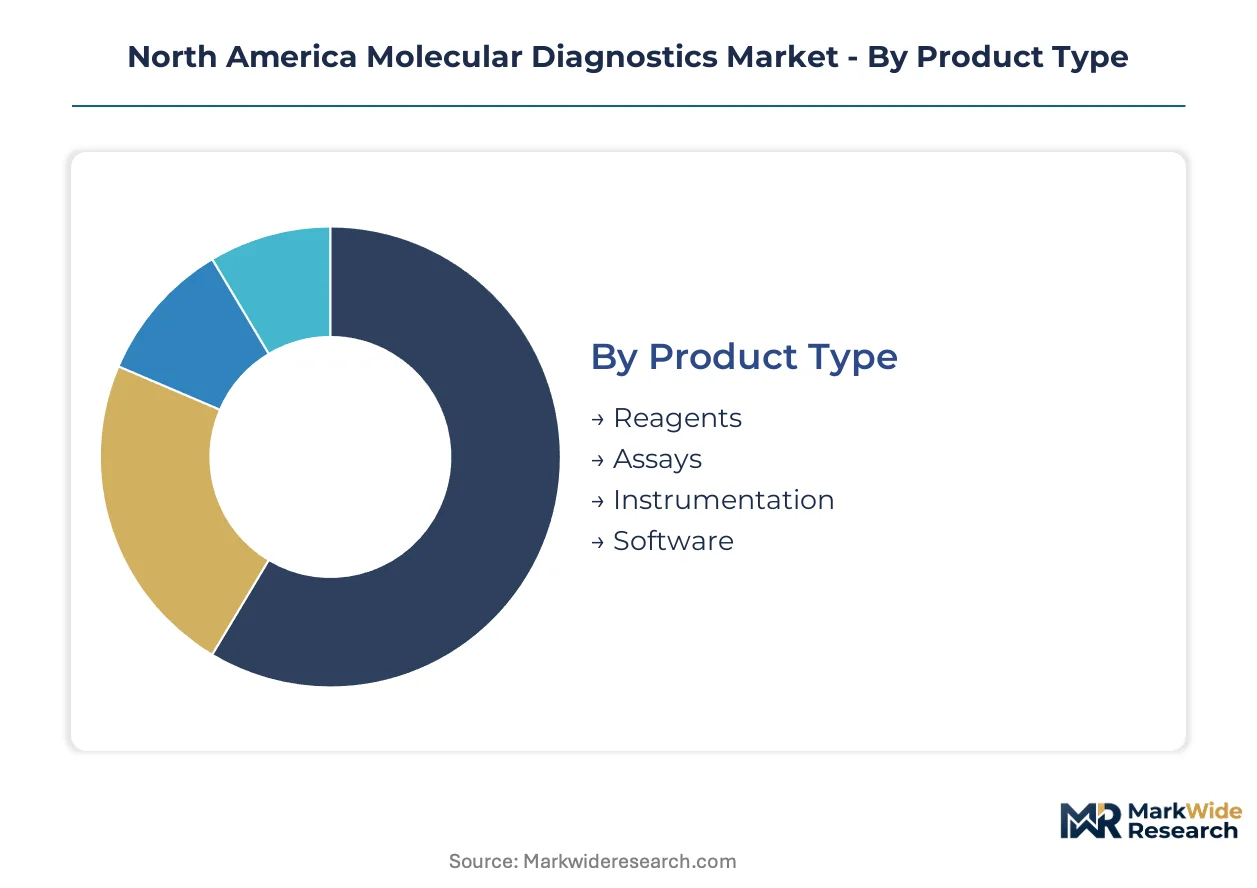
Molecular diagnostics segmentation reveals divergent margin profiles across consumables, platforms, and services. Reagent economics favor recurring revenue models while instrumentation demands capital deployment discipline. Technology choices determine regulatory pathway complexity and reimbursement eligibility.
Product Type:
Reagents and assays flow predominantly through domestic supply chains anchored by U.S. manufacturing facilities. Instrumentation and software components carry heavier import exposure from Asian contract manufacturers.
- Reagents:Enzymes, primers, and nucleotides constitute the consumable foundation of every molecular test. Hospital laboratories in Texas and Florida anchor the deepest procurement volumes through consolidated service agreements. FDA-cleared reagent kits command premium positioning against research-use-only alternatives.
- Assays:Pre-configured test panels for oncology companion diagnostics and respiratory pathogen detection bundle reagents with validated protocols. Academic medical centers in Boston and Houston drive validation study demand for multi-gene panels. CLIA complexity categorization determines whether assays deploy in high-complexity laboratories or near-patient settings.
- Instrumentation:Thermal cyclers, sequencers, and sample-to-answer platforms represent capital-intensive installed base expansion. Mid-tier hospital laboratories in the U.S. Southeast face facility constraints limiting high-throughput sequencing adoption.
- Software:Bioinformatics pipelines for variant calling and clinical interpretation require CLIA-compliant quality systems. CAP accreditation standards drive substantial validation documentation burdens for algorithm deployment.
Reagents command the established base. The steepest expansion runs through assays.
Application:
Cancer profiling concentrates in academic medical center networks while infectious disease testing disperses across community hospital laboratories. Genetic screening spans both institutional and direct-to-consumer channels with divergent regulatory oversight.
- Oncology:Solid tumor profiling and liquid biopsy applications leverage NGS and digital PCR for mutation detection. Medicare contractor coverage determinations for multi-gene panel tests create unpredictable revenue recognition timelines. FDA's evolving companion diagnostic guidance streamlines premarket pathways for assay developers.
- Infectious Diseases:Respiratory panels and sepsis detection drive automated platform adoption in hospital core laboratories. CLIA-waived PCR platforms are expanding access into urgent care settings beyond centralized lab networks.
- Genetic Testing:Hereditary cancer screening and carrier detection employ targeted NGS panels with AI-augmented variant interpretation. Health Canada-FDA harmonization enables simultaneous U.S. and Canadian market entry for validated assays.
- Infectious Disease Screening:Blood donor and prenatal pathogen detection operates under stringent FDA blood establishment regulations. Reference laboratories in California and Massachusetts anchor high-volume contract testing services.
Oncology commands the established base. The steepest expansion runs through infectious diseases.
End User:
Hospital laboratories retain procurement authority through integrated delivery network consolidation. Point-of-care deployment shifts testing economics toward per-test pricing away from capital ownership models.
- Hospitals:Centralized core laboratories process high-complexity molecular testing with managed care contracting leverage. Automated sample-to-answer platforms compress turnaround times for critical care decision-making.
- Laboratories:Reference facilities in San Diego and Houston anchor multi-site clinical trial networks. CAP accreditation requirements consume substantial operational resources for quality system documentation.
- Clinics:Specialty practices in oncology and infectious disease deploy moderate-complexity PCR for rapid diagnostic confirmation. Reagent supply concentration locks clinics into proprietary consumable ecosystems.
- Point-of-Care Testing:Retail clinics and urgent care centers adopt CLIA-waived molecular platforms for influenza and SARS-CoV-2 detection. Home-based respiratory surveillance opens direct-to-patient channels outside traditional laboratory networks.
Hospitals command the established base. The steepest expansion runs through point-of-care testing.
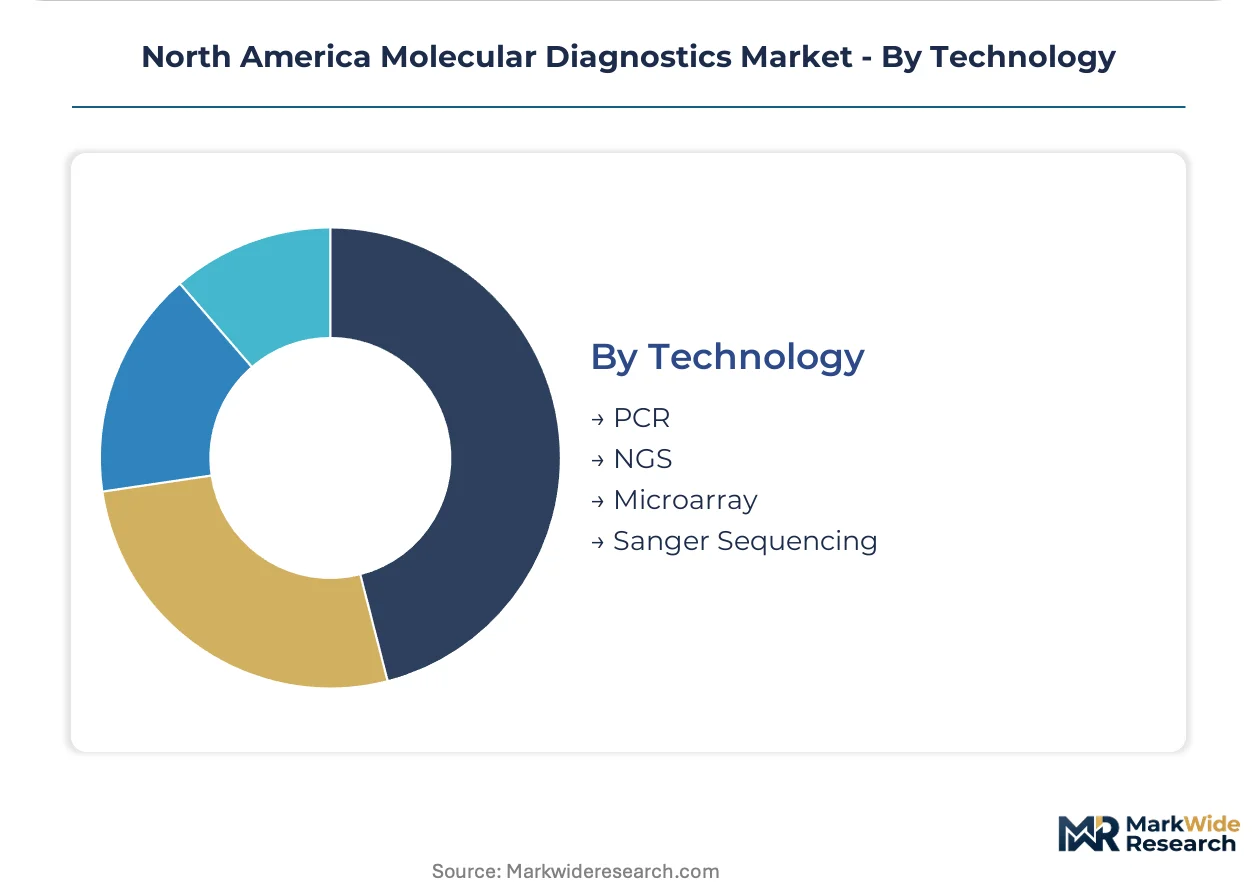
Technology:
PCR dominates installed base and reimbursement familiarity. NGS captures oncology and hereditary screening growth while facing capital intensity barriers in mid-tier facilities.
- PCR:Real-time and digital PCR platforms deliver quantitative nucleic acid detection with established clinical utility. Thermo Fisher Scientific anchors market position through captive chemistries and thermal cycler placements.
- NGS:Massively parallel sequencing enables comprehensive tumor profiling and rare disease diagnosis. Bioinformatics talent scarcity constrains laboratory service expansion for clinical-grade pipeline development.
- Microarray:Comparative genomic hybridization and SNP arrays retain niche applications in cytogenetics and pharmacogenomics. Legacy LIS integration complexity extends implementation timelines for platform upgrades.
- Sanger Sequencing:First-generation sequencing persists for targeted variant confirmation and forensic applications. Capital requirements remain modest compared to high-throughput NGS infrastructure.
PCR commands the established base. The steepest expansion runs through NGS.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States demonstrate the lowest price elasticity, absorbing premium pricing for companion diagnostics through managed care contracts. Canadian purchasers exhibit moderate sensitivity, negotiating volume discounts through provincial health authorities. Mexican laboratories face the highest cost constraints, driving demand for refurbished instruments and research-use-only reagents.
United States
Hospital laboratories in Texas and Florida consolidate procurement through integrated delivery networks, locking in multi-year reagent supply agreements. FDA's evolving guidance on NGS-based oncology companion diagnostics streamlines premarket pathways for assay developers targeting solid tumor profiling. Academic medical centers in Boston, Houston, and San Diego anchor multi-site clinical trial networks that generate reference laboratory volume and technology validation data.
Canada
Provincial health authorities in Ontario and Quebec negotiate centralized tenders for molecular testing platforms, compressing margins for instrument suppliers. Health Canada coordinates nucleic acid test standards with the FDA, enabling single validation studies for simultaneous U.S. and Canadian market entry. Research institutes in Toronto and Vancouver drive adoption of AI-augmented variant interpretation tools for hereditary cancer screening programs.
Mexico
Private hospital chains in Mexico City and Monterrey represent the primary demand channel, as public sector laboratories face chronic budget constraints. The country's national pharmaceutical regulator imposes registration requirements that extend commercialization timelines for imported diagnostic kits. Reference laboratories in Guadalajara concentrate on infectious disease testing for regional patient populations.
North America Molecular Diagnostics Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive structure. The upper tier combines instrument manufacturing with captive reagent supply chains, extracting recurring revenue from installed-base lock-in. Specialist competitors concentrate on single technology modalities or narrow application segments, competing on assay specificity rather than platform breadth. Dominant competitive moves include strategic partnerships between platform developers and bioinformatics providers, alongside portfolio diversification into adjacent testing modalities.
Within the integrated diagnostics tier, Abbott Laboratories and Thermo Fisher Scientific occupy positions defined by instrument-reagent bundling. Abbott leverages its installed base in high-throughput hospital laboratories through automated sample-to-answer architectures. Thermo Fisher anchors its position through captive chemistries for PCR and sequencing applications. Among sequencing-focused specialists, Illumina exemplifies the platform-dominant archetype, navigating pricing pressure from emerging benchtop competitors while maintaining instrument placement leadership.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd |
| Danaher Corporation |
| Hologic Corporation |
| Illumina Inc. |
| Agilent Technologies |
| Becton, Dickinson and Company |
| Thermo Fisher Scientific Inc. |
| QIAGEN N.V. |
| Others |
Value Chain & Pricing Dynamics
High-throughput sequencing capacity utilization above 80% in Massachusetts and California reference laboratories generates scale economies that compress per-test cost floors while elevating pricing power for proprietary reagent kits. This concentration of automated platform installations in academic medical center clusters creates dual pressure: captive consumable ecosystems lock in recurring revenue streams, while mid-tier hospital laboratories face capital barriers that segment the market into premium and economy tiers.
Pricing Analysis
Extended reagent supply contracts and bioinformatics service subscriptions generate lifetime value exceeding instrument placement revenue by factors of three to five. Contract-based long-term offtake structures dominate, with three-tier pricing structure across premium, standard, and economy levels differentiating by FDA clearance tier and CAP accreditation status. Cost compression in CLIA-waived point-of-care segments is intensifying because retail clinic procurement concentrates purchasing authority at integrated delivery network level. Community hospital laboratories exhibit highest price sensitivity; academic medical centers absorb premium pricing through managed care contracting leverage.
Supply Chain Analysis
Just-in-time reagent inventory cycles of 14-21 days expose laboratories to polymerase and oligonucleotide shortages originating in German and Japanese chemical manufacturing hubs. Thermostable enzyme production draws from Denmark and Singapore contract facilities, while sequencing flow cells source from San Diego and Cambridge, UK fabrication centers. Single-source vulnerability in CRISPR guide RNA synthesis creates chokepoint risk for emerging diagnostic platforms. Distribution runs through domestic cold-chain logistics networks anchored by Memphis and Louisville hub operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reagent and assay consumables expand faster than instrument hardware across the North America molecular diagnostics market, transforming capital equipment vendors into service-attach businesses with recurring revenue profiles. This shift elevates procurement contract duration and bioinformatics pipeline subscriptions as strategic value drivers.
For Market Incumbents: Consolidate installed-base loyalty through multi-year reagent supply agreements that bundle instrument maintenance with per-test pricing caps. Threat from benchtop sequencing competitors demands captive chemistry investments in PCR and NGS reagent manufacturing. Channel control via exclusive distribution partnerships with Texas and Florida integrated delivery networks protects margin pools against emerging platform developers.
For New Entrants and Emerging Players: Differentiate on AI-augmented variant interpretation for hereditary cancer screening, where bioinformatics talent scarcity constrains incumbent laboratory expansion. Point-of-care testing in urgent care and retail clinic settings represents the most penetrable channel, with CLIA-waived respiratory panels offering regulatory pathway clarity. Go-to-market angle: direct contracting with employer health clinics bypassing traditional GPO structures.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform developers with captive reagent supply chains and installed bases exceeding 500 thermal cycler placements. Long-term viability over the next decade hinges on FDA companion diagnostic pathway navigation and Medicare coverage determination timing. Acquisition target archetype: mid-scale assay developers with validated multi-gene panels awaiting 510(k) submission. Signal to watch: Health Canada-FDA harmonization announcements accelerating dual-market entry timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Multi-year service contracts with Texas IDNs lock in reagent volume commitments exceeding standalone instrument sales. |
| FDA Submission Pathway | Streamlined oncology companion diagnostic guidance accelerates premarket validation for solid tumor profiling assays. |
| Software Companion Development | CLIA-compliant bioinformatics pipelines address pathogenicity classification bottlenecks in hereditary cancer screening. |
| Reimbursement Strategy | Medicare contractor coverage determinations for multi-gene panels determine sustainable clinical adoption timelines. |
| CE Marking Pathway | Health Canada-FDA harmonization enables simultaneous U.S. and Canadian market entry from single validation studies. |
Study Parameters
Cross-validation between primary interviews with laboratory directors, GPO contracts managers, biomedical engineers, and regulatory affairs specialists anchors the qualitative findings against secondary sources including FDA 510(k) filings, CMS Medicare coverage determinations, CAP proficiency testing records, and hospital procurement databases. Bottom-up triangulation aggregates instrument placement and reagent consumption data from state-level CLIA laboratory registries, while top-down validation cross-checks against manufacturer shipment disclosures and trade flow records.
Sensitivity analysis across the projection horizon tests demand elasticity to Medicare reimbursement policy shifts and FDA enforcement discretion withdrawals. Segmentation dimensions modeled include technology modality, application area, end-user channel, and regional regulatory cluster. CAGRs derive from logistic adoption curves fitted to historical platform placement data, with inputs from health system capital expenditure surveys and clinical trial registration velocity for companion diagnostic indications.
Material uncertainties — CMS coverage determination reversals, supply chain disruptions in thermostable enzyme manufacturing, and CRISPR diagnostic platform regulatory reclassification — sit outside the modeled envelope. Forecasts reflect assumptions about continued FDA-Health Canada harmonization and sustained integrated delivery network consolidation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Tissue Transglutaminase Test Market
Diagnostics
Viral Disease Diagnosis Market
Diagnostics
Veterinary Molecular Diagnostics Market
Diagnostics
Epigenetics Diagnostics Market
Diagnostics
Latent Tuberculosis Infection Detection Market
Diagnostics
Poultry Diagnostics Market
Diagnostics
Clostridium Diagnostics Market
Diagnostics
Non-Alcoholic Steatohepatitis (NASH) Biomarkers Market
Diagnostics
Global Alzheimers Disease Diagnostic Market
Diagnostics
Paper Based Diagnostic Test Kits Market
Diagnostics
Asia-Pacific Womens Health Diagnostics Market
Diagnostics
Cancer IVD Market
Diagnostics
Global RSV Diagnostics Market
Diagnostics
Cervical Cancer Diagnostic Tests Market
Diagnostics
Brazil in Vitro Diagnostics Market
Diagnostics
Middle East and Africa Thyroid Cancer Diagnostics Market