
 US in Vitro Diagnostics Market | 2026-2036
US in Vitro Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
US in Vitro Diagnostics Market Intelligence
North Carolina's Research Triangle Park is rewriting regional IVD manufacturing density as contract manufacturers and diagnostic firms expand cleanroom assembly lines. Abbott leverages integrated immunoassay and molecular platforms to sustain hospital laboratory loyalty. Danaher anchors its position through disciplined operational excellence across Beckman Coulter and Cepheid product lines.
In vitro diagnostics encompasses medical devices and reagent systems that analyze biological specimens outside the human body to detect diseases, conditions, or infections, typically requiring controlled temperature ranges of 2-8°C for reagent stability and precise optical detection thresholds measured in absorbance units. These systems serve clinicians with actionable diagnostic information for treatment decisions. Reagents command recurring revenue streams that instruments enable, while next-generation sequencing applications attract the fastest investment intensity as oncology panels expand. Polymerase chain reaction technology maintains mature dominance in infectious disease testing workflows where throughput and turnaround time dictate purchasing criteria.
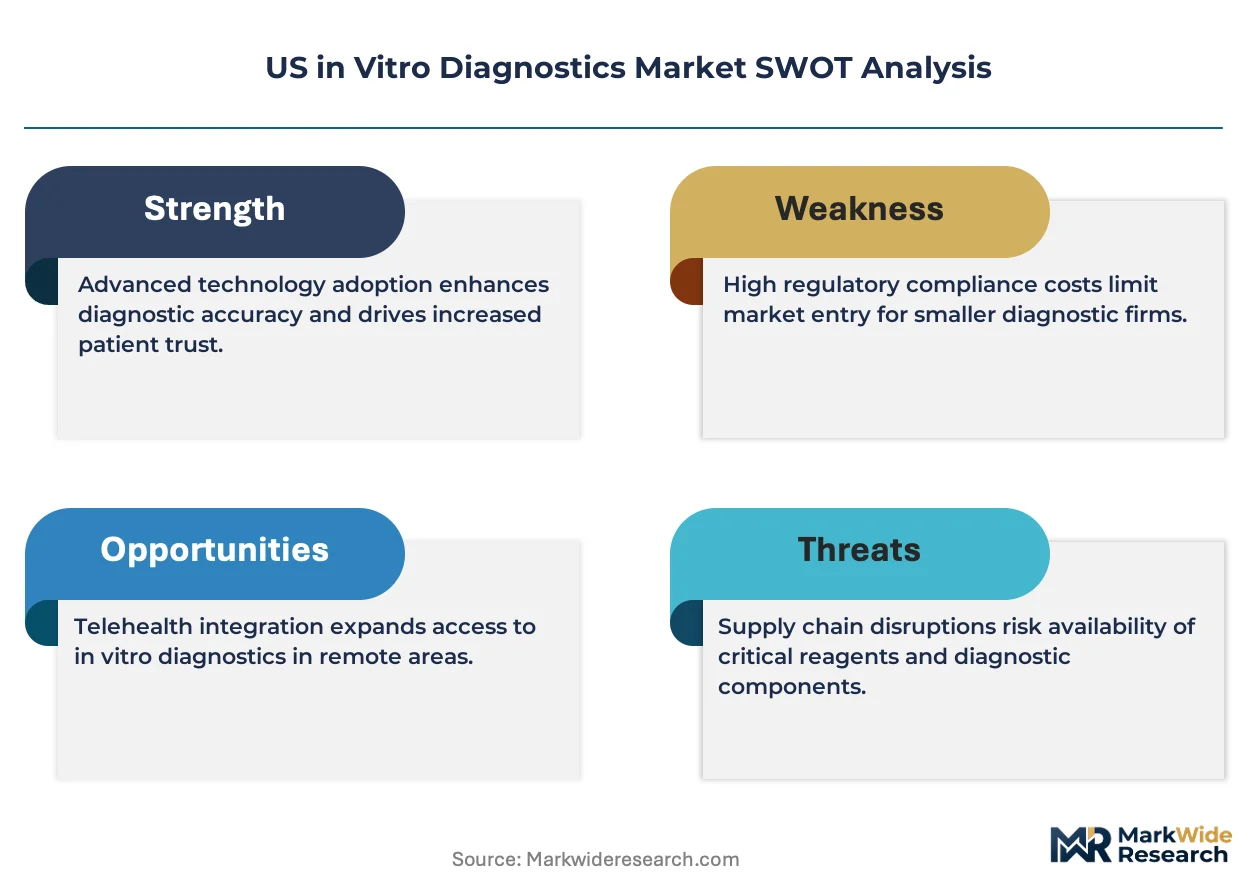
FDA premarket review pathways and CLIA complexity classifications shape which test platforms reach clinical laboratories versus point-of-care settings, with the agency's proposed rulemaking on laboratory-developed tests creating compliance uncertainty for hospital-based labs. CMS reimbursement determinations under the Protecting Access to Medicare Act establish coverage boundaries that directly influence manufacturer R&D prioritization. Stakeholders must track how FDA finalizes its LDT oversight framework and whether Congress intervenes with legislative alternatives that preserve laboratory flexibility.
Market Dynamics
FDA's proposed rulemaking on laboratory-developed tests is compressing compliance timelines for hospital-based molecular diagnostics, forcing capital reallocation toward validation infrastructure before final guidance lands.
Growth Catalysts
- Oncology Panel Expansion:Next-generation sequencing applications attract investment intensity as solid tumor profiling becomes standard-of-care across major metropolitan hospital systems, driving recurring reagent demand.
- CLIA Complexity Classifications:Moderate-complexity waivers under CLIA enable point-of-care molecular testing expansion into physician office laboratories, broadening addressable site volume.
- Infectious Disease Surveillance:Polymerase chain reaction technology maintains workflow dominance where hospital laboratories prioritize turnaround time for sepsis and respiratory pathogen identification.
Market Restraints
- Reagent Cold Chain Requirements:Controlled temperature ranges of 2-8°C for reagent stability impose logistics costs and spoilage risk that concentrate distribution power with specialized third-party logistics providers.
- FDA Premarket Review Pathways:De novo and 510(k) clearance timelines for novel biomarker assays create multi-year revenue gaps between R&D completion and commercial launch.
- CMS Reimbursement Compression:Protecting Access to Medicare Act rate-setting methodology constrains pricing flexibility for high-complexity molecular tests, compressing manufacturer margin structures.
Strategic Opportunities
- Research Triangle Park Manufacturing Density:North Carolina's cleanroom assembly expansion creates contract manufacturing scale for mid-tier diagnostic firms seeking outsourced production without coastal cost structures.
- Integrated Platform Convergence:Immunoassay and molecular testing consolidation onto single instrumentation footprints reduces capital burden for hospital laboratories managing space constraints.
- IRA Diagnostic Access Provisions:Medicare negotiation authority expansion into certain diagnostic categories may accelerate volume access for qualifying manufacturers meeting price benchmarks.
Industry Challenges
- Bioinformatics Talent Scarcity:Computational biology and variant interpretation expertise concentrates in coastal technology hubs, constraining laboratory expansion in secondary metropolitan markets.
- LDT Validation Infrastructure:FDA's anticipated enforcement discretion phase-out forces hospital laboratories to construct quality management systems equivalent to IVD manufacturers, requiring capital deployment without guaranteed revenue recovery timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US in Vitro Diagnostics Market |
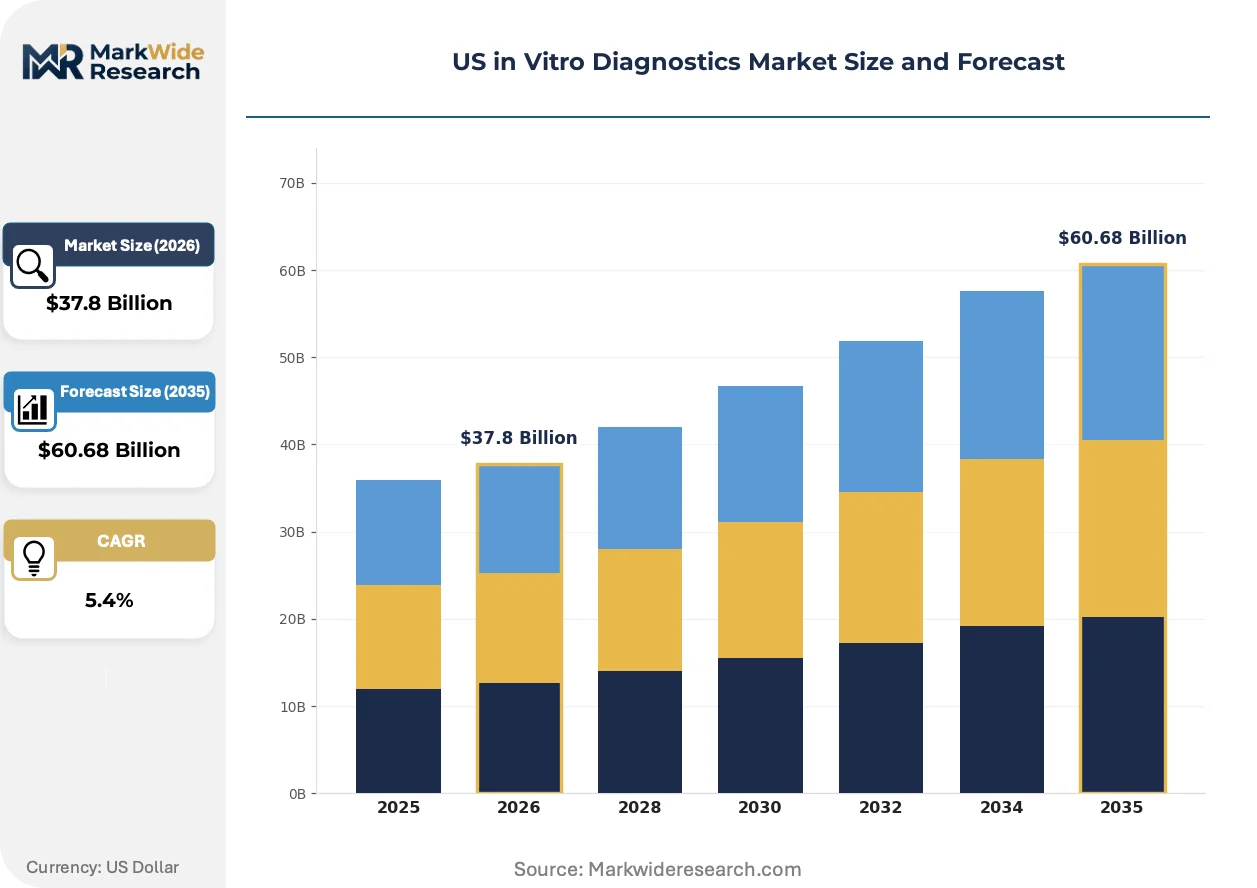
| Market Size in 2026 | $37.8 Billion |
| Market Size in 2035 | $60.68 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Software, Controls End User: Hospitals, Laboratories, Home Care, Research Institutions Application: Oncology, Infectious Diseases, Cardiology, Metabolic Disorders Technology: Polymerase Chain Reaction, Enzyme-Linked Immunosorbent Assay, Mass Spectrometry, Next-Generation Sequencing |
| Companies Covered | Abbott, F. Hoffmann-La Roche Ltd., Siemens Healthineers, Danaher, Bio-Rad Laboratories, bioMérieux, Thermo Fisher Scientific, Qiagen, BD, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US in Vitro Diagnostics Market Strategic Shifts & Innovations
Workflow automation and assay miniaturization are compressing the traditional separation between centralized laboratory testing and near-patient decision-making, redefining equipment footprints and staffing models simultaneously.
Digital PCR technology is migrating from oncology research applications into infectious disease quantification workflows. Hospital laboratories in tertiary care settings adopt droplet-based partitioning for viral load monitoring at accelerating replacement cycles. This migration from research-only to clinical-diagnostic utility is compressing the traditional five-year technology validation window into eighteen-month implementation timelines.
FDA's phased laboratory-developed test oversight framework is restructuring hospital laboratory compliance obligations. The proposed rulemaking requires quality system regulation adherence previously exempt for in-house assays, forcing capital reallocation toward documentation infrastructure. Academic medical centers with established regulatory affairs functions capture competitive advantage over community hospital systems lacking comparable expertise.
Health system procurement consolidation is compressing vendor negotiation cycles from annual to quarterly review periods. Integrated delivery networks with centralized laboratory oversight demand instrument-reagent bundling contracts that displace standalone reagent purchasing. This concentration is most visible across the Southeast and Midwest, where Catholic health system mergers have reduced qualified vendor pools to three preferred suppliers per testing category.
US in Vitro Diagnostics Market Segmentation
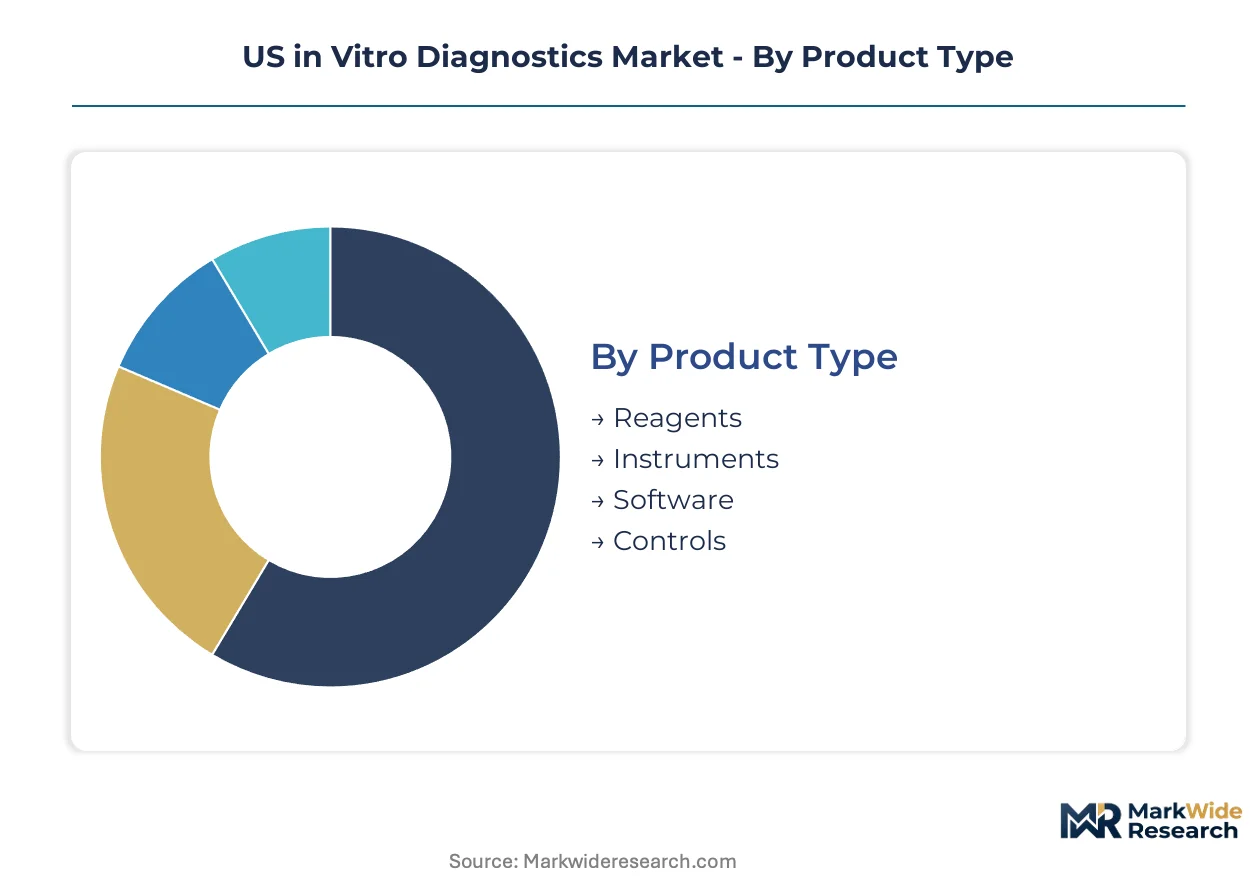
IVD market segmentation reveals distinct purchasing logics across customer types and applications. Product mix and technology choices diverge sharply between hospital laboratories managing high-throughput workflows and point-of-care settings prioritizing speed over sensitivity.
Product Type:
Cost tier differentiation separates recurring consumables from capital-intensive instrumentation and supporting infrastructure.
- Reagents:Consumable diagnostic chemicals and assay kits requiring 2-8°C cold chain integrity dominate recurring revenue streams. Hospital laboratories in metropolitan health systems concentrate purchasing power through multi-year supply agreements with preferred manufacturers. FDA premarket review timelines for novel reagent formulations create multi-year gaps between R&D completion and commercial launch.
- Instruments:Automated analyzers and detection platforms represent capital deployment decisions with 7-10 year replacement cycles. Integrated immunoassay-molecular platforms are displacing standalone systems in space-constrained clinical laboratories across the Southeast and Midwest.
- Software:Laboratory information management systems and assay data analysis tools enable workflow integration. Bioinformatics talent scarcity in secondary metropolitan markets constrains implementation velocity for advanced analytics modules.
- Controls:Quality assurance materials and calibrators ensure assay precision across testing menus. CLIA complexity classifications dictate control frequency requirements that vary by test category.
Reagents command the established base. The steepest expansion runs through software as laboratories digitize quality management systems ahead of FDA's LDT oversight enforcement.
End User:
Customer type determines purchasing criteria complexity and contract negotiation leverage.
- Hospitals:Acute care facilities with centralized laboratory services manage high-test-volume operations requiring rapid turnaround times. Catholic health system mergers across the Southeast and Midwest have consolidated vendor pools to three preferred suppliers per testing category.
- Laboratories:Independent reference laboratories and hospital-based clinical labs face divergent compliance pressures. Academic medical centers with established regulatory affairs functions capture competitive advantage over community hospital systems lacking comparable expertise.
- Home Care:Point-of-care testing in residential settings prioritizes waived complexity under CLIA regulations. Moderate-complexity waivers enable molecular testing expansion into physician office laboratories.
- Research Institutions:Translational research centers drive early adoption of novel biomarker assays before clinical validation. Digital PCR technology migration from oncology research into infectious disease workflows accelerates replacement cycles.
Hospitals anchor volume concentration. Research institutions are climbing the fastest as technology validation windows compress from five years to eighteen months.
Application:
Clinical utility and reimbursement dynamics segment demand by disease area.
- Oncology:Solid tumor profiling and companion diagnostic testing attract investment intensity as next-generation sequencing panels become standard-of-care. Major metropolitan hospital systems drive recurring reagent demand through expanded molecular testing menus.
- Infectious Diseases:Sepsis and respiratory pathogen identification prioritize polymerase chain reaction technology for turnaround time performance. Tertiary care settings adopt droplet-based digital PCR for viral load monitoring at accelerating replacement cycles.
- Cardiology:Cardiac biomarker assays for acute coronary syndrome evaluation require high-sensitivity detection thresholds. CLIA complexity classifications shape platform placement between central laboratories and emergency department point-of-care settings.
- Metabolic Disorders:Diabetes monitoring and lipid panel testing represent high-frequency routine testing with established reimbursement pathways. Protecting Access to Medicare Act rate-setting methodology constrains pricing flexibility for these high-volume categories.
Infectious diseases command the established base. Oncology is gaining share fastest as precision medicine reimbursement frameworks mature.
Technology:
Technical maturity and workflow integration requirements segment platform adoption.
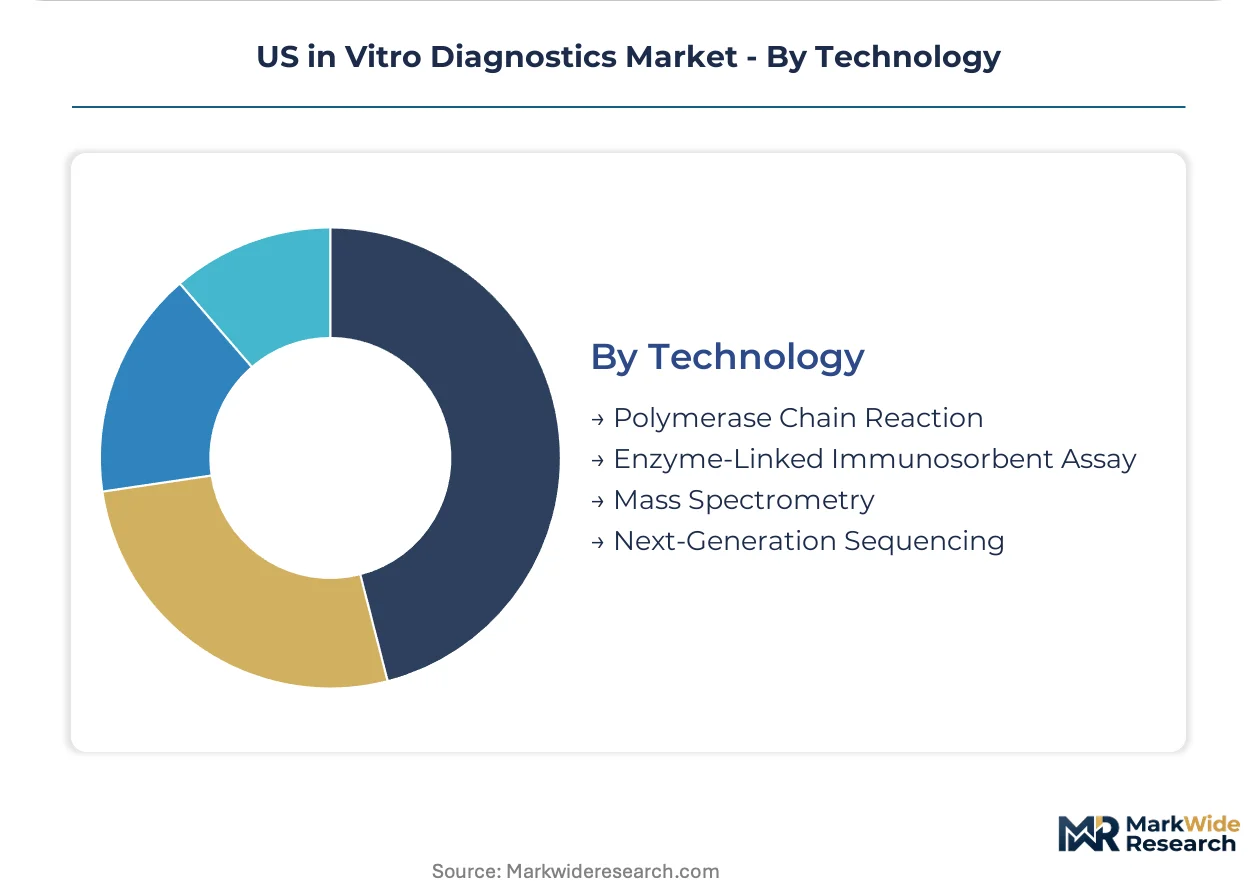
- Polymerase Chain Reaction:Thermal cycling amplification technology maintains workflow dominance for infectious disease testing where throughput and turnaround time dictate purchasing criteria. Hospital laboratories prioritize instrument reliability for sepsis identification protocols.
- Enzyme-Linked Immunosorbent Assay:Colorimetric detection methods for protein and antibody quantification serve high-volume screening applications. Immunoassay consolidation onto molecular-capable platforms reduces capital burden for space-constrained laboratories.
- Mass Spectrometry:Ion separation detection enables multiplexed metabolite and therapeutic drug monitoring with high specificity. Capital costs and specialized operator training concentrate deployment in academic medical center reference laboratories.
- Next-Generation Sequencing:Massively parallel sequencing platforms support oncology panel expansion and rare disease identification. FDA premarket review pathways for sequencing-based assays create multi-year revenue gaps between development completion and commercial availability.
Polymerase chain reaction anchors the established base. Next-generation sequencing is climbing the fastest as solid tumor profiling becomes standard-of-care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket review pathways anchor the United States as the regulatory benchmark shaping domestic IVD deployment timelines and hospital laboratory compliance investments across metropolitan health systems.
Research Triangle Park
Contract manufacturers and diagnostic firms expand cleanroom assembly lines across North Carolina's Research Triangle Park, rewriting regional IVD manufacturing density. State economic development incentives support biotechnology infrastructure expansion. Abbott and bioMérieux maintain operational footprints in the corridor alongside emerging contract manufacturers.
Greater Boston
Academic medical centers with established regulatory affairs functions capture competitive advantage over community hospital systems lacking comparable expertise. Massachusetts life sciences tax incentives sustain venture capital flow into diagnostic startups. The Longwood Medical Area anchors precision medicine research translation into clinical diagnostic applications.
San Francisco Bay Area
Bioinformatics talent scarcity concentrates computational biology expertise in coastal technology hubs, constraining laboratory expansion in secondary metropolitan markets. California stem cell research funding programs indirectly support diagnostic biomarker discovery pipelines. South San Francisco biotechnology clusters host next-generation sequencing platform development.
Midwest Manufacturing Belt
Catholic health system mergers across the Southeast and Midwest have consolidated vendor pools to three preferred suppliers per testing category. Illinois and Michigan hospital procurement networks demand instrument-reagent bundling contracts that displace standalone reagent purchasing. Danaher's Beckman Coulter operations in the region exemplify operational excellence deployment.
Pacific Northwest
Thermo Fisher Scientific maintains Pacific Northwest research instrumentation development capacity supporting infectious disease surveillance applications. Washington state global health initiatives align with molecular diagnostics for pathogen identification. Seattle-based health technology clusters attract digital PCR workflow automation engineering talent.
US in Vitro Diagnostics Market Key Industry Players
Integrated platform conglomerates and specialized molecular diagnostic firms split the market between consolidated hospital laboratory contracts and targeted assay development partnerships. The vendor structure concentrates around instruments-with-recurring-reagents business models that lock in multi-year purchasing agreements. Three archetypes dominate: diversified life sciences conglomerates with diagnostic divisions, pure-play molecular diagnostic specialists, and contract research organizations extending into regulated IVD manufacturing. Competitive moves center on CLIA complexity waiver acquisitions and point-of-care molecular testing site expansion.
Among diversified conglomerates, Abbott exemplifies integrated immunoassay and molecular platform convergence, while Danaher anchors operational excellence discipline across multiple diagnostic product lines. F. Hoffmann-La Roche Ltd. occupies the premium-tier position in oncology companion diagnostics. These three entities represent distinct strategic postures: platform integration, operational scale, and precision medicine specialization respectively.
| Leading Market Players |
|---|
| Abbott |
| F. Hoffmann-La Roche Ltd. |
| Siemens Healthineers |
| Danaher |
| Bio-Rad Laboratories |
| bioMérieux |
| Thermo Fisher Scientific |
| Qiagen |
| BD |
| Others |
Cost & Logistics Intelligence
Single-source dependency on Chinese-manufactured PCR thermal cyclers and reagent raw materials determines both tiered pricing spreads and supply chain vulnerability across US hospital laboratory networks. FDA premarket review timelines for alternative sourcing validation compress procurement flexibility while concentrating negotiating leverage with integrated platform conglomerates.
Pricing Analysis
Geographic price spreads between Research Triangle Park contract manufacturing corridors and coastal metropolitan health systems reach three-tier stratification across premium, standard, and economy levels. Instrument-reagent bundling contracts demanded by consolidated Catholic health systems in the Southeast and Midwest displace standalone reagent purchasing, compressing margin structures for mid-tier suppliers. Pricing pressure stems from CMS reimbursement compression under PAMA rate-setting methodology, with independent reference laboratories exhibiting highest price sensitivity versus academic medical centers prioritizing turnaround time performance.
Supply Chain Analysis
Jabil, Plexus, and specialized life sciences contract manufacturers hold cleanroom assembly capacity concentrated in Mexico, Malaysia, and the Research Triangle Park corridor. Raw material dependencies center on German-sourced optical detection components, Japanese precision thermal elements, and Chinese-sourced polymerase enzymes. Single-source vulnerability runs through Taq polymerase supply chains subject to tariff exposure and export licensing restrictions. Distribution runs through specialized third-party logistics providers maintaining 2-8°C cold chain integrity from manufacturing sites to hospital laboratory loading docks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement consolidation across Catholic health system mergers has shifted buyer power toward integrated delivery networks capable of extracting instrument-reagent bundling concessions from diagnostic manufacturers.
For Market Incumbents: Entrench hospital laboratory loyalty through accelerated CLIA complexity waiver acquisitions for point-of-care molecular testing expansion. Anchor defensive positioning against emerging digital PCR specialists by deepening backward integration into reagent raw material supply. Prioritize quality management system investments ahead of FDA's LDT enforcement discretion phase-out to capture compliance-driven vendor consolidation opportunities. For New Entrants and Emerging Players: Community hospital systems in secondary metropolitan markets lacking established regulatory affairs functions represent the most penetrable entry point for outsourced LDT validation services. Physician office laboratories seeking moderate-complexity molecular testing waivers offer white-space expansion beyond tertiary care concentration. Pursue partnership-first go-to-market positioning with Research Triangle Park contract manufacturers to bypass capital-intensive cleanroom infrastructure requirements. For Investors and Strategic Acquirers: FDA's final LDT oversight rulemaking reshapes the acquisition landscape toward quality system regulation-compliant laboratory service providers. Five-to-ten year viability favors targets with established hospital system GPO contracts and documented CLIA high-complexity accreditation histories. Monitor CMS Medicare coverage determinations for novel oncology companion diagnostics as the primary inflection signal for reagent revenue acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Complexity Waiver Acquisition | Enables point-of-care molecular testing expansion into physician office laboratories across consolidated health systems. |
| Integrated Platform Convergence | Immunoassay-molecular consolidation reduces capital burden for space-constrained hospital laboratories managing Southeast and Midwest mergers. |
| Research Triangle Park Manufacturing Expansion | Cleanroom assembly scale supports mid-tier diagnostic firms seeking outsourced production without coastal cost structures. |
| Quality Management System Investment | FDA LDT oversight compliance creates competitive advantage over community hospital systems lacking regulatory expertise. |
| Hospital System GPO Contracting | Instrument-reagent bundling agreements lock in multi-year purchasing relationships with consolidated Catholic health networks. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with hospital laboratory directors, biomedical engineers, GPO contracts managers, and regulatory affairs specialists; and secondary validation against FDA 510(k) and De novo submission databases, CMS Medicare reimbursement schedules, hospital procurement records, and CLIA laboratory certification registries. Bottom-up test volume modeling across oncology and infectious disease applications triangulated with top-down manufacturer revenue segmentation.
Forecast inputs considered technology adoption curves across polymerase chain reaction, next-generation sequencing, and digital PCR platforms over the projection horizon. Segmentation dimensions included product type, end user category, clinical application, and technology maturity tier. CAGRs derived from instrument replacement cycle analysis, reagent consumable attach rates, and reimbursement pathway expansion timelines for precision medicine diagnostics.
Stress conditions across FDA LDT oversight finalization timing, CMS rate-setting methodology revisions, and Taq polymerase supply chain disruptions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding health system consolidation velocity and molecular testing menu expansion. Quarterly review of FDA guidance document releases and Medicare coverage determination announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global Serological Testing Market
Diagnostics
Alzheimer's Diagnostics and Therapeutics Market
Diagnostics
Body Fluid Collection and Diagnostics Market
Diagnostics
In Vitro Diagnostic Antibodies Market
Diagnostics
North America Point of Care Diagnostics Market
Diagnostics
Saudi Arabia in-Vitro Diagnostics (IVD) Market
Diagnostics
In Vitro Diagnostics Test Kit Market
Diagnostics
Molecular Diagnostics Market
Diagnostics
Melioidosis Diagnostic Market
Diagnostics
Global Sepsis Diagnostics Market
Diagnostics
Blood Urea Nitrogen Diagnostics Market
Diagnostics
Australia in-Vitro Diagnostics Market
Diagnostics
Rapid Plasma Reagin Test Market
Diagnostics
HIV Diagnostics Market
Diagnostics
Middle East and Africa Syndromic Multiplex Diagnostic Market
Diagnostics
D-Dimer Market