
 Global Alzheimers Disease Diagnostic Market | 2026-2036
Global Alzheimers Disease Diagnostic Market Size, Share, and Industry Trends Forecast 2026-2036
Global Alzheimers Disease Diagnostic Market Intelligence
The bundling of biomarker tests with AI-powered cognitive assessment tools is repositioning how neurology clinics and research institutes procure diagnostic solutions. Siemens Healthineers leverages its strength in imaging devices to offer integrated diagnostic packages. Quanterix specializes in ultra-sensitive biomarker detection, while Hoffmann-La Roche anchors its strategy in molecular diagnostics and broad pharmaceutical research.
Alzheimer's disease diagnostics encompass a range of methods used to detect pathological biomarkers, such as amyloid-beta and tau proteins, associated with neurodegeneration. The primary purpose is to enable early and accurate diagnosis, differentiate Alzheimer's from other forms of dementia, and monitor disease progression for therapeutic management. Biomarker tests, particularly emerging blood tests, represent the fastest-growing product category due to their non-invasive nature. Diagnostic laboratories remain the largest end-user segment, driven by the volume of cerebrospinal fluid analysis and imaging procedures.
Regulatory frameworks from the US FDA, Europe's EMA, and Japan's PMDA are critical for market access. These agencies' approval pathways for novel biomarkers and imaging agents, like the recent focus on blood-based markers, directly shape product development timelines and commercial viability. Stakeholders must navigate evolving reimbursement policies and clinical guideline updates, which will determine the adoption rate of new diagnostic technologies.
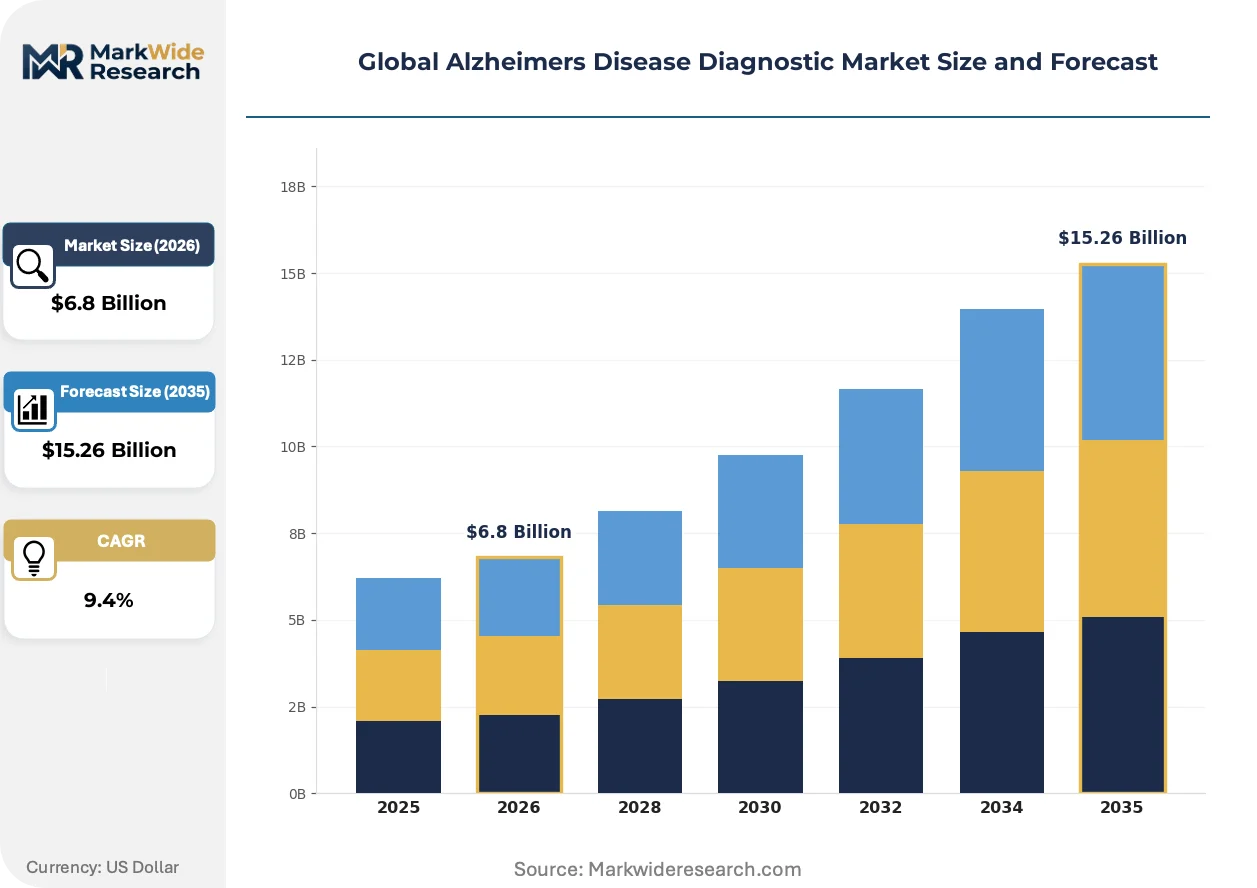
Market Dynamics
The fundamental shift from late-stage, symptom-based assessment to early, biomarker-driven detection is the central force shaping the market. This transition is propelled by technological breakthroughs in fluid biomarkers and advanced imaging, altering clinical pathways and research priorities.
Growth Catalysts
- Regulatory Tailwinds:The FDA's framework for accelerated approval of Alzheimer's therapies necessitates wider use of companion diagnostics to identify eligible patient populations, directly stimulating demand for amyloid and tau tests.
- Blood-Based Assays:The commercialization of ultra-sensitive blood tests for biomarkers like p-tau217 offers a scalable, less invasive, and more cost-effective alternative to CSF analysis or PET imaging, expanding access to early screening.
- Diagnostic Laboratory Expansion:Growing test volumes are driving significant investment by large diagnostic laboratories in automated, high-throughput platforms for cerebrospinal fluid analysis and immunoassays, increasing their capacity and market influence.
Market Restraints
- Reimbursement Hurdles:Inconsistent and often restrictive reimbursement policies for novel diagnostic tools, particularly expensive PET imaging agents and new blood tests, limit widespread clinical adoption and patient access in many healthcare systems.
- Diagnostic Ambiguity:Despite advances, biomarkers can present ambiguous results in early or atypical disease stages, making it difficult to definitively differentiate Alzheimer's from other neurodegenerative conditions and complicating clinical decision-making.
- Guideline Fragmentation:The slow and uneven adoption of updated clinical practice guidelines for biomarker use across different countries and regions creates significant friction, hindering the establishment of a global standard of care.
Strategic Opportunities
- Geographic Expansion:Japan's rapidly aging demographic and strong governmental focus on dementia research present a major opportunity for the market entry of advanced diagnostic technologies, including novel blood tests and AI-powered imaging analysis.
- Technology Convergence:Integrating digital cognitive assessment applications with fluid biomarker data allows for the creation of powerful, multi-modal diagnostic platforms that can track disease progression with greater precision than any single method.
- Multiplex Panel Development:An opportunity exists to develop diagnostic panels capable of simultaneously detecting biomarkers for multiple neurodegenerative diseases, enabling a more efficient differential diagnosis from a single patient sample.
Industry Challenges
- Assay Standardization:A lack of global standardization for biomarker quantification across different test kits and laboratory platforms complicates the comparison of results from clinical trials and routine diagnostics, creating a barrier to universal interpretation.
- Data System Integration:Implementing new diagnostic workflows requires overcoming significant interoperability challenges between imaging archives, laboratory information systems, and electronic health records, which can delay adoption in clinical settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Alzheimers Disease Diagnostic Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biomarker Tests, Imaging Devices, Genetic Tests, Cognitive Assessment Tools, Blood Tests Technology: Magnetic Resonance Imaging, Positron Emission Tomography, Electroencephalography, Artificial Intelligence, Molecular Diagnostics Application: Early Detection, Differential Diagnosis, Disease Monitoring, Risk Assessment, Treatment Planning End User: Neurology Clinics, Research Institutes, Memory Care Centers, Diagnostic Laboratories, Geriatric Care Facilities |
| Companies Covered | Quest Diagnostics, Quanterix, Siemens Healthineers, Fujirebio, Labcorb, C2N Diagnostics, Lantheus, Sysmex, Hoffmann-La Roche, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Alzheimers Disease Diagnostic Market Strategic Shifts & Innovations
The market's evolution is defined by a move toward a proactive, data-centric diagnostic ecosystem. This paradigm emphasizes predictive analytics and integrated data streams, aiming to replace reactive, late-stage diagnosis with early and precise pathological characterization.
Artificial intelligence-powered software for analyzing PET and MRI scans provides automated quantification of amyloid plaques and tau tangles. Neurology clinics and pharmaceutical research organizations are adopting these platforms to enhance diagnostic accuracy and consistency. This technology is unifying vast and variable imaging datasets into standardized, actionable reports, which reduces reader subjectivity and supports more efficient clinical trial enrollment.
Global regulatory bodies, including the US FDA and Europe's EMA, are creating clearer approval pathways for blood-based biomarkers intended for diagnostic use. This policy direction lessens the dependency on invasive cerebrospinal fluid collection or costly PET scans for initial patient screening. Consequently, the in-vitro diagnostics (IVD) segment is most affected, with manufacturers accelerating the development of high-throughput blood assays.
A distinct shift in buying patterns sees healthcare providers favoring bundled procurement of neurodegenerative diagnostic solutions. This disrupts the siloed purchasing of imaging services, biomarker assays, and cognitive assessment tools. Integrated packages that combine hardware, software analytics, and reagents are becoming the preferred model, especially within large, consolidated hospital networks in the United States and Western Europe.
Global Alzheimers Disease Diagnostic Market Segmentation
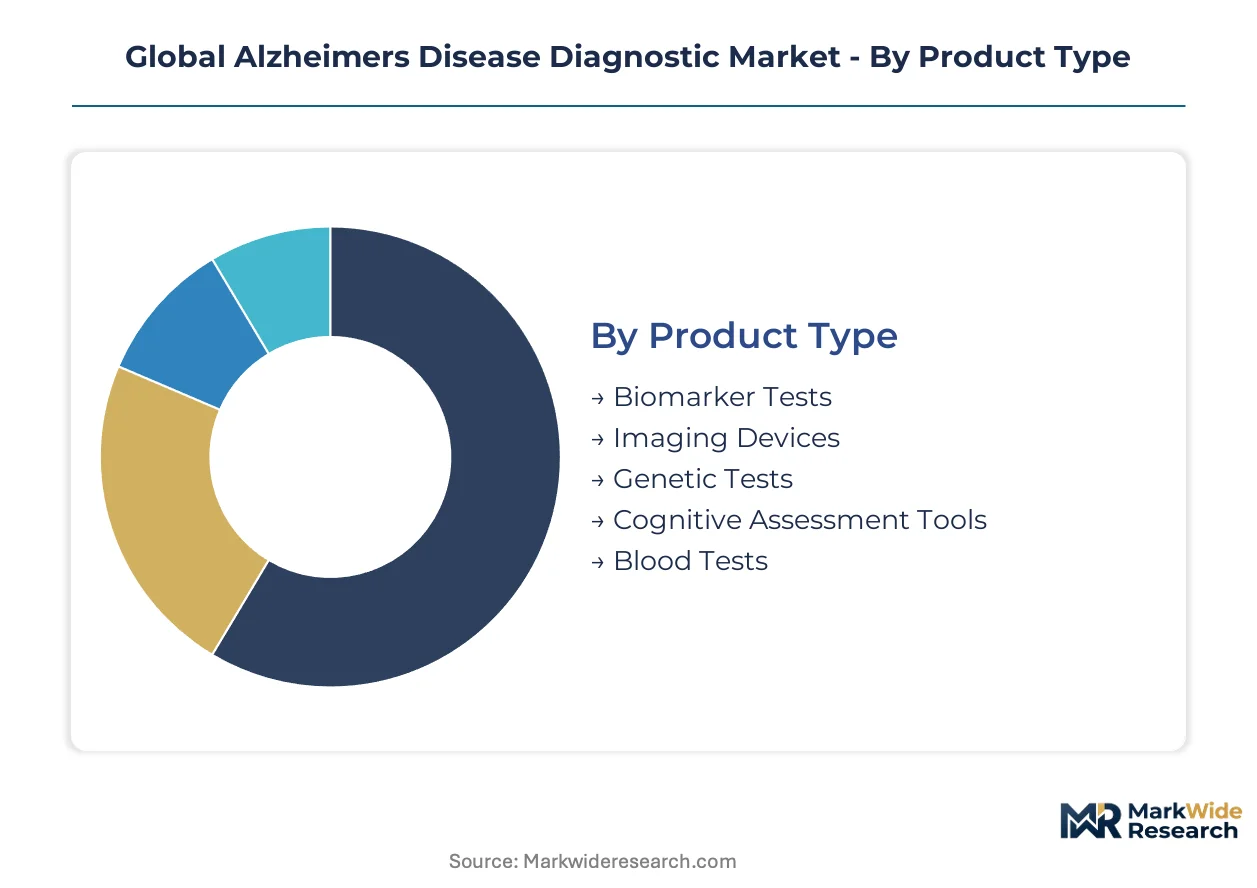
The Alzheimer's disease diagnostic market segments by product type, technology, application, and end user. Each segment reflects distinct needs and technological advancements, influencing procurement patterns and market penetration across different healthcare settings. Understanding these divisions reveals specific growth pockets and areas requiring targeted development.
Product Type:
The market for Alzheimer's diagnostics shows a clear split between high-volume, cost-effective screening tools and premium, specialized diagnostic devices. This dichotomy drives procurement decisions among various clinical and research entities.
- Blood Tests:These non-invasive assays detect specific biomarkers like p-tau217 from a simple blood draw, offering a scalable and more accessible option for early screening. Demand for blood tests is significantly expanding from primary care settings and large-scale population health initiatives.
- Biomarker Tests:These diagnostics measure pathological proteins such as amyloid-beta and tau in cerebrospinal fluid, providing definitive evidence of Alzheimer's pathology. Diagnostic laboratories heavily utilize these tests for confirming diagnoses and monitoring disease progression in specialized neurology clinics.
- Imaging Devices:This category includes PET and MRI scanners utilized for visualizing amyloid plaques, tau tangles, and structural brain changes associated with neurodegeneration. Advanced research institutes and specialized diagnostic centers drive demand for high-resolution imaging.
- Cognitive Assessment Tools:Standardized psychological tests evaluate memory, executive function, and other cognitive domains to identify potential impairment. Neurology clinics and memory care centers use these tools for initial screening and tracking cognitive decline.
- Genetic Tests:These analyses identify genetic predispositions, such as APOE4 status, which increase Alzheimer's risk. Research institutes and specialized clinics use genetic testing for early risk stratification and clinical trial enrollment.
Today's leader: Biomarker Tests. Tomorrow's challenger: Blood Tests.
Technology:
Technological advancements are reshaping diagnostic capabilities, with innovation focusing on enhancing accuracy, reducing invasiveness, and improving throughput. The integration of advanced computational methods with traditional imaging and molecular techniques is a defining trend.
- Artificial Intelligence:AI-powered software analyzes PET and MRI scans for automated quantification of amyloid plaques and tau tangles, improving diagnostic accuracy and consistency. Neurology clinics and pharmaceutical research organizations increasingly adopt these platforms.
- Positron Emission Tomography:PET imaging uses radiotracers to visualize and quantify amyloid and tau pathologies in the brain, offering direct evidence of disease. Advanced diagnostic centers and clinical trials rely on PET for precise disease characterization.
- Molecular Diagnostics:This technology identifies specific genetic markers or protein isoforms associated with Alzheimer's disease, enabling precise pathological characterization. Research institutes and specialized diagnostic laboratories utilize molecular diagnostics for advanced biomarker detection.
- Magnetic Resonance Imaging:MRI provides detailed structural images of the brain, detecting atrophy patterns indicative of neurodegeneration and excluding other causes of cognitive impairment. Neurology clinics commonly use MRI for initial assessment.
- Electroencephalography:EEG measures electrical activity in the brain to detect abnormalities in brain function, sometimes used to differentiate dementia types or assess cognitive decline. Research institutes explore EEG for non-invasive functional assessment.
The most transformative technology is Artificial Intelligence. Molecular Diagnostics is expanding most quickly.
Application:
The application landscape for Alzheimer's diagnostics is shifting from late-stage confirmation to proactive, early intervention strategies. This transition is driven by the development of disease-modifying therapies that are most effective when administered early.
- Early Detection:This application focuses on identifying Alzheimer's pathology before significant clinical symptoms manifest, enabling earlier therapeutic intervention. Demand for early detection tools stems from a growing emphasis on preventative care and clinical trial recruitment.
- Disease Monitoring:Diagnostics are used to track the progression of Alzheimer's disease and assess the effectiveness of therapeutic interventions over time. Pharmaceutical research and specialized memory clinics extensively utilize disease monitoring applications.
- Differential Diagnosis:These applications distinguish Alzheimer's disease from other forms of dementia or neurodegenerative conditions, ensuring appropriate patient management. Neurology clinics and diagnostic laboratories frequently employ these tools.
- Risk Assessment:Diagnostics evaluate an individual's genetic or biomarker profile to determine their predisposition or likelihood of developing Alzheimer's disease. Research institutes and specialized clinics use risk assessment for personalized health planning.
- Treatment Planning:Diagnostic information guides clinicians in selecting the most appropriate therapeutic strategies for patients, including pharmacological and non-pharmacological interventions. Memory care centers and neurology clinics integrate these insights into patient care pathways.
Early Detection commands the largest volume. Disease Monitoring exhibits the steepest expansion trajectory.
End User:
The diverse range of end users reflects the multi-faceted nature of Alzheimer's diagnosis and management, spanning from high-throughput laboratory services to specialized clinical care and research environments. Each segment has unique procurement needs and operational scales.
- Diagnostic Laboratories:These facilities perform high-volume analysis of cerebrospinal fluid, blood, and genetic samples using automated platforms, serving as a central hub for biomarker testing. Large diagnostic laboratories are investing heavily in high-throughput immunoassays.
- Neurology Clinics:These specialized outpatient facilities integrate clinical assessments, imaging, and biomarker tests to diagnose and manage patients with cognitive impairment. Neurology clinics are increasingly procuring bundled diagnostic solutions that combine hardware, software, and reagents.
- Research Institutes:Academic and pharmaceutical research organizations utilize advanced diagnostic tools for biomarker discovery, clinical trials, and understanding disease mechanisms. Research institutes demand cutting-edge technologies for novel biomarker detection and imaging.
- Memory Care Centers:These specialized facilities provide long-term care for individuals with dementia, utilizing diagnostics for initial assessment, ongoing monitoring, and care planning. Memory care centers focus on practical, patient-centric diagnostic approaches.
- Geriatric Care Facilities:These facilities provide comprehensive medical care for elderly populations, often involving initial screening for cognitive decline and referral for definitive diagnosis. Geriatric care facilities require accessible and non-invasive screening tools.
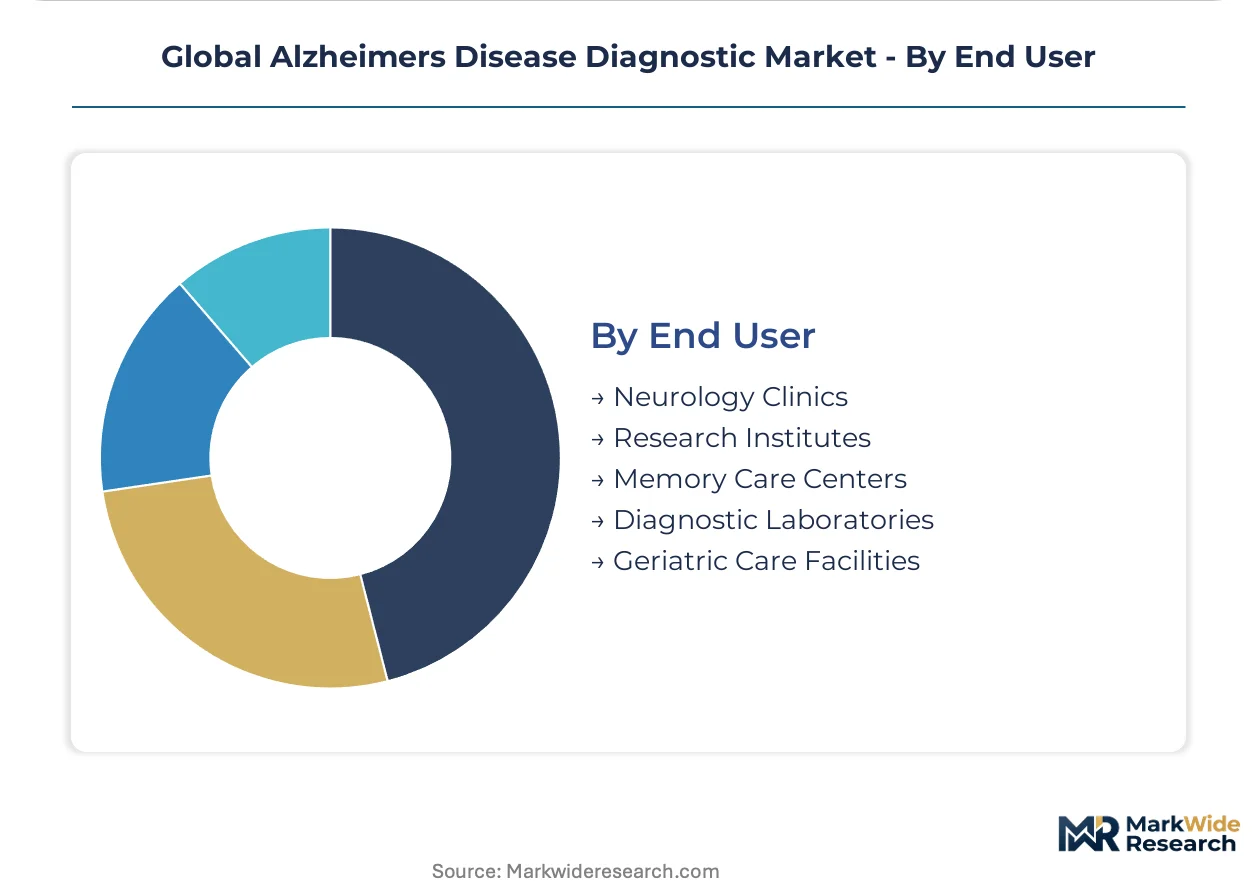
Diagnostic Laboratories represent the largest end-user segment. Neurology Clinics are showing significant growth in integrated solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The foundational understanding of Alzheimer's disease and its pathological markers largely emerged from extensive research conducted in the United States and Western Europe. Early diagnostic advancements in imaging and cerebrospinal fluid analysis were pioneered in these regions. This scientific heritage continues to influence global development and adoption of novel diagnostic tools.
United States
High demand for advanced diagnostics stems from its large aging population and significant research funding. The US FDA's accelerated approval pathways stimulate demand for companion diagnostics. Biotech hubs in Boston and San Francisco drive innovation in fluid biomarker development and AI-powered platforms.
Germany
Europe's largest economy demonstrates strong demand for sophisticated medical technologies and robust healthcare infrastructure. The EMA's rigorous approval processes ensure high diagnostic device standards. Munich and Berlin host significant medical technology clusters, fostering collaboration between research institutions and diagnostic companies.
Japan
A rapidly aging demographic creates immense pressure for early and accurate dementia diagnosis. The PMDA's focus on innovative medical devices supports advanced diagnostic solutions. Tokyo and Kyoto are centers for neurodegenerative disease research, attracting investment in novel blood tests and imaging agents.
China
A vast patient population and expanding healthcare access drive substantial investment in diagnostic capabilities. The NMPA's efforts to streamline medical device approvals facilitate market penetration. Shanghai and Beijing emerge as key innovation hubs for AI-driven diagnostics and high-throughput laboratory services.
United Kingdom
Strong academic research and a well-established National Health Service influence new diagnostic pathway adoption. The MHRA's regulatory guidance shapes product development for the local market. Cambridge and Oxford maintain world-class research clusters, contributing to biomarker discovery and clinical trial advancements.
Global Alzheimers Disease Diagnostic Market Key Industry Players
The competitive structure tilts toward diversified diagnostic conglomerates, complemented by specialized biotech innovators. The market sees a mix of large, established players offering broad diagnostic portfolios and agile firms focusing on niche, high-sensitivity detection methods. Strategic archetypes include integrated healthcare solution providers, specialized biomarker developers, and advanced imaging technology firms. Strategic partnerships between pharmaceutical companies and diagnostic providers, alongside portfolio diversification, are common competitive moves.
Diversified diagnostic players like Siemens Healthineers occupy a strong position, leveraging their extensive imaging device infrastructure. Specialized innovators such as Quanterix exemplify the focus on ultra-sensitive biomarker detection, particularly for emerging blood-based assays. Hoffmann-La Roche, a global pharmaceutical and diagnostics giant, anchors its strategy in molecular diagnostics and broad pharmaceutical research, representing a comprehensive approach to disease management. These companies collectively shape the market's technological trajectory and commercial offerings.
| Leading Market Players |
|---|
| Quest Diagnostics |
| Quanterix |
| Siemens Healthineers |
| Fujirebio |
| Labcorb |
| C2N Diagnostics |
| Lantheus |
| Sysmex |
| Hoffmann-La Roche |
| Others |
Cost & Logistics Intelligence
Diagnostic laboratories' high-volume procurement of biomarker tests and imaging devices influences a hybrid pricing model. This model combines per-test transactional costs with bundled solution contracts for integrated platforms.
Pricing Analysis
Hybrid pricing, combining per-test transactional models with integrated solution bundles, characterizes the Alzheimer's diagnostics market. Price differentiation stems from technology sophistication in AI-powered imaging and ultra-sensitive biomarker assays, alongside comprehensive after-sales support for complex diagnostic instruments. Pricing pressure intensifies for high-volume blood tests due to market expansion and increasing competition. Geriatric care facilities exhibit the highest price sensitivity, while research institutes prioritize advanced capabilities over cost.
Supply Chain Analysis
Regional distribution centers manage the complex logistics for Alzheimer's diagnostic products, including temperature-sensitive reagents and high-value imaging equipment. Supply concentration for advanced diagnostic components primarily resides in the United States, Germany, and Japan. The market draws from specialized reagents for biomarker tests and proprietary AI software components. Single-source vulnerability for niche radiotracers or ultra-sensitive assay components poses a structural risk. Distribution runs through specialized healthcare logistics providers and direct manufacturer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Alzheimer's disease diagnostic market functions as a stable compounder, driven by global aging demographics and the persistent need for early, accurate diagnosis. Therapies requiring biomarker-driven patient selection further solidify this growth trajectory.
For Market Incumbents: Acquire specialized AI analytics firms to enhance existing imaging device portfolios and integrate advanced quantification capabilities. Incumbents should also target ultra-sensitive blood test developers to counter market disruption from less invasive screening methods. Invest in R&D for multiplex diagnostic panels to address the threat of emerging blood-based assays. Strengthen channel control within diagnostic laboratories to maintain market share against new entrants.
For New Entrants and Emerging Players: Enter via non-invasive blood tests, particularly targeting primary care settings for early Alzheimer's screening. Focus on Japan's rapidly aging demographic, where demand for accessible diagnostic technologies is high. Develop AI-powered cognitive assessment software that integrates seamlessly with existing electronic health records. The go-to-market angle should emphasize cost-effectiveness and scalability to facilitate widespread adoption.
For Investors and Strategic Acquirers: Diversified diagnostic conglomerates and large pharmaceutical companies are the most active acquirers in this space, seeking to expand their neurodegenerative portfolios. The market offers long-term viability over the next decade, underpinned by the emergence of disease-modifying therapies necessitating precise companion diagnostics. Target biotech firms specializing in novel fluid biomarkers or advanced AI diagnostic algorithms. The signal to watch is regulatory approvals for new blood-based biomarkers from the US FDA or Europe's EMA.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Partnership | Accelerates biomarker validation and regulatory submission timelines for novel diagnostics. |
| Product Portfolio Diversification | Expands offerings across imaging, fluid biomarkers, and cognitive tools to capture broader market share. |
| AI Platform Integration | Enhances diagnostic accuracy and throughput for imaging analysis, reducing subjectivity in clinical assessments. |
| Geographic Market Entry (Japan) | Accesses a rapidly aging demographic with high demand for early dementia diagnosis solutions. |
| Reimbursement Advocacy | Secures favorable coverage policies for advanced diagnostic tests, improving patient access and clinical adoption. |
Research Approach
Direct dialogue with neurology clinic directors, diagnostic laboratory managers, pharmaceutical R&D leads, and regulatory affairs specialists informed this analysis. Primary insights were triangulated with extensive secondary research from US FDA filings, EMA submissions, ClinicalTrials.gov, and peer-reviewed academic journals. This approach enabled comprehensive bottom-up and top-down validation of market dynamics and trends.
Quantitative market size and growth projections were generated across the analysis window, segmented by product type, technology, application, end-user, and regional regulatory frameworks. Compound annual growth rates were derived from historical data analysis and projected future trends. Key forecast inputs included Alzheimer's disease prevalence rates and regulatory approval timelines for novel diagnostic technologies.
The model holds under conditions of a stable regulatory environment and consistent research funding; deviation in unforeseen therapeutic breakthroughs or significant shifts in reimbursement policies would alter projections. Forecasts reflect assumptions regarding clinical adoption rates and technological advancements. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
North America and Europe Companion Animal Diagnostics Imaging Market
Diagnostics
Human Immunodeficiency Virus Rapid Test Kit Market
Diagnostics
Singleplex Immunoassay Market
Diagnostics
Global HIV/AIDS Diagnostics Market
Diagnostics
Allergy Diagnostics Market
Diagnostics
Complement C3 ELISA Kits Market
Diagnostics
Viral Molecular Diagnostics Market
Diagnostics
Acute Ischemic Stroke Diagnosis Market
Diagnostics
India in-Vitro Diagnostics Market
Diagnostics
Global Liver Disease Diagnostics Market
Diagnostics
China in Vitro Diagnostics Market
Diagnostics
Thyroid Cancer Diagnostics Market
Diagnostics
Tuberculosis (TB) Diagnostics Market
Diagnostics
Antigen Skin Test Market
Diagnostics
HIV Diagnostics Market
Diagnostics
HDL Cholesterol Kits Market