
 Diagnostic Testing of Stds Market | 2026-2036
Diagnostic Testing of Stds Market Size, Share, and Industry Trends Forecast 2026-2036
Diagnostic Testing of Stds Market Analysis
Buyer concentration among hospital systems and large outpatient networks is shifting procurement toward bundled diagnostic contracts that span multiple STD pathogens. Abbott leverages its installed base of automated immunoassay platforms to sustain recurring reagent revenue across integrated delivery networks. Roche competes through centralized laboratory molecular diagnostics, while Hologic anchors its position in women's health screening with nucleic acid amplification technologies for chlamydia and gonorrhea detection.
Diagnostic testing of STDs encompasses laboratory and point-of-care methods that detect bacterial, viral, and parasitic sexually transmitted pathogens through nucleic acid amplification, antigen-antibody binding reactions, or rapid lateral flow chromatography, with sensitivity specifications typically exceeding 95% for FDA-cleared molecular assays. These tests serve public health surveillance, individual treatment decisions, and partner notification protocols across clinical and non-clinical settings. Molecular diagnostics leads in revenue contribution due to superior sensitivity for asymptomatic screening, while rapid testing captures expanding volume in urgent care and community health venues where same-day results drive treatment initiation. Home testing kits represent the fastest-growing delivery mode segment as digital platforms integrate self-collection with telemedicine consultation and electronic prescription fulfillment.
The FDA regulates in vitro diagnostic devices through premarket notification and premarket approval pathways, with recent de novo classifications enabling over-the-counter HIV self-tests that bypass clinical gatekeepers. CLIA certification requirements shape laboratory participation, while CMS reimbursement determinations directly influence provider test menu expansion decisions. Stakeholders must monitor evolving FDA guidance on multiplex panel claims and CMS coverage policies for emerging pathogen targets as these regulatory signals determine viable commercialization pathways and capital allocation priorities.
Market Dynamics
Integrated delivery networks in the United States are consolidating procurement authority, forcing diagnostic manufacturers to restructure pricing and service models around multi-year reagent supply agreements rather than instrument placement economics.
Growth Catalysts
- CLIA-waived molecular platforms:The FDA's expansion of waived complexity categories enables nucleic acid amplification testing in physician office laboratories without specialized personnel.
- Telemedicine-integrated home collection:Digital health platforms in the United States now bundle self-sampling kits with synchronous video consultation and electronic prescribing.
- CDC screening guidelines:Expanded recommendations for extragenital chlamydia and gonorrhea testing drive volume in men who have sex with men populations.
Market Restraints
- Reimbursement compression:CMS fee schedule reductions for high-throughput molecular codes squeeze margin on automated platforms.
- Supply concentration in oligonucleotide synthesis:Three contract manufacturers control specialized probe production, creating single-source vulnerability.
- Laboratory workforce shortages:Medical technologist pipeline constraints in the United States limit test menu expansion regardless of instrument capacity.
Strategic Opportunities
- Over-the-counter multiplex panels:The FDA's de novo pathway for combined HIV-syphilis self-tests opens consumer-direct channels previously restricted to clinical gatekeepers.
- Pharmacy-based screening networks:MinuteClinic and similar retail health models in the United States seek turnkey diagnostic partnerships for same-day result delivery.
- CRISPR-based detection convergence:Guide RNA-programmed diagnostics promise instrument-agnostic deployment with sensitivity matching laboratory PCR.
Industry Challenges
- LIMS integration complexity:Hospital information systems require months of validation for new instrument interfaces, delaying contract start dates.
- Quality control material scarcity:Proficiency testing providers struggle to source characterized clinical specimens for emerging pathogen targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diagnostic Testing of Stds Market |
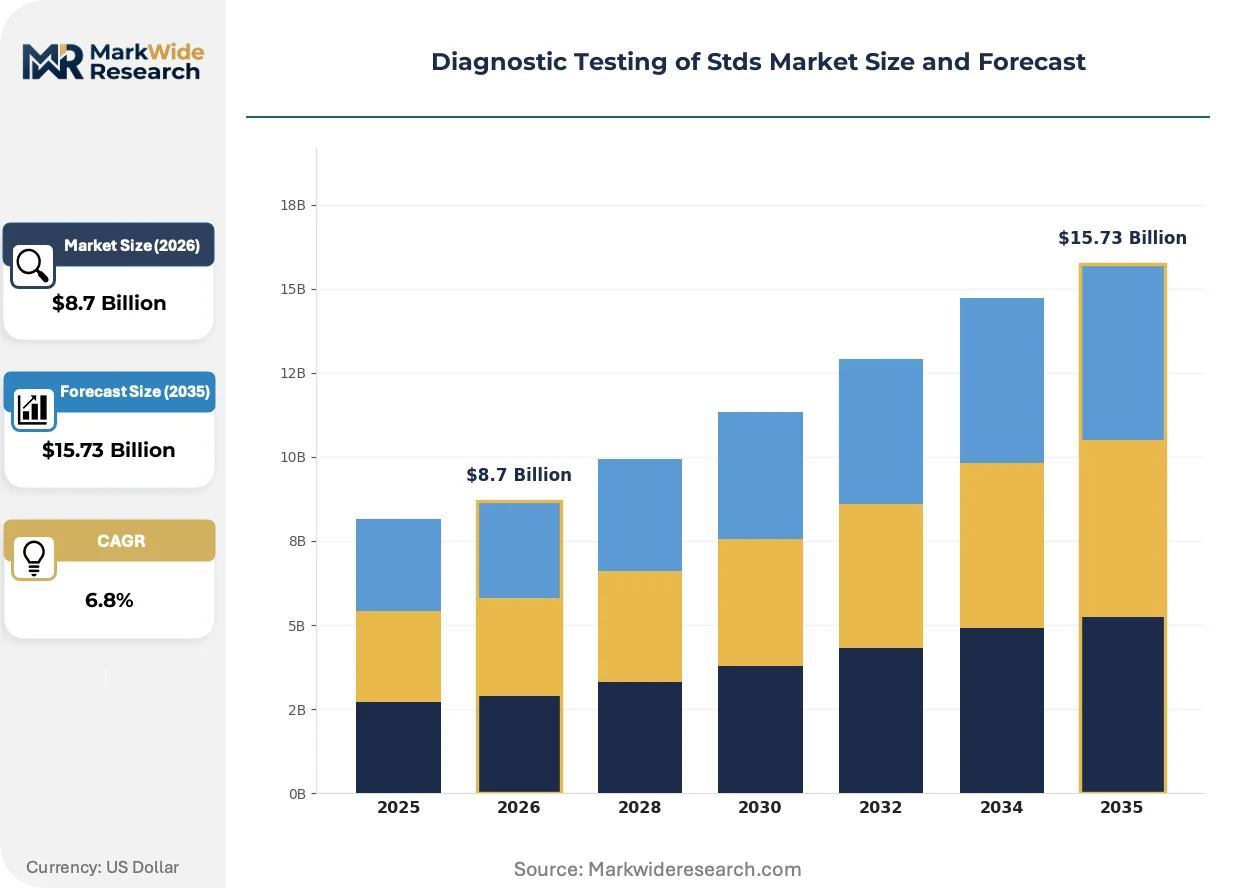
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Tests, Urine Tests, Swab Tests, Home Testing Kits Technology: Molecular Diagnostics, Immunoassays, Nucleic Acid Amplification, Rapid Testing End User: Clinics, Hospitals, Home Care, Laboratories Delivery Mode: Self-Collection, Point-of-Care, Lab Testing, Digital Platforms |
| Companies Covered | Roche, Abbott, Hologic, Becton Dickinson, bioMérieux, Danaher, Thermo Fisher Scientific, Bio-Rad Laboratories, DiaSorin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diagnostic Testing of Stds Market Emerging Trajectories
Automation and miniaturization are compressing the sensitivity gap between centralized laboratories and distributed testing sites, while regulatory frameworks struggle to keep pace with self-collection modalities.
CRISPR-Dx platforms are electrifying point-of-care detection by eliminating thermal cycling requirements. Urgent care chains in the United States are piloting instrument-free workflows that reduce capital deployment per site. This convergence is electrifying decentralized testing economics and pressuring traditional platform vendors to unbundle hardware from consumable commitments.
The FDA's evolving guidance on over-the-counter HIV self-tests is creating precedent for bypassing clinical intermediaries. Manufacturers must now design for consumer comprehension rather than laboratory technician training. Women's health screening programs represent the most affected segment, with several applicants pursuing combined chlamydia-gonorrhea home collection claims.
Hospital systems are consolidating reference laboratory send-outs into captive regional hubs. Physician practices respond by demanding integrated result reporting across multiple health information exchanges. This concentration is most visible in the United States, where three national networks now control over half of outpatient molecular volume.
Diagnostic Testing of Stds Market Segmentation
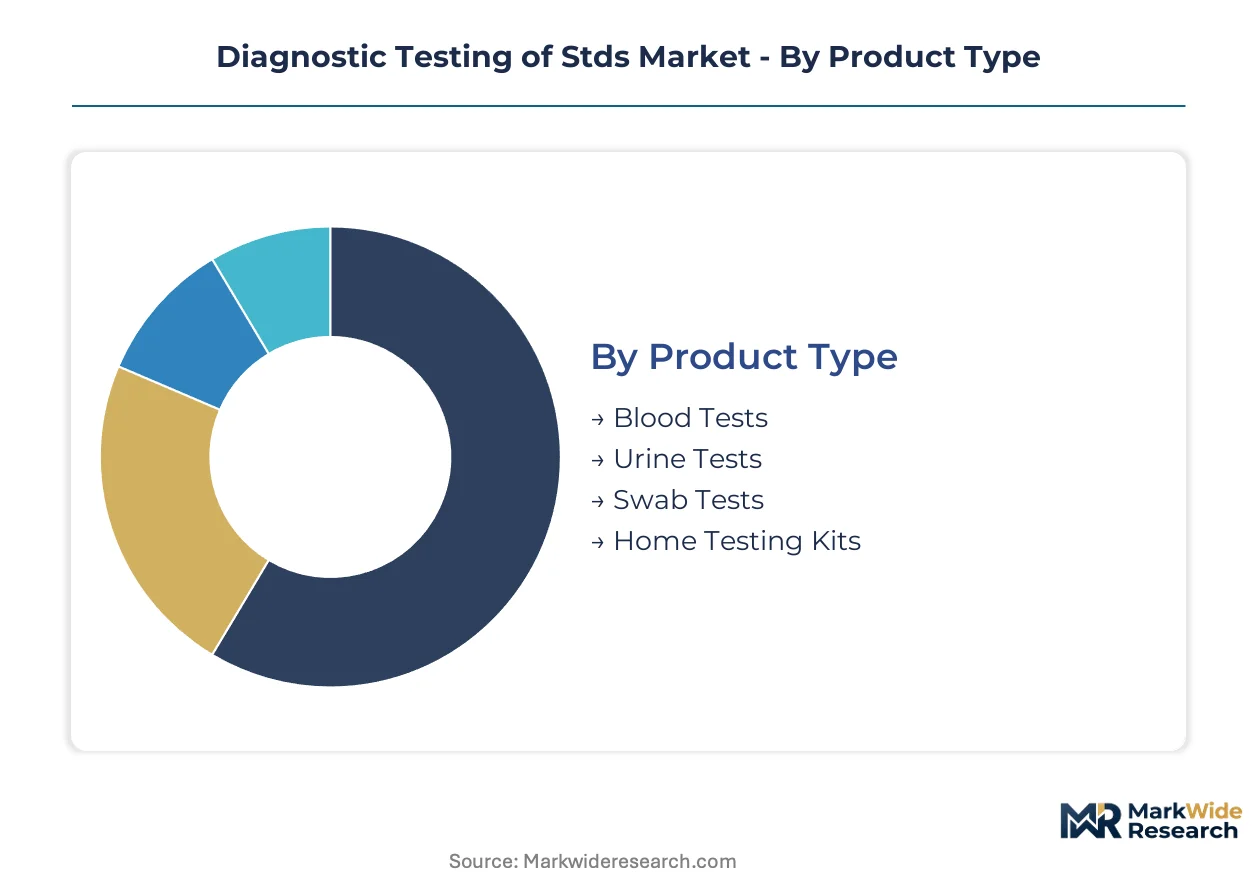
Segmentation in STD diagnostics reveals how technology choices and care settings determine procurement patterns. Upgrade cycles vary dramatically across product categories, with molecular platforms requiring 5-7 year replacement horizons while rapid test consumables turn continuously.
Product Type:
Replacement cycles differ sharply across specimen categories, driving divergent vendor engagement strategies and reagent contracting models.
- Home Testing Kits:Self-collection devices integrate dried blood spot cards, urine collection vessels, and oropharyngeal/rectal swabs with prepaid logistics. Demand concentrates in United States metropolitan corridors where telemedicine laws permit asynchronous prescribing, constrained by state-level laboratory licensing requirements for out-of-state specimen processing.
- Blood Tests:Serum and plasma-based serology detects HIV, syphilis, and hepatitis B/C antibodies through chemiluminescent or ELISA methods. Hospital laboratories in the United States anchor volume through emergency department screening protocols, with HIV fourth-generation antigen-antibody combination assays commanding premium pricing over standalone antibody tests.
- Urine Tests:First-void urine specimens enable nucleic acid detection of Chlamydia trachomatis and Neisseria gonorrhoeae without invasive collection.
- Swab Tests:Endocervical, urethral, and extragenital swabs retain dominance in symptomatic patient evaluation.
Home Testing Kits sit at the top of the volume ranking, with Home Testing Kits climbing the fastest.
Technology:
Cost tiers separate capital-intensive automated platforms from disposable rapid formats, reshaping how manufacturers structure pricing and service commitments.
- Molecular Diagnostics:Polymerase chain reaction and transcription-mediated amplification achieve analytical sensitivity below 100 copies per milliliter for asymptomatic detection. Centralized laboratories in the United States deploy high-throughput systems with random-access capabilities, with CMS reimbursement compression forcing consolidation onto fewer instrument lines.
- Rapid Testing:Lateral flow immunochromatography delivers qualitative results in 15-20 minutes without laboratory infrastructure. Urgent care chains and community health centers in the United States drive volume through same-day treatment initiation requirements, with CLIA-waived complexity designations expanding permissible operator pools.
- Nucleic Acid Amplification:Isothermal amplification methods reduce thermal cycling requirements for near-patient deployment.
- Immunoassays:Enzyme-linked and chemiluminescent methods dominate high-volume serology screening.
Molecular Diagnostics commands the highest revenue tier, while Rapid Testing gains share fastest through decentralized deployment.
End User:
Customer type determines test menu breadth, with integrated networks negotiating system-wide contracts against standalone facility purchasing.
- Laboratories:Hospital-based and reference laboratories process high-complexity molecular testing with full CLIA certification. Academic medical centers in the United States anchor demand through research-protocol screening volumes, with laboratory information system integration requirements extending sales cycles to 12-18 months.
- Clinics:Outpatient facilities range from federally qualified health centers to private OB/GYN practices with varying test sophistication. Family planning clinics in the United States concentrate chlamydia and gonorrhea screening volume under Title X funding streams, with 340B drug pricing program eligibility influencing site selection for manufacturer patient assistance programs.
- Hospitals:Inpatient and emergency department settings drive acute screening for HIV and syphilis.
- Home Care:Direct-to-consumer channels bypass clinical intermediaries through digital platform integration.
Laboratories sit at the top of the volume ranking, with Home Care climbing the fastest.
Delivery Mode:
Supply concentration in specimen logistics creates margin pressure as manufacturers internalize shipping and processing coordination.
- Digital Platforms:Telemedicine-integrated services combine self-collection kit dispatch, video consultation, electronic prescribing, and result delivery through unified interfaces. Venture-backed startups in the United States compete on turnaround time compression, with 24-hour result-to-treatment pathways now standard in urban markets.
- Point-of-Care:Physician office laboratories and retail health clinics perform waived-complexity testing during patient encounters. MinuteClinic locations and similar retail health models in the United States expand screening access in pharmacy-anchored settings, with turnkey operational partnerships reducing capital requirements for retail operators.
- Lab Testing:Traditional send-out and reference laboratory processing retains dominance for complex panels.
- Self-Collection:Unsupervised specimen acquisition with mail-back logistics enables privacy-prioritized screening.
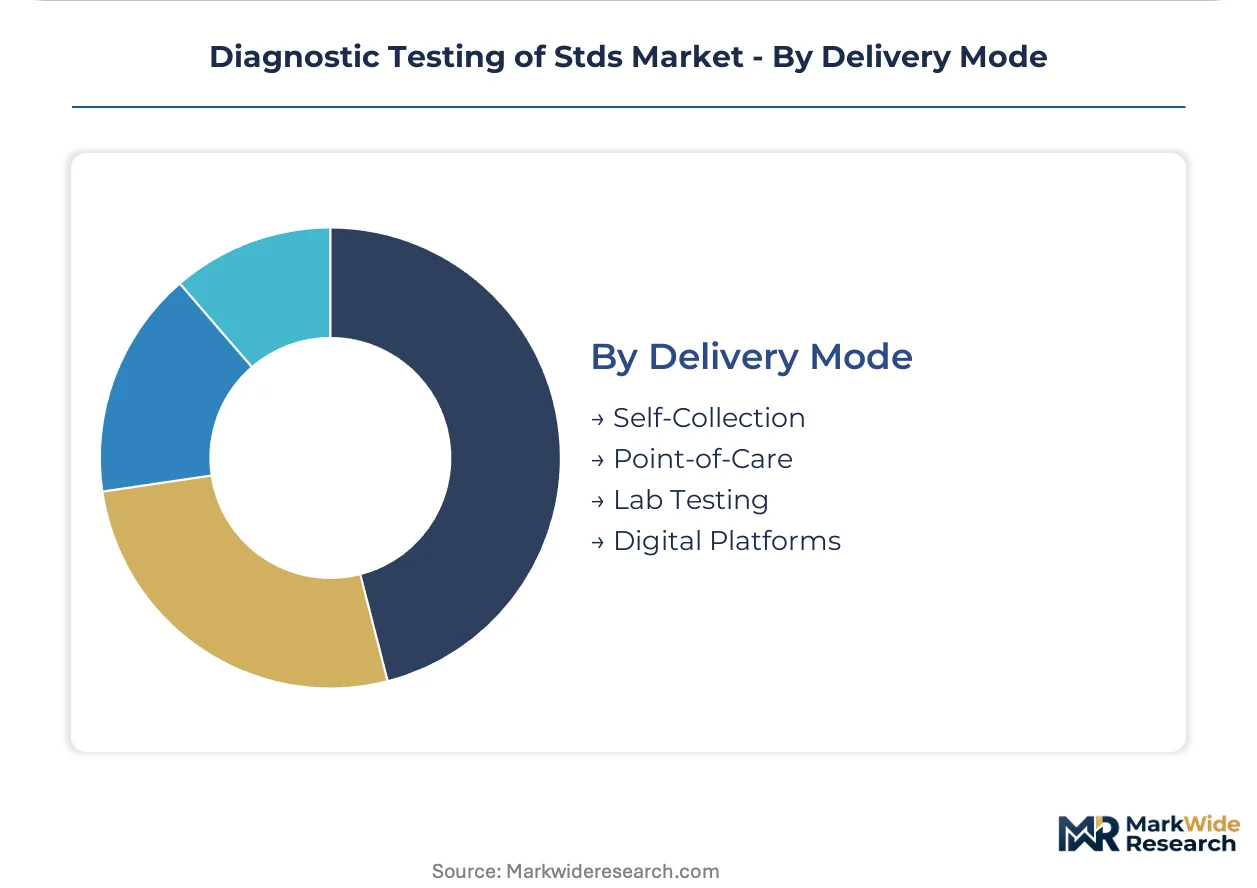
Lab Testing sits at the top of the volume ranking, with Digital Platforms climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates procurement authority through integrated delivery networks while Germany anchors European laboratory consolidation, creating divergent competitive dynamics across the two largest diagnostic markets.
United States
Hospital systems and large outpatient networks drive demand through bundled procurement contracts spanning multiple STD pathogens. FDA guidance on over-the-counter HIV and hepatitis C self-tests reshapes product development priorities for domestic manufacturers. Academic medical centers in Boston and the Research Triangle anchor high-complexity molecular testing volume.
Germany
Centralized laboratory networks process screening volume through regional reference hubs serving multiple hospital systems. EMA and national health technology assessment frameworks influence test reimbursement and adoption timelines. The Rhine-Ruhr metropolitan region concentrates diagnostic manufacturing and clinical research infrastructure.
United Kingdom
NHS integrated care boards negotiate system-wide screening contracts, consolidating previously fragmented procurement. MHRA post-Brexit regulatory pathways create distinct approval timelines from continental European markets. London and the Greater Manchester health innovation clusters pilot digital platform integration with self-collection services.
France
Regional hospital agencies coordinate public health screening programs through centralized laboratory networks. ANSM oversight of in vitro diagnostics shapes market entry requirements for novel detection platforms. The Paris-Saclay biomedical cluster supports nucleic acid amplification technology development.
Japan
PMDA regulatory frameworks maintain distinct approval requirements from Western markets, influencing manufacturer market entry sequencing. METI industrial policy supports domestic diagnostic platform development. The Kanto region around Tokyo concentrates hospital laboratory capacity and reference testing infrastructure.
Diagnostic Testing of Stds Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across instrument, reagent, and service segments. The market structure shows moderate consolidation at the platform level with fragmentation in rapid test consumables. Three strategic archetypes dominate: diversified life science conglomerates with broad diagnostic portfolios, women's health specialists with concentrated screening expertise, and emerging digital health platforms integrating self-collection with telemedicine. Competitive moves center on multi-year reagent supply agreements replacing instrument placement economics, and regulatory pathway navigation for over-the-counter claims.
Among diversified diagnostic conglomerates, Roche and Abbott exemplify platform-scale competitors leveraging installed instrument bases for recurring consumable revenue. Hologic occupies a focused position within women's health screening, anchoring nucleic acid amplification expertise for chlamydia and gonorrhea detection. These three companies represent contrasting strategic postures: broad laboratory automation, integrated delivery network contracting, and specialized clinical segment concentration.
| Leading Market Players |
|---|
| Roche |
| Abbott |
| Hologic |
| Becton Dickinson |
| bioMérieux |
| Danaher |
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| DiaSorin |
| Others |
Supply Flow & Price Mechanics
Captive integration into oligonucleotide synthesis anchors both supply security and pricing power for molecular diagnostic manufacturers, as three contract manufacturers control specialized probe production and FDA-cleared reagent sourcing determines competitive positioning in United States hospital networks.
Pricing Analysis
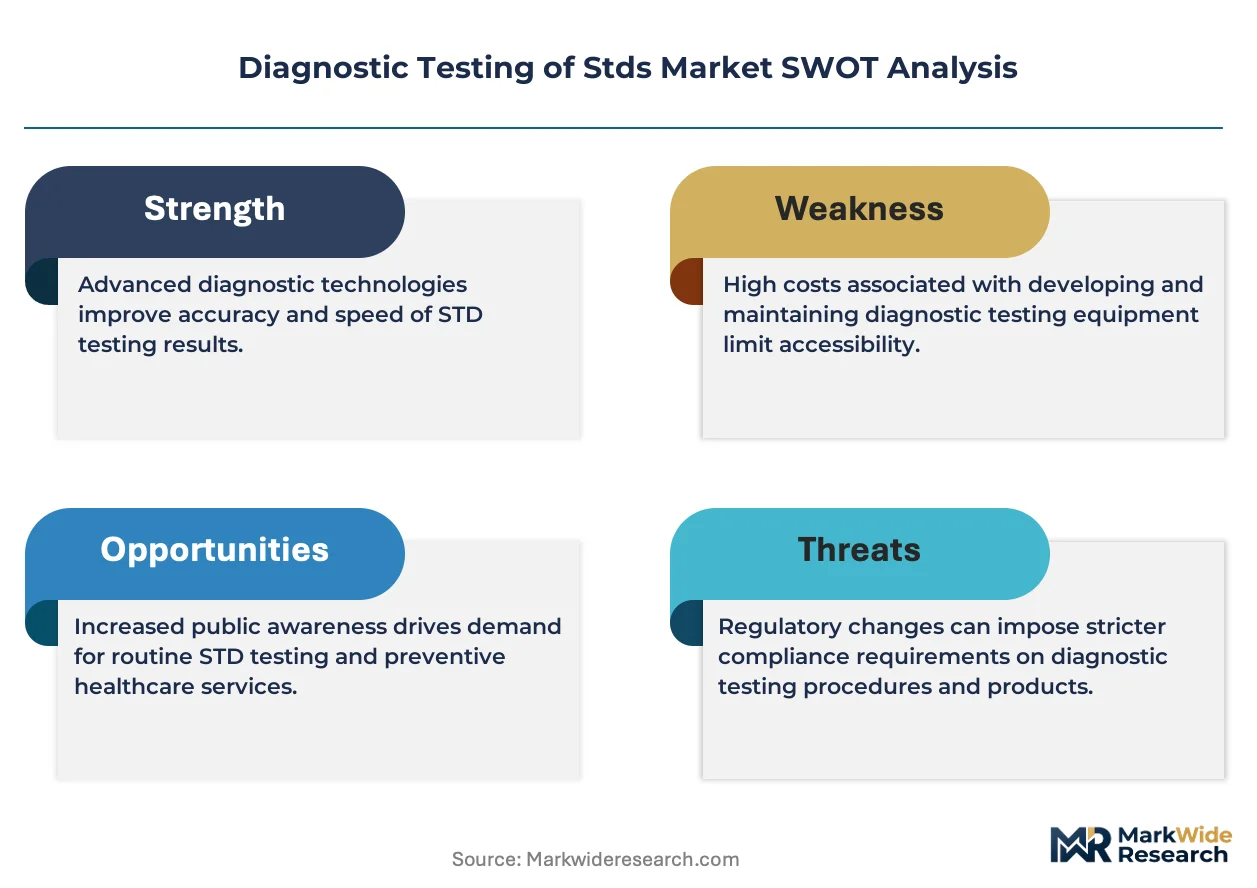
Capacity additions in South Korea and Germany are reshaping price floors for chemiluminescent immunoassay components. Contract-based long-term reagent supply agreements dominate, with price differentiation resting on CLIA certification tier and instrument platform lock-in. Cost compression in high-throughput molecular codes intensifies because CMS fee schedule reductions squeeze automated platform margins. Federally qualified health centers exhibit highest price sensitivity; academic medical centers anchored to research protocols show lowest.
Supply Chain Analysis
FDA premarket notification and CE marking pathways gate supplier qualification timelines, extending vendor onboarding to 18-24 months. Manufacturing concentrates in the United States, Germany, and China for instrument assembly, with specialized probe synthesis anchored in the United States and Singapore. Raw material dependencies include oligonucleotide primers, magnetic bead substrates, and fluorophore conjugates. Single-source vulnerability in probe production creates structural risk. Distribution runs through integrated delivery network consolidated procurement and regional reference laboratory hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory milestones into demand inflections, with FDA de novo classifications for over-the-counter HIV self-tests creating precedent for bypassing clinical gatekeepers and expanding addressable population.
For Market Incumbents: Anticipate CRISPR-Dx platform displacement by securing exclusive reagent supply agreements with emerging guide RNA manufacturers before instrument-agnostic workflows commoditize hardware economics. Defend installed base through multi-year consumable contracts spanning integrated delivery network consolidation. Prioritize CLIA-waived complexity expansion to capture physician office laboratory volume. For New Entrants and Emerging Players: Enter via pharmacy-based screening networks where MinuteClinic and similar retail health models seek turnkey diagnostic partnerships without capital deployment. Target urgent care chains in United States metropolitan corridors for same-day result delivery white space. Pursue combined chlamydia-gonorrhea home collection claims through FDA de novo pathway as the most penetrable regulatory opening. For Investors and Strategic Acquirers: Roll-up economics work for digital health platforms integrating self-collection with telemedicine because state-level laboratory licensing requirements create geographic fragmentation defensible through regulatory arbitrage. Long-term viability hinges on reimbursement strategy execution and CMS coverage policy navigation. Watch FDA guidance on multiplex panel claims as the inflection signal determining viable commercialization pathways.| Strategic Initiative | Industry Significance |
|---|---|
| FDA De Novo Pathway Navigation | Over-the-counter HIV-syphilis self-test approvals bypass clinical gatekeepers and expand consumer-direct channels. |
| CLIA-Waived Platform Expansion | FDA complexity category expansion enables nucleic acid amplification in physician office laboratories without specialized personnel. |
| Integrated Delivery Network Partnership | Multi-year reagent supply agreements with hospital systems replace instrument placement economics with recurring revenue. |
| Telemedicine Platform Integration | Digital health bundling of self-sampling kits with video consultation compresses result-to-treatment pathways to 24 hours. |
| CRISPR-Dx Technology Licensing | Guide RNA-programmed diagnostics eliminate thermal cycling and enable instrument-free urgent care deployment. |
Methodological Framework
Multiple input streams — primary interviews with diagnostic platform executives, CLIA laboratory directors, and GPO contracts managers; secondary validation through FDA 510(k) filings, CMS Medicare fee schedules, and hospital procurement databases — were reconciled through bottom-up instrument placement tracking and top-down reimbursement flow analysis.
Historical instrument install base trajectories were cross-referenced against panel input from reference laboratory operations heads to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include technology tier, delivery mode, end-user facility type, and regional regulatory cluster. CAGRs were derived from reagent consumption velocity patterns and test menu expansion timelines, with CLIA-waived category expansion and telemedicine law changes as industry-specific forecast inputs.
Inputs from FDA premarket notification databases and CMS national coverage determinations were available through the study window; gaps in real-time integrated delivery network contract terms introduce uncertainty bands around vendor market share assumptions. A model refresh is warranted upon material change in FDA guidance on multiplex panel claims or CMS reimbursement determinations for emerging pathogen targets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Alzheimer's Disease Diagnostics and Therapeutics Market
Diagnostics
Creatinine Test Market
Diagnostics
Haptoglobin Reagent Market
Diagnostics
United Kingdom in-Vitro Diagnostics Market
Diagnostics
Fungal Antigens Market
Diagnostics
North America Molecular Diagnostics Market
Diagnostics
Non-Alcoholic Steatohepatitis (NASH) Biomarkers Market
Diagnostics
BNP and NT-Probnp Market
Diagnostics
Global Liver Disease Diagnostics Market
Diagnostics
HIV Diagnostics Market
Diagnostics
Hepatitis E Diagnostic Tests Market
Diagnostics
EMEA Meningitis Diagnostic Testing Market
Diagnostics
Global Respiratory Diagnostics Market
Diagnostics
Rapid Diagnostics Market
Diagnostics
Veterinary Diagnostics Market
Diagnostics
Predictive Disease Analytics Market