
 Rapid Influenza Diagnostic Tests (RIDT) Market | 2026-2036
Rapid Influenza Diagnostic Tests (RIDT) Market Size, Share, and Industry Trends Forecast 2026-2036
Rapid Influenza Diagnostic Tests (RIDT) Market Analysis
East Asian diagnostic reagent manufacturers is repositioning global supply chains toward higher-margin immunoassay components. Abbott leverages integrated lateral-flow manufacturing to sustain cost leadership across high-volume hospital contracts. Quidel Corporation anchors its competitive stance through proprietary molecular amplification technology in combination test formats. Roche differentiates via centralized lab connectivity solutions that bridge point-of-care instruments with enterprise health networks.
Rapid Influenza Diagnostic Tests are immunochromatographic or optical biosensor devices that detect influenza A and B viral antigens in respiratory specimens within 15 minutes, employing monoclonal antibodies conjugated to colored nanoparticles or fluorescent reporters for visual or instrument-read signal generation. These devices serve the primary commercial purpose of enabling clinical triage decisions during acute respiratory illness presentations before laboratory confirmation. Combination tests capturing both Flu A and Flu B antigens command the dominant share of procurement budgets due to their utility in undifferentiated febrile respiratory cases during overlapping circulation periods. Point-of-care delivery mode exhibits the fastest structural expansion as CLIA-waived platforms displace send-out workflows in urgent care settings. Multiplex test formats represent the concentrated margin pool where respiratory pathogen panel integration justifies premium positioning.
FDA oversight through the CLIA waiver program and EPA antimicrobial device standards shape product development pathways and facility placement eligibility for RIDT manufacturers. EMA's In Vitro Diagnostic Regulation imposes new clinical evidence requirements that filter market access for European distribution. Stakeholders must monitor evolving FDA dual-claim pathways for combined COVID-19 and influenza detection as these reshape R&D allocation and capital deployment priorities across the competitive set.
Market Dynamics
CLIA-waived platform proliferation is compressing traditional send-out laboratory workflows into fifteen-minute bedside decision cycles, fundamentally restructuring how acute respiratory presentations are triaged across emergency medicine.
Growth Catalysts
- FDA CLIA Waiver Pathway:Streamlined premarket review for waived complexity devices accelerates product placement in physician office laboratories and urgent care settings.
- Hospital Emergency Department Triage:Bedside antigen detection reduces isolation precaution duration and optimizes antiviral stewardship decisions during seasonal surge periods.
- Multiplex Respiratory Panel Integration:Combined influenza and COVID-19 detection formats consolidate testing workflows and capture bundled reimbursement codes.
Market Restraints
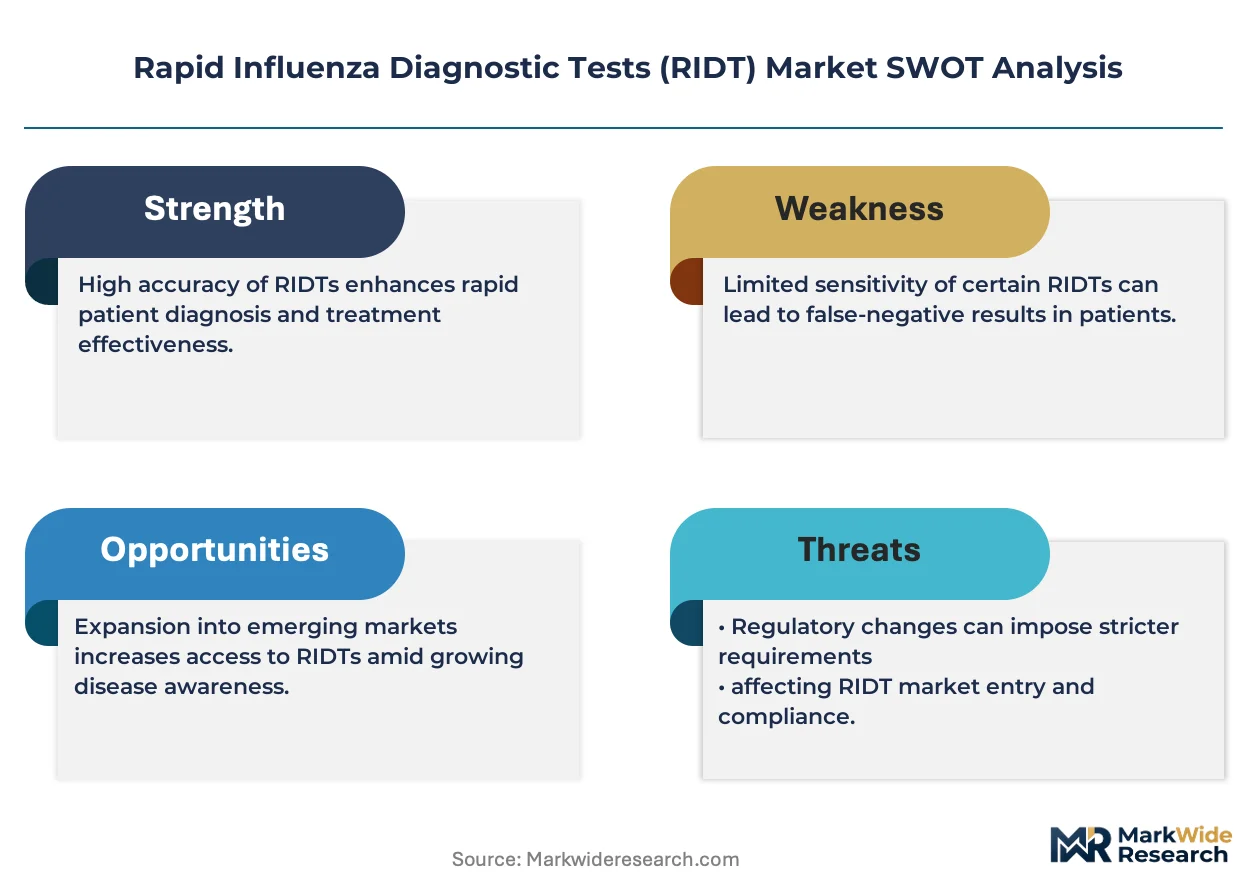
- Antigen Sensitivity Limitations:Lateral-flow immunochromatography exhibits reduced detection rates in low-viral-load specimens compared to nucleic acid amplification methods.
- East Asian Reagent Concentration:Nitrocellulose membrane and conjugated nanoparticle supply chains cluster among specialized chemical manufacturers in China and South Korea.
- Seasonal Demand Volatility:Northern hemisphere winter circulation patterns create concentrated procurement windows with extended inventory holding costs during off-peak months.
Strategic Opportunities
- Home-Based Self-Testing Channels:Over-the-counter distribution through retail pharmacy networks addresses consumer demand for pre-visit screening.
- EMA IVDR Clinical Evidence Pathways:Harmonized performance study requirements create transparent market access conditions for manufacturers seeking European commercialization.
- Telehealth Integration Workflows:Digital result capture and remote clinician consultation platforms embed diagnostic data into virtual care delivery models.
Industry Challenges
- Lateral-Flow Manufacturing Scale-Up:Precision coating and assembly automation demands significant capital deployment for quality-controlled high-throughput production.
- Cross-Reactivity Validation Burden:Extensive analytical specificity testing against circulating respiratory pathogens extends development timelines for new assay formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rapid Influenza Diagnostic Tests (RIDT) Market |
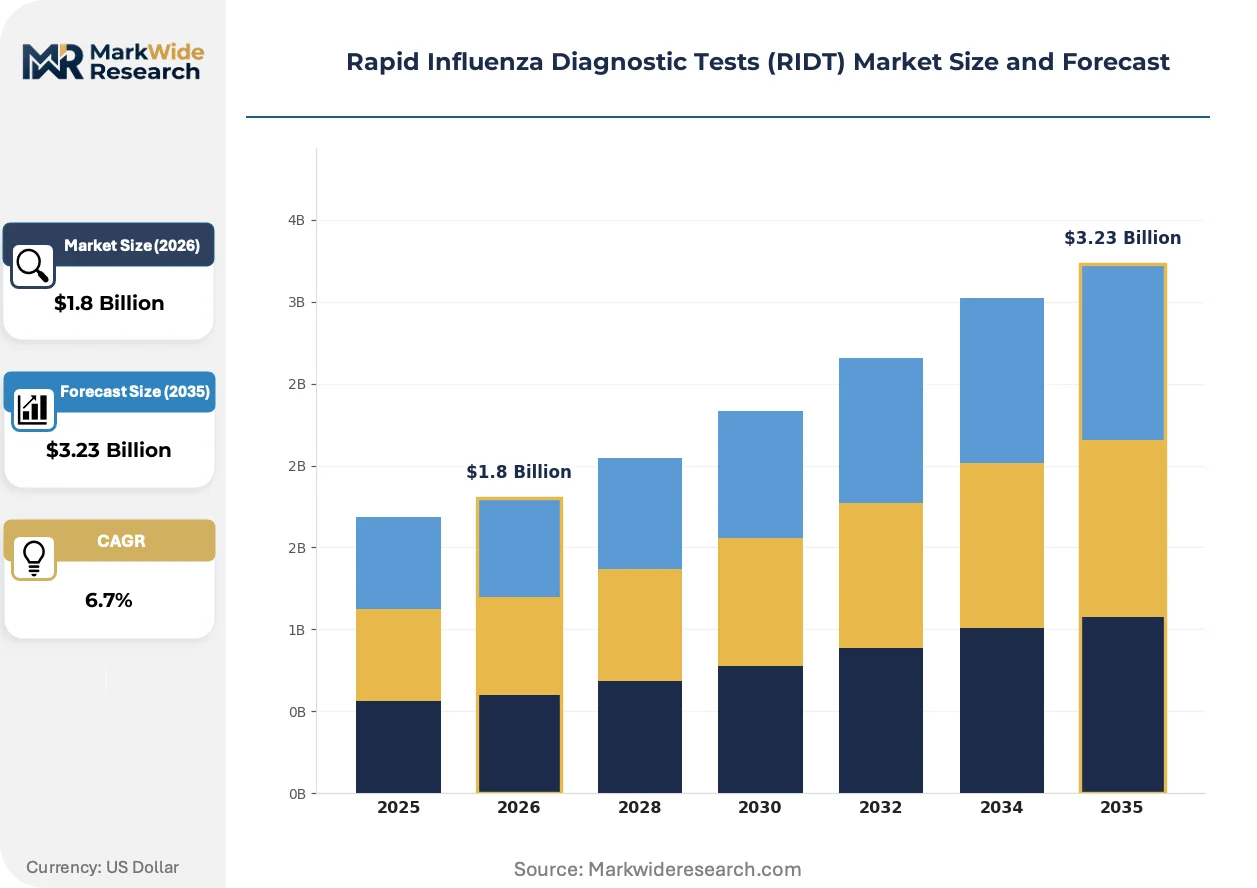
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flu A Test, Flu B Test, Combination Test, Multiplex Test End User: Hospitals, Clinics, Laboratories, Emergency Departments Delivery Mode: Point-of-Care, Rapid Testing, Lab Testing, Home Testing Application: Clinical Diagnostics, Screening, Surveillance, Research |
| Companies Covered | Abbott, Quidel Corporation, Roche, Thermo Fisher Scientific, Becton Dickinson and Company, DiaSorin, Meridian Bioscience, Siemens Healthineers, bioMérieux, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rapid Influenza Diagnostic Tests (RIDT) Market Emerging Trajectories
Digital biosensor readout systems and cloud-connected result reporting are displacing visual interpretation dependence, while regulatory convergence around combined respiratory pathogen claims reshapes product development priorities.
Fluorescence-based optical detection systems is expanding into hospital-based point-of-care settings where instrument-read quantitative outputs support antiviral treatment algorithms. Emergency medicine departments and urgent care networks in the United States are deploying these platforms to reduce subjective interpretation errors. The technology is expanding into higher-acuity clinical environments where sensitivity thresholds influence isolation and treatment decisions.
EMA's In Vitro Diagnostic Regulation imposes strengthened clinical evidence requirements for self-testing and near-patient devices entering European distribution. Manufacturers must generate prospective performance data across intended-use populations rather than relying on analytical bridging studies. Multiplex assay developers targeting combined influenza and respiratory syncytial virus claims face the most extensive documentation burdens under these revised conformity assessment procedures.
Hospital procurement committees are consolidating respiratory testing contracts around integrated platform vendors who supply both rapid antigen and molecular confirmation modalities. Single-source agreements reduce vendor management overhead and standardize operator training across nursing units. This concentration pattern is most visible in United States health system networks where value-based care contracts incentivize total cost-of-testing optimization over per-test pricing.
Rapid Influenza Diagnostic Tests (RIDT) Market Segmentation
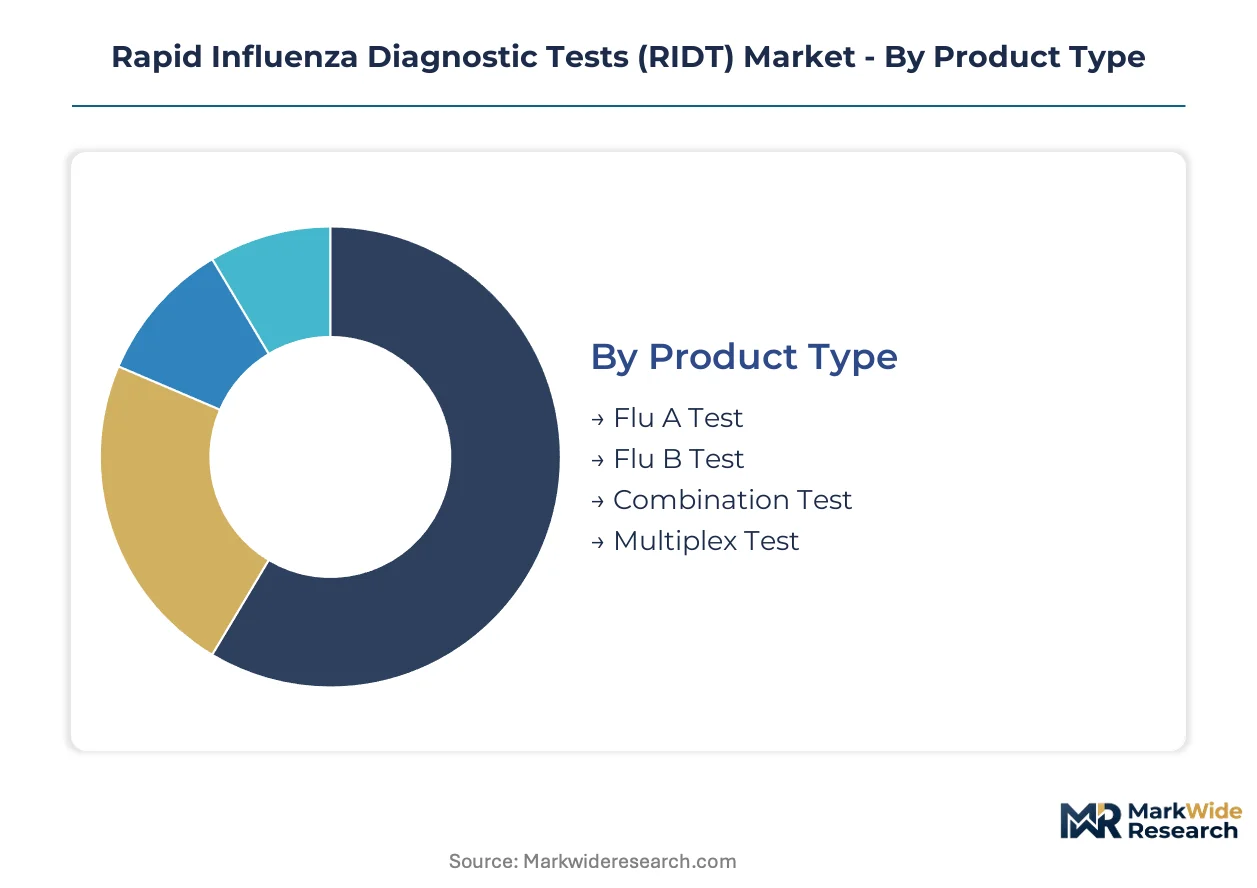
Segmentation in the RIDT market reveals distinct procurement patterns across product formats and care settings. Test complexity and result turnaround requirements drive purchasing decisions more than price alone in most institutional accounts.
Product Type:
Standalone antigen tests serve immediate triage needs in decentralized settings, while embedded multiplex formats integrate into broader respiratory diagnostic workflows.
- Flu A Test:Single-target immunochromatographic strip detects influenza A nucleoprotein antigen through lateral-flow chemistry. Demand concentrates in pediatric emergency departments during H1N1-predominant seasons where rapid subtype-agnostic confirmation guides isolation protocols.
- Flu B Test:Dedicated antigen detection format optimized for Victoria and Yamagata lineage differentiation in pediatric populations. Seasonal procurement spikes in Japan and South Korea reflect childhood influenza B burden in East Asian winter circulation patterns.
- Combination Test:Dual-line lateral-flow device capturing both A and B antigens in single specimen application.
- Multiplex Test:Respiratory pathogen panel integrating influenza with COVID-19 and RSV targets for syndromic surveillance.
Combination tests lead volumes today; multiplex formats are gaining share fastest.
End User:
Cost tier stratification separates capital-intensive hospital networks from budget-constrained outpatient facilities.
- Hospitals:Integrated health systems deploy both rapid antigen and molecular confirmation platforms across inpatient and outpatient units. United States health networks prioritize CLIA-waived instruments that reduce send-out laboratory dependency during seasonal surge capacity.
- Emergency Departments:Fifteen-minute turnaround requirements drive bedside antigen testing adoption for febrile respiratory triage. Academic medical centers in Boston and Houston anchor procurement volumes for instrument-read fluorescence platforms.
- Clinics:Physician office laboratories favor waived-complexity visual read devices for same-visit diagnosis.
- Laboratories:Centralized reference sites perform confirmatory nucleic acid amplification for equivocal antigen results.
Emergency departments lead volumes today; clinics are gaining share fastest.
Delivery Mode:
Application context determines whether testing occurs at bedside, in centralized facilities, or patient homes.
- Point-of-Care:CLIA-waived platforms enable non-laboratory personnel to perform testing in acute care settings. United States urgent care chains deploy these instruments to reduce laboratory turnaround bottlenecks during influenza season.
- Home Testing:Over-the-counter lateral-flow devices allow consumer-initiated screening before clinical consultation. Retail pharmacy distribution in the United States expands access for pre-visit triage in suburban and rural markets.
- Rapid Testing:Near-patient antigen detection with instrument-read or visual interpretation.
- Lab Testing:Centralized nucleic acid amplification for definitive pathogen identification.
Point-of-care leads volumes today; home testing is gaining share fastest.
Application:
Margin concentration varies sharply between routine clinical use and specialized surveillance contracts.
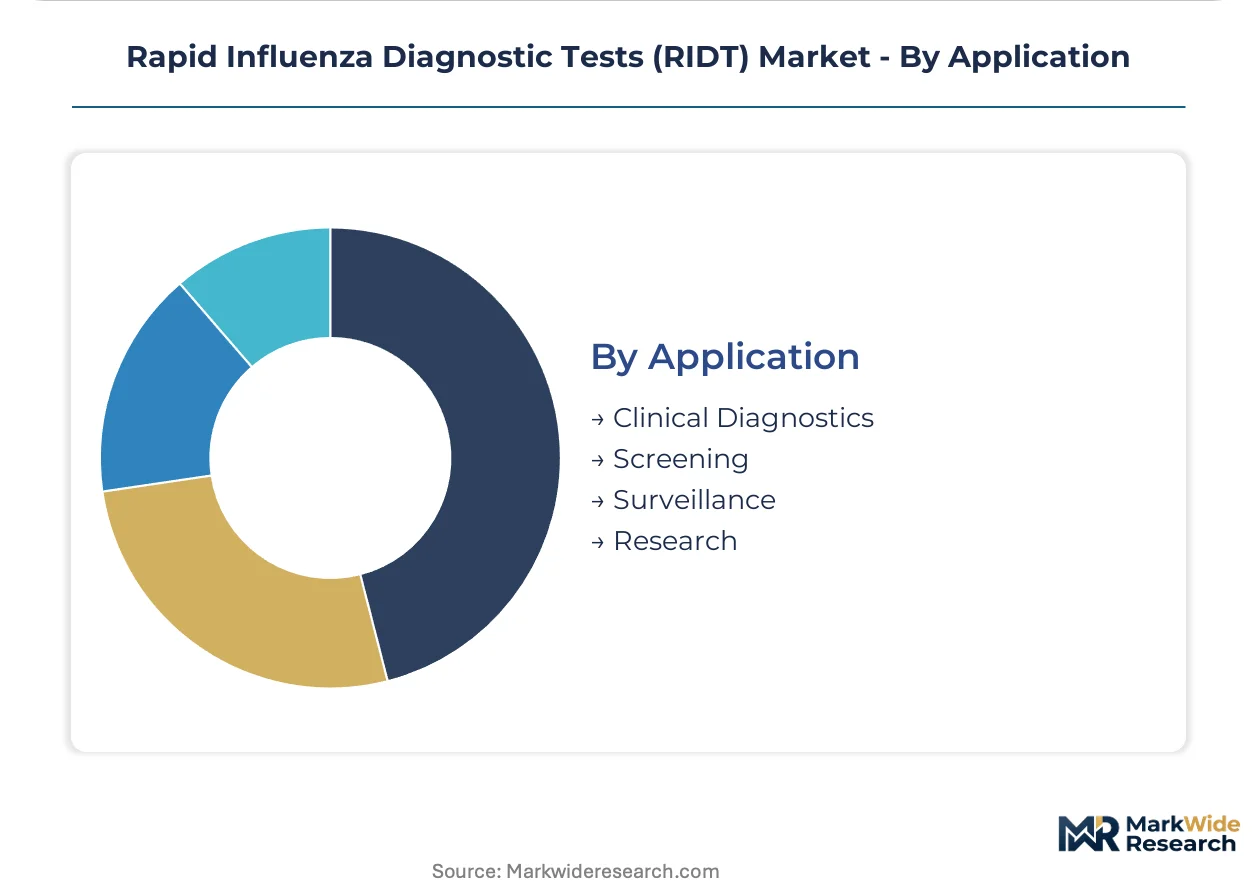
- Clinical Diagnostics:Diagnostic confirmation for individual patient management drives the majority of test consumption. Hospital emergency departments in the United States account for the largest procurement segment due to antiviral stewardship requirements.
- Surveillance:Population-level monitoring of circulating strains supports public health response and vaccine strain selection. CDC-contracted reference laboratories in Atlanta process multiplex panels for national influenza surveillance networks.
- Screening:Pre-operative and admission testing protocols in surgical units.
- Research:Clinical trial endpoints and assay validation studies for new platform development.
Clinical diagnostics leads volumes today; surveillance is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting RIDT manufacturing toward jurisdictions with streamlined premarket pathways and established lateral-flow component ecosystems. Cost-of-compliance gaps between the FDA's CLIA waiver program and EMA's IVDR clinical evidence requirements are accelerating geographic repositioning of production assets.
United States
Hospital emergency departments in Boston and Houston drive procurement volumes for instrument-read fluorescence platforms. FDA's CLIA-waived test pathway streamlines product approvals for urgent care deployment. Nitrocellulose membrane supply chains concentrate among specialized chemical manufacturers in the Southeast and California.
Germany
Centralized laboratory networks in Bavaria and North Rhine-Westphalia anchor demand for connectivity-enabled platforms bridging point-of-care instruments with enterprise health systems. EMA's In Vitro Diagnostic Regulation imposes strengthened clinical evidence requirements for near-patient devices. The Rhine-Main region hosts reference laboratories processing multiplex panels for European surveillance networks.
China
Domestic procurement for seasonal influenza triage is expanding in Shanghai and Guangzhou hospital networks. NMPA regulatory harmonization with international standards is accelerating product registration timelines. Yangtze River Delta manufacturers dominate global supply of conjugated nanoparticles and precision-coated membrane components.
Japan
Pediatric influenza B burden in Tokyo and Osaka drives seasonal procurement spikes for dedicated antigen detection formats. PMDA oversight of self-testing devices shapes over-the-counter distribution pathways. Kansai region diagnostic reagent manufacturers are repositioning toward higher-margin immunoassay component production.
South Korea
Childhood influenza B circulation patterns in Seoul anchor demand for Victoria and Yamagata lineage differentiation assays. MFDS streamlined approval pathways for waived-complexity devices accelerate urgent care placement. Busan-Ulsan manufacturing clusters supply precision coating automation equipment to global RIDT producers.
Rapid Influenza Diagnostic Tests (RIDT) Market Vendor Landscape
United States producers anchor the premium instrument-read tier; East Asian specialists hold component supply and cost-optimized manufacturing positions. Market structure consolidates around integrated platform vendors who supply both rapid antigen and molecular confirmation modalities, with single-source agreements reducing vendor management overhead across hospital networks. Three archetypes dominate: multinational conglomerates with centralized lab connectivity solutions, mid-cap specialists with proprietary amplification technologies, and regional manufacturers with captive membrane supply. Competitive intensity concentrates on M&A-driven portfolio diversification and strategic partnerships for multiplex respiratory panel development.
Within the multinational conglomerate tier, Abbott and Roche exemplify integrated platform strategies spanning point-of-care instruments through enterprise connectivity. Quidel Corporation occupies a specialist position in combination test formats with molecular amplification capabilities. These three anchors represent divergent competitive vectors: lateral-flow cost leadership, fluorescence-based optical detection systems, and proprietary chemistry integration. Their positioning reflects how procurement committees are consolidating respiratory testing contracts around vendors who can standardize operator training across nursing units while capturing bundled reimbursement codes for combined influenza and COVID-19 detection.
| Leading Market Players |
|---|
| Abbott |
| Quidel Corporation |
| Roche |
| Thermo Fisher Scientific |
| Becton Dickinson and Company |
| DiaSorin |
| Meridian Bioscience |
| Siemens Healthineers |
| bioMérieux |
| Others |
Supply Flow & Price Mechanics
Captive membrane production in the Yangtze River Delta anchors supply positions for East Asian manufacturers while granting pricing leverage through in-house nitrocellulose coating capabilities. This backward integration into precision-coated substrates insulates dominant producers from raw material volatility and compresses cost structures for high-volume hospital contracts.
Pricing Analysis
Distributor margins in the United States absorb 15-25 point spreads between manufacturer net and end-user list prices, with GPO-negotiated contracts compressing these layers for integrated health systems. Pricing stratifies across instrument-read fluorescence platforms, CLIA-waived visual devices, and economy lateral-flow strips, with FDA 510(k) clearance tier and CLIA complexity status driving differentiation. Cost compression in the economy strip segment intensifies as Chinese manufacturers scale automated coating lines. Physician office laboratories exhibit highest price sensitivity; academic medical centers prioritize sensitivity specifications over per-test economics.
Supply Chain Analysis
Conjugated nanoparticle supply rests on specialized chemical manufacturers in China, South Korea, and Japan, with Yangtze River Delta producers controlling 60-70 percent of global precision-coated membrane output. Nitrocellulose substrate, fluorescent reporter dyes, and monoclonal antibody cell lines constitute critical input dependencies. Single-source vulnerability concentrates in high-purity nitrocellulose membrane grades subject to EPA antimicrobial device standards. Distribution runs through medical device distributors, GPO contracts, and direct hospital system agreements in the United States, with retail pharmacy networks expanding for over-the-counter segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The RIDT market functions as a stable compounder anchored by recurring seasonal demand cycles and CLIA-waived platform replacement schedules in United States health systems.
For Market Incumbents: Hedge antigen sensitivity erosion by accelerating fluorescence-based optical detection deployment in emergency departments while securing captive nanoparticle supply through Southeast Asian coating facility investments. Multiplex respiratory panel integration represents the priority R&D lever for bundled reimbursement capture. For New Entrants and Emerging Players: Digital biosensor readout systems with cloud-connected result reporting offer a technology-first wedge into United States urgent care chains seeking to reduce subjective interpretation errors. Home-based self-testing channels remain underpenetrated relative to clinical segments; retail pharmacy distribution partnerships provide the cleanest go-to-market angle for over-the-counter placement. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap specialists with proprietary amplification chemistry because hospital procurement committees are consolidating respiratory testing contracts around integrated platform vendors. Five-to-ten year viability hinges on molecular confirmation modality ownership. Watch FDA dual-claim pathway decisions for combined COVID-19 and influenza detection as the signal for R&D allocation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA-Waiver Expansion | FDA streamlined review accelerates urgent care placement for waived-complexity instruments. |
| Multiplex Panel Development | Combined influenza and COVID-19 claims capture bundled reimbursement codes in United States. |
| Home Testing Channel Entry | Over-the-counter distribution through CVS and Walgreens addresses suburban pre-visit screening demand. |
| Captive Membrane Production | In-house nitrocellulose coating insulates East Asian manufacturers from raw material volatility. |
| Telehealth Integration | Digital result capture platforms embed diagnostic data into virtual care delivery models. |
Methodological Framework
Coverage spans the United States, Germany, China, Japan, and South Korea, with primary inputs from each market cluster combining executive interviews with hospital procurement managers, GPO contracts specialists, biomedical engineers, and diagnostic reagent manufacturers. Secondary validation drew from FDA 510(k) filings, EMA IVDR submission databases, CMS Medicare reimbursement schedules, and hospital procurement databases. Bottom-up test volume modeling triangulated against top-down market value estimates.
Granularity extended to product type, end user, delivery mode, and application segments, with regional regulatory clusters modeled separately for CLIA-waiver, IVDR, NMPA, PMDA, and MFDS pathways. CAGRs were derived from segment-level volume projections and average selling price trajectories across the analysis window. Seasonal demand volatility, inventory holding cost assumptions, and multiplex adoption curves informed forecast sensitivity bands.
The model holds under stable FDA and EMA regulatory frameworks; deviation in CLIA-waiver pathway scope or IVDR clinical evidence requirements would shift capital deployment timelines. A small set of named triggers warrants ongoing watch: dual-claim pathway decisions, nitrocellulose supply disruptions, and telehealth reimbursement policy evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Malaria Diagnostics Market
Diagnostics
Global Molecular Diagnostics Services Market
Diagnostics
Global Exocrine Pancreatic Insufficiency (EPI) Therapeutics and Diagnostics Market
Diagnostics
In Vitro Diagnostics (IVD) Quality Control Market
Diagnostics
Creatine Kinase Reagent Market
Diagnostics
Febrile Antigen Kits Market
Diagnostics
Hepatitis Test Solution and Diagnosis Market
Diagnostics
Europe Ovarian Cancer Diagnostics Market
Diagnostics
Brazil in Vitro Diagnostics Market
Diagnostics
Global Blood Culture Tests Market
Diagnostics
Preterm Birth Diagnostic Test Kits Market
Diagnostics
Rapid Oral Fluid Screening Device Market
Diagnostics
Tuberculosis (TB) Diagnostics Market
Diagnostics
Cervical Cancer Diagnostic Tests Market
Diagnostics
Immunoassay Interference Blocker Market
Diagnostics
Latex Agglutination Test Market