
 Global Diagnostic Testing Market | 2026-2036
Global Diagnostic Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Diagnostic Testing Market Foresight
The EU In Vitro Diagnostic Regulation is expanding the cost-of-entry calculus for commercial assay developers seeking CE-marked access. Abbott Laboratories leverages its vertically integrated manufacturing footprint to sustain compliance economies that smaller competitors cannot match. Siemens Healthineers anchors its European position through dedicated regulatory affairs infrastructure in Germany.
Diagnostic testing encompasses clinical laboratory methods that detect, measure, or analyze biological markers in patient specimens using reagent chemistry, optical detection systems, or nucleic acid amplification protocols to inform treatment decisions and disease surveillance. Molecular diagnostics and immunoassays capture divergent margin profiles, with PCR-based platforms commanding premium pricing in infectious disease panels while clinical chemistry analyzers face commoditization in high-throughput hospital labs. Next-generation sequencing competes for oncology screening budgets against established fluorescence in situ hybridization workflows.
The FDA's premarket notification pathway and the EU MDR/IVDR framework collectively shape product development timelines, reimbursement eligibility, and cross-border commercialization strategies for assay manufacturers. China's NMPA accelerates domestic innovation through prioritized review channels for novel diagnostic reagents. Stakeholders must monitor divergent evidentiary standards between FDA breakthrough device designation and EMA companion diagnostic requirements as portfolio allocation decisions hinge on regulatory sequencing.
Market Dynamics
The EU In Vitro Diagnostic Regulation is compressing product lifecycles and forcing assay manufacturers to rebuild clinical evidence packages, fundamentally altering the economics of CE-marked commercialization. Centralized hospital laboratories in China, Germany, and the United States are consolidating procurement power while point-of-care testing networks fragment demand across ambulatory settings.
Growth Catalysts
- IVDR Transition Deadlines:The EU's phased implementation timeline for Class C and D devices is accelerating portfolio rationalization among established manufacturers, creating acquisition opportunities for firms with compliant assays already in market.
- China NMPA Prioritized Review:Domestic molecular diagnostics developers are accessing accelerated approval pathways for novel infectious disease panels, compressing time-to-market for PCR-based respiratory assays.
- Hospital Consolidation:Integrated delivery networks in the United States are standardizing analyzer platforms across multi-site systems, driving volume commitments that favor vendors with comprehensive reagent menus.
Market Restraints
- Reagent Supply Concentration:Taq polymerase and fluorescent probe manufacturing clusters in specific coastal Chinese provinces expose assay producers to regional logistics disruptions and input price volatility.
- IVDR Notified Body Bottleneck:The limited pool of designated conformity assessment bodies under the new European framework is extending certification timelines for novel immunoassays by 12-18 months.
- Fluorescence In Situ Hybridization Substitution:Next-generation sequencing workflows are displacing established FISH-based oncology companion diagnostics in academic medical centers, eroding installed base value.
Strategic Opportunities
- India CDSCO Streamlined Pathway:The national pharmaceutical regulator's simplified registration process for Class A and B IVDs is opening direct market access for manufacturers previously dependent on distributor partnerships.
- Home-Based Continuous Monitoring:Integration of electrochemical biosensors with smartphone-connected readers is creating direct-to-consumer channels for chronic disease biomarker tracking outside traditional laboratory networks.
- CRISPR-Dx Convergence:Pairing guide RNA engineering with isothermal amplification is enabling instrument-free nucleic acid detection platforms suitable for resource-limited clinical settings.
Industry Challenges
- Bioinformatics Talent Scarcity:Next-generation sequencing interpretation pipelines require computational biologists with dual expertise in clinical variant classification and regulatory submission preparation.
- Legacy Analyzer Integration:Hospital laboratories demand seamless middleware connectivity between new molecular platforms and existing laboratory information systems, complicating vendor switching decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Diagnostic Testing Market |
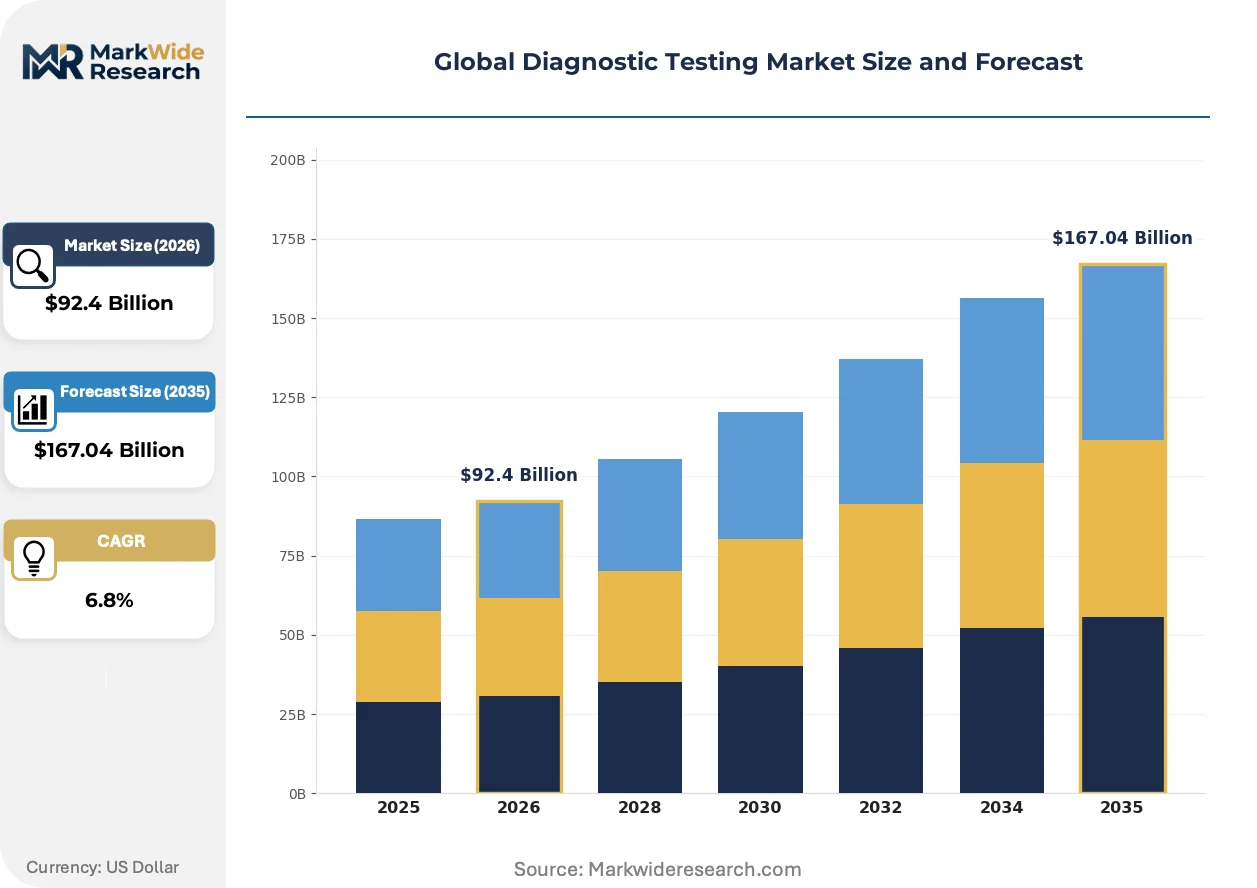
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $167.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunoassays, Molecular Diagnostics, Microbiology Tests, Hematology Analyzers, Clinical Chemistry Analyzers Application: Infectious Diseases, Genetic Testing, Oncology Screening, Cardiovascular Risk Assessment, Endocrinology Monitoring End User: Diagnostic Laboratories, Research Institutions, Blood Banks, Veterinary Clinics, Forensic Centers Technology: Polymerase Chain Reaction, Enzyme-Linked Immunosorbent Assay, Next-Generation Sequencing, Mass Spectrometry, Flow Cytometry |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche Ltd, Siemens Healthineers AG, Danaher Corporation, Thermo Fisher Scientific Inc., BD, bioMérieux SA, Quest Diagnostics Incorporated, Sysmex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Diagnostic Testing Market Shifts & Advancements
Digital connectivity and miniaturized detection hardware are collapsing the physical footprint required for complex diagnostic workflows. Assay developers are rearchitecting product strategies around distributed testing models rather than centralized laboratory automation.
Microfluidic cartridge systems are decentralizing molecular testing capacity from hospital core laboratories to urgent care clinics and retail pharmacy settings. Community health systems in the United States are deploying these platforms for same-day sexually transmitted infection panels. The technology is compressing reimbursement capture timelines and reducing specimen transport logistics costs.
MDR and IVDR convergence in Europe is forcing dual-framework compliance for manufacturers with overlapping device portfolios. Companies are consolidating European regulatory affairs functions in Germany and Ireland to manage parallel submission requirements. In vitro diagnostic manufacturers with existing MDR infrastructure are absorbing IVDR transition costs more efficiently than pure-play diagnostic entrants.
Hospital procurement committees are unbundling analyzer placement contracts from exclusive reagent supply agreements. Integrated delivery networks in the United States are negotiating reagent rental models that shift capital expenditure to operational budgets. This behavior is most visible among nonprofit health systems managing constrained capital allocation cycles.
Global Diagnostic Testing Market Segmentation
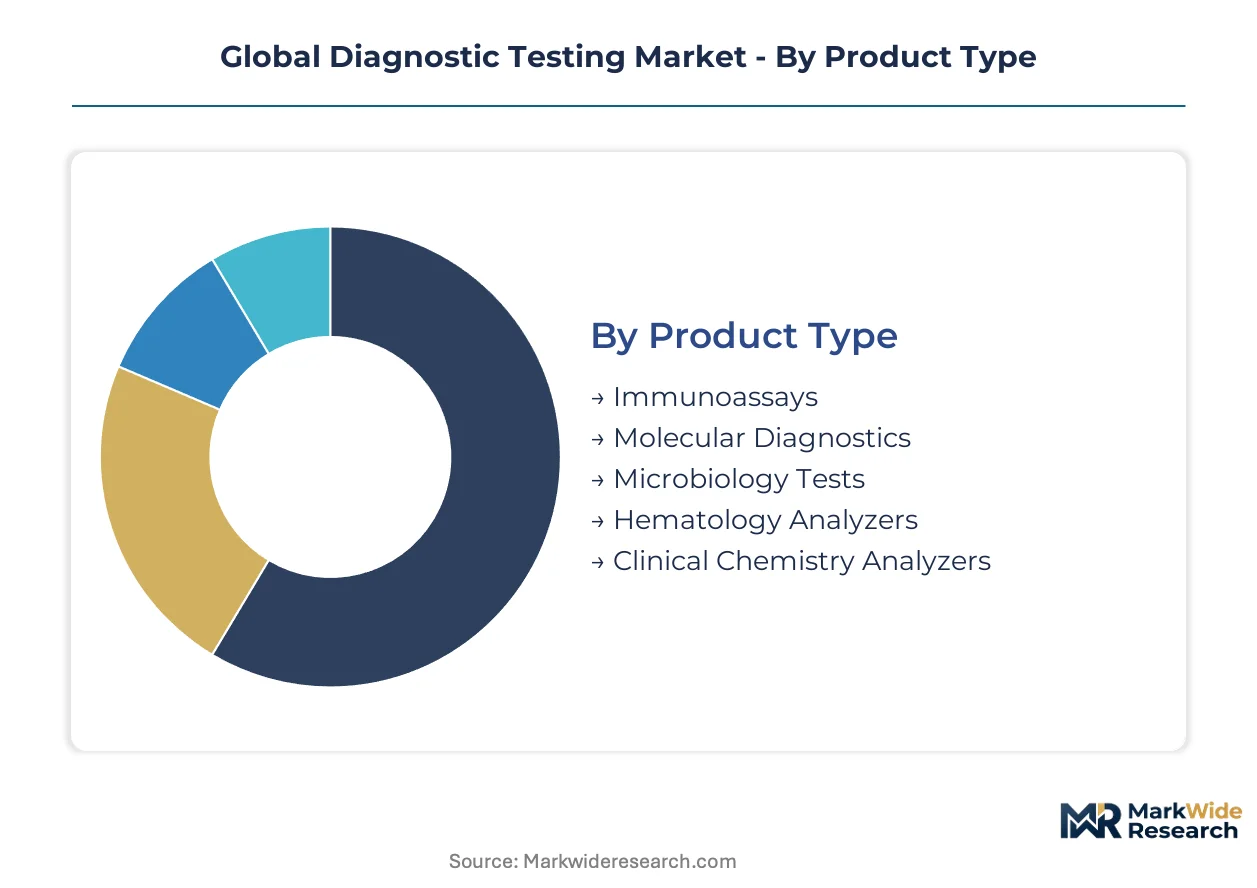
Diagnostic testing segments diverge sharply in margin structure, capital intensity, and regulatory pathway complexity. Manufacturers allocate R&D budgets across product lines based on reimbursement velocity and installed base replacement cycles rather than technology novelty alone.
Product Type:
Supply concentration in reagent manufacturing clusters shapes competitive economics across each product category.
- Molecular Diagnostics:Nucleic acid amplification platforms detect pathogen-specific RNA/DNA sequences through real-time PCR or isothermal methods. Hospital systems in China and Germany are consolidating procurement around automated extraction-amplification integrated systems to reduce hands-on time. Premium pricing persists in oncology companion diagnostics where FDA breakthrough device designation accelerates coverage.
- Immunoassays:Antibody-antigen binding reactions on chemiluminescent or electrochemiluminescent substrates dominate high-throughput infectious disease screening. Centralized laboratories in the United States favor vendors with 100+ assay menus to minimize platform proliferation. Reagent rental contracts now displace capital purchases across nonprofit health systems managing constrained allocation cycles.
- Microbiology Tests:Culture-based identification and antimicrobial susceptibility panels remain essential for sepsis protocols.
- Hematology Analyzers:Complete blood count automation serves high-volume hospital core laboratories with limited differentiation.
- Clinical Chemistry Analyzers:Routine metabolic panels face commoditization as Chinese manufacturers penetrate mid-tier hospital segments.
Today's leader: Immunoassays. Tomorrow's challenger: Molecular Diagnostics.
Application:
Reimbursement tiering separates premium-priced screening from routine monitoring across clinical use cases.
- Infectious Diseases:Respiratory, sexually transmitted, and hospital-acquired pathogen panels command priority placement in urgent care and retail pharmacy settings. Microfluidic cartridge systems are decentralizing molecular capacity from hospital core laboratories to point-of-care networks in the United States.
- Oncology Screening:Companion diagnostics for targeted therapeutics require synchronized FDA-EMA approval timelines. Academic medical centers are displacing fluorescence in situ hybridization workflows with next-generation sequencing interpretation pipelines.
- Genetic Testing:Carrier screening and pharmacogenomic profiling expand through direct-to-consumer channels.
- Cardiovascular Risk Assessment:Lipid panels and troponin assays integrate with electronic health record risk calculators.
- Endocrinology Monitoring:Diabetes and thyroid testing volumes concentrate in high-throughput reference laboratories.
Oncology Screening captures the steepest expansion trajectory as pharmaceutical pipelines demand biomarker-defined patient stratification.
End User:
Procurement authority consolidation among integrated delivery networks fragments demand across traditional and emerging access points.
- Diagnostic Laboratories:Reference laboratories and hospital core labs negotiate multi-year reagent supply commitments based on test volume guarantees. Middleware connectivity requirements complicate vendor switching decisions as laboratories demand seamless laboratory information system integration.
- Research Institutions:Academic medical centers drive next-generation sequencing adoption for translational oncology programs. Bioinformatics talent scarcity constrains interpretation pipeline development despite instrument availability.
- Blood Banks:Donor screening protocols maintain steady demand for serological and nucleic acid testing.
- Veterinary Clinics:Companion animal diagnostics replicate human testing menus at reduced regulatory burden.
- Forensic Centers:DNA profiling for criminal casework operates on government procurement cycles with extended tender timelines.
Diagnostic Laboratories anchor current revenue concentration. Research Institutions are gaining share fastest as precision medicine budgets expand.
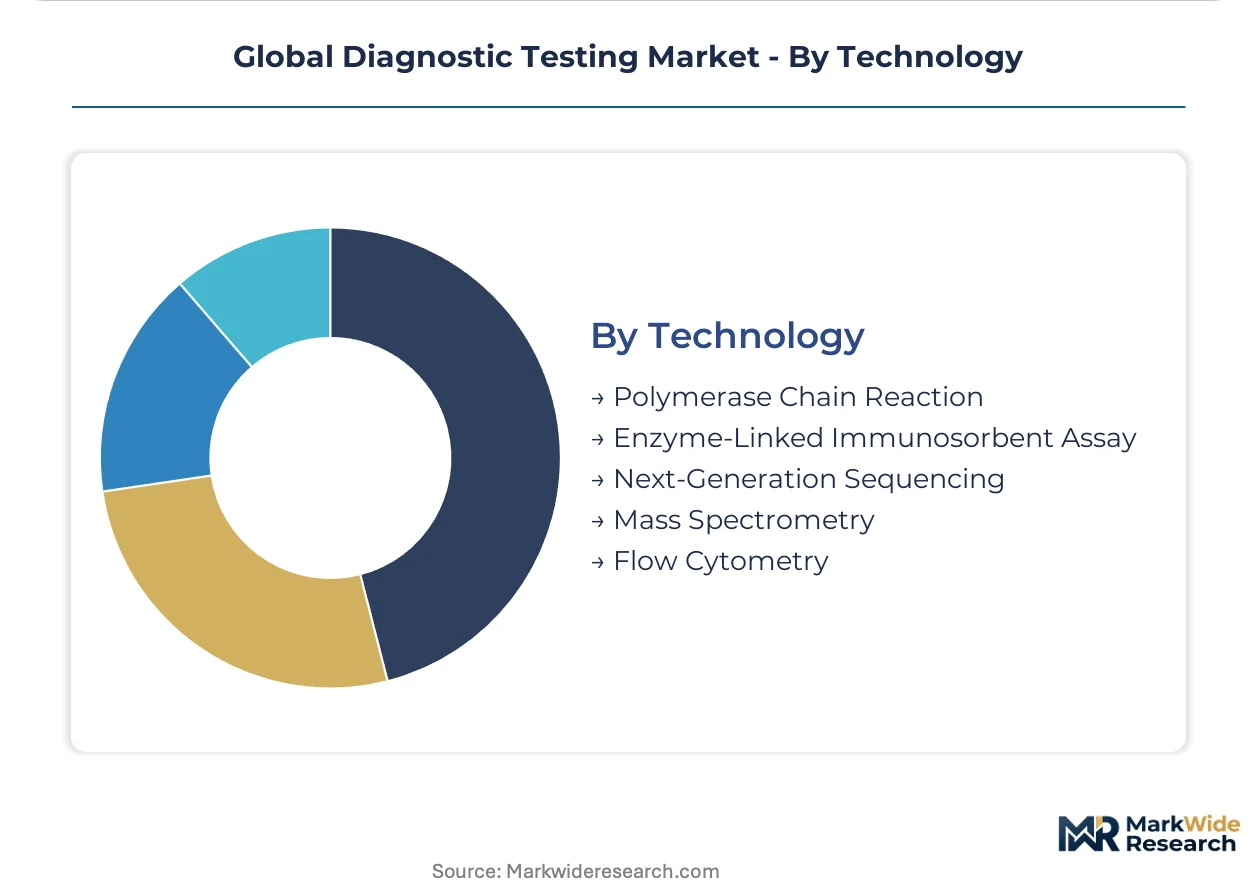
Technology:
Platform replacement cycles accelerate where miniaturization and connectivity reduce physical footprint and turnaround time.
- Polymerase Chain Reaction:Thermal cycling amplification remains the gold standard for infectious disease detection with established reimbursement codes. China's NMPA prioritized review channels compress approval timelines for domestic respiratory assay developers.
- Next-Generation Sequencing:Massively parallel sequencing platforms compete for oncology screening budgets against established workflows. Computational biologists with dual expertise in variant classification and regulatory submission preparation remain scarce.
- Enzyme-Linked Immunosorbent Assay:Plate-based serology persists in resource-limited settings for HIV and hepatitis screening.
- Mass Spectrometry:Proteomic and metabolomic profiling expands in specialized reference laboratories.
- Flow Cytometry:Cell surface marker analysis supports leukemia and lymphoma immunophenotyping protocols.
Polymerase Chain Reaction dominates installed base value. Next-Generation Sequencing is climbing the fastest as tumor mutational burden testing standardizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic testing traces its modern industrial lineage to post-war Germany and the United States, where clinical laboratory automation first achieved commercial scale during the 1960s. Those foundational manufacturing clusters continue to shape regulatory standards and supply chain geography today.
United States
Hospital consolidation into integrated delivery networks concentrates procurement authority among fewer buyers, pressuring reagent pricing across infectious disease and oncology panels. FDA breakthrough device designation accelerates Medicare coverage determinations for novel companion diagnostics. The Boston-Cambridge corridor anchors next-generation sequencing interpretation pipeline development, though bioinformatics talent scarcity constrains expansion.
Germany
Siemens Healthineers maintains dedicated regulatory affairs infrastructure in Erlangen to manage parallel MDR and IVDR submission requirements. The country's notified body designation under IVDR creates certification bottlenecks extending novel immunoassay timelines. Baden-Württemberg's precision engineering cluster supplies optical detection subsystems to automated analyzer manufacturers.
China
Domestic molecular diagnostics developers exploit NMPA prioritized review channels to compress respiratory assay approval timelines. Taq polymerase and fluorescent probe manufacturing concentrates in coastal Zhejiang and Jiangsu provinces, exposing supply chains to regional logistics disruptions. Beijing-Tianjin-Hebei hospitals are consolidating procurement around automated extraction-amplification integrated systems.
India
CDSCO's streamlined registration pathway for Class A and B IVDs opens direct market access for manufacturers previously dependent on distributor partnerships. Maharashtra's diagnostic laboratory chains negotiate multi-year reagent supply commitments based on volume guarantees. Mumbai-Pune pharmaceutical corridors absorb regulatory compliance costs more efficiently than northern competitors.
Japan
PMDA's stringent evidentiary requirements for novel biomarker claims extend development timelines relative to FDA pathways. METI funding prioritizes miniaturized detection hardware for point-of-care deployment in aging rural populations. The Kansai region's Osaka-Kobe medical device cluster specializes in hematology analyzer exports across Southeast Asia.
Global Diagnostic Testing Market Competitive Landscape
The competitive structure tilts toward diversified conglomerates with captive reagent manufacturing and established regulatory infrastructure. Three to five multinational groups capture disproportionate share in high-margin molecular diagnostics and immunoassay segments, while mid-tier specialists concentrate in microbiology and hematology niches. Strategic archetypes include vertically integrated platform vendors, reagent-focused menu expanders, and regional compliance specialists. M&A activity targets IVDR-compliant assay portfolios, and capacity expansion concentrates in Germany and China to serve divergent regulatory timelines.
Among US-based diversified health technology groups, Abbott Laboratories and Danaher Corporation exemplify the vertically integrated archetype, leveraging manufacturing footprint breadth to sustain compliance economies. F. Hoffmann-La Roche Ltd anchors the premium diagnostics tier through Swiss operational heritage. These three occupy positions where regulatory sequencing expertise and installed base scale reinforce competitive moats against pure-play entrants facing IVDR transition cost absorption.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd |
| Siemens Healthineers AG |
| Danaher Corporation |
| Thermo Fisher Scientific Inc. |
| BD |
| bioMérieux SA |
| Quest Diagnostics Incorporated |
| Sysmex Corporation |
| Others |
Supply & Pricing Matrix
Integrated delivery networks in the United States and hospital procurement consortia in Germany now command sufficient volume concentration to extract reagent rental contracts that displace capital purchases, compressing margin structures for assay manufacturers while shifting financial risk downstream. This buyer consolidation forces vendors to absorb instrument placement costs upfront and recover through multi-year consumable commitments, fundamentally altering working capital requirements across the diagnostic testing value chain.
Pricing Analysis
Reagent rental and per-test operational leasing now dominate hospital laboratory procurement, displacing capital expenditure models across nonprofit health systems managing constrained allocation cycles. Price differentiation rests on assay menu breadth and IVDR certification status, with comprehensive 100-plus test menus commanding premium positioning against narrow infectious disease panels. Cost compression in clinical chemistry analyzers is intensifying because Chinese manufacturers penetrate mid-tier hospital segments with commoditized metabolic panels. Research institutions and academic medical centers exhibit lowest price sensitivity due to precision medicine budget insulation, while community health systems in the United States demonstrate highest sensitivity to per-test operational costs.
Supply Chain Analysis
Single-source vulnerability sits with Taq polymerase and fluorescent probe manufacturing clusters concentrated in coastal Zhejiang and Jiangsu provinces of China. Critical inputs draw from German optical detection subsystem suppliers in Baden-Württemberg, Japanese precision electronics manufacturers, and Indian enzyme production facilities. Tariff exposure runs through reagent chemistry imports subject to evolving trade policy between the United States and China. Distribution runs through regional distribution hubs operated by group purchasing organizations and direct hospital system contracts, with emergency stockpiling requirements now standard in post-pandemic procurement protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
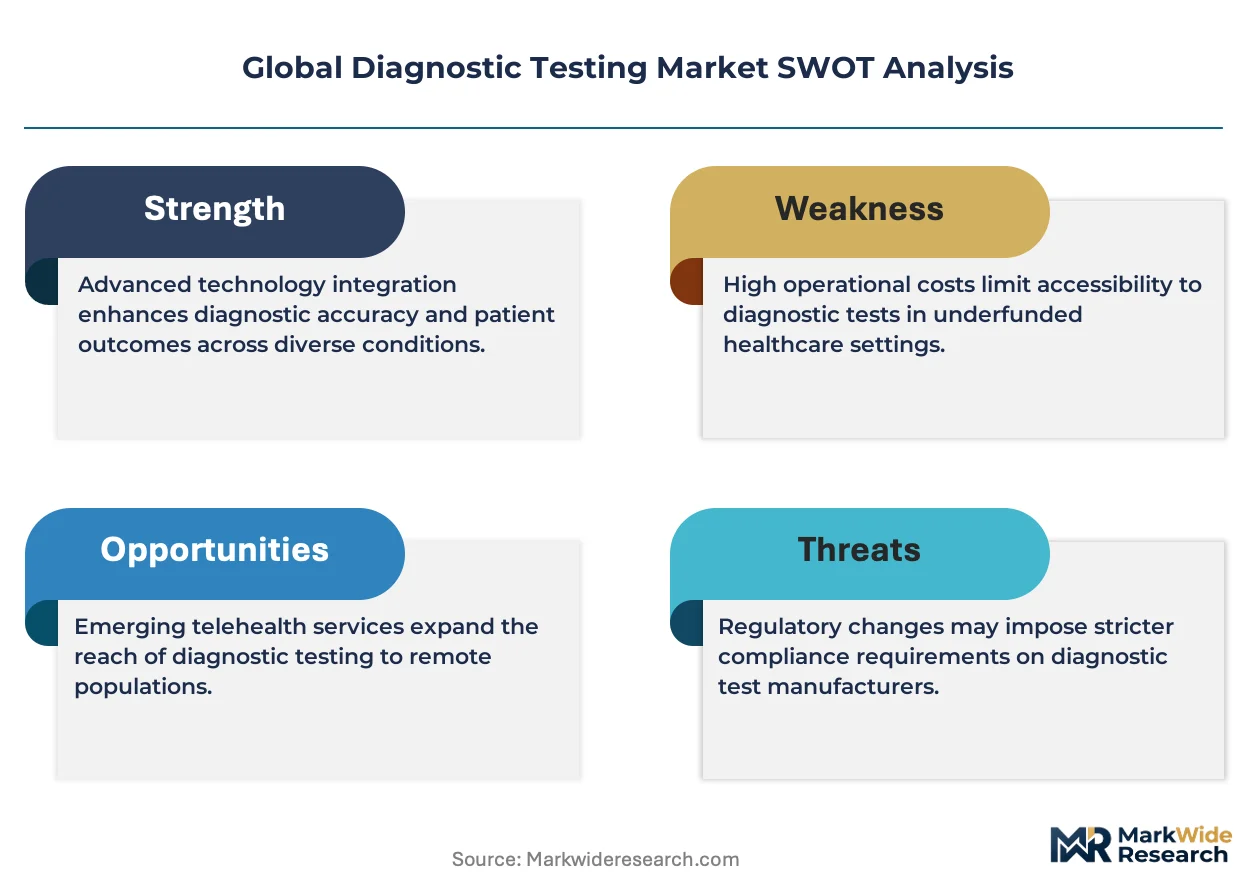
This market offers margin expansion through IVDR-compliant assay portfolio premiums and automated platform consolidation that reduces hands-on labor costs in hospital core laboratories. Manufacturers capturing regulatory sequencing expertise and installed base scale will widen competitive moats against pure-play entrants facing compliance cost absorption.
For Market Incumbents: Deepen backward integration into Taq polymerase manufacturing to mitigate Zhejiang-Jiangsu supply concentration risks and secure input cost control. Expand dedicated regulatory affairs infrastructure in Germany to manage parallel MDR and IVDR submission requirements more efficiently than competitors. Prioritize middleware connectivity investments that complicate hospital laboratory vendor switching decisions and protect installed base value against emerging molecular platform entrants. For New Entrants and Emerging Players: CRISPR-Dx instrument-free detection platforms offer a technology-first wedge into resource-limited clinical settings underserved by automated extraction-amplification integrated systems. Target India's CDSCO streamlined pathway for Class A and B IVDs to bypass distributor-dependent market access models. Pursue urgent care and retail pharmacy point-of-care networks in the United States where microfluidic cartridge systems compress reimbursement capture timelines and specimen transport logistics costs. For Investors and Strategic Acquirers: Diversified health technology conglomerates with captive reagent manufacturing are the most active acquirers in this space, targeting IVDR-compliant assay portfolios to fill regulatory sequencing gaps. Acquisition focus should center on mid-tier molecular diagnostics specialists with established NMPA prioritized review track records in China. The signal to watch is IVDR notified body designation expansion announcements, which would accelerate certification timelines and unlock trapped novel immunoassay value.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Compliance Pathway Investment | CE marking under EU In Vitro Diagnostic Regulation enables market access across 27 member states. |
| Reagent Rental Contract Expansion | Operational leasing models align vendor incentives with hospital laboratory volume growth. |
| Microfluidic Cartridge Platform Launch | Decentralized molecular testing captures urgent care and retail pharmacy placement opportunities. |
| Backward Integration into Enzyme Manufacturing | In-house Taq polymerase production reduces exposure to Zhejiang-Jiangsu supply concentration. |
| Middleware Connectivity Development | Seamless laboratory information system integration complicates hospital vendor switching decisions. |
Research Methodology
Direct dialogue with hospital procurement managers, regulatory affairs directors at assay manufacturers, GPO contracts specialists, and biomedical engineers in academic medical centers grounded the qualitative assessment. Secondary validation drew from FDA 510(k) filings, EMA companion diagnostic submissions, NMPA prioritized review announcements, hospital procurement databases, and CMS Medicare coverage determinations. Bottom-up test volume modeling and top-down market sizing triangulated against manufacturer revenue disclosures established analytical coherence.
Bottom-up segment analysis projected infectious disease panel volumes, oncology companion diagnostic adoption curves, and point-of-care testing expansion across the projection horizon. Segmentation dimensions spanned product type, application, end user, technology platform, and regional regulatory cluster. CAGRs were derived from weighted average growth across these segments, with specific inputs including IVDR transition timeline phasing, NMPA approval velocity, and hospital consolidation rates in the United States.
The model holds under stable regulatory implementation schedules and continued hospital procurement authority consolidation; deviation in IVDR notified body capacity or major trade policy shifts between the United States and China would shift trajectory assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Esoteric Testing Market
Testing Services
Over-The-Counter Tests Market
Testing Services
Home Care Testing Market
Testing Services
Phenytoin Testing Market
Testing Services
Drug Tester Market
Testing Services
In-Vitro Diagnostic Services Market
Testing Services
Paediatric and Neonatal Testing Kits Market
Testing Services
South Korea GMP Testing Service Market
Testing Services
Global Bioburden Testing Market
Testing Services
Mask Bacterial Filtration Efficiency Tester Market
Testing Services
Leukocyte Count Testing Market
Testing Services
US Bowie Dick Test Pack Market
Testing Services
Rapid Test Cards Market
Testing Services
Apoptosis Testing Market
Testing Services
Global Roadside Drug Testing Devices Market
Testing Services
Pneumococcal Testing Market