
 Global Blood Transfusion Diagnostics Market | 2026-2036
Global Blood Transfusion Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Blood Transfusion Diagnostics Market Foresight
Asset-light leasing models for molecular diagnostic platforms is narrowing the capital barrier for mid-sized blood banks and regional hospitals. Siemens Healthineers leverages its installed base of automation systems to sustain recurring revenue streams across European and North American reference sites. Grifols anchors its position through captive plasma collection networks that feed proprietary testing workflows. Abbott Laboratories differentiates via point-of-care compatibility instruments that reduce turnaround time in emergency transfusion settings.
Blood transfusion diagnostics encompass analytical systems, reagent chemistries, and informatics tools that detect infectious markers, determine blood group antigens, and verify donor-recipient compatibility prior to transfusion. Molecular diagnostics platforms employing polymerase chain reaction and transcription-mediated amplification achieve pathogen detection sensitivity below one copy per milliliter, far exceeding serological thresholds. Reagents and consumables command the most durable revenue streams due to per-test consumption patterns and lot-controlled quality requirements. Nucleic acid testing represents the fastest-expanding technology segment as regulatory bodies in the United States, Germany, and Japan mandate universal screening for HIV, hepatitis B, and hepatitis C.
The FDA governs donor screening assay approvals through biologics license applications, while the EMA coordinates blood safety standards via the EU Blood Directive and F-Gas Regulation affects cold-chain equipment specifications. WHO prequalification pathways shape procurement criteria for diagnostics in lower-resource settings, creating tiered market access conditions. Stakeholders must monitor evolving regulatory convergence between nucleic acid testing mandates and next-generation sequencing validation frameworks to anticipate platform upgrade cycles.
Market Dynamics
The blood transfusion diagnostics sector is experiencing platform consolidation as nucleic acid testing mandates force mid-sized blood banks to retire serological workflows and adopt molecular infrastructure. This technology transition is compressing equipment replacement cycles and concentrating procurement decisions among reference laboratories with capital deployment capacity.
Growth Catalysts
- EMA Blood Safety Directives:The European Medicines Agency's updated screening protocols are mandating expanded pathogen panels, compelling blood centers across Germany, France, and Italy to upgrade testing platforms.
- Hospital Transfusion Services:Rising surgical volumes and trauma care expansion in tertiary medical centers are amplifying demand for rapid-turnaround compatibility testing instruments.
- Polymerase Chain Reaction:PCR platforms achieving sub-copy-per-milliliter sensitivity are displacing serological methods in Japanese and US reference sites, opening replacement revenue streams for platform vendors.
Market Restraints
- Reagent Cost Volatility:Proprietary chemistries and lot-controlled consumables lock blood banks into single-source supply relationships with limited price negotiation leverage.
- Capital Intensity:Molecular diagnostic platforms require substantial upfront investment, restricting adoption among regional hospitals and independent blood centers with constrained capital budgets.
- FDA Biologics License Timelines:Extended approval pathways for novel donor screening assays delay market entry and compress commercialization windows for assay developers.
Strategic Opportunities
- Asset-Light Leasing Models:Equipment-as-a-service arrangements are lowering barriers for mid-tier blood banks in Spain and Australia to access nucleic acid testing capability without capital expenditure.
- Next-Generation Sequencing Convergence:Integration of NGS with existing PCR workflows promises expanded pathogen detection panels and reduced per-test costs for high-volume screening centers.
- WHO Prequalification Pathways:Emerging procurement frameworks for lower-resource settings in Southeast Asia and sub-Saharan Africa are creating tiered market access for validated screening platforms.
Industry Challenges
- Molecular Diagnostics Talent Scarcity:Blood banks face acute shortages of laboratory technicians trained in PCR workflow optimization and nucleic acid test interpretation.
- Legacy System Integration:Hospital information systems with decades-old architectures resist seamless data exchange with modern molecular diagnostic platforms, forcing costly middleware deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Blood Transfusion Diagnostics Market |
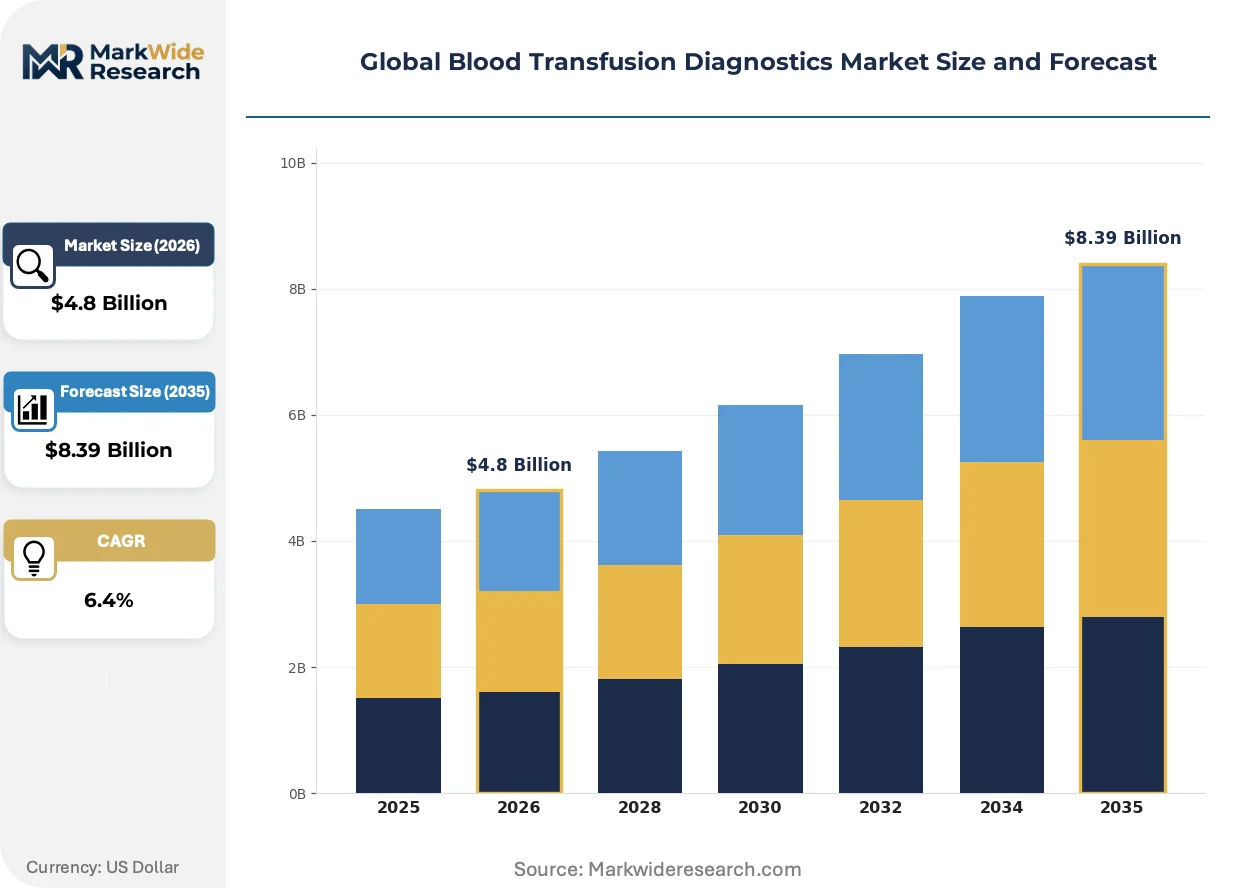
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instruments, Reagents, Software, Consumables Technology: Molecular Diagnostics, Serological Testing, Immunoassays, Nucleic Acid Testing End User: Hospitals, Blood Banks, Diagnostic Laboratories, Research Institutions Application: Infectious Disease Testing, Blood Typing, Compatibility Testing, Cross-Matching |
| Companies Covered | Bio-Rad Laboratories, Siemens Healthineers, Roche Diagnostics, DiaSorin, Becton, Dickinson and Company, Grifols, Immucor, Danaher, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Blood Transfusion Diagnostics Market Shifts & Advancements
Multiple technology trajectories are converging to reshape competitive positioning in blood transfusion diagnostics. Platform vendors are racing to integrate automation, informatics, and expanded pathogen detection into unified screening workflows.
Transcription-mediated amplification is migrating from research-only installations to routine donor screening operations. Large reference laboratories in the United States and Germany are adopting TMA platforms for simultaneous HIV, hepatitis B, and hepatitis C detection in single-reaction formats. This migration from PCR-dominant workflows is compressing assay turnaround times and reducing hands-on technician requirements.
The EU F-Gas Regulation is reshaping cold-chain specifications for reagent storage and transport equipment. Blood centers must now validate alternative refrigeration technologies to maintain nucleic acid test kit integrity across temperature excursions. German and French transfusion services are investing in compliant cold-chain infrastructure ahead of phasedown deadlines.
Point-of-care compatibility testing is gaining traction in emergency transfusion settings. Trauma centers and military field hospitals are deploying rapid serological instruments that bypass centralized laboratory workflows. This behavioral shift is most visible in Japanese tertiary hospitals and US Level I trauma centers where turnaround time directly impacts patient outcomes.
Global Blood Transfusion Diagnostics Market Segmentation
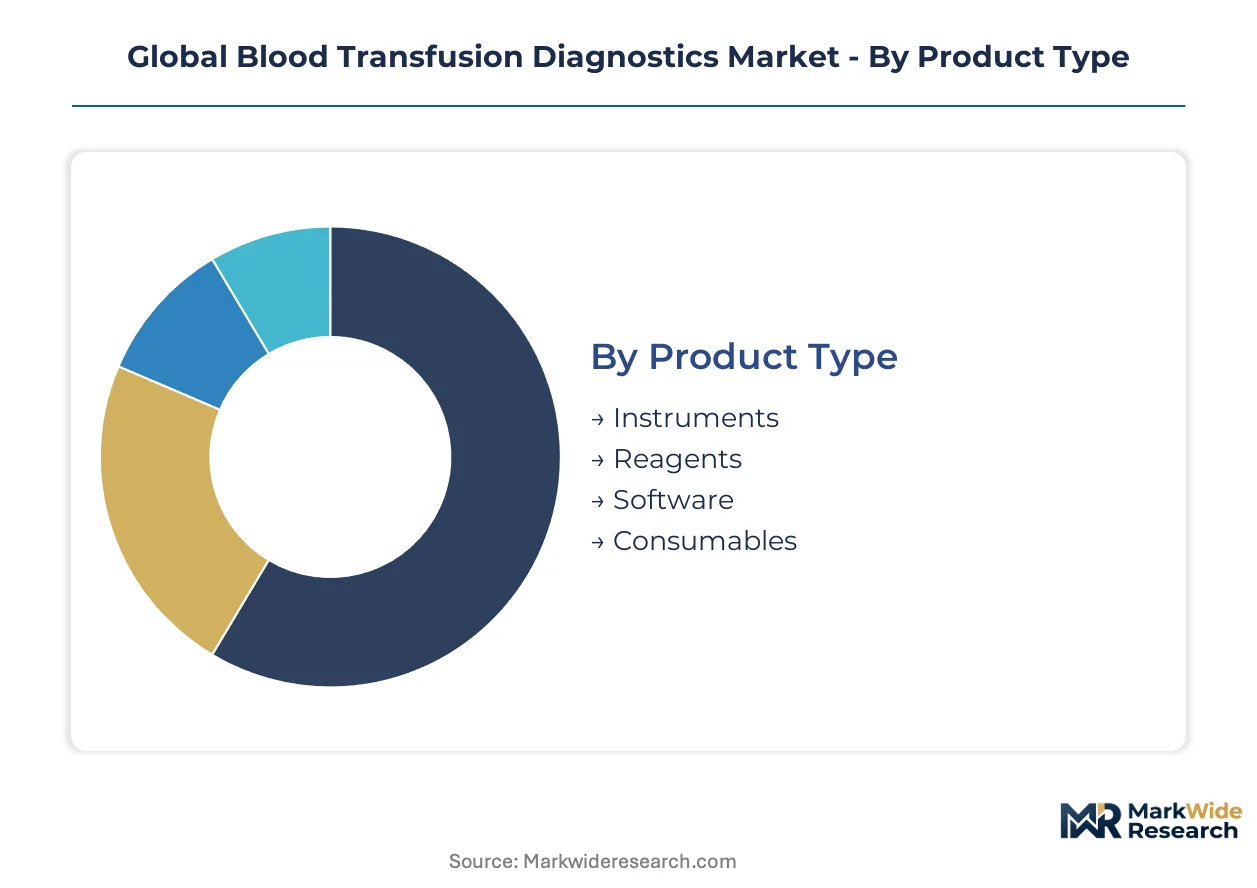
Segmentation in blood transfusion diagnostics reveals distinct procurement rhythms and margin profiles across product categories. Technology choices determine capital intensity and replacement cycles, while end-user scale shapes pricing power and service bundling strategies.
Product Type:
Consumables and reagents turn over fastest with per-test depletion, while instruments anchor multi-year depreciation schedules and software locks in recurring license streams.
- Instruments:Analytical platforms include automated immunoassay processors, PCR thermal cyclers, and TMA detection systems. German and Japanese reference laboratories concentrate procurement for high-throughput molecular platforms as EMA and PMDA mandates tighten sensitivity thresholds.
- Reagents:Proprietary chemistries for antigen-antibody binding reactions and nucleic acid amplification require lot-controlled validation and cold-chain integrity. Blood banks in the United States face single-source supply concentration with limited price negotiation leverage due to biologics license dependencies.
- Software:Laboratory information management systems and donor registry platforms enable traceability and compliance documentation.
- Consumables:Pipette tips, reaction vessels, and sample collection devices deplete with each screening cycle.
Reagents dominate installed base. Consumables are where expansion concentrates.
Technology:
Cost tiers separate capital-intensive molecular infrastructure from lower-cost serological alternatives, with hybrid immunoassay platforms occupying the middle ground.
- Molecular Diagnostics:PCR and transcription-mediated amplification platforms achieve sub-copy-per-milliliter pathogen detection. United States and German blood centers are displacing legacy workflows as FDA and EMA screening protocols mandate nucleic acid sensitivity thresholds.
- Nucleic Acid Testing:Dedicated NAT systems for HIV, hepatitis B, and hepatitis C screening operate under universal mandates in Japan, Germany, and the United States. Tertiary hospitals in Tokyo and Osaka are upgrading from pooled to individual donation testing to reduce diagnostic windows.
- Serological Testing:Rapid agglutination and gel-column methods persist in resource-constrained settings and emergency compatibility verification.
- Immunoassays:Enzyme-linked and chemiluminescent formats bridge serological simplicity with molecular sensitivity for antibody detection.
Serological testing retains volume share in lower-resource procurement. Nucleic acid testing is climbing the fastest.
End User:
Customer type determines service bundling complexity, with blood banks demanding integrated screening workflows and hospitals prioritizing turnaround speed over panel breadth.
- Blood Banks:Regional and national collection centers process donor volumes requiring high-throughput screening with full pathogen panels. French and Italian transfusion services are consolidating procurement decisions among reference sites with capital deployment capacity.
- Hospitals:Tertiary medical centers and trauma units demand rapid compatibility testing with minimal pre-transfusion delays. Level I trauma centers in the United States are deploying point-of-care instruments to bypass centralized laboratory workflows.
- Diagnostic Laboratories:Independent reference sites offer outsourced screening for smaller hospitals and regional blood centers.
- Research Institutions:Academic medical centers and transfusion medicine institutes validate novel biomarkers and next-generation sequencing applications.
Blood banks anchor platform vendor relationships. Hospitals are where point-of-care penetration accelerates.
Application:
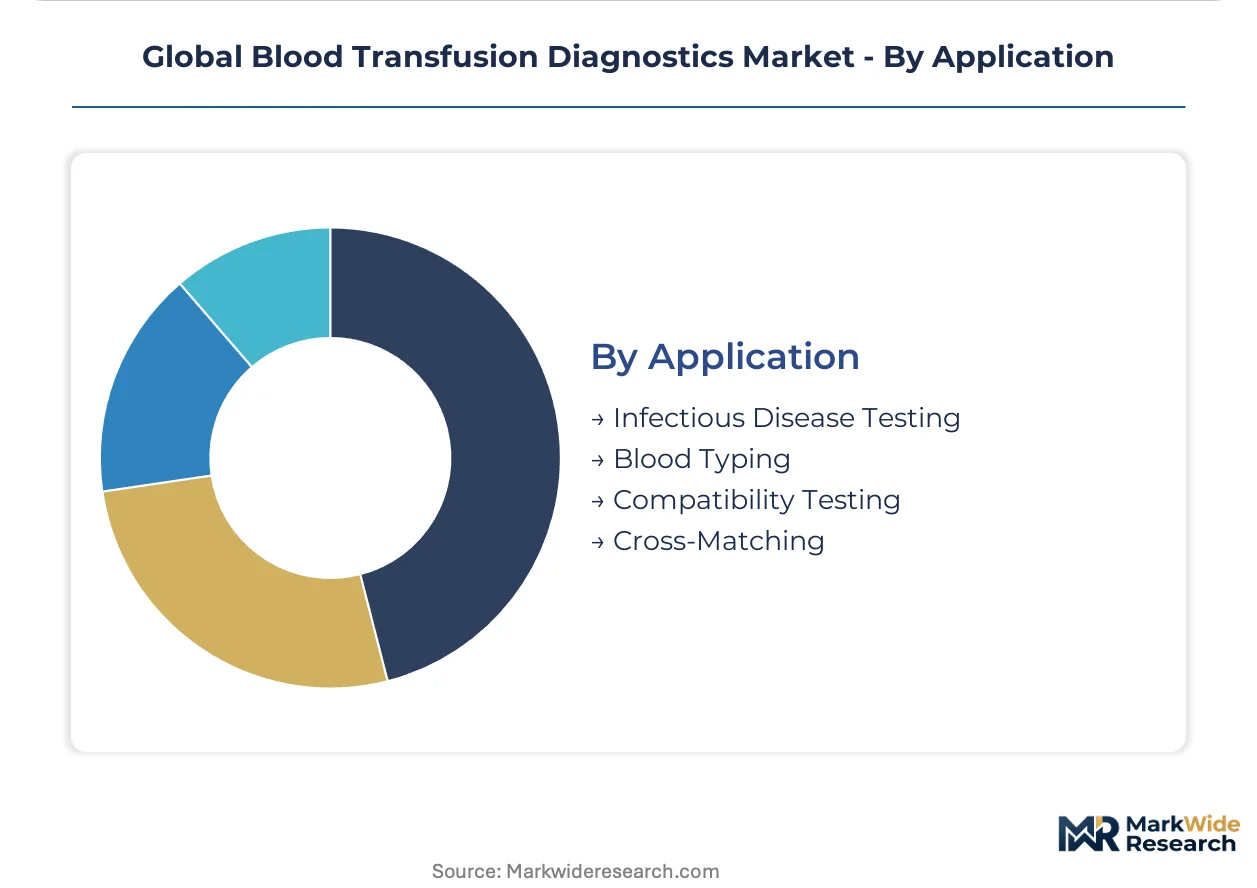
Application maturity varies from standardized infectious disease panels to emerging next-generation sequencing compatibility protocols.
- Infectious Disease Testing:Mandatory screening for HIV, hepatitis B, hepatitis C, and emerging pathogens constitutes the highest-volume application. Japanese and German regulators enforce the most expansive pathogen panels, compressing assay development timelines for platform vendors.
- Blood Typing:ABO and extended phenotype determination using serological and molecular methods guides donor-recipient matching. United States reference laboratories are adopting genotyping platforms to resolve complex antibody cases.
- Compatibility Testing:Pre-transfusion cross-matching verifies antigen-antibody compatibility between donor units and recipients.
- Cross-Matching:Final serological verification prior to transfusion release prevents acute hemolytic reactions.
Infectious disease testing commands the broadest installed base. Blood typing is gaining share fastest from genotyping adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds that in India by substantial margins, reflecting divergent regulatory stringency and procurement sophistication across these markets. German and Japanese blood centers command premium valuations for nucleic acid testing platforms due to mandatory screening protocols. Emerging procurement frameworks in Southeast Asia and Latin America are compressing margins for standardized serological instruments.
United States
FDA biologics license applications govern donor screening assay approvals, creating high barriers for market entry. Level I trauma centers in Baltimore and Houston are deploying point-of-care compatibility instruments to bypass centralized laboratory workflows. The American Red Cross and regional blood centers concentrate procurement decisions for high-throughput molecular platforms in the Northeast and Pacific Coast corridors.
Germany
EMA blood safety directives mandate expanded pathogen panels across national transfusion services. The EU F-Gas Regulation is forcing blood centers in Munich and Hamburg to validate alternative refrigeration technologies for reagent storage. Baden-Württemberg and North Rhine-Westphalia host the densest clusters of reference laboratories upgrading from pooled to individual donation testing protocols.
Japan
PMDA nucleic acid testing mandates enforce universal screening thresholds exceeding serological sensitivity limits. Tertiary hospitals in Tokyo and Osaka are accelerating platform replacement cycles to comply with individual donation testing requirements. The Kansai region anchors domestic demand for transcription-mediated amplification systems in high-volume screening operations.
China
NMPA regulatory harmonization with international nucleic acid testing standards is elevating quality thresholds for domestic blood centers. Municipal transfusion services in Shanghai and Beijing are consolidating procurement among reference sites with capital deployment capacity. The Yangtze River Delta exhibits the fastest adoption of automated immunoassay processors for donor screening workflows.
Brazil
ANVISA blood safety regulations are tightening pathogen detection requirements for regional transfusion networks. São Paulo and Rio de Janeiro blood centers are transitioning from serological to molecular infrastructure under phased compliance timelines. The Southeast region concentrates demand for leasing-based equipment arrangements that circumvent upfront capital constraints.
Global Blood Transfusion Diagnostics Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in reagent and consumable supply. The vendor base organizes around three strategic archetypes: multinational conglomerates with automation portfolios, plasma-derived therapy specialists with captive testing networks, and independent diagnostics firms with nucleic acid testing focus. Competitive moves concentrate on equipment-as-a-service arrangements and next-generation sequencing convergence to extend replacement cycles.
Among diversified healthcare conglomerates, Siemens Healthineers and Abbott Laboratories exemplify platform integrators leveraging installed automation bases for recurring revenue streams. Roche Diagnostics occupies a position within the molecular diagnostics specialist tier, anchoring nucleic acid testing penetration in reference laboratory settings. Grifols represents the vertically integrated archetype, with captive plasma collection networks feeding proprietary screening workflows across European and North American sites.
| Leading Market Players |
|---|
| Bio-Rad Laboratories |
| Siemens Healthineers |
| Roche Diagnostics |
| DiaSorin |
| Becton, Dickinson and Company |
| Grifols |
| Immucor |
| Danaher |
| Abbott Laboratories |
| Others |
Supply & Pricing Matrix
German and Japanese reagent manufacturers anchor the upstream chemistry tier, concentrating margin capture in proprietary nucleic acid test kits while downstream blood banks absorb price volatility through locked-in consumable contracts. This upstream concentration forces mid-sized transfusion services into single-source dependencies that limit procurement leverage across multi-year assay validation cycles.
Pricing Analysis
Configured-to-order PCR and TMA platform pricing commands substantial premiums over standard serological instrument configurations. The dominant structure runs through per-test reagent contracts bundled with equipment lease arrangements, where FDA biologics license tier and EMA compliance certification drive price differentiation. Pricing pressure stems from asset-light leasing models compressing capital recovery timelines for vendors. Regional hospitals exhibit highest price sensitivity due to constrained capital budgets, while reference laboratories in Germany and Japan show lowest sensitivity given mandate-driven procurement urgency.
Supply Chain Analysis
Upstream feedstock for nucleic acid amplification chemistries draws from specialized polymerase enzyme production concentrated in Germany, the United States, and Japan. Critical inputs include fluorophore-labeled probes, reverse transcriptase enzymes, and cold-chain validated reaction vessels. Single-source vulnerability runs through proprietary reagent formulations locked to specific platform architectures. Distribution feeds from regional manufacturing hubs into blood bank central stores, with EU F-Gas Regulation compliance adding validation layers for temperature-controlled logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is cycling through post-mandate infrastructure replacement as nucleic acid testing protocols mature across major jurisdictions, creating procurement windows that favor vendors with leasing flexibility.
For Market Incumbents: Insulate installed base relationships by embedding informatics platforms that raise switching costs for blood banks migrating to individual donation testing protocols. Extend backward integration into critical reagent chemistries to offset supply concentration risk from single-source enzyme suppliers. Prioritize EMA and PMDA certification maintenance as regulatory convergence tightens quality thresholds.
For New Entrants and Emerging Players: Establish a beachhead in point-of-care compatibility testing for emergency transfusion settings where turnaround time requirements bypass centralized laboratory procurement. Target mid-tier regional hospitals in Spain and Australia with equipment-as-a-service arrangements that circumvent capital expenditure barriers. Lead with rapid serological instruments validated for trauma center workflows.
For Investors and Strategic Acquirers: Capital is best deployed toward molecular diagnostics specialists with validated nucleic acid testing platforms and established biologics license pathways. Long-term viability hinges on convergence readiness with next-generation sequencing integration. Watch FDA guidance on donor screening assay validation timelines as the inflection signal for platform upgrade cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA blood safety directive compliance unlocks German and French reference laboratory procurement. |
| Hospital System Partnership | Level I trauma center deployments in Baltimore and Houston anchor point-of-care instrument demand. |
| Reimbursement Strategy | Japanese PMDA nucleic acid testing mandate coverage secures sustainable per-test revenue streams. |
| Software Companion Development | Laboratory information management integration reduces blood bank technician training burdens. |
| Backward Integration | In-house polymerase enzyme production mitigates single-source supply risk for TMA reagent chemistries. |
Research Methodology
Desk research of FDA biologics license filings, EMA blood safety directives, and PMDA nucleic acid testing guidelines preceded structured interviews with blood bank laboratory directors, transfusion medicine specialists, molecular diagnostics platform engineers, and hospital procurement managers. Secondary validation drew from WHO prequalification databases, EU F-Gas Regulation compliance records, and GPO contract disclosures. Bottom-up instrumentation and reagent demand modeling was cross-checked against top-down healthcare expenditure allocations across the analysis window.
Assumptions held fixed included regulatory mandate timelines for nucleic acid testing adoption, while variables tested included leasing penetration rates and next-generation sequencing convergence speed. The analytical framework segmented by technology platform, end-user scale, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles and per-test consumable throughput. Forecast inputs incorporated surgical volume trajectories and trauma care expansion patterns.
Stress conditions across reagent cost volatility, FDA approval timeline extensions, and cold-chain logistics disruption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions about regulatory convergence and platform upgrade cycles. Cross-checking against hospital capital expenditure surveys and blood center procurement databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Europe Antinuclear Antibody Test Market
Diagnostics
Mycoplasma Detection System Market
Diagnostics
Netherlands in-Vitro Diagnostics Market
Diagnostics
HIV/HBV/HCV Test Kits Market
Diagnostics
Global Hemoglobin A1c Testing Devices Market
Diagnostics
Blood Grouping Reagents Market
Diagnostics
North America Non-Hodgkin Lymphoma Diagnostics Market
Diagnostics
Saudi Arabia in-Vitro Diagnostics (IVD) Market
Diagnostics
Non-Alcoholic Steatohepatitis (NASH) Biomarkers Market
Diagnostics
Multiple Myeloma Diagnostics Market
Diagnostics
Connected Diagnostics Market
Diagnostics
Direct Fluorescent Antibody Test Kits Market
Diagnostics
Blood Culture Media Market
Diagnostics
Middle East and Africa Lung Cancer Diagnostics Market
Diagnostics
Hydrogen Breath Test Analyzer Market
Diagnostics
Point of Care (Poc) Molecular Diagnostics Market