
 Infectious Respiratory Disease Diagnostics Market | 2026-2036
Infectious Respiratory Disease Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Infectious Respiratory Disease Diagnostics Market Intelligence
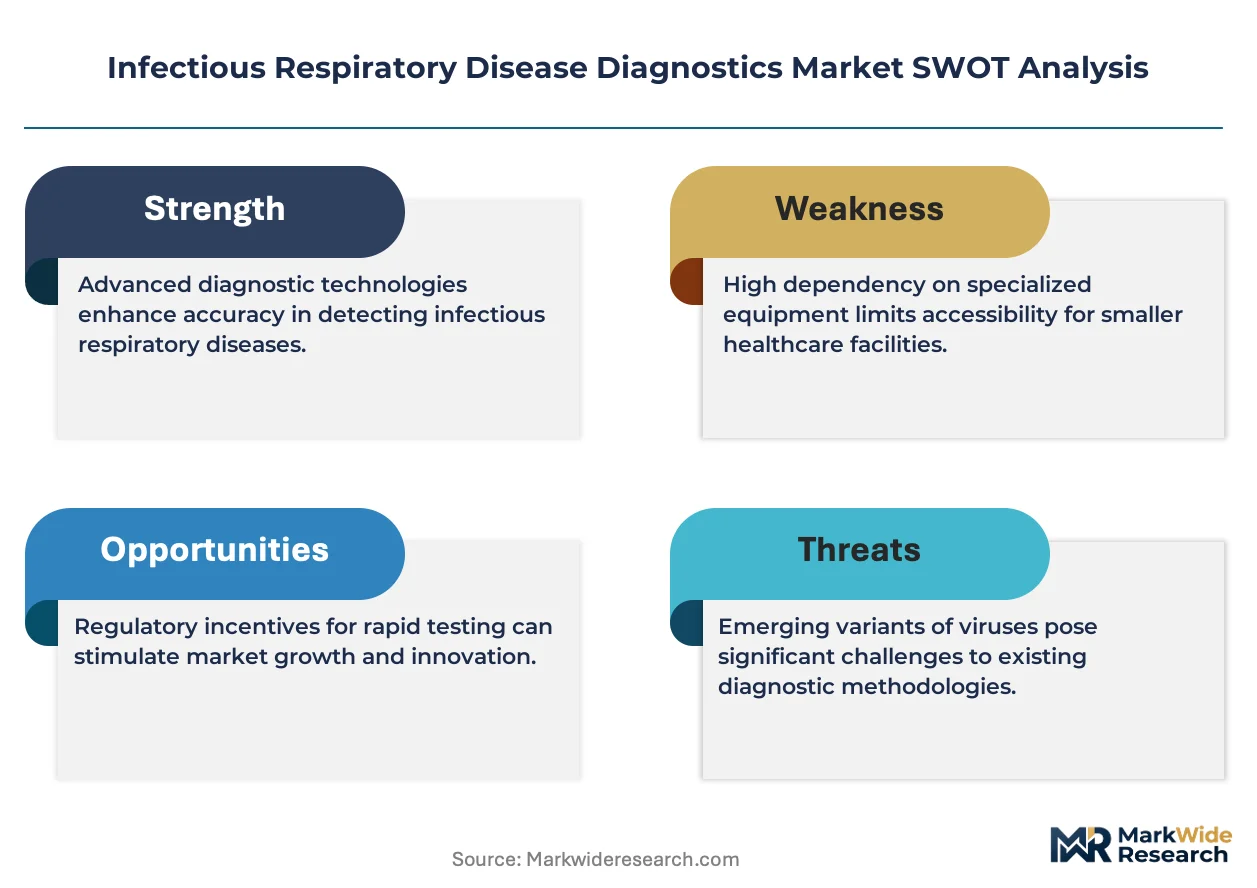
CLIA-waived molecular assay standards are rotating toward higher sensitivity thresholds and broader pathogen menus. Abbott leverages its integrated point-of-care platform to sustain channel dominance in physician offices and retail clinics. Thermo Fisher Scientific anchors high-throughput laboratory workflows through its specialized reagent and instrument portfolio. bioMérieux SA differentiates in European hospital networks with its blood culture and syndromic testing specialization.
Infectious respiratory disease diagnostics encompasses laboratory and point-of-care technologies that detect viral and bacterial pathogens causing acute respiratory infections, typically achieving analytical sensitivity below 100 copies per milliliter for nucleic acid amplification methods and delivering results within fifteen minutes to eight hours depending on platform complexity. These systems serve clinical decision-making by enabling targeted antiviral or antibiotic therapy, infection control protocols, and epidemiological surveillance. PCR tests command the deepest margin pools in centralized laboratory settings where reimbursement rates favor high-complexity molecular methods, while antigen tests occupy high-volume, lower-margin positions in seasonal retail and occupational health channels. Point-of-care delivery modes represent the fastest-expanding structural segment as decentralized diagnostic networks reduce turnaround time for critical therapeutic windows in influenza and RSV management.
FDA emergency use authorization pathways and CLIA complexity classifications shape product development priorities and commercial access for US manufacturers, while EMA in vitro diagnostic regulation and CE marking requirements under the EU IVDR govern European market entry and post-market surveillance obligations. Siemens Healthineers navigates this dual regulatory architecture through parallel quality management systems, and QIAGEN positions its sample preparation technologies to meet divergent preanalytical standards across jurisdictions. Stakeholders must monitor evolving WHO prequalification criteria for diagnostics targeting emerging respiratory pathogens in low-resource settings, as these standards increasingly influence procurement decisions by international health agencies and national pandemic preparedness programs.
Market Dynamics
CLIA-waived molecular platforms are compressing turnaround windows from centralized laboratories to retail clinics and physician offices, restructuring reimbursement flows and instrument placement economics across outpatient networks.
Growth Catalysts
- FDA Emergency Use Authorization Pathways:Accelerated clearance timelines for multiplex respiratory panels enable faster commercialization of expanded pathogen menus during seasonal surges.
- Hospital Emergency Department Networks:Point-of-care adoption concentrates in acute care settings where influenza and RSV therapeutic windows demand sub-one-hour diagnostic results.
- Antigen-Nucleic Acid Convergence:Hybrid assay formats combine rapid antigen screening with confirmatory molecular backup in single-platform workflows.
Market Restraints
- Reagent Supply Concentration:Polymerase and reverse transcriptase production clusters in specialized biochemical manufacturing regions, creating single-source vulnerability for assay developers.
- EU IVDR Transition Friction:Extended conformity assessment timelines for Class C and D in vitro diagnostics delay CE marking for syndromic respiratory panels.
- Antigen Test Margin Compression:Seasonal overcapacity in rapid immunoassay manufacturing drives pricing erosion below sustainable production economics for non-integrated suppliers.
Strategic Opportunities
- Home-Based Respiratory Surveillance:Telehealth-integrated self-collection kits for molecular testing create direct-to-consumer channels outside traditional laboratory billing.
- WHO Prequalification Alignment:Diagnostics meeting emerging international standards for pandemic preparedness unlock procurement contracts from global health agencies and national stockpile programs.
- CRISPR-PCR Convergence:Next-generation amplification methods reduce instrument complexity and power requirements for resource-limited deployment.
Industry Challenges
- Laboratory Information System Integration:Point-of-care devices require bidirectional connectivity with hospital EHR platforms, creating IT validation bottlenecks.
- Multiplex Assay Validation Complexity:Expanded pathogen menus demand larger clinical studies for analytical and clinical performance claims, extending development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infectious Respiratory Disease Diagnostics Market |
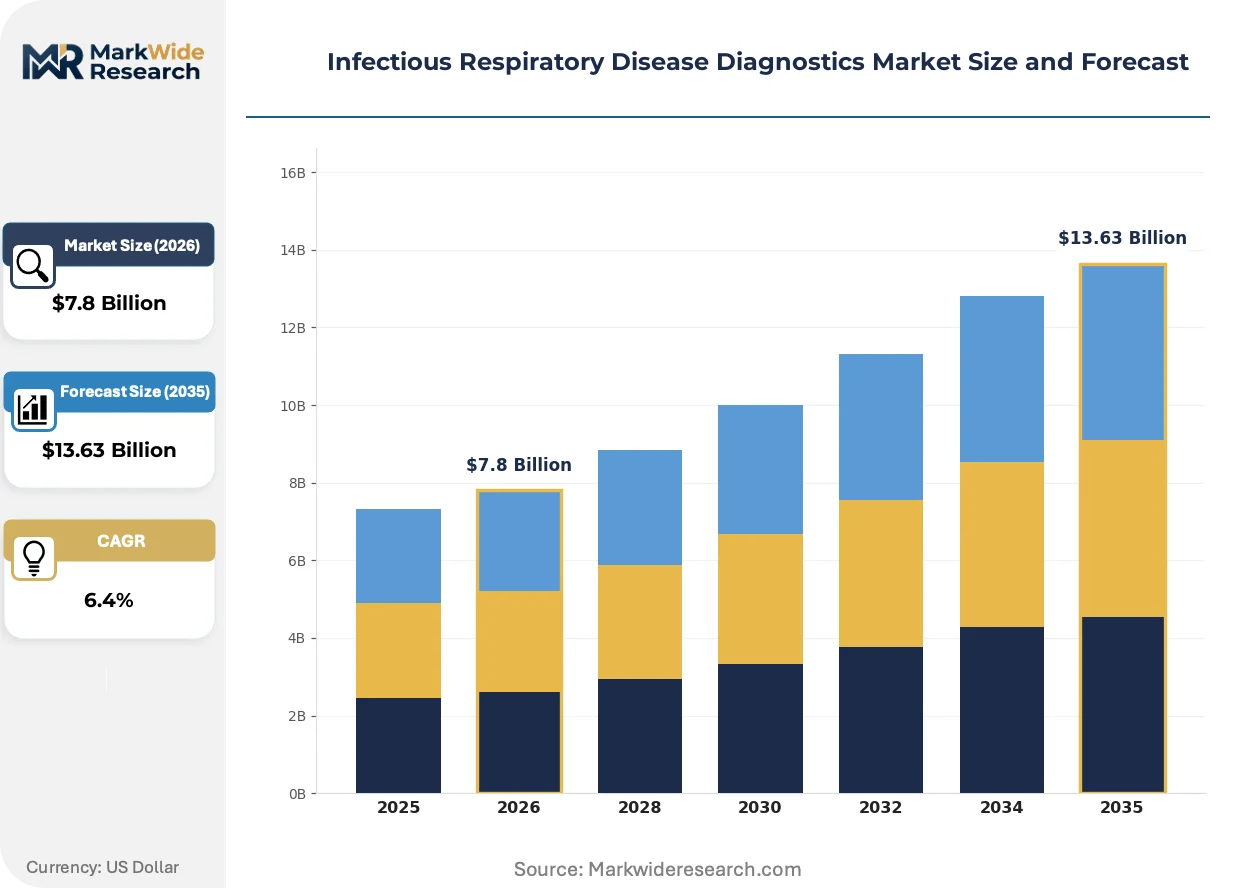
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PCR Tests, Antigen Tests, Serological Tests, Viral Culture Delivery Mode: Point-of-Care, Laboratory-based, Home Testing, Mobile Testing Units End User: Hospitals, Diagnostic Laboratories, Physician Offices, Research Institutions Application: Influenza, COVID-19, RSV, Emerging Pathogens |
| Companies Covered | Abbott, Thermo Fisher Scientific Inc., F. Hoffmann-La Roche Ltd., bioMérieux SA, BD, Danaher, Siemens Healthineers AG, QIAGEN, Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infectious Respiratory Disease Diagnostics Market Strategic Shifts & Innovations
Respiratory diagnostics is fragmenting across three simultaneous vectors: instrument miniaturization, regulatory pathway diversification, and care setting decentralization. These forces collectively compress the traditional centralized laboratory model.
Digital PCR and isothermal amplification methods are decomposing the monopoly of real-time PCR in high-sensitivity detection. Reference laboratories in Germany and Japan are adopting these alternatives for quantitative viral load monitoring in immunocompromised patients. The shift enables smaller footprint instruments and reduces dependence on thermal cycler supply chains.
EMA's In Vitro Diagnostic Regulation and FDA's transition to permanent marketing authorization for emergency-use devices are creating divergent evidence requirements. Manufacturers must maintain parallel clinical study programs to satisfy European notified bodies and US premarket submission standards. High-complexity molecular assays face the steepest compliance burden as both jurisdictions tighten post-market surveillance obligations.
Hospital procurement committees are unbundling instrument placement from reagent supply agreements, reversing decade-long exclusive vendor relationships. IDNs in the United States now negotiate platform-agnostic contracts with multiple assay suppliers. This fragmentation rewards manufacturers with flexible menu expansion capabilities rather than locked installed bases.
Infectious Respiratory Disease Diagnostics Market Segmentation
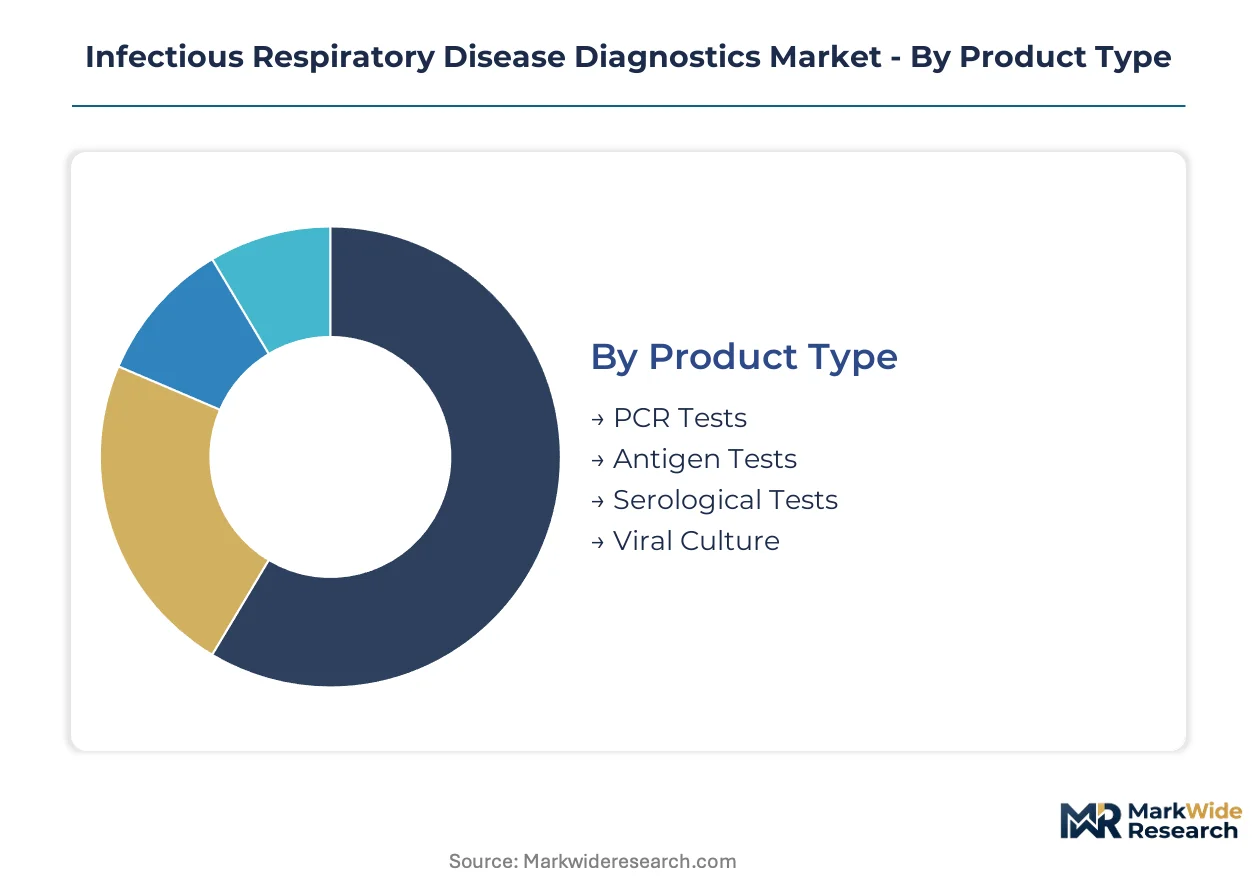
Respiratory diagnostics segments fragment across regulatory complexity tiers, with FDA CLIA classifications and EU IVDR risk categories determining commercial access routes and reimbursement economics for each product category.
Product Type:
FDA emergency use authorization pathways and CLIA complexity classifications create divergent commercial trajectories across molecular and immunoassay formats.
- PCR Tests:Nucleic acid amplification methods achieve analytical sensitivity below 100 copies per milliliter. Centralized laboratories in the United States and Germany concentrate demand here, driven by reimbursement premiums for high-complexity molecular methods.
- Antigen Tests:Lateral flow immunoassays deliver results within fifteen minutes without thermal cycling infrastructure. Retail clinics and occupational health channels in Japan absorb high seasonal volumes despite compressed margins.
- Serological Tests:Antibody detection assays serve epidemiological surveillance and immunity assessment applications.
- Viral Culture:Traditional cell-based isolation methods persist in reference laboratories for strain characterization and antiviral susceptibility testing.
PCR tests handle the majority of throughput; antigen tests are expanding most quickly on share.
Delivery Mode:
Cost tier differentiation separates capital-intensive laboratory platforms from disposable rapid formats, restructuring instrument placement economics and reagent contract structures.
- Point-of-Care:CLIA-waived molecular platforms and rapid antigen devices compress turnaround windows to under one hour. Hospital emergency departments in the United States drive adoption for influenza and RSV therapeutic decision-making.
- Laboratory-based:High-throughput automated systems process multiplex respiratory panels with syndromic pathogen menus. Centralized networks in Germany leverage this mode for population-scale surveillance.
- Home Testing:Telehealth-integrated self-collection kits bypass traditional laboratory billing channels.
- Mobile Testing Units:Deployable diagnostic trailers serve outbreak response and rural access programs.
Laboratory-based systems retain the deepest installed base; point-of-care is climbing the fastest on volume contribution.
End User:
Procurement authority and reimbursement pathways concentrate demand differently across institutional settings, with integrated delivery networks unbundling exclusive vendor relationships.
- Hospitals:Acute care networks prioritize rapid turnaround for infection control and antiviral stewardship. Emergency departments in Japan and the United States represent the highest-value placement targets for point-of-care molecular platforms.
- Diagnostic Laboratories:Reference networks anchor high-throughput PCR workflows and multiplex panel standardization.
- Physician Offices:CLIA-waived waived testing expansion reshapes retail clinic and primary care access models.
- Research Institutions:Academic medical centers validate emerging amplification methods and CRISPR-based detection formats.
Hospitals command the largest procurement budgets; physician offices are gaining share fastest on test volume.
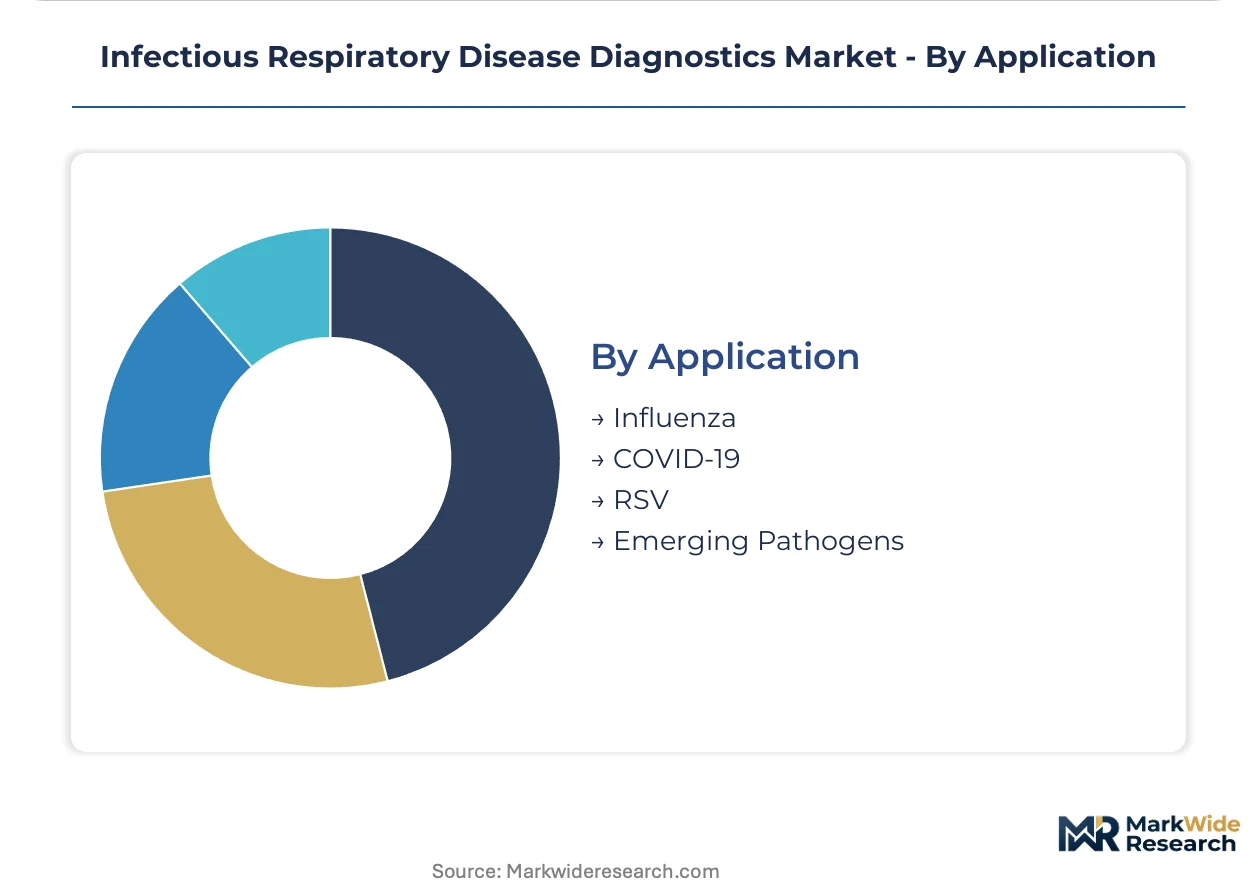
Application:
Pathogen-specific assay menus align with seasonal epidemiology and pandemic preparedness stockpiling cycles, determining R&D prioritization and manufacturing capacity allocation.
- Influenza:Seasonal surveillance drives annual assay updates for circulating strain matching. Public health laboratories in Germany coordinate sentinel monitoring networks.
- COVID-19:Transition from emergency use authorization to permanent marketing authorization reshapes commercial requirements. The FDA's evolving pathway standards continue influencing product clearance timelines.
- RSV:Pediatric and geriatric therapeutic windows demand rapid diagnostic confirmation. Hospital networks in the United States concentrate testing volume during winter surges.
- Emerging Pathogens:WHO prequalification criteria and national stockpile programs shape procurement for pandemic preparedness.
Influenza and COVID-19 together absorb the dominant test volume; emerging pathogen preparedness shows the steepest expansion trajectory on forward investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German diagnostics manufacturers export multiplex respiratory panels to hospital networks across the United States and Japan, while American point-of-care platforms flow into European emergency departments through specialized distribution channels.
United States
Hospital emergency departments in Boston and Houston drive point-of-care molecular adoption for influenza and RSV therapeutic windows. FDA emergency use authorization pathways accelerate clearance timelines for expanded pathogen menus during seasonal surges. The Research Triangle Park cluster in North Carolina anchors high-throughput reagent manufacturing for centralized laboratory networks.
Germany
Public health laboratories in Berlin and Munich coordinate sentinel monitoring networks for circulating influenza strain matching. EMA in vitro diagnostic regulation and EU IVDR conformity assessments govern CE marking timelines for syndromic respiratory panels. The Rhine-Main region concentrates automated instrument manufacturing serving reference laboratory workflows across Europe.
Japan
Pediatric and geriatric therapeutic windows in Tokyo and Osaka hospital networks demand rapid RSV and influenza diagnostic confirmation. PMDA marketing authorization requirements shape clinical study designs for multiplex molecular assays. The Kansai region hosts specialized biochemical manufacturing for polymerase and reverse transcriptase production.
United Kingdom
NHS England procurement frameworks reshape point-of-care placement economics in London and Manchester acute care networks. MHRA post-market surveillance obligations tighten evidence requirements for high-complexity molecular methods. The Cambridge-Oxford corridor anchors CRISPR-based detection research transitioning toward clinical validation.
China
NMPA regulatory pathways for innovative diagnostics create dual-track approval processes for domestic and imported respiratory assays. Nucleic acid amplification manufacturing clusters in Suzhou and Shenzhen supply reagents for regional hospital networks. The Yangtze River Delta integrates sample preparation technologies with high-throughput automated platforms.
Infectious Respiratory Disease Diagnostics Market Key Industry Players
Listed leaders compete with private specialists across instrument placement and reagent supply contracts, producing a tiered structure where scale-driven conglomerates anchor high-throughput laboratory workflows while focused innovators capture point-of-care expansion. Three archetypes dominate: integrated life science conglomerates with parallel diagnostic and research reagent portfolios, specialized in vitro diagnostic pure-plays with regulatory pathway expertise, and emerging platform developers leveraging isothermal amplification and CRISPR convergence. Competitive moves concentrate on unbundling exclusive vendor relationships through platform-agnostic procurement contracts and backward integration into polymerase supply chains.
Among the integrated conglomerates, Abbott and Danaher exemplify the dual-track model spanning centralized laboratory and decentralized point-of-care networks. Thermo Fisher Scientific occupies a position representing the life science reagent-to-diagnostics pipeline. These three entities anchor the competitive landscape through instrument installed bases and recurring reagent revenue structures rather than transactional assay sales.
| Leading Market Players |
|---|
| Abbott |
| Thermo Fisher Scientific Inc. |
| F. Hoffmann-La Roche Ltd. |
| bioMérieux SA |
| BD |
| Danaher |
| Siemens Healthineers AG |
| QIAGEN |
| Koninklijke Philips N.V. |
| Others |
Cost & Logistics Intelligence
Ninety-day polymerase inventory buffers in Japanese biochemical manufacturing clusters signal supply-chain rigidity that amplifies pricing power for integrated assay developers while squeezing non-integrated suppliers during seasonal demand surges.
Pricing Analysis
Hospital procurement committees anchor contract-based long-term offtake structures for high-throughput PCR platforms, with pricing stratification across FDA-cleared premium tiers, CE-marked standard tiers, and CLIA-waived economy tiers. Cost compression in rapid antigen manufacturing intensifies because seasonal overcapacity erodes margins below sustainable production economics. Reference laboratories exhibit lowest price sensitivity due to reimbursement premiums for high-complexity molecular methods, while retail clinics face acute sensitivity to per-test disposable costs.
Supply Chain Analysis
Ninety-day polymerase inventory buffers expose single-source vulnerability concentrated in Japanese and German biochemical manufacturing regions, where reverse transcriptase and specialized enzyme production clusters. Assay developers draw from Chinese plastic consumables molding, South Korean optical component fabrication, and domestic reagent formulation. Distribution runs through platform-agnostic procurement contracts that unbundle instrument placement from exclusive reagent supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antigen-nucleic acid hybrid platforms threaten pure-play molecular incumbents by collapsing the traditional premium-economy test segmentation that has structured respiratory diagnostics margins for a decade.
For Market Incumbents: Shield installed base economics through backward integration into polymerase supply chains and captive production of CLIA-waived molecular consumables. Consolidate channel control by embedding bidirectional EHR connectivity that raises switching costs for hospital emergency departments facing IT validation bottlenecks. The hybrid assay convergence demands defensive menu expansion into combined rapid screening and confirmatory workflows. For New Entrants and Emerging Players: FDA emergency use authorization fast-tracks offer the most penetrable regulatory pathway for multiplex respiratory panels targeting seasonal surge windows. White-space concentrates in telehealth-integrated home collection kits that bypass traditional laboratory billing channels. A direct-to-consumer go-to-market angle paired with subscription-based result delivery unlocks procurement contracts outside GPO-dominated hospital networks. For Investors and Strategic Acquirers: Carve-out targets emerge from life science conglomerates divesting non-core diagnostic divisions amid portfolio rationalization pressures. Long-term viability hinges on platform-agnostic menu expansion capabilities rather than locked instrument bases. Watch for WHO prequalification alignment as the inflection signal unlocking pandemic preparedness stockpile procurement.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA-Waived Molecular Platform Launch | Abbott and Danaher channel dominance in physician offices accelerates point-of-care volume capture. |
| Backward Integration into Polymerase Supply | Thermo Fisher Scientific reduces single-source vulnerability from Japanese biochemical manufacturing clusters. |
| Hospital System Partnership for EHR Connectivity | Siemens Healthineers navigates IT validation bottlenecks through bidirectional platform integration. |
| EU IVDR Conformity Assessment Fast-Track | bioMérieux SA differentiates syndromic panel timelines against extended CE marking delays. |
| Telehealth-Integrated Home Collection Kit | QIAGEN sample preparation technologies enable direct-to-consumer channels outside laboratory billing. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital laboratory directors, emergency department clinicians, GPO contracts managers, and point-of-care platform engineers. Secondary validation drew from FDA 510(k) filings, EMA IVDR submission databases, CMS Medicare reimbursement schedules, and hospital procurement contract repositories. Bottom-up instrument placement counts triangulated against top-down reagent revenue estimates across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type, delivery mode, end-user institution, and target pathogen application. CAGRs were derived from regression-based trending of historical placement volumes and forward-looking reimbursement trajectory assumptions. Forecast inputs incorporated seasonal epidemiology patterns, regulatory pathway velocity differentials, and pandemic preparedness stockpiling cycles.
Decision-makers should treat outputs as directional under base assumptions of stable FDA emergency use authorization pathways and uneventful EU IVDR transition timelines; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Middle East and Africa in-Vitro Diagnostics Market
Diagnostics
UAE in Vitro Diagnostics Market
Diagnostics
Chile in Vitro Diagnostics Market
Diagnostics
Direct Fluorescent Antibody Test Kits Market
Diagnostics
Infectious Disease in Vitro Diagnostics Market
Diagnostics
North America Autoimmune Disease Diagnostics Market
Diagnostics
Veterinary Molecular Diagnostics Market
Diagnostics
Diabetic Assays Market
Diagnostics
Febrile Antigen Kits Market
Diagnostics
Japan in-Vitro Diagnostics Market
Diagnostics
Middle East and Africa Thyroid Cancer Diagnostics Market
Diagnostics
Veterinary Rapid Diagnostic Tests Market
Diagnostics
IVD Antibody Market
Diagnostics
Diabetes Diagnostics Market
Diagnostics
Haptoglobin Reagent Market
Diagnostics
Antibody Testing Market