
 Intra-Abdominal Infection Treatment Market | 2026-2036
Intra-Abdominal Infection Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Intra-Abdominal Infection Treatment Market Foresight
India's active pharmaceutical ingredient manufacturing base is narrowing the cost gap for generic broad-spectrum antibiotics used in peritonitis protocols. Pfizer leverages its established carbapenem portfolio to sustain formulary positioning across major hospital systems. Merck & Co. anchors its presence through anaerobic coverage leadership, while AstraZeneca competes on newer combination therapies with improved resistance profiles.
Intra-abdominal infection treatment encompasses pharmaceutical and surgical interventions targeting peritonitis, abscess, and post-operative sepsis originating below the diaphragm, typically requiring agents with gram-negative, gram-positive, and anaerobic coverage plus source control procedures. The therapeutic paradigm demands agents achieving adequate peritoneal fluid penetration above minimum inhibitory concentrations. Antibiotics occupy the largest value share as first-line empiric therapy dominates hospital admission protocols, while intravenous delivery leads due to severity-driven initial administration in acute care settings. Oral step-down therapy represents the fastest transition point as early discharge programs expand, though home healthcare penetration for IV-to-oral conversion remains limited by reimbursement complexity.
FDA antimicrobial stewardship requirements shape prescribing patterns through mandated spectrum de-escalation reviews, while EMA's evolving environmental risk assessment guidelines for antibiotics influence manufacturing investment decisions. The WHO Essential Medicines List criteria for reserve antibiotic classification directly impact R&D prioritization for novel agents against multidrug-resistant pathogens. Stakeholders must monitor resistance surveillance data from the CDC's Emerging Infections Program to anticipate formulary shifts and guide pipeline targeting toward pathogens with documented treatment gaps.
Market Dynamics
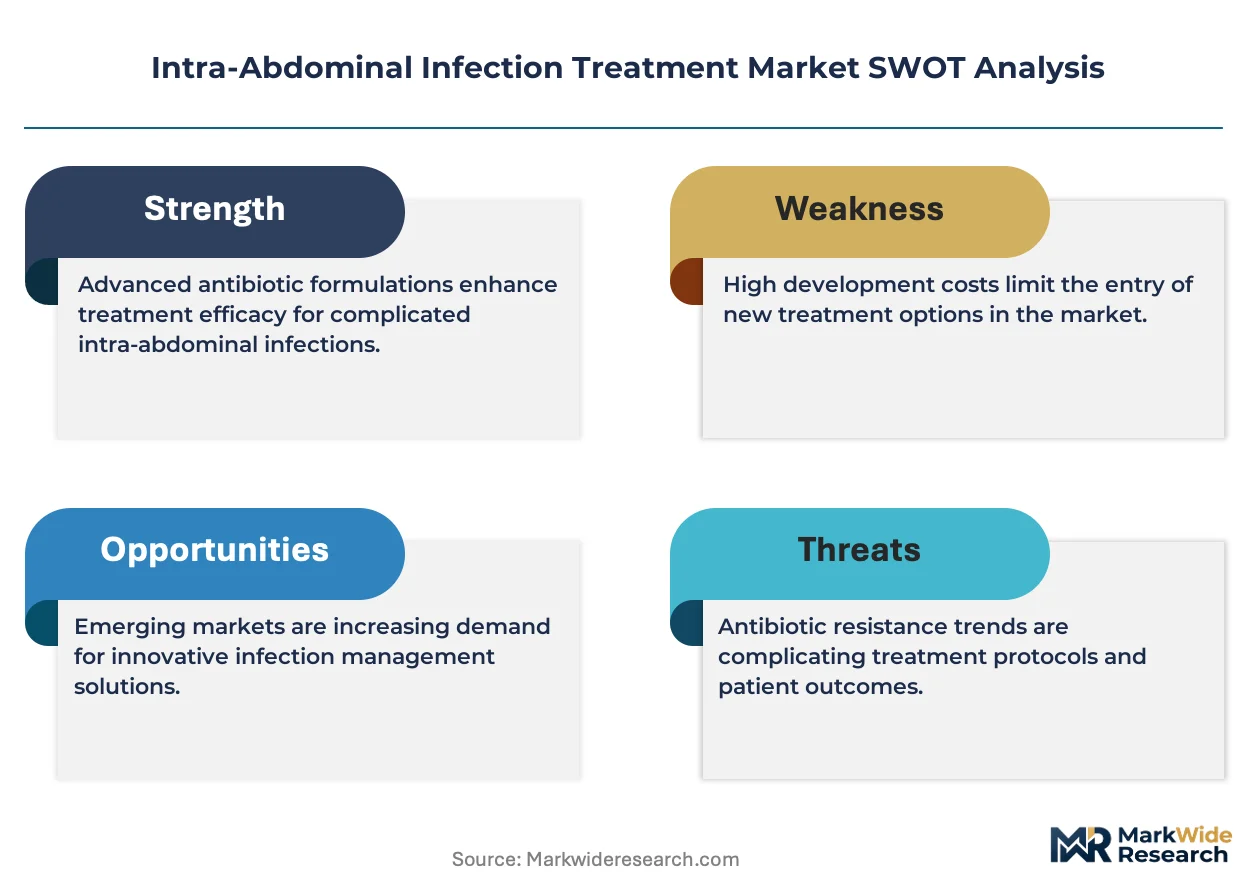
FDA antimicrobial stewardship mandates are forcing hospital formulary committees to de-escalate empiric broad-spectrum therapy within 48-72 hours, compressing the window for carbapenem and piperacillin-tazobactam dominance in complicated intra-abdominal infection protocols.
Growth Catalysts
- Rising surgical volume in tertiary centers:Complex hepatobiliary and colorectal procedures generate post-operative infection burden requiring prolonged IV antibiotic courses. Academic medical centers in the United States report the highest per-facility case volumes.
- CDC Emerging Infections Program surveillance expansion:Real-time resistance data enables faster formulary pivots toward targeted agents. Hospital pharmacists leverage this intelligence to justify narrow-spectrum substitutions.
- Peritoneal penetration pharmacokinetics:Next-generation beta-lactam/beta-lactamase combinations achieve higher peritoneal fluid concentrations. Surgeons specify these agents in enhanced recovery after surgery protocols.
Market Restraints
- API supply concentration in India:Generic carbapenem active pharmaceutical ingredients depend on facilities in Hyderabad and Ahmedabad. Quality compliance actions at these sites disrupt global antibiotic availability.
- Environmental discharge restrictions:EMA's evolving environmental risk assessment guidelines for antibiotics impose costly wastewater treatment investments on manufacturing plants.
- Oral bioavailability limitations:Few agents achieve adequate plasma exposure via enteral route for deep-seated abscess penetration. Step-down therapy options remain constrained.
Strategic Opportunities
- Home infusion for IV-to-oral transition:Medicare reimbursement simplification for outpatient parenteral antimicrobial therapy would unlock early discharge revenue. Home healthcare agencies stand to capture margin from shortened length-of-stay.
- Plazomicin and cefiderocol reserve positioning:WHO Essential Medicines List criteria for last-resort antibiotics create R&D prioritization signals. Developers target carbapenem-resistant Enterobacterales with novel mechanisms.
- AI-assisted susceptibility prediction:Machine learning models trained on local antibiograms enable pre-emptive spectrum narrowing. Early adopters in integrated delivery networks reduce unnecessary broad-spectrum exposure.
Industry Challenges
- ID physician staffing shortages:Fellowship-trained infectious disease specialists are required for stewardship compliance and de-escalation decisions. Rural hospitals face recruitment gaps that delay protocol implementation.
- IV-to-oral switch protocol standardization:Absence of harmonized clinical criteria across hospital systems creates formulary fragmentation. Pharmacy and therapeutics committees expend resources reconciling divergent guidelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intra-Abdominal Infection Treatment Market |
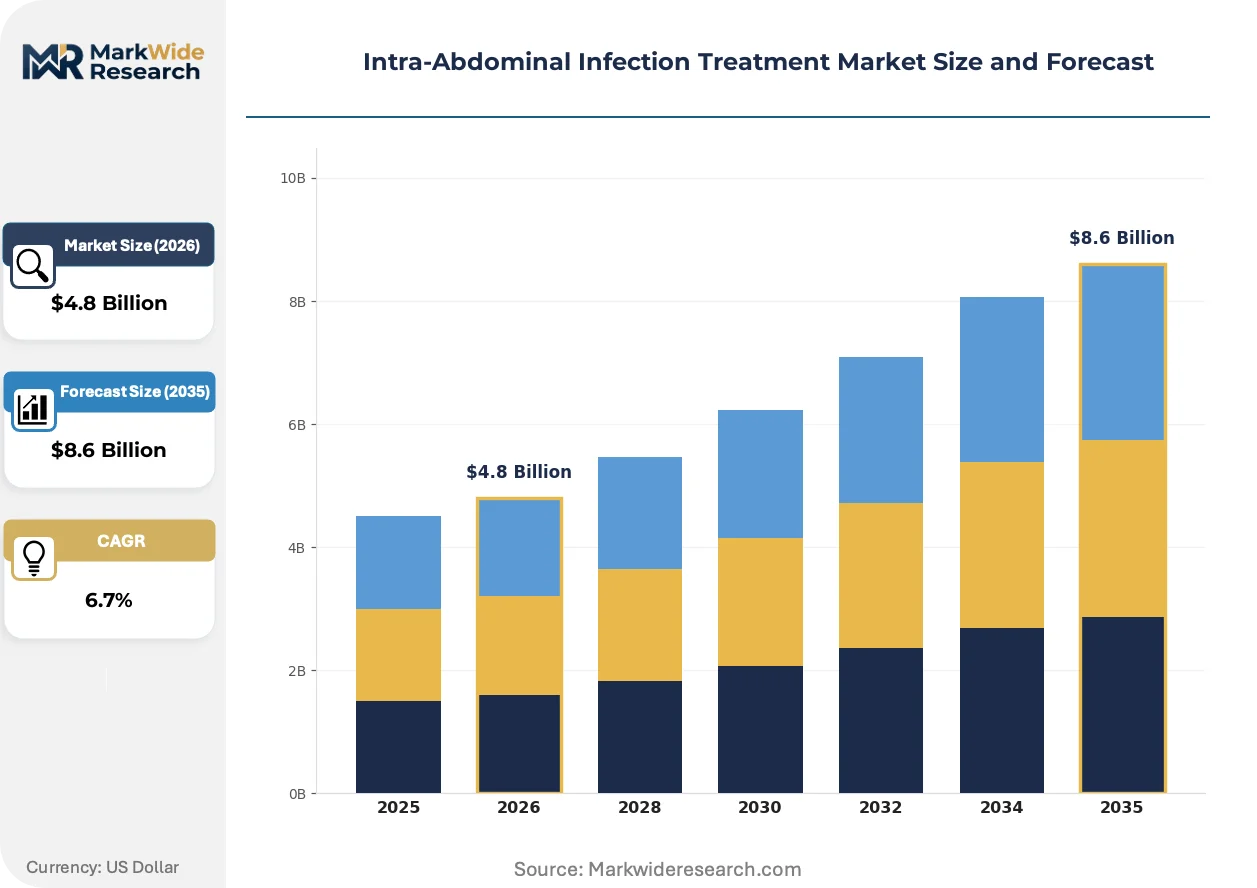
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Antifungals, Antiseptics, Non-Steroidal Anti-Inflammatory Drugs Delivery Mode: Intravenous, Oral, Topical, Intra-abdominal End User: Hospitals, Ambulatory Surgical Centers, Clinics, Home Healthcare Treatment Stage: Acute Care, Chronic Management, Surgical Intervention, Preventive Care |
| Companies Covered | Pfizer, Merck & Co., AstraZeneca, Johnson & Johnson, AbbVie, Novartis, Bayer, Bristol-Myers Squibb, Boehringer Ingelheim, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intra-Abdominal Infection Treatment Market Shifts & Advancements
Antibiotic development is pivoting toward pathogen-specific approaches as resistance surveillance reveals geographic variation in dominant mechanisms. Manufacturers now prioritize agents with demonstrated activity against carbapenem-resistant isolates.
Extended-infusion beta-lactam administration is migrating from academic research protocols to standard-of-care implementation in surgical intensive care units. Pharmacists at tertiary centers adopt software-guided dosing to optimize time above minimum inhibitory concentration. This technology is compressing mortality in severe sepsis while reducing total antibiotic consumption per episode.
EMA's tightened environmental risk assessment guidelines for antibiotics now require aquatic toxicity data prior to marketing authorization. Manufacturing investment is flowing toward closed-loop synthesis and advanced oxidation wastewater treatment. Generic producers in India face capital expenditure pressure that favors consolidated production at scale-compliant facilities.
Hospital procurement committees are bundling antibiotic spend with diagnostic stewardship contracts. Integrated delivery networks negotiate volume commitments spanning microbiology platforms and therapeutic agents. This pattern concentrates most visibly in United States health systems pursuing Medicare shared savings program incentives.
Intra-Abdominal Infection Treatment Market Segmentation
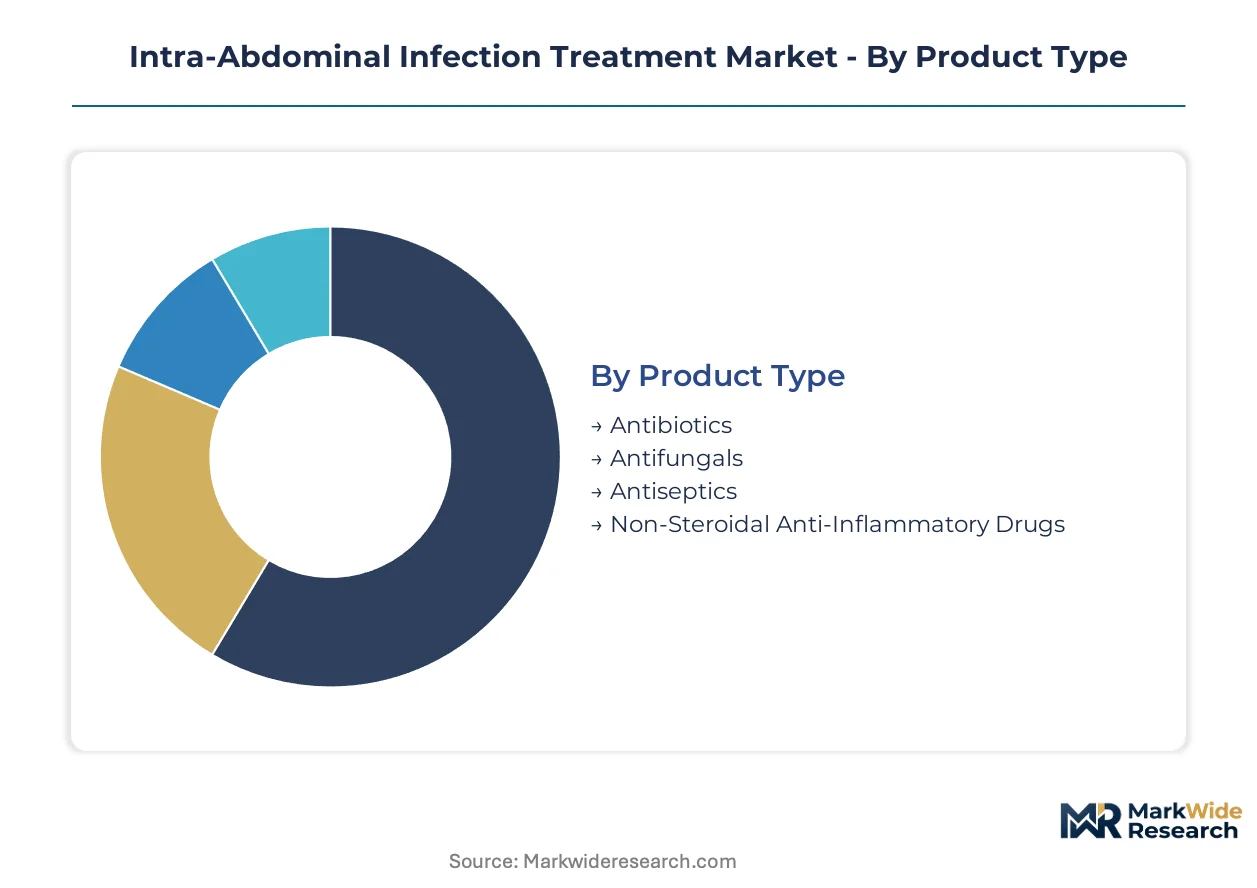
Segmentation in intra-abdominal infection treatment reveals distinct velocity profiles across therapeutic categories. Cycle times differ sharply between acute surgical interventions and chronic management protocols, dictating inventory strategies and revenue recognition patterns for manufacturers.
Product Type:
Antibiotics turn inventory fastest due to empiric protocol standardization, while antifungals and antiseptics rotate more slowly as targeted therapy applications.
- Antibiotics:Beta-lactam/beta-lactamase combinations, carbapenems, and fluoroquinolones dominate formulary positioning. Tertiary care centers in the United States drive volume through broad-spectrum empiric protocols for complicated intra-abdominal infections. FDA antimicrobial stewardship mandates compress duration of therapy, accelerating prescription turnover.
- Antifungals:Azoles and echinocandins target Candida peritonitis in immunocompromised surgical patients. Demand concentrates in oncology and transplant units where prolonged ICU stays elevate fungal superinfection risk. Narrower indication scope slows inventory velocity versus antibacterial agents.
- Antiseptics:Povidone-iodine and chlorhexidine solutions serve perioperative skin preparation and wound irrigation.
- Non-Steroidal Anti-Inflammatory Drugs:Adjunctive pain management with ketorolac and ibuprofen complements antimicrobial therapy.
Antibiotics dominate installed base. Antifungals are where expansion concentrates.
Delivery Mode:
Cost tiering separates acute parenteral administration from economical oral step-down, with reimbursement differentials shaping channel economics.
- Intravenous:Initial empiric therapy for severe sepsis and post-operative peritonitis requires hospital-based infusion. Medicare severity-adjusted diagnosis-related groups reward rapid IV initiation in acute care settings. Extended-infusion protocols optimize pharmacokinetic exposure in surgical ICUs.
- Oral:Step-down conversion enables early discharge and reduced length-of-stay penalties. Bioavailability limitations constrain agent selection for deep-seated abscess penetration. Reimbursement complexity for outpatient parenteral antimicrobial therapy suppresses home-based IV-to-oral transition.
- Topical:Surgical site irrigation and wound dressing applications serve localized infection control.
- Intra-abdominal:Direct instillation during laparotomy or percutaneous drainage procedures delivers concentrated local therapy.
Intravenous commands premium pricing. Oral conversion is climbing the fastest.
End User:
Customer type segmentation aligns procurement scale with clinical complexity, from high-volume hospital systems to dispersed home settings.
- Hospitals:Tertiary academic medical centers manage the highest per-facility case volumes of complicated intra-abdominal infections. Integrated delivery networks bundle antibiotic spend with diagnostic stewardship contracts. Pharmacy and therapeutics committees enforce formulary restrictions through antimicrobial stewardship programs.
- Ambulatory Surgical Centers:Elective procedures generate lower acuity infection burden with shorter antibiotic courses. Outpatient surgical protocols favor narrow-spectrum prophylaxis over empiric broad-spectrum therapy.
- Clinics:Community-based settings handle uncomplicated cases and post-discharge monitoring.
- Home Healthcare:IV-to-oral transition and long-term catheter management extend therapy beyond institutional walls.
Hospitals anchor volume concentration. Home healthcare is gaining share fastest.
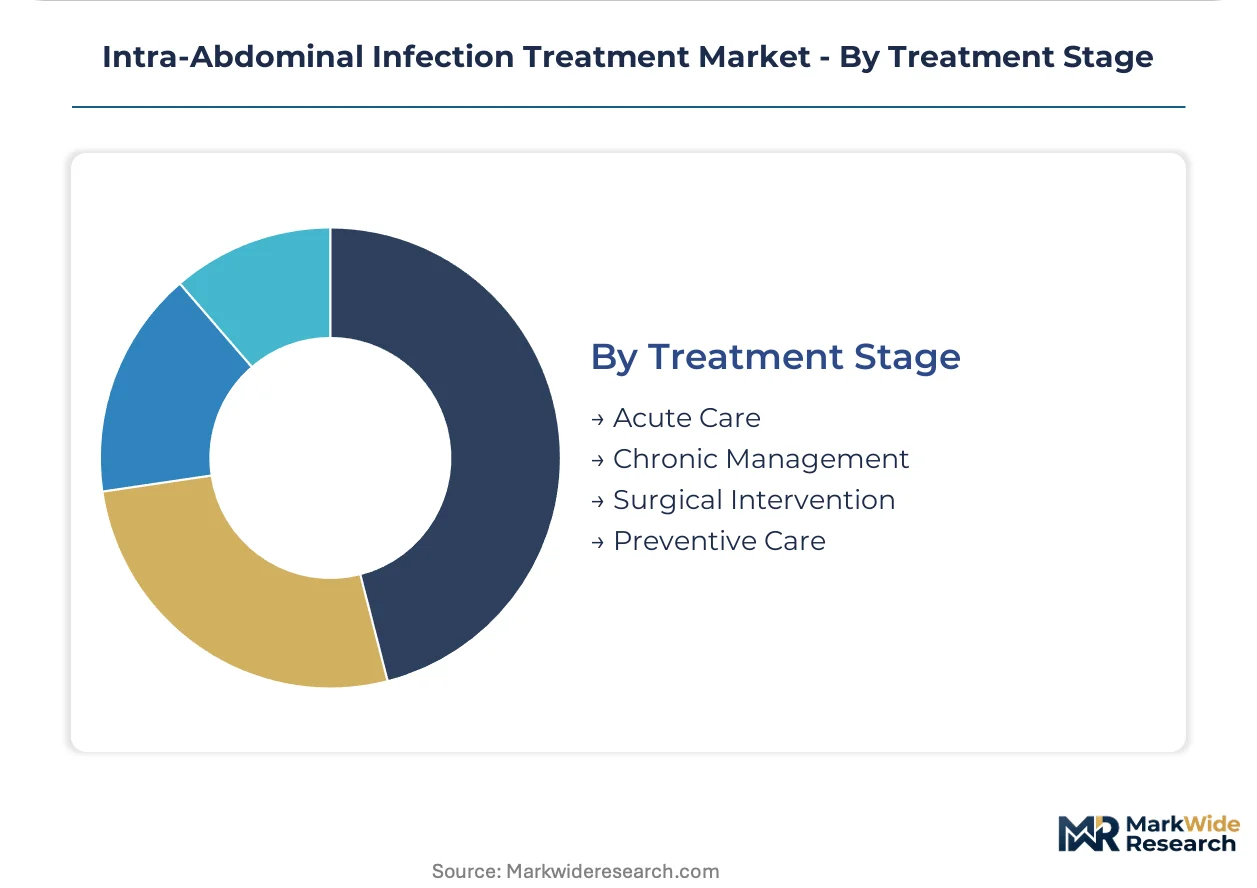
Treatment Stage:
Maturity gradients separate established acute protocols from emerging preventive approaches, with surgical intervention occupying intermediate development.
- Acute Care:Empiric antimicrobial initiation within one hour of sepsis recognition follows Surviving Sepsis Campaign guidelines. Source control through drainage or reoperation remains mandatory alongside pharmacologic therapy. Mortality reduction metrics drive protocol adherence in quality reporting.
- Surgical Intervention:Source control procedures including laparotomy, percutaneous drainage, and abscess evacuation define therapeutic success. Enhanced recovery after surgery protocols integrate antibiotic selection with minimally invasive approaches.
- Chronic Management:Recurrent intra-abdominal infections in cirrhotic patients require suppressive or rotating antibiotic strategies.
- Preventive Care:Perioperative prophylaxis and selective decontamination protocols target high-risk surgical populations.
Acute care dominates installed base. Preventive care is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA antimicrobial stewardship mandates anchor the United States as the dominant geography, while EMA environmental risk assessments reshape European manufacturing economics and India's API concentration creates supply vulnerabilities.
United States
Tertiary academic medical centers in Boston, Houston, and Cleveland manage the highest per-facility case volumes of complicated intra-abdominal infections. Medicare severity-adjusted diagnosis-related groups reward rapid IV antibiotic initiation, accelerating formulary standardization. The CDC's Emerging Infections Program surveillance expansion enables real-time resistance data feeds to hospital pharmacists.
Germany
Bavarian and North Rhine-Westphalian hospital systems drive demand for carbapenem-sparing protocols in post-operative peritonitis. EMA's tightened environmental risk assessment guidelines for antibiotics impose costly wastewater treatment investments on manufacturing plants. Frankfurt-based procurement consortia negotiate bundled antibiotic and diagnostic stewardship contracts.
India
Hyderabad and Ahmedabad API manufacturing clusters supply generic carbapenem active pharmaceutical ingredients to global antibiotic formulators. CDSCO quality compliance actions at these facilities periodically disrupt international availability. Maharashtra's contract research organizations support bioequivalence studies for abbreviated new drug applications.
Japan
Tokyo and Osaka metropolitan hospitals adopt extended-infusion beta-lactam protocols guided by PMDA-approved pharmacokinetic software. METI funding for antimicrobial resistance countermeasures accelerates local susceptibility surveillance infrastructure. Kansai-region medical device manufacturers integrate antibiotic-coated surgical meshes into enhanced recovery protocols.
United Kingdom
London and Manchester integrated care systems implement AI-assisted susceptibility prediction for pre-emptive spectrum narrowing. NHS England antimicrobial stewardship targets compress duration of therapy in complicated intra-abdominal infections. Scottish hospital pharmacies pioneer home infusion models for IV-to-oral transition.
Intra-Abdominal Infection Treatment Market Competitive Landscape
Capability concentration sits with established pharmaceutical majors possessing carbapenem and beta-lactamase inhibitor portfolios; scale advantage sits with generic API manufacturers in India. The market structures around three archetypes: broad-spectrum antibiotic developers, anaerobic coverage specialists, and combination therapy innovators. Dominant competitive moves include formulary positioning through hospital system partnerships and manufacturing consolidation to meet EMA environmental compliance.
Among established pharmaceutical developers, Pfizer, Merck & Co., and AstraZeneca exemplify distinct strategic positioning within the market. Pfizer occupies a position anchored by carbapenem portfolio breadth across major hospital systems. Merck & Co. sits within the anaerobic coverage leadership tier. AstraZeneca represents the newer combination therapy vector with improved resistance profile positioning.
| Leading Market Players |
|---|
| Pfizer |
| Merck & Co. |
| AstraZeneca |
| Johnson & Johnson |
| AbbVie |
| Novartis |
| Bayer |
| Bristol-Myers Squibb |
| Boehringer Ingelheim |
| Others |
Supply & Pricing Matrix
Hyderabad and Ahmedabad API manufacturing clusters govern cost structures for generic carbapenem antibiotics, with capacity utilization swings at these sites translating directly into hospital procurement leverage. Tertiary care centers in the United States exploit this concentration through volume-based contracting, while EMA environmental compliance costs at European finishing facilities widen transatlantic price spreads.
Pricing Analysis
Geographic price spreads between Indian-manufactured generic carbapenems and European-finished originator products exceed threefold at hospital procurement level. Three-tier pricing structure across premium originator, standard generic, and economy volume-contract tiers reflects FDA certification status and anaerobic coverage breadth. Pricing pressure stems from Medicare severity-adjusted diagnosis-related group compression, which squeezes reimbursement for prolonged IV courses. Ambulatory surgical centers exhibit highest price sensitivity due to narrow prophylaxis margins, while academic medical centers prioritize resistance profile over unit cost.
Supply Chain Analysis
Upstream feedstock for beta-lactam antibiotics draws from penicillin G potassium and 6-APA intermediate streams concentrated in China, India, and Hungary. Key inputs span fermentation-derived bulk actives, beta-lactamase inhibitor precursors, and sterile lyophilization capacity. Single-source vulnerability sits with carbapenem API synthesis requiring specialized containment infrastructure at Hyderabad facilities. Distribution runs through hospital GPO contracts and integrated delivery network bundled agreements, with cold-chain logistics for parenteral formulations adding terminal cost layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where FDA antimicrobial stewardship mandates create high switching costs for hospital formulary committees once protocols are embedded.
For Market Incumbents: Insulate formulary positioning through backward integration into beta-lactamase inhibitor production, removing API supply vulnerability to Indian quality compliance actions. Deepen hospital system partnerships by embedding pharmacokinetic dosing software within electronic health record workflows, raising substitution barriers against emerging combination therapies. Threat of carbapenem-resistant Enterobacterales coverage gaps favors incumbents with reserve antibiotic pipelines. For New Entrants and Emerging Players: Rural United States hospital systems represent underpenetrated territory where ID physician staffing shortages delay stewardship protocol implementation, creating acceptance windows for narrow-spectrum alternatives. Home healthcare IV-to-oral transition services offer second white-space target, as Medicare reimbursement simplification remains pending. Go-to-market angle should emphasize AI-assisted susceptibility prediction tools that reduce broad-spectrum exposure without requiring specialist oversight. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because EMA environmental risk assessment guidelines favor scaled manufacturers with capital for closed-loop synthesis and advanced oxidation wastewater treatment. Target acquisition archetype: mid-cap generic producers with Hyderabad API sourcing relationships and pending FDA establishment inspection clearance. Signal to watch is CDSCO enforcement action frequency at Indian facilities, which accelerates supply disruption premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Embedded formulary positioning through integrated delivery network bundled contracts secures volume commitments. |
| Manufacturing Scale-Up | EMA-compliant closed-loop synthesis capacity at Indian facilities insulates against environmental discharge restrictions. |
| Regulatory Approval Pathway | FDA QIDP designation for novel beta-lactam/beta-lactamase combinations accelerates review timelines. |
| Pipeline Diversification | Reserve antibiotic positioning against carbapenem-resistant Enterobacterales addresses documented treatment gaps. |
| Software Companion Development | Pharmacokinetic dosing platforms integrated with electronic health records raise hospital switching costs. |
Research Methodology
Cross-validation between hospital procurement database analysis and formulary director interviews anchors the qualitative findings for this study. Primary fieldwork engaged infectious disease specialists, hospital pharmacists, GPO contract managers, and regulatory affairs leads at pharmaceutical developers. Secondary validation drew from FDA antimicrobial stewardship guidance documents, CDC Emerging Infections Program surveillance reports, EMA environmental risk assessment guidelines, and WHO Essential Medicines List criteria. Bottom-up prescription volume modeling triangulates against top-down manufacturer revenue estimates.
Calibration against historical formulary shift velocities and resistance surveillance trendlines shapes the analytical framework across the projection horizon. Segmentation dimensions span product type, delivery mode, end user facility tier, and treatment stage maturity. CAGRs derive from regression against surgical volume growth, stewardship mandate implementation curves, and generic substitution elasticities observed in prior therapeutic class transitions. Forecast inputs include CDC resistance surveillance expansion rates and Medicare reimbursement policy trajectories for outpatient parenteral antimicrobial therapy.
The forecast holds incumbent behavior within observed patterns; aggressive moves by AI-assisted diagnostic developers or novel mechanism antibiotic entrants would shift outcomes beyond modeled ranges. Key revision risks encompass CDSCO enforcement escalations at Indian API facilities, FDA stewardship mandate acceleration, and carbapenem resistance prevalence inflections in CDC surveillance data. Quarterly review of hospital formulary restriction indices and generic approval timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Global Wall Mounted Ozone Disinfection Machine Market
Infection Control
Sterilization Monitoring Market
Infection Control
Hand Hygiene Market
Infection Control
Global Biofilms Treatment Market
Infection Control
Antimicrobial Wipes Market
Infection Control
Global Viral Clearance Services Market
Infection Control
Australia Hand Sanitizer Market
Infection Control
Healthcare Associated Infections (HAI) Treatment Market
Infection Control
Sterilization Market
Infection Control
Europe Ultrasound Probe Disinfection Market
Infection Control
Medical Washer Disinfector Market
Infection Control
Global Infection Prevention Devices Market
Infection Control
Steam and Hydrogen Peroxide Biological Indicators Market
Infection Control
Sterilization Technologies Market
Infection Control
Hospital Acquired Infections Market
Infection Control
Australia Healthcare Surface Disinfectant Wipes Market