
 Global Veterinary POC Diagnostic Market | 2026-2036
Global Veterinary POC Diagnostic Market Size, Share, and Industry Trends Forecast 2026-2036
Global Veterinary POC Diagnostic Market Foresight
Equipment leasing and pay-per-test financing is reshaping competitive access for mid-sized veterinary groups that previously lacked capital for analyzer procurement. IDEXX Laboratories leverages captive consumable revenue streams to sustain instrument placement density across North American clinics. Zoetis anchors its position through vertical integration into reference laboratory services alongside point-of-care hardware. Heska Corporation competes by specializing in flexible subscription models that reduce upfront barriers for independent practitioners.
Veterinary point-of-care diagnostics encompass rapid analytical systems designed for in-clinic detection of pathogens, metabolic markers, and hematologic parameters without centralized laboratory referral, typically delivering results within fifteen minutes using cartridge-based reagents or dry chemistry slides. These instruments serve the primary commercial purpose of enabling same-visit clinical decisions, reducing treatment delays, and capturing laboratory revenue within the practice rather than outsourcing to reference laboratories. Hematology analyzers occupy the most mature product category with established replacement cycles, while molecular diagnostic devices represent the fastest-expanding segment driven by polymerase chain reaction miniaturization for vector-borne disease detection. Immunoassay analyzers concentrate margin pools through high-frequency consumable repurchase tied to heartworm, Lyme disease, and feline retrovirus screening protocols.
FDA 510(k) clearances and USDA Center for Veterinary Biologics oversight shape product standards for diagnostic kits used in food animal and companion animal settings, with the former governing clinical chemistry platforms and the latter regulating pathogen detection assays with agricultural biosecurity implications. ISO 13485 quality management certification and CE marking under EU IVDR requirements govern market access for manufacturers serving European veterinary clinics and diagnostic laboratories. Stakeholders must monitor evolving regulatory divergence between FDA veterinary device pathways and EU IVDR reclassification timelines to anticipate where product registration investments will yield priority market entry.
Market Dynamics
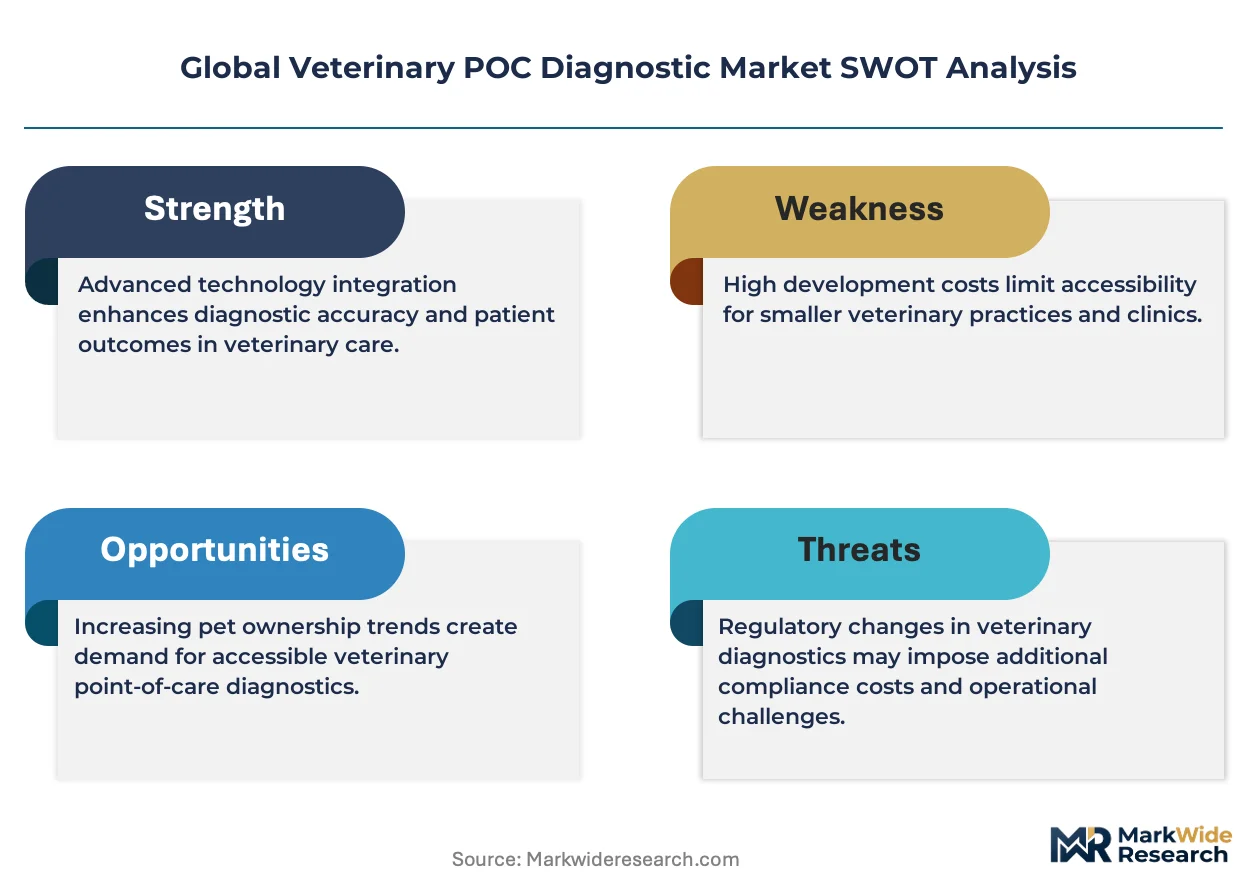
Corporate consolidation across United States veterinary practice ownership is centralizing procurement authority, compressing vendor margins while expanding minimum order volumes for diagnostic consumables.
Growth Catalysts
- CLIA-waived complexity categories:The FDA's streamlined pathway accelerates product clearance timelines for veterinary diagnostic manufacturers, reducing time-to-market for novel immunoassay platforms.
- Polymerase chain reaction miniaturization:Portable molecular devices enable vector-borne disease detection at companion animal clinics without reference laboratory referral, expanding test menu breadth.
- Germany and United Kingdom clinic expansion:Rapid immunoassay adoption in these companion animal markets creates concentrated demand pockets for hematology and chemistry analyzers.
Market Restraints
- Cartridge consumable cost volatility:Proprietary reagent pricing tied to instrument lock-in creates margin pressure for independent practitioners lacking group purchasing leverage.
- Reference laboratory substitution:Centralized veterinary diagnostic chains in urban United States markets compete on price and test breadth, diverting volume from in-clinic systems.
- EU IVDR reclassification timelines:Uncertainty around European regulatory transition requirements delays product registration investments and market entry planning.
Strategic Opportunities
- Pay-per-test financing models:Subscription-based analyzer access reduces capital barriers for mid-sized veterinary groups, opening segments previously served only by reference laboratories.
- Food animal biosecurity mandates:USDA Center for Veterinary Biologics oversight of pathogen detection assays creates procurement pull from agricultural operations requiring rapid on-site screening.
- Artificial intelligence-augmented image analysis:Integration of automated cell recognition with hematology platforms is collapsing interpretation time and skill requirements for clinic staff.
Industry Challenges
- ISO 13485 certification timelines:Quality management system implementation for multi-market registration creates 12-18 month product launch delays for emerging manufacturers.
- Legacy analyzer integration complexity:Practice management software compatibility requirements constrain hardware replacement cycles and limit vendor switching.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Veterinary POC Diagnostic Market |
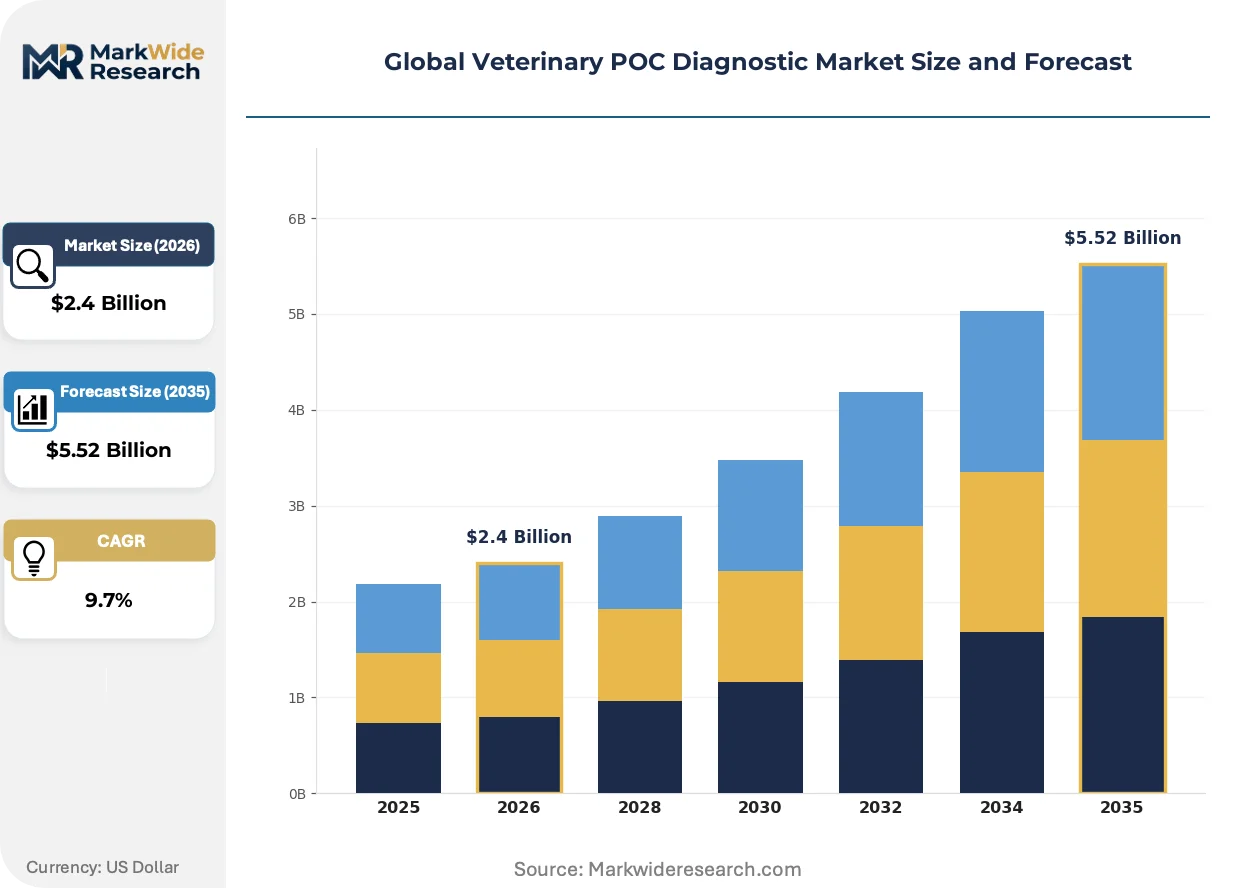
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.52 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunoassay Analyzers, Hematology Analyzers, Biochemistry Analyzers, Molecular Diagnostic Devices, Microbiology Test Kits Application: Parasitic Infections, Infectious Diseases, Reproductive Health, Nutritional Deficiencies, Endocrine Disorders End User: Veterinary Clinics, Research Institutions, Livestock Farms, Diagnostic Laboratories, Zoos Deployment: Portable Devices, Benchtop Systems, Handheld Instruments, Wearable Sensors, Mobile Units |
| Companies Covered | IDEXX Laboratories, Inc., Zoetis, Inc., Heska Corporation, Virbac, Thermo Fisher Scientific, Inc., Woodley Equipment Company Ltd., FUJIFILM Corporation, Mindray, Eurolyser Diagnostica GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Veterinary POC Diagnostic Market Shifts & Advancements
Diagnostic platform miniaturization and consumable revenue model refinement are compressing traditional boundaries between point-of-care and reference laboratory service tiers.
Real-time polymerase chain reaction miniaturization is collapsing the cost and footprint barriers that previously confined molecular diagnostics to centralized laboratories. Companion animal clinics in Germany and the United Kingdom now deploy cartridge-based systems for vector-borne pathogen detection during same-visit consultations. This technology shift is collapsing the test turnaround advantage historically held by reference laboratories.
CE marking requirements under EU IVDR are elevating clinical evidence standards for veterinary diagnostic kits entering European markets. Manufacturers must now submit expanded performance validation data for reagent stability claims. Hematology analyzer suppliers serving France and Switzerland face the steepest compliance cost increases as notified body capacity constrains review timelines.
Corporate veterinary group purchasing organizations now centralize procurement across thousands of United States practice locations, unbundling after-sales service from hardware contracts. Independent distributors lose shelf space as direct vendor relationships replace multi-brand intermediaries. This concentration is most visible in metropolitan Texas and Florida markets where corporate ownership exceeds sixty percent of clinic locations.
Global Veterinary POC Diagnostic Market Segmentation
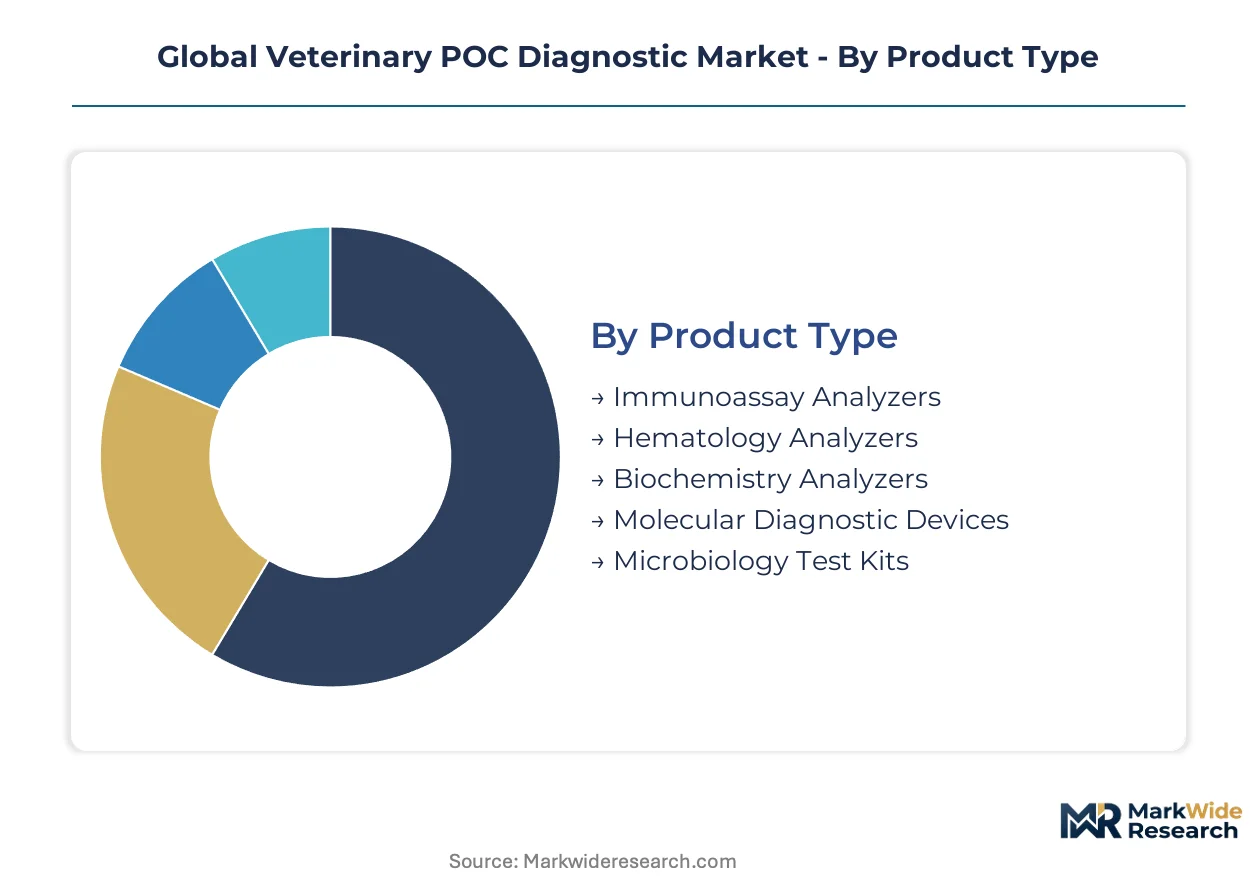
Veterinary POC diagnostic purchasing splits across four distinct category systems, each shaping vendor product roadmaps and pricing architecture differently. Equipment replacement cycles, consumable repurchase frequency, and software integration requirements vary dramatically between these segment boundaries.
Product Type:
Hematology analyzers turn over on predictable five-year replacement cycles while molecular platforms refresh every two to three years as PCR miniaturization accelerates.
- Immunoassay Analyzers:Cartridge-based systems detect heartworm, Lyme disease, and feline retrovirus antibodies through lateral flow or ELISA chemistry. United States corporate veterinary groups concentrate procurement of these platforms for same-visit screening protocols, driving consumable repurchase contracts that lock clinics into multi-year supply agreements.
- Hematology Analyzers:Automated cell counters process whole blood samples for complete blood count parameters using impedance or flow cytometry methods. Germany and United Kingdom companion animal clinics anchor replacement demand as these systems reach end-of-life across installed bases installed during the last technology refresh wave.
- Biochemistry Analyzers:Dry chemistry slide systems measure metabolic panels from serum or plasma samples.
- Molecular Diagnostic Devices:Miniaturized PCR and isothermal amplification systems enable vector-borne pathogen DNA detection.
- Microbiology Test Kits:Culture-based and rapid antigen assays identify bacterial and fungal pathogens.
Hematology analyzers anchor the volume base while molecular diagnostic devices gain share at the steepest rate.
Application:
Parasitic screening commands the highest test frequency per patient visit, whereas endocrine testing generates premium per-test revenue with lower volume throughput.
- Parasitic Infections:Heartworm antigen and tick-borne disease antibody testing dominates routine wellness protocols. United States southeastern states concentrate demand where vector exposure risks drive mandatory annual screening before preventive medication dispensing.
- Infectious Diseases:Rapid pathogen detection for canine parvovirus, feline panleukopenia, and respiratory panels enables isolation decisions during intake. Germany veterinary clinics deploy these assays most intensively following EU pet travel regulation enforcement that mandates health certification documentation.
- Reproductive Health:Progesterone timing and pregnancy confirmation assays support breeding management.
- Nutritional Deficiencies:Vitamin and mineral panel testing guides therapeutic diet prescriptions.
- Endocrine Disorders:Thyroid and cortisol assays diagnose metabolic dysfunction in geriatric patients.
Parasitic infection testing anchors the volume base while endocrine disorder applications gain share at the steepest rate.
End User:
Veterinary clinics purchase on consumable replenishment cycles while livestock farms buy on seasonal disease outbreak timing, creating complementary demand patterns.
- Veterinary Clinics:Companion and mixed animal practices represent the primary commercial channel, with corporate group purchasing organizations centralizing procurement across thousands of United States locations. These buyers prioritize CLIA-waived complexity systems that minimize technician training requirements and regulatory documentation burdens.
- Livestock Farms:Cattle, swine, and poultry operations require rapid on-site screening for respiratory and reproductive pathogens to inform culling and vaccination decisions. USDA Center for Veterinary Biologics oversight of assay quality standards shapes vendor qualification requirements for agricultural supply contracts.
- Research Institutions:Academic veterinary schools and contract research organizations validate novel diagnostic methods.
- Diagnostic Laboratories:Reference labs deploy POC systems for satellite collection site processing.
- Zoos:Exotic animal facilities require species-adapted assay validation for conservation medicine.
Veterinary clinics anchor the volume base while livestock farms gain share at the steepest rate.
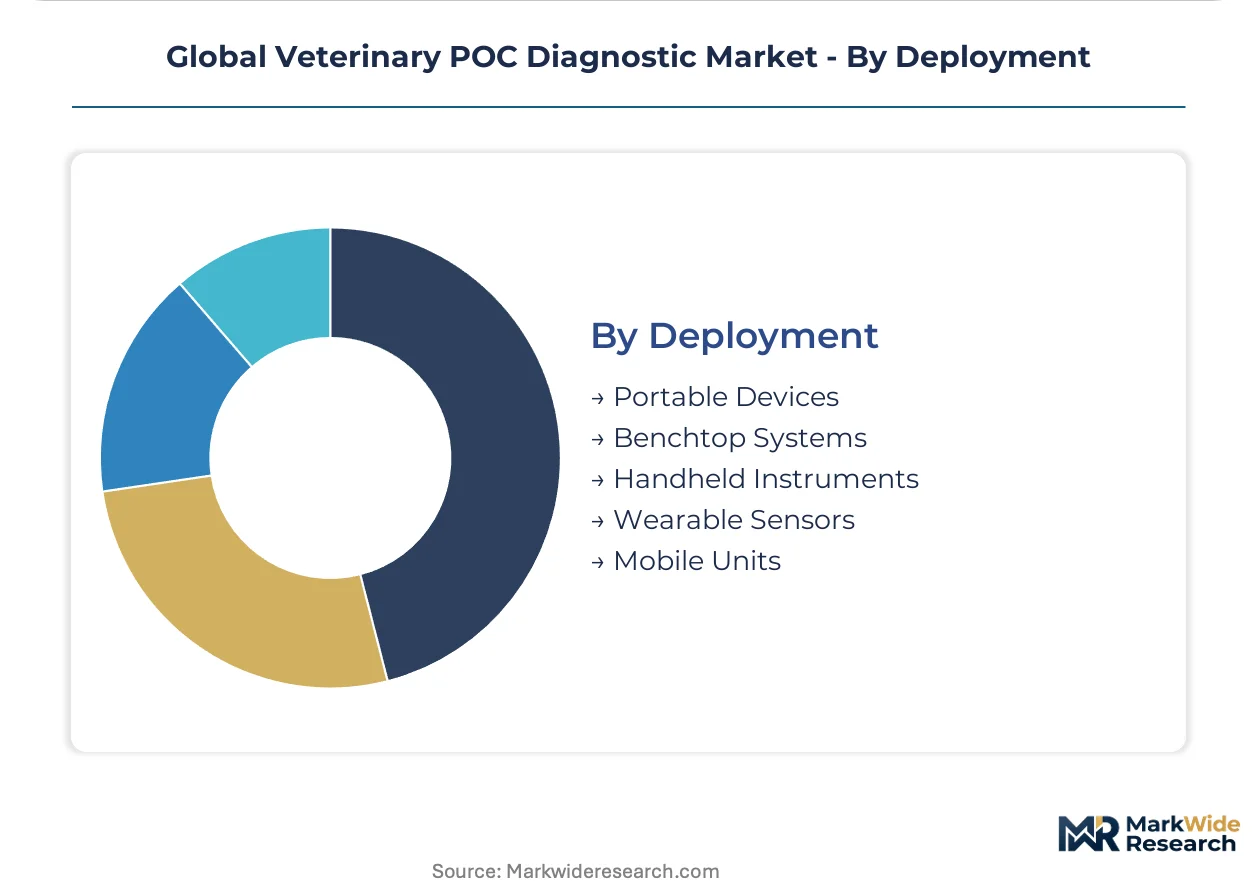
Deployment:
Benchtop systems dominate fixed clinic installations while portable configurations penetrate field service and house call segments where electricity access is unreliable.
- Benchtop Systems:Full-featured analyzers with integrated printers and touchscreen interfaces occupy permanent laboratory space within veterinary hospitals. United Kingdom corporate practice chains standardize on these configurations for brand consistency across multi-site networks.
- Portable Devices:Battery-operated or vehicle-powered systems enable testing at equine stables, livestock auctions, and remote agricultural facilities. Texas and Florida metropolitan markets concentrate demand where mobile veterinary services compete for corporate clinic overflow appointments.
- Handheld Instruments:Single-parameter readers provide spot-check functionality for glucose or ketone monitoring.
- Wearable Sensors:Continuous monitoring patches transmit physiologic data for postoperative recovery tracking.
- Mobile Units:Custom vehicle installations bring full laboratory capability to disaster response and rural outreach.
Benchtop systems anchor the volume base while portable devices gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of veterinary diagnostic consumables concentrate from German and United States manufacturing clusters toward companion animal clinics across Western Europe and North America. Import dependency for molecular diagnostic cartridges shapes procurement strategies in markets lacking domestic reagent production capacity.
United States
Corporate veterinary group purchasing organizations centralize diagnostic procurement across thousands of practice locations, compressing vendor margins while expanding minimum order volumes. FDA's streamlined 510(k) pathway accelerates product clearance timelines for novel immunoassay platforms. Metropolitan Texas and Florida markets exhibit the steepest corporate ownership concentration, exceeding sixty percent of clinic locations.
Germany
Companion animal clinics in Bavaria and North Rhine-Westphalia anchor replacement demand for hematology analyzers reaching end-of-life from prior technology refresh cycles. EU IVDR reclassification timelines elevate clinical evidence standards for reagent stability claims. The Munich-Stuttgart corridor hosts the densest concentration of veterinary diagnostic distributors serving Central European markets.
United Kingdom
Corporate practice chains standardize on benchtop analyzer configurations for brand consistency across multi-site networks in Greater London and the Southeast. CLIA-waived complexity categories from FDA influence procurement preferences even in this non-US market through multinational vendor product strategies. The Oxford-Cambridge arc generates concentrated demand from academic veterinary hospitals validating novel diagnostic methods.
China
Domestic manufacturers of biochemistry analyzers capture share in provincial veterinary stations serving livestock operations across Sichuan and Shandong provinces. NMPA oversight of in-vitro diagnostic device registration creates compliance barriers for imported molecular platforms. The Yangtze River Delta clustering of precision instrument suppliers supports rapid prototyping of cartridge-based detection systems.
Japan
Specialty companion animal hospitals in Tokyo and Osaka prefectures deploy premium hematology platforms with integrated AI-augmented cell recognition. PMDA consultation pathways for veterinary device registration extend timelines compared to human diagnostic equivalents. The Kansai region's industrial automation ecosystem supplies precision fluid handling components to regional analyzer assemblers.
Global Veterinary POC Diagnostic Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying optical sensors, precision pumps, and thermal cycling modules. The vendor base organizes around three strategic archetypes: diversified life science conglomerates with captive consumable revenue streams, mid-sized specialists leasing equipment through subscription financing, and regional manufacturers competing on reagent cost for price-sensitive agricultural markets. Dominant competitive moves include backward integration into reference laboratory services and geographic expansion through distributor acquisition in underpenetrated provincial markets.
Among United States-based platform integrators, IDEXX Laboratories and Zoetis exemplify the diversified conglomerate archetype through captive supply of consumables tied to instrument placement density. Heska Corporation occupies a position within the subscription-financing specialist tier, reducing upfront capital barriers for independent practitioners. Virbac represents the European pharmaceutical-diagnostics hybrid model, leveraging veterinary health product distribution networks for diagnostic platform penetration.
| Leading Market Players |
|---|
| IDEXX Laboratories, Inc. |
| Zoetis, Inc. |
| Heska Corporation |
| Virbac |
| Thermo Fisher Scientific, Inc. |
| Woodley Equipment Company Ltd. |
| FUJIFILM Corporation |
| Mindray |
| Eurolyser Diagnostica GmbH |
| Others |
Supply & Pricing Matrix
Munich-Stuttgart corridor manufacturing clusters anchor European reagent production capacity, with their output scale directly translating into pricing leverage for consumable suppliers serving Central European veterinary clinics. This geographic concentration enables tiered contract structures that penalize smaller buyers lacking consolidated procurement volume.
Pricing Analysis
Corporate veterinary group purchasing organizations anchor pricing structures through multi-year consumable lock-in agreements tied to instrument placement density. Three-tier pricing separates premium CLIA-waived systems from standard benchtop configurations and economy-grade portable units, with ISO 13485 certification tier serving as the primary differentiation driver. Pricing pressure stems from reference laboratory substitution in urban United States markets, where centralized chains compete on test breadth. Independent practitioners exhibit highest price sensitivity due to cartridge consumable cost volatility and absence of group purchasing leverage.
Supply Chain Analysis
Contract manufacturing concentration rests with precision instrument assemblers in Germany, United States, and China's Yangtze River Delta region. Optical sensors, precision fluid handling pumps, and thermal cycling modules constitute critical component dependencies. Single-source vulnerability for PCR miniaturization chipsets creates supply chain risk given limited qualified vendors. Distribution runs through direct vendor relationships replacing multi-brand intermediaries, particularly visible in metropolitan Texas and Florida markets where corporate ownership exceeds sixty percent of clinic locations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized regulatory navigation capabilities and multi-market quality system implementation expertise represent scarce assets constraining competitive entry. Manufacturers lacking ISO 13485 certification timelines or FDA 510(k) pathway experience face twelve-to-eighteen month launch delays.
For Market Incumbents: Build captive consumable revenue moats through cartridge chemistry lock-in and backward integration into reference laboratory services. Defend against molecular diagnostic device entrants by accelerating PCR miniaturization refresh cycles and securing exclusive distribution partnerships in Germany and United Kingdom corporate practice chains. Prioritize software integration investments that constrain legacy analyzer replacement and limit vendor switching. For New Entrants and Emerging Players: Build out flexible subscription financing models targeting mid-sized independent practitioners in United States markets lacking capital for analyzer procurement. Penetrate livestock farm segments in agricultural provinces across China and Brazil where USDA Center for Veterinary Biologics oversight and local biosecurity mandates create procurement pull. Deploy pay-per-test go-to-market structures that reduce upfront barriers previously served only by reference laboratories. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors diversified platform integrators with captive reagent supply and established GPO contract relationships. Long-term viability hinges on consolidation resilience against corporate veterinary procurement centralization. Acquisition targets should demonstrate CLIA-waived complexity category clearances and installed base density in United States metropolitan markets. Monitor FDA 510(k) clearance velocity and EU IVDR notified body capacity as inflection indicators for registration investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA-Waived Complexity Category Investment | FDA streamlined pathway accelerates product clearance timelines for novel immunoassay platforms entering United States markets. |
| PCR Miniaturization Platform Refresh | Portable molecular devices collapse test turnaround advantage historically held by reference laboratories in vector-borne disease detection. |
| Subscription Financing Model Deployment | Pay-per-test structures reduce capital barriers for independent practitioners previously excluded from in-clinic analyzer access. |
| EU IVDR Certification Advancement | CE marking under elevated clinical evidence standards secures priority market entry in Germany and United Kingdom companion animal clinics. |
| Corporate GPO Contract Consolidation | Direct vendor relationships with group purchasing organizations secure multi-year consumable repurchase agreements across thousands of practice locations. |
Research Methodology
Operator-level perspectives from veterinary practice managers, diagnostic platform procurement officers, reference laboratory operations directors, and regulatory affairs specialists anchored the qualitative base. Primary interview insights combined with secondary validation from FDA 510(k) clearance databases, USDA Center for Veterinary Biologics registration records, EU IVDR notified body submission trackers, and corporate veterinary group purchasing organization contract disclosures. Bottom-up instrument placement and consumable throughput estimates triangulated against top-down market value reconstructions.
Scenario-bracketing around regulatory transition timelines, corporate consolidation velocity, and PCR miniaturization adoption curves structured the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application, end user, and deployment configuration alongside regional regulatory cluster differentiation. CAGRs derived from instrument replacement cycle analysis, consumable repurchase frequency patterns, and test menu expansion trajectories. Veterinary clinic density projections and livestock farm biosecurity mandate enforcement schedules served as industry-specific forecast inputs.
Stress conditions across EU IVDR reclassification delays, reference laboratory pricing aggression, and cartridge consumable cost volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding corporate ownership concentration and technology refresh acceleration. Quarterly review of FDA 510(k) clearance velocity, notified body capacity constraints, and GPO contract renewal rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Asia-Pacific Thyroid Cancer Diagnostics Market
Diagnostics
Spain in-Vitro Diagnostics Market
Diagnostics
North America Autoimmune Disease Diagnostics Market
Diagnostics
Immunoassay Interference Blocker Market
Diagnostics
Shrimps Disease Diagnostics Market
Diagnostics
Rapid RNA Testing Kits Market
Diagnostics
Clostridium Diagnostics Market
Diagnostics
Blood Grouping Reagents Market
Diagnostics
Semen Analysis Systems Market
Diagnostics
Cognitive Diagnostics Market
Diagnostics
Predictive Disease Analytics Market
Diagnostics
North America and Europe Companion Animal Diagnostics Imaging Market
Diagnostics
Swine Disease Diagnostic Kit Market
Diagnostics
Acute Ischemic Stroke Diagnosis Market
Diagnostics
Digital Companion Diagnostics Market
Diagnostics
Global Chemiluminescence Immunoassay (CLIA) Market