
 Mexico in-Vitro Diagnostics Market | 2026-2036
Mexico in-Vitro Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico in-Vitro Diagnostics Market Foresight
Point-of-care molecular testing is narrowing the gap between centralized laboratory infrastructure and decentralized patient access across Mexican healthcare networks. Abbott Laboratories leverages its established distribution footprint to sustain reagent supply continuity in public hospital systems. Roche Diagnostics anchors its position through automated platform installations in major metropolitan laboratories. bioMérieux competes on specialized microbiology and infectious disease assay portfolios.
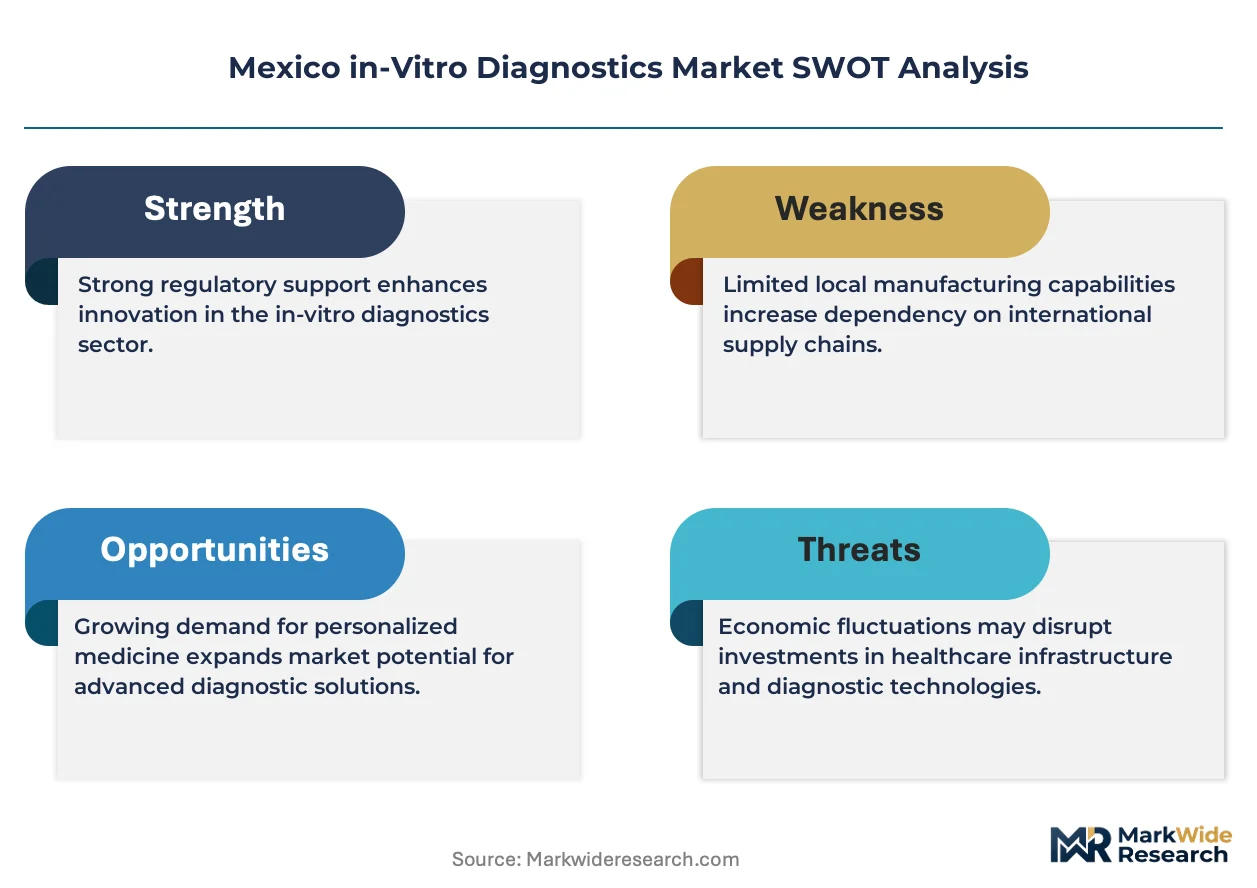
In-vitro diagnostics encompasses medical tests performed on biological specimens outside the living organism, utilizing reagent-based chemical reactions, immunological binding, or nucleic acid amplification to detect analytes with defined sensitivity and specificity thresholds. These systems serve clinical decision-making by enabling disease screening, therapeutic monitoring, and epidemiological surveillance. Reagents capture the largest value pool given their recurring consumption model, while next-generation sequencing represents the fastest-expanding technology segment as oncology and pharmacogenomic applications gain traction in Mexican research institutions. Instruments retain longer replacement cycles, concentrating margin capture among manufacturers with installed-base lock-in strategies.
COFEPRIS maintains primary oversight of IVD product registration, safety surveillance, and clinical evidence requirements, while Mexican Ministry of Health guidelines shape laboratory quality standards and testing protocols. NOM-005-SSA3-2018 establishes specific technical provisions for clinical laboratory services that directly influence equipment procurement specifications and quality management system investments. Stakeholders must monitor evolving COFEPRIS equivalence determinations with FDA and EMA standards to anticipate accelerated approval pathways for novel diagnostic platforms.
Market Dynamics
Point-of-care molecular platforms are compressing testing turnaround times from days to hours, forcing hospital networks in Jalisco and Nuevo León to reconfigure laboratory workflows around decentralized specimen processing rather than centralized batch analysis.
Growth Catalysts
- NOM-005-SSA3-2018 laboratory standards:Mandatory quality management system investments by public hospital networks are accelerating replacement of aging immunoassay analyzers with automated platforms that reduce manual handling errors.
- Infectious disease surveillance mandates:Federal epidemiological monitoring programs for dengue, chikungunya, and emerging respiratory pathogens are expanding polymerase chain reaction testing volumes in state health laboratories across central Mexico.
- Pharmacogenomic applications:Cancer treatment centers in Mexico City are integrating next-generation sequencing into oncology protocols, creating demand for companion diagnostic assays that match tumor profiles to targeted therapies.
Market Restraints
- Reagent import dependency:Over seventy percent of diagnostic reagents enter through Veracruz and Lázaro Cárdenas ports, exposing supply continuity to customs processing delays and peso-dollar exchange volatility.
- COFEPRIS equivalence determination gaps:Diagnostic platforms approved under FDA breakthrough device designation face extended review timelines pending Mexican regulator validation of foreign clinical evidence packages.
- Specialized technician scarcity:Molecular biology technologist training programs in Mexican universities produce insufficient graduates to staff expanded testing capacity in Guanajuato and Querétaro laboratory clusters.
Strategic Opportunities
- Yucatán Peninsula expansion:Merida's emerging medical tourism corridor presents untapped demand for rapid infectious disease screening serving international patient flows from the United States and Canada.
- Digital pathology convergence:Integration of whole-slide imaging with artificial intelligence-assisted cytology interpretation opens service contract opportunities for tertiary care centers in Monterrey.
- Public-private laboratory partnerships:ISSSTE and IMSS outsourcing frameworks enable private diagnostic chains to operate satellite laboratories within government hospital campuses under revenue-sharing arrangements.
Industry Challenges
- Interoperability with legacy health information systems:New analyzer installations require custom middleware development to connect with decades-old hospital electronic record platforms that lack HL7 FHIR compatibility.
- Cold chain integrity for temperature-sensitive reagents:Last-mile distribution to rural clinics in Chiapas and Oaxaca faces refrigeration gaps that compromise assay performance and generate waste.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico in-Vitro Diagnostics Market |
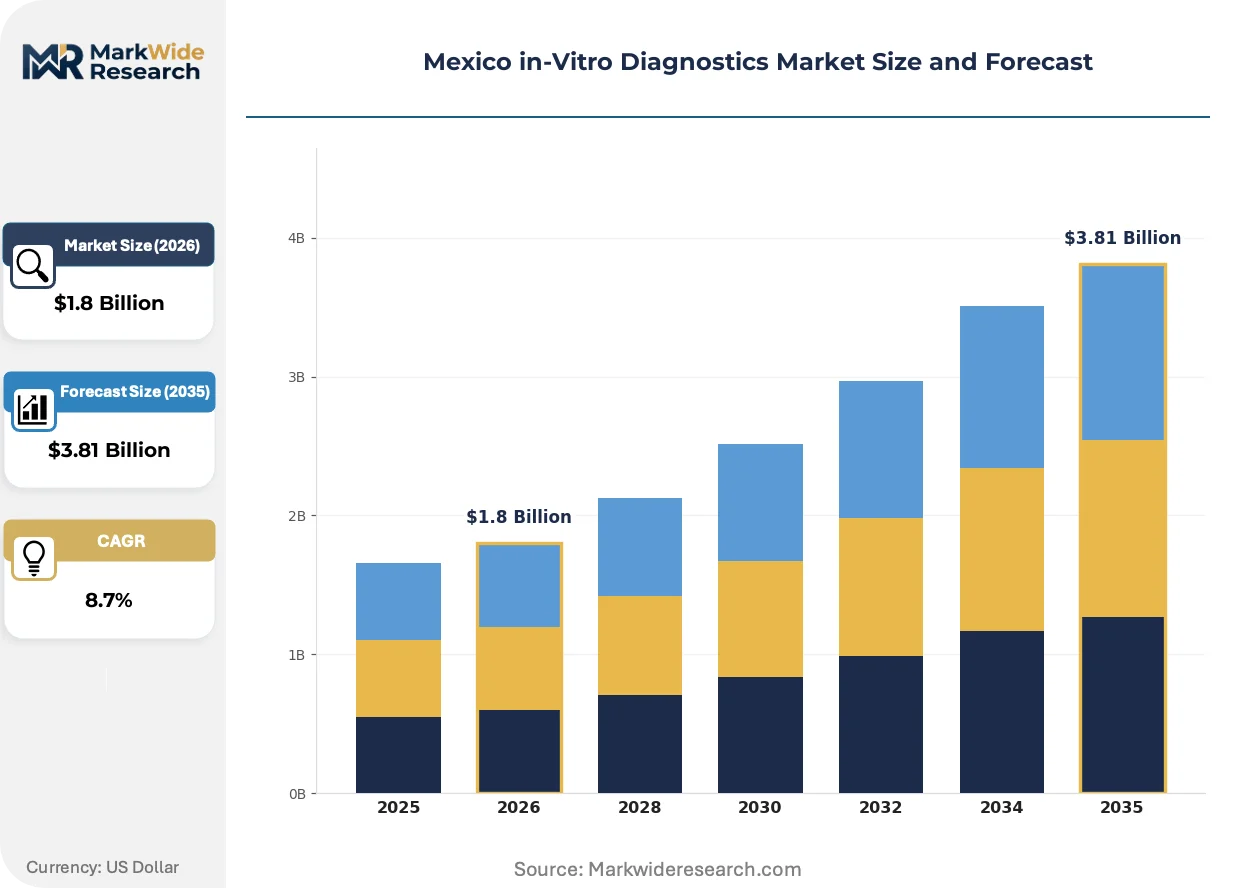
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Consumables, Software End User: Hospitals, Diagnostics Laboratories, Clinics, Research Institutions Technology: ELISA, PCR, Microarrays, Next-Generation Sequencing Delivery Mode: Point-of-Care, Centralized, Automated Systems, Lab-based |
| Companies Covered | Abbott Laboratories, Roche Diagnostics, Siemens Healthineers, Thermo Fisher Scientific, bioMérieux, Bio-Rad Laboratories, Sysmex Corporation, Danaher Corporation, Becton Dickinson, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico in-Vitro Diagnostics Market Shifts & Advancements
Automated sample-to-answer systems are eliminating manual pre-analytical steps, while regulatory data sharing agreements and shifting procurement accountability are redrawing competitive boundaries across Mexican diagnostic networks.
Multiplexed respiratory panels is migrating from reference laboratory batch processing to urgent care clinic point-of-care deployment. Hospital emergency departments in Mexico City are adopting cartridge-based systems that deliver influenza, RSV, and SARS-CoV-2 results within forty-five minutes. This technology is migrating from high-complexity molecular laboratories to mid-sized community hospitals that previously outsourced infectious disease testing.
COFEPRIS mutual recognition agreements with FDA and EMA are compressing registration timelines for novel diagnostic platforms with established foreign safety profiles. Mexican manufacturers with ISO 13485 certification gain expedited review pathways that reduce time-to-market by eight to fourteen months. Reagent producers with dual US-Mexico manufacturing footprints capture first-mover advantage in automated immunoassay segments.
Consolidated procurement through federal hospital supply agencies is displacing decentralized purchasing by individual clinical laboratories. State health secretariats in Puebla and Tlaxcala are aggregating reagent demand across multiple facilities to negotiate volume-based pricing with distributors. This concentration is most visible in the public sector, where IMSS and ISSSTE purchasing cooperatives now account for the majority of chemistry analyzer placements.
Mexico in-Vitro Diagnostics Market Segmentation
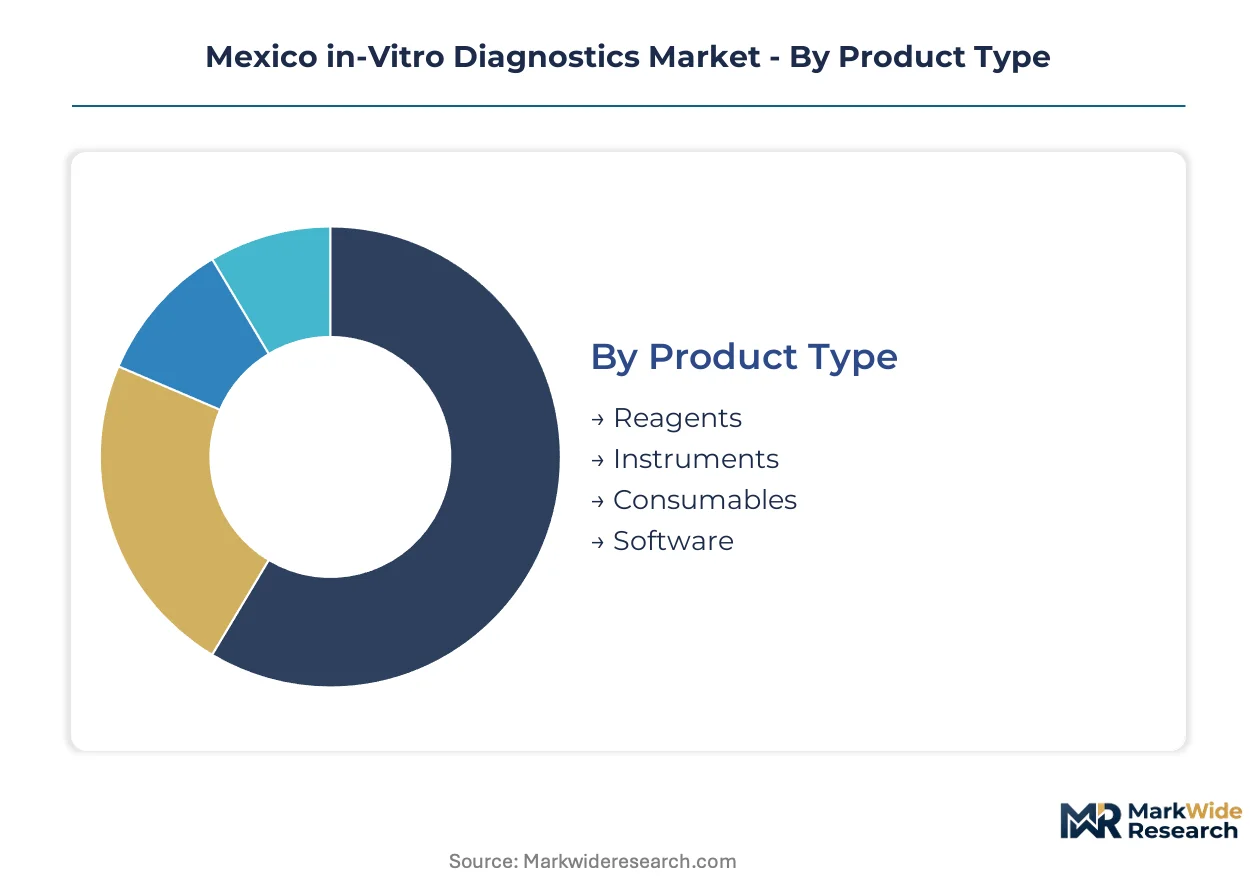
Segmentation in Mexico's IVD market reveals how procurement concentration, technology migration, and care delivery reconfiguration create distinct competitive arenas. Each dimension exposes where margin pools concentrate and where substitution threats emerge.
Product Type:
Cost tier differentiation separates recurring revenue streams from capital-intensive placements with extended replacement cycles.
- Reagents:Chemical and biological formulations consumed per-test generate predictable revenue tied to installed instrument bases. Hospital networks in Mexico City and Guadalajara lock into multi-year supply contracts that bundle reagent pricing with analyzer maintenance, creating high switching costs. Reagents command the established base.
- Instruments:Automated analyzers and molecular platforms require substantial upfront capital commitment with 5-7 year depreciation schedules. Public sector procurement through federal hospital supply agencies concentrates placements in IMSS and ISSSTE facilities, favoring vendors with established service infrastructure.
- Consumables:Disposable items including pipette tips, collection tubes, and reaction vessels flow through distributor networks to laboratories of all sizes. Demand scales linearly with test volume without the instrument lock-in dynamics.
- Software:Laboratory information management systems and data analytics platforms capture emerging value as COFEPRIS emphasizes electronic quality management documentation under NOM-005-SSA3-2018. The steepest expansion runs through software.
Reagents anchor manufacturer profitability through recurring pull. Software and automated systems capture the steepest expansion trajectory as laboratory digitization accelerates.
End User:
Customer type determines purchasing authority complexity and contract duration, from centralized federal tenders to decentralized clinic procurement.
- Hospitals:Tertiary care centers in Monterrey and Mexico City deploy comprehensive testing menus across clinical chemistry, hematology, and molecular diagnostics. Federal hospital supply agency consolidation shifts bargaining power toward volume aggregators and away from individual facility procurement officers.
- Diagnostics Laboratories:Independent reference laboratories and hospital-affiliated networks process high-throughput specimen volumes from multiple collection sites. Chains in Jalisco and Nuevo León invest in automated platforms to reduce manual handling errors and expand test turnaround capacity.
- Clinics:Primary care and urgent care facilities drive point-of-care molecular adoption for infectious disease screening. Cartridge-based systems in Mexico City emergency departments deliver influenza and respiratory pathogen results within 45 minutes.
- Research Institutions:Cancer treatment centers and university hospitals integrate next-generation sequencing into oncology protocols. Pharmacogenomic applications create demand for companion diagnostic assays matching tumor profiles to targeted therapies.
Hospitals retain the largest absolute spend. Research institutions and clinics are climbing the fastest as precision medicine and decentralized testing gain priority.
Technology:
Application specificity determines where each technology platform wins—routine screening versus complex diagnostic characterization.
- ELISA:Enzyme-linked immunosorbent assays deliver cost-effective protein detection for infectious disease serology and hormone quantification. State health laboratories across central Mexico maintain ELISA capacity for dengue and chikungunya surveillance mandated under federal epidemiological monitoring programs.
- PCR:Polymerase chain reaction amplification enables nucleic acid detection with sensitivity thresholds required for early-stage infection confirmation. Hospital networks in Guanajuato and Querétaro expand molecular technologist staffing to support expanded PCR capacity.
- Microarrays:High-density probe arrays support genotyping and gene expression profiling in research settings. Limited adoption in routine clinical diagnostics reflects cost and interpretation complexity barriers.
- Next-Generation Sequencing:Massively parallel sequencing platforms enable comprehensive genomic analysis for oncology and pharmacogenomic applications. Cancer treatment centers in Mexico City drive adoption as companion diagnostic protocols standardize.
PCR and ELISA anchor the established installed base. Next-generation sequencing is gaining share fastest as precision medicine protocols expand.
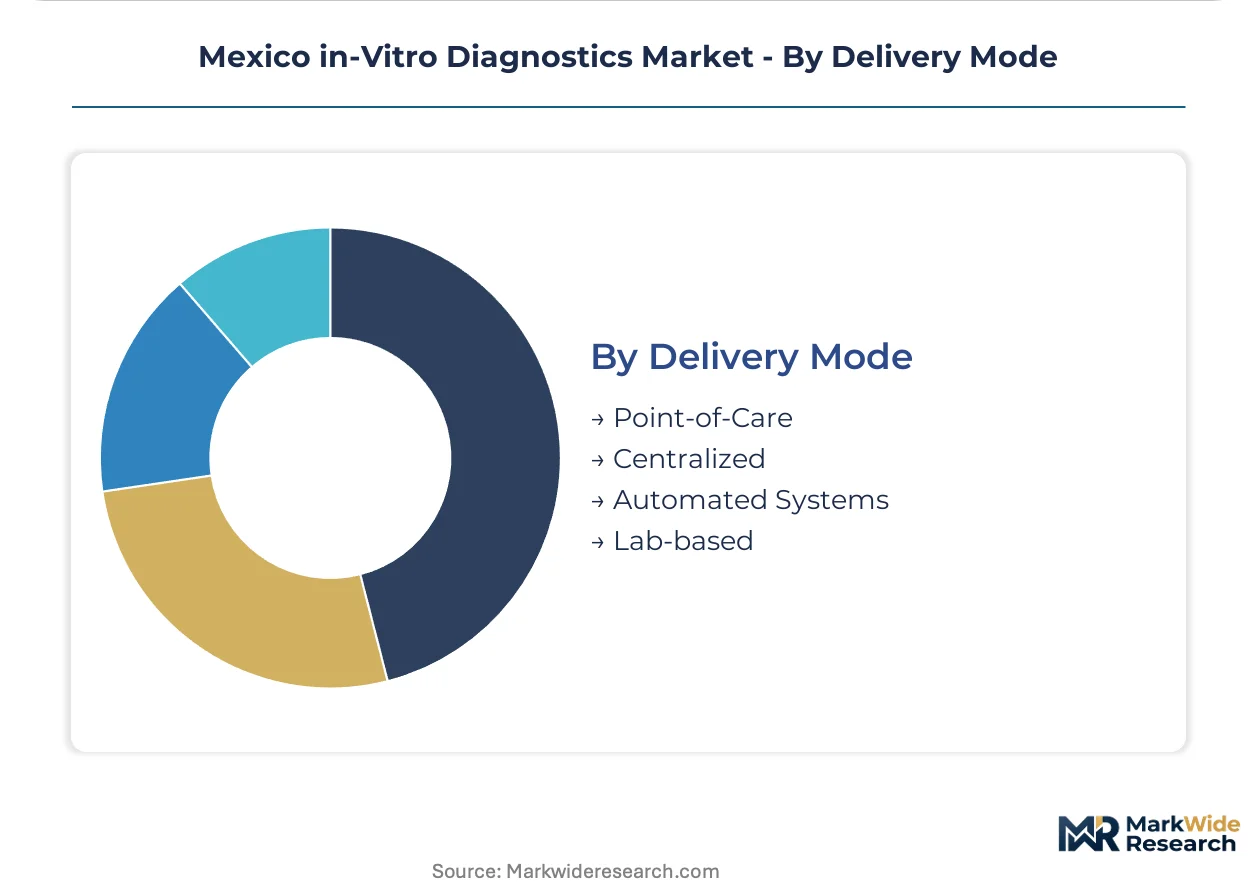
Delivery Mode:
Geography and care setting dictate whether testing occurs at specimen collection or requires transport to centralized facilities.
- Point-of-Care:Portable molecular platforms compress turnaround times from days to hours at urgent care clinics and rural health posts. Yucatán Peninsula medical tourism corridors deploy rapid infectious disease screening for international patient flows.
- Centralized:High-complexity reference laboratories in Mexico City and Guadalajara process batched specimens from satellite collection sites. Economies of scale support comprehensive test menus that decentralized sites cannot replicate.
- Automated Systems:Sample-to-answer platforms eliminate manual pre-analytical steps in mid-sized community hospitals. Jalisco and Nuevo León facilities reconfigure workflows around decentralized specimen processing rather than centralized batch analysis.
- Lab-based:Traditional wet chemistry and manual microscopy persist in resource-constrained settings. Cold chain gaps in Chiapas and Oaxaca rural distribution compromise reagent integrity for temperature-sensitive assays.
Centralized and lab-based modes retain volume dominance. Point-of-care and automated systems are expanding most quickly as network decentralization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Public hospital networks in Mexico City and Guadalajara concentrate procurement authority through federal supply agencies, while state health secretariats in Jalisco and Nuevo León drive decentralized laboratory expansion. Diagnostic demand clusters along three distinct corridors defined by infrastructure maturity, patient access patterns, and regulatory enforcement intensity.
Mexico City Metro
Tertiary cancer treatment centers and IMSS flagship hospitals generate concentrated demand for next-generation sequencing platforms and companion diagnostic assays. COFEPRIS maintains its headquarters here, accelerating registration timelines for manufacturers with established FDA equivalence documentation. The city's laboratory networks process the highest-complexity specimens from across central Mexico.
Nuevo León
Monterrey's private hospital chains and medical tourism infrastructure drive adoption of automated sample-to-answer systems. State health secretariats aggregate reagent demand across multiple facilities to negotiate volume-based pricing with distributors. Digital pathology convergence with AI-assisted cytology interpretation is emerging in tertiary care centers serving cross-border patient flows.
Jalisco
Guadalajara's expanding diagnostic laboratory clusters face acute molecular biology technologist scarcity despite university training program expansion. Federal epidemiological monitoring programs for dengue and chikungunya mandate polymerase chain reaction capacity in state health laboratories. Point-of-care molecular platforms are compressing turnaround times in community hospital emergency departments.
Bajío Region
Guanajuato and Querétaro industrial corridors attract pharmaceutical manufacturing investment that spurs demand for quality control testing and environmental monitoring assays. NOM-005-SSA3-2018 laboratory standards accelerate replacement of aging immunoassay analyzers with automated platforms. Cold chain gaps in last-mile distribution to rural clinics compromise temperature-sensitive reagent integrity.
Yucatán Peninsula
Merida's emerging medical tourism corridor generates untapped demand for rapid infectious disease screening serving international patient flows from the United States and Canada. Decentralized testing infrastructure remains underdeveloped relative to patient access requirements. Public-private laboratory partnerships under ISSSTE outsourcing frameworks present satellite laboratory expansion opportunities.
Mexico in-Vitro Diagnostics Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement tiers defined by contract duration and reagent bundling intensity. The vendor base organizes around three strategic archetypes: multinational platform manufacturers with service infrastructure, regional distributors with logistics reach, and niche assay developers with disease-specific portfolios. Consolidated procurement through IMSS and ISSSTE purchasing cooperatives favors vendors with federal supply agency relationships. Competitive moves center on multi-year reagent supply contracts and analyzer placement programs.
Among North American and European platform manufacturers, Abbott Laboratories, Roche Diagnostics, and bioMérieux occupy positions anchored by distinct competitive vectors. Abbott exemplifies the channel-controlling archetype through distribution footprint leverage in public hospital systems. Roche represents the automated platform installation strategy in major metropolitan laboratories. bioMérieux sits within the specialized microbiology and infectious disease assay tier. These three companies illustrate how product portfolio breadth, geographic coverage, and regulatory registration speed create differentiated access to procurement decision-makers.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Roche Diagnostics |
| Siemens Healthineers |
| Thermo Fisher Scientific |
| bioMérieux |
| Bio-Rad Laboratories |
| Sysmex Corporation |
| Danaher Corporation |
| Becton Dickinson |
| Others |
Supply & Pricing Matrix
Reagent manufacturing concentration in the United States and Germany anchors margin capture downstream at Mexican distributor tiers, where peso-dollar exchange volatility and customs processing delays at Veracruz and Lázaro Cárdenas ports amplify landed cost uncertainty. This upstream dependency concentrates pricing power among multinational platform manufacturers with dual US-Mexico manufacturing footprints, while federal hospital supply agency consolidation shifts bargaining leverage toward volume aggregators and away from individual clinical laboratories.
Pricing Analysis
Cost-plus contracts with dollar-indexed reagent pricing dominate public sector procurement through IMSS and ISSSTE purchasing cooperatives, insulating vendors from peso depreciation while exposing hospital networks to foreign exchange risk. Three-tier pricing structure across premium automated platforms, standard immunoassay analyzers, and economy manual systems separates COFEPRIS-registered multinationals from ISO 13485-certified regional assemblers. Pricing pressure stems from state health secretariat aggregation of demand across multiple facilities in Puebla and Tlaxcala. Public hospital networks exhibit highest price sensitivity due to fixed budget allocations, while private tertiary care centers in Monterrey prioritize turnaround time over unit economics.
Supply Chain Analysis
Upstream chemical precursors and biological raw materials draw from specialized suppliers in the United States, Germany, and Singapore, with enzyme formulations and polymerase enzymes constituting critical cost components for molecular assay production. Single-source vulnerability pervades temperature-sensitive reagent categories where cold chain integrity gaps in last-mile distribution to Chiapas and Oaxaca rural clinics generate spoilage waste. Distribution runs through Veracruz port customs clearance into regional distributor warehouses serving hospital networks and independent laboratories, with federal supply agency consolidation compressing channel margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's IVD market represents early-cycle expansion as point-of-care molecular platforms penetrate community hospital emergency departments previously dependent on centralized reference laboratory outsourcing. NOM-005-SSA3-2018 quality management mandates accelerate replacement of aging immunoassay infrastructure, creating sustained demand visibility for automated platform vendors.
For Market Incumbents: Insulate reagent revenue streams through multi-year supply contracts bundling analyzer maintenance with consumable pricing, locking in switching costs at IMSS and ISSSTE facilities. Deepen backward integration into regional distribution infrastructure to mitigate customs processing delays at Veracruz and Lázaro Cárdenas ports. Prioritize COFEPRIS equivalence documentation with FDA breakthrough device pathways to compress registration timelines against emerging entrants. For New Entrants and Emerging Players: Build out satellite laboratory partnerships under ISSSTE outsourcing frameworks in the Yucatán Peninsula, where Merida's medical tourism corridor presents untapped demand for rapid infectious disease screening. Target urgent care clinic point-of-care deployment in Jalisco and Nuevo León, where cartridge-based respiratory panels are migrating from high-complexity molecular laboratories. Pursue go-to-market alliances with regional distributors possessing established cold chain logistics reach into central Mexico hospital networks. For Investors and Strategic Acquirers: Capital is best deployed toward specialized microbiology assay developers with COFEPRIS-registered infectious disease portfolios and established service infrastructure in Guadalajara or Monterrey metropolitan clusters. Long-term viability hinges on positioning for pharmacogenomic application expansion as cancer treatment centers integrate companion diagnostic protocols. Monitor COFEPRIS mutual recognition agreement implementation velocity as inflection indicator for registration timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| COFEPRIS Registration Pathway Optimization | Expedited review timelines reduce time-to-market by eight to fourteen months for ISO 13485-certified manufacturers. |
| Public-Private Laboratory Partnership | ISSSTE outsourcing frameworks enable private diagnostic chains to operate satellite laboratories within government hospital campuses. |
| Point-of-Care Platform Deployment | Cartridge-based systems in Mexico City emergency departments deliver respiratory pathogen results within forty-five minutes. |
| Reagent Supply Contract Bundling | Multi-year agreements with analyzer maintenance lock in recurring revenue and create high switching costs. |
| Digital Pathology Convergence | AI-assisted cytology interpretation opens service contract opportunities for tertiary care centers in Monterrey. |
Research Methodology
A standing panel of hospital laboratory directors, COFEPRIS regulatory affairs specialists, biomedical equipment procurement managers, and molecular biology technologists provided ongoing calibration across the research process. Primary interviews with IMSS and ISSSTE supply chain executives were triangulated against secondary validation from COFEPRIS registration databases, NOM-005-SSA3-2018 technical provisions, federal hospital supply agency tender records, and customs import data at Veracruz and Lázaro Cárdenas ports. Bottom-up test volume modeling across technology segments was reconciled with top-down market size estimates derived from analyzer installed base counts and reagent consumption rates.
Scenario-bracketing around peso-dollar exchange volatility, COFEPRIS equivalence determination timelines, and molecular technologist supply constraints bounded the projection range across the analysis window. Segmentation dimensions modeled include product type, end user category, technology platform, and delivery mode, with regional adoption patterns and public-private procurement split as cross-cutting variables. CAGRs were derived from instrument placement trajectories, reagent pull-through per installed unit, and test volume migration from centralized to point-of-care settings. Forecast inputs incorporated NOM-005-SSA3-2018 compliance investment schedules and federal epidemiological surveillance program expansion mandates.
Stress conditions across exchange rate bands, customs processing delay scenarios, and reagent import tariff adjustments were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding COFEPRIS regulatory streamlining continuity and public hospital network budget allocation stability. Cross-checking against GPO contract databases and state health secretariat procurement disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Antigen Kit Market
Diagnostics
Global Women's Health Diagnostics Market
Diagnostics
Veterinary Rapid Diagnostic Tests Market
Diagnostics
Global Syphilis Immunoassay Diagnostics Market
Diagnostics
Latent Tuberculosis Infection Detection Market
Diagnostics
Global Lateral Flow Assay Market
Diagnostics
Cellular Health Screening Market
Diagnostics
Glaucoma Diagnostics Market
Diagnostics
Global Pelvic Floor Diagnostic Testing Market
Diagnostics
Food Allergy Diagnostics and Therapeutics Market
Diagnostics
Global Chromoendoscopy Agents Market
Diagnostics
Sweden in-Vitro Diagnostics Market
Diagnostics
Global Predictive and Presymptomatic Testing Market
Diagnostics
Rapid Influenza Diagnostic Tests (RIDT) Market
Diagnostics
At-Home Cancer Testing Market
Diagnostics
Total Iron Binding Capacity Reagents Market