
 Blood Grouping Reagents Market | 2026-2036
Blood Grouping Reagents Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Grouping Reagents Market Analysis
Software-defined assay protocols bundled with analyzer platforms is pivoting how reagent vendors monetize their installed base. Thermo Fisher Scientific extends its footprint through integrated workflow solutions that lock in consumable pull-through. Grifols, S.A. anchors European transfusion networks with specialized plasma-derived reagent portfolios. Bio-Rad Laboratories, Inc. differentiates through quality control reagents that laboratories use to maintain accreditation standards.
Blood grouping reagents comprise antibody-based solutions—typically monoclonal IgM or IgG formulations suspended in buffered saline with defined titers and specificity profiles—used to determine ABO, Rh, and extended phenotypes in human blood samples. Serological testing remains the dominant technology dimension, though molecular testing is gaining share in complex antibody identification cases where DNA-based resolution reduces transfusion reaction risks. Automated analyzers command premium positioning in high-volume hospital laboratories, while blood banks sustain demand for reagent red blood cells used in manual tube methods.
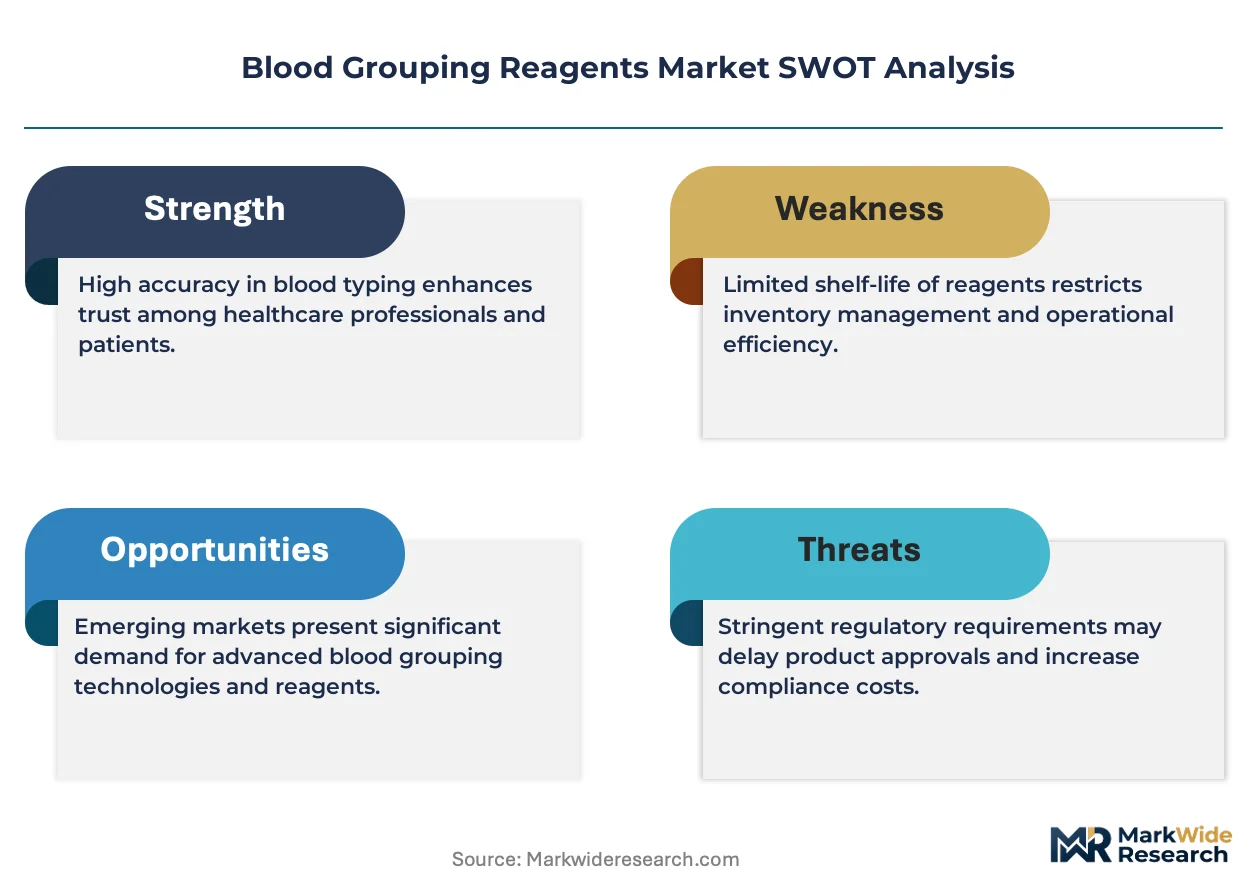
FDA blood establishment regulations and ISO 15189 laboratory accreditation standards shape product development cycles, forcing manufacturers to document lot-to-lot consistency and traceability. The EU In Vitro Diagnostic Regulation (IVDR) is tightening conformity assessment requirements for antibody reagents sold in European markets. Stakeholders must monitor how regulatory divergence between FDA and IVDR pathways affects product registration timelines and portfolio rationalization decisions.
Market Dynamics
Integrated analyzer-reagent bundling is compressing standalone reagent margins and locking hospital laboratories into consumable pull-through contracts that span five- to seven-year procurement cycles.
Growth Catalysts
- Surgical Volume Recovery:Elective procedure backlogs in tertiary care centers are expanding transfusion service throughput and reagent consumption rates.
- FDA Blood Establishment Registration:Updated quality thresholds for antibody-based diagnostics are forcing laboratory upgrades that favor validated, high-titer reagent suppliers.
- Extended Phenotyping:Molecular genotyping protocols for complex antibody identification are penetrating reference laboratories, creating parallel demand for DNA-based and serological reagents.
Market Restraints
- Plasma-Derived Input Volatility:Monoclonal antibody production depends on fetal bovine serum and human plasma fractions with price swings tied to biologics manufacturing cycles.
- IVDR Conformity Burden:The EU In Vitro Diagnostic Regulation is extending technical documentation timelines and audit costs for CE-marked reagent portfolios.
- Analyzer Platform Concentration:Three instrument vendors control seventy percent of installed immunohematology analyzers, constraining reagent interoperability and switching flexibility.
Strategic Opportunities
- Decentralized Testing Networks:Satellite blood collection sites in India and Brazil lack automated infrastructure, creating pull for stabilized liquid reagents compatible with manual tube methods.
- ISO 15189 Accreditation Wave:Quality control reagent demand is accelerating as mid-tier laboratories pursue international accreditation to access insurance reimbursement pools.
- Software-Defined Assay Protocols:Cloud-based titer optimization and lot-specific calibration algorithms are enabling subscription revenue models that decouple reagent pricing from physical unit sales.
Industry Challenges
- Serological Specialist Shortage:Complex antibody identification requires board-certified immunohematologists, and training program capacity lags replacement demand in North American hospital networks.
- Legacy Analyzer Integration:Pre-2015 immunohematology instruments lack bidirectional data interfaces, forcing middleware development costs that erode reagent margin on retrofit accounts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Grouping Reagents Market |
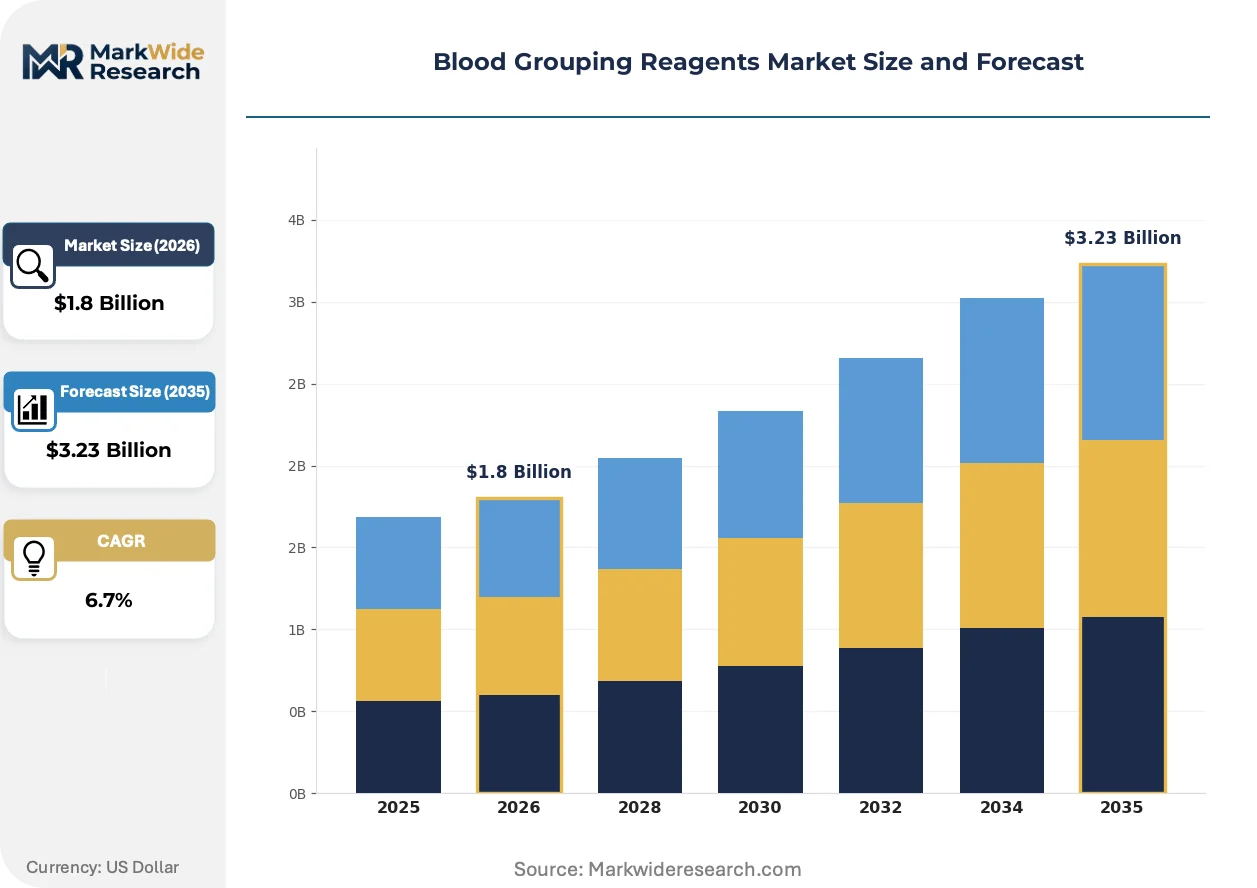
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Blood Typing Kits, Quality Control Reagents, Reagent Red Blood Cells End User: Hospitals, Blood Banks, Diagnostic Laboratories, Research Institutions Application: Transfusion Medicine, Paternity Testing, Organ Transplants, Forensic Science Technology: Serological Testing, Molecular Testing, Microplate Testing, Automated Analyzers |
| Companies Covered | Bio-Rad Laboratories, Inc., Grifols, S.A., QuidelOrtho Corporation, Immucor, Inc., Merck KGaA, Thermo Fisher Scientific Inc., Ortho Clinical Diagnostics, Danaher Corporation, Beckman Coulter, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Grouping Reagents Market Emerging Trajectories
Reagent vendors are pivoting from standalone antibody sales to integrated workflow ecosystems that embed consumables within analyzer platforms and software subscriptions.
Molecular genotyping for extended red blood cell phenotyping is consolidating complex antibody resolution workflows in high-volume reference laboratories. Transfusion services at academic medical centers are adopting PCR-based assays for Kell, Duffy, and Kidd antigen prediction to preempt alloimmunization in chronically transfused patients. This technology is consolidating serological testing into confirmatory-only roles, compressing demand for reagent red blood cells in antigen-negative screening.
The EU In Vitro Diagnostic Regulation is tightening post-market surveillance and performance verification requirements for antibody reagents sold in European markets. Manufacturers must now submit clinical evidence packages and maintain vigilance systems that track adverse events across the product lifecycle. Small and mid-sized reagent producers without dedicated regulatory affairs infrastructure are withdrawing SKUs rather than absorbing compliance costs, concentrating supply among diversified diagnostics conglomerates.
Consolidated procurement by integrated delivery networks is displacing hospital-level reagent purchasing autonomy in the United States. Systems like Kaiser Permanente and HCA Healthcare are centralizing reference laboratory contracts and mandating analyzer standardization across member facilities. This behavior is most visible in the Southeast and Midwest, where health system mergers have created multi-state transfusion service networks with uniform reagent specifications and volume-based pricing tiers.
Blood Grouping Reagents Market Segmentation
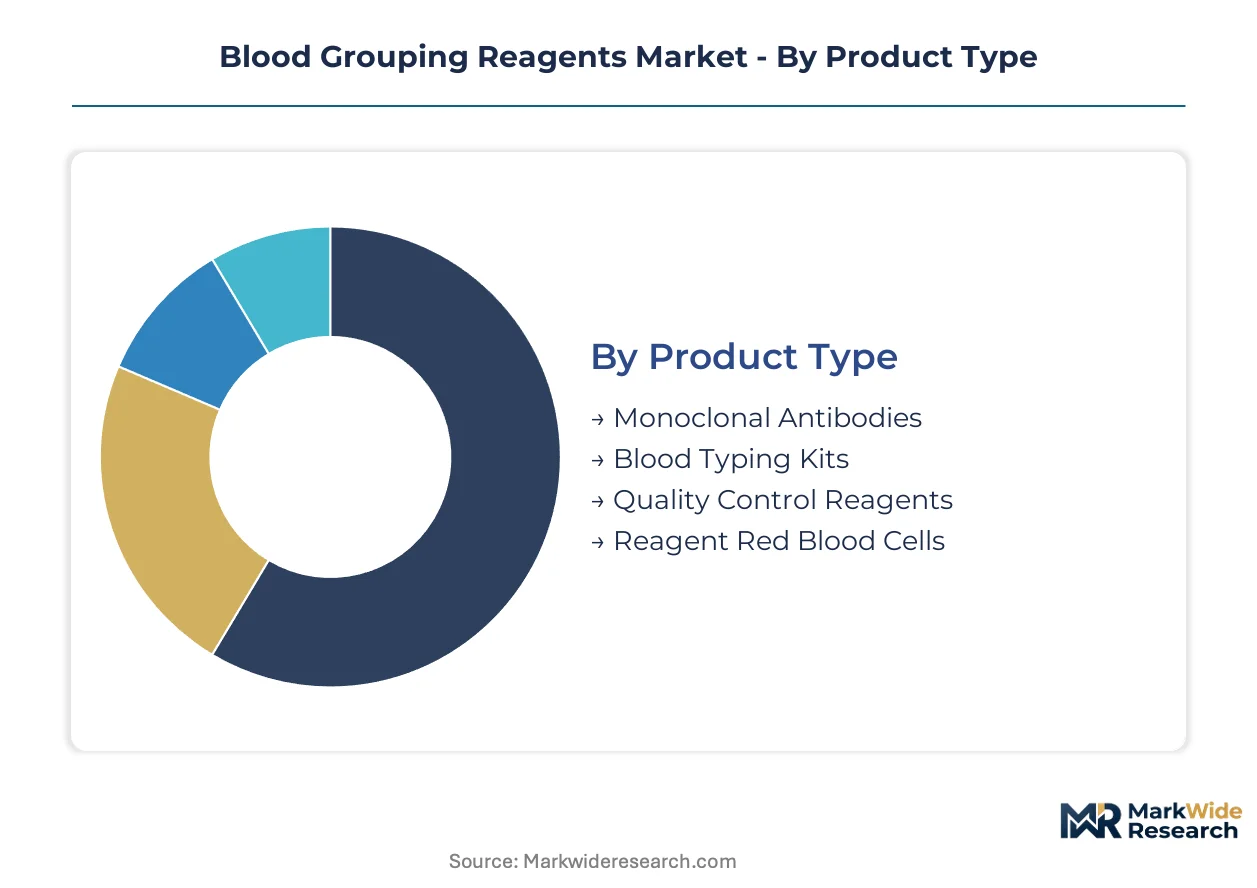
Reagent purchasing patterns fragment sharply between high-throughput hospital laboratories and resource-constrained satellite collection sites. Product specifications, technology choices, and regulatory compliance requirements diverge meaningfully across these operational contexts.
Product Type:
Monoclonal antibodies command premium pricing tiers while blood typing kits drive procurement volume in decentralized settings.
- Monoclonal Antibodies:IgM and IgG formulations with defined specificity profiles against ABO, Rh, and extended blood group antigens. Demand concentrates in United States reference laboratories where FDA blood establishment registration mandates validated, high-titer reagent documentation.
- Blood Typing Kits:Pre-configured reagent panels for forward and reverse grouping with standardized reaction matrices. Procurement volumes are climbing fastest in India and Brazil as satellite blood collection sites expand manual testing infrastructure.
- Quality Control Reagents:Certified reference materials for lot validation and accreditation maintenance.
- Reagent Red Blood Cells:Phenotyped donor cells for antibody identification and cross-matching procedures.
Today's leader: Monoclonal Antibodies. Tomorrow's challenger: Blood Typing Kits.
End User:
Hospital transfusion services anchor procurement value while blood banks sustain reagent volume through screening mandates.
- Hospitals:Tertiary care centers with surgical recovery programs are consolidating analyzer-reagent bundling contracts across integrated delivery networks. Kaiser Permanente and HCA Healthcare systems in the United States are standardizing immunohematology platforms to lock in five- to seven-year consumable agreements.
- Blood Banks:Regional and national collection facilities processing donor units for antigen-negative inventory. Manual tube methods persist in Brazilian and Indian networks where automated infrastructure remains underdeveloped.
- Diagnostic Laboratories:Reference facilities performing complex antibody identification for external clients.
- Research Institutions:Academic medical centers developing molecular genotyping protocols for extended phenotyping applications.
Procurement gravity sits with Hospitals. Volume expansion is climbing the fastest with Blood Banks.
Application:
Transfusion medicine generates recurring reagent consumption while forensic applications command specialized specifications.
- Transfusion Medicine:Pre-transfusion testing, antibody screening, and cross-matching for surgical and chronic transfusion patients. United States hospital networks are adopting extended phenotyping protocols to preempt alloimmunization in sickle cell disease populations.
- Organ Transplants:Histocompatibility testing and donor-recipient matching for solid organ and stem cell procedures. Demand is concentrating in academic medical centers with transplant authorization.
- Paternity Testing:ABO and Rh typing for relationship confirmation in legal and immigration proceedings.
- Forensic Science:Bloodstain identification and species determination for criminal investigations.
Transfusion Medicine dominates procurement. Organ Transplants is gaining share fastest.
Technology:
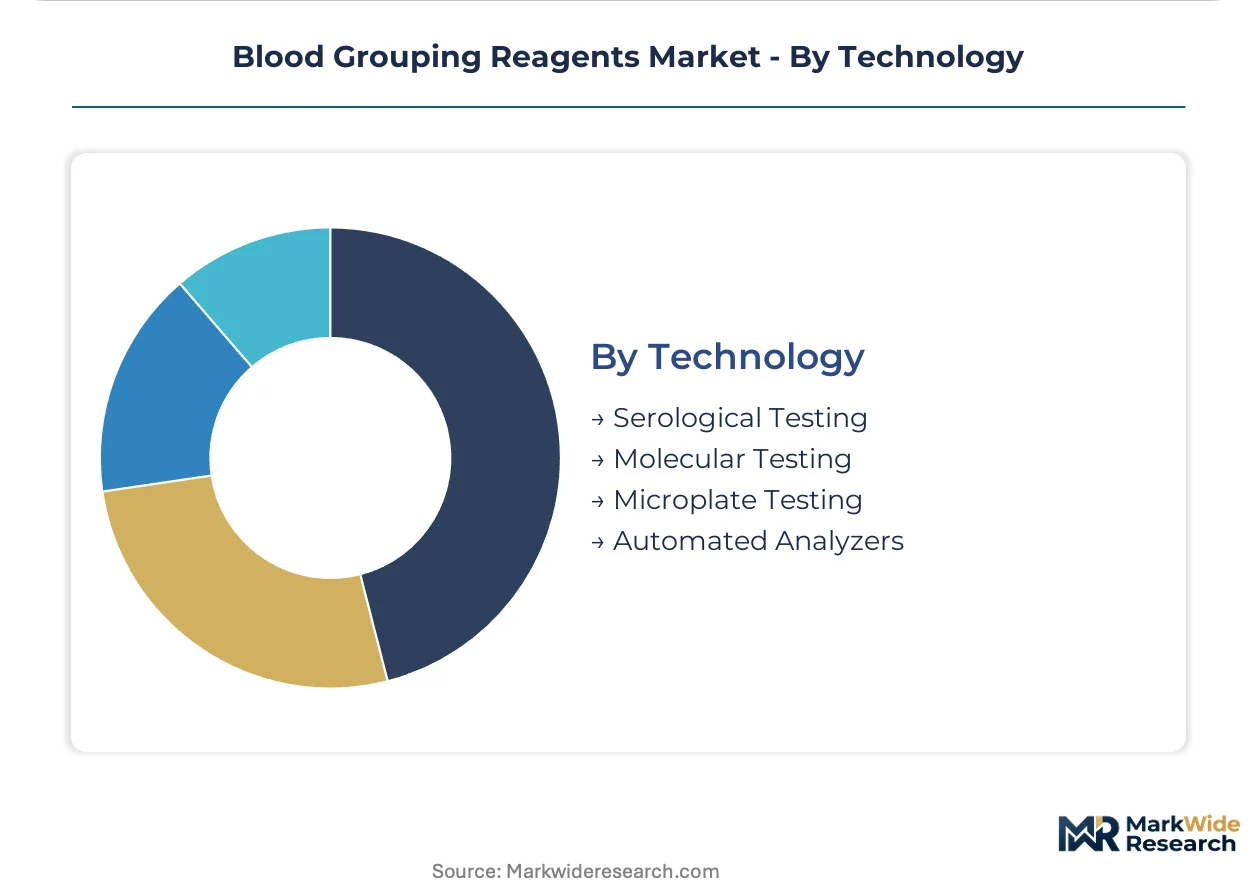
Serological methods retain volume leadership while molecular testing captures complex case resolution workflows.
- Serological Testing:Hemagglutination-based assays using reagent antisera and patient red blood cells. Blood banks across the United States, Germany, and Japan maintain manual tube methods for donor screening and antibody identification.
- Molecular Testing:PCR-based genotyping for Kell, Duffy, and Kidd antigen prediction. Reference laboratories at United States academic medical centers are consolidating complex antibody resolution into DNA-based workflows.
- Microplate Testing:High-throughput solid-phase assays for antibody screening in large-volume laboratories.
- Automated Analyzers:Closed-system immunohematology platforms with embedded reagent cartridges and bidirectional data interfaces.
Serological Testing holds installed base dominance. Molecular Testing is expanding most quickly in reference settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States procurement volumes exceed German hospital network consumption by a factor of three, while Indian satellite collection sites expand manual testing infrastructure at rates unmatched in mature markets.
United States
Kaiser Permanente and HCA Healthcare systems are consolidating immunohematology analyzer contracts across multi-state networks. FDA blood establishment registration mandates are forcing laboratory upgrades toward validated, high-titer reagent suppliers. The Southeast and Midwest regions exhibit the most concentrated procurement gravity as health system mergers create uniform reagent specifications.
Germany
University hospital transfusion services are adopting extended phenotyping protocols for chronically transfused patient populations. The EU IVDR is extending technical documentation timelines for CE-marked antibody reagents. The Rhine-Ruhr and Bavarian medical clusters anchor demand for quality control reagents supporting ISO 15189 accreditation maintenance.
India
Satellite blood collection sites in Maharashtra and Karnataka lack automated infrastructure, creating sustained demand for stabilized liquid reagents compatible with manual tube methods. The country's national pharmaceutical regulator is tightening import documentation for diagnostic antibodies. Hyderabad and Bangalore house emerging reference laboratories pursuing international accreditation to access insurance reimbursement pools.
Brazil
Regional blood banks in São Paulo and Minas Gerais sustain manual tube methods for donor screening where automated infrastructure remains underdeveloped. ANVISA conformity assessment requirements are extending product registration timelines for imported reagent portfolios. The Southeast region concentrates procurement volume as state health systems centralize transfusion service contracts.
Japan
Academic medical centers in Tokyo and Osaka are consolidating complex antibody resolution workflows through PCR-based genotyping platforms. PMDA post-market surveillance requirements are tightening lot-to-lot consistency documentation for antibody reagents. The Kanto region anchors demand as integrated hospital networks standardize immunohematology platforms across member facilities.
Blood Grouping Reagents Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with diversified diagnostics conglomerates commanding reference laboratory contracts while regional producers serve decentralized collection sites. The vendor base concentrates around three instrument-integrated ecosystems controlling seventy percent of installed analyzer capacity. Two strategic archetypes dominate: platform-integrated consumable suppliers and quality control reagent specialists. M&A activity targets regulatory affairs infrastructure, while portfolio diversification moves absorb molecular genotyping capabilities.
Among diversified diagnostics conglomerates, Thermo Fisher Scientific Inc. and Danaher Corporation exemplify the platform-integrated archetype, anchoring ecosystem strategies that embed consumable pull-through within analyzer installations. Grifols, S.A. occupies a distinct position as a European-based specialist with plasma-derived reagent portfolios. These three entities represent contrasting approaches to navigating IVDR conformity burdens and FDA registration requirements.
| Leading Market Players |
|---|
| Bio-Rad Laboratories, Inc. |
| Grifols, S.A. |
| QuidelOrtho Corporation |
| Immucor, Inc. |
| Merck KGaA |
| Thermo Fisher Scientific Inc. |
| Ortho Clinical Diagnostics |
| Danaher Corporation |
| Beckman Coulter, Inc. |
| Others |
Supply Flow & Price Mechanics
Software-defined assay protocols bundled with analyzer platforms are compressing standalone reagent margins while simultaneously concentrating supply leverage among three instrument vendors controlling seventy percent of installed immunohematology capacity. This technological shift forces mid-sized producers to absorb middleware development costs or withdraw from retrofit accounts entirely.
Pricing Analysis
Capacity additions in India and Brazil are reshaping price floors for stabilized liquid reagents compatible with manual tube methods. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with ISO 15189-accredited reference laboratories showing lowest price sensitivity. Cost compression in the economy tier is intensifying because satellite collection sites lack automated infrastructure and negotiate purely on unit cost. Blood banks in Southeast Asia and Latin America represent the most price-sensitive buyer segment.
Supply Chain Analysis
Monoclonal antibody production rests on fetal bovine serum sourced from United States and Australian suppliers, with human plasma fractions drawn from European and North American fractionation networks. Key inputs include buffered saline formulations, defined-titer antibody suspensions, and phenotyped donor cell lines. Single-source vulnerability concentrates in plasma-derived raw materials subject to biologics manufacturing cycle volatility. Distribution runs through integrated health network procurement offices and regional blood bank cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Blood Grouping Reagents Market functions as a stable compounder where recurring consumable pull-through from installed analyzer bases generates predictable revenue streams regardless of cyclical pressures.
For Market Incumbents: Anchor analyzer-reagent bundling contracts through five- to seven-year procurement cycles that lock hospital laboratories into consumable pull-through. Defend against molecular genotyping substitution by embedding serological testing within confirmatory-only workflow roles. Prioritize regulatory affairs infrastructure investments to absorb IVDR conformity burdens that force smaller competitors into SKU withdrawals. For New Entrants and Emerging Players: The price-point gap between premium analyzer-integrated reagents and economy manual tube methods creates immediate white-space opportunity. Target satellite blood collection sites in Maharashtra and Karnataka lacking automated infrastructure. Pursue quality control reagent specialization as mid-tier laboratories accelerate ISO 15189 accreditation pursuit to access insurance reimbursement pools. For Investors and Strategic Acquirers: Roll-up economics work for regional quality control reagent specialists because regulatory compliance costs are concentrating supply among diversified diagnostics conglomerates. Five-to-ten year viability hinges on molecular genotyping capability absorption. Watch FDA blood establishment registration enforcement intensity as the inflection indicator for laboratory upgrade cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Conformity Pathway Investment | CE-marked reagent portfolios require extended technical documentation timelines under EU In Vitro Diagnostic Regulation. |
| Software-Defined Assay Development | Cloud-based titer optimization enables subscription revenue models decoupled from physical unit sales. |
| Reference Laboratory Partnership | Academic medical centers at Kaiser Permanente and HCA Healthcare systems consolidate complex antibody resolution workflows. |
| Quality Control Reagent Specialization | ISO 15189 accreditation maintenance creates recurring demand for certified reference materials in mid-tier laboratories. |
| Molecular Genotyping Capability Acquisition | PCR-based Kell, Duffy, and Kidd antigen prediction consolidates serological testing into confirmatory-only roles. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with transfusion service directors, immunohematology laboratory managers, GPO contracts managers, and regulatory affairs specialists at reagent manufacturers with secondary validation against FDA blood establishment registration databases, EU IVDR technical documentation filings, hospital procurement contracts, and ISO 15189 accreditation records. Bottom-up reagent consumption modeling triangulated against top-down analyzer installed base estimates.
Segment-weighting approaches applied product type, end user, application, and technology dimensions across the modeling period. CAGRs derived from surgical volume recovery trajectories, extended phenotyping protocol penetration rates, and molecular genotyping adoption curves in reference laboratory settings. Forecast inputs incorporated health system merger activity in United States Southeast and Midwest regions alongside satellite blood collection site expansion rates in India and Brazil.
Caveats apply where FDA enforcement intensity, IVDR audit backlog resolution, or plasma-derived input price volatility could materially shift the outlook. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Pathogen Detection Market
Diagnostics
Middle East and Africa Syndromic Multiplex Diagnostic Market
Diagnostics
Primary Care POC Diagnostics Market
Diagnostics
Asia-Pacific Autoimmune Disease Diagnostics Market
Diagnostics
H. Pylori Breath Test Kit Market
Diagnostics
Mycoplasma Detection System Market
Diagnostics
EMEA Meningitis Diagnostic Testing Market
Diagnostics
UAE in Vitro Diagnostics Market
Diagnostics
Global Inflammatory Bowel Disease (IBD) Diagnostic Market
Diagnostics
Cellular Health Screening Market
Diagnostics
E.Coli Latex Agglutination Test Kits Market
Diagnostics
Diabetes Diagnostics Market
Diagnostics
North America Thyroid Cancer Diagnostics Market
Diagnostics
Mycoplasma Diagnostics Market
Diagnostics
Global Rabies Diagnostics Market
Diagnostics
Rapid Influenza Diagnostic Tests (RIDT) Market