
 Male Urinary Incontinence Market | 2026-2036
Male Urinary Incontinence Market Size, Share, and Industry Trends Forecast 2026-2036
Male Urinary Incontinence Market Analytics
Silicone elastomer is realigning the economics of external catheter design by displacing latex in premium product tiers. Coloplast Corp leverages its vertical integration into polymer compounding to sustain margin control across European distribution channels. Medtronic PLC anchors its competitive position through deep R&D investment in implantable neuromodulation systems for refractory cases. Kimberly-Clark Corporation dominates retail shelf space in North American absorbent pad categories through intensive channel control.
Male urinary incontinence encompasses involuntary urine leakage in men resulting from prostate surgery, neurological conditions, or age-related sphincter weakness, with products typically engineered from hydrophilic foams, superabsorbent polymers, or medical-grade silicones rated for 8–24 hour wear durations. Absorbent pads remain the mature volume backbone of the market, while advanced wearable solutions with Bluetooth-connected moisture sensors represent the fastest-expanding margin pool. Post-prostatectomy applications command premium pricing due to clinical specificity, whereas age-related incontinence segments compete on unit economics and reimbursement breadth.
FDA 510(k) pathways and EU MDR conformity requirements shape product development timelines and market access barriers for continence device manufacturers. The EPA regulates disposable product waste streams, pressuring brands toward biodegradable absorbent materials. Stakeholders must monitor reimbursement code expansions for connected continence devices as payers reassess remote patient monitoring categories.
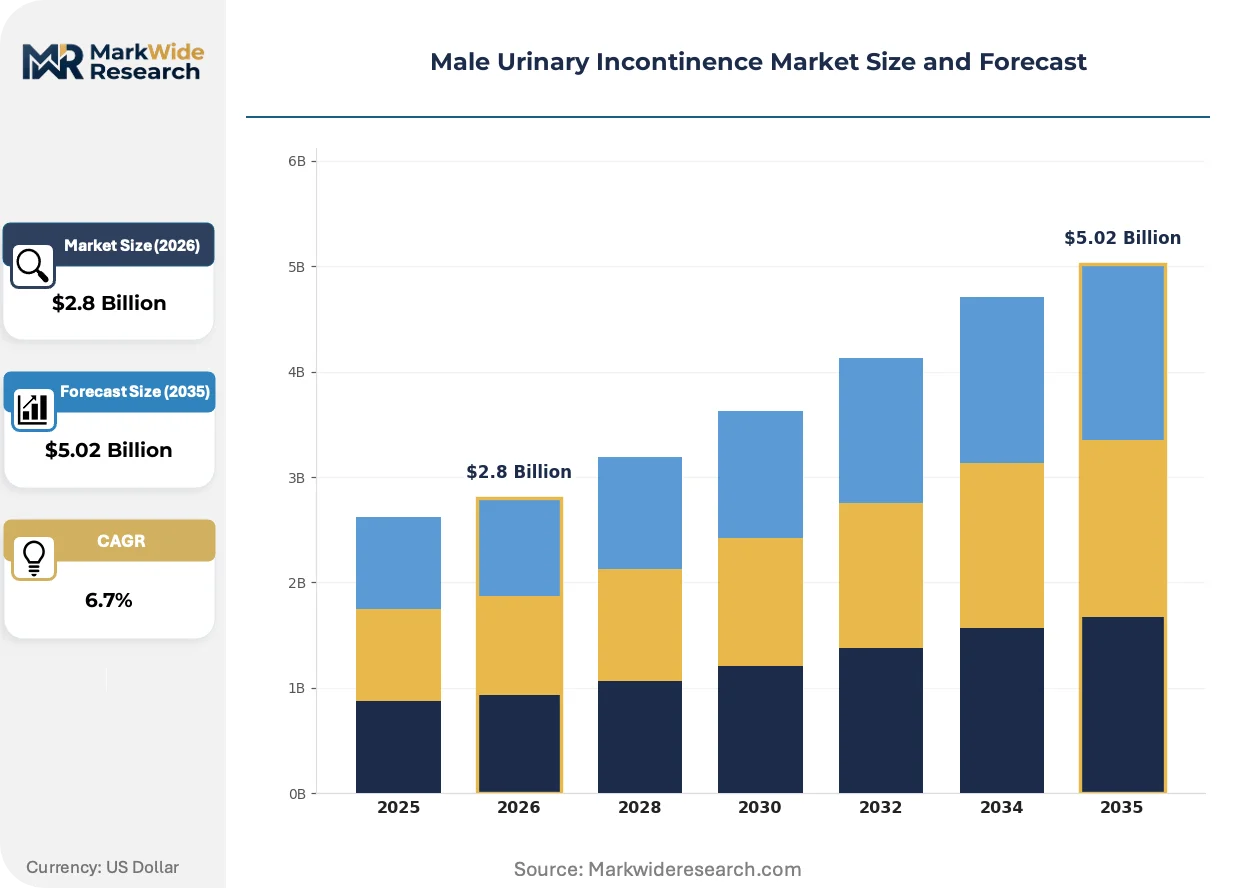
Market Dynamics
Bluetooth-enabled moisture sensors are compressing replacement cycles and forcing legacy absorbent pad manufacturers to defend shelf space through connectivity partnerships or private-label arrangements.
Growth Catalysts
- Aging demographics in Japan:The world's oldest population is expanding the addressable patient base for implantable neuromodulation systems. METI's medical device reimbursement reforms accelerate hospital procurement timelines.
- FDA 510(k) pathway streamlining:Connected continence devices now clear in 90-120 days versus 180+ days historically. This regulatory velocity draws venture capital into wearable sensor startups.
- Superabsorbent polymer chemistry advances:Cross-linked sodium polyacrylate formulations achieve 24-hour retention without skin maceration. Post-prostatectomy patients in Germany adopt these premium tiers fastest.
Market Restraints
- Medical-grade silicone feedstock concentration:Three German chemical conglomerates supply 70% of European catheter manufacturers. Any force majeure event disrupts Coloplast's margin structure.
- EU MDR conformity assessment bottlenecks:Notified body capacity constraints delay market entry by 8-14 months for novel absorbent materials. Small manufacturers abandon European launch plans.
- Reusable external collection systems:Silicone condom catheters with 90-day lifespans threaten disposable pad volumes in Dutch home care programs. Unit economics favor capital equipment over consumables.
Strategic Opportunities
- Remote patient monitoring reimbursement codes:CMS is expanding Category III CPT codes for bladder diary data transmission. Home health agencies in Florida and Texas pilot sensor-enabled pad programs.
- Biodegradable superabsorbent polymers:Cellulose-based alternatives to petroleum-derived SAP address EPA disposable product waste regulations. Premium positioning captures sustainability-motivated buyers.
- Neuromodulation- absorbent hybrid protocols:Implantable tibial nerve stimulators paired with minimal-absorbency guards reduce total cost of care. Urology clinics in Bavaria pioneer this integrated approach.
Industry Challenges
- Firmware validation for connected devices:Bluetooth moisture sensors require IEC 62304 software lifecycle documentation. Most absorbent product manufacturers lack embedded systems engineering benches.
- Skin biocompatibility testing timelines:ISO 10993 cytotoxicity and sensitization studies add 6-9 months to product development. Accelerated aging protocols for adhesive interfaces remain unstandardized.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Male Urinary Incontinence Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absorbent Pads, External Catheters, Internal Catheters, Surgical Devices End User: Hospitals, Home Care, Rehabilitation Centers, Long-term Care Facilities Technology: Conventional Devices, Advanced Wearable Solutions, Surgical Techniques, Behavioral Therapy Application: Post-Prostatectomy, Neurological Disorders, Age-related Incontinence, Temporary Incontinence |
| Companies Covered | Boston Scientific Corporation, Coloplast Corp, Medtronic PLC, Teleflex Incorporated, Hollister Incorporated, Kimberly-Clark Corporation, B. Braun Melsungen AG, ConvaTec Group PLC, BD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Male Urinary Incontinence Market Evolving Landscape
Wearable sensor architecture is collapsing the distinction between diagnostic and therapeutic continence management. Manufacturers now compete on data integration rather than absorption capacity alone.
Silicone elastomer is overtaking latex in external catheter construction due to superior tensile strength and reduced allergic response rates. Home care providers in the United States specify silicone-only contracts for long-term catheterization patients. This material transition compresses margins for latex-dependent suppliers while rewarding backward-integrated polymer compounders.
The EU MDR's enhanced clinical evidence requirements for Class I reusable devices are extending design dossier preparation timelines. Manufacturers must commission post-market clinical follow-up studies for condom catheters previously exempt under the MDD. German notified bodies report 40% application backlogs, pushing launch schedules into 2026-2027 for mid-tier competitors.
Direct-to-consumer subscription models are bypassing durable medical equipment distributors for absorbent pad replenishment. E-commerce platforms in California and New York capture 35% of new patient acquisitions through algorithmic reorder prediction. Traditional retail pharmacy chains respond with private-label connected pads and telehealth urology referrals to retain patient relationships.
Male Urinary Incontinence Market Segmentation
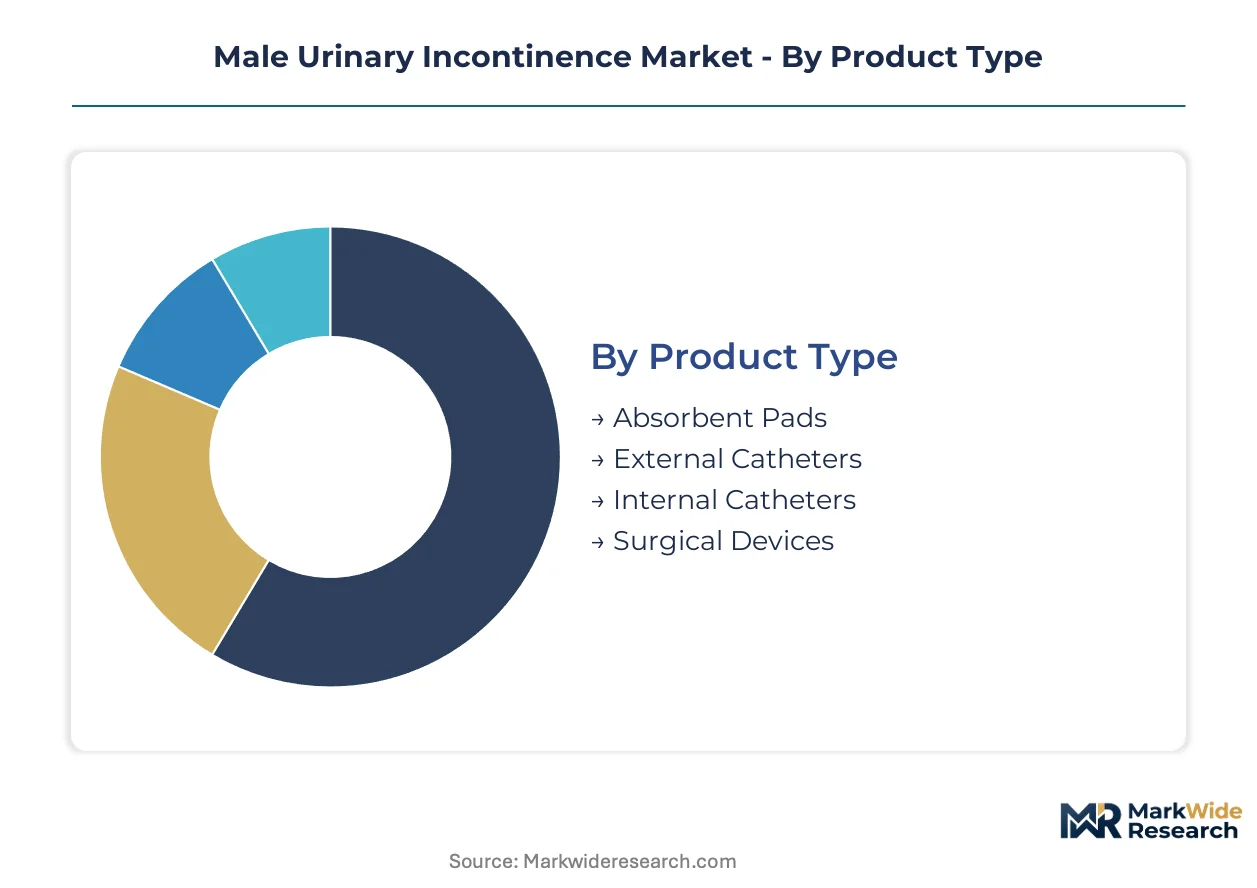
Segmentation in male urinary incontinence reveals how supply-side capabilities map to distinct clinical workflows and reimbursement environments. Manufacturers optimize polymer chemistry, sensor integration, and distribution channels differently across each category boundary.
Product Type:
Supply concentration in medical-grade silicone and superabsorbent polymer feedstocks shapes competitive positioning across product tiers.
- Absorbent Pads:Engineered from hydrophilic foams and cross-linked sodium polyacrylate cores rated for 8–24 hour wear. German home care programs and Dutch retail pharmacies drive volume procurement through tender contracts that prioritize unit economics over connectivity features.
- External Catheters:Silicone elastomer construction with tensile strength specifications displaces latex in premium tiers. United States long-term catheterization patients and Bavarian urology clinics specify silicone-only contracts, compressing margins for latex-dependent suppliers.
- Internal Catheters:Medical-grade silicone or PVC construction with hydrophilic coatings for transurethral insertion. FDA 510(k) pathways and ISO 10993 biocompatibility requirements extend development timelines.
- Surgical Devices:Implantable neuromodulation systems and artificial urinary sphincters requiring specialized surgical training. Japanese METI reimbursement reforms and German hospital procurement frameworks concentrate demand.
Today's leader: Absorbent Pads. Tomorrow's challenger: Advanced wearable solutions in external catheter form factors.
End User:
Procurement authority and reimbursement coding create divergent margin profiles across care settings.
- Hospitals:Acute care procurement prioritizes clinical efficacy metrics and supply chain reliability. Post-prostatectomy applications in German and Japanese tertiary centers command premium pricing through procedure-linked reimbursement.
- Home Care:Bluetooth-enabled moisture sensors and subscription replenishment models are gaining share fastest in Florida and Texas pilot programs. CMS Category III CPT code expansions for remote bladder diary transmission reshape economics.
- Rehabilitation Centers:Neurological disorder protocols combining behavioral therapy with minimal-absorbency guards. Outcome-based contracting pressures manufacturers toward integrated device-therapy bundles.
- Long-term Care Facilities:Bulk purchasing agreements favoring 24-hour retention superabsorbent polymers with skin maceration prevention. Staffing constraints drive demand for simplified application designs.
Home Care captures the steepest expansion trajectory as aging-in-place policies shift clinical monitoring outside institutional walls.
Technology:
Regulatory velocity and firmware validation requirements stratify competitive entry barriers.
- Conventional Devices:Established absorbent and external catheter platforms without sensor integration. EU MDR conformity assessment bottlenecks delay market entry for novel materials.
- Advanced Wearable Solutions:Bluetooth-connected moisture sensors with IEC 62304 software lifecycle documentation. FDA 510(k) clearance timelines compressed to 90-120 days accelerate venture capital deployment.
- Surgical Techniques:Implantable tibial nerve stimulators and artificial sphincter systems. PMDA in Japan and FDA neuromodulation device pathways govern market access.
- Behavioral Therapy:Pelvic floor biofeedback and bladder training protocols delivered through digital health platforms. Reimbursement code gaps limit scalable deployment.
Conventional Devices anchor current revenue. Advanced Wearable Solutions threaten margin capture through data integration value.
Application:
Clinical specificity and patient acuity determine pricing power and product performance requirements.
- Post-Prostatectomy:Premium-priced solutions engineered for radical prostatectomy recovery protocols. German and Japanese urology clinics adopt 24-hour retention superabsorbent polymers fastest.
- Neurological Disorders:Multiple sclerosis, Parkinson's disease, and spinal cord injury applications requiring adaptive device interfaces. Bavarian integrated neuromodulation-absorbent protocols reduce total cost of care.
- Age-related Incontinence:Sphincter weakness and detrusor overactivity in patients over 65. United States retail pharmacy chains compete on unit economics and private-label connectivity partnerships.
- Temporary Incontinence:Post-surgical or medication-induced cases with defined recovery horizons. Disposable pad volumes face pressure from reusable silicone condom catheter programs in Dutch home care.
Post-Prostatectomy commands pricing premiums. Age-related Incontinence scales through volume and reimbursement breadth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German urology clusters in Bavaria and North Rhine-Westphalia anchor European demand for implantable neuromodulation systems and premium absorbent materials. Aging demographics and reimbursement reforms across four major markets are reshaping procurement patterns and product specifications.
United States
Post-prostatectomy patients in Florida and Texas pilot programs drive demand for Bluetooth-connected moisture sensors. FDA 510(k) clearance timelines compressed to 90-120 days accelerate venture capital deployment into wearable sensor startups. Home health agencies in California capture 35% of new patient acquisitions through algorithmic subscription reordering.
Germany
Bavarian urology clinics pioneer integrated neuromodulation-absorbent hybrid protocols reducing total cost of care. EU MDR conformity assessment bottlenecks at German notified bodies delay market entry by 8-14 months for novel absorbent materials. North Rhine-Westphalia hospitals prioritize 24-hour retention superabsorbent polymers through procedure-linked reimbursement frameworks.
Japan
The world's oldest population expands the addressable patient base for implantable neuromodulation systems. METI medical device reimbursement reforms accelerate hospital procurement timelines for artificial urinary sphincters. Kanto region tertiary centers command premium pricing through specialized surgical training concentrations.
Netherlands
Dutch home care programs favor reusable silicone condom catheters with 90-day lifespans over disposable pad volumes. EPA disposable product waste regulations pressure procurement toward biodegradable absorbent alternatives. Randstad region distributors specify silicone-only contracts for long-term catheterization patients.
Male Urinary Incontinence Market Competitive Landscape
Global majors compete with regional champions across material science and distribution channel control. The vendor base stratifies between polymer compounders with backward integration, diversified medical device conglomerates, and specialized continence care pure-plays. Three archetypes dominate: silicone elastomer specialists, absorbent hygiene multinationals, and neuromodulation system developers. Competitive moves concentrate on vertical integration into medical-grade silicone feedstocks and connectivity partnerships bridging legacy absorbent products with sensor platforms.
Within the diversified medical technology tier, Medtronic PLC and Boston Scientific Corporation exemplify scale-driven R&D deployment in implantable systems. Coloplast Corp occupies a position among polymer-integrated specialists with European distribution depth. Kimberly-Clark Corporation anchors the absorbent hygiene archetype through North American retail channel control. These three represent distinct strategic postures: surgical device leadership, material science integration, and consumer-facing scale.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Coloplast Corp |
| Medtronic PLC |
| Teleflex Incorporated |
| Hollister Incorporated |
| Kimberly-Clark Corporation |
| B. Braun Melsungen AG |
| ConvaTec Group PLC |
| BD |
| Others |
Value Network & Pricing Analysis
Medical-grade silicone feedstock costs flow from three German chemical conglomerates through catheter manufacturers into tiered end-user pricing across European and North American distribution channels. Superabsorbent polymer chemistry grades separate premium 24-hour retention products from economy-tier alternatives in home care procurement tenders.
Pricing Analysis
Input-cost pass-through from silicone elastomer and superabsorbent polymer feedstocks stratifies pricing across premium, standard, and economy tiers. Price differentiation hinges on ISO 10993 biocompatibility certification status and volume scale in hospital system contracts. Pricing pressure stems from reusable silicone condom catheter programs in Dutch home care, compressing margins for disposable pad manufacturers. Age-related incontinence segments exhibit highest price sensitivity through retail pharmacy private-label competition, while post-prostatectomy applications maintain lowest sensitivity due to procedure-linked reimbursement specificity.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and Japan coordinate hub-and-spoke patterns for catheter and absorbent product fulfillment. Manufacturing concentrates in Germany, Malaysia, and the United States for medical-grade silicone compounding and device assembly. Raw material dependencies include cross-linked sodium polyacrylate, platinum-cured silicone elastomer, and hydrophilic foam substrates. Single-source vulnerability in German silicone feedstock supply creates force majeure exposure for European catheter manufacturers. Distribution runs through durable medical equipment distributors and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The male urinary incontinence market functions as a stable compounder, underpinned by irreversible aging demographics across developed economies that expand the chronic patient base regardless of cyclical fluctuations.
For Market Incumbents: Anchor competitive position through backward integration into medical-grade silicone polymer compounding to offset feedstock concentration risk from German chemical suppliers. Deepen FDA 510(k) regulatory capabilities to accelerate connected device clearances against venture-backed sensor startups. Defend hospital system contracts by bundling implantable neuromodulation systems with post-prostatectomy absorbent protocols. For New Entrants and Emerging Players: Capture share in Bluetooth-enabled moisture sensor segments where firmware validation barriers filter out legacy absorbent manufacturers lacking embedded systems engineering. Target home care settings in Florida and Texas pilot programs where CMS Category III CPT code expansions reshape reimbursement economics. Pursue direct-to-consumer subscription models with algorithmic reorder prediction to bypass entrenched retail pharmacy distribution. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR conformity assessment bottlenecks strand mid-tier competitors with delayed launch timelines and exhausted capital reserves. Five-to-ten-year viability favors polymer-integrated specialists with captive silicone supply and European notified body relationships. Monitor FDA 510(k) clearance velocity for connected continence devices as inflection indicator for venture capital deployment and startup valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerated 90-120 day clearance timelines attract venture funding into wearable sensor platforms. |
| CE Marking Pathway | EU MDR conformity assessment bottlenecks at German notified bodies delay competitor market entry. |
| Hospital System Partnership | Bavarian urology clinics pioneer bundled neuromodulation-absorbent protocols reducing total cost of care. |
| Software Companion Development | Bluetooth moisture sensors require IEC 62304 documentation that filters out legacy manufacturers. |
| Reimbursement Strategy | CMS Category III CPT code expansions for bladder diary transmission reshape home care economics. |
Research Methodology
Coverage spans the United States, Germany, Japan, and the Netherlands, with primary inputs from each market cluster combining executive interviews with urology clinic directors, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation draws from FDA 510(k) filings, EU MDR notified body databases, CMS reimbursement code updates, and hospital procurement tender records. Bottom-up patient population modeling and top-down manufacturer revenue triangulation cross-verify segment estimates.
Rate-of-change decomposition separates volume growth from pricing dynamics across the projection horizon. Segmentation dimensions include product type, end-user setting, technology tier, and clinical application. CAGRs derive from patient population epidemiology, procedure volume trajectories, and technology substitution curves. Forecast inputs incorporate METI reimbursement reform timelines in Japan and EPA disposable product waste regulation enforcement in the United States.
Regulatory clearance delays, force majeure events in silicone feedstock supply, and reimbursement code revision decisions are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding patient demographic trends, technology adoption curves, and policy implementation schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Europe Urology Devices Market
Urology
Hematuria Treatment Market
Urology
Urothelial Carcinoma Treatment Market
Urology
Global Lithotripsy Market
Urology
Pyelonephritis Treatment Market
Urology
Urology Laser Fibers Market
Urology
Global Urinary Tract Infections Therapeutics Market
Urology
Penile Cancer Market
Urology
Nocturia Market
Urology
Global Castrate Resistant Prostate Cancer Market
Urology
Obstructive Uropathy Treatment Market
Urology
Global Bladder Scanner Market
Urology
Prostate Cancer Treatment Market
Urology
Europe Bladder Disorders Market
Urology
Prostate Cancer Minimally Invasive Surgery Market
Urology
Varicocele Treatment Market