
 Global Antinuclear Antibody Test Market | 2026-2036
Global Antinuclear Antibody Test Market Size, Share, and Industry Trends Forecast 2026-2036
Global Antinuclear Antibody Test Market Foresight
Multiplex immunoassay technology is fragmenting the traditional indirect immunofluorescence workflow into parallel, high-throughput platforms. Thermo Fisher Scientific leverages its reagent-instrument bundled model to sustain installed-base loyalty across clinical reference labs. Bio-Rad Laboratories anchors its position through vertical control over assay calibrators and substrate slides. EUROIMMUN Medizinische Labordiagnostika AG dominates the European immunofluorescence segment with its standardized HEp-2 cell line portfolio.
An antinuclear antibody test detects autoantibodies directed against components within the cell nucleus, typically performed on human epithelial type 2 (HEp-2) cells fixed to glass slides and visualized through fluorescent conjugated secondary antibodies at defined serum dilutions. The primary purpose is differential diagnosis of systemic lupus erythematosus, Sjögren syndrome, and systemic sclerosis in rheumatology and immunology workflows. Enzyme-linked immunosorbent assay kits retain the largest volume share in high-throughput hospital labs where cost-per-test efficiency governs procurement decisions. Chemiluminescence immunoassay platforms represent the fastest-expanding delivery mode as manufacturers integrate random-access analyzers into core laboratory automation lines. Point-of-care testing occupies a narrow but strategically defended niche in rheumatology specialty clinics requiring same-day triage.
The FDA governs antinuclear antibody tests as Class II medical devices under 21 CFR 866, requiring substantial equivalence demonstrations for new assay clearances. The EU IVDR reclassifies immunofluorescence devices to higher-risk categories, forcing manufacturers to generate expanded clinical performance data for CE marking renewal. Japan's PMDA maintains distinct reference ranges for HEp-2 patterns among East Asian populations, creating localized validation requirements. Stakeholders must monitor how regulatory divergence between FDA predicate rules and IVDR clinical evidence demands reshapes product development priorities and geographic launch sequencing.
Market Dynamics
Multiplex immunoassay platforms are fragmenting the traditional indirect immunofluorescence workflow, forcing manufacturers to defend installed bases through reagent-instrument bundling while laboratories demand higher throughput per square meter of bench space.
Growth Catalysts
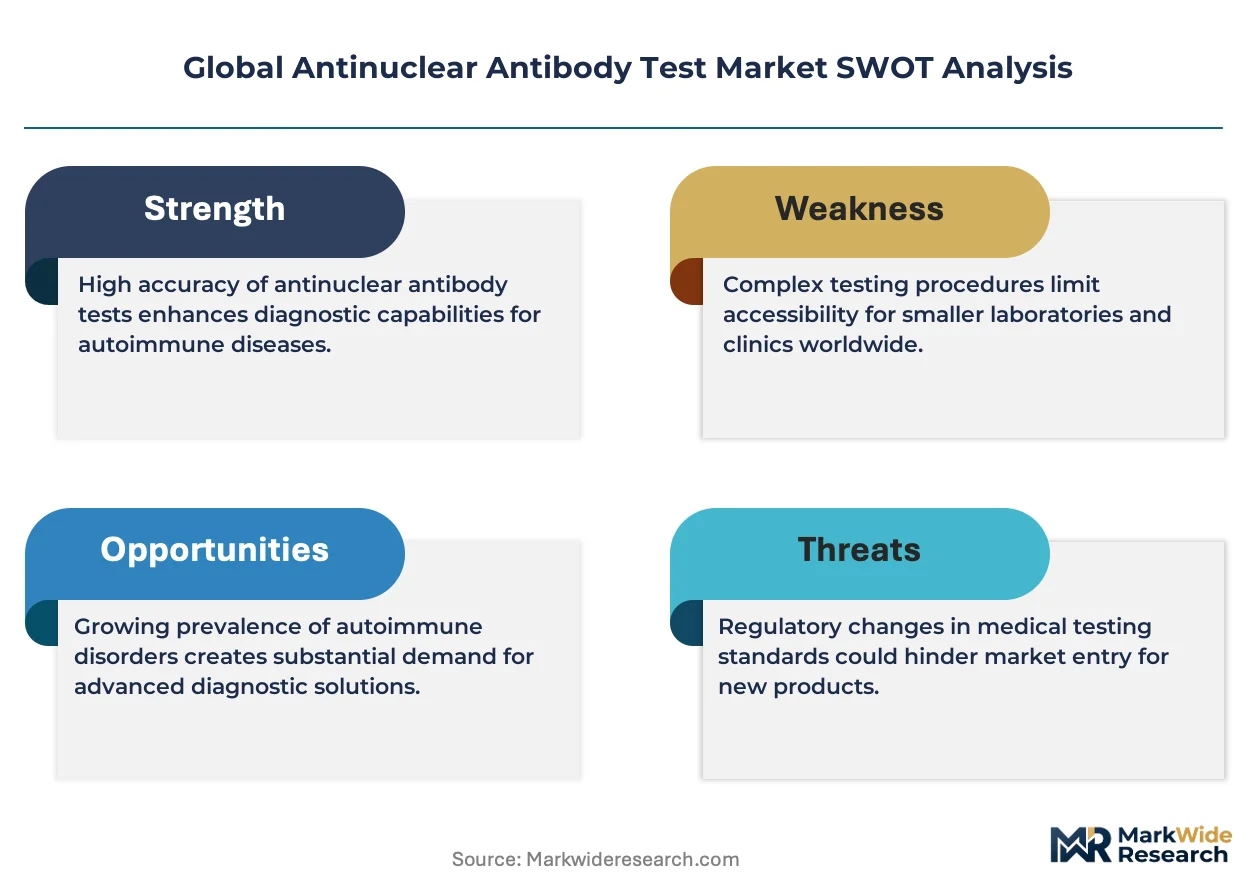
- EU IVDR Reclassification:The European Union's In Vitro Diagnostic Regulation is elevating immunofluorescence devices to higher-risk categories, compelling laboratories to upgrade to validated automated platforms that reduce manual interpretation variability.
- Rheumatology Clinic Expansion:Specialty clinics in the United States and Germany are consolidating autoimmune testing into centralized laboratory networks, creating pull-through demand for random-access chemiluminescence analyzers.
- HEp-2 Substrate Standardization:Commercial cell line maturation is reducing lot-to-lot variability in fluorescent pattern recognition, improving diagnostic concordance across hospital networks and reference laboratories.
Market Restraints
- Fluorophore Cost Volatility:Rhodamine and fluorescein isothiocyanate conjugate prices fluctuate with specialty chemical supply chains concentrated in Chinese manufacturing zones.
- Interpretation Labor Intensity:Indirect immunofluorescence pattern classification requires trained morphologists, creating throughput ceilings that resist full automation despite hardware advances.
- Predicate Device Pathway Rigidity:The FDA's 21 CFR 866 substantial equivalence framework limits novel assay format introductions, compressing innovation returns for platform developers.
Strategic Opportunities
- Japanese Population-Specific Validation:The PMDA maintains distinct HEp-2 reference ranges for East Asian populations, creating localized product differentiation opportunities for manufacturers willing to conduct dedicated clinical trials.
- Point-of-Care Triage Integration:Rheumatology specialty clinics in Germany are piloting same-day ANA screening to accelerate specialist referral decisions, opening a premium channel outside core laboratory automation.
- Random-Access Analyzer Convergence:Chemiluminescence immunoassay modules are integrating into existing immunoassay lines, allowing hospitals to add autoimmune testing without dedicated capital equipment footprints.
Industry Challenges
- Morphologist Training Pipeline Collapse:Clinical laboratory science programs are graduating fewer specialists capable of pattern interpretation, widening the gap between automated screening and confirmatory microscopy.
- IVDR Technical Documentation Burden:Manufacturers face 12-18 month performance study timelines to renew CE markings for legacy immunofluorescence kits, straining regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Antinuclear Antibody Test Market |
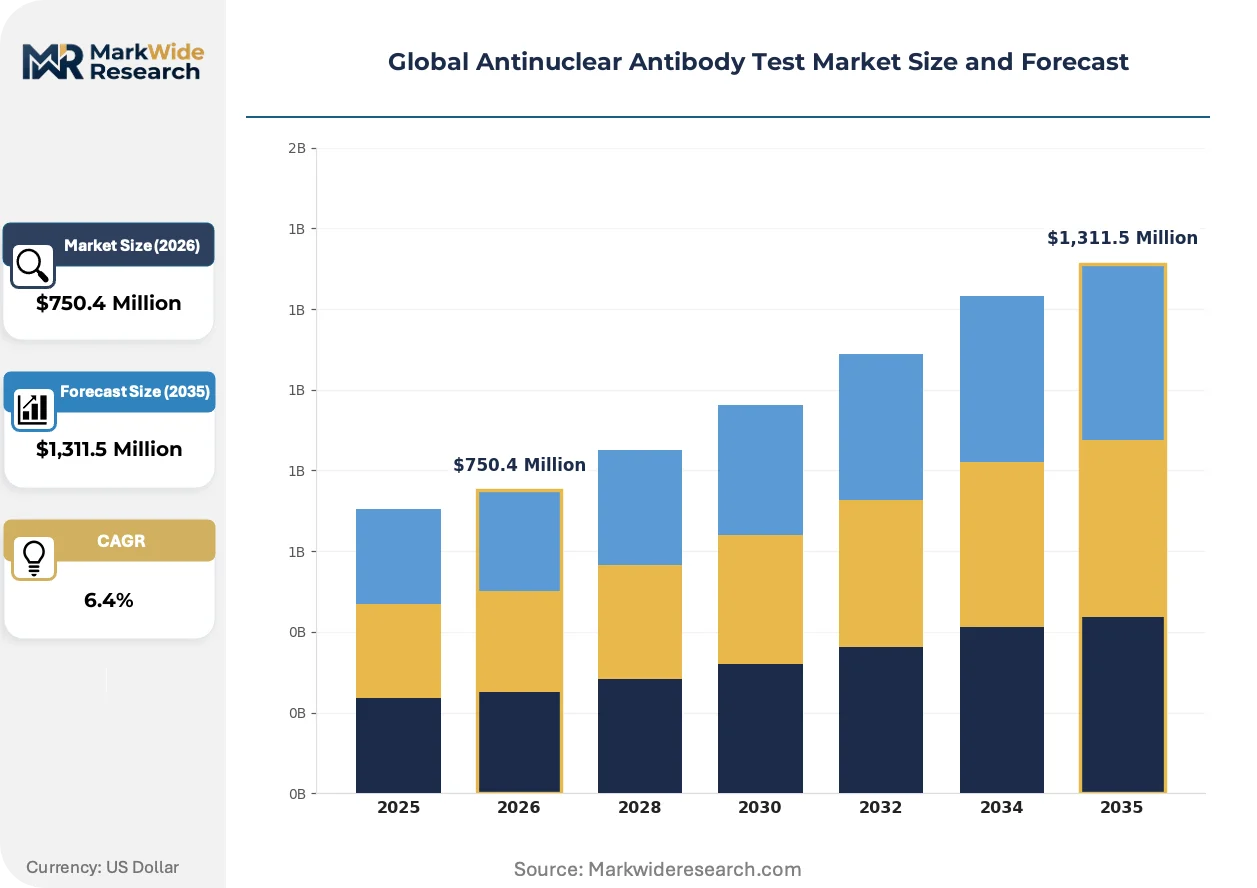
| Market Size in 2026 | $750.4 Million |
| Market Size in 2035 | $1,311.5 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indirect Immunofluorescence Assay, Enzyme-Linked Immunosorbent Assay, Multiplex Immunoassay, Chemiluminescence Immunoassay Application: Autoimmune Disorders, Rheumatology Diagnostics, Infectious Diseases, Oncology Screening End User: Diagnostic Laboratories, Specialty Clinics, Research Institutes, Blood Banks Delivery Mode: Manual Testing, Automated Testing, Point-of-Care Testing, Centralized Laboratory Services |
| Companies Covered | Abbott Laboratories, Bio-Rad Laboratories, Inc., Thermo Fisher Scientific, Inc., Trinity Biotech Plc., Antibodies Incorporated, EUROIMMUN Medizinische Labordiagnostika AG, Grifols SA, Erba Diagnostics, ZEUS Scientific, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Antinuclear Antibody Test Market Shifts & Advancements
Automation architectures are converging with artificial intelligence-assisted pattern recognition, compressing the gap between high-throughput screening and definitive morphological diagnosis while regulatory frameworks force evidence generation at unprecedented scale.
Multiplex bead-based immunoassay technology is hybridizing the specificity of antigen-specific confirmation with the throughput of initial screening. Large reference laboratories in the United States are adopting these platforms at accelerated replacement cycles for aging ELISA infrastructure. This convergence is compressing the traditional two-step workflow into single-instrument random-access processing, reducing hands-on time per patient sample.
Japan's PMDA is tightening post-market surveillance requirements for immunofluorescence devices used in clinical settings, mandating real-world performance tracking that mirrors pharmaceutical vigilance standards. Device manufacturers must now maintain active registries for pattern concordance studies. The chemiluminescence segment faces the steepest compliance burden as it captures volume from legacy methods.
Hospital procurement departments are unbundling reagent contracts from instrument placement agreements, reversing decades of bundled exclusivity arrangements. German laboratory networks are leading this shift, negotiating multi-vendor supply frameworks that prioritize cost-per-test transparency over single-source loyalty. This behavioral change is most visible in university hospital systems where centralized purchasing committees have displaced departmental autonomy.
Global Antinuclear Antibody Test Market Segmentation
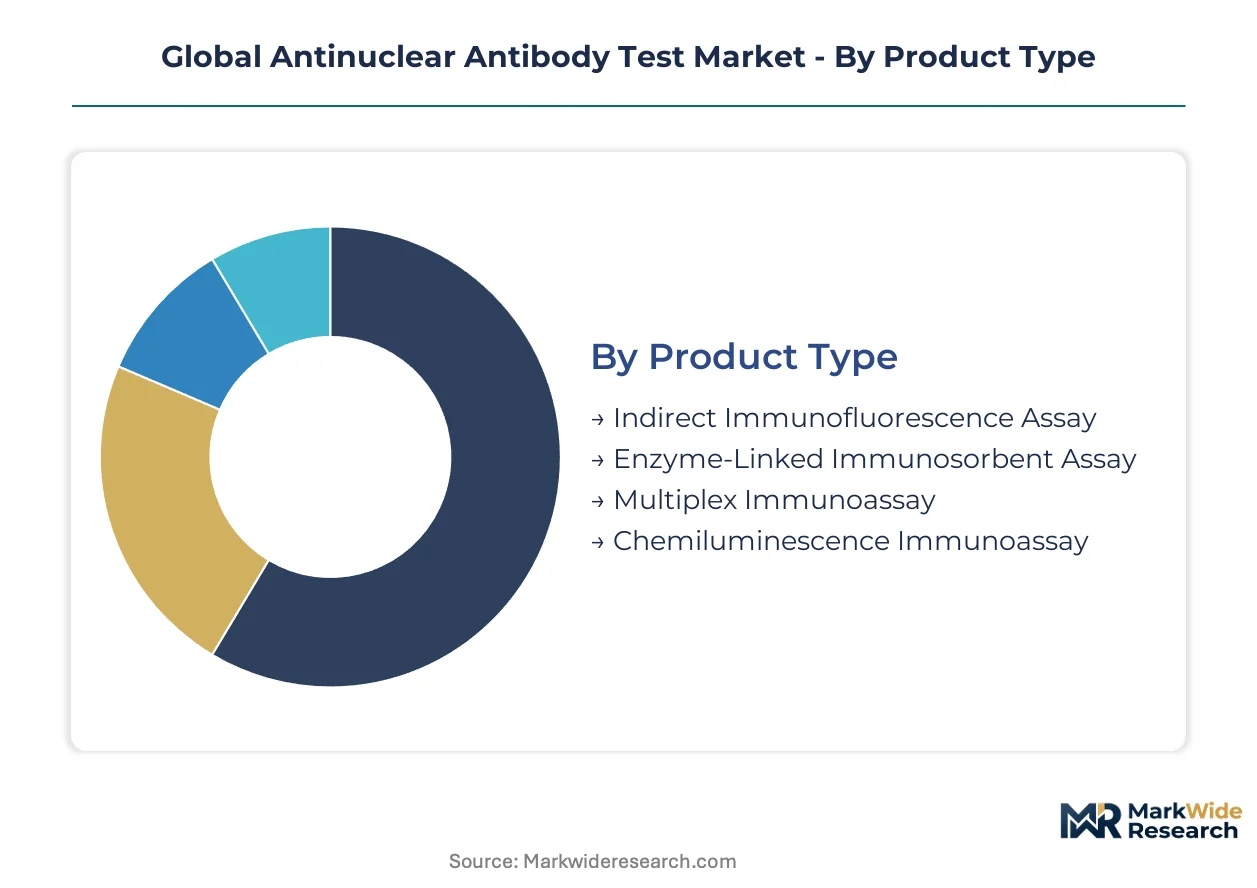
Antinuclear antibody testing fragments across four critical dimensions that determine procurement priorities, regulatory pathways, and automation investment cycles. Product type dictates capital equipment requirements and interpretive labor intensity. Application scope governs reimbursement codes and clinical validation evidence. End-user concentration shapes distribution channel economics and service contract structures. Delivery mode determines throughput ceilings and regulatory classification risk.
Product Type:
Indirect immunofluorescence assays anchor the reference standard tier, while chemiluminescence and multiplex platforms are displacing legacy workflows through automation integration.
- Indirect Immunofluorescence Assay:HEp-2 cell substrate fixed to glass slides enables morphological pattern classification through fluorescent conjugate visualization at defined serum dilutions. Demand concentrates in European reference laboratories where EU IVDR reclassification mandates validated automation to reduce manual interpretation variability.
- Chemiluminescence Immunoassay:Random-access analyzer integration delivers quantitative antibody detection with walkaway processing capability. United States hospital networks are consolidating autoimmune testing into core laboratory automation lines, pulling through chemiluminescence modules that slot into existing immunoassay tracks.
- Enzyme-Linked Immunosorbent Assay:Cost-per-test efficiency governs high-throughput procurement in budget-constrained hospital settings.
- Multiplex Immunoassay:Bead-based platforms hybridize screening throughput with antigen-specific confirmation in single-instrument processing.
The dominant share belongs to indirect immunofluorescence assays, while chemiluminescence immunoassay is closing the gap fastest through core laboratory automation convergence.
Application:
Clinical utility concentrates in autoimmune differential diagnosis, with rheumatology workflows generating the highest test volume per installed analyzer.
- Autoimmune Disorders:Systemic lupus erythematosus, Sjögren syndrome, and systemic sclerosis screening constitutes the foundational use case with established reimbursement pathways.
- Rheumatology Diagnostics:Specialty clinic consolidation in Germany and the United States is centralizing testing volume into networks that demand same-day turnaround and standardized pattern reporting.
- Infectious Diseases:ANA testing assists in ruling out autoimmune mimics during infectious workups.
- Oncology Screening:Paraneoplastic antibody panels incorporate ANA as a baseline exclusion marker.
Rheumatology diagnostics commands the largest procedure volume, though autoimmune disorders maintains the broadest addressable patient base across generalist and specialist settings.
End User:
Procurement authority is migrating from departmental autonomy to centralized purchasing committees that prioritize cost-per-test transparency over single-source instrument loyalty.
- Diagnostic Laboratories:Reference networks in Japan, Germany, and the United States dominate testing volume through automated platform consolidation and standardized quality protocols.
- Specialty Clinics:Rheumatology practices in Germany are piloting same-day ANA triage to accelerate specialist referral decisions, opening a premium channel outside core laboratory workflows.
- Research Institutes:Academic medical centers drive protocol development and biomarker discovery with flexible assay customization requirements.
- Blood Banks:Transfusion medicine protocols incorporate ANA screening for donor qualification in specific autoimmune indication contexts.
Diagnostic laboratories capture the dominant share, while specialty clinics are expanding most quickly through point-of-care integration pilots.
Delivery Mode:
Automation architectures are compressing the gap between high-throughput screening and definitive diagnosis through artificial intelligence-assisted pattern recognition.
- Automated Testing:Integrated immunoassay lines with random-access capability enable continuous loading and STAT prioritization without batch processing delays.
- Manual Testing:Indirect immunofluorescence microscopy retains necessity for confirmatory pattern classification where algorithmic interpretation remains non-definitive.
- Point-of-Care Testing:Rheumatology specialty clinics requiring same-day triage defend this narrow niche against core laboratory consolidation pressure.
- Centralized Laboratory Services:Networked hub-and-spoke models concentrate specialized morphology expertise in regional reference centers.
Automated testing holds the dominant position, while point-of-care testing is gaining share fastest through specialty clinic workflow integration pilots in Germany and Japan.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export immunofluorescence substrates and automated slide processors to diagnostic networks across the United States and Japan, establishing the primary trade corridor in specialized autoimmune testing equipment.
United States
Rheumatology clinic consolidation and hospital network centralization drive demand for random-access chemiluminescence analyzers. The FDA's 21 CFR 866 predicate device pathway governs new assay clearances through substantial equivalence demonstrations. Boston and San Diego biotech clusters host reference laboratories piloting AI-assisted pattern recognition for HEp-2 microscopy.
Germany
University hospital purchasing committees unbundle reagent contracts from instrument agreements, prioritizing cost-per-test transparency. The EU IVDR elevates immunofluorescence devices to higher-risk categories, mandating expanded clinical performance documentation. The Rhine-Ruhr laboratory network concentrates automated platform validation expertise for CE marking renewal.
Japan
East Asian population-specific HEp-2 reference ranges create localized validation requirements distinct from Western protocols. The PMDA tightens post-market surveillance with real-world performance registries mirroring pharmaceutical vigilance standards. Tokyo and Osaka medical centers anchor regional hub-and-spoke models for specialized morphology interpretation.
United Kingdom
NHS consolidation into regional pathology networks standardizes autoimmune testing procurement across hospital trusts. The MHRA aligns with EU IVDR quality standards post-Brexit, maintaining CE marking recognition for continental suppliers. London reference laboratories concentrate expertise in multiplex bead-based assay adoption.
China
Domestic diagnostic reagent manufacturers expand automated immunofluorescence capacity to reduce import dependence. The NMPA accelerates Class II device review timelines for autoimmune assays with established international predicate data. Shanghai and Beijing hospital networks pilot centralized ANA screening to manage rising systemic lupus erythematosus prevalence.
Global Antinuclear Antibody Test Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: multinational conglomerates with bundled reagent-instrument platforms, mid-cap specialists with vertical control over substrates and calibrators, and regional manufacturers competing on cost-per-test efficiency. The dominant competitive moves involve regulatory affairs capacity expansion to manage IVDR documentation burdens and strategic partnerships with reference laboratories for real-world performance data generation.
Among the multinational conglomerates, Thermo Fisher Scientific and Abbott Laboratories exemplify the reagent-instrument bundling archetype, while Bio-Rad Laboratories occupies a position within the substrate-specialist tier through its vertical control over assay calibrators and HEp-2 cell line production.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Bio-Rad Laboratories, Inc. |
| Thermo Fisher Scientific, Inc. |
| Trinity Biotech Plc. |
| Antibodies Incorporated |
| EUROIMMUN Medizinische Labordiagnostika AG |
| Grifols SA |
| Erba Diagnostics |
| ZEUS Scientific, Inc. |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese fluorophore conjugate manufacturing is compressing margins for indirect immunofluorescence reagent suppliers while simultaneously enabling aggressive pricing postures from domestic diagnostic manufacturers seeking to displace European substrate imports.
Pricing Analysis
Next-generation chemiluminescence modules command 40-60% premiums over aging ELISA infrastructure, while legacy indirect immunofluorescence workflows face sustained price erosion from automated platform consolidation. Three-tier pricing structure across premium, standard, and economy levels separates AI-assisted pattern recognition systems from basic automated slide processors from manual microscopy kits. Pricing pressure stems from hospital procurement committees unbundling reagent contracts and demanding cost-per-test transparency. Reference laboratories exhibit lowest price sensitivity due to reimbursement stability, while budget-constrained community hospitals drive volume toward economy tiers.
Supply Chain Analysis
Export control restrictions on specialized optical components and precision manufacturing equipment constrain domestic production capacity in emerging diagnostic markets. HEp-2 cell substrate production concentrates in Germany and the United States, while fluorophore conjugate synthesis anchors in Chinese chemical manufacturing zones. Supply chain vulnerability rests on single-source dependencies for rhodamine and fluorescein isothiocyanate precursors subject to specialty chemical tariff exposure. Distribution runs through regional laboratory networks that consolidate procurement through group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Workflow fragmentation across multiplex, chemiluminescence, and immunofluorescence modalities creates specialized niche opportunities as rheumatology clinic consolidation demands tailored automation solutions.
For Market Incumbents: Harden installed-base loyalty through captive reagent-instrument bundling and preemptive IVDR technical documentation investments that exhaust mid-cap regulatory affairs capacity. Defend against unbundling pressure by embedding AI-assisted pattern recognition modules that create switching costs. Prioritize backward integration into HEp-2 cell line production to secure substrate quality control.
For New Entrants and Emerging Players: Point-of-care triage pilots in German rheumatology specialty clinics represent the most penetrable entry point outside consolidated core laboratory networks. Japanese population-specific validation requirements for East Asian HEp-2 reference ranges create localized differentiation opportunities shielded from Western incumbent dominance. Pursue strategic partnerships with regional reference laboratories for real-world performance data generation.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among substrate-specialist manufacturers with vertical control over assay calibrators and cell line production. Long-term viability favors mid-cap specialists with demonstrated IVDR compliance capacity and established clinical evidence packages. Monitor morphologist training program graduation rates as an inflection indicator for automation substitution acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Technical Documentation Investment | CE marking renewal timelines strain regulatory affairs capacity across European immunofluorescence manufacturers. |
| AI-Assisted Pattern Recognition Development | Boston and San Diego biotech clusters pilot machine learning modules to compress diagnostic workflow gaps. |
| Reagent-Contract Unbundling Response | German university hospital purchasing committees displace departmental autonomy with centralized procurement frameworks. |
| Japanese Population-Specific Validation | PMDA distinct reference ranges for East Asian populations create localized clinical trial requirements. |
| Point-of-Care Triage Integration | Rheumatology specialty clinics in Germany pilot same-day ANA screening outside core laboratory automation. |
Research Methodology
The analysis maps indirect immunofluorescence, chemiluminescence, ELISA, and multiplex immunoassay sub-sectors, each validated through rheumatology clinic directors, hospital laboratory managers, diagnostic reagent procurement officers, and regulatory affairs specialists. Primary interview intelligence triangulates against FDA 510(k) filings, EU IVDR technical documentation databases, PMDA approval registries, hospital GPO contract disclosures, and CMS reimbursement code analyses. Bottom-up instrument placement and reagent consumption estimates reconcile with top-down market sizing across the analysis window.
Assumptions held fixed include current IVDR enforcement timelines, FDA predicate device pathway continuity, and established autoimmune disorder prevalence trajectories; variables stress-tested include fluorophore cost volatility, morphologist training pipeline collapse, and procurement unbundling acceleration. Segmentation modeling incorporates product type, application scope, end-user concentration, and delivery mode dimensions. CAGRs derive from instrument replacement cycle analysis, reagent pull-through coefficients, and geographic adoption pattern differentials calibrated against immunofluorescence substrate consumption trends.
Stress conditions across regulatory enforcement intensity, supply chain disruption severity, and procurement behavioral shift magnitude were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding IVDR implementation pace and automation substitution elasticity. Material shifts in EU IVDR reclassification scope or FDA substantial equivalence pathway modification would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Argentina in Vitro Diagnostics Market
Diagnostics
Diagnostic Exosome Biomarkers Market
Diagnostics
Cancer Tissue Diagnostics Market
Diagnostics
Global Prostate Specific Antigen (PSA) Test Market
Diagnostics
Tissue Transglutaminase Test Market
Diagnostics
Food Allergy Diagnostics and Therapeutics Market
Diagnostics
Rapid Influenza Diagnostic Tests (RIDT) Market
Diagnostics
BRIC in-Vitro Diagnostics (IVD) Market
Diagnostics
Equine Diagnostic Services Market
Diagnostics
Epigenetics Diagnostics Market
Diagnostics
Germany in-Vitro Diagnostics Market
Diagnostics
Europe Antinuclear Antibody Test Market
Diagnostics
Thrombosis and Hemostasis Biomarkers Market
Diagnostics
EMEA Meningitis Diagnostic Testing Market
Diagnostics
Cushing's Syndrome Diagnostics and Therapeutics Market
Diagnostics
Sperm Density Testing Market