
 Hepatitis E Diagnostic Tests Market | 2026-2036
Hepatitis E Diagnostic Tests Market Size, Share, and Industry Trends Forecast 2026-2036
Hepatitis E Diagnostic Tests Market Intelligence
Chinese assay manufacturers is decoupling from Western reagent supply chains, building independent enzyme and antibody production lines that reduce import dependency for ELISA substrate components. Roche Diagnostics leverages its nucleic acid amplification platform to dominate high-throughput blood screening contracts in European reference laboratories. Abbott Laboratories anchors its position through integrated chemiluminescence systems that consolidate hepatitis E testing within broader viral hepatitis panels. Wantai Biological specializes in recombinant antigen production, giving it cost advantages in public health procurement across endemic regions.
Hepatitis E diagnostic tests detect IgM, IgG antibodies or viral RNA in human serum, plasma, or stool specimens using immunological or molecular methods with analytical sensitivity thresholds typically below 50 IU per milliliter for serological formats. These assays serve primarily to identify acute infection, confirm past exposure, and prevent transfusion-transmitted outbreaks in immunocompromised recipients. Among product types, ELISA Kits sustain the largest installed base due to decades of protocol standardization, while PCR Assays capture the fastest expansion as nucleic acid amplification displaces serology in organ transplant monitoring. By end user, Diagnostic Laboratories occupy the deepest margin pools through bundled hepatitis panel pricing, whereas Public Health Agencies compete on volume tenders that prioritize unit cost over feature breadth.
FDA clearance pathways for serological devices and WHO prequalification standards for endemic-country procurement together shape product development priorities and market access timelines for manufacturers. EMA's In Vitro Diagnostic Regulation tightens clinical evidence requirements for CE-marked hepatitis E assays, favoring firms with robust post-market surveillance infrastructure. India's CDSCO mandates domestic clinical trials for imported diagnostic kits, creating regulatory friction that local manufacturers navigate more efficiently. Stakeholders must monitor how decentralized nucleic acid testing platforms reshape procurement patterns away from centralized laboratory contracts toward point-of-care deployment models.
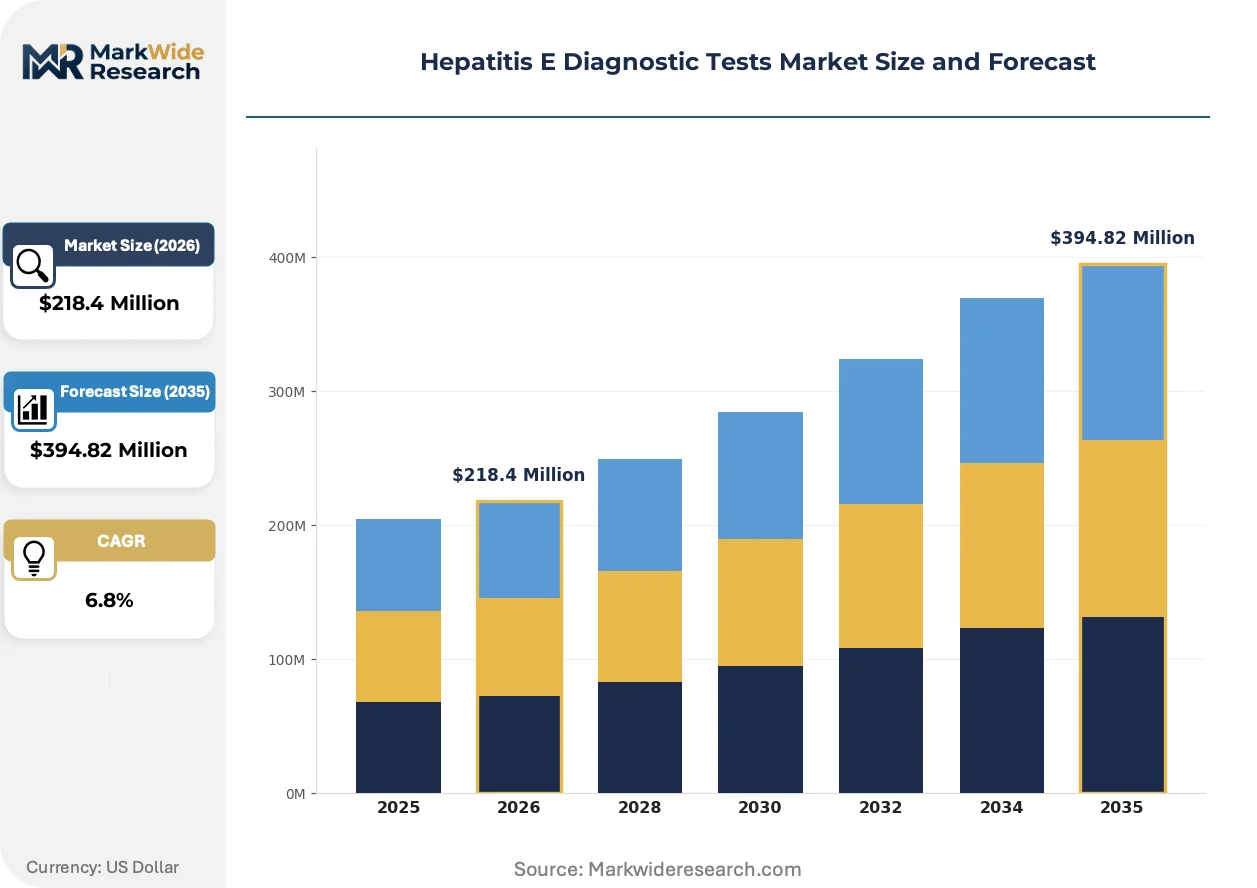
Market Dynamics
Nucleic acid amplification is displacing serological screening in transplant centers, compressing turnaround times from days to hours and forcing ELISA-dominant manufacturers to defend installed base through panel bundling.
Growth Catalysts
- WHO prequalification pathway:The WHO's streamlined approval mechanism accelerates test standardization across low-resource settings, enabling faster market entry for manufacturers targeting endemic regions.
- Blood bank screening mandates:Southeast Asian plasma collection facilities are expanding hepatitis E protocols to prevent transfusion-transmitted infections in immunocompromised recipients.
- Waterborne outbreak surveillance:India's endemic transmission patterns sustain procurement volume for both IgM serology and RNA detection assays across public health networks.
Market Restraints
- Reagent import dependency:Substrate enzyme supply chains remain concentrated in Western chemical manufacturers, exposing Asian assay producers to tariff and logistics volatility.
- Clinical evidence requirements:EMA's In Vitro Diagnostic Regulation mandates expanded post-market surveillance datasets, extending CE-marking timelines and compliance costs.
- Serology substitution pressure:Molecular platforms in reference laboratories are capturing acute-diagnosis volume previously assigned to IgM ELISA protocols.
Strategic Opportunities
- Decentralized testing deployment:Point-of-care nucleic acid platforms open procurement channels outside centralized laboratory contracts, reaching district hospitals and mobile screening units.
- Integrated hepatitis panels:Chemiluminescence systems that consolidate hepatitis A through E testing command premium positioning in high-throughput diagnostic networks.
- Domestic manufacturing incentives:India's PLI scheme for medical devices reduces cost barriers for local recombinant antigen production serving endemic markets.
Industry Challenges
- CDSCO trial mandates:India's requirement for domestic clinical validation of imported kits creates regulatory friction that delays market access for foreign manufacturers.
- Platform integration complexity:Reference laboratories face workflow reconfiguration costs when consolidating discrete serological and molecular assays onto unified automation tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hepatitis E Diagnostic Tests Market |
| Market Size in 2026 | $218.4 Million |
| Market Size in 2035 | $394.82 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ELISA Kits, PCR Assays, Rapid Diagnostic Tests, Immunoblotting, Chemiluminescence Assays Application: Blood Screening, Clinical Diagnosis, Surveillance Programs, Organ Transplant Monitoring, Epidemiological Studies End User: Diagnostic Laboratories, Blood Banks, Research Institutions, Veterinary Clinics, Public Health Agencies Technology: Nucleic Acid Amplification, Immunoassay, Biosensor Techniques, Microfluidics, Signal Amplification |
| Companies Covered | Roche Diagnostics, Abbott Laboratories, Siemens Healthineers, Thermo Fisher Scientific, Bio-Rad Laboratories, QIAGEN, Danaher Corporation, Fujirebio, Wantai Biological, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hepatitis E Diagnostic Tests Market Strategic Shifts & Innovations
Automation architectures and regulatory tightening are compressing assay development cycles while procurement patterns fragment across centralized and point-of-care deployment models.
Cartridge-based molecular diagnostics is automating sample-to-answer workflows previously requiring batch processing in centralized labs. European transplant centers are adopting these platforms for same-day pre-transplant screening. The technology is automating technician labor out of high-complexity testing, reducing per-test handling time and enabling 24-hour operational coverage.
EMA's In Vitro Diagnostic Regulation tightens clinical evidence thresholds for CE-marked hepatitis E assays, favoring manufacturers with established post-market surveillance infrastructure. The regulation forces retrospective data collection on sensitivity and specificity across diverse populations. Smaller assay developers without regulatory affairs scale are exiting the European market or pursuing notified body partnerships.
Bundled hepatitis panel pricing is displacing standalone assay procurement in diagnostic laboratories seeking operational simplicity. Reference networks in Germany and France now specify multi-pathogen chemiluminescence contracts that subsume hepatitis E within broader viral hepatitis menus. This concentration of purchasing power favors integrated platform suppliers over specialized ELISA manufacturers in Western European tenders.
Hepatitis E Diagnostic Tests Market Segmentation
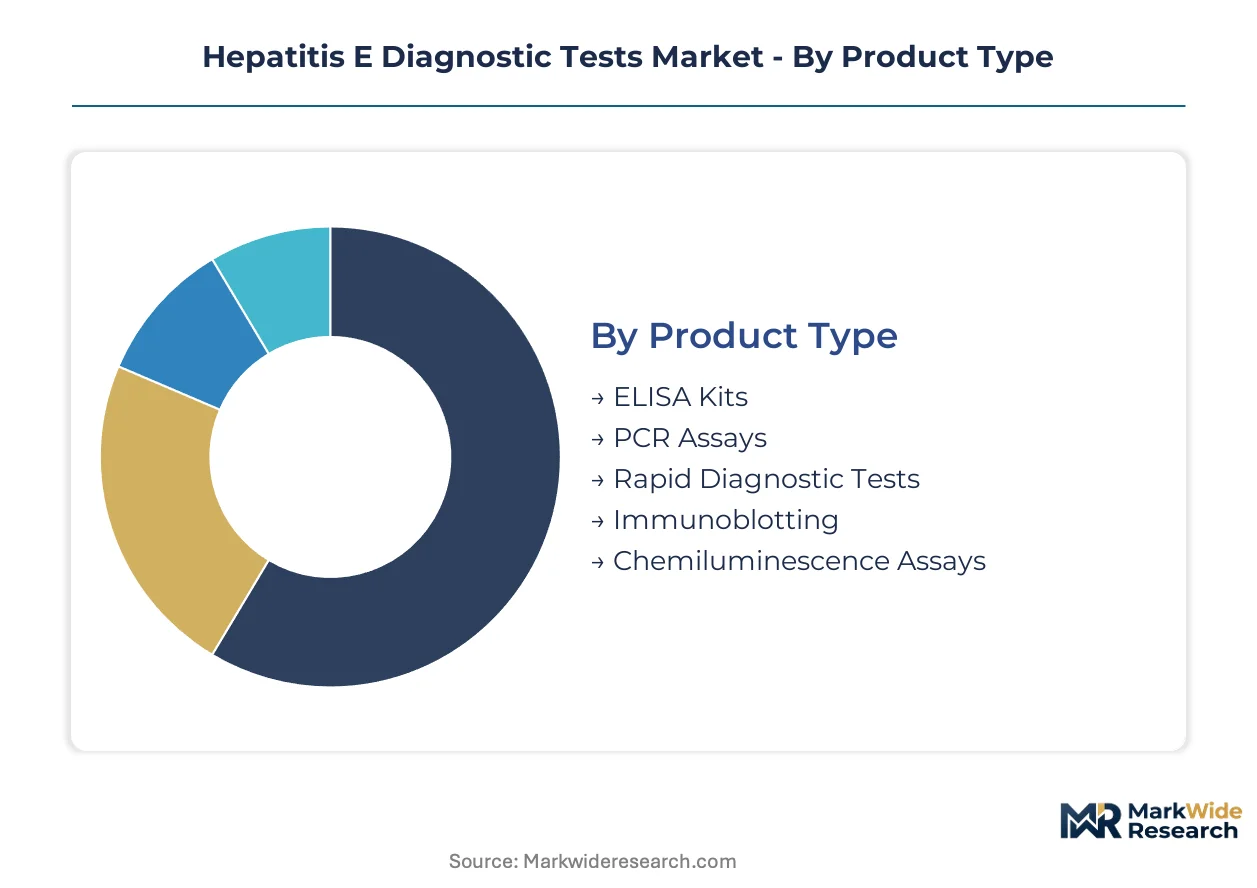
Segmentation in hepatitis E diagnostics reveals how regulatory pathways and procurement channels diverge across testing formats and institutional buyers. Manufacturers must align certification strategies with the specific compliance burdens each segment carries.
Product Type:
Certification requirements vary sharply across product types, with ELISA kits facing streamlined WHO prequalification while chemiluminescence assays navigate EMA's tightened clinical evidence standards.
- ELISA Kits:Enzyme-linked immunosorbent assays detect IgM and IgG antibodies through standardized colorimetric reactions with established sensitivity thresholds below 50 IU per milliliter. Demand concentrates in Indian public health networks where waterborne outbreak response prioritizes cost-efficient serological screening at district hospital laboratories.
- PCR Assays:Polymerase chain reaction platforms amplify viral RNA with analytical specificity exceeding serological methods, enabling acute infection confirmation in immunocompromised transplant candidates. European reference laboratories in Germany and France are displacing IgM protocols with same-day nucleic acid turnaround for pre-transplant screening.
- Rapid Diagnostic Tests:Lateral flow immunoassays deliver point-of-care results without laboratory infrastructure, serving mobile screening units in rural endemic zones.
- Immunoblotting:Western blot confirmation resolves serological indeterminacies through recombinant antigen line immunoassays, retaining niche utility in reference validation workflows.
- Chemiluminescence Assays:Automated light-emission detection integrates hepatitis E within multi-pathogen viral hepatitis panels, commanding premium positioning in high-throughput diagnostic networks.
ELISA Kits sit at the top of the volume ranking, with PCR Assays climbing the fastest.
Application:
Application segments separate by urgency and reimbursement tier, with transplant monitoring commanding premium pricing and surveillance programs operating on fixed public health budgets.
- Blood Screening:Plasma collection facilities in Southeast Asia mandate hepatitis E RNA detection to prevent transfusion-transmitted infections in immunosuppressed recipients, with nucleic acid testing displacing serological protocols in Thai and Vietnamese blood bank networks.
- Clinical Diagnosis:Acute hepatitis differentiation requires IgM serology for initial patient triage, sustained by outpatient laboratory networks across endemic regions where waterborne exposure drives symptomatic presentation.
- Surveillance Programs:Population-level seroprevalence studies deploy standardized ELISA protocols to map transmission geography and inform vaccination policy in high-burden districts.
- Organ Transplant Monitoring:Pre-transplant nucleic acid screening prevents donor-derived hepatitis E in solid organ and stem cell recipients, with European transplant centers mandating PCR-negative confirmation.
- Epidemiological Studies:Research cohorts require combined serological and molecular testing to characterize subclinical infection patterns and genotype distribution.
Blood Screening commands the deepest margin pools, while Organ Transplant Monitoring is gaining share fastest through nucleic acid platform adoption.
End User:
End user segmentation tracks procurement authority concentration, with public health agencies tendering on unit cost and diagnostic laboratories optimizing for workflow integration.
- Diagnostic Laboratories:Centralized testing networks in Germany and France bundle hepatitis E within automated viral hepatitis panels, favoring chemiluminescence platforms that consolidate multiple analytes on single instrumentation tracks.
- Blood Banks:Plasma fractionation facilities across Southeast Asia expand mandatory hepatitis E screening protocols, with nucleic acid testing contracts awarded to platform suppliers offering 24-hour operational coverage.
- Research Institutions:Academic medical centers source specialized immunoblotting and sequencing assays for genotype characterization and vaccine efficacy studies.
- Veterinary Clinics:Zoonotic transmission surveillance in swine and deer populations drives veterinary hepatitis E serology demand, particularly in agricultural regions with close human-animal contact.
- Public Health Agencies:India's national disease control programs tender large-volume ELISA contracts for outbreak response, with CDSCO domestic trial requirements favoring local recombinant antigen producers.
Diagnostic Laboratories anchor procurement volume, with Public Health Agencies expanding most quickly through endemic-country screening scale-up.
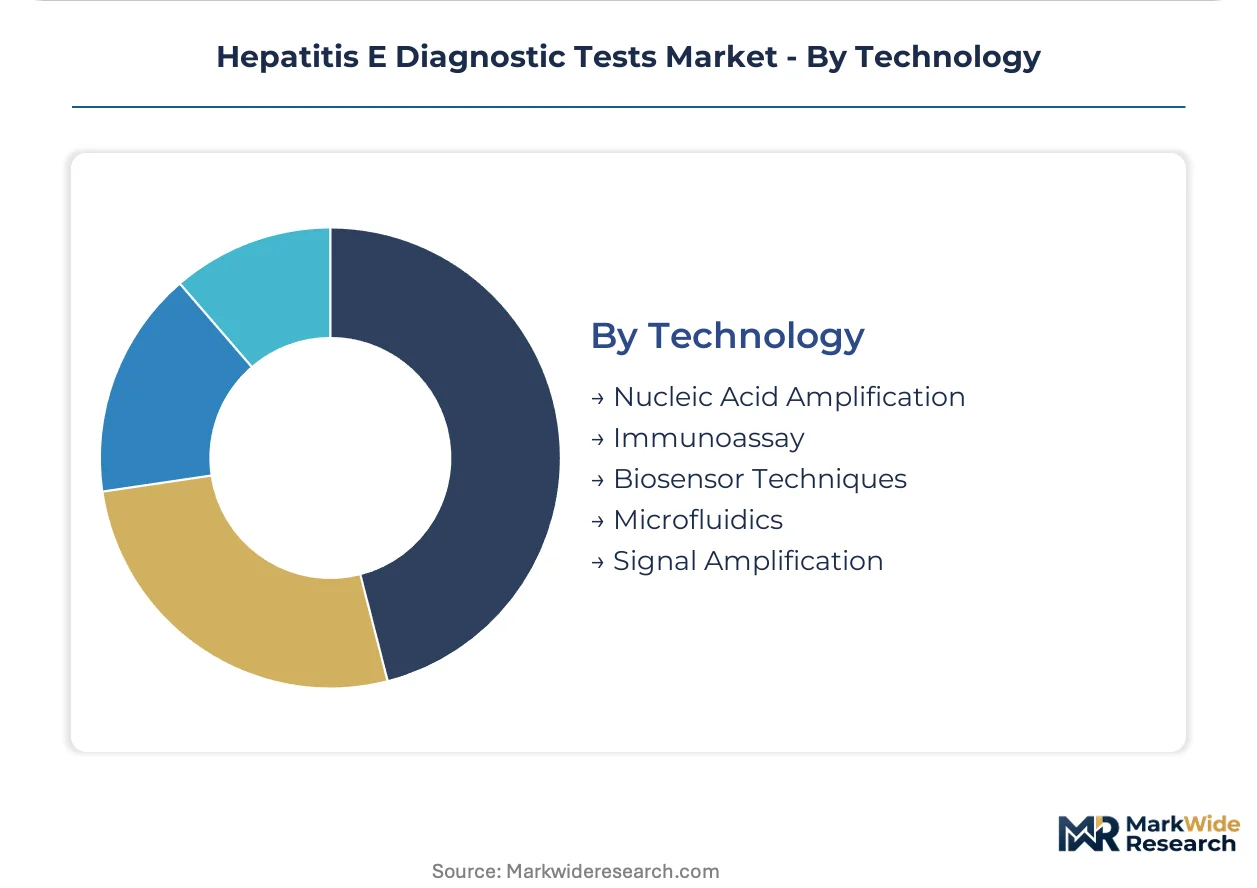
Technology:
Technology segments diverge by automation maturity, with nucleic acid amplification requiring complex thermal cycling infrastructure and biosensor platforms promising eventual point-of-care miniaturization.
- Nucleic Acid Amplification:Real-time PCR and isothermal amplification methods detect viral RNA with analytical sensitivity below 10 copies per milliliter, dominating European transplant center protocols where same-day turnaround prevents surgical delay.
- Immunoassay:Antibody-antigen binding reactions in ELISA and chemiluminescence formats retain the largest installed base through decades of protocol standardization and WHO prequalification pathway access.
- Biosensor Techniques:Electrochemical and optical transducers promise label-free detection with reduced reagent consumption, though clinical validation remains incomplete for hepatitis E-specific applications.
- Microfluidics:Lab-on-chip architectures automate sample preparation and detection in cartridge-based formats, enabling decentralized deployment without centralized laboratory infrastructure.
- Signal Amplification:Branched DNA and hybrid capture methods amplify detection signal without target amplification, offering alternative molecular approaches for resource-limited settings.
Immunoassay technology holds the dominant share, with Nucleic Acid Amplification showing the steepest expansion trajectory through transplant and blood bank adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as producers migrate toward jurisdictions with streamlined clinical trial pathways and localized antigen production incentives. Cost-of-compliance gaps between Western certification regimes and emerging-market fast-track programs now determine where recombinant enzyme supply chains concentrate.
India
Waterborne outbreak surveillance sustains procurement volume for IgM serology and RNA detection assays across national disease control networks. CDSCO mandates domestic clinical validation for imported diagnostic kits, creating regulatory friction that local recombinant antigen producers navigate more efficiently. Maharashtra and Gujarat house concentrated manufacturing clusters serving endemic-market tenders.
Germany
European reference laboratories in Berlin and Munich displace IgM protocols with same-day nucleic acid turnaround for pre-transplant screening. EMA's In Vitro Diagnostic Regulation tightens clinical evidence thresholds for CE-marked assays, extending compliance timelines. Bavaria anchors high-throughput diagnostic network procurement through integrated chemiluminescence platform contracts.
China
Assay manufacturers are decoupling from Western reagent supply chains, building independent enzyme and antibody production lines that reduce import dependency for ELISA substrate components. NMPA streamlined approval mechanisms accelerate domestic market entry for nucleic acid amplification platforms. Yangtze River Delta clusters concentrate cartridge-based molecular diagnostics production.
United States
FDA clearance pathways for serological devices shape product development priorities and market access timelines for manufacturers targeting transplant center networks. Blood screening protocols in academic medical centers drive demand for high-sensitivity RNA detection assays. Greater Boston and San Diego biotech corridors concentrate assay development operations.
France
ANSM oversight of post-market surveillance requirements favors manufacturers with established pharmacovigilance infrastructure for hepatitis E assays. Bundled hepatitis panel pricing in Île-de-France reference networks consolidates purchasing power around integrated platform suppliers. Paris-region diagnostic laboratories specify multi-pathogen chemiluminescence contracts subsuming hepatitis E within broader viral hepatitis menus.
Hepatitis E Diagnostic Tests Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue decentralized testing deployment and point-of-care miniaturization. The vendor base stratifies across three maturity levels: multinational diagnostics conglomerates with integrated automation platforms, regional specialists in recombinant antigen production, and niche innovators in cartridge-based molecular formats. Two dominant competitive moves define current positioning: strategic partnerships between platform suppliers and blood bank networks, plus backward integration into enzyme and substrate manufacturing to secure supply chain autonomy.
Among the multinational tier, Roche Diagnostics and Abbott Laboratories exemplify divergent platform strategies. Roche anchors high-throughput nucleic acid amplification contracts in European reference laboratories, while Abbott consolidates hepatitis E testing within broader viral hepatitis panels through chemiluminescence integration. Wantai Biological occupies a distinct position as a regional specialist, with cost advantages in public health procurement across endemic markets deriving from recombinant antigen production capabilities.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Abbott Laboratories |
| Siemens Healthineers |
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| QIAGEN |
| Danaher Corporation |
| Fujirebio |
| Wantai Biological |
| Others |
Cost & Logistics Intelligence
Public health procurement programs in endemic countries anchor hepatitis E diagnostic demand to volume-based tendering structures that compress unit margins while rewarding scale. Blood bank screening mandates across Southeast Asia and India's national disease control networks concentrate purchasing power among institutional buyers who negotiate multi-year supply contracts against standardized WHO prequalification benchmarks.
Pricing Analysis
Distributor margins in European reference laboratory channels absorb 15-25 percent of manufacturer net pricing before reaching end-user contracts. Pricing stratifies across premium, standard, and economy tiers based on automation integration level and EMA clinical evidence grade, with chemiluminescence platforms commanding premium positioning against ELISA alternatives. Cost compression in Indian public health tenders intensifies as domestic recombinant antigen producers undercut import-dependent competitors. Diagnostic laboratories exhibit lowest price sensitivity due to bundled panel procurement, while district hospitals in rural endemic zones operate on fixed per-test budgets that favor economy-tier rapid diagnostic formats.
Supply Chain Analysis
Enzyme and antibody substrate supply rests on Western specialty chemical manufacturers in Germany, Switzerland, and the United States, exposing Asian assay producers to logistics volatility and tariff exposure. Chinese manufacturers are building captive production of horseradish peroxidase and alkaline phosphatase conjugates to reduce import dependency, while Indian PLI scheme incentives accelerate domestic recombinant antigen fermentation capacity. Single-source vulnerability concentrates in high-purity substrate enzymes where patent-protected formulations limit qualified suppliers. Distribution runs through regional diagnostics distributors serving hospital networks and direct tenders to national disease control programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
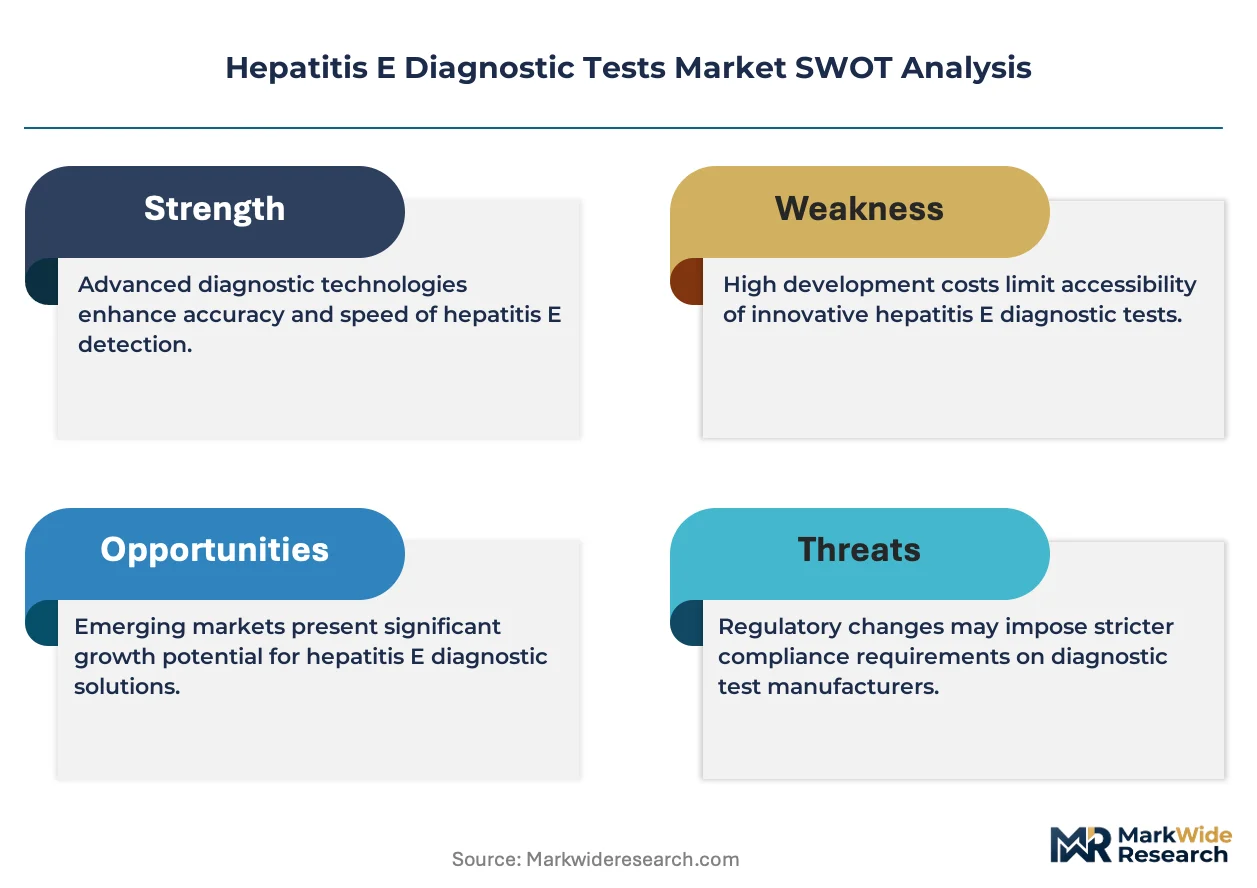
Hepatitis E diagnostic manufacturing is becoming a geographic-arbitrage play where EMA compliance costs in Europe run three to four times above CDSCO fast-track pathways in India for equivalent serological assay categories.
For Market Incumbents: Deploy backward integration into enzyme substrate manufacturing to neutralize supply chain vulnerability from Western chemical suppliers. Consolidate reference laboratory contracts through chemiluminescence platform bundling that displaces standalone ELISA competitors, while accelerating WHO prequalification dossiers to defend volume share in Indian public health tenders against emerging domestic recombinant antigen specialists. For New Entrants and Emerging Players: Launch via decentralized nucleic acid testing platforms targeting district hospitals and mobile screening units outside centralized laboratory procurement channels. Penetrate the organ transplant monitoring segment where same-day PCR turnaround commands premium pricing and incumbent platform integration lags, using cartridge-based sample-to-answer workflows that require minimal laboratory infrastructure. For Investors and Strategic Acquirers: Platform diagnostics conglomerates are the most active acquirer in this space, seeking recombinant antigen production capabilities and point-of-care molecular formats. Long-term viability hinges on regulatory pathway efficiency and supply chain autonomy rather than serology volume exposure. Watch WHO prequalification approval velocity for nucleic acid amplification platforms as the inflection signal for procurement pattern shift.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway Acceleration | Streamlined approval unlocks endemic-country procurement contracts in India and Southeast Asia. |
| Backward Integration into Enzyme Manufacturing | Captive substrate production insulates margins from Western chemical supply volatility. |
| Cartridge-Based Molecular Platform Launch | Sample-to-answer automation penetrates district hospitals outside centralized lab networks. |
| Chemiluminescence Panel Integration | Multi-pathogen bundling consolidates European reference laboratory purchasing power. |
| Domestic Clinical Trial Infrastructure | CDSCO-compliant validation capabilities accelerate market access for India tenders. |
Research Approach
Direct dialogue with regulatory affairs directors at IVD manufacturers, blood bank procurement managers across Thai and Vietnamese networks, and public health laboratory coordinators in Indian endemic districts grounded qualitative findings. Secondary validation drew from FDA 510(k) filings, WHO prequalification assessment reports, CDSCO import registration databases, and EMA In Vitro Diagnostic Regulation guidance documents. Bottom-up assay volume estimates triangulated against top-down disease burden projections from national hepatitis surveillance programs.
Segment-level demand outputs across product type, application, and end user dimensions were generated through structured modeling of procurement channel dynamics and technology substitution patterns over the projection horizon. CAGRs were derived from fitted adoption curves incorporating nucleic acid platform displacement rates in transplant centers and serology retention in outbreak response settings. Forecast inputs included blood bank screening mandate expansion timelines, PLI scheme incentive disbursement schedules, and EMA post-market surveillance compliance cost trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged WHO prequalification backlogs or sudden substrate enzyme supply disruptions. Projections reflect assumptions regarding regulatory pathway efficiency and technology adoption elasticity that may require revision if cartridge-based molecular platforms achieve breakthrough cost parity with ELISA formats. A small set of triggers—blood bank RNA screening mandate acceleration, CDSCO trial requirement relaxation, and Chinese enzyme substrate export restrictions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Cellular Health Screening Market
Diagnostics
Veterinary Chemistry Analyzers Market
Diagnostics
Blood Grouping Reagents Market
Diagnostics
Respiratory Pathogen Testing Kits Market
Diagnostics
Singleplex Immunoassay Market
Diagnostics
Cancer IVD Market
Diagnostics
Global Comprehensive Metabolic Panel Market
Diagnostics
Global Fecal Occult Blood Tests Market
Diagnostics
Thrombosis and Hemostasis Biomarkers Market
Diagnostics
Food Allergy Diagnostics and Therapeutics Market
Diagnostics
Non-Alcoholic Steatohepatitis (NASH) Biomarkers Market
Diagnostics
Anatomic Pathology Market
Diagnostics
Direct Fluorescent Antibody Test Kits Market
Diagnostics
LDL Test Market
Diagnostics
Lipid Panel Test Market
Diagnostics
Paper Based Diagnostic Test Kits Market