
 Glucose Biosensors Market | 2026-2036
Glucose Biosensors Market Size, Share, and Industry Trends Forecast 2026-2036
Glucose Biosensors Market Analysis
A capital-intensity divergence between players is bifurcating competitive tiers in glucose biosensors. Abbott Laboratories leverages vertically integrated sensor manufacturing to sustain cost advantages at scale. Dexcom Inc. anchors its position through proprietary algorithm development for real-time glucose prediction. F. Hoffmann-La Roche Ltd. competes across multiple technology platforms while maintaining diagnostic laboratory channel control.
Glucose biosensors are electrochemical or optical transducer systems that enzymatically detect blood glucose concentration through glucose oxidase-mediated electron transfer, typically operating within a 20-600 mg/dL measurement range for clinical or consumer metabolic monitoring. Continuous glucose monitoring systems lead technology deployment due to recurring sensor revenue models and superior glycemic visibility, while electrochemical platforms dominate manufacturing volume owing to mature screen-printing processes and established supply chains. Optical and nanomaterial-based approaches represent faster-growing segments where margin pools concentrate around patent-protected photonic interfaces and graphene-enhanced electrode architectures.
FDA premarket notification requirements and the EU Medical Device Regulation shape product development cycles, with FDA 510(k) pathways for moderate-risk devices and MDR Class IIa classification dictating clinical evidence thresholds for European market access. ISO 15197 accuracy standards for blood glucose monitoring systems further constrain design specifications and inter-laboratory variability tolerances. Stakeholders must monitor evolving reimbursement classifications for non-invasive platforms as payor evidence requirements increasingly determine commercial viability ahead of technical feasibility milestones.
Market Dynamics
Reimbursement policy divergence between national health systems is fragmenting market access pathways and forcing manufacturers to maintain parallel commercial strategies for each major territory.
Growth Catalysts
- EU MDR Class IIa streamlining:The European Medical Device Regulation's consolidated clinical evidence requirements for moderate-risk glucose monitors are compressing time-to-market for compliant manufacturers relative to legacy MDD processes.
- Home care metabolic monitoring:Patient demand for real-time glycemic visibility outside clinical settings is expanding addressable volume beyond traditional diabetes management populations into prediabetes and wellness segments.
- Germany's statutory reimbursement expansion:The G-BA's broadened coverage criteria for continuous glucose monitoring systems is removing out-of-pocket barriers and accelerating penetration among Type 2 diabetes populations previously excluded from full subsidy.
Market Restraints
- Platinum-group metal electrode costs:Electrochemical sensor fabrication relies on palladium and ruthenium catalyst layers, exposing gross margins to commodity volatility concentrated in South African and Russian supply corridors.
- FDA 510(k) predicate device dependency:Substantial equivalence pathways for next-generation optical platforms face predicate scarcity, forcing innovators toward lengthier De Novo classifications that extend capital lockup periods.
- Enzymatic sensor calibration drift:Glucose oxidase degradation over sensor wear duration creates accuracy decay that limits usable lifespan and compresses per-patient revenue capture relative to theoretical device potential.
Strategic Opportunities
- India's CDSCO fast-track pathway:The country's abbreviated review track for in-vitro diagnostics with established predicate approvals in regulated markets offers accelerated entry into a diabetes population exceeding seventy million diagnosed cases.
- Photonic-nanomaterial convergence:Integration of graphene field-effect transistor architectures with near-infrared spectroscopy is enabling calibration-free optical platforms that eliminate enzymatic consumables entirely.
- Pharmacy-direct distribution in Brazil:ANVISA's relaxed point-of-sale restrictions for Class II glucose monitors permits bypass of hospital procurement committees and capture of chronic patient refill loyalty through retail pharmacy networks.
Industry Challenges
- Biocompatibility certification timelines:ISO 10993 cytotoxicity and sensitization testing for novel adhesive and membrane materials extends development schedules by twelve to eighteen months for platform refreshes.
- Algorithm validation workforce scarcity:Machine learning glucose prediction models require specialized clinical data science talent that concentrates in Boston, Basel, and Tel Aviv clusters, inflating compensation premiums for distributed development teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glucose Biosensors Market |
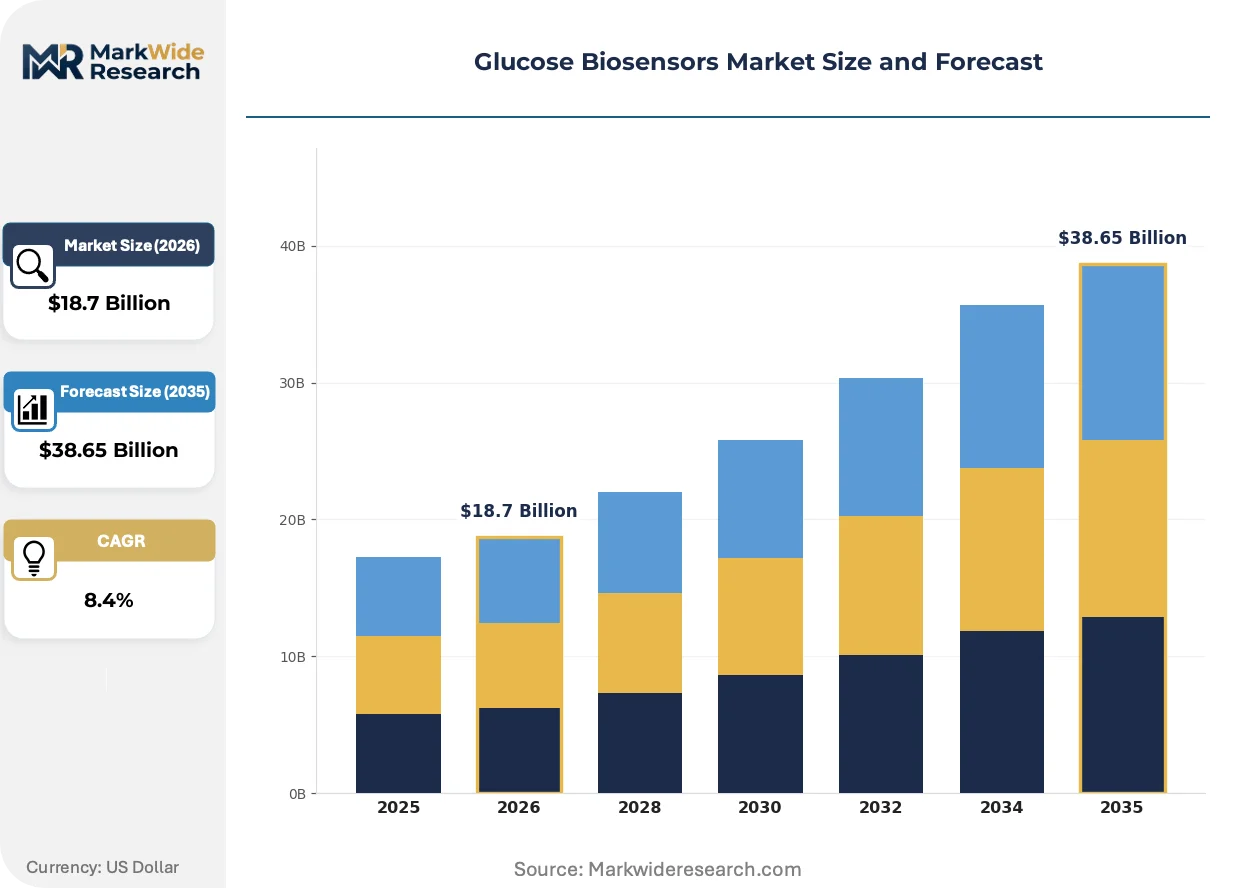
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Sensors, Continuous Glucose Monitoring, Implantable Devices, Handheld Meters Technology: Electrochemical, Optical, Nanomaterial-Based, Gravitational End User: Hospitals, Home Care, Diagnostic Laboratories, Research Institutions Application: Diabetes Management, Clinical Research, Fitness Tracking, Health Monitoring |
| Companies Covered | Abbott Laboratories, Dexcom Inc., F. Hoffmann-La Roche Ltd., Ascensia Diabetes Care Holdings AG, Medtronic plc, Sanofi, LifeScan IP Holdings, Nova Diabetes Care, Trividia Health, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glucose Biosensors Market Emerging Trajectories
Manufacturing process innovation and regulatory science evolution are compressing product lifecycles while expanding the addressable patient population beyond traditional diagnostic thresholds.
Optical glucose sensing is bifurcating competitive positioning between established electrochemical incumbents and photonics entrants. Raman spectroscopy and photoacoustic approaches are attracting venture funding from diabetes technology specialists seeking non-invasive alternatives. This technology divergence is forcing legacy manufacturers to defend installed base through software ecosystem lock-in rather than sensor hardware superiority alone.
FDA's emerging guidance on artificial intelligence-enabled medical devices is reshaping predicate requirements for algorithm-driven glucose prediction systems. The agency's predetermined change control plans permit post-market algorithm updates without fresh 510(k) submissions, reducing validation burden for adaptive machine learning models. Continuous glucose monitoring vendors with substantial real-world evidence repositories are restructuring regulatory affairs teams to exploit this pathway.
Patient data ownership preferences are disrupting traditional device-manufacturer-physician relationships. Individuals managing diabetes through consumer wearables increasingly demand direct API access to raw glucose streams for integration with third-party nutrition and exercise applications. This behavioral shift concentrates in Germany and the Netherlands, where GDPR enforcement has normalized personal data portability expectations and eroded proprietary platform exclusivity.
Glucose Biosensors Market Segmentation
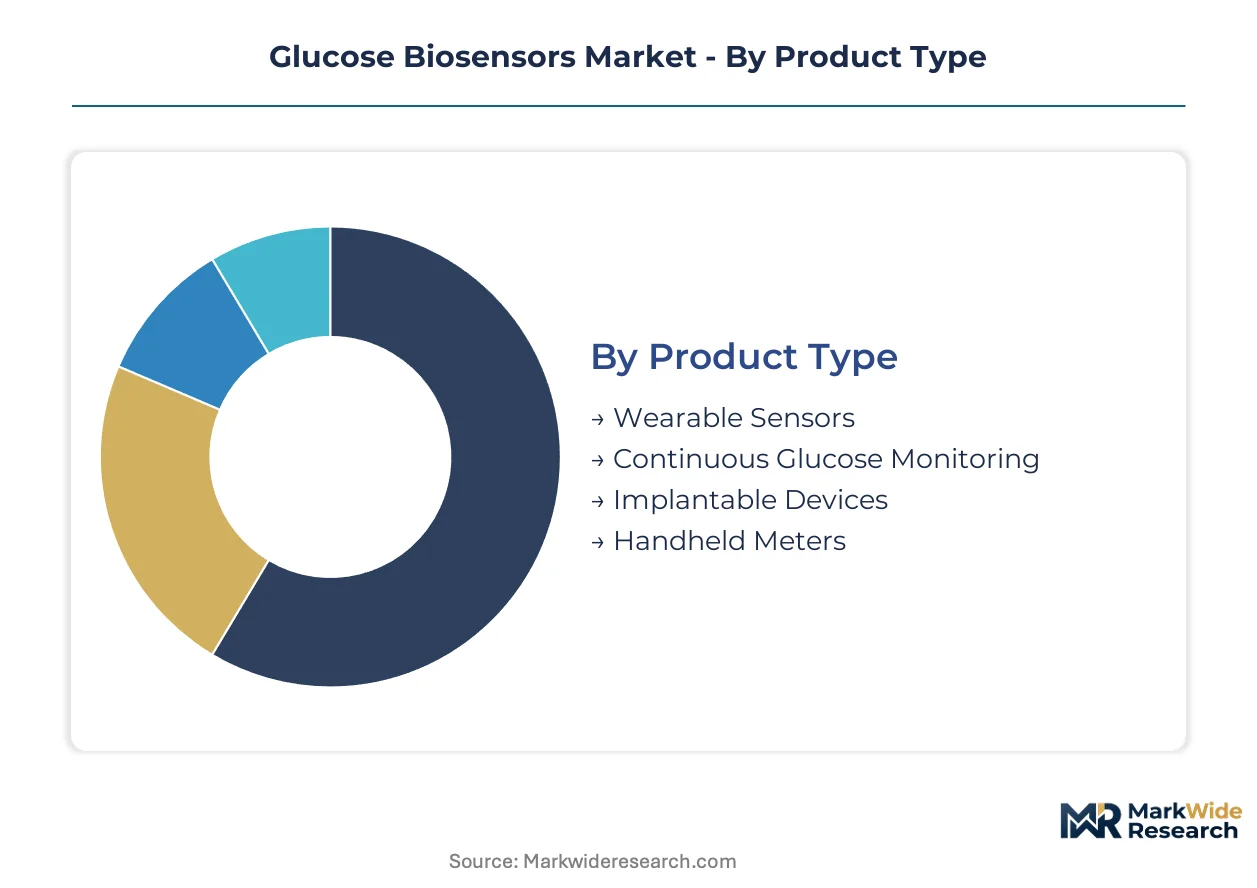
Glucose biosensor manufacturers face divergent channel economics across product architectures. Technology choices determine reimbursement pathways, while end-user settings dictate calibration requirements and regulatory classification burdens.
Product Type:
Wearable sensors and continuous systems flow through pharmacy and durable medical equipment channels, whereas handheld meters concentrate in retail and hospital procurement.
- Continuous Glucose Monitoring:Subcutaneous sensor-transmitter systems generate recurring revenue through disposable sensor replacements. Demand concentrates in Germany and the United States where statutory reimbursement removes patient cost barriers for Type 1 and insulin-dependent Type 2 populations.
- Wearable Sensors:Non-invasive optical patches and microneedle arrays target wellness and prediabetes segments outside traditional diagnostic thresholds. Fitness integrators and employer wellness programs in the Netherlands and California are piloting subscription models for metabolic visibility.
- Implantable Devices:Long-term intradermal sensors require surgical placement and specialist follow-up, limiting addressable volume to severe glycemic variability cases.
- Handheld Meters:Strip-based electrochemical devices dominate emerging market volume through low unit costs and minimal training requirements.
By volume, Handheld Meters leads. By growth pace, Continuous Glucose Monitoring is ahead.
Technology:
Cost tiers separate mature electrochemical manufacturing from premium optical and nanomaterial platforms still seeking scale economies.
- Electrochemical:Glucose oxidase-mediated electron transfer through screen-printed electrodes remains the manufacturing volume leader. Mature supply chains in South Korea and Ireland constrain cost reduction potential as platinum-group metal prices fluctuate.
- Optical:Near-infrared spectroscopy and Raman approaches eliminate enzymatic consumables entirely. FDA De Novo pathways and MDR Class IIa clinical evidence requirements are compressing development timelines for compliant photonics entrants.
- Nanomaterial-Based:Graphene field-effect transistors and quantum dot architectures enable calibration-free operation. Research institutions in Tel Aviv and Boston are validating biocompatibility profiles for adhesive integration.
- Gravitational:Microfluidic density-based measurement remains experimental, with no commercial scale deployment.
Electrochemical platforms capture the widest installed base. Optical approaches are expanding most quickly as predicate device scarcity forces regulatory innovation.
End User:
Application settings determine accuracy requirements and calibration protocols, with home care demanding simplicity and hospitals requiring integration with electronic health records.
- Home Care:Patient-operated devices with smartphone connectivity dominate addressable volume expansion. Germany's G-BA reimbursement expansion and United States Medicare coverage for therapeutic CGM are removing out-of-pocket barriers for chronic populations.
- Hospitals:Point-of-care systems require CLIA-waived or moderate-complexity certification. Inpatient glycemic control protocols in academic medical centers are driving demand for integrated insulin dosing algorithms.
- Diagnostic Laboratories:Centralized reference analyzers process venous samples with highest accuracy specifications for HbA1c correlation studies.
- Research Institutions:Closed-loop artificial pancreas trials and nutrition metabolism studies require raw data API access and custom calibration protocols.
Home Care leads by patient touchpoint volume. Research Institutions show the steepest expansion trajectory as real-world evidence requirements intensify for regulatory submissions.
Application:
Customer type stratification separates reimbursed diabetes management from direct-pay wellness and clinical trial instrumentation.
- Diabetes Management:FDA-cleared and CE-marked devices for insulin dosing decisions carry the highest accuracy standards and liability exposure. Reimbursement codes in Germany, France, and Japan determine commercial viability ahead of technical performance.
- Clinical Research:Investigational device exemption pathways and ISO 14155 compliance enable pharma-sponsored trials. Contract research organizations in Singapore and Switzerland are consolidating procurement for multinational metabolism studies.
- Fitness Tracking:General wellness devices escape medical device classification in the United States but face MDR uncertainty in Europe for metabolic claims.
- Health Monitoring:Employer and payor population health programs are piloting CGM for prediabetes progression prevention.
Diabetes Management commands the largest revenue pool. Fitness Tracking is gaining share fastest as consumer wearables encroach on traditional diagnostic boundaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's statutory reimbursement environment while cost-sensitive volume accumulates in India's pharmacy-direct channels. This asymmetry forces manufacturers to maintain parallel product architectures and pricing strategies across territories.
United States
Medicare therapeutic CGM coverage and employer wellness subsidies drive demand expansion beyond Type 1 populations. FDA De Novo pathways for optical platforms compress development timelines for photonics entrants. Boston and San Diego clusters concentrate algorithm validation talent for machine learning glucose prediction models.
Germany
G-BA reimbursement expansion removes out-of-pocket barriers for insulin-dependent Type 2 patients previously excluded from full subsidy. EU MDR Class IIa streamlining accelerates time-to-market for compliant glucose monitors relative to legacy MDD processes. Baden-Württemberg manufacturing corridors host vertically integrated sensor fabrication facilities serving European distribution networks.
India
Seventy million diagnosed diabetes cases create volume opportunity in pharmacy-direct channels bypassing hospital procurement. CDSCO fast-track pathways for IVDs with established predicate approvals in regulated markets offer accelerated market entry. Maharashtra and Gujarat industrial zones concentrate electrochemical strip manufacturing for export to Middle East and African markets.
Brazil
ANVISA relaxed point-of-sale restrictions for Class II glucose monitors enable retail pharmacy network capture of chronic patient refill loyalty. Employer wellness programs and private payor expansion drive CGM penetration among affluent urban populations. São Paulo state anchors distribution infrastructure serving Mercosur regional markets.
Japan
PMDA regulatory harmonization with FDA standards reduces duplicate clinical evidence requirements for multinational manufacturers. Aging demographics and prediabetes screening programs expand addressable population beyond traditional diagnostic thresholds. Kanto region concentration of precision manufacturing supports miniaturized sensor component supply chains.
Glucose Biosensors Market Vendor Landscape
Concentration sits with diversified medtech conglomerates and glucose-specialized platform developers. Tier-one players sustain advantage through proprietary algorithm ecosystems and vertically integrated sensor manufacturing. Mid-tier competitors differentiate through regional regulatory expertise and pharmacy-direct distribution relationships. Dominant competitive moves include strategic partnerships for photonic-nanomaterial convergence and geographic expansion into India's abbreviated approval pathways.
Among diversified healthcare conglomerates, Abbott Laboratories and F. Hoffmann-La Roche Ltd. exemplify multi-platform portfolios spanning electrochemical, optical, and laboratory diagnostic channels. Dexcom Inc. occupies a specialized position within continuous glucose monitoring, anchoring real-time algorithm development for predictive glycemic analytics. These three entities represent divergent strategic archetypes: vertical integration at scale, multi-technology diversification, and focused platform specialization.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Dexcom Inc. |
| F. Hoffmann-La Roche Ltd. |
| Ascensia Diabetes Care Holdings AG |
| Medtronic plc |
| Sanofi |
| LifeScan IP Holdings |
| Nova Diabetes Care |
| Trividia Health, Inc. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts for platinum-group metals lock in sensor fabrication costs and shield electrochemical manufacturers from South African supply volatility while constraining margin flexibility for optical platform entrants. Subscription-based CGM pricing in Germany and the United States anchors recurring revenue visibility, yet enzymatic consumable dependencies tether gross margins to palladium and ruthenium commodity curves.
Pricing Analysis
The customization-premium spread separates configured-to-order continuous monitoring systems from standard handheld meters. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA clearance tier and calibration protocol complexity, with ISO 15197-certified hospital-grade devices commanding substantial premiums over CLIA-waived retail units. Cost compression in economy electrochemical strips intensifies as Indian and Chinese manufacturers scale screen-printing capacity. Pharmacy-direct channels in Brazil and India exhibit highest price sensitivity, while German statutory reimbursement insulates premium CGM segments from out-of-pocket elasticity.
Supply Chain Analysis
South Korea and Ireland anchor electrochemical electrode fabrication through mature roll-to-roll screen-printing infrastructure serving Abbott and Roche manufacturing networks. Sensor production draws from South African palladium mines, Irish adhesive membrane suppliers, and Taiwanese semiconductor foundries for transmitter ASICs. Single-source vulnerability concentrates in platinum-group metal catalyst layers exposed to export restriction risk. Distribution runs through pharmacy networks in Europe and Latin America, hospital procurement committees in Japan, and durable medical equipment suppliers in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Glucose biosensors occupy an early-cycle expansion phase as home care metabolic monitoring penetrates prediabetes and wellness populations beyond traditional diabetes management. Germany's G-BA reimbursement expansion and United States Medicare therapeutic CGM coverage accelerate addressable market widening.
For Market Incumbents: Secure algorithm ecosystem lock-in through API access restrictions and proprietary glucose prediction models that raise switching costs for existing CGM subscribers. Invest in backward integration into platinum-group metal recycling to offset commodity volatility in electrochemical sensor fabrication. Defend against photonic-nanomaterial convergence threats by accelerating FDA De Novo submissions for calibration-free optical platforms. For New Entrants and Emerging Players: India's CDSCO fast-track pathway for IVDs with established predicate approvals offers accelerated entry into seventy million diagnosed diabetes cases with abbreviated clinical evidence requirements. Target pharmacy-direct distribution in Maharashtra and Gujarat industrial corridors bypassing hospital procurement committees. Pursue wellness segment white-space through non-invasive optical patches for employer metabolic screening programs in California and the Netherlands. For Investors and Strategic Acquirers: Capital is best deployed toward algorithm-specialist platforms with substantial real-world evidence repositories capable of exploiting FDA predetermined change control plans for post-market machine learning updates. Long-term viability centers on photonic-nanomaterial convergence plays eliminating enzymatic consumables entirely. Monitor FDA guidance publication on AI-enabled medical devices as inflection indicator for regulatory pathway accessibility.| Strategic Initiative | Industry Significance |
|---|---|
| FDA De Novo Submission | Accelerates market entry for optical platforms facing predicate device scarcity in 510(k) pathways. |
| CE Marking Pathway | EU MDR Class IIa streamlining compresses clinical evidence timelines relative to legacy MDD processes. |
| Hospital System Partnership | Academic medical center integration secures inpatient glycemic control protocol adoption and insulin dosing algorithm validation. |
| Software Companion Development | Smartphone connectivity and third-party nutrition app API access respond to GDPR-driven patient data portability demands. |
| Reimbursement Strategy | G-BA statutory coverage expansion in Germany removes out-of-pocket barriers for Type 2 insulin-dependent populations. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs leads at continuous glucose monitoring developers. Secondary validation incorporated FDA 510(k) and De Novo submission databases, EMA MDR compliance filings, CMS Medicare reimbursement code updates, and ISO 15197 inter-laboratory variability studies. Bottom-up patient population modeling triangulated against top-down manufacturer revenue segmentation across technology platforms and end-user settings.
Across the analysis window, forecast outputs reflect disaggregated modeling by product architecture, technology platform, end-user setting, and application type. CAGRs were derived from logistic diffusion curves calibrated to reimbursement policy implementation timelines and regulatory approval pathway velocity. Industry-specific inputs incorporated glucose oxidase degradation curves affecting sensor replacement frequency, platinum-group metal price volatility indices, and real-world evidence repository scale for algorithm validation workforce assessment.
Decision-makers should treat outputs as directional under base assumptions of stable FDA and EU MDR regulatory frameworks, continued G-BA reimbursement generosity, and absence of disruptive non-invasive optical platform commercialization; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
In-Vitro Diagnostics (IVD) Packaging Market
Diagnostics
DNA Probes - Based Diagnostics Market
Diagnostics
Immunoassay Interference Blocker Market
Diagnostics
Malaria Diagnostics Market
Diagnostics
In Vitro Diagnostic Substrate Market
Diagnostics
Population Screening Market
Diagnostics
Fructosamine Test Market
Diagnostics
Anatomic Pathology Market
Diagnostics
Complement C3 ELISA Kits Market
Diagnostics
Gastrointestinal Diagnostics Market
Diagnostics
South Korea in Vitro Diagnostics Market
Diagnostics
Global Diagnostic Radiopharmaceuticals and Contrast Media Market
Diagnostics
FISH Probe Market
Diagnostics
Melioidosis Diagnostic Market
Diagnostics
BNP and NT-Probnp Market
Diagnostics
Human Immunodeficiency Virus Rapid Test Kit Market