
 Global Meningitis Diagnostic Testing Market | 2026-2036
Global Meningitis Diagnostic Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Meningitis Diagnostic Testing Market Foresight
Asset-light leasing models for multiplex molecular diagnostic platforms is rewriting competitive entry barriers for mid-sized laboratories. Thermo Fisher Scientific leverages its installed base of real-time PCR instrumentation to sustain service revenue streams across academic hospital networks. BioFire Diagnostics anchors its position through integrated film array technology that reduces technician training burdens in high-volume settings. Abbott Laboratories competes via portable instrument footprints designed for rapid deployment in field testing centers with limited infrastructure.
Meningitis diagnostic testing encompasses laboratory and near-patient methods that detect bacterial, viral, fungal, or chemical agents in cerebrospinal fluid, blood, or serum specimens through nucleic acid amplification, immunoassay, or culture-based techniques. Polymerase Chain Reaction dominates value generation due to superior analytical sensitivity for partially treated infections where culture yields false negatives. Enzyme Immunoassay occupies stable demand in resource-constrained settings where cold chain requirements for molecular reagents present logistical barriers. Point-of-Care Testing represents the fastest-expanding deployment mode as decentralized diagnostic networks reduce time-to-treatment intervals for acute meningococcal cases.
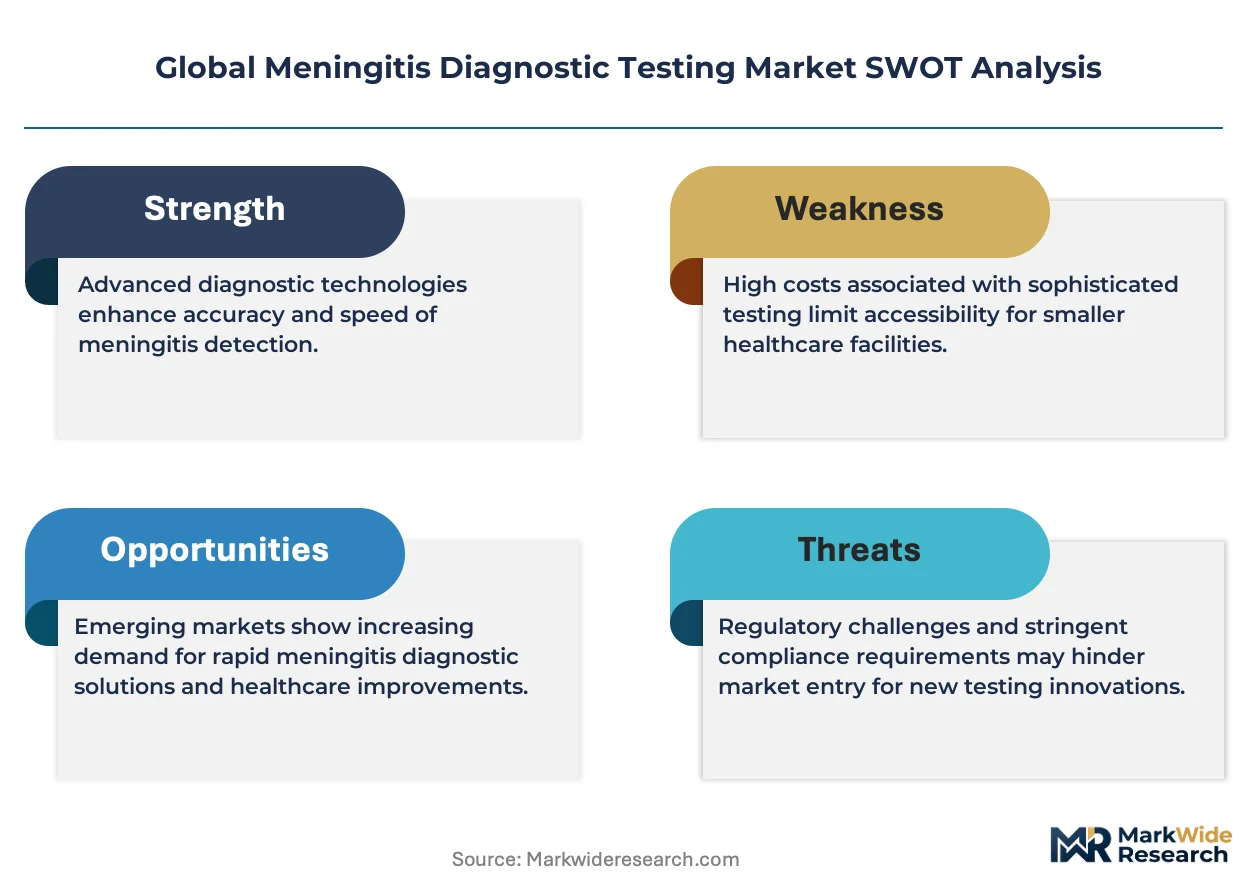
The FDA's 510(k) clearance pathway and the EMA's In Vitro Diagnostic Regulation shape product development priorities by mandating clinical validation standards that favor well-capitalized registrants. WHO prequalification and ISO 13485 quality management requirements further filter market access for manufacturers targeting procurement contracts through international health agencies. Stakeholders must monitor evolving antimicrobial stewardship mandates that tie diagnostic reimbursement to rapid pathogen identification and resistance profiling capabilities.
Market Dynamics
Multiplex PCR platform deployment is compressing diagnostic turnaround times from 48 hours to under two hours, forcing laboratories to restructure staffing models and capital allocation around molecular triage workflows.
Growth Catalysts
- Antimicrobial Stewardship Mandates:Hospital networks in Germany now tie diagnostic reimbursement to rapid pathogen identification, accelerating molecular platform procurement in tertiary care centers.
- WHO Prequalification Pathway:The streamlined IVD registration process is reducing product entry timelines for multiplex meningitis panels targeting procurement contracts through international health agencies.
- CSF Sample Volume Concentration:Centralized laboratory infrastructure across India, Brazil, and Nigeria is consolidating testing demand into high-throughput hubs capable of processing 500-plus specimens daily.
Market Restraints
- Cold Chain Logistics Burden:Molecular reagents requiring continuous refrigeration impose distribution costs that exclude peripheral clinics in regions with unreliable electricity infrastructure.
- Technical Skill Stratification:Film array and real-time PCR platforms demand technicians with nucleic acid extraction competencies that remain scarce in resource-constrained settings.
- Reimbursement Compression:Payer consolidation in the United States is narrowing coverage differentials between rapid molecular methods and conventional culture-based testing.
Strategic Opportunities
- Point-of-Care Network Penetration:Decentralized testing deployment in Nigerian field centers addresses acute meningococcal triage gaps where centralized laboratory access exceeds four-hour transport windows.
- Integrated Resistance Profiling:Convergent platforms combining pathogen identification with antimicrobial susceptibility reporting command procurement preference under FDA 510(k) and EMA MDR pathways.
- Leasing Model Expansion:Asset-light instrument financing is lowering entry barriers for mid-sized Brazilian laboratories previously excluded from multiplex molecular capacity.
Industry Challenges
- ISO 13485 Certification Timelines:Quality management system audits for meningitis IVD manufacturers average 18 months, delaying market entry for novel platform developers.
- Legacy System Integration:Hospital laboratory information systems in Japan require custom middleware development to interface with new molecular diagnostic data outputs.
- Specimen Transport Standardization:Variable CSF collection and stabilization protocols across clinical sites degrade nucleic acid integrity and invalidate molecular sensitivity claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Meningitis Diagnostic Testing Market |
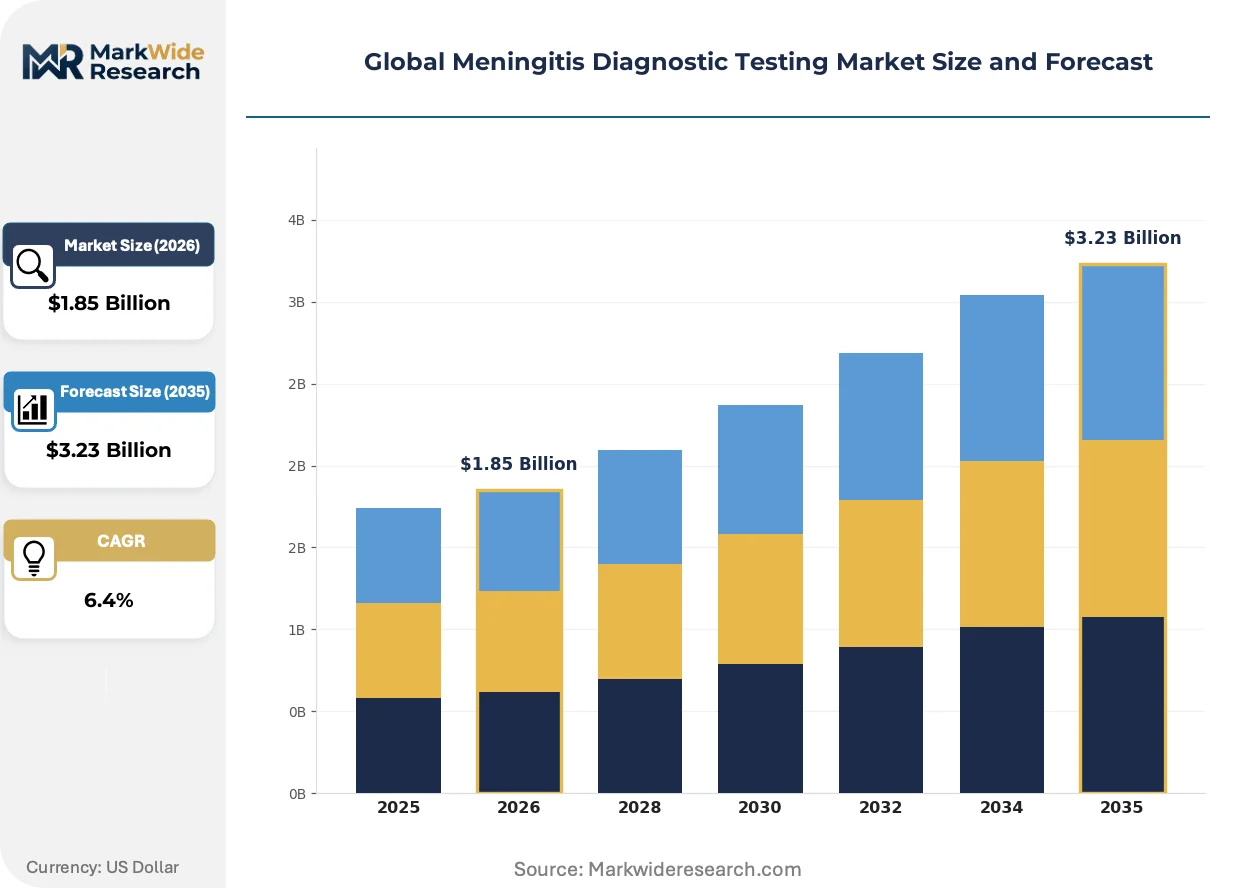
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymerase Chain Reaction, Enzyme Immunoassay, Culture Tests, Antigen Detection, Serology Application: Bacterial Meningitis, Viral Meningitis, Fungal Meningitis, Parasitic Meningitis, Chemical Meningitis End User: Diagnostic Laboratories, Research Institutes, Academic Hospitals, Reference Laboratories, Specialty Clinics Deployment: Point-of-Care Testing, Centralized Laboratories, Mobile Testing Units, Hospital-Based Laboratories, Field Testing Centers |
| Companies Covered | BioFire Diagnostics, Thermo Fisher Scientific, Bio-Rad Laboratories, Abbott Laboratories, Seegene, Siemens Healthineers, Luminex Corporation, IMMY, Becton, Dickinson and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Meningitis Diagnostic Testing Market Shifts & Advancements
Cloud-connected diagnostic instrumentation is restructuring how laboratories manage quality control, remote calibration, and predictive maintenance across distributed testing networks.
Cartridge-based molecular systems is digitizing result interpretation through automated algorithmic analysis that eliminates subjective band-reading errors. Academic hospital networks in the United States are adopting these platforms at replacement-cycle pace as existing thermal cyclers reach end-of-life. This shift is compressing technician training duration from six months to two weeks while centralizing troubleshooting support through manufacturer-hosted digital infrastructure.
EMA's In Vitro Diagnostic Regulation is mandating clinical performance studies with defined sensitivity thresholds for meningitis pathogen detection. Manufacturers must now submit prospective validation data from European reference laboratories rather than retrospective analytical studies. Multiplex PCR panel developers targeting the EU market are restructuring regulatory timelines to accommodate expanded clinical trial requirements before CE marking authorization.
Consolidated procurement through group purchasing organizations is displacing individual laboratory purchasing autonomy in tertiary care networks. Hospital systems in Germany and Japan now negotiate three-year exclusive supply agreements covering instruments, reagents, and service contracts as bundled offerings. This concentration is most visible in metropolitan academic medical centers where procurement committees prioritize total cost-of-ownership metrics over upfront capital expenditure minimization.
Global Meningitis Diagnostic Testing Market Segmentation
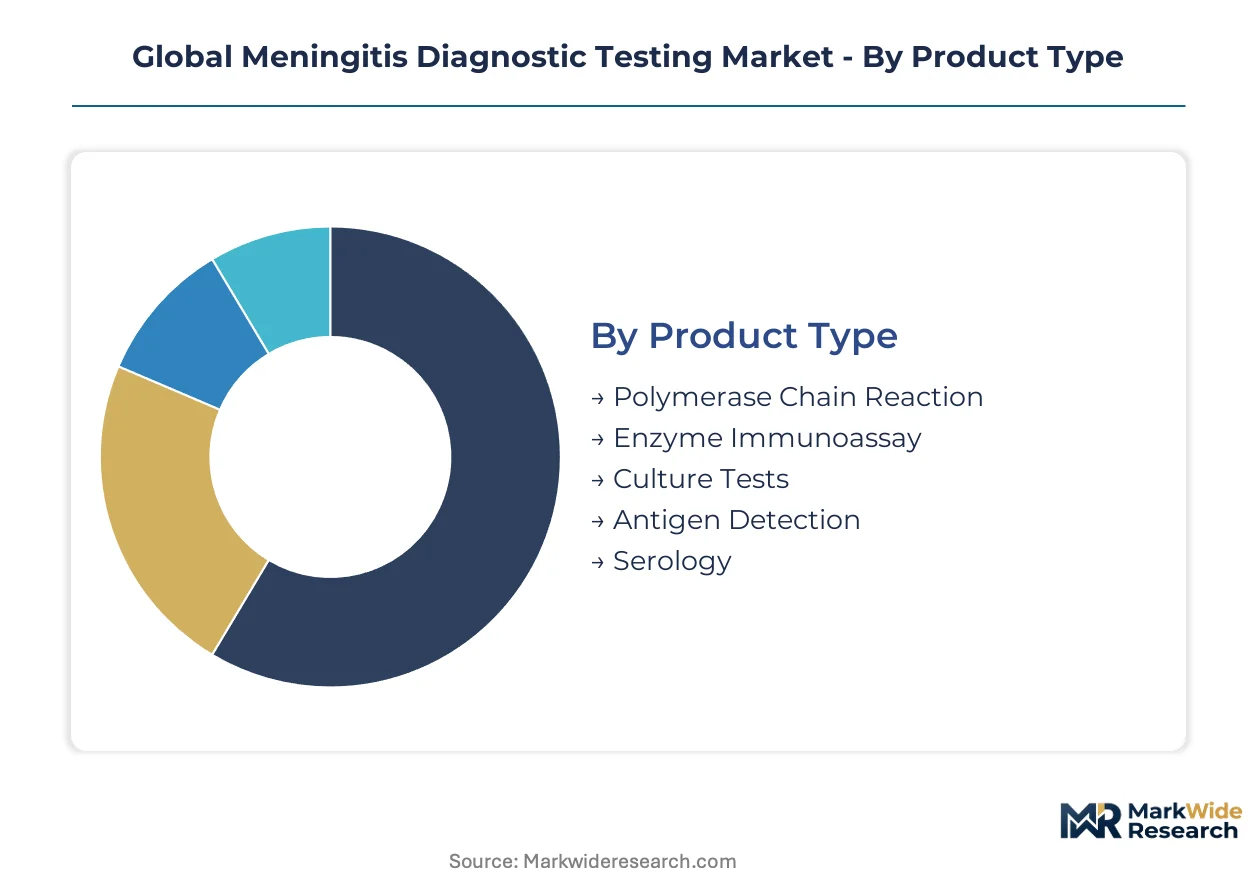
Diagnostic modality selection in meningitis testing hinges on specimen quality, treatment history, and infrastructure availability. Product differentiation across molecular, immunological, and culture-based platforms creates distinct competitive arenas with divergent margin profiles and regulatory pathways.
Product Type:
Cost tier stratification separates premium molecular platforms from conventional immunoassay and culture alternatives.
- Polymerase Chain Reaction:Nucleic acid amplification detects bacterial and viral pathogens in cerebrospinal fluid with analytical sensitivity exceeding 95% for partially treated infections. Academic hospitals in Germany and the United States concentrate procurement for multiplex real-time PCR platforms where rapid pathogen identification directly influences empiric therapy decisions.
- Enzyme Immunoassay:Antibody-antigen binding assays detect capsular polysaccharides from Neisseria meningitidis, Streptococcus pneumoniae, and Haemophilus influenzae type b without thermal cycling infrastructure. Demand clusters in Nigerian and Indian peripheral clinics where cold chain logistics for molecular reagents remain unreliable.
- Culture Tests:Gold-standard bacteriological isolation enables antimicrobial susceptibility profiling.
- Antigen Detection:Latex agglutination and immunochromatographic lateral flow devices deliver rapid results.
- Serology:Antibody titer measurement supports retrospective diagnosis and epidemiological surveillance.
Polymerase Chain Reaction holds installed capacity. Enzyme Immunoassay is rotating up the share rankings.
Application:
Clinical presentation drives testing volume distribution across infectious and non-infectious etiologies.
- Bacterial Meningitis:Acute pyogenic infection demands rapid pathogen identification given high mortality rates exceeding 10% without appropriate antibiotics. Tertiary care networks across Brazil and Japan prioritize multiplex PCR panels covering S. pneumoniae, N. meningitidis, and Listeria monocytogenes under antimicrobial stewardship mandates.
- Viral Meningitis:Enterovirus and herpes simplex virus detection differentiates aseptic from bacterial etiologies, preventing unnecessary antibiotic exposure. Reference laboratories in the United States deploy comprehensive viral meningitis panels as CSF-to-blood glucose ratio screening reduces empirical antibacterial prescribing.
- Fungal Meningitis:Cryptococcus neoformans and Candida species detection serves immunocompromised populations.
- Parasitic Meningitis:Naegleria fowleri and neurocysticercosis testing addresses geographic risk exposure.
- Chemical Meningitis:Drug-induced and contrast media reactions require exclusion of infectious causes.
Bacterial Meningitis maintains dominant procedure volumes. Viral Meningitis is climbing the fastest as enterovirus surveillance expands.
End User:
Customer type determines instrument specifications, service contract structures, and reagent consumption patterns.
- Diagnostic Laboratories:High-throughput facilities process 200-plus CSF specimens daily with automated nucleic acid extraction and liquid handling robotics. Centralized laboratory infrastructure across India's metropolitan tier-1 cities consolidates testing demand previously fragmented across district hospitals.
- Academic Hospitals:Research-active institutions integrate diagnostic testing with antimicrobial resistance surveillance and clinical trial enrollment. University medical centers in Germany negotiate bundled procurement covering instruments, reagents, and bioinformatics support under three-year exclusive agreements.
- Research Institutes:Epidemiological studies and vaccine efficacy trials drive specialized assay development.
- Reference Laboratories:Regional hubs provide confirmatory testing and quality assurance services.
- Specialty Clinics:Neurology and infectious disease practices require rapid turnaround for outpatient lumbar puncture evaluation.
Diagnostic Laboratories anchor installed base. Academic Hospitals are gaining procurement influence through consolidated health system purchasing.
Deployment:
Geographic accessibility constraints reshape where testing infrastructure locates relative to patient presentation.
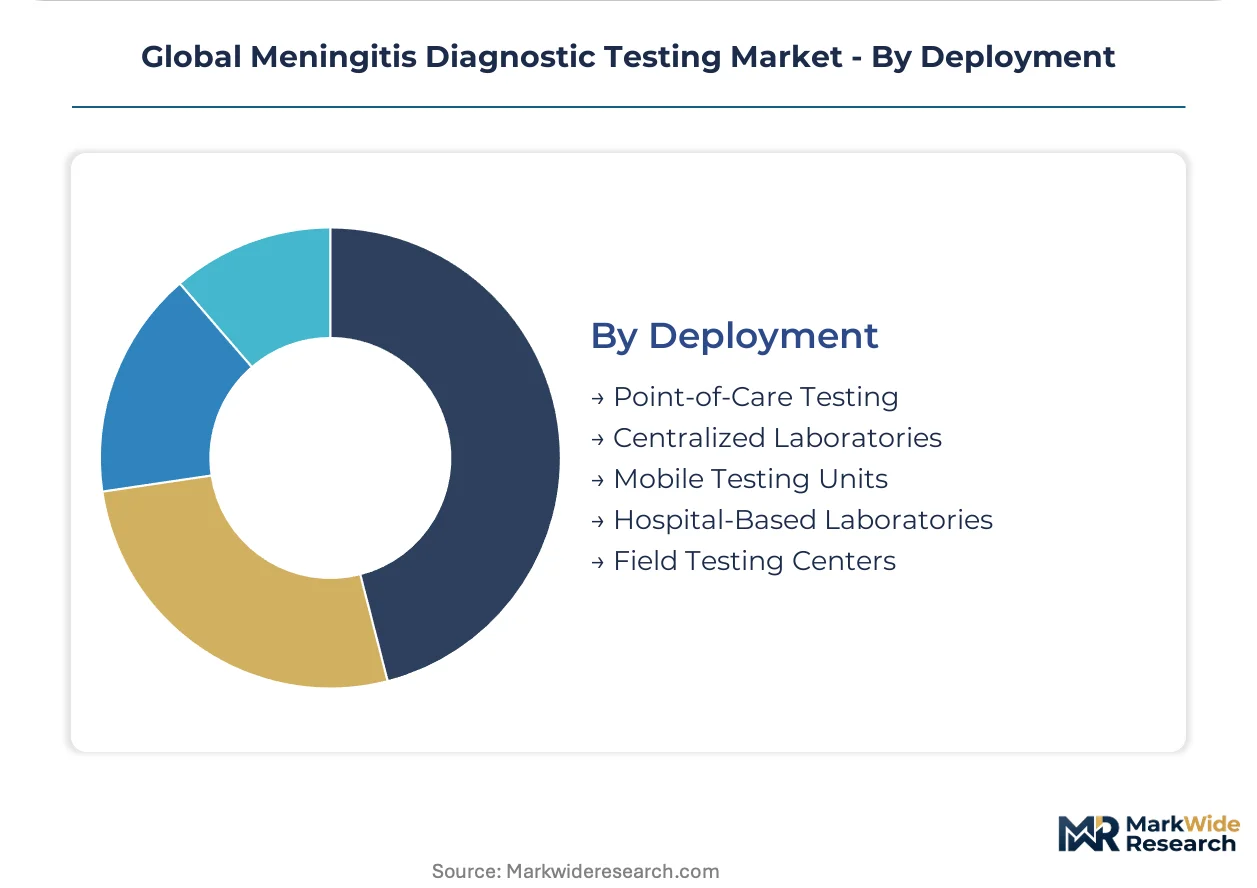
- Point-of-Care Testing:Cartridge-based molecular systems deliver nucleic acid amplification results within 60 minutes at peripheral clinical sites. Nigerian field testing centers deploy portable platforms where centralized laboratory access exceeds four-hour transport windows for acute meningococcal triage.
- Centralized Laboratories:Consolidated hubs achieve economies of scale through batch processing and specialized technician staffing. Brazil's public health laboratory network concentrates multiplex PCR capacity in state capital facilities serving multiple municipalities.
- Mobile Testing Units:Vehicle-mounted laboratories extend diagnostic reach to outbreak settings.
- Hospital-Based Laboratories:Inpatient facilities integrate testing with emergency department and intensive care workflows.
- Field Testing Centers:Temporary installations address epidemic response and refugee health screening.
Centralized Laboratories retain volume concentration. Point-of-Care Testing is expanding most quickly as decentralized networks proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains a diagnostic reagent trade surplus with concentrated exports of molecular assay components to European and Asian hospital networks. Germany and Japan balance import dependence for specialized PCR consumables against domestic instrument manufacturing. India, Brazil, and Nigeria represent net importers of finished diagnostic platforms, with local value addition limited to specimen collection logistics and field deployment services.
United States
FDA 510(k) clearance pathways accelerate multiplex PCR panel introductions for hospital laboratory networks. The Centers for Medicare & Medicaid Services ties diagnostic reimbursement to rapid pathogen identification under antimicrobial stewardship programs. Boston and San Diego academic medical centers consolidate procurement through group purchasing organizations covering instruments, reagents, and bioinformatics support.
Germany
EMA In Vitro Diagnostic Regulation mandates clinical performance studies with defined sensitivity thresholds for meningitis pathogen detection. The country's national pharmaceutical regulator enforces expanded clinical trial requirements before CE marking authorization. Bavarian and North Rhine-Westphalian tertiary care centers negotiate three-year exclusive supply agreements prioritizing total cost-of-ownership metrics.
Japan
METI promotes cloud-connected diagnostic instrumentation through regulatory harmonization with international quality standards. PMDA oversight shapes product development priorities by mandating clinical validation standards for molecular diagnostic platforms. Tokyo and Osaka metropolitan academic medical centers restructure staffing models around molecular triage workflows compressing turnaround times.
India
CDSCO registration requirements filter market access for manufacturers targeting procurement contracts through public health programs. Centralized laboratory infrastructure across Maharashtra and Karnataka consolidates testing demand previously fragmented across district hospitals. Mumbai and Bangalore diagnostic hubs process 500-plus CSF specimens daily with automated nucleic acid extraction robotics.
Brazil
ANVISA regulatory timelines shape entry strategies for multiplex PCR platform developers targeting Latin American expansion. Asset-light instrument financing lowers entry barriers for mid-sized São Paulo and Rio de Janeiro laboratories previously excluded from molecular capacity. State capital facilities concentrate multiplex PCR capacity serving multiple municipalities through public health laboratory networks.
Global Meningitis Diagnostic Testing Market Competitive Landscape
On the supply side, the industry is consolidating around integrated platform providers with installed base advantages and service revenue streams. Three strategic archetypes dominate: multinational life science conglomerates with broad diagnostic portfolios, specialized molecular diagnostic firms with cartridge-based systems, and diversified healthcare conglomerates with point-of-care footprints. Competitive moves center on exclusive supply agreement negotiations with group purchasing organizations and technology licensing partnerships for cloud-connected instrument platforms.
Within the integrated platform tier, Thermo Fisher Scientific and BioFire Diagnostics exemplify contrasting approaches to sustaining competitive position. Thermo Fisher leverages its installed base of real-time PCR instrumentation across academic hospital networks. BioFire anchors its market presence through integrated film array technology reducing technician training burdens. Abbott Laboratories occupies a distinct position with portable instrument footprints designed for rapid deployment in field testing centers.
| Leading Market Players |
|---|
| BioFire Diagnostics |
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| Abbott Laboratories |
| Seegene |
| Siemens Healthineers |
| Luminex Corporation |
| IMMY |
| Becton, Dickinson and Company |
| Others |
Supply & Pricing Matrix
Single-source dependency on Taq polymerase and fluorescent probe chemistries from United States and German suppliers determines both three-tier pricing stratification across premium, standard, and economy levels and the geographic concentration of molecular diagnostic manufacturing. Cold chain logistics costs for reagent distribution amplify pricing spreads between centralized laboratory hubs and peripheral field testing centers.
Pricing Analysis
Academic hospital buyers anchor subscription-based instrument leasing with per-test reagent pricing across the meningitis diagnostic market. Pricing stratifies across premium, standard, and economy tiers based on multiplex panel breadth and ISO 13485 certification status. Cost compression in economy-tier immunoassay segments is intensifying because Brazilian and Nigerian procurement committees prioritize upfront capital minimization over total cost-of-ownership metrics. Reference laboratories exhibit lowest price sensitivity due to bundled bioinformatics and service contract requirements, while peripheral clinics in India demonstrate highest sensitivity to cold chain surcharges.
Supply Chain Analysis
Upstream nucleic acid extraction chemistries and thermal-stable polymerase enzymes concentrate manufacturing in the United States, Germany, and Japan. Finished multiplex PCR platforms draw from Taiwanese semiconductor components, Chinese injection-molded plastics, and Swiss precision optics. Single-source vulnerability in fluorescence detection module supply creates procurement risk for cartridge-based system manufacturers. Distribution runs through exclusive supply agreements negotiated by group purchasing organizations in German and Japanese tertiary care networks, with regional warehousing in São Paulo, Mumbai, and Lagos serving emerging market demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-connected diagnostic instrumentation is restructuring this market toward platform economics where interoperability and data network effects determine competitive survival. Manufacturers must prioritize API standardization and LIS middleware development to capture ecosystem value.
For Market Incumbents: Insulate installed base revenue through exclusive bioinformatics service contracts that lock academic hospital networks into multi-year relationships. Prioritize backward integration into nucleic acid extraction chemistry manufacturing to reduce exposure to Thermo Fisher supply bottlenecks. Defend against emerging cartridge-based entrants by accelerating FDA 510(k) clearance timelines for integrated resistance profiling panels that match BioFire's technician training reduction claims.
For New Entrants and Emerging Players: Nigerian field testing centers and Indian district hospital networks represent the most penetrable white-space targets where centralized laboratory access exceeds four-hour transport windows. Target point-of-care deployment modes with ambient-temperature stable reagents that eliminate cold chain infrastructure requirements. Pursue WHO prequalification pathway acceleration to unlock procurement contracts through international health agencies serving Brazilian and African public health programs.
For Investors and Strategic Acquirers: EMA In Vitro Diagnostic Regulation implementation reshapes the acquisition landscape toward platforms with completed clinical performance studies and European reference laboratory validation. Long-term viability favors integrated molecular diagnostic firms with cartridge-based systems and cloud-connected service infrastructure over pure-play reagent suppliers. Monitor FDA breakthrough device designation grants as early signals of regulatory pathway acceleration that compresses competitive entry timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Connected Instrument Platform | Enables remote calibration and predictive maintenance across distributed testing networks. |
| Integrated Resistance Profiling Panel | Combines pathogen identification with antimicrobial susceptibility reporting under FDA 510(k). |
| WHO Prequalification Acceleration | Streamlines IVD registration for procurement contracts through international health agencies. |
| Asset-Light Leasing Model | Lowers entry barriers for mid-sized Brazilian laboratories excluded from molecular capacity. |
| LIS Middleware Development | Resolves legacy system integration challenges in Japanese hospital laboratory networks. |
Research Methodology
Desk research of regulatory filings, hospital procurement databases, and GPO contract disclosures preceded structured interviews with clinical laboratory directors, biomedical engineers, GPO contracts managers, and IVD regulatory affairs leads. Secondary validation drew from FDA 510(k) clearances, EMA In Vitro Diagnostic Regulation guidance documents, WHO prequalification assessment reports, and CDSCO registration databases. Bottom-up and top-down triangulation reconciled instrument shipment data with reagent consumption patterns across academic medical centers.
Assumptions regarding antimicrobial stewardship mandate expansion, cloud connectivity adoption curves, and cartridge-based system replacement cycles remained fixed across the projection horizon while regulatory timeline scenarios and cold chain infrastructure investment rates were stress-tested. Segmentation modeling incorporated diagnostic modality, pathogen target, end-user facility type, and deployment mode dimensions. CAGRs were derived from logarithmic trend fitting to historical procurement volumes with sensitivity analysis around WHO prequalification throughput and group purchasing organization consolidation rates.
Practitioners should monitor EMA clinical performance study requirement amendments and FDA breakthrough device designation velocity for early signals of competitive entry timeline compression. Forecasts reflect assumptions regarding stable reimbursement differentials between molecular and culture-based methods. Cross-checking against CMS Medicare laboratory fee schedule updates and German DRG code revisions is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
United Kingdom in-Vitro Diagnostics Market
Diagnostics
Epilepsy Diagnosis and Treatment Market
Diagnostics
Global Veterinary POC Diagnostic Market
Diagnostics
Global STD Diagnostics Market
Diagnostics
Glucose Tolerance Test Market
Diagnostics
Meningitis Diagnosis and Treatment Market
Diagnostics
Viral Molecular Diagnostics Market
Diagnostics
Infectious Disease Point-Of-Care (POC) Diagnostics Market
Diagnostics
South Africa in-Vitro Diagnostics Market
Diagnostics
Infectious Disease in Vitro Diagnostics Market
Diagnostics
Italy in Vitro Diagnostics Market
Diagnostics
Global Lateral Flow Assay Market
Diagnostics
Biochips Based in-Vitro Diagnostics Market
Diagnostics
Japan in-Vitro Diagnostics Market
Diagnostics
Diagnostic Exosome Biomarkers Market
Diagnostics
Lipid Panel Test Market