
 In Vitro Diagnostic Antibodies Market | 2026-2036
In Vitro Diagnostic Antibodies Market Size, Share, and Industry Trends Forecast 2026-2036
In Vitro Diagnostic Antibodies Market Insights
The gap between premium-grade recombinant antibodies and commodity polyclonal serum products is expanding as diagnostic manufacturers face stricter analytical validation requirements. Thermo Fisher Scientific leverages its vertically integrated protein production network to supply high-batch-consistency reagents for regulated assays. Abcam plc sustains competitive positioning through recombinant monoclonal validation protocols that reduce lot-to-lot variability. Roche Diagnostics anchors its antibody supply chain through captive bioreactor capacity serving its automated diagnostic platform installed base.
In vitro diagnostic antibodies are affinity proteins engineered or harvested for specific antigen binding in clinical laboratory settings, typically requiring purity thresholds above 95% and endotoxin levels below 1 EU/mg to prevent assay interference. These reagents enable quantitative and qualitative detection of disease biomarkers, therapeutic drug monitoring, and infectious agent identification across automated and manual testing workflows. Monoclonal antibodies command premium positioning due to their clonal specificity and renewable production economics, while polyclonal antibodies retain share in complex antigen detection where epitope diversity matters. The ELISA technology segment maintains substantial volume absorption given its equipment ubiquity, though immunohistochemistry applications are gaining faster growth in oncology companion diagnostic expansion.
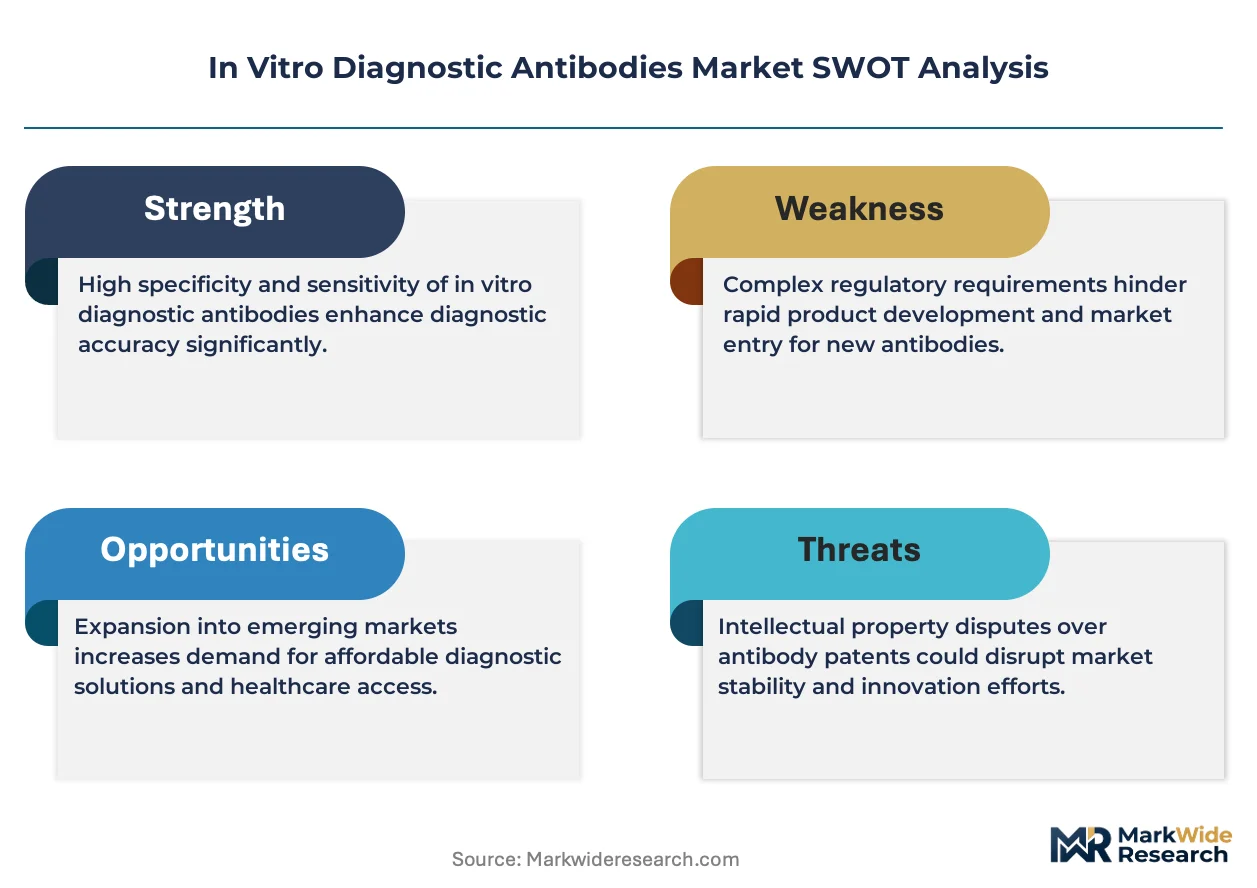
The FDA enforces Quality System Regulation and pre-market notification pathways for antibody-based IVD components, while the EU IVDR mandates notified body oversight and performance study documentation for reagent suppliers seeking CE marking. These frameworks elevate compliance costs for smaller antibody producers and consolidate procurement relationships toward vendors with established regulatory affairs infrastructure. Stakeholders must monitor evolving harmonization efforts between FDA and IVDR technical documentation requirements, as divergence in validation standards threatens to fragment supply chain economics for multinational diagnostic manufacturers.
Market Dynamics
EU IVDR recertification deadlines are compressing manufacturing timelines and forcing diagnostic antibody suppliers to rebuild quality management systems around performance study documentation. This regulatory pressure is concentrating procurement toward vendors with established notified body relationships and captive analytical validation infrastructure.
Growth Catalysts
- Companion diagnostic expansion:Oncology biomarker testing protocols are expanding antibody consumption in pathology workflows across hospital networks in the United States and Germany.
- IVDR compliance services:European diagnostic manufacturers are outsourcing antibody reagent validation to specialized contract research organizations with notified body accreditation.
- Automated platform integration:High-throughput immunoassay systems in clinical reference laboratories require recombinant monoclonal antibodies with batch-to-batch consistency specifications.
Market Restraints
- Serum supply volatility:Polyclonal antibody production depends on animal-derived raw materials subject to veterinary health restrictions and seasonal collection variations.
- Regulatory documentation burden:EU IVDR technical file requirements and FDA Quality System Regulation audits extend product launch timelines by twelve to eighteen months for new reagent entrants.
- Substitute detection technologies:CRISPR-based diagnostic platforms and nucleic acid amplification methods are displacing antibody-dependent assays in infectious disease screening applications.
Strategic Opportunities
- Point-of-care decentralization:Lateral flow and cartridge-based immunoassay formats are creating demand for lyophilized antibody reagents in primary care settings across India and Brazil.
- Regulatory harmonization incentives:FDA-IVDR mutual recognition pilot programs could reduce dual certification costs for antibody suppliers serving multinational diagnostic manufacturers.
- Multiplex panel convergence:Chemiluminescence and bead-based multiplexing technologies are unifying previously separate antibody detection workflows into single-platform configurations.
Industry Challenges
- Skilled regulatory affairs scarcity:Experienced professionals capable of navigating simultaneous FDA pre-market notification and IVDR notified body submission processes command premium compensation.
- Legacy assay revalidation costs:Diagnostic laboratories must repeat analytical performance studies when switching antibody lots or suppliers, creating operational friction and inventory risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In Vitro Diagnostic Antibodies Market |
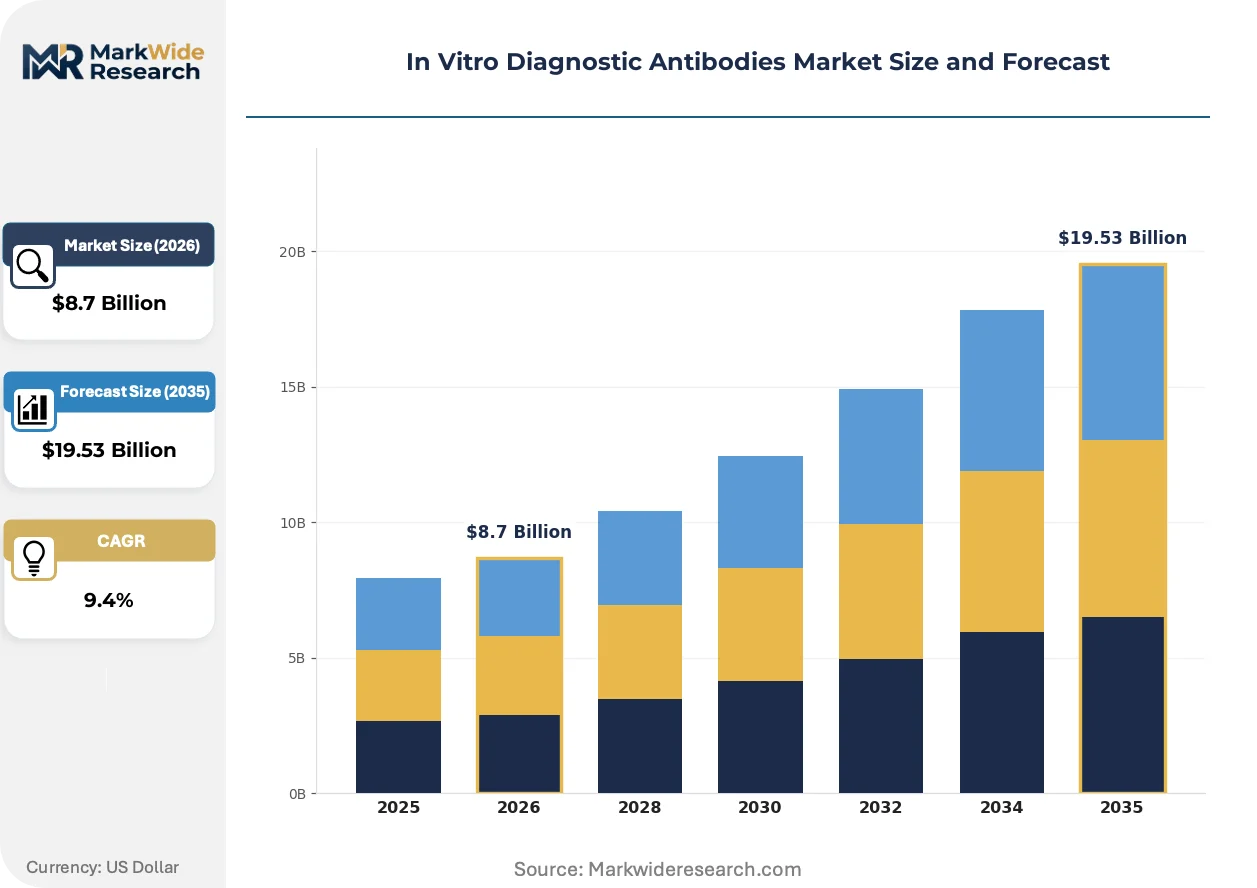
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Polyclonal Antibodies, Primary Antibodies, Secondary Antibodies Delivery Mode: Injections, Liquid Solutions, Lyophilized Forms, Kits End User: Hospitals, Diagnostic Laboratories, Research Institutes, Blood Banks Technology: ELISA, RIA, Western Blotting, Immunohistochemistry |
| Companies Covered | Thermo Fisher Scientific, Abcam plc, Bio-Rad Laboratories, Roche Diagnostics, Abbott Laboratories, Rockland Immunochemicals Inc., GenScript, HyTest Ltd, Agilent Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In Vitro Diagnostic Antibodies Market Trends and Innovations
Recombinant antibody engineering is displacing hybridoma-dependent production across regulated diagnostic applications. Three convergent developments are reshaping competitive positioning: protein display technologies, regulatory documentation automation, and procurement consolidation around integrated supply contracts.
Single B-cell screening and phage display libraries are unifying epitope mapping with high-throughput candidate selection. Contract manufacturing organizations serving IVD developers are adopting these platforms to compress lead times from antigen immunization to validated master cell banks. The structural consequence is compressing the economic viability window for traditional hybridoma-based service providers.
EU IVDR performance study templates and FDA pre-submission pathways are converging toward modular technical documentation standards. Diagnostic antibody suppliers are investing in electronic quality management systems capable of generating dual-use validation packages. European notified bodies and FDA review divisions are piloting parallel assessment procedures for well-characterized recombinant reagents.
Hospital network procurement offices are consolidating antibody reagent purchasing through group purchasing organizations with mandatory ISO 13485 supplier certification. Reference laboratories in the United States are shifting from spot-buying catalog antibodies to multi-year supply agreements with guaranteed lot continuity provisions. This behavioral shift is visible most acutely in oncology companion diagnostic programs where assay standardization across regional lab networks is mandatory.
In Vitro Diagnostic Antibodies Market Segmentation
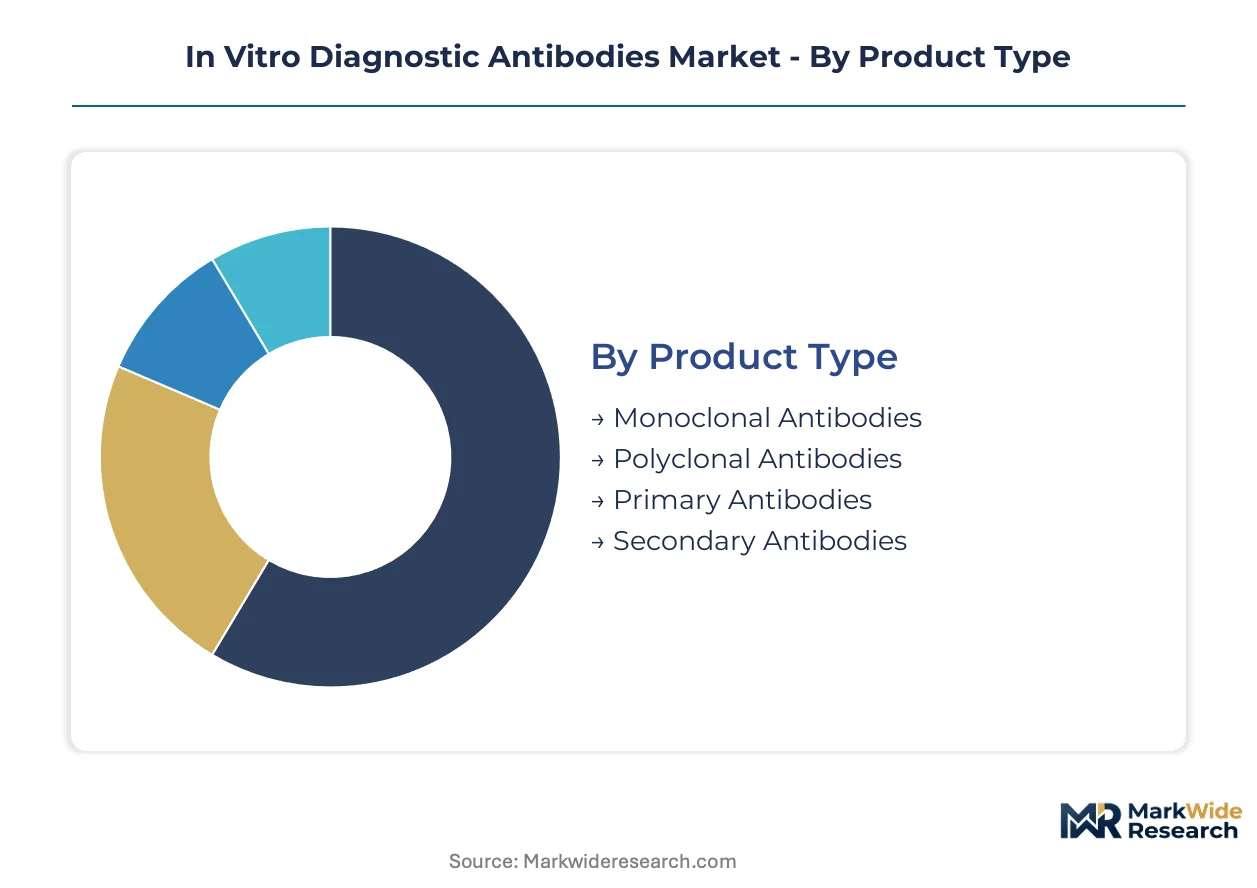
Antibody segmentation determines regulatory pathway complexity and manufacturing scale economics for diagnostic reagent suppliers. Product type and technology choices cascade into validation requirements, while end-user concentration shapes distribution channel strategy across clinical and research settings.
Product Type:
Clonal specificity versus epitope breadth defines the standardization-to-customization spectrum across antibody formats, with renewable production methods commanding premium positioning.
- Monoclonal Antibodies:Single-epitope binding proteins derived from immortalized B-cell clones deliver batch-to-batch consistency below 5% coefficient of variation. Automated immunoassay platforms in United States hospital networks specify recombinant monoclonals for therapeutic drug monitoring workflows.
- Polyclonal Antibodies:Heterogeneous antibody populations harvested from immunized serum recognize multiple epitopes simultaneously. Complex antigen detection in infectious disease panels retains polyclonal preference where epitope diversity compensates for lower lot consistency.
- Primary Antibodies:Direct antigen-binding reagents unconjugated to detection systems require matched secondary antibody pairing for signal amplification in manual protocols.
- Secondary Antibodies:Anti-species conjugates bridge primary antibody binding to enzymatic or fluorescent reporters, enabling modular assay architecture across detection platforms.
Volume leader: Monoclonal Antibodies. Steepest expansion trajectory: Primary Antibodies in companion diagnostic development.
Delivery Mode:
Stability requirements and point-of-care deployment distance separate high-volume liquid formats from specialized lyophilized configurations.
- Injections:Formulated antibody solutions in pre-filled syringes enable direct administration for in vivo diagnostic imaging applications. Nuclear medicine departments in German university hospitals specify endotoxin-controlled injection-grade antibodies for radioimmunoconjugate synthesis.
- Liquid Solutions:Ready-to-use antibody preparations in buffered preservatives dominate high-throughput clinical laboratory workflows. Reference labs in the United States procure liquid reagents in bulk carboys for automated platform integration.
- Lyophilized Forms:Freeze-dried antibody cakes extend shelf stability for ambient temperature distribution. Primary care settings in India and Brazil favor lyophilized lateral flow components where cold chain infrastructure remains fragmented.
- Kits:Pre-configured antibody panels with matched controls and substrates reduce assay development burden. European diagnostic manufacturers outsource kit assembly to contract packagers with ISO 13485 certification.
Dominant by throughput: Liquid Solutions. Gaining share fastest: Lyophilized Forms in decentralized testing expansion.
End User:
Procurement scale and regulatory sophistication stratify antibody demand from centralized hospital networks to fragmented research installations.
- Hospitals:Integrated delivery networks consolidate antibody purchasing through group purchasing organizations with mandatory lot continuity guarantees. Oncology companion diagnostic standardization across United States health systems drives multi-year supply agreements.
- Diagnostic Laboratories:Independent reference labs and hospital-affiliated core facilities absorb the highest antibody volumes per installation. Automated platform integration in high-complexity testing menus specifies recombinant monoclonal consistency specifications.
- Research Institutes:Academic and government laboratories purchase catalog antibodies in smaller batch quantities with less stringent validation documentation. Grant-funded investigators prioritize cost over lot-to-lot consistency for exploratory biomarker studies.
- Blood Banks:Transfusion medicine services require antibody reagents for infectious disease screening and blood group serology. Regulatory oversight from FDA and national blood authorities mandates extensive donor screening assay validation.
Largest procurement volume: Diagnostic Laboratories. Expanding most quickly: Blood Banks in emerging market transfusion safety programs.
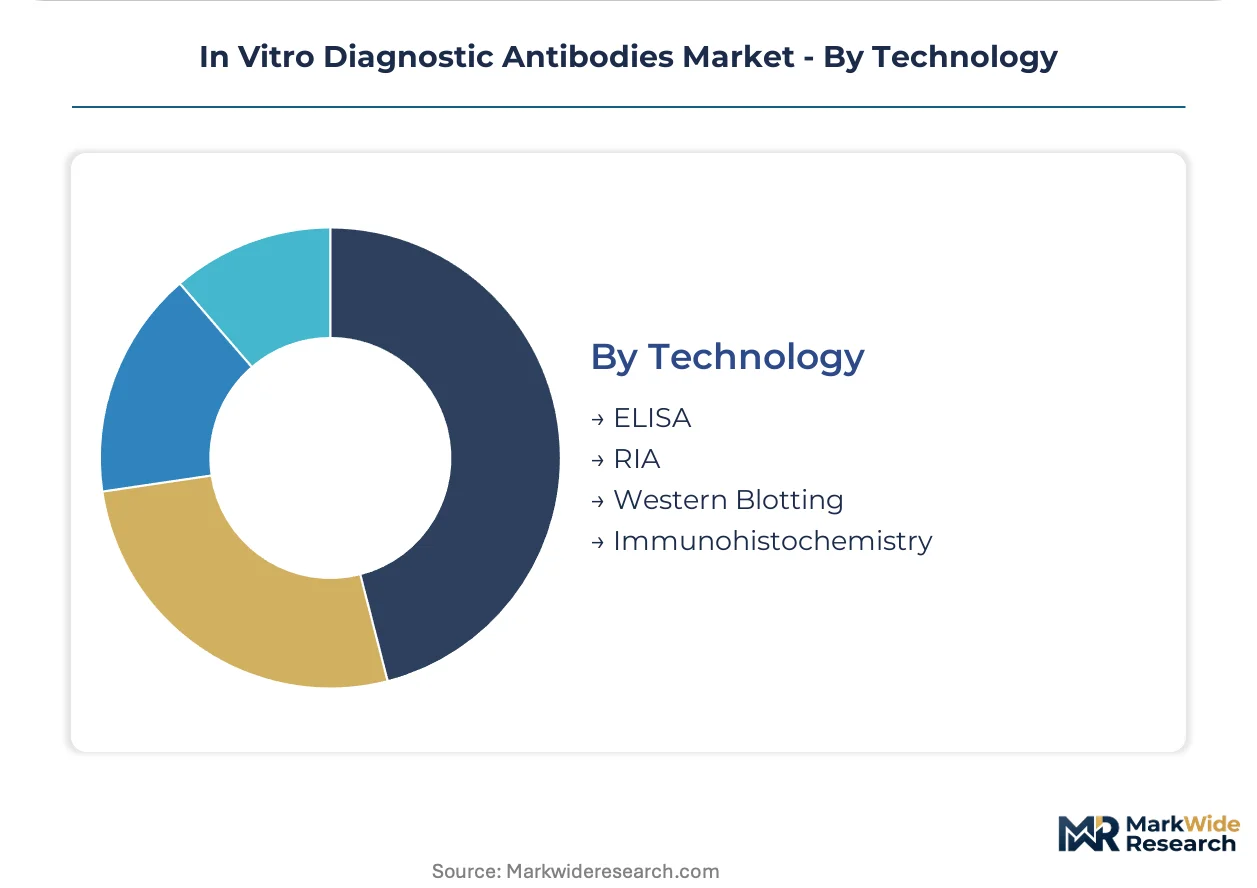
Technology:
Detection sensitivity, throughput capacity, and regulatory clearance history differentiate antibody-dependent assay platforms.
- ELISA:Enzyme-linked immunosorbent assays absorb the highest antibody volumes globally due to equipment ubiquity and protocol standardization. Clinical chemistry departments in the United States deploy ELISA for routine hormone and tumor marker quantification.
- RIA:Radioimmunoassays retain niche applications where picomolar sensitivity exceeds chemiluminescence performance. Endocrinology reference laboratories specify RIA for peptide hormone measurement despite radioactive waste handling costs.
- Western Blotting:Protein separation and antibody detection hybrid technique serves confirmatory diagnostic applications. HIV diagnostic algorithms in multiple jurisdictions mandate Western blot confirmation following screening assay positivity.
- Immunohistochemistry:Tissue-based antibody staining enables morphological context for biomarker expression. Pathology workflows in oncology companion diagnostics are shifting toward automated immunohistochemistry platforms with quantitative scoring algorithms.
Antibody consumption leader: ELISA. Climbing the fastest: Immunohistochemistry in precision oncology expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Kendall Square corridor anchors North American diagnostic antibody development, hosting contract research organizations that validate reagents for FDA pre-market notification pathways.
United States
Hospital networks in the United States consolidate antibody procurement through group purchasing organizations with mandatory lot continuity guarantees. The FDA enforces Quality System Regulation audits that extend product launch timelines for new reagent entrants. Reference laboratories in North Carolina's Research Triangle Park specify recombinant monoclonal antibodies for automated immunoassay platforms.
Germany
German university hospitals drive consumption of endotoxin-controlled injection-grade antibodies for radioimmunoconjugate synthesis in nuclear medicine departments. The EU IVDR mandates notified body oversight and performance study documentation for reagent suppliers seeking CE marking. Munich's biotechnology cluster hosts contract manufacturing organizations adopting single B-cell screening platforms.
China
Domestic diagnostic manufacturers in China are rebuilding quality management systems around IVDR-equivalent documentation standards for export markets. The NMPA enforces pre-market notification pathways for antibody-based IVD components that parallel FDA technical requirements. Shanghai's Zhangjiang Hi-Tech Park concentrates lyophilized reagent production for point-of-care decentralization across India and Brazil.
India
Primary care settings in India favor lyophilized lateral flow components where cold chain infrastructure remains fragmented. The CDSCO regulates diagnostic antibody imports through mandatory registration and quality testing protocols. Hyderabad's Genome Valley hosts contract research organizations with notified body accreditation for IVDR compliance services.
Japan
Endocrinology reference laboratories in Japan specify radioimmunoassays for peptide hormone measurement where picomolar sensitivity exceeds chemiluminescence performance. The PMDA enforces quality system requirements that align with FDA technical documentation standards. Osaka's pharmaceutical corridor concentrates automated immunohistochemistry platform development for oncology companion diagnostics.
In Vitro Diagnostic Antibodies Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the diagnostic antibody landscape, creating a tiered structure where captive bioreactor capacity faces modular contract manufacturing networks. The vendor base stratifies between vertically integrated life science conglomerates, specialized recombinant antibody developers, and hybridoma-dependent service providers. Three archetypes dominate: platform-integrated suppliers with automated diagnostic installed bases, recombinant engineering specialists with phage display libraries, and catalog distributors with ISO 13485 certification. Consolidation pressures favor M&A activity around regulatory affairs infrastructure and strategic partnerships for dual FDA-IVDR validation packages.
Within the platform-integrated tier, Thermo Fisher Scientific and Roche Diagnostics exemplify capital-intensive positioning through captive production networks serving automated diagnostic installed bases. Abcam plc occupies a specialist position representing recombinant monoclonal validation protocols that reduce lot-to-lot variability. These three anchors illustrate the competitive divergence between scale-driven supply security and precision-engineered consistency specifications.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Abcam plc |
| Bio-Rad Laboratories |
| Roche Diagnostics |
| Abbott Laboratories |
| Rockland Immunochemicals Inc. |
| GenScript |
| HyTest Ltd |
| Agilent Technologies |
| Others |
Pricing and Supply Chain Analysis
Captive bioreactor capacity at vertically integrated diagnostic conglomerates anchors both supply security and premium pricing power for recombinant monoclonal antibodies. These manufacturers leverage in-house protein production networks to guarantee batch-to-batch consistency below 5% coefficient of variation, commanding price premiums from United States hospital networks facing IVDR-equivalent documentation demands.
Pricing Analysis
Throughput-based pricing anchors contract structures for automated immunoassay platforms, with United States reference laboratories paying premium rates for guaranteed lot continuity across multi-year supply agreements. Price differentiation hinges on ISO 13485 certification tier and recombinant validation depth, with non-certified catalog distributors facing cost compression from group purchasing organization consolidation. Academic research institutes exhibit highest price sensitivity, while oncology companion diagnostic programs show lowest sensitivity due to mandatory assay standardization requirements.
Supply Chain Analysis
Direct-to-diagnostic-laboratory channels handle high-volume liquid reagent demand from United States reference labs, while distributor-mediated pathways serve fragmented primary care settings in India and Brazil. Manufacturing concentrates in the United States, Germany, and China, with Chinese facilities specializing in lyophilized formats for tropical distribution. Raw material dependencies include fetal bovine serum for polyclonal production, recombinant expression vectors, and endotoxin-controlled purification resins. Single-source vulnerability around validated master cell banks poses structural risk, compounded by EU IVDR recertification timelines compressing supplier qualification windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a technology-transition phase as recombinant antibody engineering displaces hybridoma-dependent production, with single B-cell screening and phage display libraries compressing lead times from antigen immunization to validated reagents.
For Market Incumbents: Anchor defensive positioning through captive analytical validation infrastructure capable of generating dual FDA-IVDR technical documentation packages. Consolidate procurement relationships around multi-year supply agreements with guaranteed lot continuity provisions, while investing in electronic quality management systems to automate regulatory submission workflows against skilled regulatory affairs scarcity. For New Entrants and Emerging Players: E-commerce platforms and digital catalog distribution offer lower-friction entry routes into research institute segments where validation documentation requirements remain less stringent. Target academic laboratories and grant-funded investigators in India and Brazil with cost-optimized polyclonal catalog products, leveraging contract manufacturing organizations in China's Zhangjiang Hi-Tech Park for lyophilized format production. For Investors and Strategic Acquirers: Exit pathways concentrate in platform-integrated diagnostic conglomerates seeking regulatory affairs infrastructure and recombinant antibody engineering capabilities. Long-term viability favors asset-light designers with phage display libraries and notified body relationships over capital-heavy hybridoma-dependent service providers. Watch IVDR-FDA mutual recognition pilot program expansion as inflection signal for dual certification cost reduction.| Strategic Initiative | Industry Significance |
|---|---|
| Recombinant Engineering Platform Investment | Single B-cell screening compresses lead times for regulated diagnostic applications. |
| Dual Certification Documentation Automation | Electronic quality management systems generate parallel FDA-IVDR submission packages. |
| Group Purchasing Organization Consolidation | Multi-year supply agreements with lot continuity guarantees secure United States hospital network access. |
| Point-of-Care Format Development | Lyophilized lateral flow components address cold chain gaps in India and Brazil. |
| Notified Body Relationship Acquisition | Established EU IVDR performance study infrastructure accelerates CE marking timelines. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with diagnostic reagent procurement managers, regulatory affairs leads at antibody suppliers, pathology laboratory directors, and contract manufacturing organization executives. FDA pre-market notification databases, EU IVDR notified body submission records, CDSCO import registration logs, and hospital group purchasing organization contract databases provided validation anchors. Bottom-up antibody consumption estimates by technology platform triangulated against top-down diagnostic manufacturer revenue disclosures.
Segment-level granularity modeled product type, delivery mode, end user, and technology dimensions across the projection horizon, with additional stratification by regulatory certification tier and geographic procurement cluster. CAGRs derived from logistic growth curve fitting to historical volume trajectories, incorporating IVDR recertification deadline impacts and automated platform installation base expansion rates. Forecast inputs included pathology workflow automation adoption curves and companion diagnostic biomarker panel expansion timelines.
The model holds under stable regulatory harmonization progress between FDA and IVDR technical documentation standards; deviation in mutual recognition pilot program suspension or notified body capacity constraints would shift supply concentration assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Asia-Pacific Molecular Diagnostics Market
Diagnostics
Infectious Disease in Vitro Diagnostics Market
Diagnostics
Critical Care Diagnostics Market
Diagnostics
Influenza Diagnostics Market
Diagnostics
Tissue Transglutaminase Test Market
Diagnostics
Global Liver Disease Diagnostics Market
Diagnostics
Gastrointestinal Diagnostics Market
Diagnostics
Blood Culture Media Market
Diagnostics
IVD Antibody Market
Diagnostics
Global Prostate Specific Antigen (PSA) Test Market
Diagnostics
Rapid Influenza Diagnostic Tests (RIDT) Market
Diagnostics
Rapid Oral Fluid Screening Device Market
Diagnostics
Fructosamine Reagents Market
Diagnostics
Animal Diagnostics Market
Diagnostics
Heart Attack Diagnostics Market
Diagnostics
Semen Analysis Market