
 Hepatitis B Treatment Market | 2026-2036
Hepatitis B Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Hepatitis B Treatment Market Outlook
China is reshaping hepatitis B manufacturing capacity through expanded biologics facilities serving domestic and export demand. Gilead Sciences sustains its nucleos(t)ide analogue portfolio through established regulatory dossiers across major markets. Bristol-Myers Squibb anchors its position in immune modulator development with sustained clinical investment. Merck & Co. dominates vaccine production scale, leveraging decades of immunization program integration.
Hepatitis B treatment encompasses antiviral and immunomodulatory interventions targeting HBV polymerase inhibition and host immune restoration, with nucleos(t)ide analogues such as tenofovir and entecavir achieving sustained viral suppression through once-daily oral dosing regimens. The clinical purpose centers on preventing cirrhosis progression, hepatocellular carcinoma incidence reduction, and transmission interruption. Nucleos(t)ide analogues occupy the largest revenue pool due to chronic patient maintenance requirements and generic erosion resistance in tenofovir alafenamide formulations. Immune modulators represent the fastest-growing category as finite-duration therapies promise functional cure endpoints. Hospital end users capture disproportionate margin concentration through infusion center economics and specialist-managed protocols.
FDA accelerated approval frameworks and EMA conditional marketing authorization pathways shape hepatitis B drug development timelines and evidentiary thresholds for novel mechanisms. China's NMPA priority review channels for infectious disease therapies are shortening registration lags for domestic innovators like Ascletis Pharmaceuticals. WHO prequalification standards govern vaccine procurement eligibility for national immunization programs across low- and middle-income settings. Stakeholders must monitor functional cure trial readouts and their capacity to displace long-term nucleos(t)ide analogue maintenance paradigms.
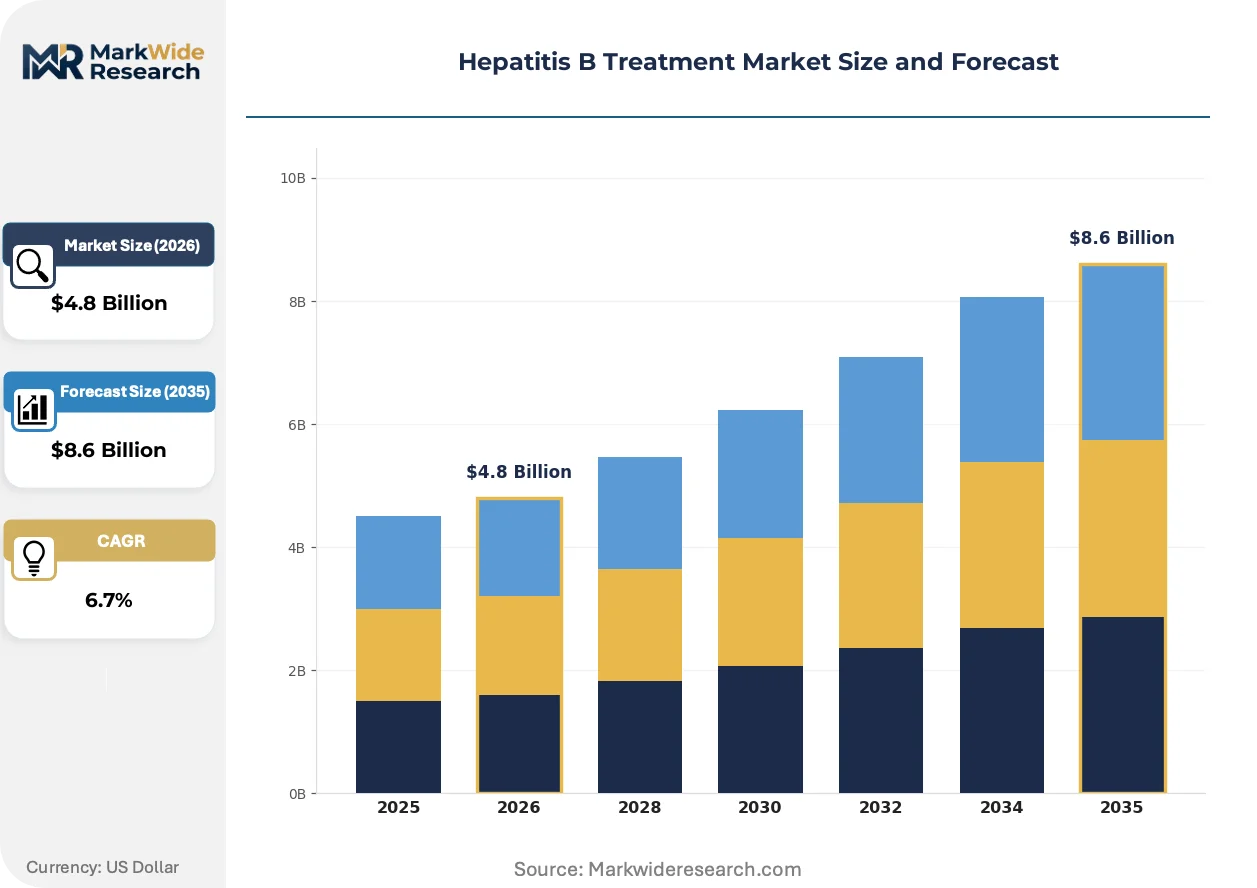
Market Dynamics
Functional cure development is collapsing the chronic maintenance paradigm that has sustained nucleos(t)ide analogue revenues for decades, forcing incumbents to restructure clinical investment priorities around finite-duration endpoints.
Growth Catalysts
- FDA Accelerated Approval:Compressed development timelines for novel hepatitis B mechanisms are attracting biotech venture capital into immune modulator pipelines. Tertiary care centers are expanding dedicated hepatology units to manage complex patient cohorts.
- China NMPA Priority Review:Domestic innovators are securing faster market access for infectious disease therapies, expanding manufacturing capacity for export markets. Biologics facility construction is accelerating in Jiangsu and Guangdong provinces.
- Antiviral Therapy Programs:Hospital-based protocols are standardizing nucleos(t)ide analogue initiation criteria, driving consistent patient intake volumes. Specialist-managed care models are improving treatment adherence rates.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient production for tenofovir and entecavir concentrates in Zhejiang and Shandong provinces, creating geographic vulnerability to environmental compliance disruptions.
- Generic Erosion Resistance:Tenofovir alafenamide formulations maintain pricing power through formulation patents, but entecavir faces commoditization pressure from Indian manufacturers.
- Functional Cure Uncertainty:Immune modulator mechanisms require complex biomarker validation, extending evidentiary thresholds beyond traditional virologic endpoints and delaying reimbursement negotiations.
Strategic Opportunities
- Sub-Saharan Africa Vaccine Access:WHO prequalification pathways are opening procurement eligibility for national immunization programs in Nigeria, Kenya, and Ethiopia, expanding addressable populations.
- Combination Therapy Development:Convergence of toll-like receptor agonists with capsid inhibitors is creating novel mechanism synergies for finite-duration regimens.
- Telehepatology Channels:Remote monitoring platforms are enabling specialist-managed care extension into community health settings, reducing geographic access barriers.
Industry Challenges
- Biomarker Standardization Delays:Inconsistent functional cure endpoint definitions across FDA, EMA, and NMPA guidance documents are complicating multi-registrational trial design.
- Specialist Workforce Scarcity:Hepatology fellowship programs are producing insufficient clinicians to manage expanding chronic patient cohorts in tertiary care centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hepatitis B Treatment Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interferon, Nucleos(t)ide Analogues, Immune Modulators, Vaccines End User: Hospitals, Clinics, Outpatient Facilities, Home Care Treatment Stage: Acute, Chronic, Recurrent, Preventive Administration Route: Oral, Intravenous, Subcutaneous, Intramuscular |
| Companies Covered | Merck & Co., Arbutus Biopharma, Gilead Sciences, Antios Therapeutics, Vir Biotechnology, Bristol-Myers Squibb, Johnson & Johnson, Ascletis Pharmaceuticals, GlaxoSmithKline, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hepatitis B Treatment Market Strategic Shifts
RNA interference therapeutics and capsid inhibitors are compressing the treatment duration paradigm, while regulatory pathways adapt evidentiary standards to capture durable virologic response endpoints.
Small interfering RNA constructs targeting HBV messenger RNA are collapsing the viral antigen production machinery that sustains immune tolerance. Academic medical centers are integrating these agents into combination protocols ahead of formal approval, compressing the timeline for functional cure validation. The structural consequence is a shift in pharmaceutical R&D allocation away from incremental nucleos(t)ide analogue improvements.
EMA conditional marketing authorization frameworks are adapting evidentiary thresholds for hepatitis B therapies to accommodate biomarker-based surrogate endpoints. This regulatory flexibility is accelerating European access timelines for immune modulator candidates. Hospital pharmacy committees in Germany, France, and Italy are pre-positioning budget impact models around finite-duration therapy assumptions.
Consolidated procurement by integrated delivery networks is displacing individual hospital pharmacy purchasing for high-cost hepatitis B therapies. United States health systems are centralizing formulary decisions through specialty pharmacy carve-outs, concentrating negotiating leverage with manufacturers. This pattern is most visible in California and Texas, where large IDNs manage hepatitis B patient volumes exceeding ten thousand active cases.
Hepatitis B Treatment Market Segmentation
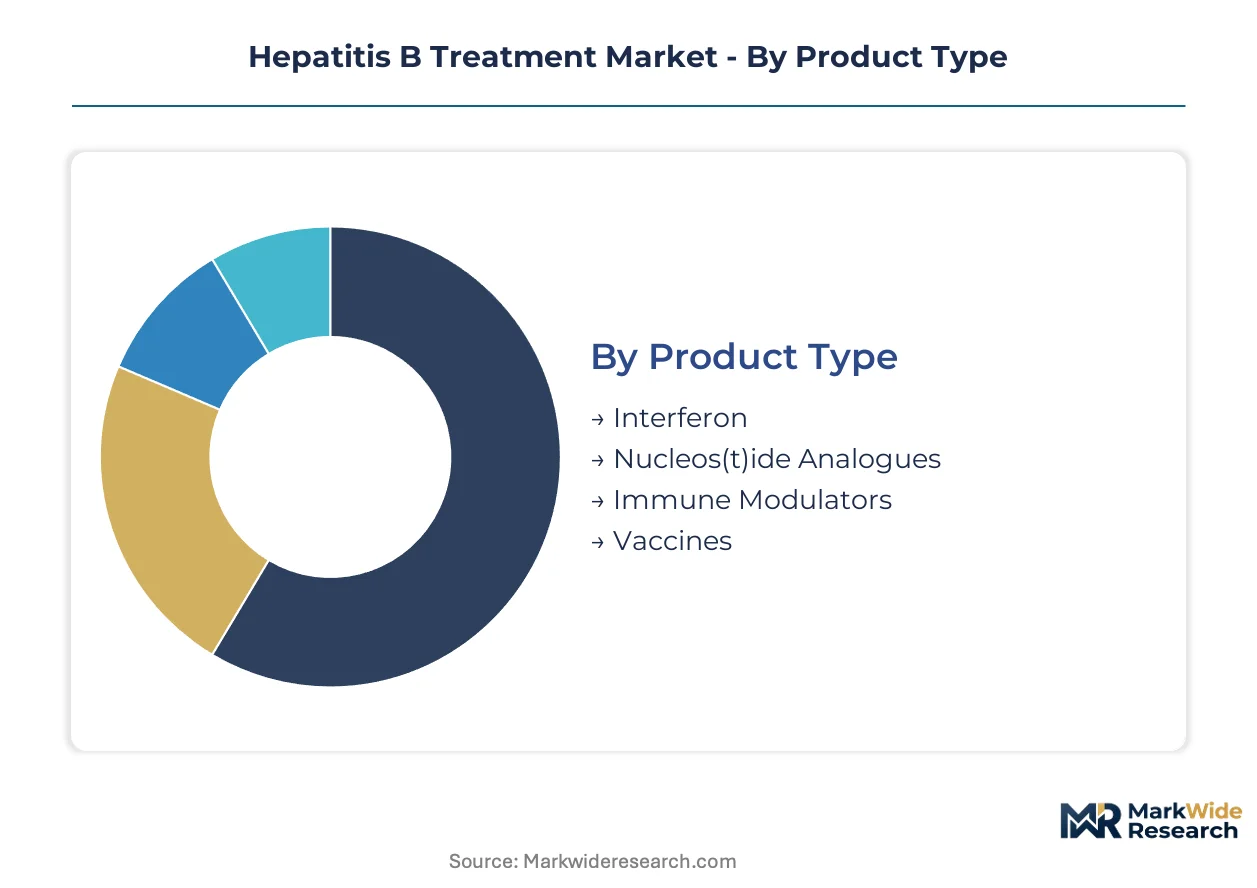
Hepatitis B treatment segmentation reveals distinct service intensity profiles across therapeutic modalities. Each product category demands specialized monitoring protocols that reshape after-sales clinical support requirements and patient management economics.
Product Type:
After-sales-service intensity varies dramatically across therapeutic classes, with infusion-dependent modalities requiring dedicated nursing support versus oral regimens that rely on remote adherence monitoring.
- Nucleos(t)ide Analogues:Oral polymerase inhibitors including tenofovir and entecavir achieve sustained viral suppression through once-daily dosing. Demand concentrates in United States tertiary care centers managing complex chronic cohorts, driven by maintenance therapy protocols that extend treatment duration over decades.
- Immune Modulators:Finite-duration therapies targeting functional cure endpoints through toll-like receptor agonists and checkpoint modulation. Germany's university hospitals are expanding dedicated hepatology units to manage biomarker-intensive monitoring requirements, attracted by curative potential that promises to collapse chronic maintenance paradigms.
- Interferon:Injectable cytokine therapy with established but declining utilization due to tolerability limitations.
- Vaccines:Prophylactic immunization administered through national program infrastructure with minimal follow-up requirements.
By volume, Nucleos(t)ide Analogues leads. By growth pace, Immune Modulators is ahead.
End User:
Cost tier stratification separates high-complexity institutional settings from lower-acuity community delivery channels.
- Hospitals:Integrated delivery networks in California and Texas centralize formulary decisions through specialty pharmacy carve-outs, managing hepatitis B patient volumes exceeding ten thousand active cases per system. These institutions capture disproportionate margin concentration through infusion center economics and specialist-managed protocols.
- Clinics:Community hepatology practices in France and Italy are pre-positioning budget impact models around finite-duration therapy assumptions, adapting to EMA conditional marketing authorization frameworks.
- Outpatient Facilities:Ambulatory infusion centers with intermediate complexity requirements.
- Home Care:Remote monitoring platforms enabling specialist-managed care extension into residential settings.
By patient volume, Hospitals dominates. By expansion trajectory, Home Care is climbing the fastest.
Treatment Stage:
Application urgency shapes regulatory pathway selection and evidentiary threshold requirements across disease progression states.
- Chronic:Long-term antiviral suppression targeting cirrhosis prevention and hepatocellular carcinoma risk reduction. China's NMPA priority review channels are accelerating access for domestic innovators serving this prevalent cohort.
- Preventive:Pre- and post-exposure prophylaxis through vaccination and immunoglobulin administration. Nigeria, Kenya, and Ethiopia are expanding procurement eligibility through WHO prequalification pathways.
- Acute:Time-limited intervention during initial infection window.
- Recurrent:Re-treatment protocols following virologic breakthrough or relapse.
By prevalence, Chronic leads. By policy attention, Preventive is gaining share fastest.
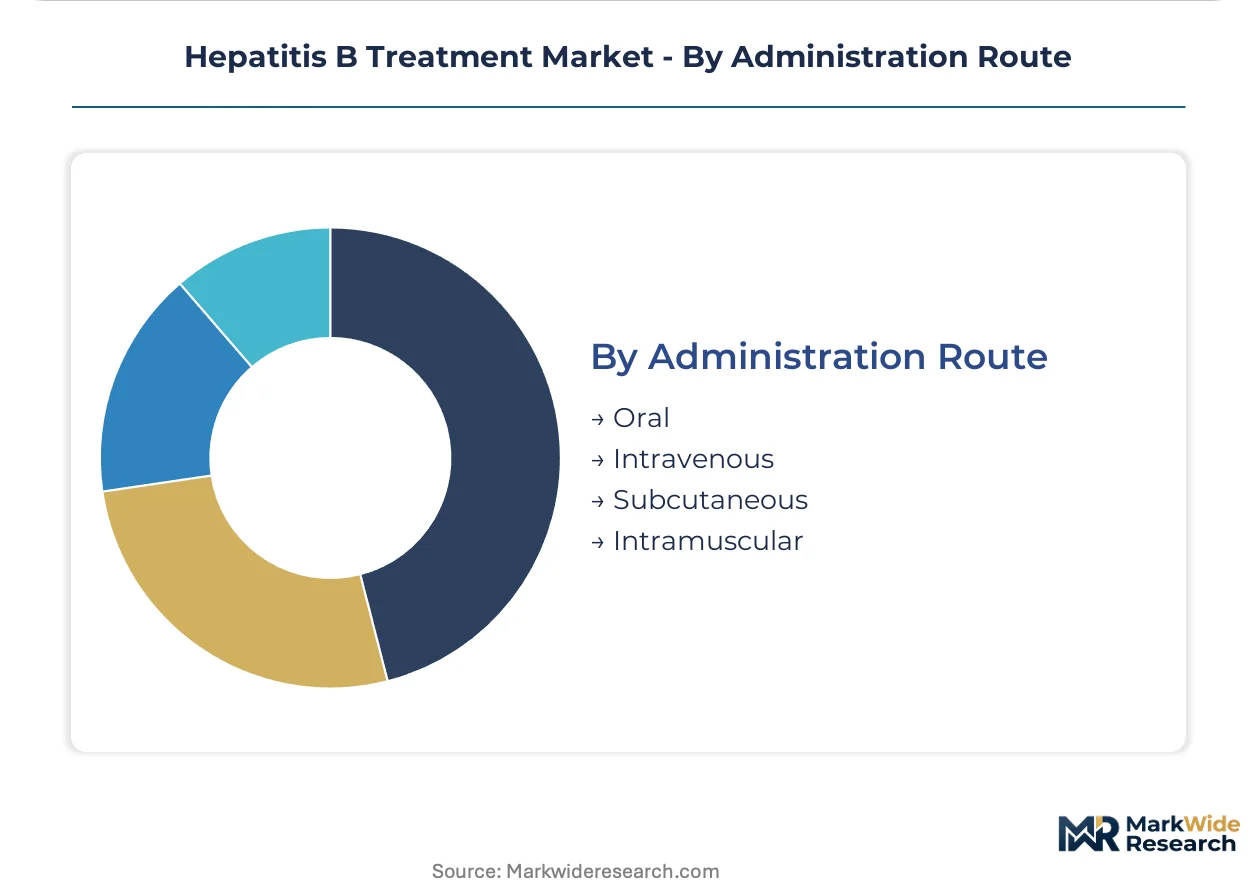
Administration Route:
Supply concentration in Zhejiang and Shandong provinces for active pharmaceutical ingredients creates geographic vulnerability that influences route-specific manufacturing economics.
- Oral:Once-daily tablet formulations dominate maintenance therapy. Tenofovir alafenamide maintains pricing power through formulation patents, while entecavir faces commoditization pressure from Indian manufacturers.
- Subcutaneous:Self-administered immune modulator delivery enabling outpatient functional cure protocols. Academic medical centers in Germany are integrating these agents into combination regimens ahead of formal approval.
- Intravenous:Hospital-based infusion for acute intervention and research protocols.
- Intramuscular:Vaccine delivery through standardized immunization infrastructure.
By prescription volume, Oral leads. By protocol innovation, Subcutaneous is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient production for tenofovir and entecavir concentrates heavily in eastern Chinese provinces, creating geographic vulnerability that shapes manufacturing economics across all major demand centers. Hospital procurement patterns in tertiary care systems drive differentiated pricing power by region.
United States
Tertiary care centers in California and Texas manage hepatitis B patient volumes exceeding ten thousand active cases per integrated delivery network, driving concentrated demand for nucleos(t)ide analogue maintenance protocols. FDA accelerated approval pathways compress development timelines for novel immune modulator mechanisms. Specialty pharmacy carve-outs in these states centralize formulary decisions and negotiating leverage.
China
Domestic innovators leverage NMPA priority review channels to secure faster market access for infectious disease therapies serving the world's largest chronic hepatitis B cohort. Biologics facility construction accelerates in Jiangsu and Guangdong provinces to serve domestic and export demand. Zhejiang and Shandong provinces host concentrated API production for global tenofovir and entecavir supply.
Germany
University hospitals expand dedicated hepatology units to manage biomarker-intensive monitoring requirements for finite-duration immune modulator therapies. EMA conditional marketing authorization frameworks adapt evidentiary thresholds to accommodate surrogate endpoints. Academic medical centers in Berlin and Munich integrate RNA interference agents into combination protocols ahead of formal approval.
Nigeria
National immunization programs expand procurement eligibility through WHO prequalification standards for hepatitis B vaccines serving birth-dose protocols. Federal Ministry of Health initiatives target vertical transmission interruption in high-prevalence states. Lagos and Kano metropolitan areas concentrate cold-chain distribution infrastructure for vaccine delivery.
Japan
PMDA review timelines for hepatitis B therapies align with global regulatory convergence on functional cure endpoints. METI industrial policy supports domestic biologics manufacturing capacity expansion. Osaka and Tokyo clusters concentrate specialist hepatology workforce and clinical trial site infrastructure.
Hepatitis B Treatment Market Competitive Environment
Large-cap pharmaceutical incumbents and mid-cap biotech specialists split the market into distinct capability tiers. Nucleos(t)ide analogue portfolios sustain revenue through chronic maintenance paradigms while immune modulator pipelines attract venture capital for functional cure development. Three archetypes dominate: established antiviral portfolio holders, immune-oncology platform extenders, and domestic Chinese innovators. Capacity expansion in biologics manufacturing and strategic partnerships for combination therapy development represent the dominant competitive moves.
Among established antiviral portfolio holders, Gilead Sciences and Bristol-Myers Squibb exemplify distinct strategic positions. Gilead Sciences occupies a position sustained through established regulatory dossiers across major markets. Bristol-Myers Squibb anchors immune modulator development with sustained clinical investment. Domestic Chinese innovator Ascletis Pharmaceuticals represents the emerging challenger archetype leveraging NMPA priority review channels.
| Leading Market Players |
|---|
| Merck & Co. |
| Arbutus Biopharma |
| Gilead Sciences |
| Antios Therapeutics |
| Vir Biotechnology |
| Bristol-Myers Squibb |
| Johnson & Johnson |
| Ascletis Pharmaceuticals |
| GlaxoSmithKline |
| Others |
Value Chain & Pricing Dynamics
Single-source API dependency on eastern Chinese provinces determines both the three-tier pricing structure across premium, standard, and economy levels and the geographic vulnerability of global tenofovir and entecavir supply. Environmental compliance disruptions in Zhejiang and Shandong directly compress margin spreads between originator formulations and commoditized alternatives.
Pricing Analysis
FDA accelerated approval pathways dictate the pricing tier structure for hepatitis B therapies, separating tenofovir alafenamide premium formulations protected by formulation patents from entecavir commoditization pressure emanating from Indian manufacturers. Price differentiation rests on bioequivalence certification tiers and hospital formulary positioning rather than clinical efficacy alone. Pricing pressure intensifies in the standard tier as domestic Chinese innovators leverage NMPA priority review channels to undercut multinational originators. Tertiary care centers in California and Texas integrated delivery networks exhibit lowest price sensitivity due to specialty pharmacy carve-out concentration, while community clinics in France and Italy face acute budget impact constraints from finite-duration therapy assumptions.
Supply Chain Analysis
Tariff exposure between China and major import markets dominates supply chain risk calculus for hepatitis B active pharmaceutical ingredients. API production concentrates in Zhejiang and Shandong provinces for tenofovir and entecavir, with secondary sourcing from Indian generic manufacturers in Hyderabad and Ahmedabad. Raw material dependencies span acyclic nucleoside phosphonate precursors, specialized fermentation media, and high-purity solvents subject to commodity volatility. Single-source vulnerability intensifies from environmental compliance enforcement actions by China's MEE. Distribution runs through hospital-based specialty pharmacy channels in the United States, centralized procurement by national immunization programs in Nigeria and Kenya, and regional biologics distribution hubs serving German university hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Functional cure development represents a high-growth disruption vector, with RNA interference therapeutics and capsid inhibitors collapsing the chronic maintenance paradigm that has sustained nucleos(t)ide analogue revenues for decades. FDA and EMA evidentiary adaptations for biomarker-based surrogate endpoints compress development timelines and restructure competitive entry economics.
For Market Incumbents: Build regulatory dossier moats through accelerated approval pathway pre-positioning for immune modulator combinations. Defensive consolidation moves center on backward integration into biologics manufacturing capacity in Jiangsu and Guangdong provinces to offset API supply concentration risk, plus specialist workforce cultivation through hepatology fellowship program endowments at tertiary care centers. The emerging threat of finite-duration functional cure protocols demands R&D allocation shifts away from incremental nucleos(t)ide analogue improvements. For New Entrants and Emerging Players: Build out telehepatology platform infrastructure to capture community clinic extension opportunities in France, Italy, and underserved United States rural markets. White-space targets concentrate on subcutaneous immune modulator delivery systems for outpatient functional cure protocols and WHO prequalification pathway navigation for vaccine access expansion in Nigeria, Kenya, and Ethiopia. The most penetrable segment spans biomarker-intensive monitoring services bundled with finite-duration therapy administration. For Investors and Strategic Acquirers: FDA functional cure endpoint guidance reshapes the acquisition landscape toward immune-oncology platform extenders with toll-like receptor agonist pipelines and capsid inhibitor assets. Long-term viability over the coming decade hinges on combination therapy development capabilities rather than single-mechanism assets. Target acquisition archetypes include mid-cap biotech specialists with EMA conditional marketing authorization experience and domestic Chinese innovators with NMPA priority review track records. The critical signal to watch is biomarker standardization convergence across FDA, EMA, and NMPA guidance documents.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Functional cure endpoint validation compresses development timelines for immune modulator candidates. |
| Regulatory Approval Pathway | NMPA priority review channels accelerate domestic Chinese innovator market access. |
| Manufacturing Scale-Up | Biologics facility construction in Jiangsu and Guangdong provinces expands export capacity. |
| Pipeline Diversification | RNA interference therapeutic integration creates novel mechanism synergies. |
| Strategic Partnership | Toll-like receptor agonist and capsid inhibitor combinations enable finite-duration regimens. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with drug development executives, regulatory affairs leads, hospital formulary directors, and payer access specialists; and secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and WHO prequalification databases. Bottom-up patient volume modeling across treatment stages and administration routes triangulated with top-down revenue estimates from disclosed pharmaceutical sales data.
Forecast inputs incorporated nucleos(t)ide analogue maintenance therapy adherence rates, immune modulator clinical trial progression probabilities, and regional regulatory approval timeline differentials across the projection horizon. Segmentation dimensions spanned product type, end user, treatment stage, and administration route, with CAGR derivation anchored in historic pricing trajectory analysis and patient cohort expansion patterns. Industry-specific inputs included hospital pharmacy committee formulary decision timelines and national immunization program procurement cycle phases.
Stress conditions across API supply disruption severity, functional cure trial failure rates, and reimbursement negotiation delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory pathway adaptations and evidentiary threshold evolution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Liraglutide Market
Pharmaceuticals
New Zealand Diabetes Drugs Market
Pharmaceuticals
Leuprolide Acetate Market
Pharmaceuticals
Omeprazole Market
Pharmaceuticals
Sulfonylureas Market
Pharmaceuticals
Global Oxytocic Pharmaceuticals Market
Pharmaceuticals
Cefdinir API Market
Pharmaceuticals
South Africa Insulin Drugs and Delivery Devices Market
Pharmaceuticals
G Protein Coupled Receptors (Gpcrs) Market
Pharmaceuticals
Alectinib Drugs Market
Pharmaceuticals
Gastrointestinal OTC Drugs Market
Pharmaceuticals
Global Cancer Vaccines Drug Pipeline Market
Pharmaceuticals
Anti-Infective Vaccines Market
Pharmaceuticals
Peptic Ulcer Drugs Market
Pharmaceuticals
Celiac Disease Drugs Market
Pharmaceuticals
Global Central Nervous System (CNS) Stimulant Drugs Market