
 Global Overall EUV Lithography Market | 2026-2036
Global Overall EUV Lithography Market Size, Share, and Industry Trends Forecast 2026-2036
Global Overall EUV Lithography Market Intelligence
The shift to High-NA EUV lithography is reorganizing the competitive landscape for leading-edge semiconductor manufacturing. ASML Holding NV exclusively controls the supply of commercial EUV scanner systems, creating a significant technological bottleneck. KLA Corporation specializes in the essential process control and inspection equipment required for EUV yield management. Meanwhile, Samsung Electronics Co. Ltd. leverages these advanced tools to produce next-generation logic and memory chips.
EUV lithography is an advanced optical process employing extreme ultraviolet light at a 13.5 nm wavelength to pattern silicon wafers. Its primary purpose is to enable the fabrication of transistor features at nodes below 7 nanometers, a critical step for modern microprocessors. The market's technology progression is defined by the transition to High-NA EUV systems for future scaling. Among applications, Logic Devices and advanced Memory Chips command the largest share of investment from Semiconductor Foundries.
Export control regulations, particularly from the United States and the Netherlands, heavily govern the sale and distribution of EUV systems to specific countries. Concurrently, manufacturing operations must adhere to international standards from bodies like the IEC for electrical equipment and comply with environmental directives such as the EU's RoHS. The ability to manage geopolitical risk and secure a position within this highly constrained supply chain will determine future market leadership.
Market Dynamics
The central force shaping the EUV lithography market is the extreme concentration of core technology, creating a critical bottleneck for the entire semiconductor industry. This single-point dependency for scanner systems is amplified by the immense capital investment required for each successive technological generation, such as High-NA EUV.
Growth Catalysts
- Next-Generation Logic:The fabrication of advanced processors for artificial intelligence and high-performance computing requires patterning at nodes only achievable with EUV, driving investment from leading foundries.
- Government Incentives:National industrial policies, including the US CHIPS Act and the EU Chips Act, provide significant financial support for establishing domestic, leading-edge semiconductor manufacturing capabilities.
- High-NA Transition:The technological roadmap towards sub-3-nanometer process nodes is entirely dependent on the adoption of High-NA EUV systems, creating a non-discretionary upgrade cycle for top-tier manufacturers.
Market Restraints
- Supplier Monoculture:An absolute single-supplier condition for commercial EUV scanner systems creates significant pricing power, long lead times, and a systemic risk for the entire semiconductor value chain.
- Extreme Capital Cost:The multi-hundred-million-dollar price tag for a single High-NA EUV system limits the addressable market to only the largest and best-capitalized semiconductor manufacturers.
- Export Controls:Geopolitical restrictions, particularly from the Netherlands and the United States, prohibit the sale of advanced lithography equipment to certain nations, fragmenting the market and limiting expansion.
Strategic Opportunities
- Advanced Packaging Integration:The use of EUV for patterning interconnects in chiplet-based designs and other advanced packaging formats represents a new application area beyond front-end-of-line logic and memory.
- EUV Pellicle Development:Creating more durable and transmissive pellicles to protect photomasks is a critical area for innovation, offering a significant opportunity for materials science and components firms.
- Emerging Foundry Locations:Government-backed initiatives to build new semiconductor foundry ecosystems in locations like India or Germany could create new pockets of demand for EUV tooling and support services.
Industry Challenges
- Specialized Talent Scarcity:A severe shortage of physicists, optical engineers, and service technicians with the requisite skills to install, calibrate, and maintain EUV systems constrains operational capacity.
- Yield Management Complexity:Controlling stochastic defects and ensuring high yields at extremely small feature sizes requires an ecosystem of advanced process control and metrology tools that must evolve with the scanners.
- Infrastructure and Power Demands:The substantial facility, cleanroom, and power requirements for operating EUV systems present a major engineering and financial challenge for semiconductor fabs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Overall EUV Lithography Market |
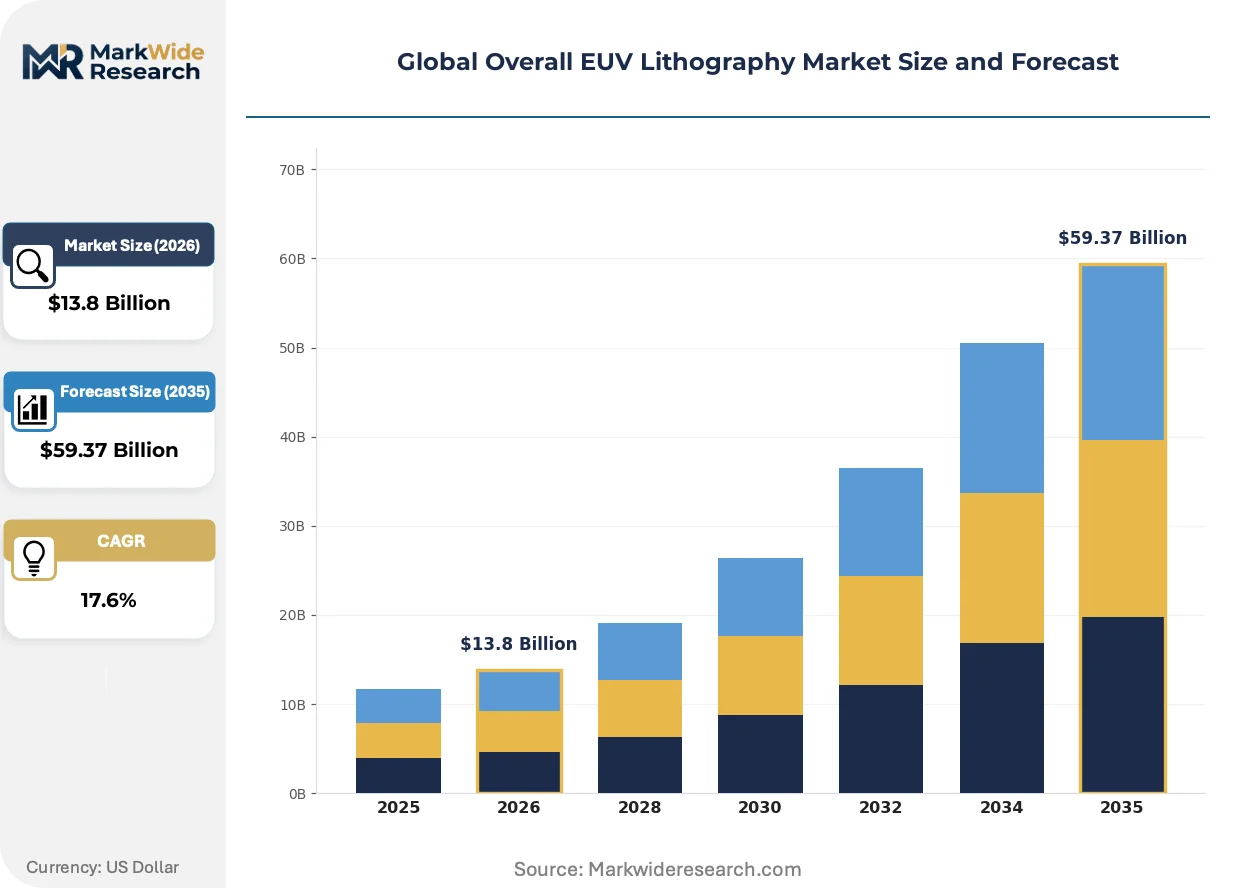
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $59.37 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: High-NA EUV, Medium-NA EUV, Step-and-Scan, Scanner Systems Application: Logic Devices, Memory Chips, Microprocessors, ASICs, SoCs End User Industry: Semiconductor Foundries, IDM Companies, Fabless Manufacturers, Packaging & Testing Firms Deployment Type: On-Premises Installation, Cloud-Integrated Platforms, Hybrid Systems, Remote Operation Solutions |
| Companies Covered | Canon Inc., NTT Advanced Technology Corporation, ASML Holding NV, Ushio Inc., ADVANTEST Corporation, Samsung Electronics Co. Ltd., Nikon Corporation, TOPPAN PHOTOMASKS, KLA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Overall EUV Lithography Market Strategic Shifts & Innovations
Intensifying technological demands for sub-2-nanometer logic are intersecting with a tightening geopolitical environment. This dynamic forces foundries to make long-term, high-stakes commitments to a supply chain governed by a few key technology holders and stringent export regulations.
High-NA Systems Displace Current-Generation EUV
High-NA EUV lithography, featuring a numerical aperture of 0.55, enables finer resolution for patterning critical layers in future chip designs. Leading-edge logic manufacturers in Taiwan and South Korea are the primary adopters, installing initial systems for process development. This shift to High-NA technology is displacing current 0.33 NA EUV systems for the most advanced nodes, enabling the industry's path to 2-nanometer manufacturing and beyond.
Heightened Export Control Scrutiny
National security-driven export controls from the United States and the Netherlands are increasingly strict, directly governing the sale of EUV systems. These regulations, aligned with frameworks like the Wassenaar Arrangement, restrict access to advanced lithography tools for specific entities, particularly in China. Semiconductor manufacturers must now embed geopolitical risk analysis into their long-range capital expenditure and supply chain planning.
Co-Development Models Alter Procurement
A transition toward collaborative development partnerships between foundries and fabless AI chip designers is reshaping equipment acquisition strategies. This approach moves beyond simple transactional purchases, creating deep integration where process technology is optimized for specific, high-value chip architectures. The trend is most pronounced in Taiwan's foundry ecosystem, where close collaboration with US-based design leaders accelerates the deployment of next-generation computing hardware.
Global Overall EUV Lithography Market Segmentation
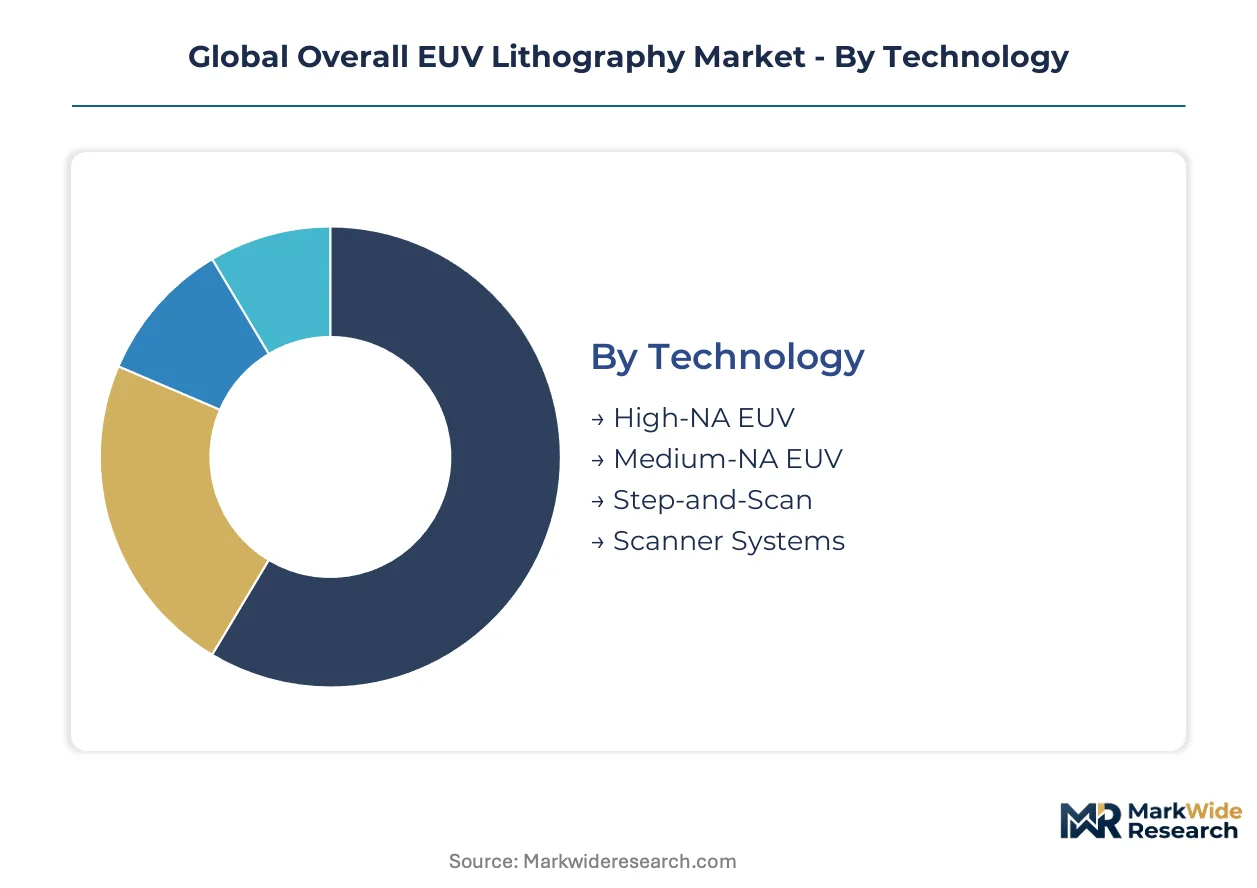
The Global Overall EUV Lithography Market segmentation illuminates the specialized technologies and strategic applications driving semiconductor manufacturing advancements. Understanding these distinct segments reveals how leading foundries and integrated device manufacturers deploy advanced patterning solutions. This granular analysis provides clarity on investment priorities and technological roadmaps within the industry.
Technology:
The distribution of EUV lithography systems depends heavily on the specific technological capabilities required by advanced semiconductor fabrication processes.
- High-NA EUV:These advanced systems feature a numerical aperture of 0.55, enabling patterning of features below 2 nanometers for next-generation logic. Demand for High-NA EUV concentrates in Taiwan and South Korea, driven by the need for sub-3-nanometer process nodes in AI and high-performance computing chip production.
- Scanner Systems:These are the core machines that project patterns onto silicon wafers using extreme ultraviolet light, forming the foundation of modern chip fabrication. Procurement of scanner systems is highly concentrated among a few major foundries, particularly in Taiwan, due to their immense capital cost and technical complexity.
- Medium-NA EUV:These systems, typically with a numerical aperture of 0.33, are employed for current-generation 7nm and 5nm process nodes.
- Step-and-Scan:This technique involves moving the wafer and reticle during exposure, ensuring uniform illumination and pattern transfer across the silicon substrate.
Medium-NA EUV systems dominate the current installed base for volume production. High-NA EUV is where expansion concentrates for future process nodes.
Application:
The volume of EUV lithography deployment directly correlates with the specific demands of advanced chip applications, influencing foundry investment strategies.
- Logic Devices:These are complex integrated circuits designed for processing and computation, including CPUs and GPUs, crucial for AI and high-performance computing. Investment in EUV for logic devices is heavily concentrated in leading semiconductor foundries in Taiwan and South Korea, driven by the relentless pursuit of smaller transistor geometries.
- Memory Chips:This segment includes DRAM and NAND flash, essential for data storage and retrieval in computing systems and mobile devices. Fabrication of advanced memory chips with EUV is a key focus for companies like Samsung Electronics Co. Ltd., pushing the boundaries of density and performance.
- Microprocessors:These central processing units execute instructions and manage computer operations, requiring precise patterning.
- ASICs:Application-Specific Integrated Circuits are custom-designed chips, demanding tailored EUV patterning for specialized functionalities.
- SoCs:Systems-on-Chip integrate multiple components, driving demand for advanced EUV to enable complex heterogeneous integration.
Demand for EUV lithography is broadly distributed across various chip types. However, the most intensive and complex patterning requirements arise from logic devices.
End User Industry:
The customer type significantly influences the scale and nature of EUV lithography procurement, reflecting distinct business models and capital expenditure capacities.
- Semiconductor Foundries:These companies specialize in manufacturing chips for other firms, requiring massive investments in EUV systems for leading-edge process nodes. Foundries like TSMC in Taiwan represent the largest purchasers of EUV equipment, driving the market for advanced logic and memory.
- IDM Companies:Integrated Device Manufacturers design, manufacture, and sell their own chips, necessitating in-house EUV capabilities for competitive differentiation. Samsung Electronics Co. Ltd. exemplifies an IDM leveraging EUV technology for both its logic and memory chip production.
- Fabless Manufacturers:These firms design chips but outsource manufacturing to foundries, indirectly driving EUV demand through their advanced design requirements.
- Packaging & Testing Firms:These companies perform post-fabrication processes, with some increasingly exploring EUV for advanced packaging interconnects.
Market share concentration for EUV equipment is highest among semiconductor foundries. IDM companies also hold significant purchasing power for this technology.
Deployment Type:
The maturity of EUV deployment types dictates the operational models adopted by chip manufacturers, balancing traditional infrastructure with emerging cloud-based solutions.
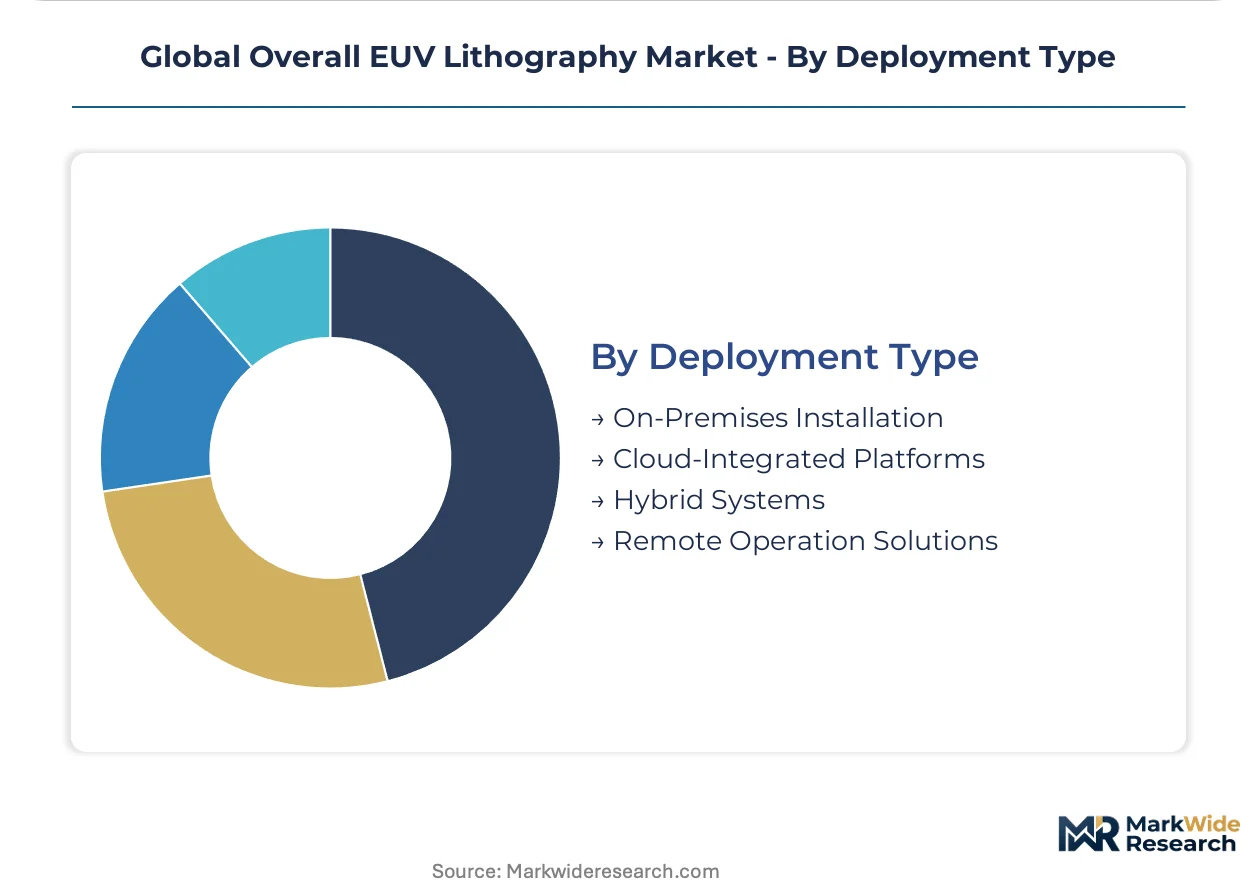
- On-Premises Installation:This traditional deployment involves physically housing EUV systems within a manufacturer's own cleanroom facilities, ensuring maximum control and security. The vast majority of EUV systems are deployed on-premises, particularly in high-volume production fabs in Taiwan and South Korea.
- Hybrid Systems:These deployments combine local EUV operations with cloud-based data management or computational support, offering flexibility for specific workflow requirements. Hybrid systems are gaining traction for process optimization and data analytics, especially in research and development environments.
- Cloud-Integrated Platforms:These platforms leverage cloud infrastructure for data analysis, simulation, and remote monitoring of EUV processes.
- Remote Operation Solutions:These solutions allow for off-site control and troubleshooting of EUV equipment, enhancing operational efficiency and technician support.
Adoption patterns for EUV deployment types heavily favor on-premises installations. However, hybrid systems represent a growing trend for data-intensive applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Netherlands exports highly advanced EUV lithography systems to key semiconductor manufacturing hubs globally, particularly in Asia. This critical technology transfer fuels the production of next-generation logic and memory chips. Foundries in Taiwan and South Korea represent the primary recipients of these specialized tools.
Taiwan
Taiwan's foundries demand High-NA EUV for AI and high-performance computing logic devices. US export controls influence the acquisition strategy for advanced lithography tools. Hsinchu Science Park and other major foundry sites in Taiwan drive significant investment in sub-3-nanometer process nodes.
South Korea
South Korea's integrated device manufacturers require EUV for advanced memory chips and leading-edge logic production. National industrial policies support the expansion of domestic semiconductor manufacturing capabilities. Major fabs in Gyeonggi Province are rapidly adopting High-NA EUV systems for future scaling.
United States
The United States drives demand for EUV through its advanced chip design firms and domestic manufacturing initiatives. The US CHIPS Act provides substantial financial support for establishing leading-edge semiconductor fabs. New facilities in Arizona and Texas are attracting significant investment for future EUV deployment.
Netherlands
Netherlands serves as the global hub for EUV system manufacturing and advanced lithography research. Dutch export controls heavily govern the distribution of these critical tools to specific nations. Veldhoven remains the core of EUV innovation, concentrating specialized talent and production capabilities.
Germany
Germany is positioning itself as an emerging foundry location, attracting investment for new semiconductor manufacturing capabilities. The EU Chips Act provides incentives for establishing advanced production facilities within the region. Dresden's Silicon Saxony cluster is expanding its infrastructure to support future EUV tooling and services.
Global Overall EUV Lithography Market Key Industry Players
Listed leaders compete with private specialists across the highly concentrated EUV lithography value chain. The market exhibits a tiered structure, with a single dominant supplier of core scanner systems creating a critical bottleneck. Strategic archetypes include equipment manufacturers, process control specialists, and advanced chip fabricators. Key competitive moves involve technology co-development partnerships, targeted capacity expansion, and securing positions within constrained supply chains.
Within the equipment manufacturing tier, ASML Holding NV represents the sole supplier of commercial EUV scanner systems, anchoring the entire market. KLA Corporation, a specialist in process control and inspection equipment, supports yield management and defect detection for advanced nodes, ensuring high-volume production. Samsung Electronics Co. Ltd., an integrated device manufacturer, exemplifies the end-user segment leveraging these advanced tools for both its leading-edge logic and high-density memory chips. These prominent entities collectively drive technological progression and strategic investment across the global semiconductor ecosystem.
| Leading Market Players |
|---|
| Canon Inc. |
| NTT Advanced Technology Corporation |
| ASML Holding NV |
| Ushio Inc. |
| ADVANTEST Corporation |
| Samsung Electronics Co. Ltd. |
| Nikon Corporation |
| TOPPAN PHOTOMASK |
| KLA Corporation |
| Others |
Cost & Logistics Intelligence
Multi-year lead times for advanced EUV systems directly influence the market's pricing power and deeply shape the supply chain configuration for next-generation logic.
Pricing Analysis
Industrial OEM buyers anchor the highly specialized, contract-based pricing for EUV systems. Price differentiation stems from the extensive customization required for specific fab integration and the comprehensive after-sales service bundles. Pricing exhibits upward pressure due to the immense R&D investments needed for each successive EUV generation and the single-source supplier condition. Leading semiconductor foundries demonstrate low price sensitivity, viewing EUV as a strategic imperative, while emerging fabs face higher cost barriers.
Supply Chain Analysis
Protracted lead times for EUV equipment introduce significant systemic risk within the semiconductor supply chain. Geographic supply concentration centers in the Netherlands for scanner systems, with specialized optics drawing from Japan and Germany. The market relies on ultra-pure materials and high-power laser sources as critical components for system functionality. Single-source vulnerability for core scanner systems represents a primary structural risk for global chip production. Downstream distribution runs directly from equipment manufacturers to major semiconductor foundries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EUV lithography market presents a significant service-attach opportunity, with process control and metrology software expanding faster than scanner hardware sales for advanced chip production.
For Market Incumbents: Fortify core technological leadership by deepening co-development partnerships with leading foundries in Taiwan and South Korea for High-NA EUV. Invest heavily in advanced materials science R&D for next-generation pellicles, mitigating a critical yield management threat. Address the specialized talent scarcity through dedicated training initiatives and academic collaborations to maintain operational capacity.
For New Entrants and Emerging Players: Anchor in specialized components, such as more durable EUV pellicles, or advanced process control solutions for stochastic defect management. The most penetrable segment lies within emerging foundry ecosystems in Germany, seeking localized support services. A viable go-to-market angle involves offering niche solutions that integrate seamlessly with existing ASML and KLA equipment.
For Investors and Strategic Acquirers: Carve-out targets emerge from large industrial conglomerates or integrated device manufacturers with non-core, but highly specialized, EUV-related IP. This market offers long-term viability, essential for sub-2-nanometer chip fabrication over the next decade. Acquisition archetypes include specialized materials science firms and advanced metrology startups. Increased government funding for domestic EUV component supply chains signals inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen Co-development Partnerships | Deepens process technology optimization for future logic devices. |
| Invest in Advanced Pellicle R&D | Enhances EUV system uptime and yield for leading foundries. |
| Launch Talent Development Programs | Ensures operational continuity for complex EUV installations. |
| Geographic Capacity Expansion (e.g., Germany) | Supports national semiconductor independence goals in Germany. |
| Enhance Metrology System Integration | Improves defect detection for sub-3-nanometer process nodes. |
Research Approach
The analysis maps High-NA EUV, Logic Devices, and Semiconductor Foundries, each validated through extensive primary interviews with industry executives. Foundry CTOs, equipment procurement leads, optical engineers, and materials scientists provided crucial insights. Secondary validation drew from SEC 10-K filings, SEMI reports, and academic lithography publications. This approach employed both bottom-up market sizing and top-down revenue validation.
Market outputs were cross-referenced against external benchmarks and historical growth patterns for consistency over the projection horizon. Segmentation dimensions modeled included technology, application, end user, deployment type, and process node roadmap. Compound annual growth rates derived from historical trends, projected technological adoption, and anticipated capital expenditure cycles. Key forecast inputs included foundry capital expenditure plans and process node adoption curves.
Decision-makers should treat outputs as directional under assumptions of continued technological progression and stable geopolitical landscape; material deviation would warrant model refresh. Forecasts reflect these assumptions. Escalating export controls or unforeseen breakthroughs represent key risk factors. Outputs are directional, not point estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Manufacturing
China Electronic Design Automation (EDA) Tools Market
Semiconductor Manufacturing
Surface Mount Technology (SMT) Market
Semiconductor Manufacturing
Photoresist Stripper Market
Semiconductor Manufacturing
Semiconductor and Electronic Parts Manufacturing Market
Semiconductor Manufacturing
EUV Lithography Service Market
Semiconductor Manufacturing
Silicon Wafer Reclaim Market
Semiconductor Manufacturing
Photomask Market
Semiconductor Manufacturing
Semiconductor Bonding Machine Market
Semiconductor Manufacturing
Silicon Turners Market
Semiconductor Manufacturing
Middle East and Africa Cell Manufacturing Market
Semiconductor Manufacturing
Chip Melting Furnace Market
Semiconductor Manufacturing
Battery Manufacturing Machines Market
Semiconductor Manufacturing
Global Wafer Cutting Fluids Market
Semiconductor Manufacturing
Medical Component Manufacturing Market
Semiconductor Manufacturing
High Purity Process Systems for Semiconductor Market
Semiconductor Manufacturing
Thin Film Semiconductor Deposition Market