
 Thin Film Semiconductor Deposition Market | 2026-2036
Thin Film Semiconductor Deposition Market Size, Share, and Industry Trends Forecast 2026-2036
Thin Film Semiconductor Deposition Market Intelligence
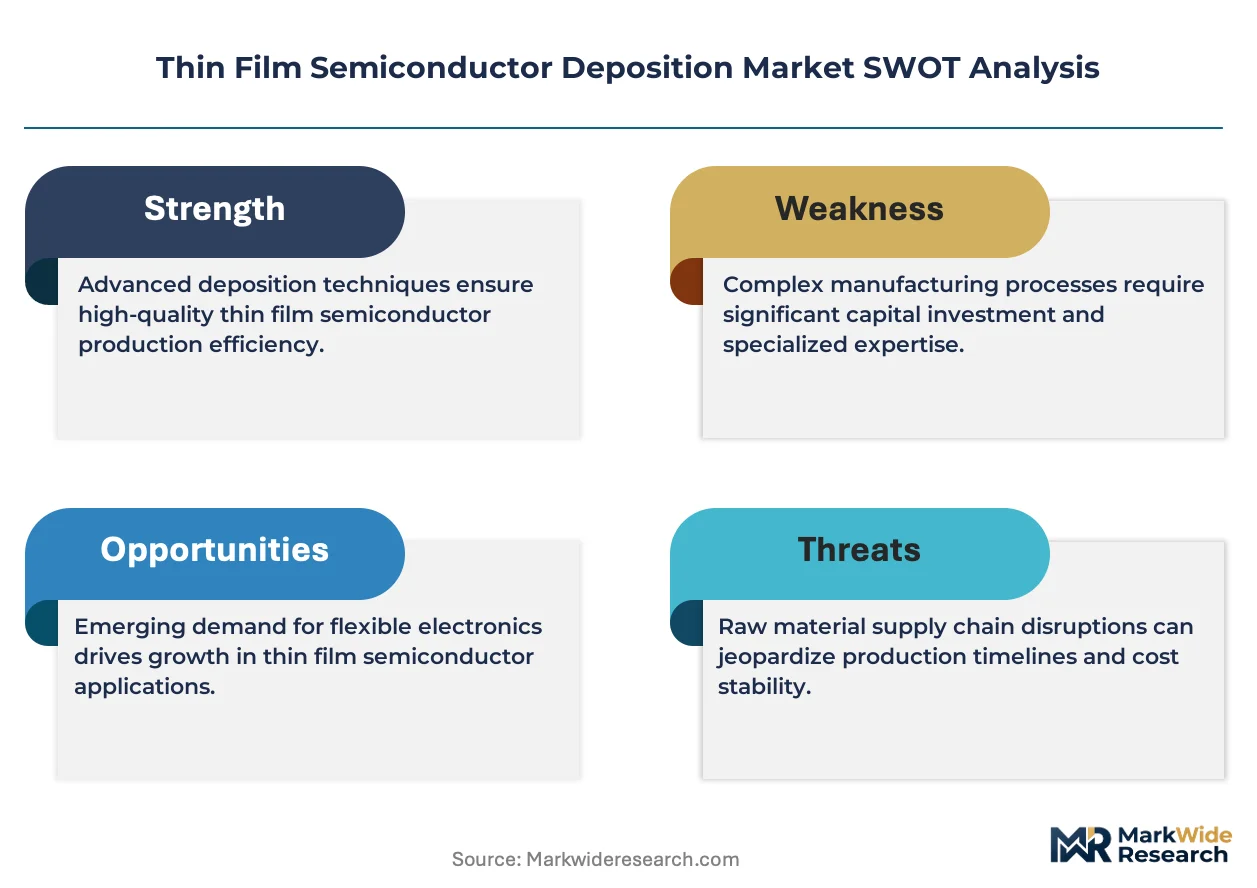
Software-defined process control is broadening what equipment vendors monetize beyond hardware shipments. Applied Materials sustains its position through extensive service contracts and predictive maintenance platforms. Tokyo Electron Limited leverages vertical integration into chamber subsystems to capture recurring revenue streams. Lam Research Corporation differentiates through proprietary plasma modeling software that locks customers into upgrade cycles.
Thin film semiconductor deposition encompasses the controlled application of material layers ranging from angstroms to micrometers onto wafer substrates through vacuum-based processes such as chemical vapor deposition and atomic layer deposition, enabling precise electrical, optical, or protective properties essential for integrated circuit fabrication. Physical vapor deposition retains mature margins in legacy nodes and specialty applications, while atomic layer deposition commands premium positioning for sub-7nm logic and 3D NAND vertical scaling where angstrom-level thickness control is mandatory. Chemical vapor deposition occupies the largest installed base across memory and logic foundries, though cluster tool configurations increasingly dominate high-volume manufacturing for their throughput advantages in single-wafer processing.
EPA regulations on fluorinated greenhouse gas emissions constrain CVD chamber chemistry choices in US fabrication facilities, while REACH authorization requirements in Europe restrict precursor chemical portfolios available to deposition equipment operators. Japan's METI enforces stringent export controls on advanced deposition equipment, directly shaping market access for frontier node technologies. Stakeholders must monitor how dual-use technology classifications and subsidy-linked domestic content rules in the United States, China, and the European Union redirect equipment procurement decisions across the semiconductor supply chain.
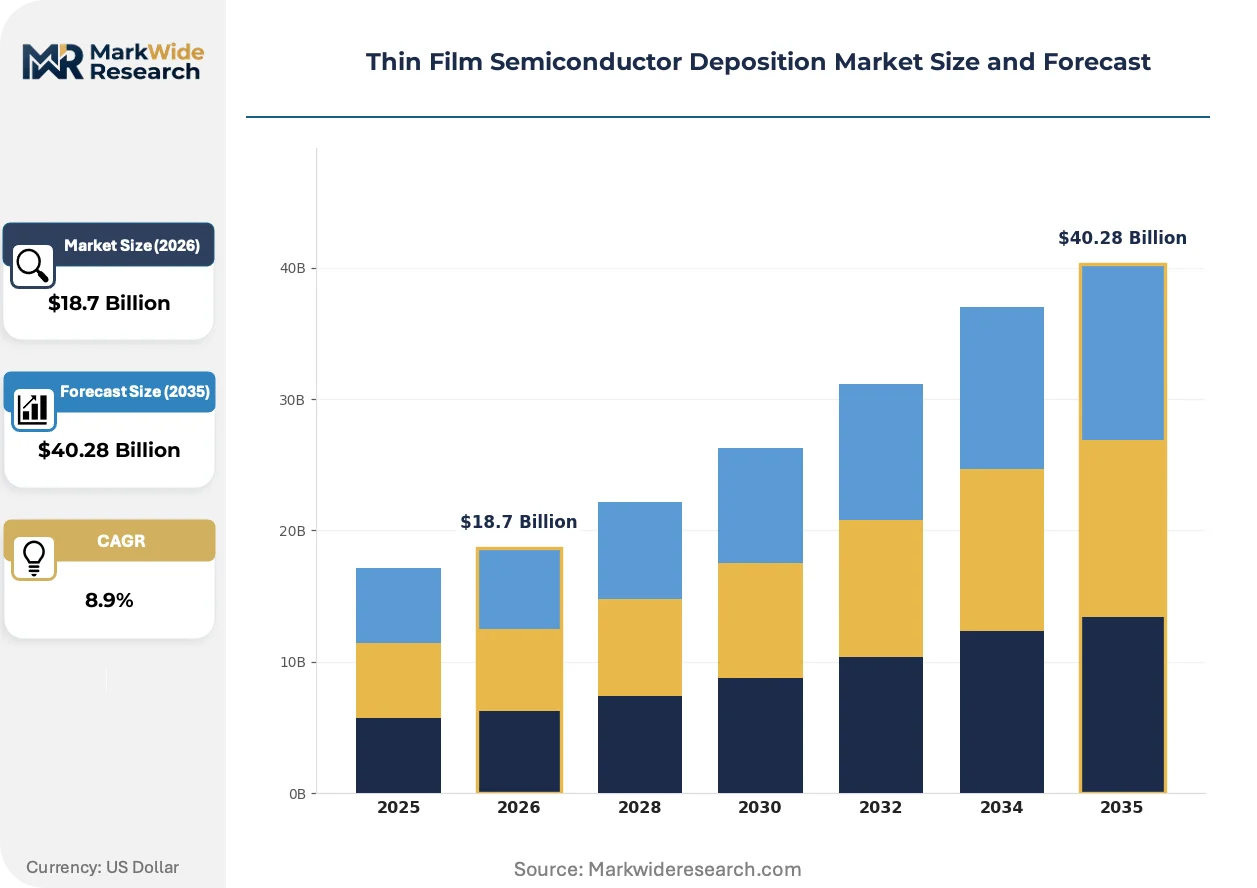
Market Dynamics
Foundry demand for sub-7nm logic nodes is compressing equipment refresh cycles as Taiwan, South Korea, and the United States compete for advanced semiconductor manufacturing capacity. This concentration of capital expenditure is reshaping how deposition equipment vendors structure service contracts and technology roadmaps.
Growth Catalysts
- 3D NAND vertical scaling:Memory manufacturers are stacking over 200 layers, creating insatiable demand for atomic layer deposition systems that deliver angstrom-level thickness uniformity.
- CHIPS Act incentives:Subsidy-linked domestic content requirements in the United States are redirecting procurement decisions toward localized equipment supply chains.
- Fluorinated gas restrictions:EPA emissions rules are forcing CVD chamber chemistry innovations that favor advanced precursor delivery systems.
Market Restraints
- Precursor supply concentration:Specialty chemical production for high-purity deposition precursors concentrates among German and Japanese suppliers, creating input vulnerability.
- Technical limitation in selectivity:Atomic layer deposition still struggles with area-selective deposition on complex 3D geometries without additional patterning steps.
- REACH authorization friction:ECHA chemical restrictions in Europe are eliminating legacy precursor portfolios faster than replacements achieve commercial scale.
Strategic Opportunities
- India's emerging fab ecosystem:The country's PLI scheme for semiconductor manufacturing is creating greenfield demand for deposition equipment without incumbent vendor lock-in.
- Power device silicon carbide:Automotive electrification is driving thermal CVD demand for wide-bandgap epitaxial layers on non-silicon substrates.
- Photonics packaging convergence:Silicon photonics integration with CMOS logic is opening deposition applications in optical waveguide fabrication.
Industry Challenges
- Process engineer scarcity:Atomic layer deposition expertise requires rare combinations of surface chemistry and vacuum systems knowledge that outpaces university pipeline output.
- Legacy cluster tool integration:New single-wafer ALD modules must interface with 1990s-era CVD platform architectures without throughput degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thin Film Semiconductor Deposition Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $40.28 Billion |
| CAGR (2026 – 2036) | 8.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deposition Technology: Physical Vapor Deposition, Chemical Vapor Deposition, Atomic Layer Deposition, Molecular Beam Epitaxy, Electrochemical Deposition Equipment Type: Batch Reactors, Inline Systems, Rotary Systems, Cluster Tools, Single Wafer Systems Application: Logic Devices, Memory Chips, Optoelectronics, Power Semiconductors, Sensors End User Industry: Consumer Electronics Manufacturers, Semiconductor Foundries, Telecommunications, Aerospace Technology, Defense Contractors |
| Companies Covered | ASM International NV, AIXTRON SE, Applied Materials, ULVAC, Canon Anelva Corporation, Tokyo Electron Limited, Veeco Instruments Inc., Hitachi High-Tech Corporation, Lam Research Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thin Film Semiconductor Deposition Market Strategic Shifts & Innovations
Software-defined process control is redefining how deposition equipment creates value, shifting vendor monetization from hardware shipments toward predictive maintenance platforms and recipe optimization services. This transformation is accelerating as fabs seek to extract more utilization from existing installed bases.
Plasma-enhanced atomic layer deposition is expanding into high-aspect-ratio contact and via filling for sub-3nm logic nodes. Memory foundries in South Korea are adopting this technology for replacement metal gate stacks. The structural consequence is compressing thermal ALD market share in front-end-of-line applications where temperature sensitivity limits conventional approaches.
Japan's METI export controls on advanced deposition equipment are fragmenting technology access across geopolitical blocs. Equipment classified as dual-use now requires case-by-case licensing for frontier node capabilities. Chinese memory manufacturers are responding by accelerating domestic tool qualification timelines and accepting performance gaps in non-critical layers.
Service contract unbundling is reshaping how fabs procure deposition equipment lifecycle support. Tier-one foundries in Taiwan are negotiating predictive maintenance subscriptions separate from hardware purchases, displacing traditional break-fix service agreements. This shift is most visible in 300mm high-volume manufacturing where unplanned chamber downtime costs exceed $100,000 per hour.
Thin Film Semiconductor Deposition Market Segmentation
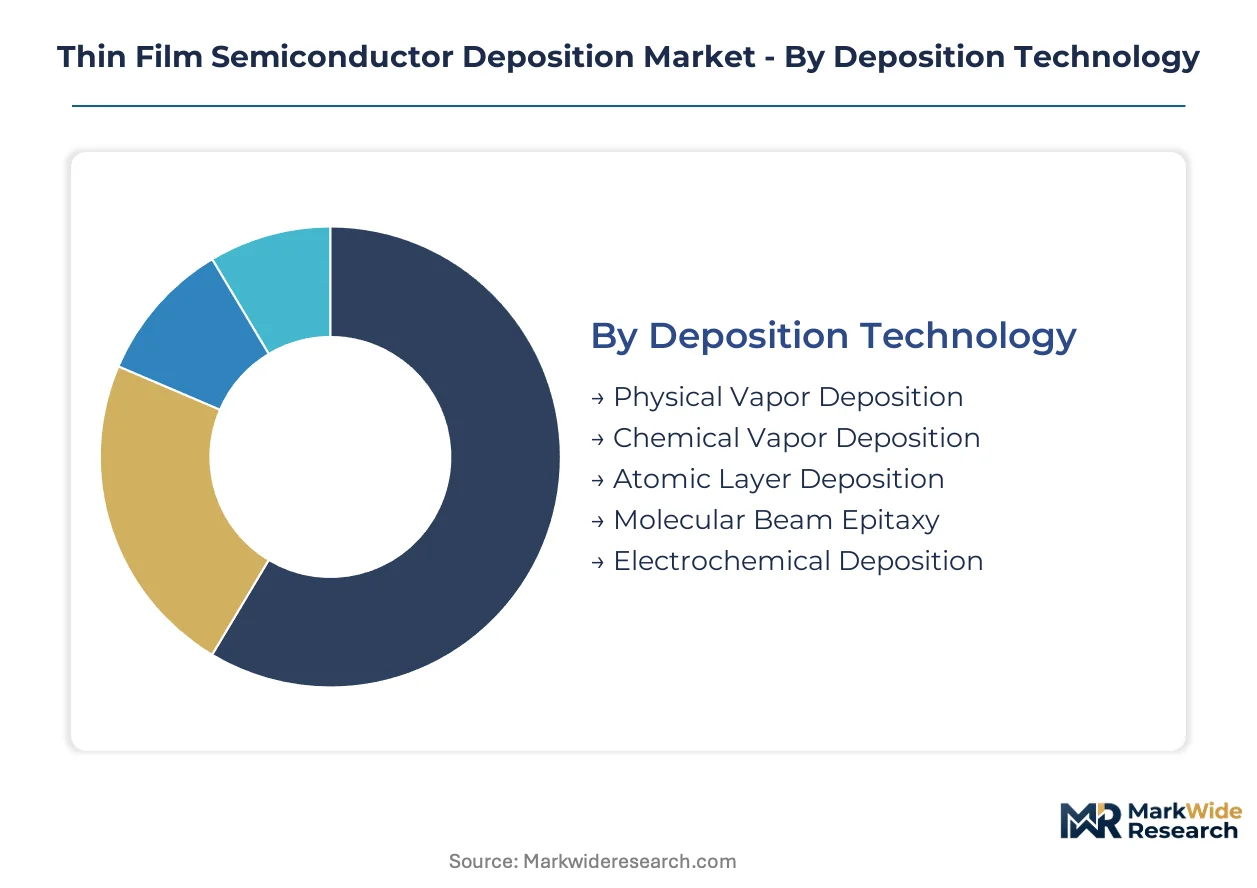
Segmentation in thin film semiconductor deposition equipment reveals how technology choices cascade through procurement decisions. Equipment vendors structure product portfolios around deposition physics, wafer handling architecture, and end-use thermal budgets.
Deposition Technology:
Thickness control precision and conformality requirements determine technology selection across logic and memory fabs.
- Physical Vapor Deposition:Sputtering and evaporation techniques deposit metal interconnects and barrier layers through momentum transfer in high-vacuum environments. Taiwan and South Korea foundries deploy PVD extensively for mature node aluminum and titanium nitride stacks where cost-per-wafer optimization outweighs atomic-scale precision requirements.
- Chemical Vapor Deposition:Gas-phase precursor decomposition builds dielectric and conductive films with superior step coverage over topography. Memory manufacturers in the United States and Japan favor thermal CVD for silicon dioxide and silicon nitride interlayer dielectrics in 3D NAND fabrication, driven by throughput demands in high-volume manufacturing.
- Atomic Layer Deposition:Sequential self-limiting surface reactions enable angstrom-level thickness uniformity for sub-7nm logic nodes. South Korean memory fabs are the primary demand center for high-k metal gate and capacitor dielectric applications.
- Molecular Beam Epitaxy:Ultra-high vacuum evaporation of elemental sources produces crystalline compound semiconductor layers for photonics and RF devices. Defense contractors in the United States specify MBE for gallium arsenide and indium phosphide epitaxy in radar and satellite communications.
- Electrochemical Deposition:Electroplating chemistry deposits copper interconnects with bottom-up fill characteristics for damascene processing. Semiconductor foundries in Taiwan rely on ECD for back-end-of-line metallization where bulk fill rates determine manufacturing economics.
Mature deployment sits with Chemical Vapor Deposition. Newer deployment is concentrated in Atomic Layer Deposition.
Equipment Type:
Wafer throughput and process integration complexity drive capital allocation between batch and single-wafer architectures.
- Batch Reactors:Simultaneous processing of 25-200 wafers minimizes cost-per-wafer for thick films with relaxed uniformity specifications. Japanese power semiconductor manufacturers deploy batch thermal oxidation and LPCVD systems for silicon carbide epitaxy where process time dominates economics.
- Inline Systems:Continuous wafer transport through sequential process zones suits high-volume solar cell and display manufacturing. Chinese photovoltaic producers represent the primary installed base for inline PVD and CVD platforms.
- Rotary Systems:Cylindrical substrate carriers enable uniform precursor distribution for batch ALD of conformal coatings. Aerospace technology suppliers in Germany utilize rotary ALD for turbine blade thermal barrier coatings.
- Cluster Tools:Central wafer handling robots integrate multiple process chambers for sequential deposition without vacuum break. Taiwan foundries standardize on cluster tool configurations for copper barrier-seed-capping film stacks.
- Single Wafer Systems:Individual wafer processing enables precise temperature and precursor dose control for advanced node applications. South Korean memory manufacturers deploy single-wafer ALD exclusively for high-aspect-ratio 3D NAND channel and gate stack formation.
Volume concentration favors Cluster Tools. Process control differentiation concentrates in Single Wafer Systems.
Application:
Device architecture complexity and layer count determine deposition equipment specifications and service intensity.
- Logic Devices:FinFET and gate-all-around transistor geometries demand multi-layer high-k dielectric and metal gate stacks with sub-nanometer thickness control. Taiwan and United States foundries drive equipment refresh cycles for sub-3nm node development.
- Memory Chips:3D NAND vertical scaling exceeds 200 layers, requiring alternating deposition and etch sequences with extreme aspect ratio conformality. South Korean and Japanese manufacturers consume the majority of atomic layer deposition capacity for this application.
- Optoelectronics:III-V compound semiconductor epitaxy for lasers and photodetectors requires ultra-high vacuum deposition with precise stoichiometry control. Telecommunications equipment vendors in the United States and Germany specify MBE and MOCVD platforms.
- Power Semiconductors:Wide-bandgap silicon carbide and gallium nitride epitaxy operates at elevated temperatures with specialized precursor chemistries. Automotive electrification in Germany and Japan accelerates thermal CVD demand for vertical power devices.
- Sensors:MEMS and image sensor fabrication combines sacrificial and structural film deposition with release etch compatibility. Consumer electronics manufacturers in Japan and South Korea integrate deposition tools with MEMS-specific handling systems.
Equipment utilization intensity peaks in Memory Chips. Technology refresh frequency runs highest in Logic Devices.
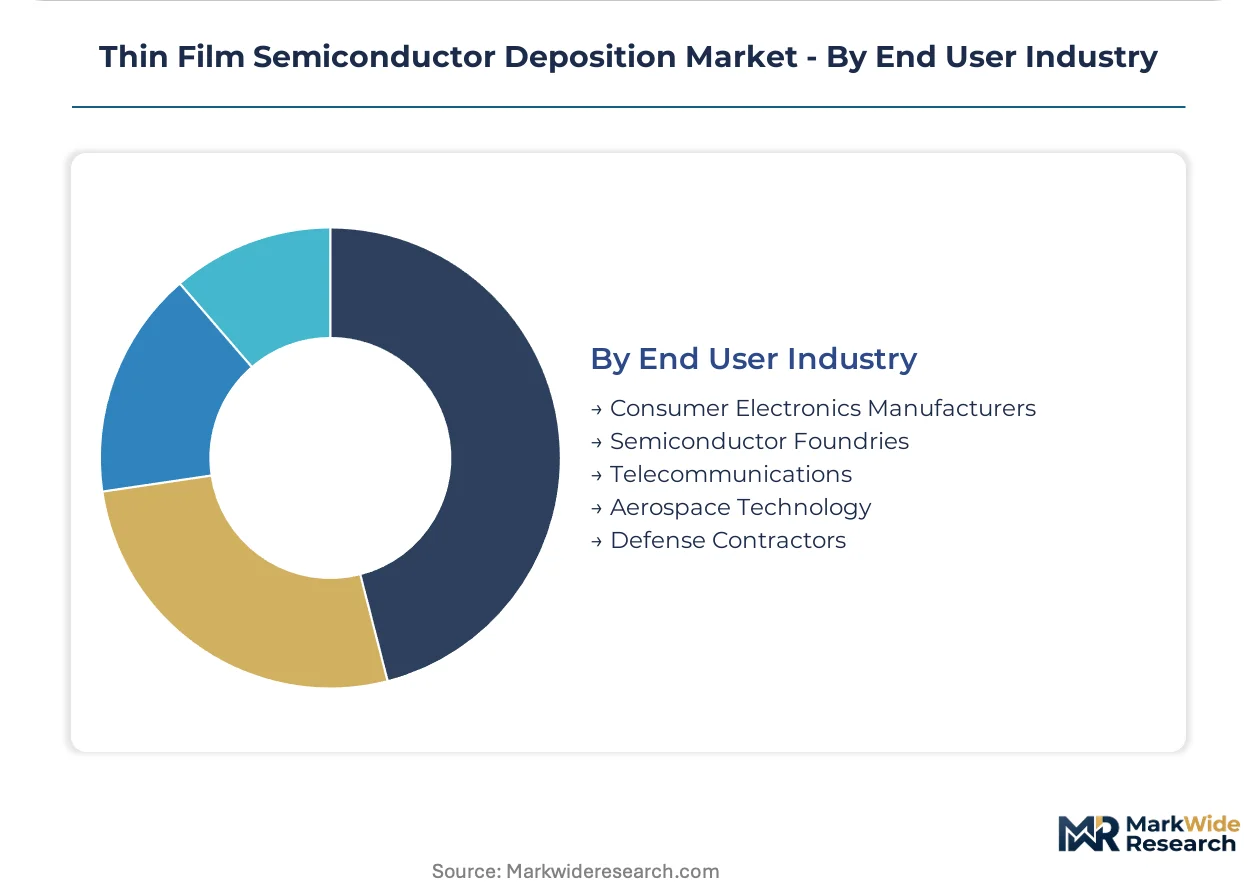
End User Industry:
Procurement authority and volume concentration vary significantly across customer categories, shaping vendor sales engagement models.
- Consumer Electronics Manufacturers:Fabless design houses and IDMs with captive fabrication source deposition equipment through turnkey fab construction contracts. Apple and Samsung supplier ecosystems in Taiwan and South Korea drive coordinated equipment procurement.
- Semiconductor Foundries:Pure-play foundries operate the largest installed bases and negotiate enterprise service agreements with predictive maintenance provisions. TSMC and Samsung Foundry in Taiwan and South Korea set technology roadmaps that equipment vendors must align with.
- Telecommunications:5G base station and optical network component suppliers require compound semiconductor epitaxy equipment for RF and photonic integration. Ericsson and Nokia supply chains in Sweden and Finland specify European deposition tool suppliers.
- Aerospace Technology:Satellite and avionics semiconductor applications demand radiation-hardened device fabrication with specialized deposition processes. NASA and ESA contractors in the United States and France operate small-volume, high-mix fabrication lines.
- Defense Contractors:Classified programs for radar and electronic warfare systems drive secure supply chain requirements for domestic deposition equipment. Raytheon and Lockheed Martin suppliers in the United States face ITAR and export control compliance obligations.
Contract value concentration sits with Semiconductor Foundries. Procurement cycle volatility runs highest in Defense Contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment consumption concentrates in Taiwan, South Korea, and the United States where foundries operate the newest fabrication lines. Production of deposition systems remains anchored in Japan, the Netherlands, and the United States. This geographic split creates procurement dependencies that national subsidy programs actively reshape.
United States
CHIPS Act incentives are redirecting capital expenditure toward domestic fabrication capacity in Arizona, Texas, and New York. EPA fluorinated greenhouse gas regulations constrain CVD chamber chemistry choices at Intel and GlobalFoundries facilities. Applied Materials and Lam Research anchor equipment supply from Santa Clara, California, while new fab construction in Phoenix and Albany drives installation demand.
Taiwan
TSMC's sub-3nm node development compresses equipment refresh cycles for atomic layer deposition systems. The island's national science council coordinates technology roadmaps with vendor qualification timelines. Hsinchu Science Park hosts the densest concentration of 300mm high-volume manufacturing, where unplanned chamber downtime costs exceed $100,000 per hour.
South Korea
Samsung and SK Hynix are stacking over 200 layers in 3D NAND, creating insatiable demand for ALD thickness uniformity. MFDS chemical safety requirements align with REACH precursor authorization standards for import compliance. Pyeongtaek and Icheon fabrication complexes represent the primary demand center for high-k metal gate and capacitor dielectric applications.
Japan
Tokyo Electron and Canon Anelva manufacture deposition equipment for export under METI dual-use technology licensing. Export controls on frontier node capabilities fragment technology access across geopolitical blocs. Hiroshima and Kyoto production facilities supply cluster tool architectures to memory foundries in South Korea and Taiwan.
China
Domestic memory manufacturers accelerate tool qualification timelines to offset restricted access to Japanese and Dutch equipment. MIIT industrial policy targets captive supply of deposition systems for mature nodes by 2027. Yangtze Memory Technologies in Wuhan accepts performance gaps in non-critical layers while building parallel supplier relationships.
Thin Film Semiconductor Deposition Market Key Industry Players
Capital-heavy equipment manufacturers compete with asset-light process technology licensors for value capture in thin film deposition. The market structure consolidates around three Japanese and two American vendors controlling over 70% of advanced node shipments. Two strategic archetypes dominate: integrated platform vendors bundling hardware with predictive maintenance subscriptions, and specialized chamber subsystem suppliers capturing recurring revenue through vertical integration. Competitive moves center on unbundling service contracts from hardware sales and securing precursor chemical partnerships.
Within the integrated platform tier, Applied Materials and Lam Research occupy positions defined by software-defined process control monetization. Tokyo Electron Limited anchors the Japanese vendor cluster with extensive service contract penetration. ASM International NV represents the specialized ALD equipment archetype. These three companies exemplify how vendor positioning shifts from hardware shipment volumes toward lifecycle value extraction.
| Leading Market Players |
|---|
| ASM International NV |
| AIXTRON SE |
| Applied Materials |
| ULVAC |
| Canon Anelva Corporation |
| Tokyo Electron Limited |
| Veeco Instruments Inc. |
| Hitachi High-Tech Corporation |
| Lam Research Corporation |
| Others |
Cost & Logistics Intelligence
Semiconductor foundries in Taiwan and South Korea anchor procurement volume and negotiate enterprise service agreements with predictive maintenance subscriptions displacing traditional hardware-centric pricing. This buyer concentration compresses margins for equipment vendors while creating pricing power for precursor chemical suppliers with captive process knowledge.
Pricing Analysis
Cost-down pressure on thermal CVD systems accelerates because memory manufacturers prioritize throughput economics over precision specifications for interlayer dielectric applications. Pricing stratifies across single-wafer ALD premium tiers, cluster tool standard configurations, and batch reactor economy offerings for power semiconductor epitaxy. Price differentiation hinges on chamber subsystem certification level and predictive maintenance bundling intensity. Memory chip manufacturers exhibit highest price sensitivity due to cyclical capital expenditure constraints, while defense contractors accept premium positioning for ITAR-compliant domestic sourcing.
Supply Chain Analysis
Equipment qualification timelines governed by METI export licensing and EPA fluorinated gas certifications gate market access for frontier node capabilities. Manufacturing concentrates in Japan, the Netherlands, and the United States, while specialty precursor production draws from German and Japanese chemical suppliers. High-purity gas distribution and ceramic heater components create single-source vulnerability for advanced ALD platforms. Distribution runs through direct sales teams for tier-one foundries and regional representatives for emerging fab ecosystems in India and Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Atomic layer deposition systems are displacing thermal CVD for sub-7nm logic and 3D NAND vertical scaling, compressing refresh cycles and reshaping vendor competitive positioning around software-defined process control monetization.
For Market Incumbents: Acquire predictive maintenance platform capabilities and precursor chemical formulation expertise to lock customers into recurring revenue streams. Defend against Chinese domestic tool qualification acceleration by deepening service contract penetration at Taiwan and South Korean foundries. Prioritize backward integration into chamber subsystems to capture margin currently flowing to specialized component suppliers. For New Entrants and Emerging Players: The premium-to-economy pricing gap in batch thermal oxidation systems for silicon carbide power devices offers white-space entry without direct competition from established ALD vendors. Target India's PLI-linked greenfield fab construction where incumbent vendor relationships remain unformed. Pursue joint development agreements with domestic memory manufacturers in China seeking qualified alternatives to restricted Japanese equipment. For Investors and Strategic Acquirers: The window for entry favors specialized ALD chamber subsystem suppliers with proprietary plasma modeling software and established foundry qualification records. Long-term viability rests on capturing lifecycle value extraction as hardware shipment growth moderates. Watch for METI licensing expansion or contraction as the inflection signal for Japanese vendor market access and corresponding valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Launch | Applied Materials and Lam Research monetize software subscriptions beyond hardware shipments to TSMC and Samsung Foundry. |
| Precursor Chemical Backward Integration | Tokyo Electron captures margin from German and Japanese specialty gas suppliers while securing supply chain control. |
| Domestic Equipment Qualification Acceleration | Yangtze Memory Technologies and CXMT reduce dependence on METI-licensed Japanese tools for mature node production. |
| India Greenfield Fab Partnership | ASM International and ULVAC establish early relationships with Tata Electronics and ISMC Digital without incumbent displacement costs. |
| Silicon Carbide Epitaxy Capacity Expansion | AIXTRON and Veeco Instruments address automotive electrification demand from Bosch and Infineon for wide-bandgap power devices. |
Research Approach
Multi-period observation of equipment shipment patterns, foundry capital expenditure announcements, and precursor chemical trade flows anchored the trend analysis, supplemented by interviews with deposition equipment product managers, fab process engineering directors, semiconductor procurement leads, and specialty chemical supply chain managers. Secondary validation drew from SEC 10-K filings, METI export licensing disclosures, EPA fluorinated gas emission reports, and customs trade data. Bottom-up wafer demand modeling and top-down equipment spending forecasts were triangulated to constrain projection ranges.
Input-output matrices mapped deposition technology adoption to end-use device layer counts across the projection horizon, with segmentation dimensions spanning deposition physics, wafer handling architecture, and thermal budget requirements. CAGRs were derived from equipment unit forecasts multiplied by average selling price trajectories informed by service contract unbundling trends. Forecast inputs incorporated 3D NAND layer stacking roadmaps from Samsung and SK Hynix, plus sub-3nm logic node timelines from TSMC and Intel.
Inputs from primary stakeholder interviews and regulatory filing databases were available through the study window; gaps in Chinese domestic tool performance benchmarking and classified defense program specifications introduce uncertainty bands around frontier node adoption assumptions. Forecasts reflect documented assumptions regarding METI licensing continuity and CHIPS Act disbursement pacing. A model refresh is warranted upon material change in EPA fluorinated gas regulation stringency or METI dual-use technology classification expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Manufacturing
Global Overall EUV Lithography Market
Semiconductor Manufacturing
Silicon Turners Market
Semiconductor Manufacturing
IC CMP Slurries and Pads Market
Semiconductor Manufacturing
Global EUV Lithography Market
Semiconductor Manufacturing
Photoresist and Photoresist Ancillaries Market
Semiconductor Manufacturing
PCB Photoresist Market
Semiconductor Manufacturing
Silicon Wafer Reclaim Market
Semiconductor Manufacturing
High Purity Process Systems for Semiconductor Market
Semiconductor Manufacturing
China Electronic Design Automation (EDA) Tools Market
Semiconductor Manufacturing
Battery Manufacturing Machines Market
Semiconductor Manufacturing
Solder Paste Market
Semiconductor Manufacturing
Photoresist Stripper Market
Semiconductor Manufacturing
Advanced Process Control Market
Semiconductor Manufacturing
United States Photoresist and Photoresist Ancillaries Market
Semiconductor Manufacturing
Malaysia and Thailand Precession Cleaning for Electronic Market
Semiconductor Manufacturing
Surface Mount Technology (SMT) Market