
 Photomask Market | 2026-2036
Photomask Market Size, Share, and Industry Trends Forecast 2026-2036
Photomask Market Intelligence
Automotive semiconductor demand is restructuring the photomask procurement landscape as electric vehicle powertrain and advanced driver-assistance systems require mature-node and leading-edge chips simultaneously. Photronics Inc. leverages its captive mask blank supply to secure delivery timelines for foundry customers. Toppan Photomasks Inc. anchors its position through deep ultraviolet and extreme ultraviolet process specialization across Asian manufacturing corridors. HOYA Corporation dominates high-end quartz substrate production, giving it upstream control over mask blank quality tiers.
A photomask is a fused silica or quartz substrate coated with patterned chrome or molybdenum silicide film, manufactured through electron beam or laser writing followed by etch and repair steps, serving as the master template for transferring circuit geometries onto semiconductor wafers via lithographic projection. Phase shift masks command premium positioning as resolution enhancement techniques become mandatory at nodes below seven nanometers, while extreme ultraviolet lithography masks require entirely distinct pellicle and blank architectures that concentrate margin pools among qualified suppliers. Binary masks retain volume leadership in mature-node integrated circuits and flat panel display applications where cost sensitivity overrides resolution demands.
The United States Environmental Protection Agency regulates chrome etching effluents from mask fabrication facilities, while Japan's Ministry of Economy, Trade and Industry coordinates extreme ultraviolet infrastructure investments through national semiconductor programs. South Korea's Ministry of Trade, Industry and Energy ties photomask supplier qualification to domestic foundry expansion timelines, shaping regional supply security priorities. Stakeholders must monitor which regulatory frameworks accelerate domestic mask manufacturing capacity versus those that restrict chemical process inputs.
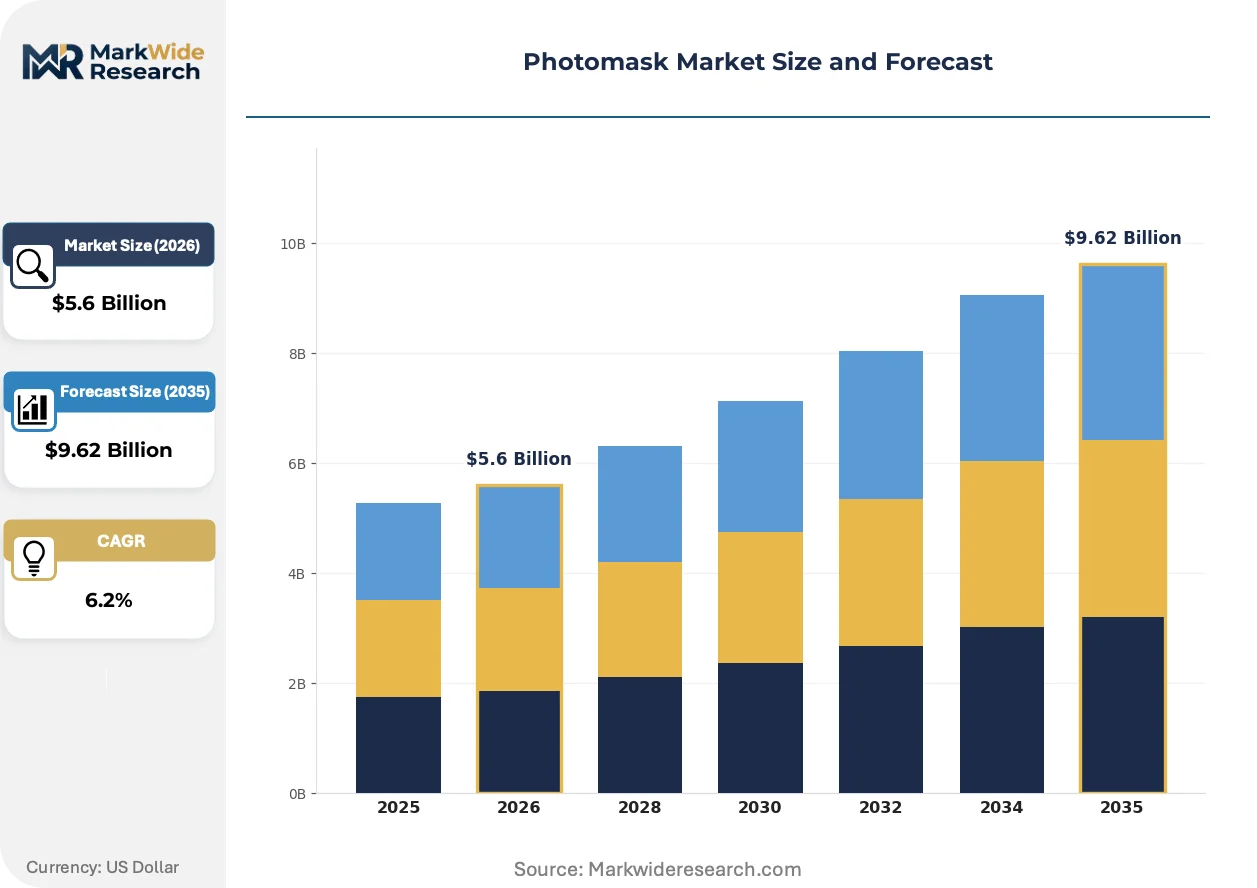
Market Dynamics
Extreme ultraviolet lithography adoption at sub-seven-nanometer nodes is restructuring photomask complexity tiers and concentrating qualified supplier pools among captive mask blank producers.
Growth Catalysts
- Automotive semiconductor proliferation:Electric vehicle powertrains and advanced driver-assistance systems require simultaneous procurement of mature-node and leading-edge photomasks, expanding foundry order books across process generations.
- REACH chemical compliance:European Union regulations on chrome etching effluents are accelerating closed-loop recycling investments at fabrication facilities, reducing environmental liability exposure for qualified suppliers.
- Hsinchu-Giheung cluster concentration:Taiwan's Science Park and South Korea's foundry corridor anchor photomask demand density, creating localized economies of scale in mask blank logistics and repair services.
Market Restraints
- High-purity quartz substrate scarcity:Synthetic fused silica ingot production concentrates among Japanese and German suppliers, creating input bottlenecks for advanced extreme ultraviolet blanks.
- Extreme ultraviolet pellicle fragility:Technical limitations in membrane durability under high-power source illumination restrict mask lifetime and elevate replacement frequency costs.
- EPA chrome discharge limits:United States Environmental Protection Agency effluent regulations impose capital-intensive wastewater treatment requirements on domestic fabrication facilities.
Strategic Opportunities
- India semiconductor manufacturing incentives:Production-linked incentive schemes for domestic foundry construction create qualification pathways for mask suppliers establishing local repair and metrology operations.
- Phase shift mask retrofitting:Resolution enhancement technology convergence with deep ultraviolet immersion lithography extends optical lithography viability at legacy nodes, preserving equipment utilization rates.
- Flat panel display pivot:Large-area photomask demand from organic light-emitting diode and quantum dot manufacturing diversifies revenue streams beyond semiconductor applications.
Industry Challenges
- Electron beam lithography technician scarcity:Specialized mask writing and repair skills require multi-year apprenticeship pipelines that lag current capacity expansion timelines.
- Extreme ultraviolet blank defect detection:Sub-nanometer particle inspection demands capital-intensive actinic inspection tools with limited installed base and extended procurement lead times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photomask Market |
| Market Size in 2026 | $5.6 Billion |
| Market Size in 2035 | $9.62 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Binary Masks, Phase Shift Masks, Attenuated Phase Shift Masks, Immersion Masks Technology: Extreme Ultraviolet Lithography, Deep Ultraviolet Lithography, Electron Beam Lithography, X-Ray Lithography End User: Semiconductors, Microelectronics, MEMS, Optoelectronics Application: Integrated Circuits, Flat Panel Displays, Photovoltaics, Sensors |
| Companies Covered | Photronics Inc., Toppan Photomasks Inc., HOYA Corporation, Dai Nippon Printing Co. Ltd., SK-Electronics Co. Ltd., LG Innotek Co. Ltd., Advance Reproductions Corp., Nippon Filcon Co. Ltd., Tekscend Photomask Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photomask Market Strategic Shifts & Innovations
Photomask fabrication is bifurcating between extreme ultraviolet process complexity and mature-node cost optimization, with equipment architecture and service models diverging accordingly.
Multi-beam mask writers is consolidating electron beam lithography throughput advantages for advanced node production. Leading foundries in Taiwan and South Korea are adopting these systems for seven-nanometer and below mask sets, compressing write times from days to hours. This consolidation is eliminating competitive positioning for single-beam tool suppliers in the high-end segment.
Japan's Ministry of Economy, Trade and Industry coordinates extreme ultraviolet infrastructure investments through national semiconductor programs, directing subsidy flows toward domestic mask blank and pellicle development. Industrial consequence includes accelerated qualification timelines for Japanese suppliers in extreme ultraviolet supply chains. South Korean foundries are responding by tightening local content requirements for photomask procurement.
Consolidated procurement contracts are displacing transactional spot purchasing among foundry customers. Long-term supply agreements with captive mask blank provisions now dominate leading-edge node procurement, replacing quarterly price negotiations. Taiwan's foundry ecosystem exhibits this behavioral shift most visibly, with Photronics and Toppan anchoring multi-year service contracts.
Photomask Market Segmentation
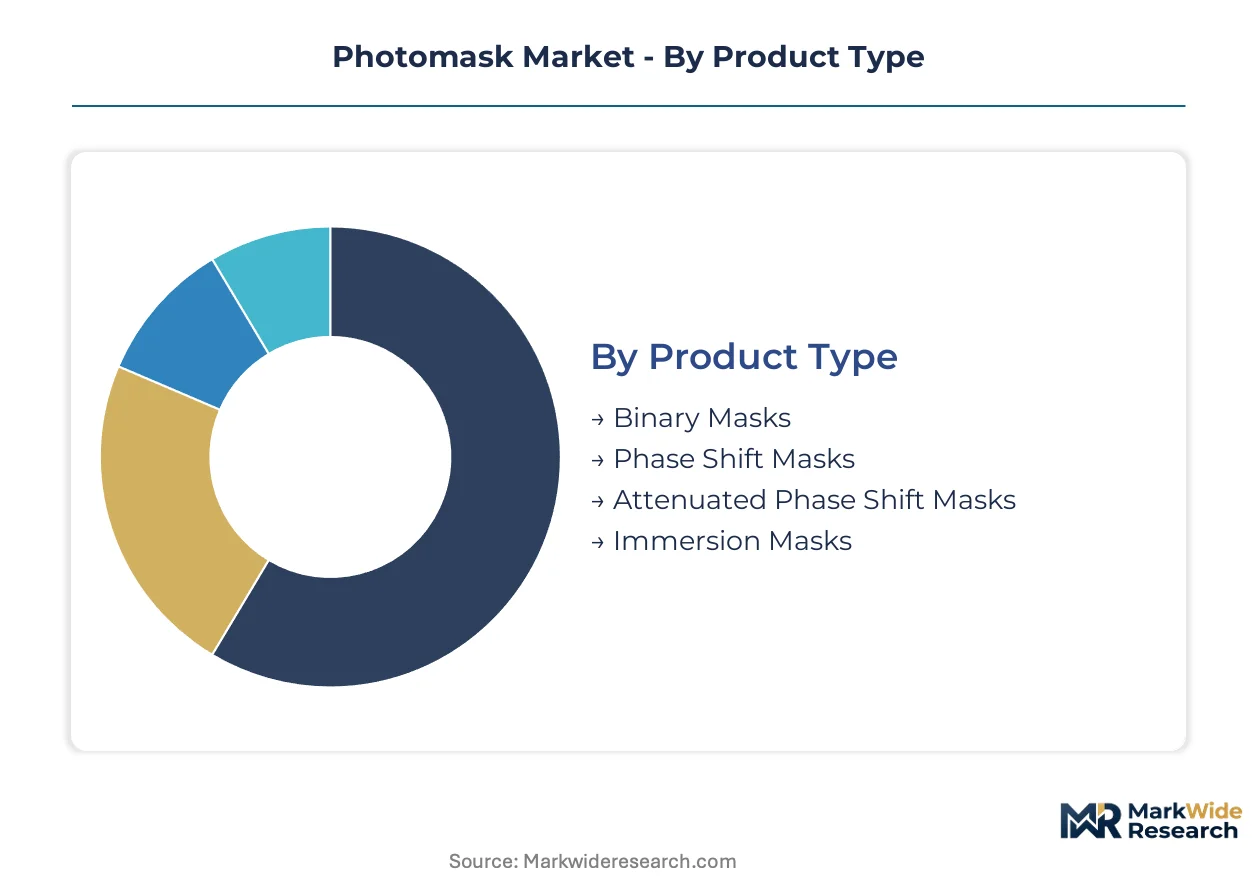
Photomask segmentation reflects diverging technical requirements between leading-edge semiconductor nodes and cost-sensitive display applications. Supply concentration patterns vary sharply across product architectures, with extreme ultraviolet-qualified suppliers commanding distinct margin tiers from mature-node competitors.
Product Type:
Mask blank supply concentrates among Japanese and German ingot producers, creating tiered access to high-purity synthetic fused silica for advanced versus standard specifications.
- Binary Masks:Chrome-on-glass or chrome-on-quartz substrates with opaque and transparent regions define the simplest photomask architecture. Foundries in Taiwan's Hsinchu Science Park and South Korea's Giheung cluster procure binary masks in volume for mature-node logic and memory production where resolution requirements permit single-layer patterning.
- Phase Shift Masks:Molybdenum silicide and etched quartz structures manipulate light phase to enhance resolution at sub-wavelength geometries. Leading foundries mandate these masks at nodes below seven nanometers, concentrating procurement among suppliers with captive blank supply and multi-beam writing capability.
- Attenuated Phase Shift Masks:Partial transmission films enable improved process windows for critical layers in deep ultraviolet immersion lithography. Memory manufacturers in South Korea deploy these masks for high-density NAND string formation.
- Immersion Masks:Specialized pellicle mounting and flatness specifications address liquid-immersion lithography requirements. ArF immersion tool fleets at Taiwan Semiconductor Manufacturing Company and Samsung Electronics drive replacement demand.
Binary masks absorb the bulk of installed capacity; phase shift masks are expanding most quickly.
Technology:
Equipment architecture diverges between multi-billion-dollar extreme ultraviolet installations and established deep ultraviolet tool bases, fragmenting supplier qualification pathways.
- Extreme Ultraviolet Lithography:Reflective mask technology employing multilayer molybdenum-silicon coatings on ultra-flat substrates enables patterning at three nanometers and below. ASML's EUV scanner deployments at TSMC and Samsung concentrate mask demand among three qualified blank suppliers.
- Deep Ultraviolet Lithography:ArF and KrF laser-based projection systems continue serving mature-node and specialty chip production. Foundry maintenance contracts sustain mask demand for 193nm and 248nm wavelengths across Taiwan, South Korea, and China.
- Electron Beam Lithography:Maskless direct-write and mask writing applications leverage variable-shaped beam and multi-beam architectures. Multi-beam systems from NuFlare and IMS Nanofabrication dominate advanced node mask production.
- X-Ray Lithography:Synchrotron-based proximity printing serves niche MEMS and packaging applications with thick resist requirements. Japanese research consortia maintain limited operational capacity.
Deep ultraviolet lithography retains the largest installed base; extreme ultraviolet lithography is climbing the fastest.
End User:
Customer concentration in East Asian foundry corridors creates geographic lock-in effects for mask logistics and repair services.
- Semiconductors:Logic and memory foundries account for the dominant share of advanced photomask procurement. Taiwan Semiconductor Manufacturing Company and Samsung Electronics qualification requirements dictate supplier technical roadmaps.
- Microelectronics:Analog, power, and radio-frequency device manufacturers source masks for 180nm to 65nm process nodes. Automotive semiconductor demand from electric vehicle powertrain suppliers is restructuring order patterns.
- MEMS:Microelectromechanical systems require thick-film masks with high aspect ratio features. Bosch and STMicroelectronics fabrication facilities in Germany and France drive specialty mask specifications.
- Optoelectronics:Laser diode and photodetector manufacturing employs compound semiconductor mask sets. Data center optical interconnect demand is expanding III-V foundry capacity.
Semiconductors dominate current procurement volumes; microelectronics is gaining share fastest.
Application:
Application-driven mask specifications range from sub-nanometer overlay precision in logic devices to meter-scale flat panel display formats.
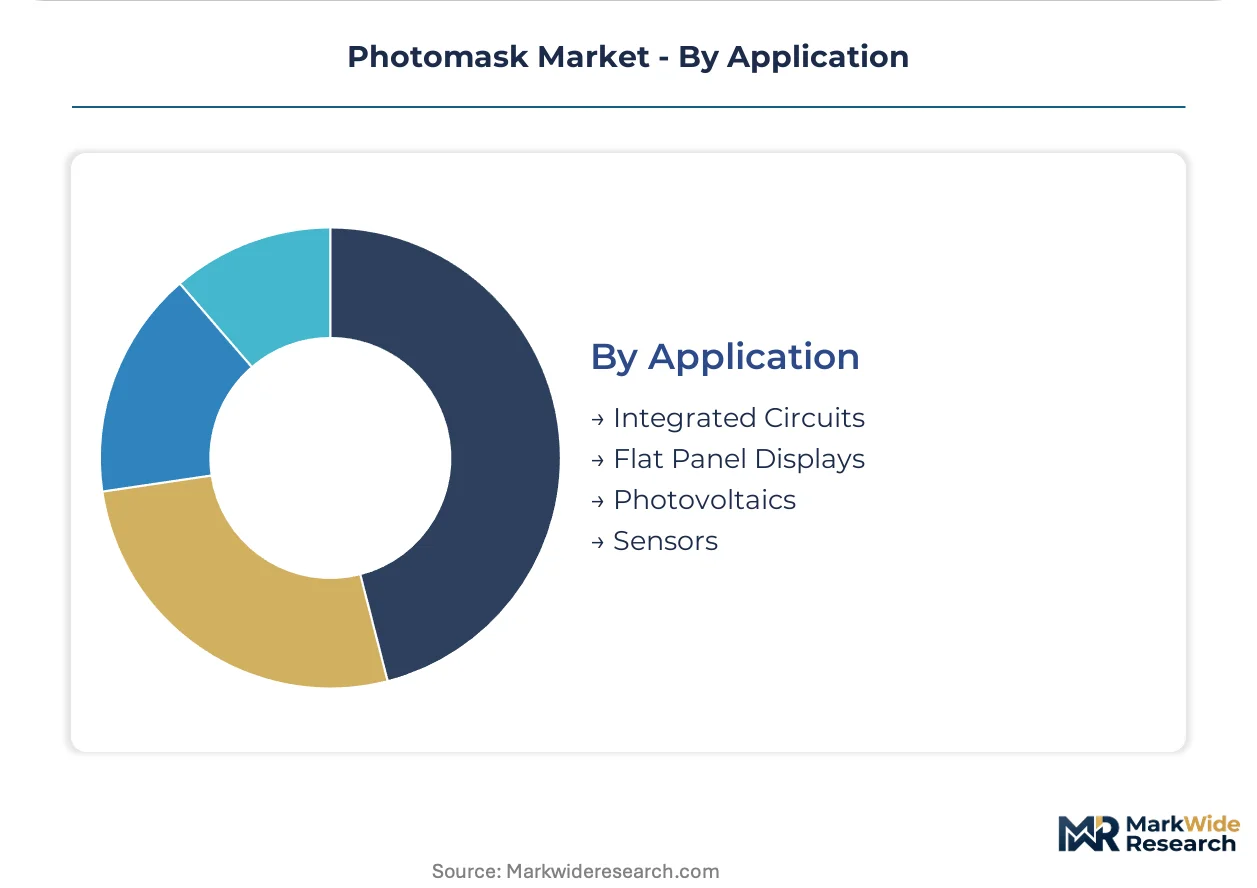
- Integrated Circuits:Logic, memory, and specialty chip production demands the most stringent mask specifications. Leading-edge node masks require actinic inspection and pellicle mounting that binary display masks never encounter.
- Flat Panel Displays:Large-area masks for organic light-emitting diode and quantum dot manufacturing diversify revenue streams. Samsung Display and LG Display procurement in South Korea anchors regional production capacity.
- Photovoltaics:Screen-printing and metallization patterning for solar cell contacts employs lower-cost mask alternatives. Chinese photovoltaic manufacturing expansion sustains volume demand.
- Sensors:Image sensor and environmental sensor fabrication combines mature-node logic with specialized optical layers. Sony and Omnivision design activity drives mask set complexity.
Integrated circuits command the largest mask fabrication capacity; flat panel displays are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Photomask production concentrates in East Asian manufacturing corridors while consumption spreads across semiconductor fabrication clusters worldwide. Japan and Germany dominate high-purity quartz substrate supply, creating upstream bottlenecks for advanced mask blank fabrication. Foundry demand anchors in Taiwan and South Korea, with emerging procurement nodes forming in India and Southeast Asia.
Taiwan
Taiwan Semiconductor Manufacturing Company and United Microelectronics Corporation drive photomask procurement intensity for three-nanometer and five-nanometer node production. The National Development Council coordinates domestic semiconductor supply chain investments through the Chip Implementation Center. Hsinchu Science Park anchors mask logistics infrastructure, with repair and metrology services clustering around foundry fabrication facilities.
South Korea
Samsung Electronics and SK Hynix expand extreme ultraviolet lithography mask sets for memory and logic production at Pyeongtaek and Giheung complexes. The Ministry of Trade, Industry and Energy ties photomask supplier qualification timelines to domestic foundry expansion schedules. Giheung cluster concentration creates localized economies of scale in mask blank inventory management and pellicle mounting services.
Japan
HOYA Corporation and Shin-Etsu Chemical control synthetic fused silica ingot production for advanced extreme ultraviolet blanks. The Ministry of Economy, Trade and Industry directs subsidy flows toward domestic mask blank and pellicle development through national semiconductor programs. Kyushu and Nagoya manufacturing corridors host electron beam lithography equipment suppliers and mask writing service providers.
United States
Intel and GlobalFoundries sustain mask demand for domestic logic and specialty chip production at Arizona and New York fabrication facilities. The Environmental Protection Agency regulates chrome etching effluents under discharge limits that impose capital-intensive wastewater treatment requirements. Greater Phoenix and Hudson Valley clusters attract mask repair and inspection equipment suppliers serving captive foundry operations.
India
Tata Electronics and CG Power are constructing domestic foundry capacity that will require mature-node photomask procurement for analog and power semiconductor production. The Production-Linked Incentive scheme for semiconductor manufacturing creates qualification pathways for mask suppliers establishing local repair operations. Gujarat and Karnataka sub-regions concentrate proposed fabrication facilities with associated mask logistics requirements.
Photomask Market Key Industry Players
Top-tier vendors anchor the extreme ultraviolet-qualified segment, while mid-tier fabricators compete on mature-node volume and turnaround speed. The supplier base stratifies into captive mask blank producers, independent mask shops, and equipment-integrated service providers. Strategic archetypes include quartz substrate specialists, multi-beam writing operators, and display-focused large-area mask fabricators. Competitive moves center on backward integration into blank supply and long-term foundry service contracting.
Within the captive supply tier, Photronics Inc. and Toppan Photomasks Inc. exemplify foundry-integrated service models, while HOYA Corporation represents upstream substrate control. These three entities occupy positions that reflect divergent strategic bets on extreme ultraviolet infrastructure versus mature-node volume scaling.
| Leading Market Players |
|---|
| Photronics Inc. |
| Toppan Photomasks Inc. |
| HOYA Corporation |
| Dai Nippon Printing Co. Ltd. |
| SK-Electronics Co. Ltd. |
| LG Innotek Co. Ltd. |
| Advance Reproductions Corp. |
| Nippon Filcon Co. Ltd. |
| Tekscend Photomask Inc. |
| Others |
Cost & Logistics Intelligence
Multi-beam mask writer adoption at leading foundries is compressing write times from days to hours while simultaneously concentrating procurement power among three qualified blank suppliers. This technology transition is bifurcating cost structures between extreme ultraviolet-qualified captive producers and mature-node independent shops.
Pricing Analysis
Lead-time-driven pricing premiums dominate extreme ultraviolet mask procurement, with foundries paying substantial markups for sub-72-hour turnaround on critical layer sets. Three-tier pricing structure across premium, standard, and economy levels separates extreme ultraviolet-qualified masks from deep ultraviolet phase shift variants and binary mature-node alternatives. Cost compression in binary mask tiers is intensifying because Chinese display manufacturers are expanding captive mask writing capacity. Automotive semiconductor foundries exhibit highest price sensitivity, while leading-edge logic producers prioritize qualification security over unit cost.
Supply Chain Analysis
High-purity synthetic fused silica ingot supply rests on HOYA Corporation and Shin-Etsu Chemical in Japan, with Schott AG in Germany providing secondary sourcing for specialty grades. Raw material dependencies span synthetic quartz substrates, molybdenum silicide films, and chrome etching chemicals. Single-source vulnerability in extreme ultraviolet blank qualification creates procurement bottlenecks for new market entrants. Distribution runs through direct long-term service contracts with foundry customers, displacing spot market transactions at advanced nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extreme ultraviolet infrastructure requirements are forcing consolidation among mask fabricators unable to secure captive blank supply or multi-beam writing capacity. Technical qualification barriers and capital intensity will eliminate sub-scale competitors within the analysis window.
For Market Incumbents: Lock in multi-year foundry service contracts with dedicated repair and metrology capacity at Hsinchu and Giheung clusters. Secure backward integration into mask blank supply through equity partnerships with Japanese ingot producers. The threat of South Korean local content requirements demands preemptive capacity positioning.
For New Entrants and Emerging Players: The gap between premium extreme ultraviolet mask pricing and economy binary mask rates creates entry space for mid-tier deep ultraviolet specialists. Target India's emerging foundry corridor for qualification partnerships with Tata Electronics and CG Power. Establish local repair operations under PLI scheme incentives rather than competing on leading-edge mask writing.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by captive foundry operations seeking supply security. Long-term viability favors suppliers with demonstrated extreme ultraviolet blank qualification and established electron beam lithography technician pipelines. Watch ASML scanner deployment schedules as the inflection indicator for mask demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Mask Blank Supply Agreement | Photronics secures HOYA quartz substrate allocation, insulating delivery timelines from Japanese supply constraints. |
| Multi-Beam Writer Fleet Expansion | NuFlare tool installations at Toppan compress mask write times, enabling foundry qualification for three-nanometer node production. |
| India Repair and Metrology Localization | Establishing Gujarat operations under PLI schemes positions suppliers for Tata Electronics foundry procurement. |
| Phase Shift Mask Retrofitting Program | Resolution enhancement technology extends deep ultraviolet immersion viability, preserving equipment utilization at legacy nodes. |
| Long-Term Foundry Service Contracting | Samsung Electronics multi-year agreements displace quarterly price negotiations, locking in margin stability. |
Research Approach
Independent corroboration across mask fabrication executives, foundry procurement directors, and electron beam lithography equipment suppliers underwrites the qualitative findings. Primary interviews with TSMC and Samsung mask qualification managers, Photronics and Toppan operations leads, and HOYA substrate specialists were validated against secondary sources including SEMI equipment forecasts, Japan Ministry of Economy Trade and Industry subsidy disclosures, and South Korea Ministry of Trade Industry and Energy supply chain reports. Bottom-up mask shipment estimates triangulate with top-down foundry capex allocations.
Comparable-period anchoring tied projection assumptions to historical extreme ultraviolet adoption curves and deep ultraviolet tool fleet depreciation schedules. The analytical framework segments by product type, technology node, end-user vertical, and geographic manufacturing cluster across the analysis window. CAGRs derive from foundry node transition timelines and display panel capacity expansion. Forecast inputs incorporate ASML scanner installation forecasts and automotive semiconductor content per vehicle trajectories.
Inputs from foundry procurement databases and equipment supplier order backlogs were available through the study window; gaps in extreme ultraviolet pellicle durability field data introduce uncertainty bands around replacement frequency assumptions. Forecasts reflect documented assumptions regarding node migration speed and blank defect detection yield improvements. A small set of triggers warrants ongoing watch: ASML high-numerical-aperture scanner qualification timelines, India foundry construction pace, and Japanese export control adjustments on high-purity quartz.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Manufacturing
China Electronic Design Automation (EDA) Tools Market
Semiconductor Manufacturing
Global EUV Lithography Market
Semiconductor Manufacturing
High Purity Process Systems for Semiconductor Market
Semiconductor Manufacturing
Surface Mount Technology (SMT) Market
Semiconductor Manufacturing
Semiconductor Polishing Pads Market
Semiconductor Manufacturing
Global Overall EUV Lithography Market
Semiconductor Manufacturing
Silicon Wafer Reclaim Market
Semiconductor Manufacturing
PCB Photoresist Market
Semiconductor Manufacturing
Semiconductor and Electronic Parts Manufacturing Market
Semiconductor Manufacturing
Solar Laser Drilling Market
Semiconductor Manufacturing
Semiconductor Bonding Machine Market
Semiconductor Manufacturing
Europe Electronic Manufacturing Services Market
Semiconductor Manufacturing
Europe Photoresist and Photoresist Ancillaries Market
Semiconductor Manufacturing
Photoresist and Photoresist Ancillaries Market
Semiconductor Manufacturing
IC CMP Slurries and Pads Market
Semiconductor Manufacturing
Middle East and Africa Cell Manufacturing Market