
 China Flash Memory Market | 2026-2036
China Flash Memory Market Size, Share, and Industry Trends Forecast 2026-2036
China Flash Memory Market Insights
A multi-source procurement model is shifting toward captive supply among Chinese device makers. Yangtze Memory Technologies Co., Ltd. anchors Beijing's push for semiconductor self-sufficiency through in-house 3D NAND fabrication. GigaDevice Semiconductor Inc. competes in NOR flash segments where design flexibility matters. Samsung Electronics Co., Ltd. leverages its Xi'an fab complex to sustain premium NAND supply for domestic smartphone OEMs.
Flash memory stores data in semiconductor cells without mechanical parts, using floating-gate transistors with oxide layers roughly 10 nanometers thick to retain charge for years without power. NAND variants serve high-density bulk storage in servers and mobile devices, while NOR flash enables fast random access for code execution in automotive controllers. Embedded form factors dominate automotive electronics as ECU counts rise, whereas SSD configurations capture margin pools in telecommunications infrastructure. TLC technology leads consumer electronics volumes, though SLC persists in industrial applications where write endurance determines lifecycle cost.
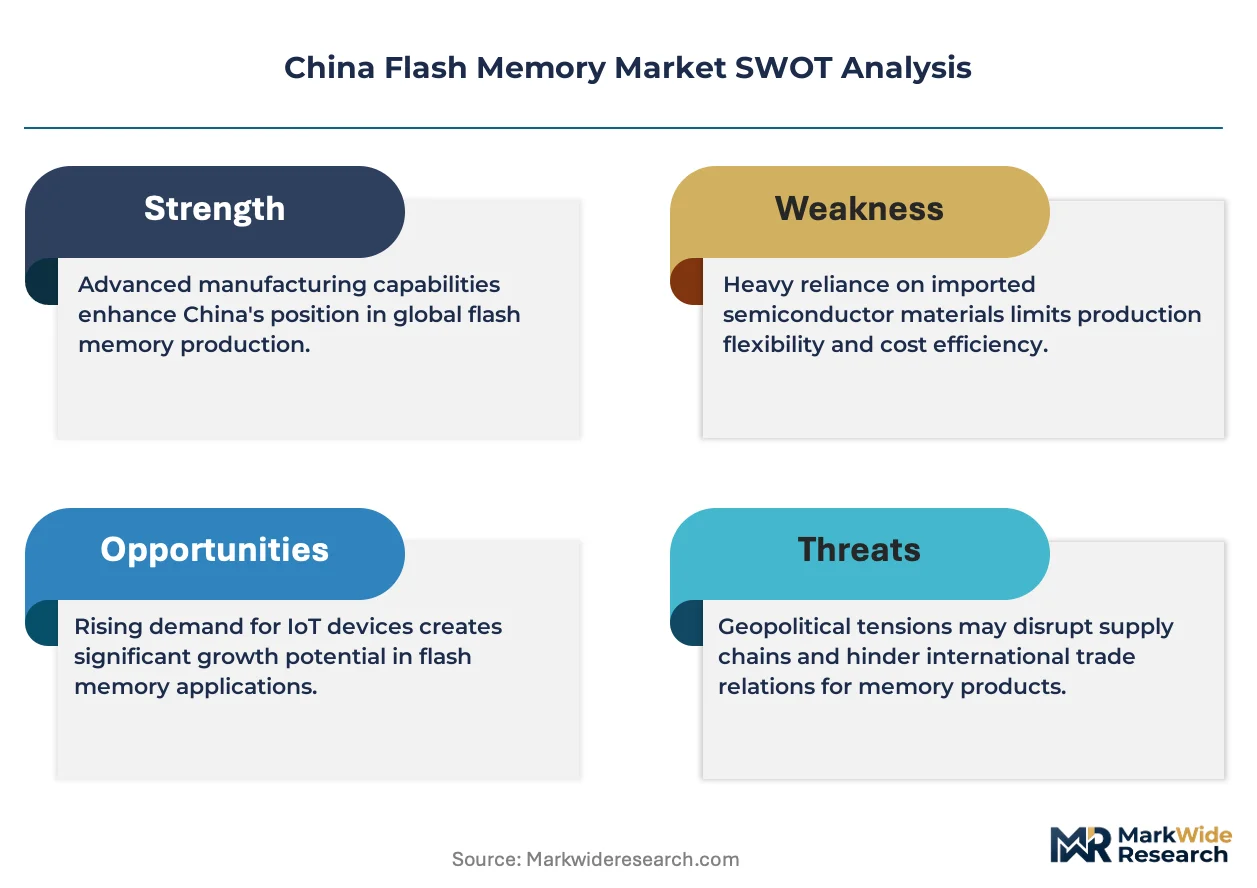
SAMR enforces GB standards on data retention and write endurance for flash products sold domestically. MIIT's dual carbon goals pressure fabs to reduce per-wafer energy intensity. NMPA oversight of medical devices indirectly shapes embedded flash specifications for healthcare equipment. Stakeholders must monitor whether MIIT expands domestic content requirements beyond current government procurement thresholds.
Market Dynamics
MIIT's domestic substitution mandates are restructuring procurement flows across China's flash memory sector, forcing device makers to requalify supply chains around Yangtze Memory Technologies and other local fabricators.
Growth Catalysts
- Automotive electronics demand:Yangtze River Delta cluster ECU manufacturers are expanding embedded NOR flash orders for electric vehicle controllers. Tier-1 suppliers in Suzhou and Hangzhou are qualifying domestic 3D NAND for telematics modules.
- Dual carbon goals:MIIT energy intensity benchmarks are accelerating fab upgrades toward lower-power 3D NAND architectures. Domestic producers capturing green procurement preferences in government data center tenders.
- Enterprise storage procurement:Shanghai and Shenzhen data center operators are expanding SSD deployments under cloud service provider capacity expansion programs. Hyperscale buyers are diversifying beyond Samsung Xi'an supply.
Market Restraints
- Equipment import dependency:Lithography and etching tools from Dutch and Japanese suppliers face export control friction, constraining domestic 3D NAND layer-count advancement.
- Raw material concentration:High-purity silicon wafers and specialty gases concentrate in South Korean and Japanese supply bases, exposing Chinese fabs to input cost volatility and logistics risk.
- SLC endurance premium:Industrial automation and medical device buyers still specify single-level cell flash for write-intensive applications, limiting TLC penetration in high-margin segments.
Strategic Opportunities
- Western China fab expansion:Chengdu and Xi'an infrastructure incentives under MIIT regional development programs are attracting test and packaging investment for captive supply chains.
- Healthcare equipment qualification:NMPA medical device registration pathways are opening for embedded flash in diagnostic imaging and patient monitoring systems, a segment previously dominated by imported components.
- PCIe Gen5 controller integration:Convergence of domestic NAND fabrication with local controller IC design is enabling complete SSD subsystem production without foreign silicon.
Industry Challenges
- Process engineering talent scarcity:3D NAND charge trap and replacement gate expertise concentrates in experienced engineers from Samsung and SK Hynix, constraining domestic fab yield ramp timelines.
- GB standard compliance duration:SAMR data retention and write endurance certification cycles extend product qualification periods, delaying revenue recognition for new device introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Flash Memory Market |
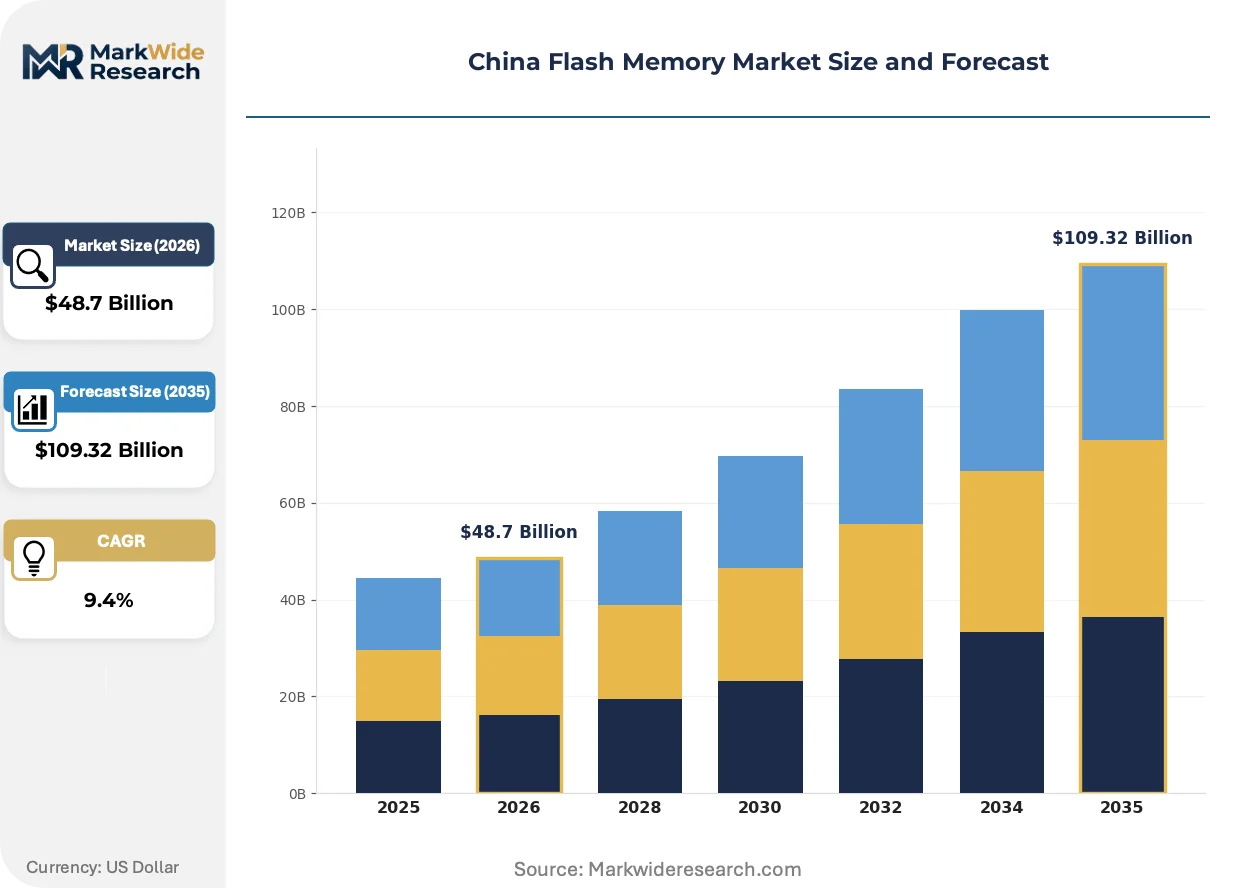
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $109.32 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
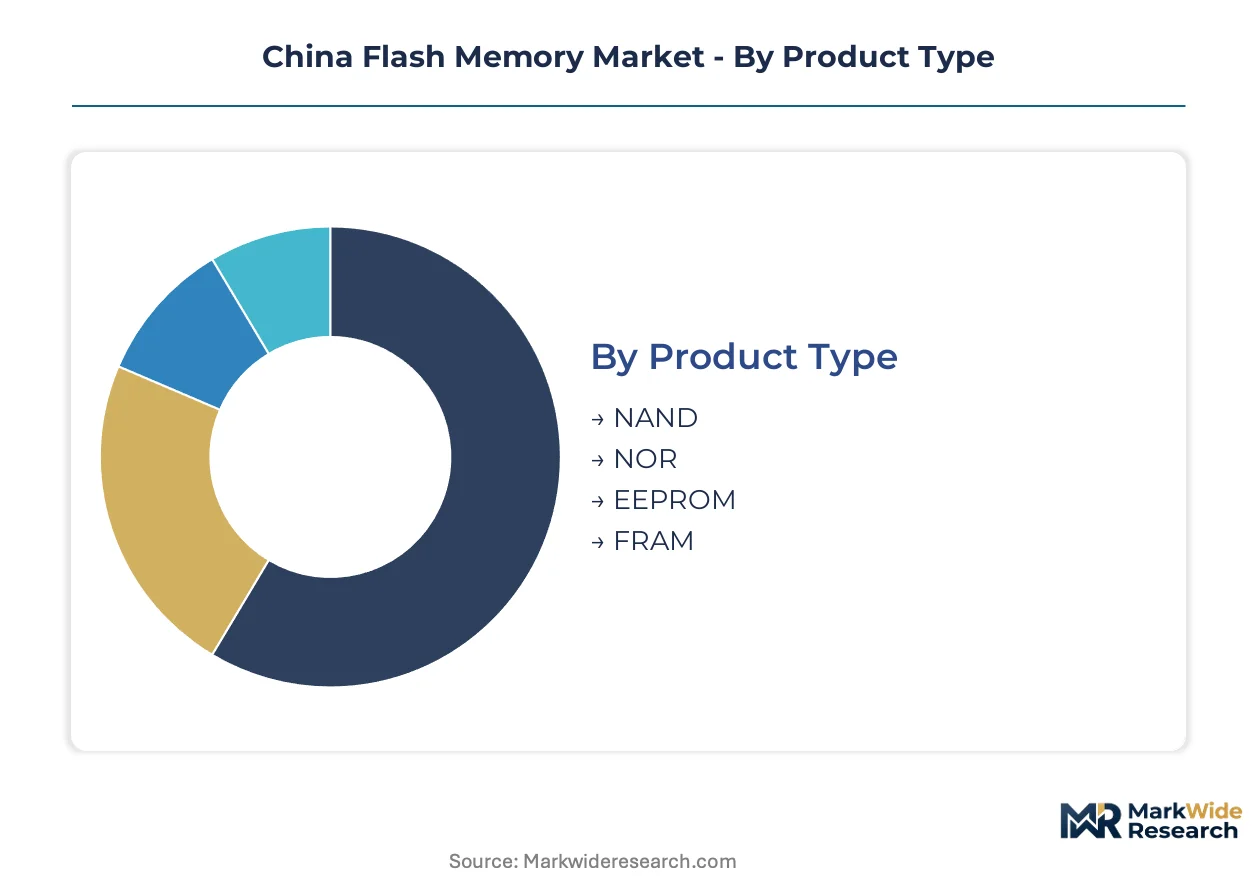
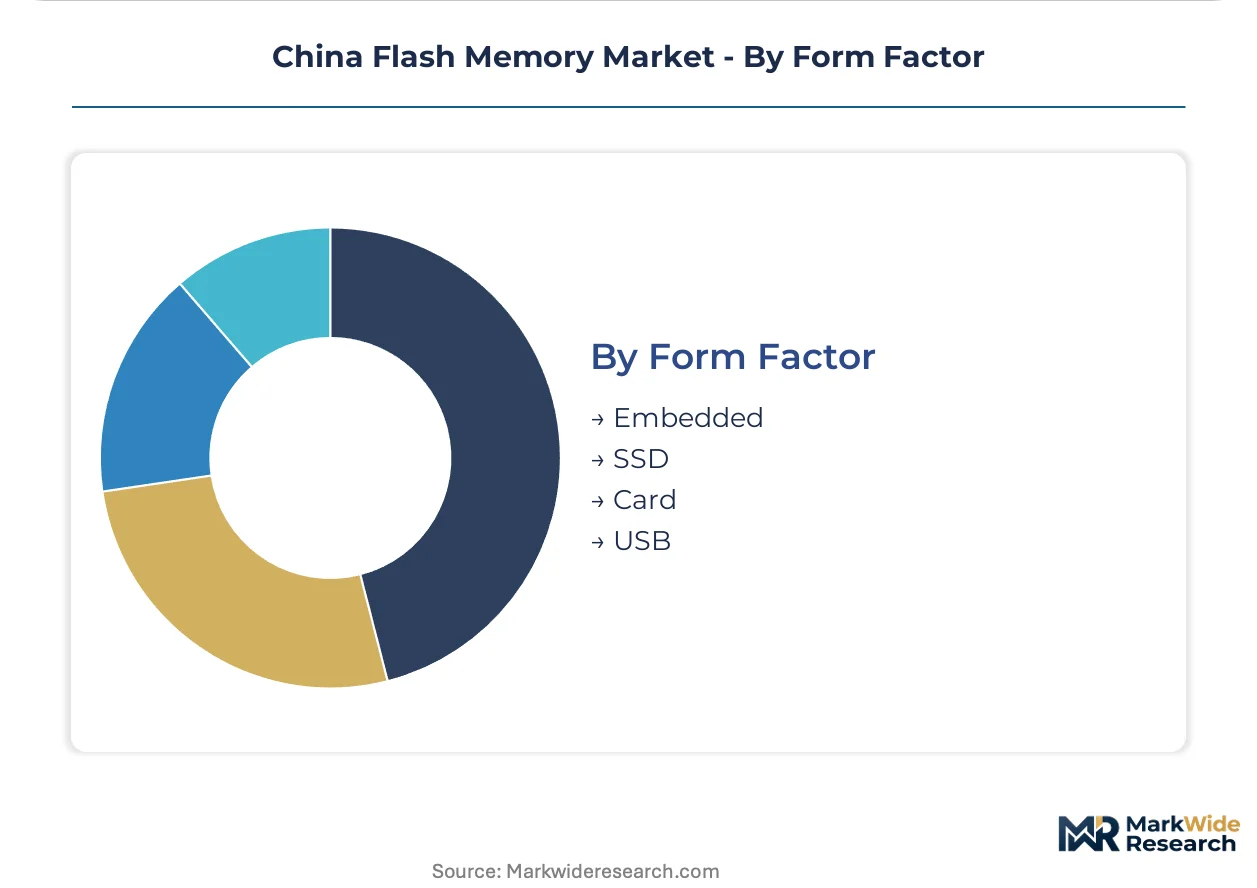
| Segmentation | Product Type: NAND, NOR, EEPROM, FRAM End Use: Consumer Electronics, Automotive Electronics, Industrial Applications, Telecommunications Technology: 3D NAND, SLC, MLC, TLC Form Factor: Embedded, SSD, Card, USB |
| Companies Covered | Yangtze Memory Technologies Co., Ltd., GigaDevice Semiconductor Inc., Longsys Electronics, Samsung Electronics Co., Ltd., SK Hynix Inc., Micron Technology, Inc., Kioxia Corporation, Western Digital Corporation, Macronix International Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Flash Memory Market Trends and Innovations
Xtacking architecture and hybrid bonding techniques are redefining layer-stacking economics in Chinese 3D NAND fabrication. Domestic producers are leapfrogging conventional string-stacking limitations through wafer-to-wafer integration approaches.
QLC NAND is overtaking TLC in cold storage and archival server deployments. Hyperscale operators in Inner Mongolia and Guizhou data centers are adopting four-level cell devices for write-once-read-occasionally workloads. This density architecture is compressing cost-per-gigabyte floors and enabling domestic suppliers to compete on terabyte-scale unit economics against established Korean producers.
GB standards enforcement through SAMR market surveillance is tightening data retention specifications for flash products sold domestically. Industrial consequence includes accelerated obsolescence of older TLC generations that marginally meet legacy endurance thresholds. Automotive and medical device segments are responding with accelerated requalification programs around newer domestic 3D NAND vintages that certify cleanly under updated test protocols.
Device makers are consolidating supplier panels around captive and quasi-captive flash sources. Smartphone OEMs in Dongguan and Shenzhen are reducing qualified vendor lists from six to three, with preference for suppliers offering co-development roadmaps. This concentration is most visible in flagship product lines where BOM stability and volume commitment pricing override spot-market flexibility.
China Flash Memory Market Segmentation
China's flash memory market exhibits distinct demand profiles across technology generations and application verticals. Domestic procurement mandates from MIIT are reshaping how segments compete on cost, endurance, and supply security.
Product Type:
NAND and NOR architectures anchor the technology axis with divergent density and access-speed tradeoffs.
- NAND:High-density cell arrays using floating-gate or charge-trap transistors enable terabit-scale storage in minimal die area. Yangtze Memory Technologies' 3D NAND output is capturing enterprise SSD slots in Shanghai data centers as hyperscale buyers diversify beyond Korean supply sources.
- NOR:Parallel address architectures deliver sub-microsecond random read latency for code execution. Suzhou-based ECU manufacturers are expanding embedded NOR orders for electric vehicle motor controllers under Yangtze River Delta automotive cluster expansion.
- EEPROM:Byte-addressable non-volatile storage serves configuration data in industrial sensors with moderate rewrite requirements.
- FRAM:Ferroelectric polarization switching enables unlimited write endurance for energy-harvesting IoT edge nodes.
Mature deployment sits with NAND bulk storage. Newer deployment is concentrated in NOR flash for automotive safety systems.
End Use:
Application verticals separate consumer volume plays from industrial margin pools.
- Consumer Electronics:Smartphones and tablets absorb TLC-based UFS and eMMC modules in high volumes. Dongguan OEMs are consolidating qualified flash vendor lists from six suppliers to three, favoring partners with co-development roadmaps for flagship BOM stability.
- Automotive Electronics:Functional safety requirements drive SLC and industrial-grade NOR adoption for powertrain and chassis controllers. Hangzhou telematics module makers are qualifying domestic 3D NAND for infotainment storage under NMPA automotive component pathways.
- Industrial Applications:Programmable logic controllers and automation systems specify extended-temperature flash with decade-long data retention.
- Telecommunications:Baseband units and edge servers deploy NVMe SSDs for low-latency packet processing in 5G infrastructure.
Consumer electronics commands unit volume leadership. Automotive electronics is climbing the fastest on electrification and ADAS penetration.
Technology:
Cell-level bit density determines cost-per-gigabyte floors and write endurance ceilings.
- 3D NAND:Vertical string stacking of charge-trap cells breaks planar scaling limits through Xtacking and hybrid bonding approaches. Domestic fabs are leapfrogging layer-count constraints via wafer-to-wafer integration to compete with Samsung Xi'an output on terabyte economics.
- SLC:Single-bit-per-cell storage delivers maximum program-erase cycles for medical devices and military systems. SAMR GB standard compliance cycles are accelerating obsolescence of marginal TLC generations, preserving SLC premiums in write-intensive segments.
- MLC:Two-level cell storage balances endurance and density for enterprise read-intensive workloads.
- TLC:Three-bit quantization dominates consumer SSD and mobile storage on cost-optimized controllers with aggressive error correction.
Mature deployment sits with SLC in mission-critical systems. Newer deployment is concentrated in 3D NAND layer-stack advancement for cloud storage density gains.
Form Factor:
Physical integration level shapes procurement patterns across device assembly tiers.
- Embedded:BGA and WLCSP packages integrate flash directly onto smartphone and automotive PCBs. Shenzhen smartphone OEMs are reducing socketed storage in favor of soldered-down eMMC and UFS for thickness and reliability.
- SSD:Modular drives with PCIe and SATA interfaces capture enterprise and PC upgrade demand. Domestic controller IC designers are converging with local NAND fabrication to enable complete SSD subsystem production without foreign silicon.
- Card:Removable SD and microSD formats persist in camera and drone applications requiring field-swappable storage.
- USB:Thumb drives and external enclosures serve portable data transfer with minimal performance requirements.
Mature deployment sits with USB mass-market accessories. Newer deployment is concentrated in embedded packages for space-constrained automotive and mobile designs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration in China clusters around three coastal manufacturing belts where device makers and data center operators co-locate. These regional formations drive procurement patterns and shape how MIIT's domestic substitution mandates cascade through supply chains.
United States
Hyperscale cloud operators in Northern Virginia and Oregon data center corridors absorb enterprise NAND SSD volumes for AI training infrastructure. The CHIPS and Science Act directs federal procurement preferences toward domestic semiconductor content, though flash memory fabs remain concentrated abroad. Austin and Phoenix host advanced packaging facilities that integrate imported die into subsystem assemblies.
South Korea
Memory fabricators in Pyeongtaek and Icheon supply premium 3D NAND to Chinese smartphone OEMs through the Xi'an and Dalian assembly nodes. METI-aligned export control frameworks constrain equipment resale to Chinese fabs, forcing Seoul-based suppliers to navigate licensing friction. The Gyeonggi-do cluster maintains process engineering leadership in charge-trap cell architectures.
Japan
Equipment and materials suppliers in Tokyo and Osaka prefectures dominate lithography and etching tool shipments for 3D NAND layer expansion. METI foreign exchange regulations shape payment terms for Chinese fab capital expenditure cycles. Yokohama-based chemical producers supply high-purity gases to both domestic and Chinese fabrication facilities.
Taiwan
Controller IC designers in Hsinchu Science Park enable SSD subsystem integration for Chinese module assemblers. The National Development Council semiconductor initiatives prioritize advanced packaging capacity that supports flash memory die stacking. Taichung and Tainan host backend test facilities serving cross-strait supply chain coordination.
Germany
Automotive ECU manufacturers in Bavaria and Baden-Württemberg specify industrial-grade NOR flash for powertrain controllers exported to Chinese vehicle assembly plants. The EU Green Deal carbon border adjustments pressure Chinese suppliers to document fab energy intensity for component qualification. Stuttgart-based Tier-1 suppliers are requalifying supply chains around dual-source flash strategies.
China Flash Memory Market Competitive Landscape
Capacity expansion dominates the current landscape as domestic and foreign fabricators race to capture hyperscale procurement slots. The market structure exhibits tiered concentration: a narrow top tier of integrated memory producers, a mid-tier of module assemblers and controller designers, and a fragmented base of branded distributors. Two strategic archetypes define competitive positioning: captive supply chain builders leveraging MIIT preference programs, and technology licensors preserving premium positioning through process leadership. Dominant competitive moves center on fab scale-up in Western China and strategic partnerships between domestic NAND producers and local controller IC designers.
Among China-based fabricators, Yangtze Memory Technologies Co., Ltd. occupies the position of domestic 3D NAND anchor, while GigaDevice Semiconductor Inc. exemplifies specialization in NOR flash segments where design flexibility commands premium positioning. Samsung Electronics Co., Ltd. represents the foreign incumbent archetype, sustaining volume relationships with Chinese device makers through its Xi'an manufacturing presence. These three companies illustrate how competitive positioning stratifies across domestic substitution mandates, technology specialization vectors, and foreign incumbent scale advantages.
| Leading Market Players |
|---|
| Yangtze Memory Technologies Co., Ltd. |
| GigaDevice Semiconductor Inc. |
| Longsys Electronics |
| Samsung Electronics Co., Ltd. |
| SK Hynix Inc. |
| Micron Technology, Inc. |
| Kioxia Corporation |
| Western Digital Corporation |
| Macronix International Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
High-purity silicon wafer and specialty gas costs from Japanese and South Korean suppliers cascade through three distinct pricing tiers for Chinese flash memory buyers. Contracted enterprise SSD volumes for Shanghai data centers absorb premium pricing on assured supply, while spot-market smartphone OEM procurement faces sharper cost volatility.
Pricing Analysis
Volume-driven consumer electronics segments operate on thin margins with hyperscale buyers extracting scale discounts, whereas industrial and automotive NOR flash commands premium pricing on SLC endurance specifications. Price differentiation rests on MIIT domestic content certification tiers and SAMR GB standard compliance levels. Cost compression in TLC consumer NAND is intensifying because Yangtze Memory Technologies capacity expansion creates domestic supply abundance. Smartphone OEMs in Dongguan exhibit highest price sensitivity, while medical device manufacturers accept premium pricing for decade-long data retention guarantees.
Supply Chain Analysis
Refurbishment flows for enterprise SSDs remain nascent in China, with most end-of-life drives shredded rather than remanufactured due to data security protocols. Supply concentrates in South Korea, Japan, and Taiwan for lithography tools, high-purity gases, and controller ICs respectively. Raw material dependencies include photoresist chemicals from Tokyo-based suppliers, silicon wafers from SK Siltron, and etching equipment from Tokyo Electron. Single-source vulnerability in extreme ultraviolet lithography systems creates procurement risk for domestic 3D NAND layer advancement. Distribution runs through module assemblers in Shenzhen and Chengdu before reaching OEM integration facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment import licensing friction constrains domestic 3D NAND fab expansion, propping pricing power for qualified suppliers with assured capacity. This supply-constrained structure favors incumbents with captive fabrication and entrants with differentiated controller technology.
For Market Incumbents: Deploy co-development roadmaps with Dongguan smartphone OEMs to lock flagship BOM positions before Yangtze Memory Technologies saturates TLC supply. Defend against Korean rival volume aggression by securing MIIT green procurement preferences through documented dual carbon compliance. Add captive test and packaging capacity in Xi'an to reduce logistics exposure to coastal port congestion.
For New Entrants and Emerging Players: Enter via PCIe Gen5 controller design partnerships with domestic NAND fabricators, enabling complete SSD subsystem qualification without foreign silicon. Target NMPA medical device registration pathways for embedded flash in diagnostic imaging, a segment where incumbent concentration remains lowest. Pursue white-label module assembly for hyperscale cloud operators seeking supply diversification beyond Samsung Xi'an.
For Investors and Strategic Acquirers: SAMR accelerated GB standard compliance cycles are the leading indicator that older TLC vintages face accelerated obsolescence, favoring producers with clean certification on newer 3D NAND architectures. Long-term viability centers on backward integration into wafer fab or forward integration into branded module sales. Monitor MIIT announcements on domestic content threshold expansion for government procurement as the primary inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Xtacking Architecture Licensing | Enables domestic fabs to leapfrog string-stacking limitations through wafer-to-wafer bonding. |
| Western China Fab Expansion | Chengdu and Xi'an infrastructure incentives attract test and packaging investment under MIIT programs. |
| Healthcare Equipment Qualification | NMPA registration pathways open embedded flash slots in diagnostic imaging and patient monitoring. |
| PCIe Gen5 Controller Integration | Convergence with local NAND fabrication enables complete SSD production without foreign silicon. |
| Dual Carbon Compliance Certification | Documented energy intensity reduction captures green procurement preferences in government tenders. |
Research Methodology
SEC filings from Samsung Electronics and SK Hynix, MIIT policy circulars on semiconductor domestic substitution, and SAMR GB standard documentation formed the secondary backbone for this analysis. Primary interviews with NAND fab operations directors, smartphone OEM procurement managers, and data center infrastructure planners provided demand-side validation. Trade data from Japanese and South Korean customs authorities supplied import flow verification. Bottom-up die production estimates were triangulated against top-down module shipment volumes from Shenzhen and Dongguan distribution channels.
Historical trendline analysis examined layer-count progression, yield improvement curves, and capital intensity per wafer start across the analysis window. The forecast framework modeled technology generation transitions, form factor shifts from socketed to embedded storage, and end-use vertical penetration rates. Segmentation dimensions included NAND versus NOR architecture, SLC through QLC cell density tiers, and consumer versus automotive versus enterprise application profiles. CAGRs were derived from supply-demand balance projections incorporating known fab construction timelines and equipment delivery schedules.
Revisions become necessary when METI export control enforcement tightens, SAMR accelerates GB standard update cycles, or Yangtze Memory Technologies achieves yield parity with Samsung Xi'an output. Forecasts reflect assumptions on equipment import licensing continuity and domestic substitution mandate enforcement intensity. Practitioners should monitor MIIT regional development fund disbursements and NMPA medical device registration queue lengths for early signals of supply or demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
In-Memory Computing Market
Memory Chips
Static RAM Market
Memory Chips
Memory Module Market
Memory Chips
Memory Interface Chip Market
Memory Chips
Global Emerging Non-Volatile Memory Market
Memory Chips
Next Generation Memory Market
Memory Chips
Digital RF Memory Market
Memory Chips
Nano RAM Market
Memory Chips
China Dynamic Random Access Memory (DRAM) Market
Memory Chips
Japan Flash Memory Market
Memory Chips
Static Random-Access Memory (SRAM) Market
Memory Chips
APAC Dynamic Random Access Memory (DRAM) Market
Memory Chips
New RAM Market
Memory Chips
DDR SDRAM Market
Memory Chips
Graphics DDR SDRAM Market
Memory Chips
United States Semiconductor Memory Market