
 Chip Melting Furnace Market | 2026-2036
Chip Melting Furnace Market Size, Share, and Industry Trends Forecast 2026-2036
Chip Melting Furnace Market Insights
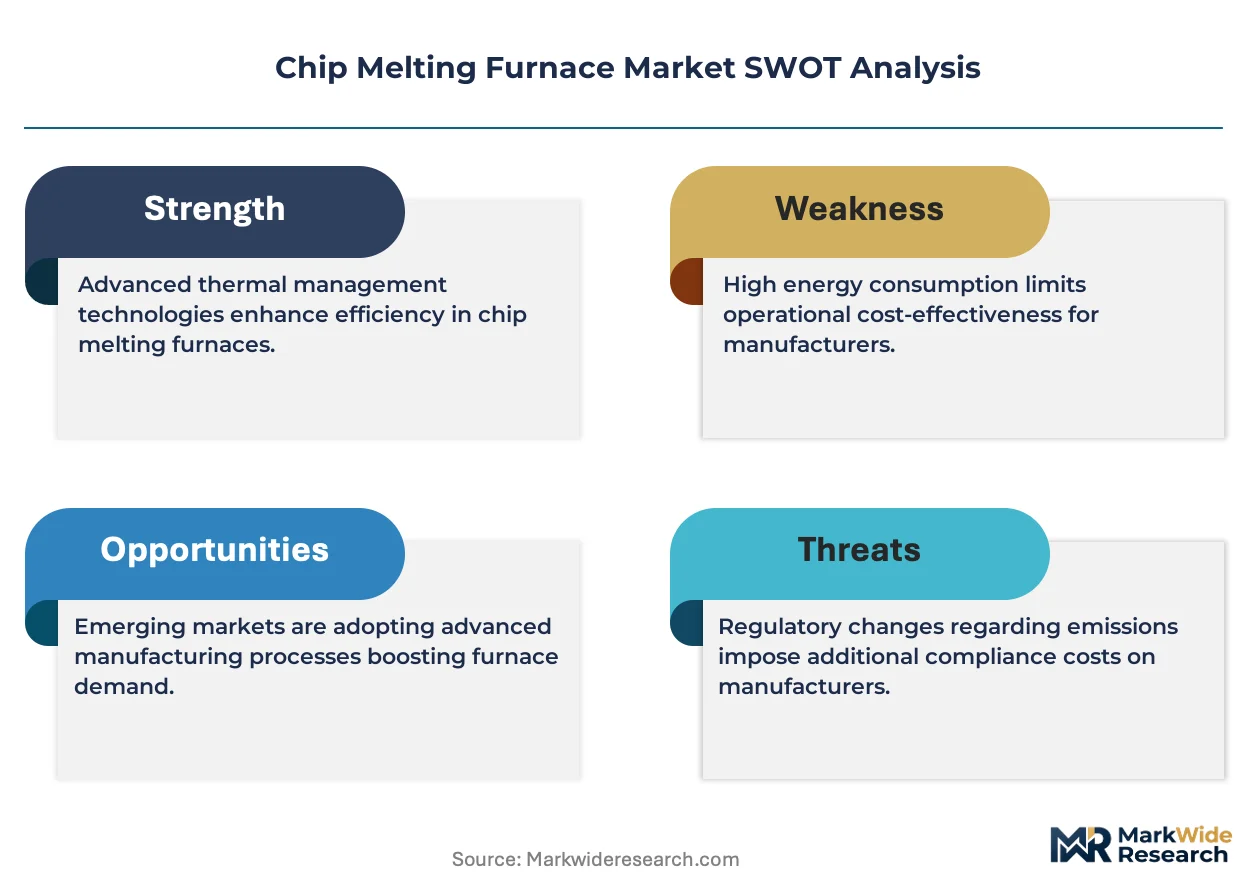
Multi-source procurement for crucible and heating elements is broadening as foundries reduce dependency on single suppliers. Inductotherm Corp leverages its induction heating heritage to anchor North American demand for precision melting systems. Ferrotec specializes in graphite crucible integration, sustaining its position in high-purity silicon processing. Beijing Jingyuntong Technology competes on cost-optimized electric furnace platforms for mid-scale Chinese foundries.
A chip melting furnace is a thermal processing unit designed to liquefy semiconductor-grade silicon, metals, or alloys at temperatures typically exceeding 1,400°C, utilizing induction, resistance, or arc heating mechanisms to achieve controlled melt chemistry and minimize contamination. Its primary purpose is to supply homogeneous molten feedstock for crystal growth, ingot casting, and alloy formulation in electronics and advanced materials manufacturing. Induction furnaces dominate premium installations where electromagnetic stirring ensures melt uniformity, while resistance furnaces occupy cost-sensitive segments with simpler thermal management requirements. Electric heating technology leads technology adoption as foundries phase out gas-fired systems to meet tightening carbon intensity targets.
EPA emissions standards and OSHA workplace exposure limits in the United States compel foundries to retrofit gas-fired systems with electric alternatives or install fume capture infrastructure. China's MEE enforces dual carbon goals that restrict coal-dependent melting operations, channeling investment into induction and resistance platforms. India's BIS certification mandates for industrial electrical equipment create compliance barriers for imported furnace systems. Stakeholders must monitor how regional energy transition timelines reshape total cost of ownership calculations across their installed base.
Market Dynamics
Induction heating technology is electrifying chip melting operations worldwide as foundries abandon gas-fired systems to meet tightening carbon intensity mandates and achieve precise electromagnetic stirring control.
Growth Catalysts
- EPA emissions standards:United States foundries face retrofit deadlines that accelerate electric furnace procurement cycles and fume capture infrastructure deployment.
- Silicon ingot demand:Semiconductor foundries in Taiwan and South Korea are expanding capacity for 300mm wafer production, requiring additional high-purity melting capacity.
- Hsinchu Science Park corridor:Concentrated fabrication investment in this Taiwanese cluster generates localized demand for precision induction systems with contamination control.
Market Restraints
- Graphite crucible supply concentration:Premium isostatic graphite production concentrates among limited specialized suppliers, creating input bottlenecks during capacity expansions.
- High-purity silicon feedstock volatility:Polysilicon price swings directly impact foundry operating budgets and furnace utilization planning.
- India BIS certification:Mandatory industrial electrical equipment standards create compliance delays and testing costs for imported furnace systems.
Strategic Opportunities
- China dual carbon goals:MEE restrictions on coal-dependent melting channel investment toward induction and resistance platforms for domestic foundry upgrades.
- Electromagnetic stirring integration:Convergence of advanced power electronics with precision temperature control enables next-generation melt uniformity for specialty alloys.
- Mid-scale Chinese foundries:Cost-optimized electric furnace platforms address underpenetrated domestic tier seeking automated melting without premium induction specifications.
Industry Challenges
- Induction coil engineering expertise:Shortage of specialized technicians capable of designing and maintaining high-frequency electromagnetic systems for semiconductor-grade applications.
- Legacy gas-fired retrofit integration:Existing foundry infrastructure requires complex electrical infrastructure upgrades and thermal management reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chip Melting Furnace Market |
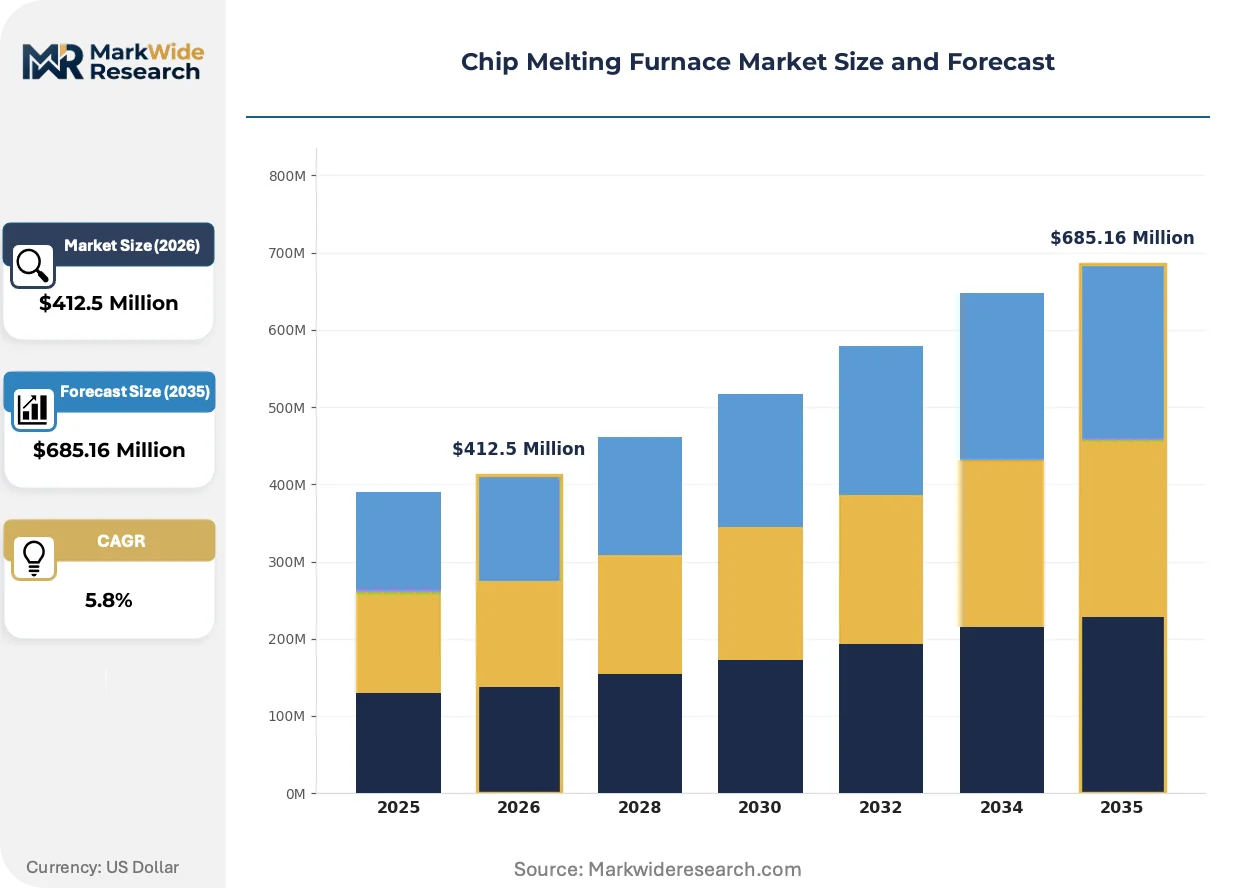
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Induction Furnace, Arc Furnace, Resistance Furnace, Crucible Furnace, Electric Furnace Technology: Electric Heating, Gas Heating, Oil Heating, Resistance Heating, Induction Heating Application: Metal Refining, Scrap Recycling, Metal Casting, Alloy Production, Waste Treatment End User: Foundries, Metal Fabrication Plants, Recycling Facilities, Die Casting Companies, Heat Treatment Workshops |
| Companies Covered | Inductotherm Corp, PVA TePla AG, Linton Crystal, Ferrotec, Jingsheng, Beijing Jingyuntong Technology, ECM Technologies, MegaMelt Furnaces, Crystal Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chip Melting Furnace Market Trends and Innovations
Active transformation across heating modalities, regulatory compliance architectures, and procurement methodologies is restructuring competitive positioning and investment priorities for melting system suppliers.
Induction furnace technology is electrifying premium chip melting installations by replacing gas-fired systems with electromagnetic heating that delivers precise temperature control and intrinsic melt stirring. Taiwan Semiconductor Manufacturing Company and Samsung Foundry are adopting these systems at scale for 300mm silicon ingot production. This electrification is compressing the addressable market for resistance furnaces in high-purity applications while expanding service revenue streams for power electronics maintenance.
REACH chemical registration requirements in Europe are forcing foundries to document crucible material compositions and heating element coatings for environmental compliance. The regulation mandates supply chain transparency for graphite and refractory materials used above 1,400°C. German and Dutch semiconductor material suppliers are responding by qualifying alternative crucible formulations and establishing certified material traceability systems.
Multi-source procurement for critical furnace components is displacing single-supplier dependencies as foundries mitigate concentration risk in graphite crucible and heating element supply. Large semiconductor foundries now mandate qualified secondary sources for all consumable components. This pattern is most visible in the Hsinchu-Taichung manufacturing corridor where foundries maintain approved vendor lists spanning Japanese, European, and domestic Taiwanese suppliers.
Chip Melting Furnace Market Segmentation
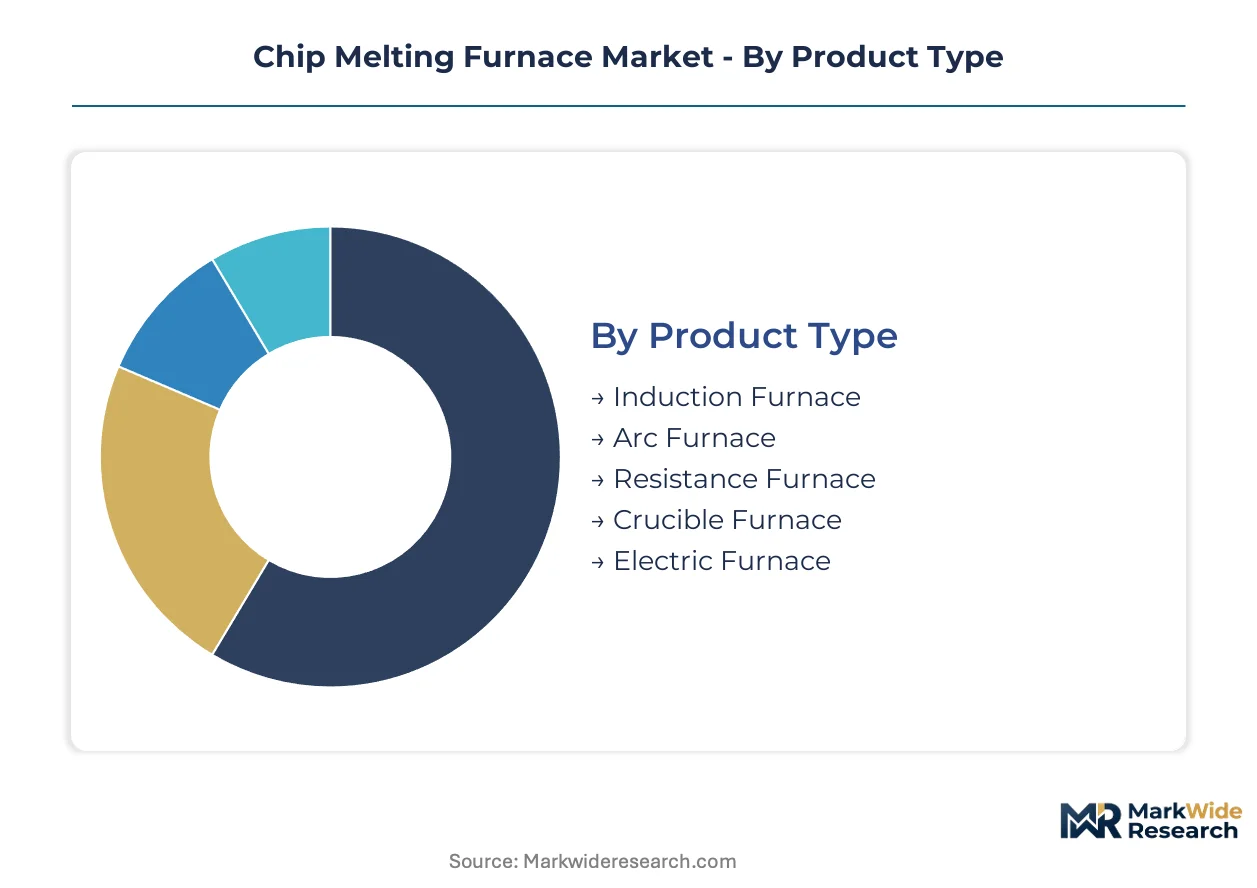
Segmentation in chip melting furnaces reveals how heating modality, thermal precision requirements, and end-use contamination standards partition procurement budgets across semiconductor and advanced materials supply chains.
Product Type:
Volume installations favor electromagnetic platforms for melt uniformity, while cost-optimized foundries retain resistance and crucible systems for simpler thermal management.
- Induction Furnace:Electromagnetic heating coils generate eddy currents for precise temperature control and intrinsic melt stirring without mechanical agitation. Taiwan Semiconductor Manufacturing Company and Samsung Foundry specify these systems for 300mm silicon ingot production at Hsinchu Science Park and Pyeongtaek complexes, where contamination control mandates non-contact heating.
- Arc Furnace:Electrode-generated plasma achieves extreme temperatures exceeding 3,000°C for specialty alloy formulation and high-melting-point metal recovery. Demand concentrates in Japanese specialty steel foundries serving aerospace turbine blade manufacturers, constrained by electrode consumption costs and power intensity.
- Resistance Furnace:Electrical current through refractory heating elements provides straightforward thermal management for mid-purity applications. Chinese domestic foundries in Jiangsu province deploy these platforms for cost-sensitive silicon metal processing.
- Crucible Furnace:Container-based melting with graphite or ceramic vessels suits small-batch specialty alloy development and R&D scale operations.
- Electric Furnace:Broad category encompassing multiple electromagnetic and resistive heating architectures unified by grid-powered operation.
Mature deployment sits with resistance and crucible furnaces in legacy foundries. Newer deployment is concentrated in induction systems for 300mm wafer feedstock production.
Technology:
Carbon intensity regulations are channeling investment toward grid-connected platforms and away from combustion-based thermal sources.
- Electric Heating:Grid-powered resistive or electromagnetic systems eliminate on-site combustion emissions and enable precise power modulation for temperature profiling. EPA emissions standards in the United States and China's MEE dual carbon goals accelerate retrofit procurement across Texas and Shandong province foundries.
- Induction Heating:High-frequency alternating current through copper coils generates electromagnetic fields for non-contact, contamination-free melting. South Korean semiconductor material suppliers at Giheung cluster specify these systems for polysilicon purification.
- Resistance Heating:Current through refractory elements provides economical thermal input for standard-grade silicon and aluminum melting.
- Gas Heating:Natural gas combustion retains niche presence where electrical infrastructure is inadequate or for backup thermal capacity.
- Oil Heating:Liquid fuel combustion persists in legacy installations and remote operations lacking pipeline gas or grid capacity.
Foundry electrification is expanding most quickly in East Asian semiconductor corridors, while gas and oil heating contract to maintenance-only replacement cycles.
Application:
Purity requirements and batch scale determine heating technology selection across downstream material processing stages.
- Metal Refining:High-purity silicon and specialty alloy purification demands electromagnetic stirring and atmosphere control for semiconductor-grade output. Taiwan and South Korean ingot producers dominate capacity expansion.
- Alloy Production:Controlled addition of dopant elements to base metals requires precise temperature maintenance and homogeneous mixing.
- Metal Casting:Pouring molten feedstock into molds for component fabrication suits resistance-heated systems with simpler thermal profiles.
- Scrap Recycling:Recovery of silicon kerf loss and metal swarf employs lower-purity melting specifications with cost-optimized equipment.
- Waste Treatment:Thermal processing of hazardous or contaminated materials requires specialized fume capture and refractory designs.
Semiconductor feedstock refining commands premium equipment specifications. Scrap recycling and waste treatment concentrate demand for standardized resistance platforms.
End User:
Scale and purity requirements stratify procurement patterns across metal processing facility types.
- Foundries:Primary silicon and specialty alloy producers specify induction systems with electromagnetic stirring for ingot casting and crystal growth feedstock preparation. Hsinchu-Taichung corridor foundries maintain multi-source vendor qualification for critical components.
- Metal Fabrication Plants:Secondary processing of ingots into wrought forms employs resistance and arc heating for remelting and shaping operations.
- Recycling Facilities:Kerf loss recovery and scrap reprocessing prioritize throughput economics over purity specifications.
- Die Casting Companies:Aluminum and magnesium alloy melting for automotive and electronics housings uses crucible and resistance furnaces.
- Heat Treatment Workshops:Surface hardening and stress relief operations require controlled thermal cycling rather than full melting capacity.
Integrated foundries with captive crystal growth operations anchor demand for precision induction platforms. Independent recyclers and die casters represent the steepest expansion trajectory for cost-optimized electric furnace categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor foundry investment concentrates in East Asian manufacturing corridors, with Taiwan and South Korea anchoring precision melting capacity expansion for 300mm wafer feedstock production.
United States
Texas and Arizona foundries face EPA emissions retrofit deadlines that compress electric furnace procurement cycles. OSHA workplace exposure limits compound compliance costs for legacy gas-fired installations. The Phoenix-Tucson corridor attracts polysilicon purification capacity as Intel expands domestic ingot sourcing.
Taiwan
Hsinchu Science Park foundries specify induction systems with electromagnetic stirring for contamination-controlled silicon melting. The country's EPA equivalent enforces semiconductor manufacturing emissions standards that phase out combustion-based thermal processing. Taichung's expanding fabrication cluster generates localized demand for precision furnace maintenance services.
South Korea
Samsung Foundry and SK Hynix anchor polysilicon demand at the Giheung and Pyeongtaek complexes. METI-aligned energy efficiency mandates accelerate grid-powered melting system adoption. The Yongin semiconductor cluster attracts induction furnace service providers for high-frequency coil maintenance.
China
MEE dual carbon goals restrict coal-dependent melting operations in Jiangsu and Shandong provinces. Beijing Jingyuntong Technology and domestic competitors supply cost-optimized electric platforms for mid-scale foundry upgrades. The Yangtze River Delta concentrates silicon metal processing capacity seeking electrification retrofit.
Germany
REACH chemical registration requirements force foundries to document crucible material compositions above 1,400°C. The country's federal emissions trading scheme penalizes gas-fired thermal processing in industrial zones. Saxony's semiconductor material suppliers qualify alternative graphite formulations for environmental compliance.
Chip Melting Furnace Market Competitive Landscape
Capacity expansion dominates the current landscape as foundries retrofit gas-fired systems to meet tightening carbon intensity mandates. The vendor base stratifies across three tiers: premium induction specialists, mid-scale electric platform suppliers, and legacy resistance furnace maintainers. Technology licensing and multi-source procurement partnerships represent the dominant competitive vectors as foundries reduce single-supplier dependencies for critical consumable components.
Within the premium induction tier, Inductotherm Corp and PVA TePla AG exemplify electromagnetic heating heritage that anchors North American and European demand for precision melting systems. Ferrotec occupies a position among graphite crucible integration specialists, while Beijing Jingyuntong Technology represents the cost-optimized electric platform archetype serving mid-scale Chinese foundry upgrades. ECM Technologies and MegaMelt Furnaces sit within the specialized service provider segment, with Linton Crystal and Crystal Systems exemplifying crystal growth equipment suppliers whose furnace specifications shape downstream melting system procurement.
| Leading Market Players |
|---|
| Inductotherm Corp |
| PVA TePla AG |
| Linton Crystal |
| Ferrotec |
| Jingsheng |
| Beijing Jingyuntong Technology |
| ECM Technologies |
| MegaMelt Furnaces |
| Crystal Systems |
| Others |
Pricing and Supply Chain Analysis
Induction furnace electrification across East Asian semiconductor corridors simultaneously compresses operating cost structures and concentrates procurement leverage among premium equipment vendors. Taiwan Semiconductor Manufacturing Company and Samsung Foundry procurement teams now bundle long-term service contracts with initial capital expenditure, reshaping how suppliers structure revenue recognition and aftermarket capture.
Pricing Analysis
Warranty and preventive maintenance bundling separates premium induction system vendors from unbundled resistance furnace suppliers competing on upfront capital cost alone. Pricing stratifies across electromagnetic stirring capability tiers, ISO-certified contamination control levels, and regional service network density. Cost compression in mid-scale Chinese foundry segments intensifies because Beijing Jingyuntong Technology and domestic competitors automate quoting for standardized electric platforms. Price sensitivity peaks among Jiangsu province silicon metal processors seeking electrification retrofit without premium induction specifications, while Hsinchu Science Park foundries prioritize electromagnetic uniformity over capital cost minimization.
Supply Chain Analysis
Regional distribution centers in Taichung, Giheung, and Dresden maintain crucible and coil inventory buffers for just-in-time furnace maintenance windows. Isostatic graphite production concentrates in Japan, France, and China, creating input dependency for semiconductor-grade crucible supply. Supply chain risk centers on single-source vulnerability for high-purity graphite formulations qualified to specific furnace architectures. Distribution runs through authorized service partnerships rather than direct OEM-to-foundry relationships, with Inductotherm Corp and Ferrotec maintaining captive technician networks for coil replacement and crucible installation protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into graphite crucible manufacturing and captive polysilicon purification represents the dominant competitive lever as foundries seek supply security for critical melting inputs. Players are racing upstream to control material specifications that determine final ingot purity.
For Market Incumbents: Deepen electromagnetic stirring intellectual property portfolios through patent filing acceleration in South Korea and Taiwan, insulating premium positioning against emerging Chinese electric platform competitors. Secure multi-year crucible supply agreements with Japanese isostatic graphite specialists to defend against input concentration risk. Expand certified technician training programs at Taichung and Yongin service hubs to capture aftermarket revenue streams as installed induction base matures. For New Entrants and Emerging Players: Launch via remote monitoring and predictive maintenance subscription models targeting mid-scale Chinese foundries in Shandong province seeking automation without premium capital deployment. Target alloy production and scrap recycling segments where purity specifications tolerate resistance furnace economics and electromagnetic stirring adds limited value. Pursue qualification partnerships with Yangtze River Delta silicon metal processors seeking MEE-compliant electrification retrofit pathways. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by industrial conglomerates seeking semiconductor materials vertical integration, with financial sponsor secondary buyouts representing alternative liquidity for scaled platform vendors. Long-term viability hinges on electromagnetic coil engineering talent scarcity and foundry electrification mandate durability across EPA and MEE jurisdictions. Watch induction furnace service revenue attachment rates as inflection indicator for installed base monetization maturity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Graphite Crucible Manufacturing | Captive supply of isostatic graphite secures input qualification timelines for Hsinchu foundry contracts. |
| Electromagnetic Stirring Patent Portfolio Expansion | IP protection in Taiwan and South Korea defends premium positioning against Chinese electric platform competitors. |
| Remote Monitoring Platform Launch | Predictive maintenance subscriptions penetrate mid-scale Chinese foundries seeking automation without capital intensity. |
| Certified Technician Network Expansion | Taichung and Yongin service hubs capture aftermarket revenue as installed induction base matures. |
| Multi-Source Crucible Qualification Program | Secondary vendor approval mitigates concentration risk in Japanese and French graphite supply. |
Research Methodology
Multi-period observation of foundry capital expenditure cycles, EPA enforcement timelines, and polysilicon price volatility anchored the trend analysis, supplemented by interviews with semiconductor materials procurement directors, induction furnace service technicians, graphite crucible manufacturing executives, and MEE compliance officers. Primary fieldwork combined with secondary validation drawing from SEC equipment supplier filings, Taiwan EPA emissions disclosure databases, China MEE enforcement bulletins, and semiconductor industry association capacity tracking reports. Bottom-up installation counts across Hsinchu, Giheung, and Pyeongtaek complexes triangulated against top-down foundry capital expenditure aggregation.
The input-output matrix modeled furnace shipments against silicon ingot capacity expansion, electrification retrofit mandates, and crucible consumption rates across the projection horizon. Segmentation dimensions included heating modality, purity specification tier, end-use application, and regional regulatory cluster. CAGRs derived from curve-fitting historical procurement cycles to announced foundry buildout schedules, with polysilicon price elasticity and EPA compliance deadline acceleration serving as scenario sensitivity inputs.
Polysilicon feedstock price collapse, EPA enforcement delay, and graphite crucible supply disruption are the dominant revision risks that could compress or extend electrification retrofit timelines. Forecasts reflect documented assumptions regarding regulatory mandate durability and foundry capital availability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Manufacturing
China Electronic Design Automation (EDA) Tools Market
Semiconductor Manufacturing
PCB Photoresist Market
Semiconductor Manufacturing
Malaysia and Thailand Precession Cleaning for Electronic Market
Semiconductor Manufacturing
Europe Electronic Manufacturing Services Market
Semiconductor Manufacturing
Surface Mount Technology (SMT) Market
Semiconductor Manufacturing
Semiconductor and Electronic Parts Manufacturing Market
Semiconductor Manufacturing
Solder Paste Market
Semiconductor Manufacturing
Global EUV Lithography Market
Semiconductor Manufacturing
Semiconductor and Circuit Manufacturing Market
Semiconductor Manufacturing
Europe Photoresist and Photoresist Ancillaries Market
Semiconductor Manufacturing
Global Wafer Cutting Fluids Market
Semiconductor Manufacturing
Silicon Wafer Reclaim Market
Semiconductor Manufacturing
Semiconductor Polishing Pads Market
Semiconductor Manufacturing
Photomask Market
Semiconductor Manufacturing
High Purity Process Systems for Semiconductor Market
Semiconductor Manufacturing
Global Overall EUV Lithography Market