
 Medical Component Manufacturing Market | 2026-2036
Medical Component Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Component Manufacturing Market Intelligence
A sourcing model shift from in-house production toward specialized contract manufacturing is expanding opportunities for component specialists. Large medical device OEMs increasingly rely on external partners for non-core components to focus on R&D and market access. Medtronic leverages a vast network of suppliers for its diverse portfolio, while Stryker Corporation specializes in high-precision orthopedic components. Johnson & Johnson MedTech sustains its market position by controlling critical component design and quality through strategic partnerships.
Medical component manufacturing involves the precision fabrication of parts for medical devices, instruments, and apparatus. These components, often requiring sub-micron tolerances and biocompatible surfaces, are integral to the function and safety of healthcare technologies. High-performance plastics and specialized metal alloys like titanium represent the core of the material segment, driven by applications in single-use devices and implants. Within applications, components for surgical tools command higher margins due to stringent performance and sterilization requirements.
Regulatory compliance is a primary barrier to entry, governed by bodies like the US FDA and China's NMPA. The European Union's Medical Device Regulation (MDR) imposes rigorous traceability and quality management system requirements on all component suppliers. Component manufacturers must now decide between specializing in high-margin, complex parts or achieving scale in high-volume, standardized components to maintain competitiveness.
Market Dynamics
The central structural force shaping the market is the strategic outsourcing by large medical device OEMs. This shift toward specialized contract manufacturing is a direct response to escalating regulatory burdens and the internal need to dedicate capital to core research and development.
Growth Catalysts
- Advanced Biocompatible Polymers:The development of high-performance plastics like PEEK and bioresorbable polymers creates new applications in single-use surgical instruments and temporary implants, reducing sterilization costs and infection risks.
- Diagnostic Equipment Expansion:Demand for precision components for in-vitro diagnostic (IVD) systems and medical imaging apparatus is rising, driven by a focus on early disease detection and personalized medicine.
- Manufacturing Hub Concentration:Government incentives and established logistics networks in countries like Ireland, Costa Rica, and Germany attract investment, creating dense ecosystems of specialized component suppliers and skilled labor.
Market Restraints
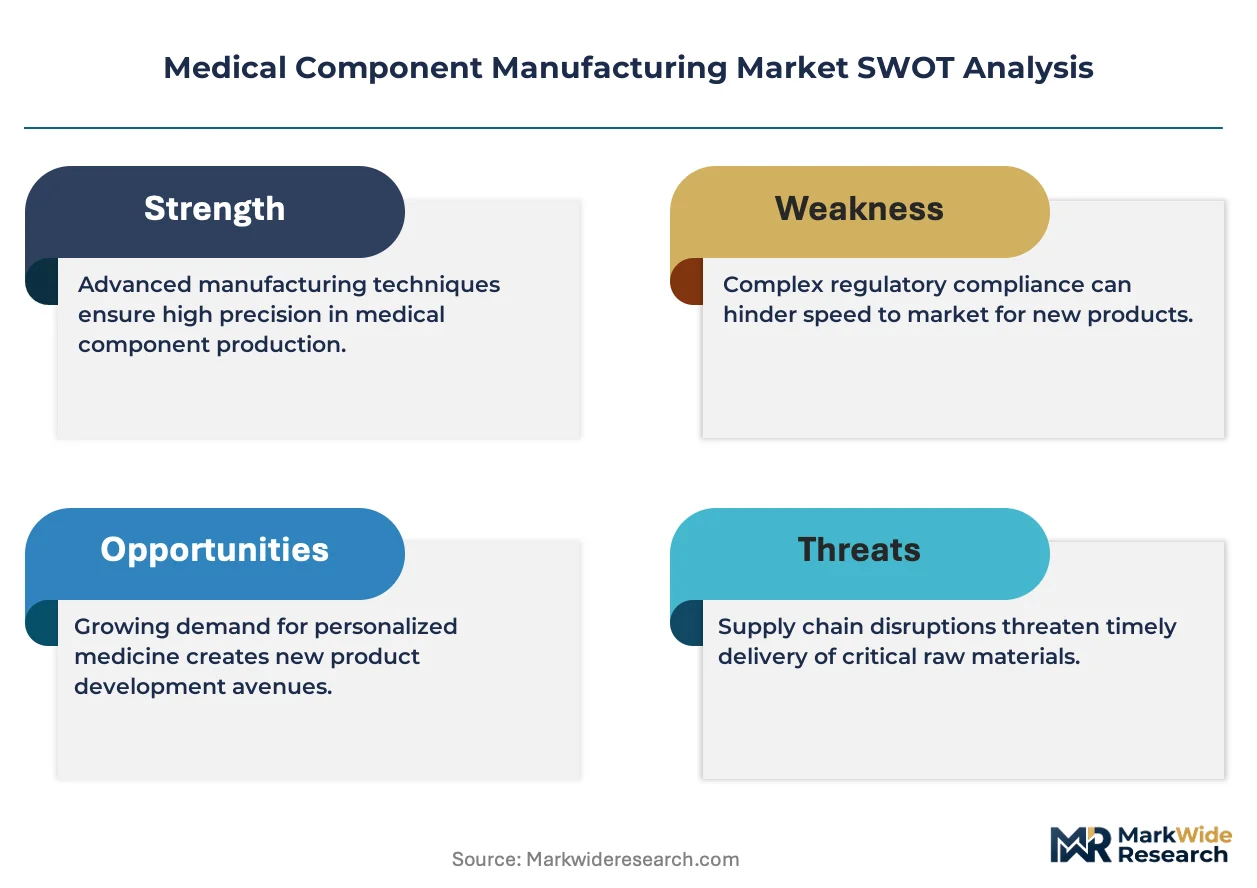
- Stringent Regulatory Hurdles:The European Union's Medical Device Regulation (MDR) imposes rigorous quality and traceability requirements that increase compliance costs and timelines, acting as a significant barrier for new and smaller entrants.
- Raw Material Price Volatility:The market for specialized inputs like medical-grade titanium and cobalt-chrome alloys is subject to supply fluctuations and geopolitical factors, creating input cost uncertainty for implant manufacturers.
- Technical Production Limits:Achieving and verifying sub-micron tolerances for complex micro-components at industrial scale remains a significant technical challenge, limiting the pool of qualified suppliers for the most advanced devices.
Strategic Opportunities
- Robotic Surgery Systems:Manufacturing high-precision actuators, end-effectors, and sterile-drape components for robotic surgical platforms represents a high-margin opportunity tied to the expansion of minimally invasive procedures.
- Sensor Integration:Incorporating micro-sensors and wireless communication capabilities into traditional components for implants and diagnostic tools opens avenues for smart devices that provide real-time patient data.
- Emerging Market Capabilities:As medical device production grows in Southeast Asian nations, there is an opportunity for component specialists to establish local facilities to serve this expanding regional manufacturing base.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of skilled labor, including CNC machinists and quality engineers with expertise in medical device standards like ISO 13485, constrains production capacity and quality control.
- High Capital Expenditure:The need for certified cleanroom environments, advanced metrology equipment, and multi-axis machining centers requires substantial upfront capital investment, raising the barrier to entry for complex component manufacturing.
- Protracted Validation Cycles:The extensive testing and documentation required for component validation by regulatory bodies such as the US FDA and China's NMPA can significantly delay product launches and revenue generation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Component Manufacturing Market |
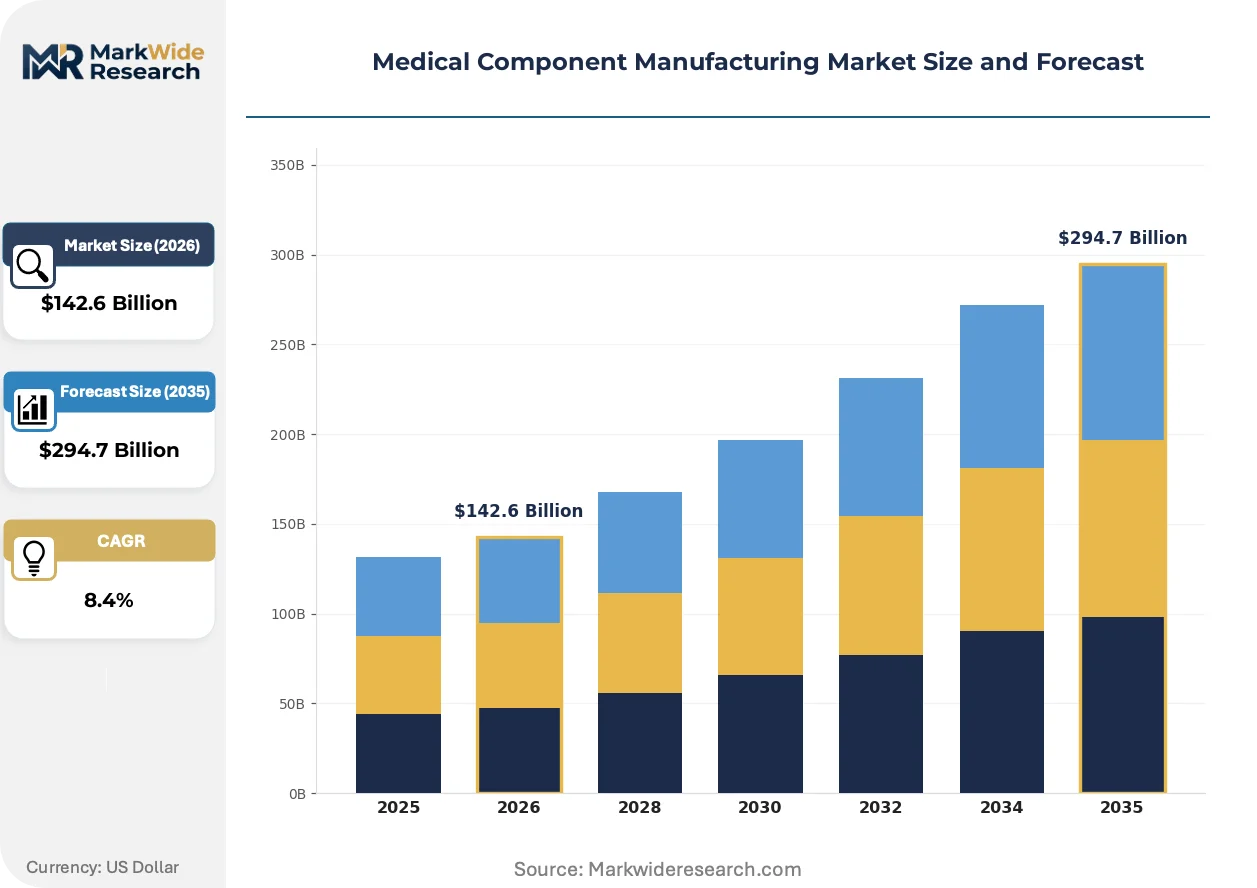
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $294.7 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Devices, Instruments, Apparatus, Tools Material: Plastic, Metal, Ceramic, Composite Application: Diagnostic Equipment, Surgical Tools, Patient Monitoring, Rehabilitation Devices End User: Hospitals, Clinics, Laboratories, Research Centers |
| Companies Covered | Medtronic, Johnson & Johnson MedTech, GE Healthcare, Siemens Healthineers, Stryker Corporation, Abbott Laboratories, Boston Scientific, Philips Healthcare, Becton Dickinson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Component Manufacturing Market Strategic Shifts & Innovations
Material science advancements and digital manufacturing technologies are fundamentally altering component design and production capabilities. This evolution occurs within a framework of increasingly stringent global regulations that prioritize device traceability and patient safety, forcing suppliers to innovate their processes.
Additive manufacturing using materials like titanium and cobalt-chrome powders allows for the creation of intricate, lightweight components with porous structures that promote osseointegration. Orthopedic and craniomaxillofacial device makers are the primary adopters for producing patient-specific implants. This production method is converging with surgical planning software to create a seamless, digitized workflow from medical scan to final implant.
The global push for Unique Device Identification (UDI) systems, enforced by regulators like the US FDA and under the EU's MDR, is a critical policy shift. This mandate necessitates direct part marking on even small components, establishing a comprehensive traceability record from factory to patient. Suppliers of high-risk cardiovascular and neurological components are most impacted, investing in laser marking technology and integrated data management systems.
A shift in healthcare delivery toward value-based models is changing purchasing criteria for medical devices. Hospital procurement now evaluates the total cost of care, favoring components that enhance device reliability and longevity to minimize costly revision procedures. This trend is most pronounced in the orthopedics sector in markets like Germany and the United States, where reimbursement is increasingly tied to long-term patient outcomes.
Medical Component Manufacturing Market Segmentation
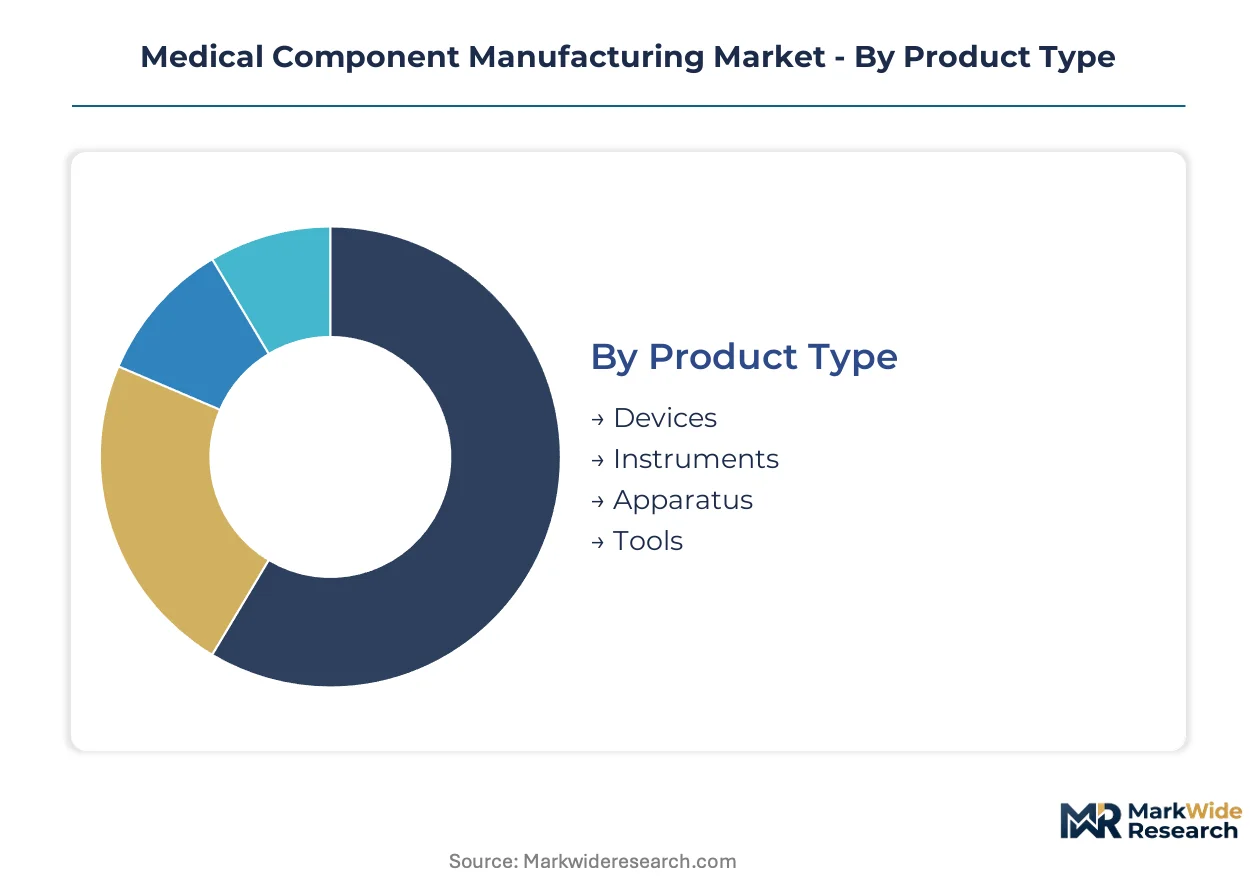
Understanding the varied requirements across the medical component manufacturing landscape is vital for strategic market engagement. Segmentation provides clarity on the diverse product types, materials, applications, and end-users driving demand and value within this specialized industry.
Product Type:
The product type segmentation differentiates between high-volume, standardized components and complex, custom-fabricated parts, influencing manufacturing processes and pricing structures.
- Devices:These encompass complex assemblies or sub-assemblies integral to finished medical products, often requiring specialized tooling and multi-component integration. Demand concentrates in implantable devices for orthopedics and cardiovascular health, driven by an aging global population.
- Instruments:Instruments include precision-machined tools used in surgical procedures and diagnostic examinations, frequently demanding specific surface finishes and sterilization capabilities. Demand for these components is high in minimally invasive surgery, requiring smaller, more intricate designs.
- Apparatus:Apparatus components are typically larger, often forming the structural or functional core of medical equipment like imaging machines or patient support systems.
- Tools:Medical tools represent a broad category of hand-held or power-assisted instruments, with components ranging from simple grips to intricate cutting edges.
Today's leader: Devices. Tomorrow's challenger: Instruments.
Material:
Material selection is critical, balancing biocompatibility, mechanical properties, and cost, leading to distinct supply chain dynamics across different material types.
- Plastic:High-performance plastics, including PEEK and bioresorbable polymers, are utilized for lightweight, single-use surgical components and temporary implants. Demand is expanding for these materials in diagnostic consumables due to their cost-effectiveness and versatility.
- Metal:Specialized metal alloys such as medical-grade titanium and cobalt-chrome are essential for load-bearing implants and precision surgical instruments. Demand for metal components remains robust in orthopedic reconstruction, driven by their strength and long-term durability.
- Ceramic:Ceramic components offer exceptional hardness and wear resistance, finding application in joint replacements and dental implants.
- Composite:Composite materials combine different elements to achieve enhanced properties, often used in lightweight structural components for medical equipment.
The plastic material segment is expanding most quickly due to innovation in polymer science. Metal components continue to command significant market value.
Application:
Application segments reflect the specific functional requirements of different medical technologies, dictating component design, regulatory compliance, and market growth trajectories.
- Diagnostic Equipment:Components for diagnostic equipment, including IVD systems and medical imaging apparatus, require high precision and often incorporate sensor technologies. Demand is rising in Asia-Pacific nations for early disease detection systems, necessitating specialized optical and fluidic components.
- Surgical Tools:Components for surgical tools are critical for procedural efficacy, demanding sub-micron tolerances and resistance to harsh sterilization cycles. Demand for these components is particularly strong in robotic surgery platforms, driving innovation in micro-actuators.
- Patient Monitoring:Components for patient monitoring devices include sensors and connectors that ensure accurate real-time data collection in clinical settings.
- Rehabilitation Devices:Rehabilitation device components support patient recovery, ranging from prosthetic parts to structural elements in therapeutic equipment.
Diagnostic Equipment applications are gaining share fastest as healthcare systems prioritize preventative care. Surgical Tools maintain a high-value position.
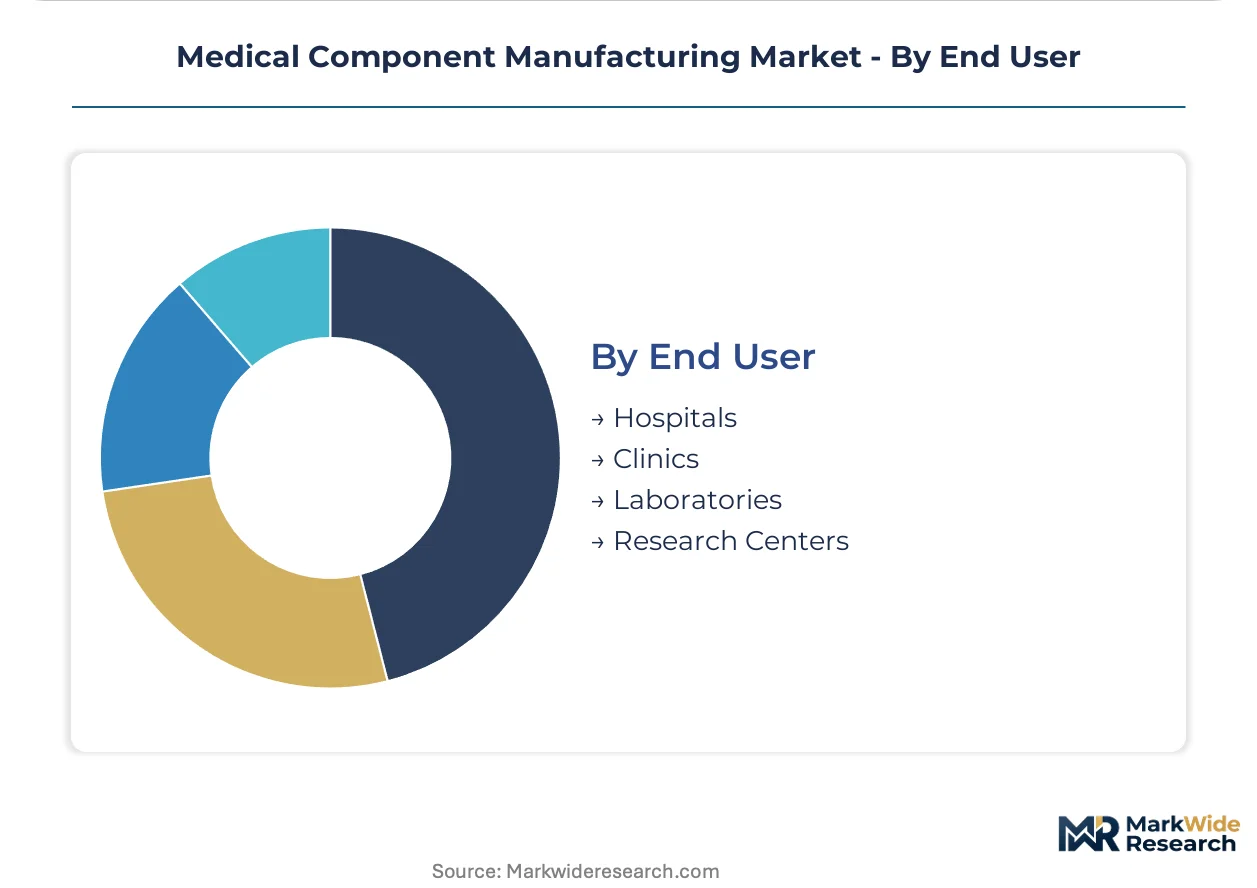
End User:
End-user segments highlight where medical components are ultimately integrated and consumed, influencing procurement patterns and volume requirements.
- Hospitals:Hospitals represent a major end-user segment, procuring a wide array of components for their surgical departments, diagnostic labs, and patient care units. Demand from hospitals is influenced by evolving surgical techniques and the adoption of new medical technologies in urban centers.
- Clinics:Clinics, including specialized outpatient facilities, require components for diagnostic procedures, minor surgeries, and patient consultations. Demand is growing in primary care clinics in Europe for cost-effective, high-quality disposable components.
- Laboratories:Medical laboratories utilize components for in-vitro diagnostics, research, and analytical testing, often requiring sterile and precision-engineered parts.
- Research Centers:Research centers drive demand for specialized, often custom-made components for experimental devices and advanced medical studies.
Hospitals remain the largest purchasing segment for medical components. Clinics exhibit a steepest expansion trajectory in component procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing hubs in Germany, Ireland, and Costa Rica drive significant medical component production. These regions benefit from established logistics networks and specialized labor pools. Demand for precision components also rises across Asia-Pacific nations.
Germany
Germany's medical component sector experiences demand from advanced diagnostic equipment and high-precision surgical tools. The European Union's Medical Device Regulation (MDR) enforces rigorous quality management systems across the supply chain. Bavaria and North Rhine-Westphalia host numerous specialized suppliers focusing on complex micro-components for medical imaging and robotic surgery systems.
Ireland
Ireland's medical device industry necessitates components for implantable devices and single-use surgical instruments. Irish regulatory bodies align with EU MDR, ensuring strict traceability and quality controls for all manufacturers. The "Medical Technologies Cluster" around Galway and Cork attracts significant foreign direct investment, fostering a dense ecosystem for high-performance plastics and specialized metal alloys.
United States
The United States drives demand for components in robotic surgery systems and advanced patient monitoring devices. The US FDA imposes stringent approval processes for medical device components, influencing design and manufacturing. The Boston-Cambridge area and Southern California are key centers for R&D and precision manufacturing, developing cutting-edge sensor integration for smart medical devices.
Costa Rica
Costa Rica demonstrates strong demand for high-volume production of disposable medical devices and surgical kits for export. Costa Rica's Free Trade Zone regime offers incentives for medical device manufacturers, supporting export-oriented component production. The Greater Metropolitan Area, particularly Heredia, serves as a significant manufacturing base for plastic injection molding and assembly operations, leveraging skilled labor and proximity to North American markets.
Japan
Japan's aging population necessitates advanced orthopedic implants and diagnostic imaging components. Japan's PMDA ensures rigorous quality standards and safety protocols for medical device components. Tokyo and Osaka regions house specialized manufacturers focusing on micro-precision machining and advanced material science for surgical instruments and minimally invasive technologies.
Medical Component Manufacturing Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue high-precision, specialized component niches. The market exhibits a tiered structure, from high-volume standardized parts to custom-engineered, sub-micron tolerance components. Strategic archetypes include diversified medical technology giants, specialized contract manufacturers, and innovative material science firms. Dominant competitive moves involve strategic partnerships for non-core components and targeted acquisitions to expand technological capabilities.
Within the diversified medical technology giant archetype, Medtronic represents a vast network approach, leveraging external partners for its diverse portfolio of medical devices. Johnson & Johnson MedTech occupies a position emphasizing stringent control over critical component design and quality, often achieved through strategic partnerships. Stryker Corporation exemplifies a focus on high-precision orthopedic components, anchoring its specialization within the broader medical device landscape. These entities often outsource non-core manufacturing to specialized component suppliers, allowing them to concentrate capital on research and development and market access. This strategic outsourcing reshapes competitive positioning for smaller, specialized manufacturers.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson MedTech |
| GE Healthcare |
| Siemens Healthineers |
| Stryker Corporation |
| Abbott Laboratories |
| Boston Scientific |
| Philips Healthcare |
| Becton Dickinson |
Cost & Logistics Intelligence
Skilled labor concentrations in Germany, Ireland, and Costa Rica drive distinct labor-cost differentials that contribute to the pricing tier spreads for specialized medical components. These regional hubs, bolstered by government incentives, attract advanced manufacturing operations requiring highly trained technicians. The strategic outsourcing by large medical device OEMs further influences pricing by creating demand for both high-volume and highly specialized component suppliers.
Pricing Analysis
Input cost pass-throughs significantly influence medical component pricing, particularly for specialized metal alloys and high-performance polymers. Contract-based long-term offtake agreements dominate for critical components supplied to major OEMs, while per-unit transactional pricing applies to smaller, custom orders. Price differentiation stems from certification level, such as EU MDR compliance, and the complexity of achieving sub-micron tolerances. Pricing softness reflects OEM strategies to optimize supply chain costs, especially for high-volume standardized components. Hospitals exhibit higher price sensitivity for disposable components, while Medtronic and Stryker Corporation prioritize quality and reliability for implantable devices.
Supply Chain Analysis
Medical-grade titanium and cobalt-chrome alloy supply rests on a global network with significant processing capabilities concentrated in specific regions. Geographic supply concentration includes manufacturing hubs in Germany, Ireland, and Costa Rica, which serve as key nodes for precision fabrication. Raw material price volatility, influenced by geopolitical factors, poses a structural risk to implant manufacturers. The distribution model primarily runs through direct channels to large medical device OEMs and specialized distributors for smaller component buyers. Advanced biocompatible polymers, like PEEK, are sourced from a specialized chemical industry base, often with limited alternative suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Medical Component Manufacturing Market operates as a regulatory compounder, with the European Union's Medical Device Regulation (MDR) driving significant investment in traceability and quality management systems across the supply chain.
For Market Incumbents: To counter the rising capital expenditure for certified cleanroom environments and advanced metrology equipment, incumbents should pursue targeted acquisitions of specialized contract manufacturers. Strategic partnerships with material science firms can secure access to next-generation biocompatible polymers, maintaining a competitive edge. Investment in ISO 13485 certification and robust quality management systems remains a critical lever for market defense against new entrants.
For New Entrants and Emerging Players: Additive manufacturing capabilities for patient-specific implants present a technology-first wedge into the orthopedic and craniomaxillofacial device segments. Focus on niche applications requiring intricate geometries and rapid prototyping, which traditional manufacturing struggles to achieve. Collaborate with surgical planning software providers to offer integrated design-to-production workflows. Target emerging markets in Southeast Asia by establishing localized production facilities to serve regional medical device manufacturers.
For Investors and Strategic Acquirers: Large medical device OEMs are the most active acquirers in this space, seeking to consolidate specialized capabilities and secure critical component supply. The long-term viability of this market is strong, driven by an aging global population and increasing demand for advanced healthcare technologies. Acquisition targets should include specialized contract manufacturers with expertise in micro-components or advanced material processing. The consolidation of regional manufacturing hubs, particularly in Ireland and Costa Rica, is a key signal to watch as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquire specialized contract manufacturers | Expands high-precision fabrication capabilities and secures supply for Medtronic and Johnson & Johnson MedTech. |
| Invest in additive manufacturing technologies | Enables production of complex, patient-specific implants for orthopedic and craniomaxillofacial applications. |
| Establish facilities in Southeast Asian hubs | Serves the expanding medical device production base in emerging markets. |
| Develop advanced biocompatible polymer components | Creates new applications in single-use surgical instruments and temporary implants. |
| Integrate micro-sensors into traditional components | Facilitates the development of smart medical devices providing real-time patient data for Philips Healthcare. |
Research Approach
Multiple input streams — primary interviews, secondary validation, and internal databases — were reconciled to construct a robust market analysis. Researchers conducted in-depth discussions with medical device OEMs, component suppliers, regulatory affairs specialists, and hospital procurement managers. Secondary data sources included US FDA filings, EU MDR guidelines, industry association reports, and financial disclosures of key market participants. Both bottom-up and top-down triangulation methods were employed to ensure data accuracy and consistency.
The data-stream reconciliation informed an analytical framework that integrated qualitative insights with quantitative models to project market trends. Segmentation dimensions modeled included product type, material, application, end-user, and regional manufacturing ecosystems. Compound annual growth rates were derived from historical data analysis and projected shifts in healthcare expenditure and technological adoption across the analysis window. Key forecast inputs included demographic changes, material science breakthroughs, and evolving regulatory landscapes impacting medical component demand.
The model holds under conditions of a stable regulatory environment and consistent raw material supply; deviation in geopolitical supply disruptions or major regulatory overhauls would shift market projections. Forecasts reflect assumptions regarding technological advancements and healthcare infrastructure development. Raw material price volatility and specialized talent scarcity represent specific risk factors that warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Manufacturing
United States Photoresist and Photoresist Ancillaries Market
Semiconductor Manufacturing
EUV Lithography Service Market
Semiconductor Manufacturing
Europe Electronic Manufacturing Services Market
Semiconductor Manufacturing
Solar Laser Drilling Market
Semiconductor Manufacturing
Battery Manufacturing Machines Market
Semiconductor Manufacturing
High Purity Process Systems for Semiconductor Market
Semiconductor Manufacturing
Solder Paste Market
Semiconductor Manufacturing
Advanced Process Control Market
Semiconductor Manufacturing
Electronic Manufacturing Services (EMS) Market
Semiconductor Manufacturing
PCB Photoresist Market
Semiconductor Manufacturing
Surface Mount Technology (SMT) Market
Semiconductor Manufacturing
Semiconductor and Electronic Parts Manufacturing Market
Semiconductor Manufacturing
Photoresist Stripper Market
Semiconductor Manufacturing
Global Wafer Cutting Fluids Market
Semiconductor Manufacturing
IC CMP Slurries and Pads Market
Semiconductor Manufacturing
Malaysia and Thailand Precession Cleaning for Electronic Market