
 China Electronic Design Automation (EDA) Tools Market | 2026-2036
China Electronic Design Automation (EDA) Tools Market Size, Share, and Industry Trends Forecast 2026-2036
China Electronic Design Automation (EDA) Tools Market Outlook
Subscription-based licensing is pivoting how vendors monetize EDA workflows across China's design ecosystem. Synopsys Inc. leverages recurring revenue frameworks to deepen engagement with domestic foundry partners. Cadence Design Systems Inc. anchors its position through advanced node verification suites tailored for Chinese process technologies. Beijing Huada Jiutian Software Co., Ltd. competes on localized support and government-backed procurement channels.
Electronic Design Automation tools encompass software platforms that enable integrated circuit and printed circuit board design through algorithmic simulation, layout verification, and parasitic extraction down to nanometer-scale geometries. These systems automate the translation of electronic specifications into manufacturable mask layouts for semiconductor fabrication. IC Design commands the deepest investment pools as Chinese foundries advance toward sub-7nm process nodes. Cloud-Based deployment is expanding fastest among mid-tier fabless startups seeking elastic compute capacity without capital-intensive infrastructure. Simulation retains durable margin strength due to its critical role in pre-silicon validation cycles.
MIIT mandates GB standards compliance for domestic EDA procurement in sensitive technology sectors, while SAMR enforces anti-monopoly scrutiny on foreign software licensing terms. The country's dual carbon goals pressure data center operators hosting cloud-based EDA workloads to improve energy efficiency metrics. Stakeholders must weigh sovereign technology mandates against interoperability requirements when selecting toolchains for multi-node design pipelines.
Market Dynamics
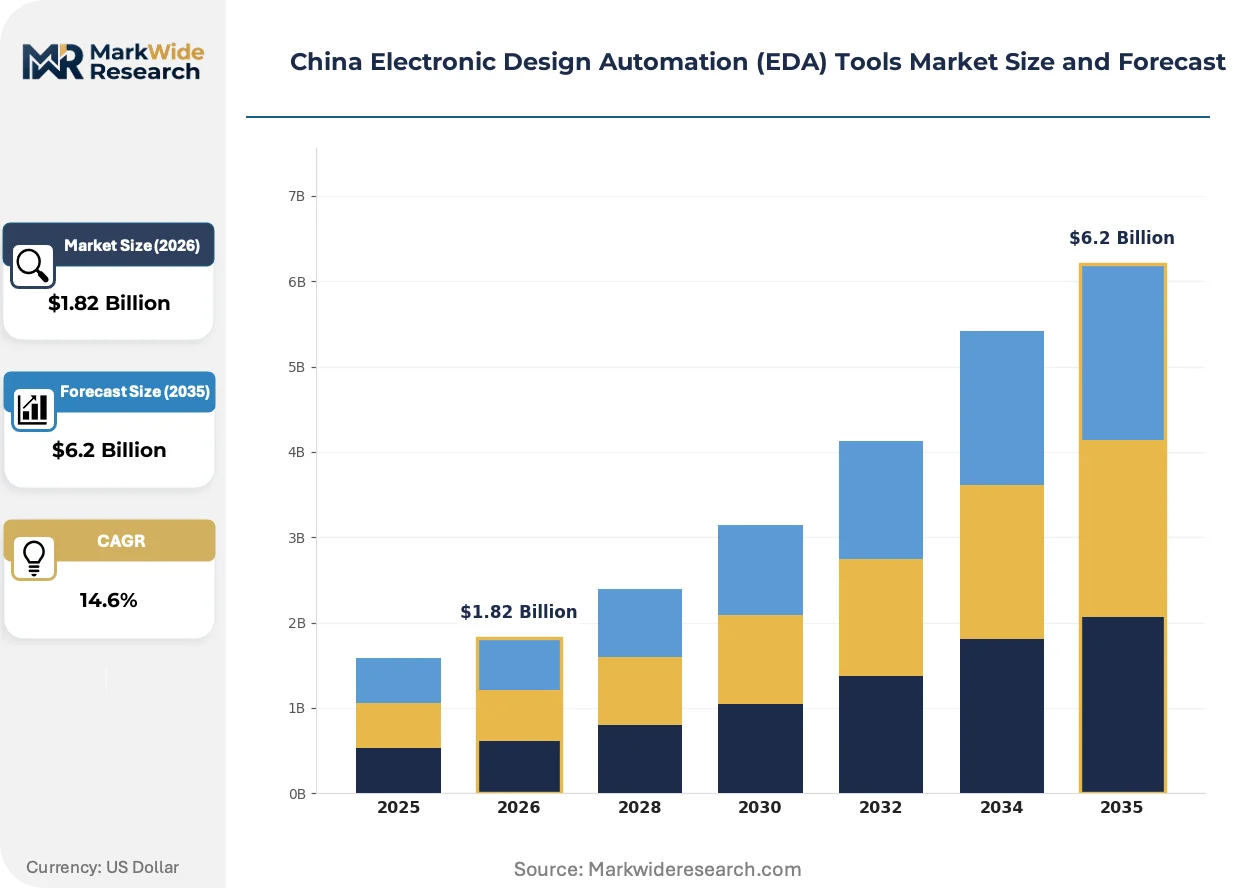
Cloud-based EDA deployment is compressing capital barriers for Chinese fabless startups while MIIT procurement mandates force toolchain localization decisions across the semiconductor design ecosystem.
Growth Catalysts
- MIIT Domestic Procurement Mandates:GB standards compliance requirements channel government-backed R&D funding toward indigenous EDA vendors. State-backed foundries must certify domestic toolchains for sensitive node development.
- Sub-7nm Process Node Expansion:Advanced verification suites attract capital as SMIC and Hua Hong ramp domestic logic and memory production. Physical design complexity multiplies compute demand per tape-out cycle.
- Shanghai-Shenzhen Design Cluster Density:Fabless concentration in eastern coastal provinces creates network effects for cloud-based EDA platform adoption. Proximity to foundry engineering teams accelerates iteration velocity.
Market Restraints
- Advanced Node IP Licensing Costs:Foundry-specific process design kit fees escalate non-recurring engineering budgets for sub-10nm tape-outs. Foreign IP aggregators control critical standard cell libraries.
- High-Performance Computing Infrastructure Concentration:Cloud-based EDA workloads depend on limited domestic data center GPU clusters. NVIDIA export controls constrain elastic simulation capacity expansion.
- SAMR Anti-Monopoly Enforcement:Foreign vendor licensing term investigations create procurement uncertainty for multinational design houses. Compliance reviews delay enterprise agreement renewals.
Strategic Opportunities
- Western China Design House Expansion:Chengdu and Xi'an fabless startups remain underserved by on-premise EDA infrastructure. Cloud-native deployment models bypass capital constraints in inland provinces.
- AI-Accelerated Verification Convergence:Machine learning inference engines compress formal verification runtime for complex SoC designs. Neural network-based parasitic extraction reduces signoff iteration counts.
- Dual Carbon Data Center Incentives:MEE efficiency mandates for cloud computing facilities favor EDA workload migration to renewable-powered server farms. Carbon accounting integration becomes procurement evaluation criteria.
Industry Challenges
- Multi-Physics Simulation Talent Scarcity:Electromagnetic-thermal co-simulation expertise concentrates among senior engineers at foreign-trained domestic vendors. University pipeline output lags foundry demand curves.
- Heterogeneous Integration Verification Complexity:Chiplets and 3D stacking architectures break traditional flat verification methodologies. Legacy toolchains require expensive methodology re-engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Electronic Design Automation (EDA) Tools Market |
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $6.2 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Schematic Capture, PCB Layout, Simulation, IC Design Deployment Model: On-Premises, Cloud-Based, Hybrid, Subscription-Based End User: Semiconductor Companies, Telecom, Automotive, Aerospace Application: Telecommunications, Consumer Electronics, Industrial Automation, Medical Devices |
| Companies Covered | Altium Limited, Xpeedic Technology, Inc., Synopsys Inc., Ansys Inc., Zuken Ltd., Cadence Design Systems Inc., Beijing Huada Jiutian Software Co., Ltd., Keysight Technologies Inc., Siemens EDA (Mentor Graphics), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Electronic Design Automation (EDA) Tools Market Strategic Shifts
Computational lithography and AI-assisted physical design are compressing time-to-tape-out cycles while regulatory pressure on software supply chains forces architectural decisions around data sovereignty and cross-border collaboration protocols.
Machine learning-accelerated place-and-route engines are unifying timing closure and power optimization into single-pass workflows. Mid-tier fabless houses in Shenzhen adopt these tools aggressively to compensate for smaller physical design teams. This unifying architecture collapses the traditional iterative loop between synthesis and signoff, reducing mask preparation schedules by substantial margins.
MIIT's GB standards compliance framework for sensitive technology procurement is mandating domestic EDA toolchain certification for government-funded chip projects. Foreign vendors must establish localized code escrow and data residency architectures to maintain foundry partnerships. Advanced node verification suites face the steepest adaptation requirements under these technical security specifications.
Subscription licensing models are displacing perpetual seat purchases across China's design ecosystem. Fabless startups in Beijing and Hangzhou favor consumption-based simulation access over capital-intensive infrastructure commitments. This behavioral pivot concentrates vendor revenue predictability while fragmenting buyer negotiating leverage across quarterly renewal cycles.
China Electronic Design Automation (EDA) Tools Market Segmentation
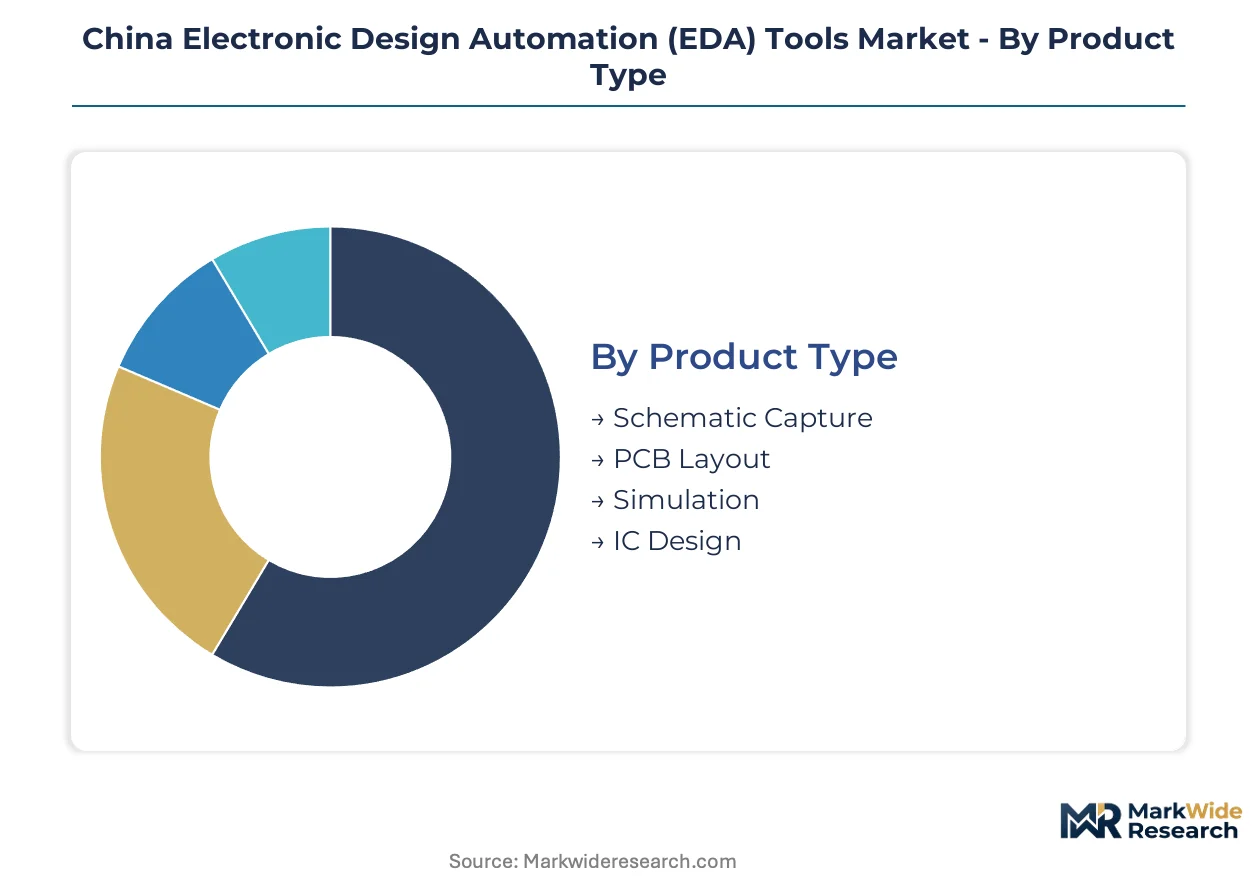
EDA tool segmentation in China reveals how procurement priorities diverge between state-backed foundry mandates and fabless startup agility. Deployment models and end-user verticals fragment the addressable market across distinct technology maturity curves and capital intensity thresholds.
Product Type:
IC Design commands premium pricing while Simulation captures volume deployment across China's eastern coastal design clusters.
- IC Design:Physical design, synthesis, and place-and-route tools translate RTL specifications into manufacturable mask layouts. Shanghai-based foundries drive demand for sub-7nm node support as domestic logic production scales.
- Simulation:Pre-silicon validation platforms model circuit behavior under thermal, electromagnetic, and process variation stress. Shenzhen fabless houses deploy these tools aggressively for tape-out risk mitigation.
- Schematic Capture:Entry-level circuit diagramming tools serve educational institutions and hobbyist hardware developers.
- PCB Layout:Printed circuit board routing and verification software addresses industrial automation and medical device manufacturers in Guangdong province.
Today's leader: IC Design. Tomorrow's challenger: Simulation.
Deployment Model:
Capital expenditure sensitivity among mid-tier design houses accelerates cloud migration, while security-conscious state projects retain on-premise infrastructure.
- Cloud-Based:Elastic compute provisioning eliminates server procurement cycles for Beijing and Hangzhou startups. MIIT efficiency mandates for data center energy consumption shape vendor selection criteria.
- Subscription-Based:Recurring licensing converts upfront capital burdens into operational expenditures. Fabless houses favor quarterly renewal flexibility over perpetual seat purchases.
- On-Premises:Air-gapped installations satisfy GB standards compliance for sensitive node development at state-backed foundries.
- Hybrid:Mixed deployment architectures partition confidential IP development locally while bursting simulation workloads to cloud infrastructure.
Cloud-Based deployment expands most quickly among venture-funded startups. Hybrid architectures gain traction among established design houses navigating data sovereignty requirements.
End User:
Semiconductor companies anchor procurement volume while Automotive emerges as the fastest-climbing vertical on chiplet integration timelines.
- Semiconductor Companies:Foundries and fabless design houses constitute the core installed base. SMIC and Hua Hong procurement decisions cascade through domestic supply chains.
- Automotive:Functional safety verification requirements for autonomous driving SoCs reshape tool selection. Tier-1 suppliers in Chongqing and Wuhan invest in ISO 26262-compliant validation suites.
- Telecom:Baseband processor development for 5G infrastructure drives physical design complexity at state-owned equipment vendors.
- Aerospace:Radiation-hardened design methodologies serve satellite and avionics programs with extended qualification cycles.
Semiconductor companies retain procurement dominance. Automotive verticals show steepest expansion trajectory on electrification and autonomy investment.
Application:
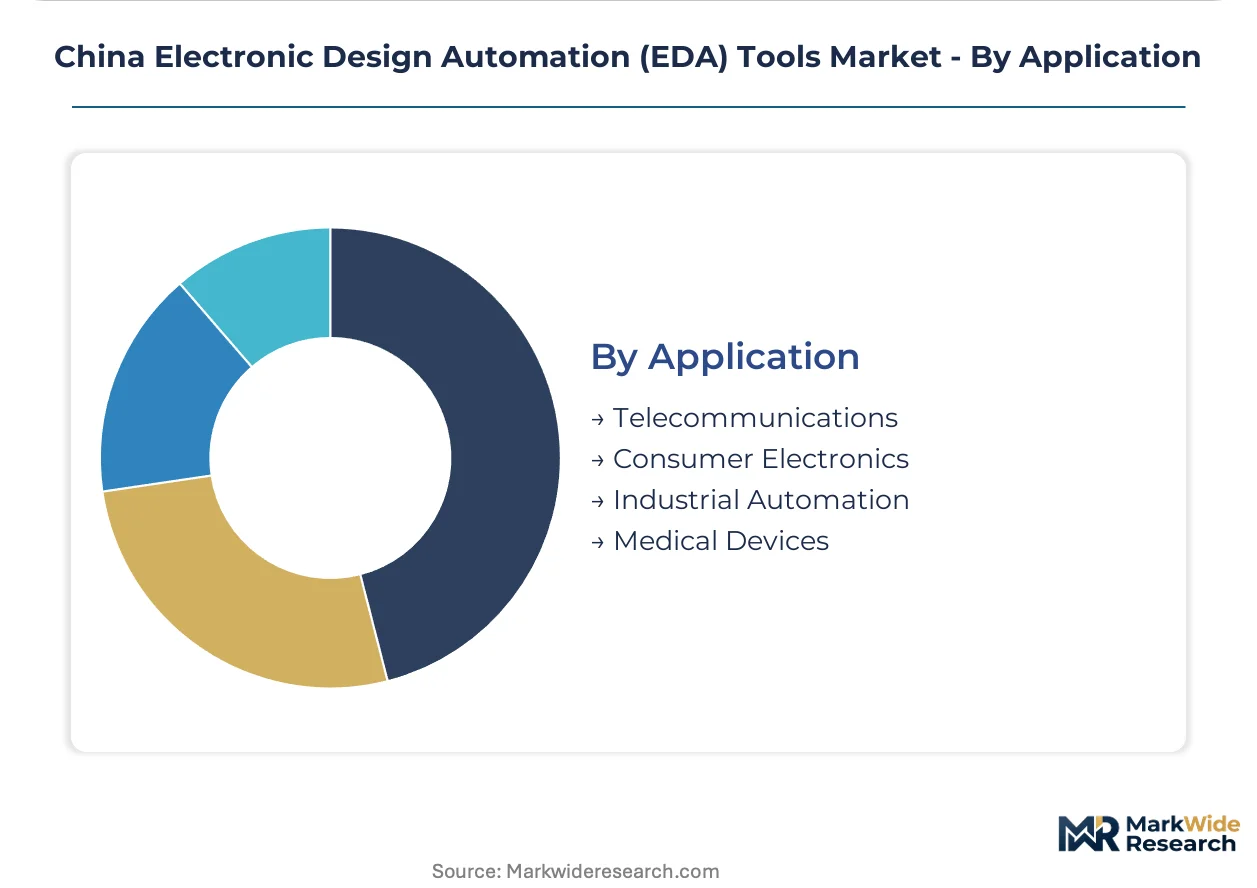
Telecommunications absorbs the deepest engineering hours while Medical Devices commands the highest verification rigor per design.
- Telecommunications:Base station and optical networking silicon require mixed-signal simulation at scale. Huawei and ZTE procurement patterns influence domestic EDA roadmap priorities.
- Consumer Electronics:Smartphone and wearable SoC design cycles compress timing closure requirements. Shenzhen ecosystem density accelerates iteration velocity.
- Industrial Automation:Motor control and power management ICs prioritize electromagnetic co-simulation for reliability certification.
- Medical Devices:Implantable and diagnostic equipment demands fault-tolerant verification methodologies with extensive documentation trails.
Telecommunications leads by design starts. Medical Devices climbs fastest on regulatory compliance tool investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's EDA procurement patterns diverge sharply from South Korea's concentrated chaebol-driven demand, where Samsung and SK Hynix dominate tool selection. Japan maintains legacy vendor relationships through decades-old keiretsu ties, while Taiwan's foundry-centric ecosystem prioritizes process-specific verification suites.
United States
Silicon Valley fabless houses and Austin-based analog design firms drive demand for cloud-native EDA platforms. FDA oversight of medical device semiconductors imposes verification documentation requirements that shape tool selection. Boston's defense electronics cluster sustains air-gapped on-premise installations for sensitive aerospace programs.
South Korea
Samsung Electronics and SK Hynix procurement teams negotiate enterprise-wide EDA licenses covering memory and logic design pipelines. The country's national semiconductor regulator enforces export control compliance for advanced node tool transfers. Seoul-Pangyo corridor concentration enables rapid vendor engineering support deployment.
Japan
Automotive MCU specialists in Nagoya and Renesas operations in Tokyo sustain demand for ISO 26262-compliant verification methodologies. METI's semiconductor revitalization program channels subsidies toward domestic EDA toolchain development. Kyushu's silicon foundry cluster maintains legacy tool compatibility requirements that slow cloud migration.
Taiwan
TSMC's process design kit roadmaps dictate EDA vendor prioritization across the Hsinchu Science Park ecosystem. The island's national technology regulator coordinates foundry-specific certification standards for external tool vendors. Taipei-based fabless startups burst simulation workloads to domestic cloud infrastructure during tape-out crunches.
China Electronic Design Automation (EDA) Tools Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with consolidated leadership in advanced node verification and fragmented competition in PCB layout tools. The vendor base organizes into three strategic archetypes: global platform vendors with recurring revenue frameworks, regional specialists leveraging localized support networks, and cloud-native challengers attacking mid-market elasticity needs. Dominant competitive moves include strategic partnerships with foundry process development teams and geographic expansion through code escrow arrangements satisfying data sovereignty mandates.
Among global platform vendors, Synopsys Inc., Cadence Design Systems Inc., and Siemens EDA occupy positions defined by decades-long foundry relationship depth. Beijing Huada Jiutian Software Co., Ltd. exemplifies the regional specialist archetype, anchoring government-backed procurement channels through GB standards compliance. Xpeedic Technology, Inc. represents cloud-native challengers targeting electromagnetic simulation workloads for 5G baseband development.
| Leading Market Players |
|---|
| Altium Limited |
| Xpeedic Technology, Inc. |
| Synopsys Inc. |
| Ansys Inc. |
| Zuken Ltd. |
| Cadence Design Systems Inc. |
| Beijing Huada Jiutian Software Co., Ltd. |
| Keysight Technologies Inc. |
| Siemens EDA (Mentor Graphics) |
| Others |
Value Chain & Pricing Dynamics
Cloud-based EDA deployment compresses both capital expenditure thresholds and supplier concentration as domestic GPU clusters expand in Shanghai and Beijing data centers. MIIT efficiency mandates for data center energy consumption simultaneously reshape vendor selection criteria and procurement cost structures across fabless design houses.
Pricing Analysis
Capacity additions in western China data center zones are reshaping price floors for elastic simulation workloads as renewable-powered server farms attract EDA migration. Subscription licensing dominates, converting perpetual seat purchases into quarterly operational expenditures. Price differentiation hinges on certification tier under GB standards compliance and compute elasticity for burst simulation demand. Cost compression in mid-tier verification suites intensifies as domestic vendors compete on localized support. Venture-funded startups in Hangzhou exhibit highest price sensitivity; state-backed foundries prioritize security certification over cost.
Supply Chain Analysis
GB standards certification gates software procurement for sensitive node development, forcing foreign vendors into localized code escrow arrangements. Supply concentrates in the United States, Taiwan, and South Korea for advanced verification engines and GPU acceleration hardware. Raw material dependencies span NVIDIA data center GPUs, foundry-specific process design kits, and electromagnetic simulation IP cores. Single-source vulnerability in GPU cluster provisioning constrains elastic capacity expansion. Distribution runs through direct enterprise sales teams for multinational vendors and government-backed procurement channels for domestic suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's EDA market functions as a geographic-arbitrage play where MIIT procurement mandates create artificial demand premiums for GB-certified toolchains unavailable to foreign competitors facing SAMR licensing scrutiny.
For Market Incumbents: Extend foundry partnership depth through co-developed process design kits for sub-7nm nodes. Establish localized engineering support centers in Shanghai and Shenzhen to defend against domestic vendor substitution. Invest in air-gapped deployment architectures to satisfy data residency requirements for state-backed projects. Certification investment in GB standards compliance represents the critical defensive lever against procurement channel exclusion.
For New Entrants and Emerging Players: AI-accelerated formal verification engines offer entry into mid-tier fabless houses seeking compressed signoff cycles. Target western China design clusters in Chengdu and Xi'an where cloud-native deployment bypasses capital constraints. Electromagnetic-thermal co-simulation for automotive SoCs presents the most penetrable white space given talent scarcity at incumbent vendors. Go-to-market through foundry referral programs accelerates trust formation with risk-averse procurement teams.
For Investors and Strategic Acquirers: Roll-up economics work for regional specialists with GB standards certification because MIIT procurement mandates consolidate buyer demand onto compliant vendor shortlists. Long-term viability hinges on sustained government R&D funding flows and foundry localization timelines. Acquisition targets should demonstrate established code escrow arrangements and data center partnerships with MEE-efficient facilities. Watch NVIDIA export control enforcement as the primary inflection signal for domestic GPU cluster investment urgency.
| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Process Design Kit Co-Development | SMIC and Hua Hong partnerships lock in advanced node verification suite demand. |
| Localized Code Escrow Establishment | GB standards compliance enables participation in government-funded chip projects. |
| AI-Accelerated Verification Platform Launch | Machine learning inference engines compress formal verification runtime for complex SoCs. |
| Western China Cloud Infrastructure Expansion | Chengdu and Xi'an data centers capture underserved fabless startup demand. |
| Automotive Functional Safety Certification | ISO 26262 compliance opens Tier-1 supplier procurement channels in Chongqing. |
Study Parameters
Multiple input streams — primary interviews with EDA vendor executives, foundry procurement leads, and fabless CTOs; secondary validation through MIIT policy filings, SAMR regulatory announcements, and hyperscaler data center capex disclosures; plus customs records for GPU import patterns — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations spanned physical design engineers at Shanghai-based startups, verification specialists at Beijing fabless houses, and government technology procurement officers. Secondary sources included GB standards documentation, foundry earnings disclosures, and renewable energy certificates for data center facilities.
Data-stream reconciliation anchored volume projections to segment-specific adoption curves across deployment models and end-user verticals. The analytical framework modeled IC design tool penetration, simulation workload migration to cloud infrastructure, and PCB layout demand from industrial automation manufacturers throughout the forecast period. CAGRs derived from foundry capacity expansion timelines, domestic R&D funding allocations, and foreign vendor licensing renewal patterns. Industry-specific inputs encompassed sub-7nm tape-out cycle frequencies, electromagnetic simulation core-hour consumption rates, and GB standards certification pipeline velocities.
The model holds under sustained MIIT domestic procurement enforcement and stable hyperscaler GPU cluster expansion; deviation in NVIDIA export control severity or SAMR anti-monopoly investigation intensity would shift vendor share trajectories. Forecasts reflect assumptions regarding foundry localization progress and government R&D funding continuity. A model refresh is warranted upon material change in dual carbon policy enforcement or foreign software licensing term negotiations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Manufacturing
Middle East and Africa Cell Manufacturing Market
Semiconductor Manufacturing
Europe Photoresist and Photoresist Ancillaries Market
Semiconductor Manufacturing
EUV Lithography Service Market
Semiconductor Manufacturing
Semiconductor Bonding Machine Market
Semiconductor Manufacturing
Battery Manufacturing Machines Market
Semiconductor Manufacturing
Silicon Turners Market
Semiconductor Manufacturing
Silicon Wafer Reclaim Market
Semiconductor Manufacturing
Advanced Process Control Market
Semiconductor Manufacturing
Global EUV Lithography Market
Semiconductor Manufacturing
PCB Photoresist Market
Semiconductor Manufacturing
IC CMP Slurries and Pads Market
Semiconductor Manufacturing
Thin Film Semiconductor Deposition Market
Semiconductor Manufacturing
Semiconductor and Electronic Parts Manufacturing Market
Semiconductor Manufacturing
Medical Component Manufacturing Market
Semiconductor Manufacturing
Global Wafer Cutting Fluids Market
Semiconductor Manufacturing
Semiconductor and Circuit Manufacturing Market