
 Global Wafer Cutting Fluids Market | 2026-2036
Global Wafer Cutting Fluids Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wafer Cutting Fluids Market Outlook
Specialty chemical distribution is fragmenting as regional blenders and semiconductor foundries build direct procurement relationships with base fluid suppliers. BASF SE leverages its integrated additive chemistry portfolio to supply formulated concentrates directly to wafer manufacturers in Germany and Southeast Asia. Evonik Industries AG anchors its position through siloxane surfactant technology tailored for sub-10nm node cutting processes. Henkel competes by extending its electronics materials footprint into cutting fluid adjacencies.
Wafer cutting fluids are precision lubricants and coolants engineered with controlled viscosity between 2 and 10 cSt at 40°C, containing corrosion inhibitors, biocides, and extreme-pressure additives to prevent subsurface damage during silicon ingot slicing. Their primary purpose is thermal management and debris evacuation in wire saw and dicing operations that produce photovoltaic and semiconductor wafers. Synthetic formulations command the strongest margin pools due to extended bath life and compatibility with advanced abrasive slurries. Aqueous products dominate volume in photovoltaic applications where cost sensitivity overrides performance requirements. The cleaning application segment is gaining traction as post-cut residue specifications tighten for logic chip manufacturing.
EPA regulates discharge of spent cutting fluids under the Clean Water Act, while REACH restricts certain boron-based biocides and chlorinated paraffins in European formulations. China's MEE enforces wastewater COD limits that push fabs toward closed-loop synthetic systems with longer service intervals. Japan's METI encourages fluorinated surfactant phase-outs through its chemical substance evaluation framework. Stakeholders must monitor evolving substance restrictions and foundry sustainability scorecards that increasingly penalize fluid changeout frequency.
Market Dynamics
Semiconductor foundries in Taiwan and South Korea are consolidating wire saw operations into megafabs, concentrating fluid procurement volumes and forcing reformulation contracts toward longer service intervals and lower changeout frequencies.
Growth Catalysts
- Sub-10nm node expansion:Logic chip manufacturers in Taiwan are demanding synthetic formulations with siloxane surfactants that prevent subsurface microcracking during ultra-thin wafer slicing.
- REACH biocide restrictions:European ECHA pressure on boron-based additives is accelerating R&D into nitrogen-stabilized alternatives that extend bath life without environmental discharge penalties.
- China's dual carbon mandates:MEE wastewater COD limits are pushing photovoltaic wafer producers toward closed-loop synthetic systems with 40% longer service intervals than aqueous alternatives.
Market Restraints
- Base fluid supply concentration:Polyalphaolefin feedstock production clusters in the US Gulf Coast and Rotterdam, exposing blenders to hurricane and logistics disruption risk.
- Fluorinated surfactant phase-outs:Japan's METI chemical substance evaluation framework is banning perfluorinated compounds used in precision cutting, forcing costly reformulation cycles.
- Silicon carbide substitution:Wide-bandgap semiconductor substrates are displacing silicon in power electronics, shrinking addressable wafer volume in automotive inverter applications.
Strategic Opportunities
- India's PLI scheme:Semiconductor fabrication incentives are attracting foundry investments in Gujarat and Karnataka, creating greenfield fluid specification windows without incumbent supplier lock-in.
- Post-cut cleaning integration:Logic chip manufacturers are bundling residue removal specifications into cutting fluid contracts, opening adjacent chemistry service revenue streams.
- EU Green Deal alignment:CSRD reporting requirements are rewarding fabs with documented fluid recycling rates, creating premium pricing tiers for closed-loop system providers.
Industry Challenges
- Tribology expertise scarcity:Formulation chemists with simultaneous competence in semiconductor process constraints and extreme-pressure additive behavior command salaries 35% above specialty chemical industry medians.
- ISO 14001 certification timelines:New entrants face 18-24 month approval cycles to qualify for Samsung and TSMC supplier scorecards, compressing runway for commercial traction.
- Legacy aqueous system integration:Photovoltaic wafer producers in China retain substantial capital investment in open-loop aqueous infrastructure, complicating synthetic upgrade economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wafer Cutting Fluids Market |
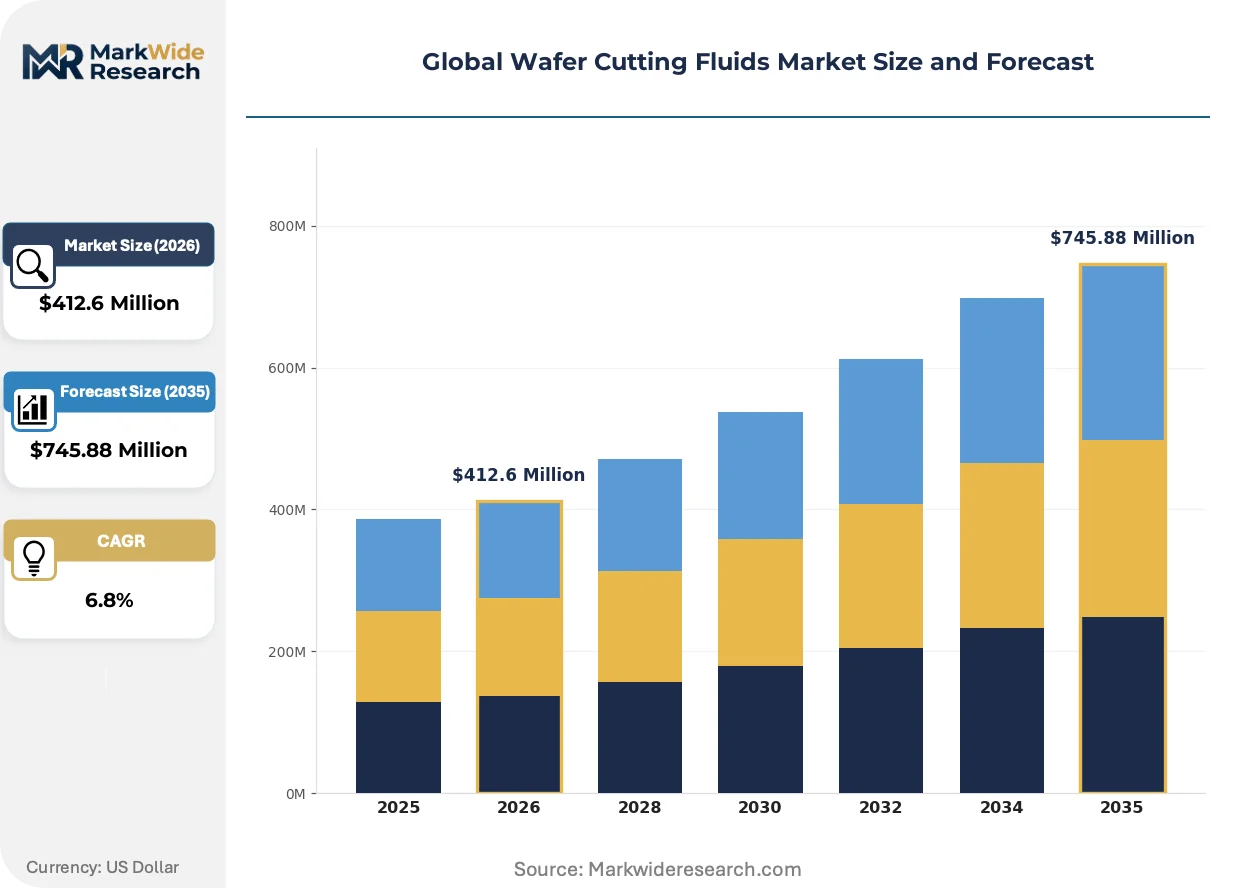
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aqueous, Non-Aqueous, Synthetic, Semi-Synthetic Application: Cutting, Grinding, Polishing, Cleaning End User: Semiconductor, Electronics Manufacturing, Automotive, Aerospace Delivery Mode: Centrifugal Spray, Flow-Through, Direct Application, Mist |
| Companies Covered | Dynatex International, BASF SE, Evonik Industries AG, UDM Systems, SINO-JAPAN CHEMICAL CO. LTD., Momentive, Keteca Singapore, Henkel, Exxon Mobil Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wafer Cutting Fluids Market Strategic Shifts
Wire saw telemetry and inline viscosity monitoring are transforming fluid management from scheduled replacement to predictive intervention, compressing the value capture available to traditional maintenance service providers.
Machine learning algorithms analyzing wire tension, temperature gradients, and particle count are digitizing process optimization for silicon ingot slicing operations. Taiwan-based foundries are deploying these systems across 300mm wafer lines to predict fluid degradation before subsurface damage occurs. The technology is digitizing the traditional relationship between fluid suppliers and fab process engineers, shifting value toward data-integrated service contracts.
REACH restrictions on chlorinated paraffins and boron-based biocides are eliminating legacy additive packages from European formulations. Blenders are reformulating with nitrogen-stabilized and isothiazolinone alternatives that maintain microbial control without ECHA substance of very high concern classification. Synthetic formulations containing these substitutes command price premiums in German and French photovoltaic wafer operations where discharge compliance costs dominate total cost of ownership calculations.
Direct procurement relationships between semiconductor foundries and base fluid suppliers are disintermediating regional blenders in East Asian supply chains. TSMC and Samsung are negotiating polyalphaolefin supply contracts with integrated oil companies, then contracting independent additive houses for formulation services. This pattern is most visible in Taiwan and South Korea, where foundry procurement teams are building in-house tribology capabilities to specify performance metrics rather than finished fluid brands.
Global Wafer Cutting Fluids Market Segmentation
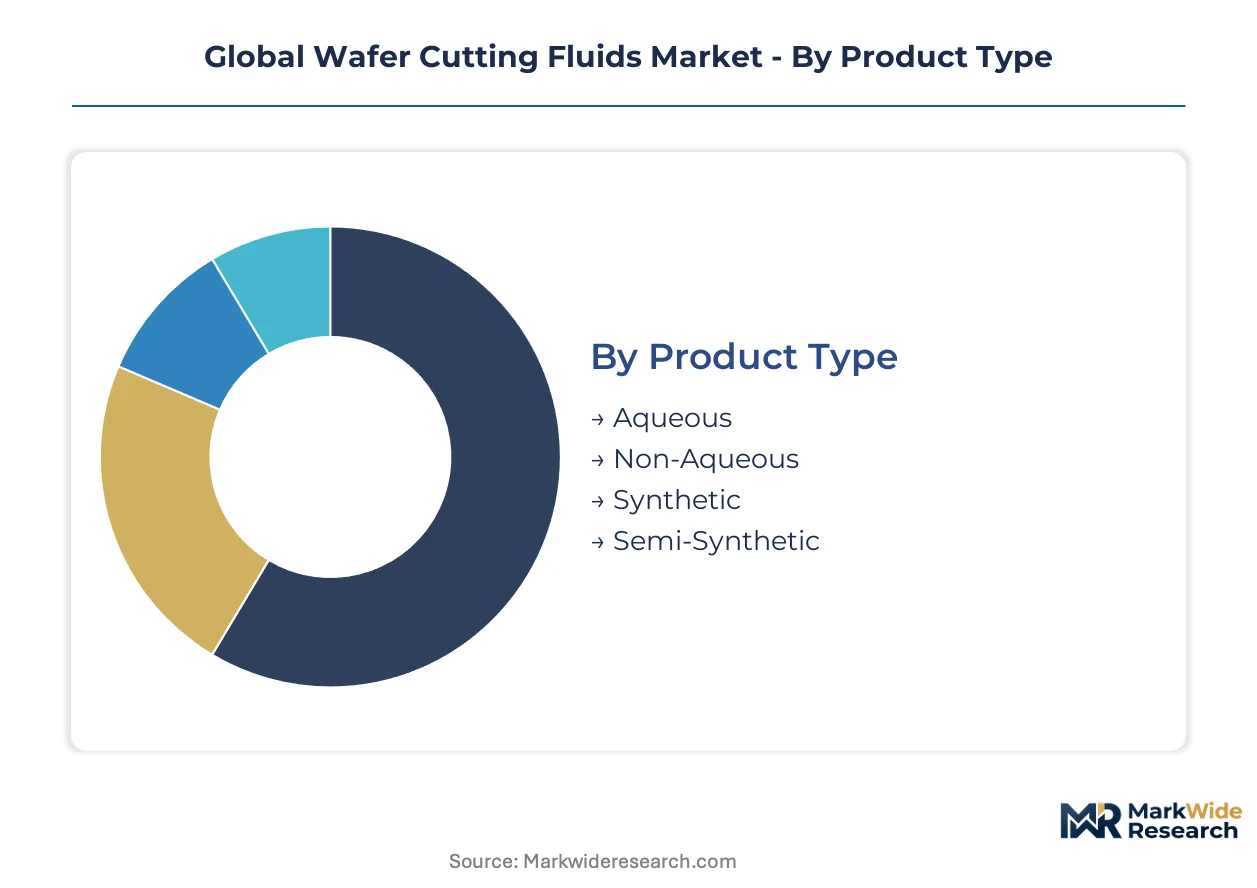
Wafer cutting fluid procurement decisions hinge on process-specific performance requirements, regulatory discharge constraints, and total cost of ownership calculations across semiconductor and photovoltaic manufacturing lines. Segmentation reveals divergent margin structures between precision semiconductor applications and cost-sensitive solar wafer operations.
Product Type:
After-sales service intensity varies sharply across formulation chemistries, with synthetic systems demanding predictive monitoring contracts and aqueous products requiring frequent technical support for microbial control.
- Synthetic:Formulated from polyalphaolefin base stocks with siloxane surfactants and nitrogen-stabilized biocides, these fluids deliver 40% longer bath life than aqueous alternatives. Demand concentrates in Taiwan's sub-10nm logic chip foundries where subsurface microcracking prevention justifies premium pricing.
- Aqueous:Water-based emulsions with mineral oil content below 15% dominate photovoltaic wafer slicing in China, where MEE wastewater COD limits are accelerating closed-loop system adoption despite lower upfront fluid costs.
- Non-Aqueous:Solvent-based formulations containing hydrocarbon carriers serve specialty silicon carbide wafer processing where water contamination risks exceed thermal management benefits.
- Semi-Synthetic:Hybrid chemistries blending 30-50% mineral oil with synthetic base stocks occupy the mid-tier for legacy 200mm semiconductor lines in Southeast Asia seeking performance upgrades without full synthetic conversion costs.
Synthetic formulations hold the largest share; momentum sits with aqueous systems as China's dual carbon mandates tighten discharge economics.
Application:
Process stage determines additive package complexity, with post-cut cleaning applications commanding the highest technical specification density and most intensive supplier-fab engineering collaboration.
- Cutting:Wire saw and dicing operations require extreme-pressure additives and controlled viscosity between 2-10 cSt at 40°C to manage thermal loads during silicon ingot slicing. Taiwan-based foundries are consolidating megafab procurement volumes and demanding reformulation contracts with extended service intervals.
- Cleaning:Post-cut residue removal specifications for logic chip manufacturing are bundling cleaning chemistry into cutting fluid contracts, creating adjacent service revenue streams as particle count thresholds tighten below 0.1 micron.
- Grinding:Back-grinding operations for wafer thinning utilize lower-viscosity formulations with enhanced debris evacuation properties, primarily in South Korea's memory chip packaging facilities.
- Polishing:Chemical mechanical planarization adjacencies require ultra-low residue formulations compatible with subsequent copper interconnect processing steps.
Cutting applications generate the highest absolute volumes; cleaning specifications are expanding most quickly as node geometries shrink.
End User:
Customer technical sophistication determines specification authority, with semiconductor foundries dictating additive chemistry requirements and electronics manufacturers accepting standard formulated concentrates.
- Semiconductor:Logic and memory chip foundries in Taiwan and South Korea specify performance metrics rather than finished fluid brands, building direct procurement relationships with polyalphaolefin suppliers and contracting independent additive houses for formulation services.
- Electronics Manufacturing:Printed circuit board and discrete component producers in Southeast Asia purchase standard semi-synthetic concentrates through regional distributors with limited in-house tribology capabilities.
- Automotive:Power electronics manufacturers face silicon carbide substrate substitution pressures as wide-bandgap semiconductors displace silicon in inverter applications, shrinking addressable wafer volumes.
- Aerospace:Radiation-hardened chip producers represent a niche segment with specialized cleanliness specifications and extended qualification timelines.
Semiconductor end users command the largest procurement volumes; electronics manufacturing offers the steepest expansion trajectory as India's PLI scheme attracts foundry investments.
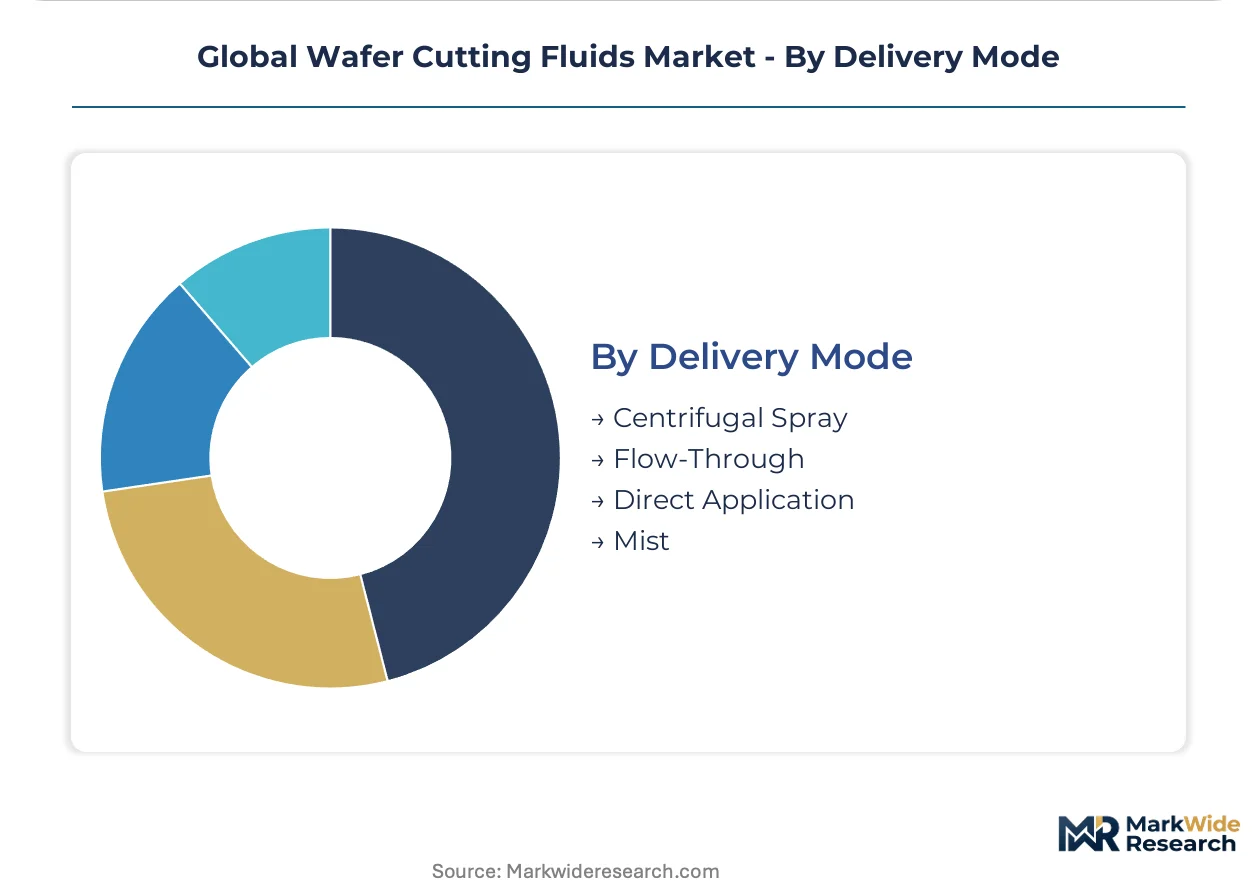
Delivery Mode:
Fluid application method interfaces directly with wire saw telemetry systems, with centrifugal spray and flow-through configurations enabling predictive intervention algorithms that compress traditional maintenance service value capture.
- Centrifugal Spray:High-velocity atomized delivery systems integrate with inline viscosity monitoring and machine learning algorithms analyzing wire tension and temperature gradients, digitizing process optimization for 300mm wafer lines in Taiwan.
- Flow-Through:Continuous circulation systems with particle filtration and temperature control dominate closed-loop synthetic installations in China where MEE regulations mandate extended service intervals.
- Direct Application:Point-source dispensing suits prototype and research wafer operations with low volume requirements and frequent chemistry changeovers.
- Mist:Ultra-low volume delivery minimizes fluid consumption in precision dicing operations but requires specialized exhaust handling for worker exposure compliance.
Flow-through systems retain the largest installed base; centrifugal spray configurations are gaining share fastest as predictive maintenance platforms proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MEE wastewater COD limits and India's PLI semiconductor incentives are redrawing procurement maps for wafer cutting fluid suppliers. Taiwan and South Korean foundries concentrate advanced node demand, while European REACH compliance costs reshape formulation economics.
China
Photovoltaic wafer producers in Jiangsu and Zhejiang provinces are retrofitting open-loop aqueous systems with closed-loop synthetic alternatives. MEE enforcement of dual carbon mandates tightens discharge economics. The Yangtze River Delta fabrication cluster absorbs reformulation costs to extend bath life intervals.
Taiwan
TSMC and United Microelectronics are consolidating megafab wire saw operations into Hsinchu and Tainan Science Parks. The island's EPA aligns with METI-influenced fluorinated surfactant phase-out timelines. Sub-10nm logic chip slicing specifications command premium synthetic formulations with siloxane additive packages.
South Korea
Samsung Electronics and SK Hynix are expanding 300mm memory wafer capacity in Giheung and Pyeongtaek. K-Battery regulations indirectly pressure power electronics substrate choices toward silicon carbide. The Seoul Capital Area dominates procurement volumes for extreme-pressure cutting fluid concentrates.
Germany
Siltronic and GlobalWafers operations in Saxony and Bavaria face ECHA biocide restrictions on boron-based additives. REACH compliance costs accelerate nitrogen-stabilized alternative adoption. The Dresden semiconductor cluster sources reformulated concentrates directly from integrated chemical suppliers.
India
Gujarat and Karnataka are attracting greenfield foundry investments under the PLI scheme without incumbent supplier relationships. State pollution control boards are drafting semiconductor effluent standards. The Dholera Special Investment Region represents unconstrained specification windows for fluid system providers.
Global Wafer Cutting Fluids Market Competitive Environment
On the supply side, the industry is bifurcating between integrated chemical conglomerates and specialized additive houses. Polyalphaolefin base stock concentration in Rotterdam and US Gulf Coast locations exposes blenders to logistics disruption. Two strategic archetypes dominate: integrated suppliers with captive additive chemistry and independent formulators with tribology service capabilities. Competitive moves center on direct procurement relationships with foundries and predictive maintenance platform integration.
Among German-integrated chemical suppliers, BASF SE and Evonik Industries AG exemplify the additive-chemistry-to-formulation pipeline archetype. BASF SE leverages integrated polyalphaolefin and surfactant portfolios to supply concentrates directly to wafer manufacturers. Evonik Industries AG anchors its position through siloxane technology specialization for precision cutting applications. Henkel occupies a position extending electronics materials capabilities into fluid adjacencies. These three represent distinct competitive vectors: backward integration, technology specialization, and portfolio extension.
| Leading Market Players |
|---|
| Dynatex International |
| BASF SE |
| Evonik Industries AG |
| UDM Systems |
| SINO-JAPAN CHEMICAL CO. LTD. |
| Momentive |
| Keteca Singapore |
| Henkel |
| Exxon Mobil Corporation |
| Others |
Value Chain & Pricing Dynamics
Polyalphaolefin feedstock concentration in Rotterdam and the US Gulf Coast exposes blenders to hurricane and logistics disruption risk, compressing margin spreads between premium synthetic formulations and semi-synthetic alternatives while forcing foundries to diversify procurement geography.
Pricing Analysis
Certification level creates the primary spread between qualified suppliers and commodity blenders, with ISO 14001 and Samsung/TSMC scorecard approval commanding 15-25% premiums over unqualified competitors. Three-tier pricing structure across premium synthetic, mid-grade semi-synthetic, and economy aqueous levels reflects bath life differentials and discharge compliance bundling. Pricing pressure stems from direct procurement relationships between foundries and base fluid suppliers disintermediating regional blenders. Photovoltaic wafer producers in China exhibit highest price sensitivity, while sub-10nm logic foundries in Taiwan prioritize performance over unit cost.
Supply Chain Analysis
Polyalphaolefin base stocks originate primarily from integrated refineries in the Netherlands, United States, and Singapore, with additive packages sourced from German and Japanese specialty chemical houses. Formulated concentrates draw from siloxane surfactants, nitrogen-stabilized biocides, and extreme-pressure additive packages. Single-source vulnerability concentrates in Rotterdam port logistics and Gulf Coast petrochemical corridors. Distribution runs through direct procurement contracts to megafabs, bypassing traditional regional distributor networks in Taiwan and South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance platforms are redefining supplier-fab relationships as data-integrated service contracts displace transactional fluid sales, creating platform-economics dynamics where telemetry interoperability determines long-term contract viability.
For Market Incumbents: Entrench through captive additive chemistry pipelines and backward integration into polyalphaolefin base stocks to defend against direct procurement disintermediation. Secure predictive maintenance platform partnerships with wire saw OEMs before independent software vendors capture process optimization value. Prioritize ISO 14001 certification maintenance to preserve Samsung and TSMC supplier scorecard positions against emerging Asian competitors. For New Entrants and Emerging Players: Build out tribology service capabilities in India's Gujarat and Karnataka greenfield foundry zones where incumbent supplier relationships remain unformed. Target aqueous-to-synthetic conversion opportunities in China's Jiangsu province photovoltaic clusters facing MEE wastewater COD enforcement. Lead with closed-loop system engineering rather than commodity fluid formulations to differentiate from established blenders. For Investors and Strategic Acquirers: Japan's METI fluorinated surfactant phase-out timelines reshape the acquisition landscape toward nitrogen-stabilized biocide specialists and siloxane surfactant technology holders. Long-term viability favors formulators with demonstrated REACH compliance pathways and documented fab recycling rate credentials. Monitor TSMC and Samsung direct procurement contract announcements as signals of additive house consolidation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Stocks | Captures margin pools threatened by direct foundry-polyalphaolefin supplier relationships. |
| Predictive Maintenance Platform Partnership | Positions fluid suppliers for data-integrated service contracts with Taiwan megafabs. |
| REACH-Compliant Biocide Reformulation | Preserves European market access as ECHA eliminates boron-based additive packages. |
| India Greenfield Specification Capture | Exploits PLI scheme foundry investments in Gujarat without incumbent supplier lock-in. |
| Closed-Loop System Engineering | Aligns with China's MEE wastewater COD mandates and extends service interval economics. |
Study Parameters
The analysis maps synthetic, aqueous, semi-synthetic, and non-aqueous formulation chemistries, each validated through formulation chemists, fab process engineers, procurement leads at TSMC and Samsung, and regional distributor technical directors. Primary interviews with semiconductor foundry tribology specialists and photovoltaic wafer operations managers combined with secondary validation from ECHA substance restriction databases, MEE wastewater discharge filings, and SEC 10-K chemical segment disclosures. Bottom-up triangulation across product-type consumption volumes and top-down cross-check against end-user procurement spend estimates anchored the market sizing.
Assumptions held fixed include REACH biocide restriction timelines, China's dual carbon mandate enforcement intensity, and polyalphaolefin feedstock capacity expansion plans, while variables included India's PLI scheme foundry investment pace and silicon carbide substitution rates in automotive power electronics. Segmentation dimensions encompassed formulation chemistry, application stage, end-user technical sophistication, and delivery mode integration with predictive maintenance platforms. CAGRs derived from regression analysis of historical fab capacity additions correlated with fluid consumption intensity metrics across the projection horizon.
Sensitivities concentrate around MEE enforcement variability, METI fluorinated surfactant phase-out acceleration, and hurricane disruption frequency in Gulf Coast petrochemical corridors. Forecasts reflect documented assumptions on foundry consolidation patterns and synthetic conversion economics. Cross-checking against SEMI wafer capacity forecasts and chemical industry trade flow data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Manufacturing
Medical Component Manufacturing Market
Semiconductor Manufacturing
Thin Film Semiconductor Deposition Market
Semiconductor Manufacturing
High Purity Process Systems for Semiconductor Market
Semiconductor Manufacturing
Silicon Wafer Reclaim Market
Semiconductor Manufacturing
Malaysia and Thailand Precession Cleaning for Electronic Market
Semiconductor Manufacturing
Global EUV Lithography Market
Semiconductor Manufacturing
Semiconductor Bonding Machine Market
Semiconductor Manufacturing
Advanced Process Control Market
Semiconductor Manufacturing
Global Overall EUV Lithography Market
Semiconductor Manufacturing
Europe Electronic Manufacturing Services Market
Semiconductor Manufacturing
Semiconductor Polishing Pads Market
Semiconductor Manufacturing
Middle East and Africa Cell Manufacturing Market
Semiconductor Manufacturing
Stencil Lithography Market
Semiconductor Manufacturing
Photomask Market
Semiconductor Manufacturing
IC CMP Slurries and Pads Market
Semiconductor Manufacturing
PCB Photoresist Market