
 Middle East and Africa Cell Manufacturing Market | 2026-2036
Middle East and Africa Cell Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Cell Manufacturing Market Foresight
Morocco's Tangier Med industrial corridor is narrowing the region's cell production gap with European and Asian suppliers. Thermo Fisher Scientific Inc. leverages its bioproduction instrumentation footprint to serve quality-control labs at emerging African cell plants. Sartorius AG anchors single-use bioreactor supply lines for cell-culture media preparation in Middle Eastern manufacturing hubs. Lonza Group Ltd competes through contract development capabilities that bridge pilot-scale electrochemical research to commercial deposition lines.
Middle East and Africa cell manufacturing encompasses the industrial production of electrochemical energy storage devices, including lithium-ion and solid-state configurations fabricated through chemical deposition, laser structuring, and sintering processes, typically operating at voltages from 2.5V to 4.4V depending on cathode chemistry, primarily serving electric vehicle propulsion and grid-scale energy storage applications. Solid-state cells command premium positioning due to thermal stability requirements in Gulf climate conditions, while laser structuring sustains margin pools through precision electrode patterning for aerospace-rated power densities. Lead-acid cells occupy mature utility roles across African telecom backup installations, though nickel-cadmium alternatives face substitution pressure from lithium-ion cost curves in portable electronics segments.
South Africa's National Regulator for Compulsory Specifications and Morocco's Institute of Standardization enforce electrochemical safety protocols that dictate cell import certification timelines and local assembly incentives. Saudi Standards, Metrology and Quality Organization alignment with IEC 62660 testing frameworks shapes product qualification pathways for Gulf-based energy storage providers. Stakeholders must monitor how Egypt's industrial licensing reforms and Ethiopia's renewable energy auctions reshape cell demand geography without assuming uniform regulatory convergence across the region.
Market Dynamics
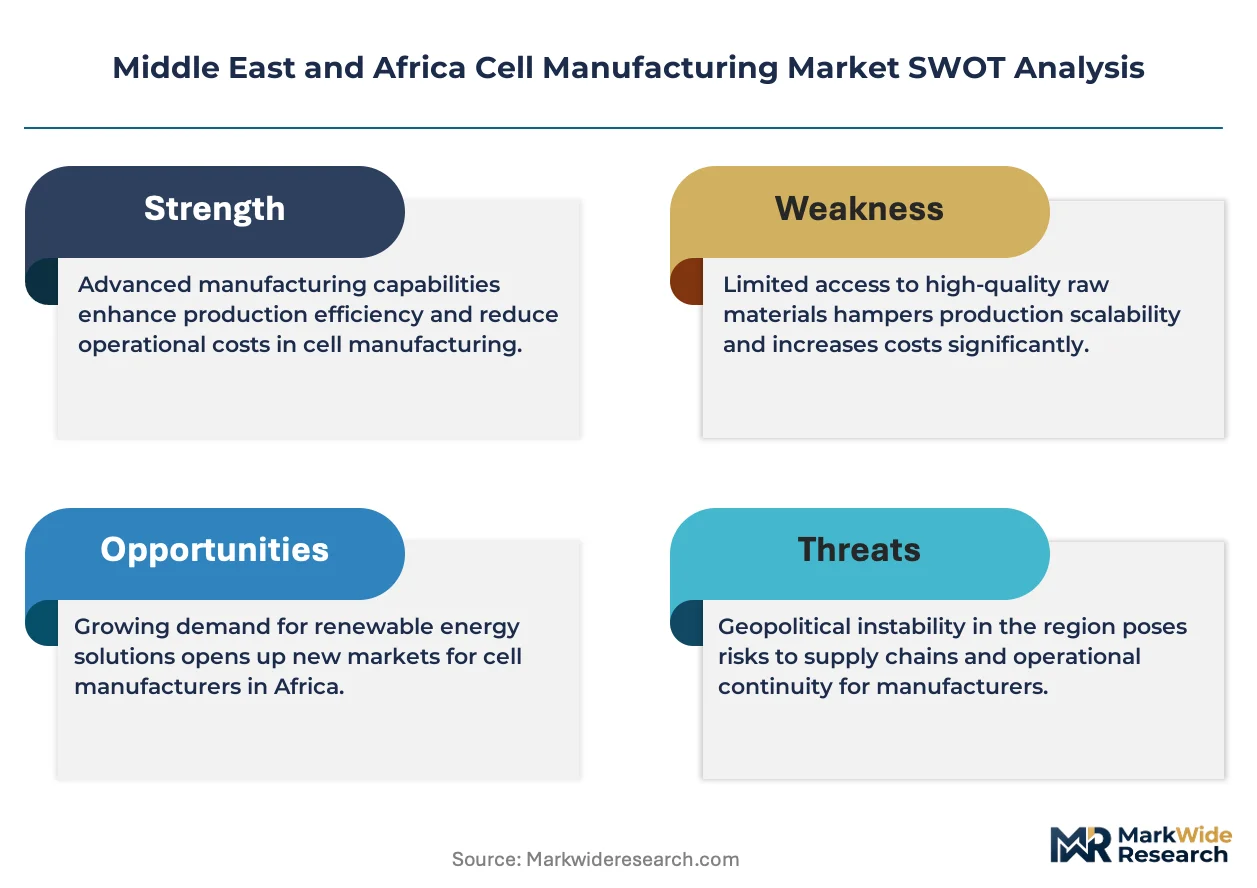
European EV supply chain localization mandates are compressing procurement timelines for Tangier Med corridor cell producers, forcing rapid qualification of African-manufactured lithium-ion cells for EU automotive OEMs.
Growth Catalysts
- Automotive OEM localization mandates:European electric vehicle manufacturers require regional cell sourcing to qualify for EU battery passport regulations, directing capital toward Moroccan assembly facilities.
- IEC 62660 alignment:Saudi Standards, Metrology and Quality Organization adoption of international electrochemical testing frameworks accelerates product certification for Gulf-based energy storage providers.
- Solid-state thermal stability:Gulf climate conditions above 45°C ambient temperatures create structural demand for solid-state cell architectures that eliminate thermal runaway risks in grid-scale installations.
Market Restraints
- Cathode active material import dependency:Lithium carbonate and nickel sulfate supply concentrates in Chilean and Indonesian processing corridors, exposing African cell plants to 12-18 month offtake contract volatility.
- Electrolyte formulation IP concentration:Proprietary lithium hexafluorophosphate additive packages remain controlled by Northeast Asian chemical conglomerates, limiting local formulation autonomy.
- Lead-acid installed base inertia:Mature telecom backup infrastructure across sub-Saharan African markets resists lithium-ion substitution due to established maintenance ecosystems and technician familiarity.
Strategic Opportunities
- Ethiopian renewable energy auctions:Grid-scale solar and wind procurement rounds create captive demand for domestic cell assembly serving utility-scale storage installations.
- Egyptian industrial licensing reforms:New special economic zone frameworks for clean technology manufacturing reduce import duty exposure for electrode coating equipment.
- Laser structuring-aerospace convergence:Precision electrode patterning capabilities developed for EV power density targets transfer to satellite and drone battery applications with premium pricing.
Industry Challenges
- Electrochemical process engineering talent scarcity:Thin-film deposition technicians and solid-state sintering specialists command compensation premiums that inflate African plant operating costs relative to Asian benchmarks.
- Multi-standard certification parallelism:Simultaneous pursuit of South African NRCS electrochemical safety marks, Moroccan Institute of Standardization approvals, and Saudi SASO conformity requirements fragments quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Cell Manufacturing Market |
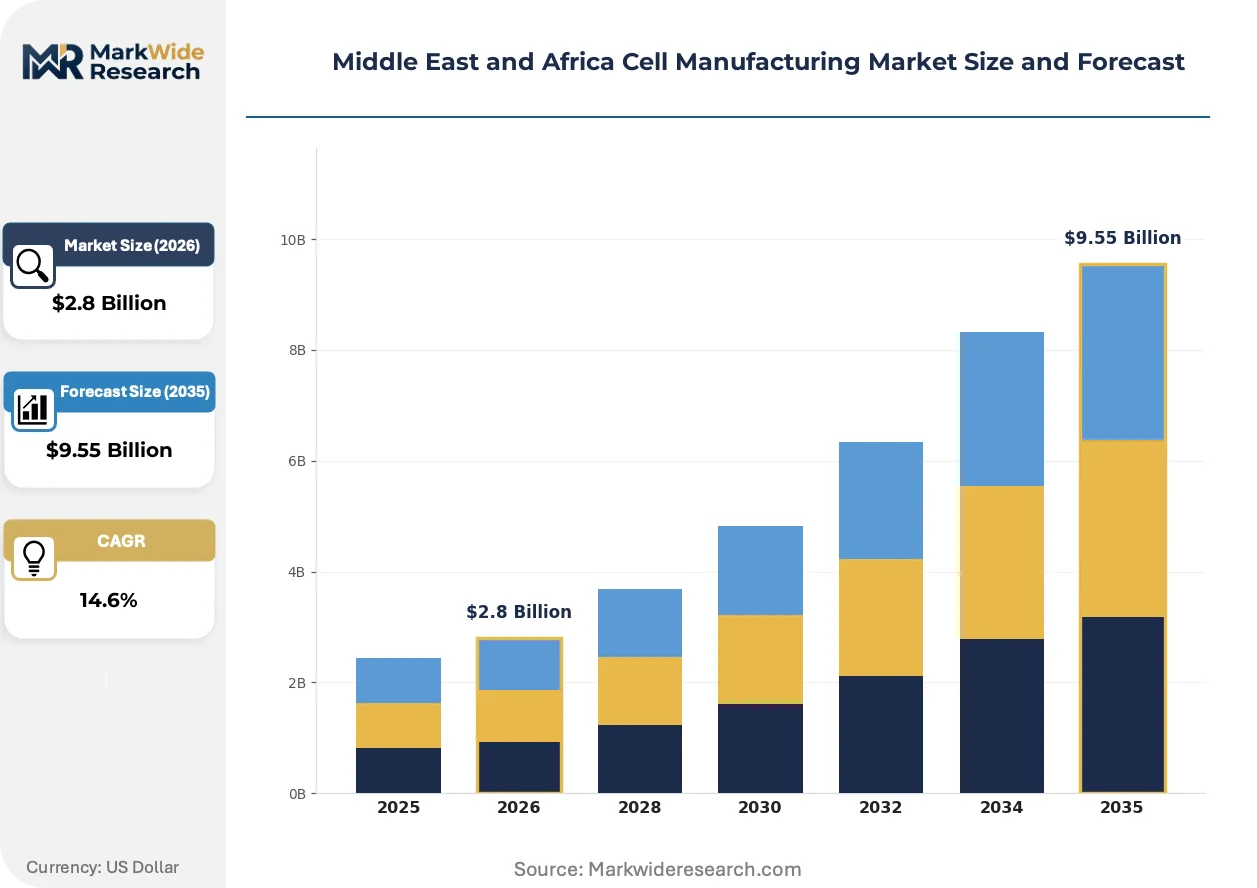
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion Cells, Lead-Acid Cells, Nickel-Cadmium Cells, Solid-State Cells End User: Automotive OEMs, Electronics Manufacturers, Renewable Energy Providers, Aerospace Companies Technology: Chemical Deposition, Laser Structuring, Electrochemical Deposition, Sintering Application: Energy Storage Systems, Electric Vehicles, Portable Electronics, Industrial Applications |
| Companies Covered | Thermo Fisher Scientific Inc., Merck KGaA, GE Healthcare, Sartorius AG, Corning Incorporated, Lonza Group Ltd, Catalent Inc, Charles River Laboratories International Inc, Cytiva, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Cell Manufacturing Market Shifts & Advancements
Digital twin architectures are compressing pilot-to-production timelines for cell manufacturing lines across Middle Eastern and African facilities, enabling virtual commissioning before physical equipment installation.
Dry electrode coating is virtualizing traditional solvent-based slurry processing in emerging African gigafactories. Tangier Med corridor producers adopt this technology to eliminate N-methyl-2-pyrrolidone recovery infrastructure and reduce drying energy consumption by half. The structural consequence is collapsing capital intensity requirements for electrode production, enabling faster capacity scaling with reduced environmental permitting complexity.
South Africa's National Regulator for Compulsory Specifications enforces stricter electrochemical safety protocols for energy storage imports, mandating UN 38.3 testing documentation and thermal abuse propagation assessments. This regulatory friction extends certification timelines for Asian cell suppliers while creating preferential market access for locally assembled products meeting NRCS marks. Automotive OEMs respond by accelerating South African joint venture negotiations to secure compliant supply sources.
Buyer concentration among European EV manufacturers is consolidating procurement authority toward direct long-term offtake agreements with African cell producers, displacing traditional trading house intermediaries. This channel compression eliminates margin layers but exposes African suppliers to concentrated counterparty risk and stringent performance guarantees. The shift is most visible in Morocco's Tangier Med industrial zone, where gigafactory operators negotiate decade-spanning supply contracts with German and French automotive groups.
Middle East and Africa Cell Manufacturing Market Segmentation
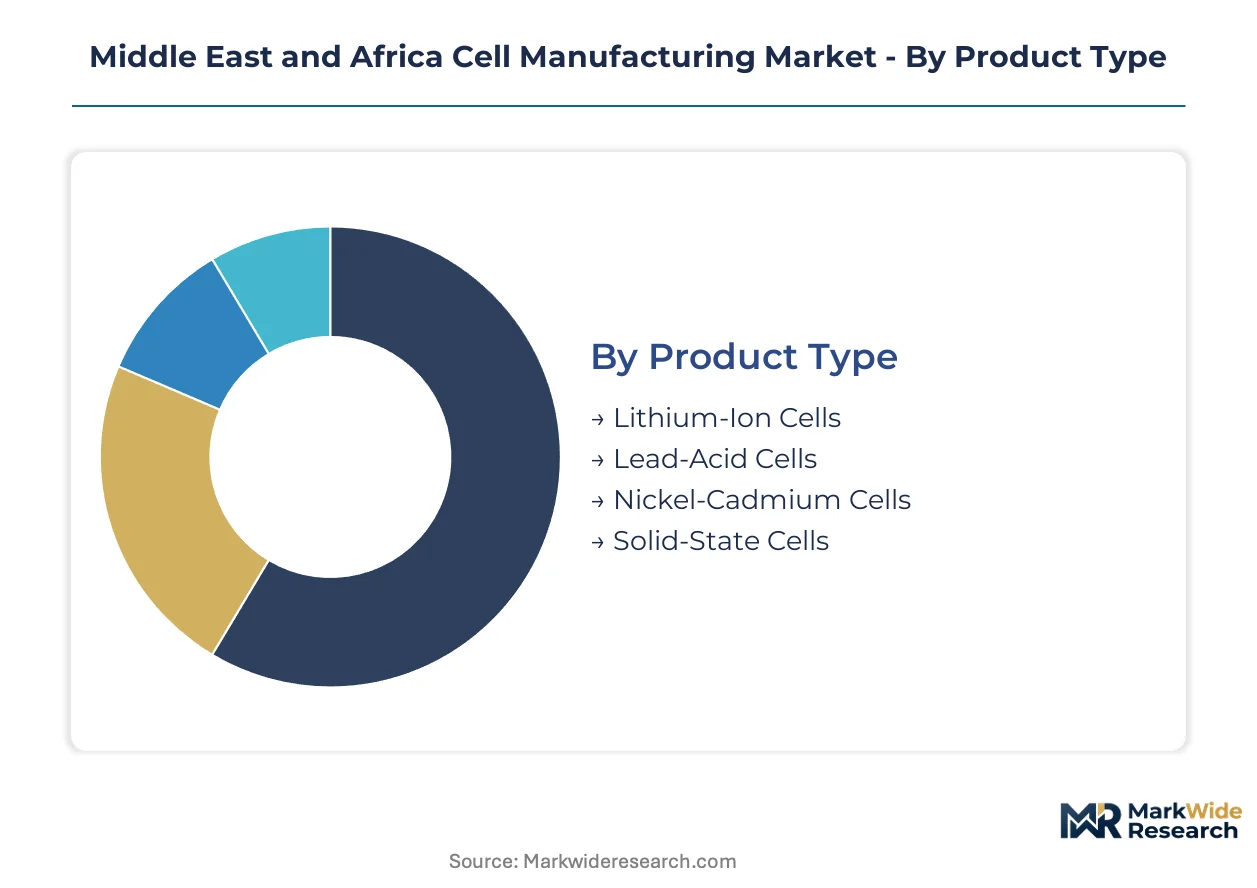
Cell manufacturing across the Middle East and Africa fragments across electrochemical chemistries, end-use verticals, and fabrication technologies. Each dimension carries distinct margin profiles, certification burdens, and localization incentives that shape investment prioritization.
Product Type:
After-sales service intensity varies sharply by chemistry—lithium-ion and solid-state cells demand sophisticated thermal management diagnostics, while lead-acid maintenance relies on established technician networks across African telecom infrastructure.
- Lithium-Ion Cells:Cobalt-oxide and lithium-iron-phosphate cathode configurations dominate electrode coating lines in Morocco's Tangier Med corridor. Automotive OEMs from Germany and France negotiate direct offtake agreements with local assemblers to satisfy EU battery passport traceability requirements.
- Solid-State Cells:Sulfide and oxide electrolyte architectures eliminate liquid electrolyte fire risks in Gulf climate conditions exceeding 45°C ambient. Saudi Arabian grid-scale storage procurement favors these cells despite premium pricing, driven by thermal runaway elimination mandates from the Saudi Standards, Metrology and Quality Organization.
- Lead-Acid Cells:Mature flooded and valve-regulated designs persist across sub-Saharan African telecom backup installations due to technician familiarity and established recycling networks.
- Nickel-Cadmium Cells:Declining aerospace and rail signaling applications face substitution pressure from lithium-ion cost curves in portable electronics segments.
By volume, lithium-ion cells lead. By growth pace, solid-state architectures are climbing the fastest.
End User:
Cost tier stratification separates premium aerospace qualification pathways from mass-market automotive volume plays, with renewable energy providers occupying a mid-tier procurement position sensitive to financing structures.
- Automotive OEMs:European electric vehicle manufacturers compress procurement timelines for Moroccan cell producers, forcing rapid UN 38.3 testing documentation and thermal abuse propagation assessments to qualify for EU market access.
- Renewable Energy Providers:Ethiopian utility-scale solar and wind auctions create captive demand for domestic cell assembly serving grid storage installations, though project finance timelines extend 18-24 months.
- Electronics Manufacturers:Portable device assemblers in Egypt's special economic zones source cylindrical and pouch cells for regional consumer electronics distribution.
- Aerospace Companies:Satellite and drone battery applications command premium pricing for precision laser-structured electrodes with aerospace-rated power densities.
Automotive OEMs drive absolute revenue. Renewable energy providers are expanding most quickly.
Technology:
Application specificity determines technology selection—EV power density targets favor laser structuring, while grid storage cost minimization drives chemical deposition adoption.
- Laser Structuring:Precision electrode patterning enables high surface-area architectures for automotive power density requirements. Tangier Med producers transfer these capabilities to satellite battery applications with margin premiums.
- Chemical Deposition:Slurry-based cathode and anode coating dominates volume production, though dry electrode alternatives are virtualizing solvent recovery infrastructure in emerging African gigafactories.
- Sintering:Solid-state electrolyte densification requires controlled atmosphere furnaces operating at elevated temperatures, constraining capacity scaling to specialized equipment providers.
- Electrochemical Deposition:Thin-film techniques for specialized aerospace and medical power applications remain niche due to throughput limitations.
Chemical deposition handles greatest volume. Laser structuring shows steepest expansion trajectory.
Application:
Customer type concentration clusters procurement authority—utility buyers consolidate through auction mechanisms while automotive OEMs negotiate bilateral long-term agreements.
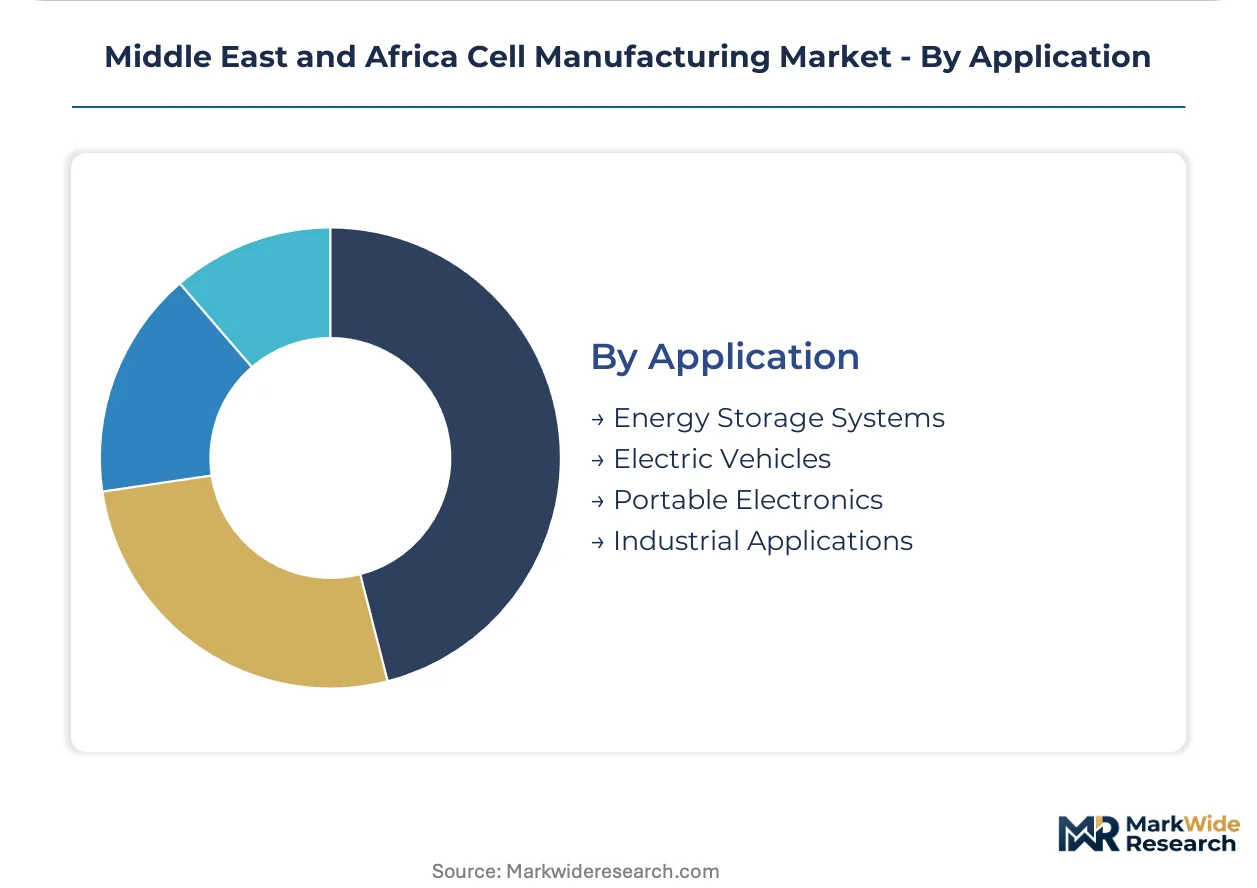
- Electric Vehicles:Passenger car and commercial truck propulsion systems demand high-cycle-life cells with automotive-grade quality systems. South Africa's National Regulator for Compulsory Specifications enforces stricter electrochemical safety standards that extend certification timelines for imports.
- Energy Storage Systems:Grid-scale and residential installations across the Gulf Cooperation Council prioritize thermal stability in ambient conditions above 45°C, favoring solid-state architectures.
- Portable Electronics:Smartphone and laptop battery demand concentrates in Egyptian and Moroccan assembly zones serving regional distribution.
- Industrial Applications:Forklift, mining equipment, and material handling systems utilize both lithium-ion substitutions and persistent lead-acid infrastructure.
Electric vehicles anchor revenue concentration. Energy storage systems are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia and Morocco consume cell manufacturing capacity for diverging end uses—Riyadh prioritizes grid-scale thermal stability while Tangier Med serves European automotive qualification pathways. South Africa anchors electrochemical safety enforcement. Egypt and Ethiopia represent emerging demand frontiers with distinct procurement mechanisms.
Saudi Arabia
Saudi Standards, Metrology and Quality Organization procurement mandates drive solid-state cell demand for grid installations operating above 45°C ambient. SASO alignment with IEC 62660 testing frameworks compresses product qualification timelines for energy storage providers. Riyadh and the Eastern Province concentrate utility-scale battery procurement authority through centralized renewable energy auctions.
Morocco
European EV manufacturers enforce EU battery passport traceability requirements that favor Tangier Med corridor assembly facilities. The Institute of Standardization electrochemical safety protocols extend certification timelines for Asian imports while privileging locally manufactured cells. Tangier Med industrial zone hosts gigafactory investments targeting decade-spanning supply contracts with German and French automotive groups.
South Africa
Automotive OEMs expand procurement of locally assembled battery cells to satisfy National Regulator for Compulsory Specifications electrochemical safety marks. NRCS mandates UN 38.3 testing documentation and thermal abuse propagation assessments that fragment quality assurance resources for importers. Gauteng industrial corridors concentrate joint venture negotiations between domestic assemblers and European vehicle manufacturers.
Egypt
Special economic zone frameworks for clean technology manufacturing reduce import duty exposure for electrode coating equipment. Industrial licensing reforms streamline permitting for cell assembly facilities serving regional consumer electronics distribution. Cairo and the Suez Canal Economic Zone attract portable device battery producers targeting Middle Eastern and African markets.
Ethiopia
Utility-scale solar and wind procurement rounds create captive demand for domestic cell assembly serving grid storage installations. Project finance timelines extend 18-24 months, constraining rapid capacity scaling despite renewable energy auction momentum. Addis Ababa and surrounding industrial zones host early-stage manufacturing investments targeting captive utility demand rather than export markets.
Middle East and Africa Cell Manufacturing Market Competitive Landscape
Capability concentration sits with instrumentation and bioproduction specialists; scale advantage sits with contract development organizations bridging pilot research to commercial lines. The vendor base organizes around three archetypes: laboratory equipment providers serving quality-control infrastructure, single-use system suppliers for cell-culture media preparation, and contract manufacturing organizations spanning electrochemical research to deposition processes. Dominant competitive moves include strategic partnerships with emerging African gigafactories and technology licensing arrangements for dry electrode coating processes.
Among laboratory instrumentation specialists, Thermo Fisher Scientific Inc. and Sartorius AG occupy positions aligned with quality-control lab expansion at emerging cell plants. Lonza Group Ltd exemplifies the contract development archetype that connects pilot-scale electrochemical research to commercial manufacturing lines. Merck KGaA and GE Healthcare represent diversified chemical and life science conglomerates whose bioproduction footprints transfer to cell manufacturing quality assurance applications.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| GE Healthcare |
| Sartorius AG |
| Corning Incorporated |
| Lonza Group Ltd |
| Catalent Inc |
| Charles River Laboratories International Inc |
| Cytiva |
| Others |
Supply & Pricing Matrix
Tangier Med industrial zone capacity additions are compressing contract pricing for European automotive OEMs while elevating margin pressure on Asian import competitors. South Africa's NRCS certification requirements and Morocco's local assembly incentives create a bifurcated pricing environment where compliant domestic producers command premium positioning against uncertified imports.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between Moroccan gigafactories and German automotive groups, with price differentiation driven by EU battery passport traceability compliance and volume scale commitments. Cost compression in standard lithium-ion tiers is intensifying because dry electrode coating technology eliminates solvent recovery infrastructure. Renewable energy providers in Ethiopia exhibit highest price sensitivity due to extended project finance timelines, while aerospace satellite battery buyers show lowest sensitivity given precision laser-structured electrode premiums.
Supply Chain Analysis
Lithium carbonate feedstock draws from Chilean and Indonesian processing corridors, with nickel sulfate and cobalt hydroxide completing the cathode active material trinity. Cathode precursor supply rests on South American and Southeast Asian chemical conglomerates, creating single-source vulnerability for African cell plants lacking backward integration into mining assets. Distribution runs through direct bilateral agreements with European OEMs, displacing traditional trading house intermediaries in Morocco's automotive-qualified supply tier.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thin-film deposition technicians and solid-state sintering specialists command compensation premiums that inflate operating costs, creating a structural talent gap that shapes competitive positioning across the region.
For Market Incumbents: Entrench qualification advantages by accelerating South African NRCS and Moroccan Institute of Standardization certification investments ahead of Asian competitor import timelines. Pursue backward integration into electrode coating equipment supply through Egyptian special economic zone frameworks, defending against emerging dry electrode technology disruptors that collapse capital intensity requirements. For New Entrants and Emerging Players: Ethiopian utility-scale storage procurement rounds offer the most penetrable white-space target, with captive demand from renewable energy auctions and limited incumbent manufacturing presence. Enter through joint venture structures with domestic industrial zone developers, leveraging 18-24 month project finance timelines to establish operational track records before export market qualification. For Investors and Strategic Acquirers: Long-term, this sits as a regional supply chain localization play because European EV battery passport mandates structurally favor African assembly capacity with EU market access. Target contract development organizations bridging pilot-scale electrochemical research to commercial deposition lines as acquisition archetypes. Monitor Saudi SASO procurement mandate acceleration as the critical inflection signal for solid-state grid storage demand scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Active Materials | Mitigates Chilean lithium carbonate offtake contract volatility for Tangier Med producers. |
| Dry Electrode Coating Technology Licensing | Eliminates N-methyl-2-pyrrolidone recovery infrastructure and halves drying energy consumption. |
| Multi-Standard Certification Parallelism Investment | Simultaneous NRCS, Moroccan Institute, and SASO approvals fragment competitor quality assurance resources. |
| Laser Structuring Capability Transfer to Aerospace | Precision electrode patterning for satellite batteries commands margin premiums above automotive tiers. |
| Egyptian Special Economic Zone Manufacturing Footprint | Reduced import duty exposure for electrode coating equipment serving regional consumer electronics distribution. |
Research Methodology
Operator-level perspectives from gigafactory plant managers, European automotive OEM procurement leads, Saudi utility planning officers, and Egyptian industrial zone developers anchored the qualitative base. Secondary validation drew from IEC 62660 testing documentation, UN 38.3 certification registries, customs trade data for lithium carbonate and nickel sulfate flows, and national regulator compulsory specifications filings. Bottom-up capacity buildout timelines across Tangier Med, Gauteng, and Suez Canal Economic Zone clusters were triangulated against top-down European EV demand projections.
Scenario-bracketing framed low, base, and high cases across the projection horizon, with segmentation modeling spanning electrochemical chemistry, end-use vertical, fabrication technology, and regional regulatory cluster dimensions. CAGRs were derived from capacity commissioning schedules, offtake contract tenor analysis, and substitution elasticity estimates for solid-state versus liquid electrolyte architectures. Forecast inputs incorporated Saudi SASO procurement mandate trajectories and Ethiopian renewable energy auction pipeline visibility.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Northeast Asian chemical conglomerates or accelerated European battery passport enforcement would shift outcomes. Cross-checking against European automotive OEM platform electrification timelines and Gulf Cooperation Council grid interconnection investment disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Manufacturing
High Purity Process Systems for Semiconductor Market
Semiconductor Manufacturing
Advanced Process Control Market
Semiconductor Manufacturing
Global Overall EUV Lithography Market
Semiconductor Manufacturing
Electronic Manufacturing Services (EMS) Market
Semiconductor Manufacturing
Malaysia and Thailand Precession Cleaning for Electronic Market
Semiconductor Manufacturing
PCB Photoresist Market
Semiconductor Manufacturing
Global EUV Lithography Market
Semiconductor Manufacturing
Semiconductor and Circuit Manufacturing Market
Semiconductor Manufacturing
Photomask Market
Semiconductor Manufacturing
Solar Laser Drilling Market
Semiconductor Manufacturing
Semiconductor Polishing Pads Market
Semiconductor Manufacturing
Medical Component Manufacturing Market
Semiconductor Manufacturing
United States Photoresist and Photoresist Ancillaries Market
Semiconductor Manufacturing
Photoresist and Photoresist Ancillaries Market
Semiconductor Manufacturing
Silicon Turners Market
Semiconductor Manufacturing
Global Wafer Cutting Fluids Market