
 Global EUV Lithography Market | 2026-2036
Global EUV Lithography Market Size, Share, and Industry Trends Forecast 2026-2036
Global EUV Lithography Market Analysis
Software-defined predictive maintenance contracts is pivoting the commercial model for EUV lithography from capital-only transactions to recurring revenue streams. ASML leverages its installed base of over 200 EUV systems to sustain long-term service agreements across foundry customers. ZEISS Group anchors the optics supply chain through its exclusive mirror production for ASML's EUV platforms. KLA Corporation competes in process control by extending metrology tools that monitor EUV patterning fidelity at leading-edge nodes.
Extreme ultraviolet lithography employs 13.5-nanometer wavelength light generated by tin droplet laser-produced plasma to pattern silicon wafers at sub-7nm resolution. The technology enables single-exposure patterning of critical layers that previously required multiple immersion lithography passes, reducing manufacturing cycle time and defect rates. Foundries represent the dominant end-user segment as memory devices and logic devices absorb the majority of EUV system output, with logic applications commanding premium pricing due to tighter overlay specifications. Wafer optics constitutes the most concentrated product type segment, where mirror surface roughness tolerances below 50 picometers create formidable barriers to competitive entry.
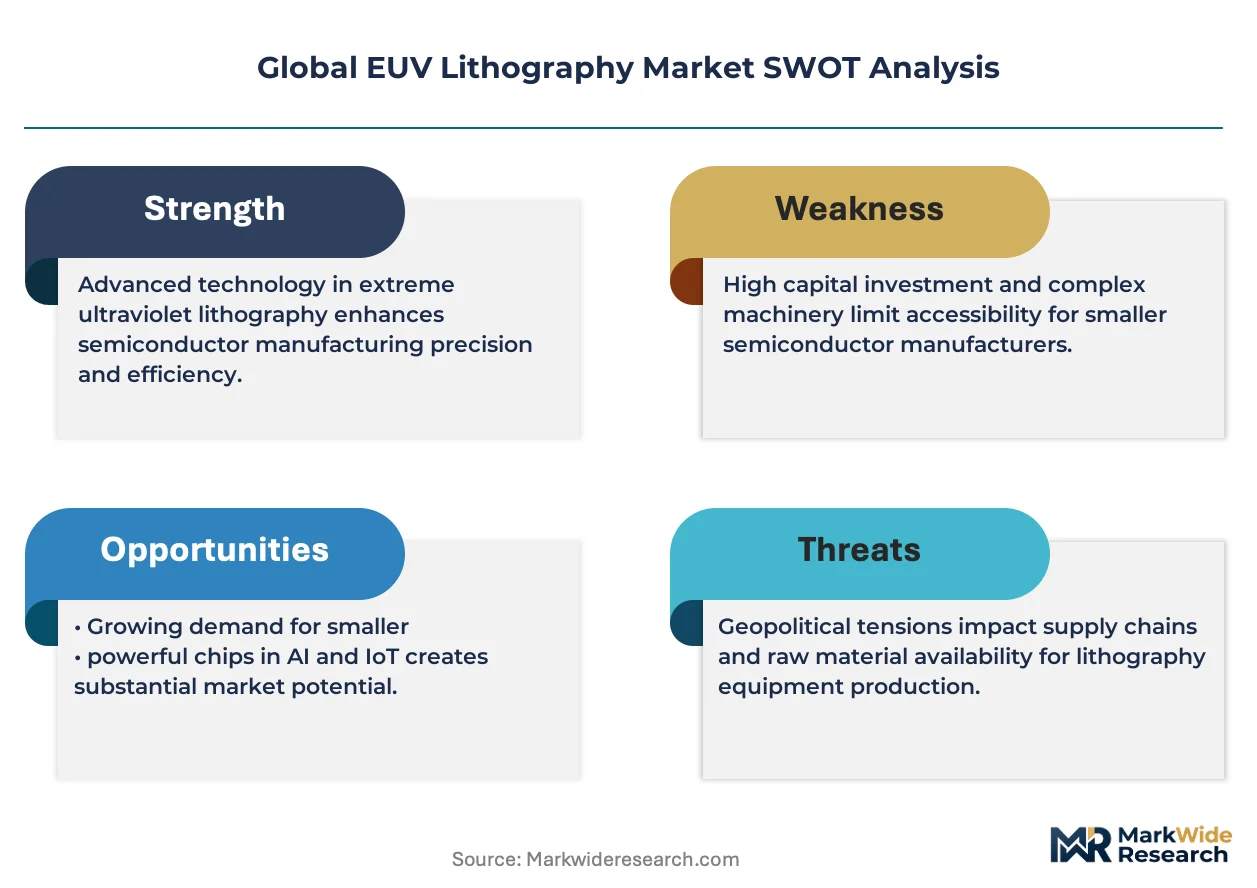
The US Department of Commerce Bureau of Industry and Security administers export controls on EUV equipment and components, restricting system deployment to approved end-users and geographies. The EU F-Gas Regulation governs fluorinated compound use in EUV laser cooling systems, compelling equipment redesigns to reduce greenhouse gas intensity. Japan's METI coordinates domestic supply chain investments in EUV pellicles and resist materials through its semiconductor strategy. Stakeholders must monitor regulatory alignment between the US, EU, and Japan as trilateral coordination on advanced lithography controls tightens, since divergent implementation timelines could fragment equipment deployment schedules and foundry expansion plans.
Market Dynamics
Equipment suppliers face intensifying pressure from the US Department of Commerce Bureau of Industry and Security export controls, which restrict EUV system deployment to approved end-users while foundries accelerate sub-3nm logic device production timelines.
Growth Catalysts
- Logic device scaling:Foundries are extending EUV patterning to transistor-level features below 3nm, creating sustained equipment pull through single-exposure process simplification.
- F-Gas Regulation compliance:The EU mandate for fluorinated compound reduction in laser cooling systems is compelling equipment redesigns that lower greenhouse gas intensity and unlock certification advantages.
- Taiwan fab clustering:Concentrated leading-edge manufacturing in Hsinchu and Tainan generates localized demand density that amortizes field service infrastructure across multiple customers.
Market Restraints
- Mirror supply concentration:Wafer optics fabrication depends on a single German supplier capable of achieving sub-50 picometer surface roughness tolerances, creating catastrophic single-point vulnerability.
- Tin droplet generator reliability:Laser-produced plasma source components exhibit mean-time-between-failure rates that compress equipment availability below contractual uptime guarantees.
- Export licensing latency:US Bureau of Industry and Security approval timelines for EUV component shipments extend delivery schedules by quarters, freezing foundry expansion synchronization.
Strategic Opportunities
- India semiconductor incentives:The country's PLI scheme for fab construction creates first-mover positioning for equipment vendors willing to localize service capabilities ahead of greenfield site completion.
- Predictive maintenance software:Sensor data monetization through AI-driven failure prediction is converting capital transactions into recurring revenue streams with decade-long contract durations.
- High-NA EUV convergence:Next-generation numerical aperture expansion combined with computational lithography is integrating to enable single-exposure patterning at 2nm resolution thresholds.
Industry Challenges
- Plasma physics specialist scarcity:The talent pool for laser-produced plasma source engineering is concentrated among fewer than five academic programs globally, constraining supplier scaling.
- Metrology-tool integration complexity:KLA Corporation process control systems require extensive calibration cycles to achieve overlay specifications below 1.5 nanometers, extending fab qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global EUV Lithography Market |
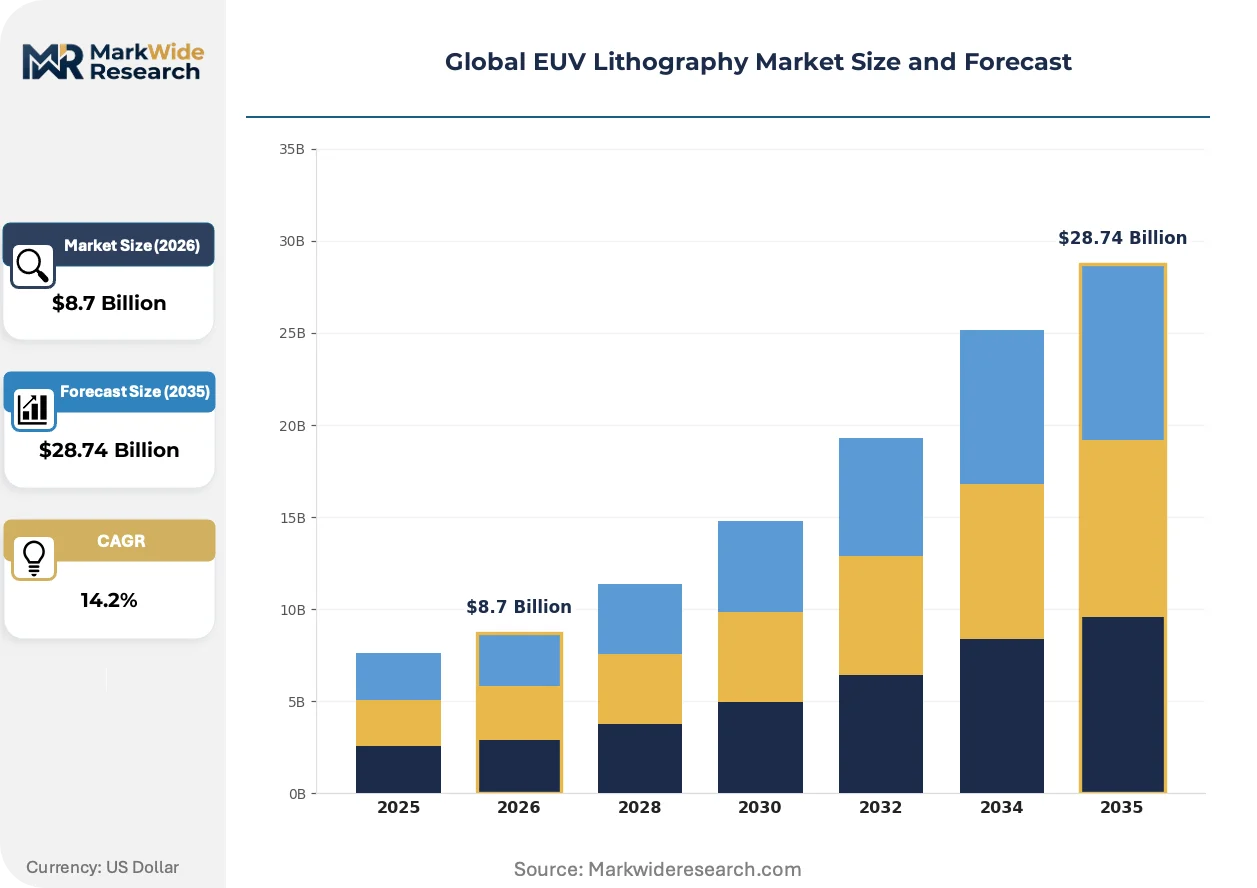
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Sources, Mask/Etch Equipment, Metrology Tools, Wafer Optics End User: Semiconductor Manufacturers, Research Institutions, Foundries, OEMs Technology: Optical Lithography, EUV Technology, Nanoimprint Lithography, Maskless Lithography Application: Memory Devices, Logic Devices, Nanoelectronics, Miscellaneous |
| Companies Covered | ASML, ZEISS Group, KLA Corporation, Canon Inc., TRUMPF, Samsung Electronics Co. Ltd., NTT Advanced Technology Corporation, Ushio Inc., Toppan Photomasks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global EUV Lithography Market Emerging Trajectories
Computational lithography algorithms and high-numerical-aperture optical systems are converging to extend single-exposure resolution limits while regulatory frameworks on fluorinated compounds force thermal management redesigns across supplier portfolios.
High-NA EUV lithography is integrating 0.55 numerical aperture optics with anamorphic imaging to pattern critical dimensions below 8nm without multiple patterning. Foundries in Taiwan and South Korea are piloting these systems for 2nm logic node risk production starting 2026. The technology is integrating resolution extension with productivity gains by reducing layer counts and cycle time in critical metal and via stacks.
The EU F-Gas Regulation is mandating phasedown schedules for hydrofluorocarbon refrigerants used in CO2 laser cooling loops, compelling ASML and subcomponent suppliers to qualify alternative thermal transfer fluids with lower global warming potential. Equipment redesigns must maintain laser stability within 0.1 degree Celsius while meeting 2030 phase-down milestones. Memory manufacturers in South Korea face accelerated compliance timelines compared to logic foundries due to higher laser duty cycles in high-volume DRAM production.
Foundry procurement teams are consolidating lithography tool purchasing under multi-year framework agreements that bundle equipment, consumables, and predictive maintenance into unified contracts. Equipment availability guarantees and uptime-based payment terms are displacing traditional capital purchase structures with milestone-based service fees. This shift is most pronounced in Taiwan, where TSMC's supplier consolidation strategy has compressed qualified vendor lists to single-source relationships for each technology generation.
Global EUV Lithography Market Segmentation
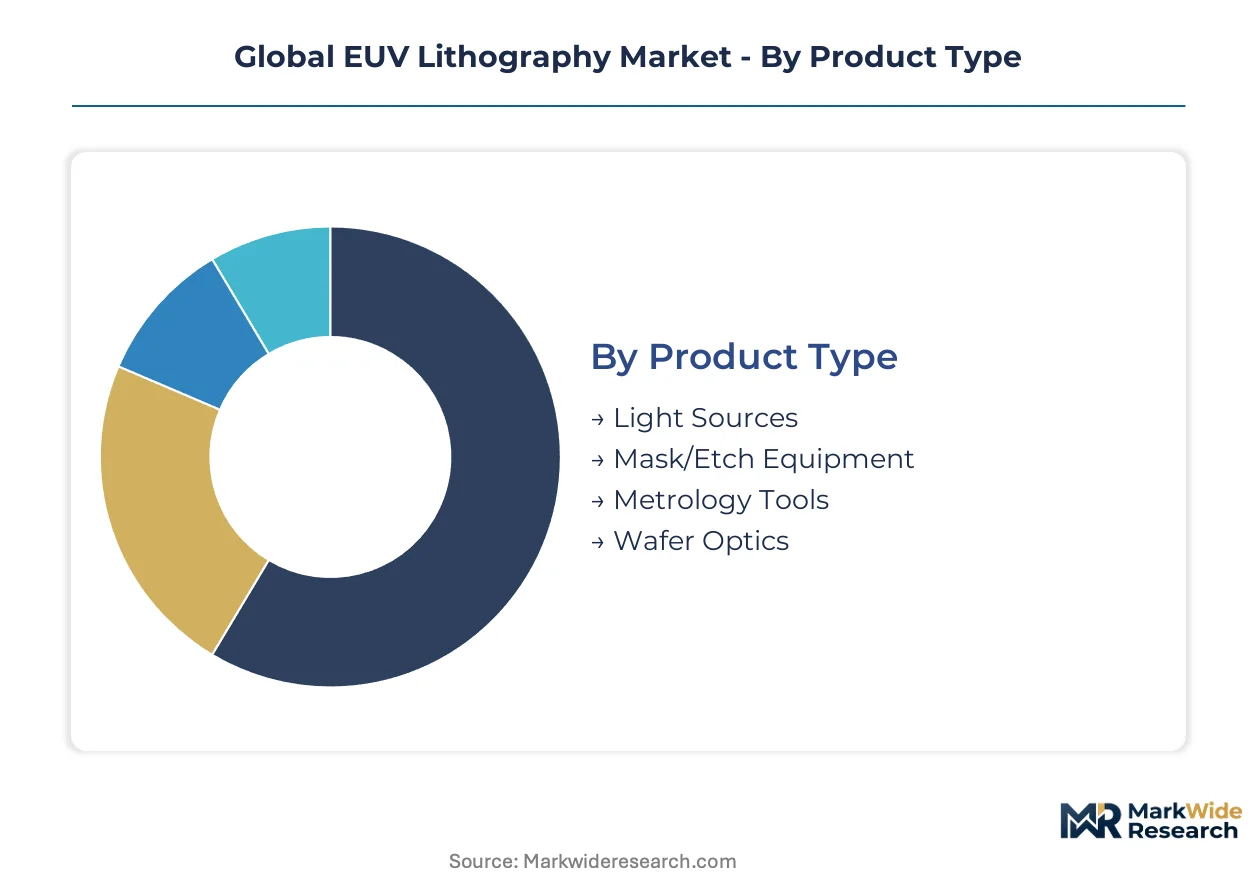
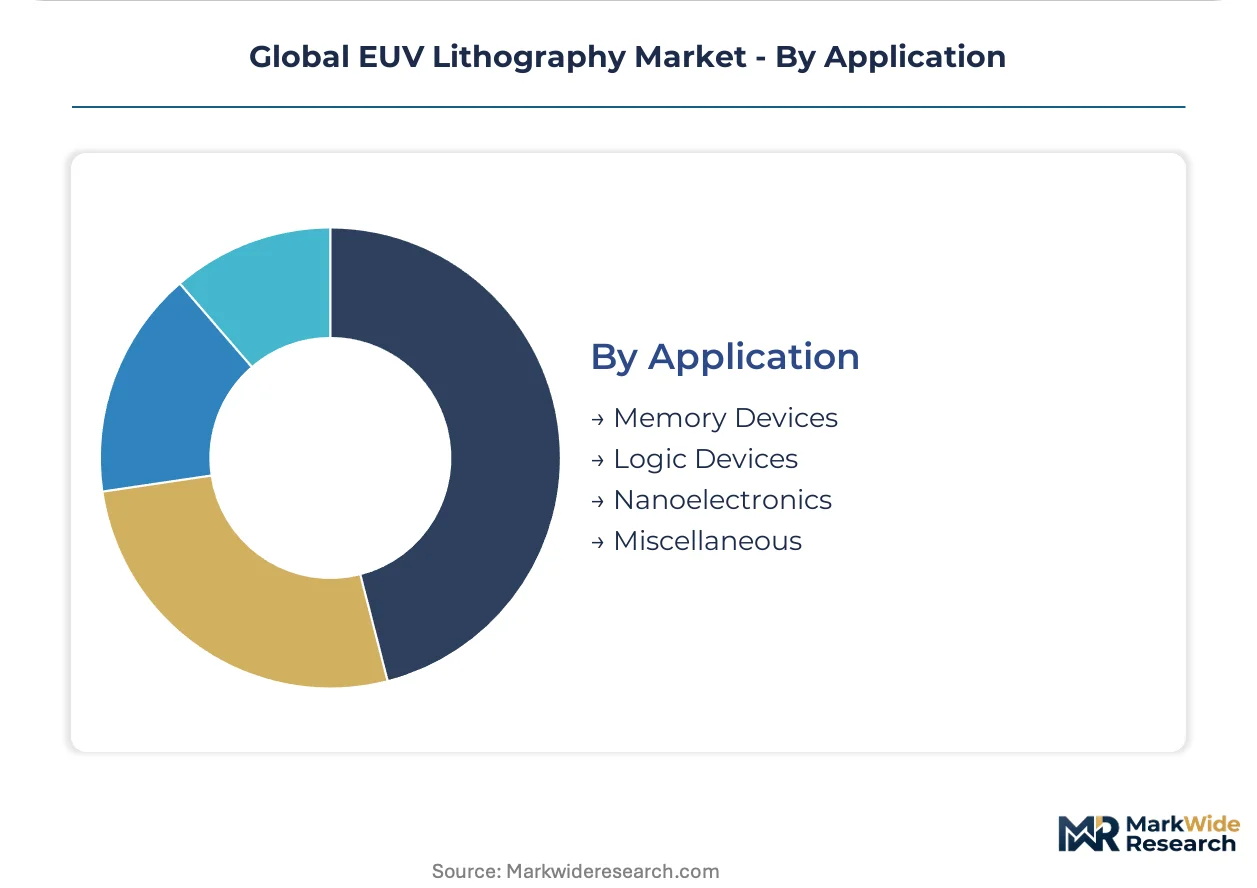
EUV lithography market segmentation reveals how technology complexity, end-use specialization, and application-specific resolution requirements create distinct commercial clusters with varying margin profiles and equipment qualification timelines.
Product Type:
Optical precision thresholds differentiate equipment tiers, with surface roughness tolerances and plasma stability specifications determining supplier concentration and pricing power.
- Wafer Optics:Mirror systems achieving sub-50 picometer surface roughness enable patterning fidelity at 2nm resolution thresholds. Demand concentrates in Dutch and German supply chains serving TSMC and Samsung foundry clusters, where single-source dependency creates catastrophic vulnerability exposure.
- Light Sources:Tin droplet laser-produced plasma generators emitting 13.5-nanometer wavelength light constitute the core enabling technology. Foundries in Taiwan and South Korea absorb the majority of source output, with reliability limitations compressing equipment availability below contractual uptime guarantees.
- Mask/Etch Equipment:Pattern transfer systems align EUV-exposed resist layers to underlying substrate features.
- Metrology Tools:Overlay measurement instruments verify pattern placement accuracy against sub-1.5 nanometer specifications.
Mature deployment sits with Wafer Optics. Newer deployment is concentrated in Metrology Tools.
End User:
Capital intensity and process integration depth separate customer tiers, with volume scale and technology node leadership determining equipment allocation priority.
- Foundries:Pure-play contract manufacturers extend EUV patterning to sub-3nm logic device production, commanding premium pricing due to tighter overlay specifications. TSMC in Taiwan and Samsung in South Korea dominate equipment absorption, with single-exposure process simplification reducing manufacturing cycle time.
- Semiconductor Manufacturers:Integrated device producers including memory specialists deploy EUV for high-volume DRAM and NAND fabrication. South Korean memory manufacturers face accelerated EUV F-Gas compliance timelines compared to logic foundries due to higher laser duty cycles.
- Research Institutions:Academic and national laboratory users pilot next-generation patterning techniques.
- OEMs:Original equipment manufacturers integrate lithography subsystems into broader fabrication platforms.
Foundries capture the steepest expansion trajectory. Research Institutions maintain stable procurement levels.
Technology:
Wavelength architecture and mask dependency define competitive substitution boundaries, with single-exposure capability and throughput economics driving migration patterns.
- EUV Technology:Extreme ultraviolet systems employing 13.5-nanometer wavelength light enable single-exposure patterning of critical layers previously requiring multiple immersion passes. Logic device scaling below 3nm in Taiwan and South Korea sustains equipment pull through process simplification and defect rate reduction.
- Optical Lithography:Deep ultraviolet immersion systems using 193-nanometer wavelength with liquid immersion extend legacy node production.
- Nanoimprint Lithography:Mechanical pattern replication techniques target specific memory and sensor applications.
- Maskless Lithography:Direct-write electron beam systems serve low-volume prototyping and photomask fabrication.
EUV Technology commands the dominant share. Nanoimprint Lithography is gaining traction in specialty memory segments.
Application:
Device physics and layer complexity determine exposure count requirements, with transistor density and interconnect stacking driving equipment utilization rates.
- Logic Devices:Microprocessor and system-on-chip production employs EUV for transistor-level features and critical metal layers, with overlay specifications tighter than memory applications. Taiwan foundries pilot high-NA systems for 2nm node risk production, integrating 0.55 numerical aperture optics with anamorphic imaging.
- Memory Devices:DRAM and NAND flash fabrication utilizes EUV for storage cell and peripheral circuit patterning. South Korean manufacturers deploy high-volume production lines with accelerated laser duty cycles that intensify F-Gas regulatory exposure.
- Nanoelectronics:Emerging device architectures including quantum and neuromorphic computing explore EUV patterning.
- Miscellaneous:Photonics, MEMS, and advanced packaging applications represent peripheral demand.
Logic Devices anchor premium pricing. Memory Devices expand most quickly in absolute unit terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment production concentrates in the Netherlands and Germany while consumption clusters in Taiwan and South Korea, creating a transcontinental supply-demand asymmetry that shapes logistics and service infrastructure investments.
Taiwan
TSMC's foundry expansion in Hsinchu and Tainan drives EUV system absorption for sub-3nm logic production. The island's National Development Council coordinates industrial park zoning for semiconductor clusters. Kaohsiung's emerging fab zone anchors southern Taiwan's capacity buildout alongside established northern facilities.
South Korea
Samsung Electronics and SK Hynix deploy EUV for high-volume DRAM and advanced logic, with memory manufacturers facing accelerated F-Gas compliance timelines. METI coordinates Japanese supply chain investments in resist materials serving Korean fabs. Pyeongtaek and Hwaseong host concentrated EUV-equipped production lines with localized service hubs.
Netherlands
ASML's Veldhoven headquarters anchors the sole source of commercial EUV lithography systems worldwide. The EU F-Gas Regulation governs fluorinated compound use in laser cooling systems, compelling thermal management redesigns. Eindhoven's Brainport tech corridor clusters optics specialists and subcomponent suppliers within 50 kilometers of final assembly.
United States
Intel's domestic fab investments in Arizona and Ohio create emerging EUV demand alongside established R&D activity. The Bureau of Industry and Security administers export controls restricting system deployment to approved end-users. Albany Nanotech Complex in New York maintains pilot line capabilities for high-NA EUV process development.
Japan
Domestic suppliers concentrate in EUV pellicles, resist materials, and metrology components rather than complete systems. METI's semiconductor strategy directs funding toward supply chain resilience in critical materials. Yokohama and Kyoto host specialized component manufacturers serving Dutch and Korean equipment integrators.
Global EUV Lithography Market Vendor Landscape
Capital-heavy equipment producers compete with asset-light component specialists for margin capture across the EUV value chain. The market structure consolidates around a single lithography system integrator supported by exclusive optical and laser source suppliers. Two strategic archetypes dominate: integrated platform vendors controlling full-stack architecture and specialized component suppliers with irreplaceable process expertise. Competitive moves center on long-term service contract conversion and exclusive supply agreements locking out rival component sources.
Among Dutch and German equipment specialists, ASML and ZEISS Group occupy positions that exemplify the platform-vendor and exclusive-supplier archetypes respectively. KLA Corporation represents the process control tier, extending metrology capabilities that monitor patterning fidelity. These three anchors demonstrate how geographic clustering in the Netherlands and Germany creates defensive moats through talent density and multi-decade supplier relationships.
| Leading Market Players |
|---|
| ASML |
| ZEISS Group |
| KLA Corporation |
| Canon Inc. |
| TRUMPF |
| Samsung Electronics Co. Ltd. |
| NTT Advanced Technology Corporation |
| Ushio Inc. |
| Toppan Photomasks |
| Others |
Supply Flow & Price Mechanics
Performance-grade divergence between sub-50 picometer wafer optics and commodity-grade lithography components manifests in stark pricing power asymmetries, with mirror surface roughness tolerances anchoring premium tiers while tin droplet generator reliability failures compress margins in source equipment. This bifurcation concentrates supplier margins in German and Dutch optical clusters while exposing laser-produced plasma component vendors to penalty clauses and uptime-based payment erosion.
Pricing Analysis
Margin tightening in laser source equipment reflects contractual uptime guarantees that ASML cannot meet due to tin droplet generator mean-time-between-failure limitations. Three-tier pricing structure across premium, standard, and economy levels separates foundry-grade systems with sub-1.5 nanometer overlay specifications from memory-optimized configurations and research-lab pilot tools. Pricing pressure stems from export licensing latency extending US Bureau of Industry and Security approval timelines by quarters, freezing foundry expansion synchronization. Logic foundries in Taiwan exhibit lowest price sensitivity due to single-exposure process simplification value capture, while memory manufacturers in South Korea face acute cost compression from accelerated F-Gas compliance timelines.
Supply Chain Analysis
Single-source vulnerability sits with ZEISS Group's exclusive mirror production for ASML's EUV platforms, where sub-50 picometer surface roughness tolerances create irreplaceable process expertise. Manufacturing gravity centers on the Netherlands for final system integration, Germany for optical components, and Japan for EUV pellicles and resist materials. Raw material dependencies include high-purity silicon substrates, tin feedstock for laser-produced plasma generation, and fluorinated compounds for laser cooling systems. Tariff exposure intensifies as US export controls fragment equipment deployment schedules across approved and restricted geographies. Distribution runs through direct field service teams co-located with TSMC and Samsung fab clusters in Taiwan and South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capacity constraints in laser-produced plasma source engineering—where fewer than five academic programs globally produce qualified specialists—prop pricing power for incumbent equipment vendors and sustain decade-long service contract premiums.
For Market Incumbents: Anticipate regulatory fragmentation as US, EU, and Japan coordinate divergent export control implementation timelines, compressing equipment deployment windows. Defensive consolidation through exclusive supply agreements locking out rival component sources in mirror fabrication and tin droplet generation preserves margin position. Prioritize backward integration into predictive maintenance software to convert capital transactions into recurring revenue streams with foundry customers. For New Entrants and Emerging Players: Enter via India's PLI scheme for fab construction, where first-mover positioning in localized service capabilities precedes greenfield site completion. White-space targets concentrate in EUV pellicles and resist materials, where Japanese suppliers currently dominate but capacity expansion lags demand growth. Alternative thermal transfer fluids for F-Gas-compliant laser cooling represent the most penetrable component segment. Go-to-market angle: partner with domestic Indian system integrators ahead of Intel and TSMC site operationalization. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by ASML or its tier-one subsystem suppliers seeking to eliminate single-source vulnerabilities. Long-term viability favors component specialists with irreplaceable process expertise in plasma physics or sub-picometer optical fabrication over capital-heavy system integrators facing cyclical foundry capex compression. Acquisition target archetype: German or Japanese mid-cap suppliers with exclusive technology positions in wafer optics or laser sources. Signal to watch: Bureau of Industry and Security licensing queue length as inflection indicator for equipment delivery schedule risk.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Software Monetization | ASML leverages sensor data from 200+ installed systems to convert capital sales into decade-long service contracts. |
| High-NA EUV System Deployment | 0.55 numerical aperture optics integration enables single-exposure patterning at 2nm resolution thresholds for TSMC and Samsung. |
| F-Gas Alternative Thermal Fluid Qualification | Equipment redesigns maintain laser stability within 0.1°C while meeting EU phasedown milestones for fluorinated compounds. |
| India Service Infrastructure Pre-Positioning | Equipment vendors localize capabilities ahead of Intel and TSMC fab completion under PLI scheme incentives. |
| Exclusive Optical Supply Agreement Extension | ZEISS Group's sub-50 picometer mirror monopoly locks out competitive entry through multi-decade supplier relationships. |
Methodological Framework
Document review covered SEC filings from lithography equipment vendors, EU regulatory submissions on F-Gas compliance, and US Bureau of Industry and Security export control determinations, complemented by interviews with foundry procurement executives, plasma physics specialists, and metrology tool engineers. Secondary validation drew from customs trade data on EUV component shipments, SEMI equipment market databases, and patent filings in laser-produced plasma source technology. Bottom-up and top-down triangulation reconciled equipment unit forecasts with foundry capex disclosure patterns.
Model outputs span unit shipments, installed base service revenue, and component-level demand across the projection horizon. Segmentation dimensions include product type hierarchy from wafer optics through metrology tools, end-user categories separating foundries from integrated device manufacturers, technology migration paths from EUV to high-NA EUV, and application splits between logic and memory devices. CAGRs were derived from equipment absorption rates tied to TSMC and Samsung node transition schedules, with inputs from ASML order backlog disclosure patterns and foundry utilization rate assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of extended US-China technology restrictions or accelerated F-Gas phase-down timelines. Forecasts reflect assumptions on laser source reliability improvement curves, high-NA EUV yield ramp schedules, and trilateral regulatory alignment between US, EU, and Japan export control frameworks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Manufacturing
Middle East and Africa Cell Manufacturing Market
Semiconductor Manufacturing
Photoresist and Photoresist Ancillaries Market
Semiconductor Manufacturing
China Electronic Design Automation (EDA) Tools Market
Semiconductor Manufacturing
IC CMP Slurries and Pads Market
Semiconductor Manufacturing
Malaysia and Thailand Precession Cleaning for Electronic Market
Semiconductor Manufacturing
High Purity Process Systems for Semiconductor Market
Semiconductor Manufacturing
Semiconductor and Circuit Manufacturing Market
Semiconductor Manufacturing
Advanced Process Control Market
Semiconductor Manufacturing
Photoresist Stripper Market
Semiconductor Manufacturing
Semiconductor Bonding Machine Market
Semiconductor Manufacturing
PCB Photoresist Market
Semiconductor Manufacturing
Solar Laser Drilling Market
Semiconductor Manufacturing
Global Wafer Cutting Fluids Market
Semiconductor Manufacturing
Stencil Lithography Market
Semiconductor Manufacturing
Chip Melting Furnace Market
Semiconductor Manufacturing
Europe Electronic Manufacturing Services Market