
 EUV Lithography Service Market | 2026-2036
EUV Lithography Service Market Size, Share, and Industry Trends Forecast 2026-2036
EUV Lithography Service Market Insights
Foundry demand for sub-3nm logic nodes is expanding faster than memory-sector uptake, pulling EUV service hours toward advanced logic customers. ASML leverages its monopoly on EUV scanner systems to anchor service pricing power across the installed base. ZEISS Group sustains optics refurbishment leadership through captive control over mirror metrology and recoating workflows. KLA Corporation competes in defect inspection services that extend tool uptime for EUV lithography bays.
EUV lithography service encompasses technical support, preventive maintenance, and yield optimization for extreme ultraviolet projection systems operating at 13.5nm wavelength with plasma-generated light sources. These services sustain semiconductor fabrication at sub-7nm geometries where optical lithography fails, requiring vacuum environments and precision thermal management to maintain overlay accuracy below 1.5nm. Contract manufacturing services capture the largest revenue pool as foundries outsource mask blank production and resist coating steps, while maintenance support commands premium pricing due to ASML's proprietary control over source collector modules and droplet generator replacement cycles. Equipment leasing is accelerating among research institutions seeking EUV access without capital commitment.
US export controls administered by BIS restrict EUV service transfers to certain foundries, fragmenting service availability across geopolitical boundaries. REACH and RoHS frameworks in Europe govern chemical handling in photoresist supply chains, adding compliance overhead for service providers operating EUV resist track systems. Taiwan's NSTC and South Korea's MOTIE each fund domestic EUV infrastructure programs that shape where service capacity localizes. Stakeholders must decide whether to build captive service teams or accept vendor lock-in from ASML's expanding service contract portfolio.
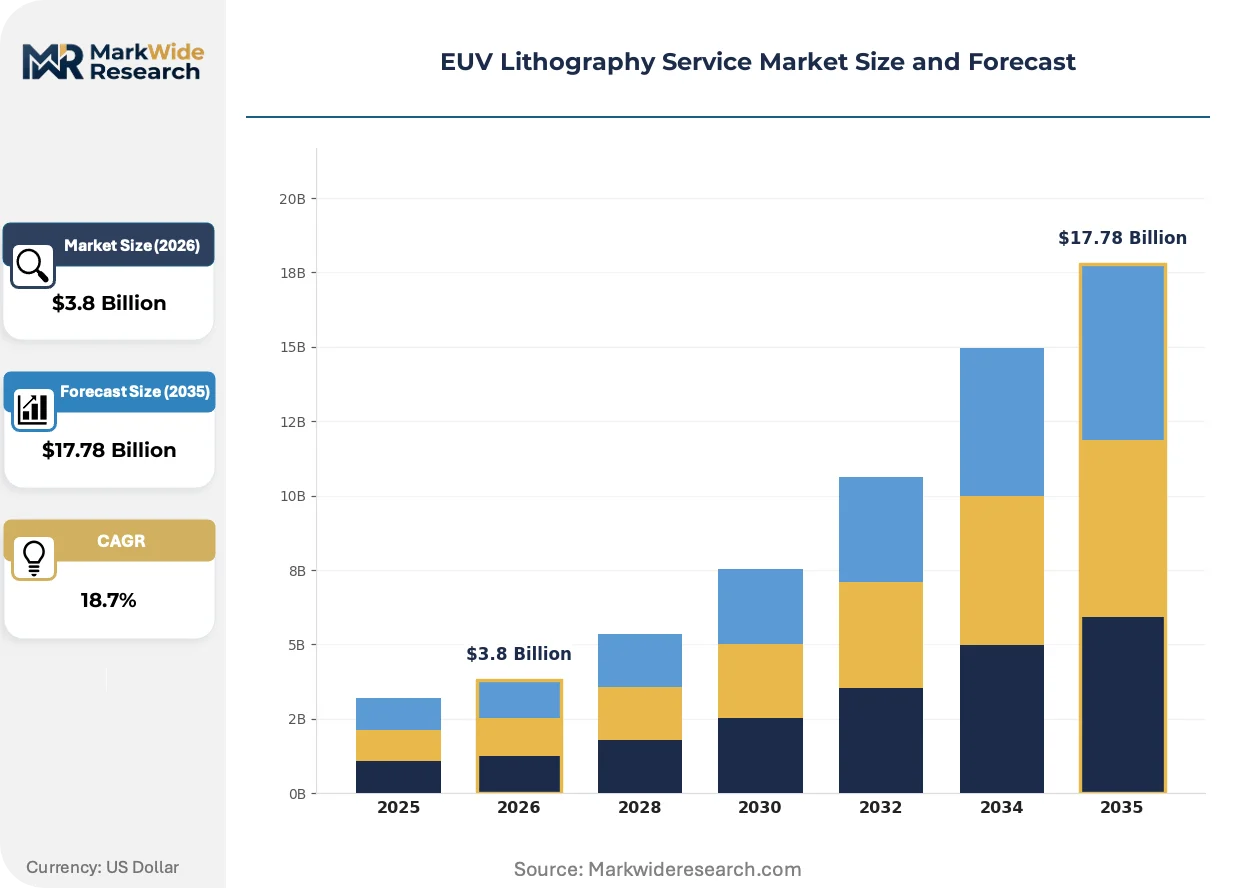
Market Dynamics
ASML's monopoly on EUV source collector modules and droplet generator replacement cycles concentrates service pricing power in a single vendor, forcing foundries to choose between vendor lock-in and the technical risk of captive maintenance teams.
Growth Catalysts
- Sub-3nm logic node ramp:Taiwan Semiconductor Manufacturing Company and Samsung Foundry are expanding EUV bay counts for angstrom-scale transistor production, pulling service hours toward advanced logic.
- EU AI Act compliance requirements:Semiconductor supply chain traceability mandates under the EU AI Act are accelerating localized EUV service certification programs across European fabrication sites.
- High-NA EUV scanner deployment:Next-generation 0.55 numerical aperture systems require specialized vacuum chamber refurbishment and thermal management protocols that expand addressable service scope.
Market Restraints
- Single-source optics dependency:ZEISS Group's captive control over mirror metrology and recoating workflows creates irreplaceable supply concentration for critical refurbishment steps.
- US BIS export control fragmentation:Bureau of Industry and Security restrictions on EUV service transfers to certain Chinese foundries bifurcate service availability and complicate spare parts logistics.
- Helium supply volatility:Cryogenic cooling systems for EUV plasma sources depend on helium extraction from natural gas processing, exposing service operations to input cost swings.
Strategic Opportunities
- India semiconductor infrastructure buildout:India's PLI scheme and semiconductor fabrication incentives are creating greenfield EUV service demand as the country establishes its first advanced logic fabs.
- Research institution equipment leasing:Universities and national laboratories are adopting subscription-based EUV access models that bundle maintenance, training, and upgrade pathways.
- Predictive maintenance AI integration:Machine learning models trained on scanner telemetry are converging with remote diagnostics platforms to enable condition-based service scheduling.
Industry Challenges
- Vacuum technician scarcity:EUV systems require specialists trained in ultra-high vacuum engineering and plasma physics, with certification timelines extending 18-24 months.
- Legacy DUV integration complexity:Hybrid lithography bays combining EUV and deep ultraviolet tools demand cross-platform overlay calibration expertise that strains service team bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EUV Lithography Service Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.78 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Contract Manufacturing, Equipment Leasing, Maintenance Support, Consulting Technology: Thin Film, Chemical Vapor Deposition, Photoresist, Imaging Industry Vertical: Semiconductors, Electronics, Automotive, Aerospace End User: Foundries, Integrated Device Manufacturers, Research Institutions, Government Agencies |
| Companies Covered | ASML, KLA Corporation, ZEISS Group, TRUMPF, AGC Inc., Lasertec Corporation, HOYA Corporation, TOPPAN Inc., ADVANTEST Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EUV Lithography Service Market Trends and Innovations
Service delivery models for EUV lithography are fragmenting as geopolitical boundaries harden and foundries seek alternatives to single-vendor dependency. Three forces are actively reshaping technical support, maintenance protocols, and buyer-vendor relationships.
Computational lithography software is converging with real-time scanner metrology to enable dynamic process correction during exposure sequences. Foundries operating sub-3nm nodes are adopting these closed-loop systems to compress overlay error budgets below 1.2nm. This convergence is displacing static correction tables and expanding software-intensive service revenue pools relative to hardware maintenance.
REACH chemical authorization requirements are tightening photoresist supply chain documentation for EUV resists containing fluorinated polymers. Service providers must now track substance volumes through resist track systems and report usage to ECHA. European fabs are responding by consolidating resist coating steps with qualified contract manufacturers who maintain dedicated compliance teams.
Buyers are unbundling preventive maintenance contracts from equipment purchase agreements, negotiating standalone service level agreements with shorter renewal cycles. Taiwan's Hsinchu Science Park cluster is driving this shift as foundries seek competitive bidding for collector module replacement and droplet generator refurbishment. Independent service providers are capturing share in non-proprietary subsystems while ASML retains captive control over source technology.
EUV Lithography Service Market Segmentation
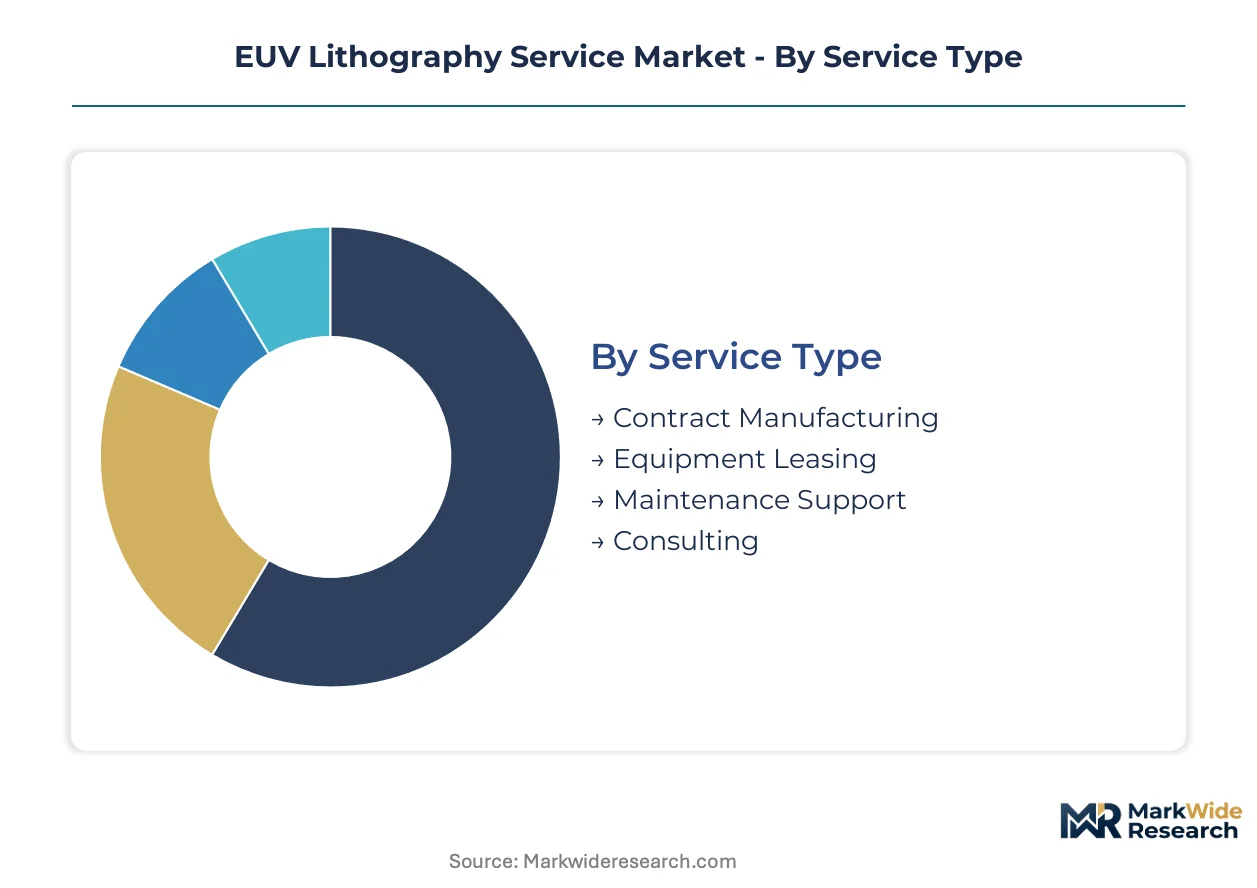
EUV lithography service segmentation reveals how vendor capabilities align with divergent buyer technical requirements and capital deployment strategies. Distinct service models, technology dependencies, and end-user sophistication levels create tiered pricing and delivery structures across the installed base.
Service Type:
Buyer capital intensity and in-house technical depth determine which service model dominates procurement decisions across the EUV installed base.
- Contract Manufacturing:Outsourced mask blank production and resist coating workflows capture the largest revenue pool as foundries seek to avoid captive chemical handling infrastructure. Taiwan's Hsinchu Science Park cluster concentrates demand for these services, driven by TSMC and Samsung Foundry requirements for sub-3nm node ramp.
- Maintenance Support:Preventive and corrective services for source collector modules, droplet generators, and vacuum systems command premium pricing due to ASML's proprietary control over replacement cycles and technical documentation. South Korea's Pyeongtaek semiconductor corridor generates concentrated demand for 24/7 uptime guarantees.
- Equipment Leasing:Subscription-based EUV scanner access bundles maintenance, training, and upgrade pathways for capital-constrained research institutions.
- Consulting:Yield optimization and process integration advisory services address hybrid lithography bay complexity for fabs transitioning from DUV to EUV.
Maintenance Support leads volumes today; Contract Manufacturing is gaining share fastest.
Technology:
Technical differentiation in EUV service delivery traces directly to which subsystem expertise a provider controls.
- Photoresist:Specialized coating and development services for chemically amplified resists operate under stringent REACH substance tracking requirements. European fabs in Dresden and Leuven drive demand for ECHA-compliant resist handling workflows.
- Imaging:Optical proximity correction and computational lithography integration services enable real-time overlay correction during exposure sequences. Foundries operating angstrom-scale transistor production in Taiwan and South Korea pull service hours toward dynamic process control.
- Thin Film:Multilayer mirror coating and refurbishment services sustain EUV optics performance through controlled deposition environments.
- Chemical Vapor Deposition:Protective capping layer deposition for collector modules extends component lifetime in high-volume production settings.
Imaging services command the steepest expansion trajectory as computational lithography converges with scanner metrology.
Industry Vertical:
End-market semiconductor content requirements dictate EUV service specification levels and certification protocols.
- Semiconductors:Advanced logic and memory fabrication consumes the dominant share of EUV service hours, with sub-3nm node production in Taiwan and South Korea requiring specialized vacuum chamber refurbishment and thermal management protocols.
- Electronics:High-performance computing and mobile system-on-chip packaging drives secondary demand for EUV-based interconnect patterning services.
- Automotive:Functional safety certification under ISO 26262 shapes EUV service requirements for automotive-grade semiconductor reliability.
- Aerospace:Radiation-hardened device production generates niche demand for specialized process control and documentation services.
Semiconductors anchors current volumes; Automotive is climbing the fastest as electrification multiplies chip content per vehicle.
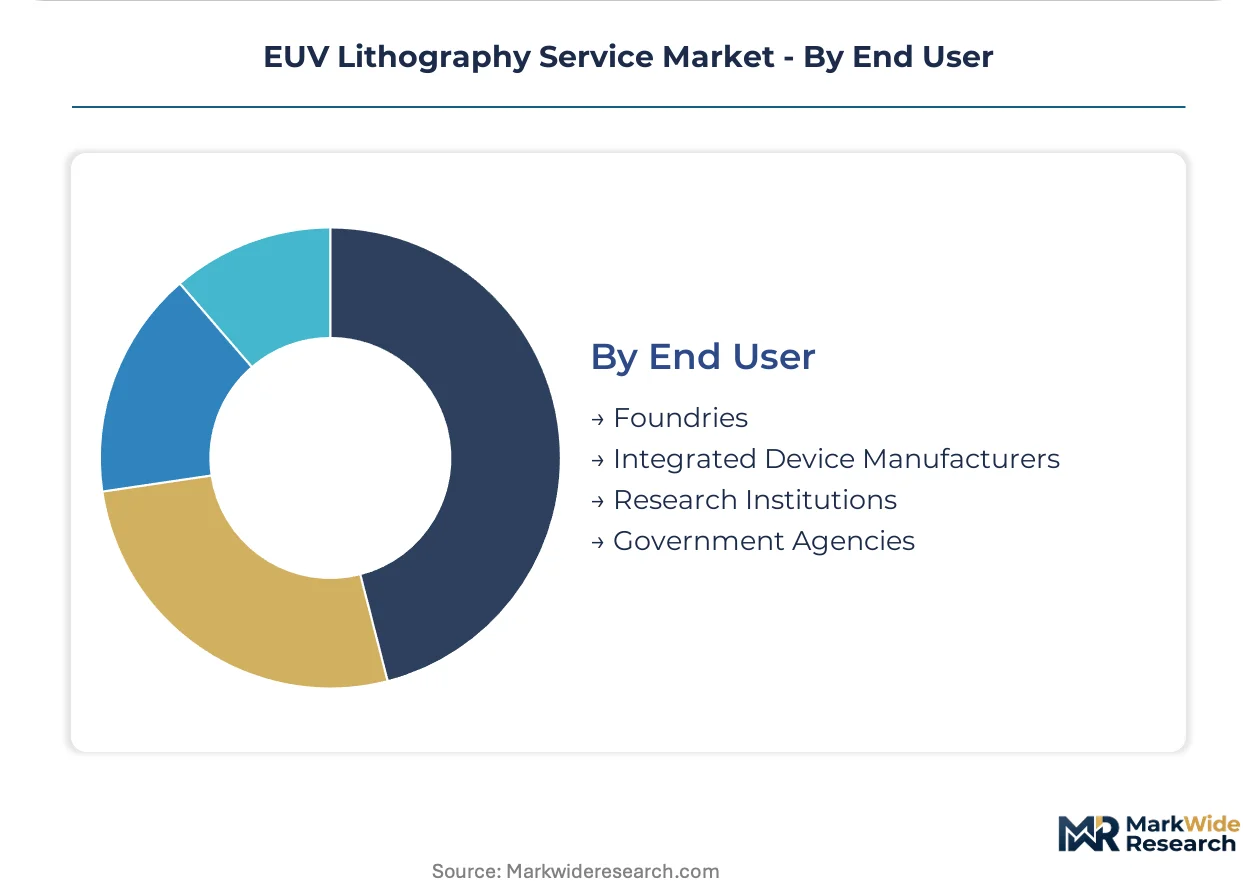
End User:
Technical sophistication and capital availability segment EUV service buyers into distinct procurement behavior patterns.
- Foundries:Pure-play and captive foundry operations generate concentrated demand for full-service EUV bay management, with TSMC and Samsung Foundry negotiating multi-year service level agreements covering source technology and optics refurbishment.
- Integrated Device Manufacturers:IDMs with captive fabrication maintain hybrid in-house and outsourced service models for proprietary process protection.
- Research Institutions:Universities and national laboratories adopt equipment leasing and training-bundled services to access EUV capability without capital commitment.
- Government Agencies:Defense and space programs fund specialized EUV process development through contracted research services.
Foundries dominate procurement volumes today; Research Institutions are expanding most quickly through subscription-based access models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where EUV service capacity localizes, with foundries migrating maintenance operations toward jurisdictions offering streamlined export licensing and lower compliance overhead for vacuum technician certification programs.
Taiwan
TSMC's sub-3nm node ramp at Fab 18 and Fab 20 is pulling record EUV service hours toward Hsinchu Science Park and Taichung's Central Taiwan Science Park. The National Science and Technology Council (NSTC) funds domestic EUV infrastructure programs that accelerate technician certification pipelines. Kaohsiung's emerging semiconductor corridor is attracting independent service providers seeking proximity to advanced packaging facilities.
South Korea
Samsung Foundry and SK Hynix are expanding EUV bay counts at Pyeongtaek and Yongin complexes for angstrom-scale memory and logic production. The Ministry of Trade, Industry and Energy (MOTIE) channels subsidies into localized source collector refurbishment capabilities. Seongnam's Pangyo tech cluster houses specialized vacuum engineering firms serving the semiconductor corridor.
United States
Intel's Ohio and Arizona fab buildouts are generating greenfield demand for EUV installation and commissioning services. Bureau of Industry and Security (BIS) export controls restrict service transfers to certain foreign foundries, fragmenting spare parts logistics. Phoenix's semiconductor ecosystem is developing captive maintenance training programs to reduce vendor dependency.
Netherlands
ASML's Veldhoven headquarters anchors global EUV service engineering and source technology development. REACH chemical authorization requirements govern photoresist handling workflows across European fabs served from Dutch logistics hubs. Eindhoven's Brainport tech cluster concentrates metrology and optics refurbishment expertise.
Japan
Lasertec and ADVANTEST anchor defect inspection and test equipment services supporting EUV yield optimization. The Ministry of Economy, Trade and Industry (METI) funds domestic supply chain resilience programs for critical lithography subsystems. Yokohama's Kanagawa cluster houses specialized coating and mirror refurbishment operations.
EUV Lithography Service Market Competitive Landscape
Strategic partnerships dominate the current landscape as service providers seek to unbundle ASML's captive control over proprietary subsystems. The market structure concentrates around a single dominant equipment vendor with tiered layers of specialized subcontractors and emerging independent challengers. Three archetypes define competitive positioning: source technology captives, optics refurbishment specialists, and independent subsystem service providers. Geographic expansion and technology licensing represent the primary vectors for competitive differentiation.
Within the source technology captive tier, ASML anchors global service pricing power through proprietary control over droplet generators and collector modules. ZEISS Group exemplifies the optics refurbishment archetype with captive mirror metrology workflows. KLA Corporation occupies a position among inspection and metrology specialists extending tool uptime for EUV lithography bays. These three entities represent distinct strategic positions without direct overlap in core service domains.
| Leading Market Players |
|---|
| ASML |
| KLA Corporation |
| ZEISS Group |
| TRUMPF |
| AGC Inc. |
| Lasertec Corporation |
| HOYA Corporation |
| TOPPAN Inc. |
| ADVANTEST Corporation |
| Others |
Pricing and Supply Chain Analysis
ASML's captive financing of source technology development through retained earnings and strategic R&D partnerships anchors supply discipline across the EUV service ecosystem, concentrating pricing power in proprietary subsystems while forcing foundries to absorb premium service rates or accept technical risk from independent alternatives.
Pricing Analysis
Direct-to-foundry service contracts bypass traditional distributor margins, with ASML capturing full value through captive control over droplet generators and collector modules. Three-tier pricing structure across premium uptime guarantees, standard preventive maintenance, and economy break-fix tiers differentiates by certification level and response time. Cost compression in standard-tier maintenance is intensifying because independent providers are unbundling non-proprietary subsystems. Research institutions exhibit highest price sensitivity due to capital constraints, while sub-3nm foundries accept premium pricing for source technology access.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale foundry demand for source collector modules and vacuum subsystems, with ASML maintaining captive fabrication in the Netherlands. Taiwan, South Korea, and the United States concentrate EUV service capacity, drawing from German optics, Japanese metrology equipment, and Dutch source technology. Helium extraction from natural gas processing in Qatar and the United States feeds cryogenic cooling systems, exposing operations to commodity price volatility. Distribution runs through qualified logistics hubs in Veldhoven, Hsinchu, and Pyeongtaek that maintain cleanroom-compatible handling protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EUV lithography service market reads as a late-cycle quality story, with sub-3nm logic node ramp forcing foundries toward premium-certified service tiers that guarantee angstrom-scale overlay precision.
For Market Incumbents: Extend captive control over source technology through accelerated certification pipelines for vacuum technicians, reducing foundry incentives to develop independent maintenance capabilities. Deepen backward integration into mirror metrology workflows to offset ZEISS Group's optics refurbishment dominance. Prioritize multi-year service level agreements with TSMC and Samsung Foundry that bundle predictive maintenance AI to lock out emerging diagnostic specialists. For New Entrants and Emerging Players: Predictive maintenance software trained on scanner telemetry offers the most penetrable wedge for technology-first challengers, with research institutions in India and Europe representing underserved subscription-based demand. Target equipment leasing bundled with training services for capital-constrained national laboratories seeking EUV access without source technology dependency. Lead with remote diagnostics platforms that converge machine learning models with real-time overlay correction capabilities. For Investors and Strategic Acquirers: Valuations sit cheapest among independent subsystem service providers with vacuum engineering expertise and established foundry relationships outside ASML's direct control. Long-term viability hinges on geopolitical fragmentation persisting, with BIS export controls sustaining bifurcated service markets. Watch for MOTIE and NSTC funding announcements as inflection indicators for localized capacity buildouts that reshape competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance AI Integration | Machine learning convergence with scanner telemetry enables condition-based service scheduling for TSMC and Samsung Foundry bays. |
| Localized Source Collector Refurbishment | South Korea's MOTIE subsidies accelerate domestic capabilities that reduce ASML captive dependency in Pyeongtaek corridor. |
| Research Institution Equipment Leasing | Subscription-based EUV access bundles maintenance and training for India's emerging semiconductor infrastructure. |
| REACH-Compliant Resist Handling Certification | ECHA substance tracking requirements in Dresden and Leuven consolidate coating steps with qualified contract manufacturers. |
| High-NA EUV Vacuum Chamber Specialization | Next-generation 0.55 numerical aperture systems expand addressable service scope for thermal management protocols. |
Research Methodology
Multiple input streams — primary interviews with EUV service directors, vacuum engineering specialists, and foundry procurement leads; secondary validation through ASML annual disclosures, BIS export control filings, and NSTC infrastructure program announcements; plus customs data on helium and specialty gas imports — were reconciled through bottom-up installed base modeling and top-down semiconductor capital expenditure triangulation.
Data-stream reconciliation across service type segmentation, technology subsystem categories, and end-user procurement patterns shaped the analytical framework over the projection horizon. CAGRs were derived from EUV scanner installation forecasts, service contract renewal rates, and regional fab buildout pipelines. Modeling incorporated sub-3nm node ramp timelines, High-NA EUV deployment schedules, and geopolitical licensing assumptions as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to BIS export control expansion, helium supply disruptions, and vacuum technician certification pipeline bottlenecks. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Manufacturing
PCB Photoresist Market
Semiconductor Manufacturing
China Electronic Design Automation (EDA) Tools Market
Semiconductor Manufacturing
Medical Component Manufacturing Market
Semiconductor Manufacturing
Chip Melting Furnace Market
Semiconductor Manufacturing
Battery Manufacturing Machines Market
Semiconductor Manufacturing
Silicon Turners Market
Semiconductor Manufacturing
IC CMP Slurries and Pads Market
Semiconductor Manufacturing
Photoresist Stripper Market
Semiconductor Manufacturing
Photomask Market
Semiconductor Manufacturing
Semiconductor Polishing Pads Market
Semiconductor Manufacturing
Semiconductor and Electronic Parts Manufacturing Market
Semiconductor Manufacturing
Solder Paste Market
Semiconductor Manufacturing
Global Overall EUV Lithography Market
Semiconductor Manufacturing
United States Photoresist and Photoresist Ancillaries Market
Semiconductor Manufacturing
Photoresist and Photoresist Ancillaries Market
Semiconductor Manufacturing
Electronic Manufacturing Services (EMS) Market