
 Silicon Turners Market | 2026-2036
Silicon Turners Market Size, Share, and Industry Trends Forecast 2026-2036
Silicon Turners Market Analytics
Subscription-based predictive maintenance for CNC lathes is repositioning how silicon turners monetize equipment uptime. Dow leverages its materials science portfolio to supply high-purity silicon blanks optimized for tight-tolerance turning. Wacker Chemie AG sustains geographic dominance through integrated polysilicon-to-wafer capabilities that downstream turners depend upon. Shin-Etsu Chemical Co. Ltd differentiates via proprietary crystal orientation control that reduces tool wear during high-speed machining.
Silicon turners are precision machining systems that rotate monocrystalline or polycrystalline silicon workpieces against fixed cutting tools, typically achieving surface finishes below 0.4 micrometers Ra and dimensional tolerances of ±2 micrometers for semiconductor and optical applications. Their primary purpose centers on producing silicon components with exacting thermal and electrical properties for devices where material integrity cannot degrade through alternative forming methods. CNC lathes dominate installed capacity due to repeatability requirements from aerospace manufacturers and electronics producers, while automation solutions represent the fastest-expanding technology segment as fabs pursue lights-out production for circuit board fabrication. Horizontal turners command premium positioning in defense contractor supply chains where long-bore silicon insulators require gravity-stable workholding.
OSHA lockout-tagout standards and EPA hazardous waste rules govern coolant handling and silica dust containment in US-based turning operations, directly influencing capital allocation toward enclosed machining centers. The EU's CE marking and RoHS substance restrictions constrain material choices for decorative items and custom parts exported into European electronics supply chains. Stakeholders must weigh regulatory compliance costs against automation payback periods when expanding precision component capacity.
Market Dynamics
Aerospace manufacturers are consolidating procurement of precision-machined silicon components for thermal management systems, compressing supplier qualification timelines and forcing turners to certify processes against stricter material traceability standards.
Growth Catalysts
- EU F-Gas Regulation:Compliance mandates are pushing fabricators toward cleaner machining chemistries, expanding the addressable market for low-emission coolant systems and closed-loop filtration equipment.
- Stuttgart-Aachen precision corridor:Geographic clustering of automotive suppliers and electronics producers in Germany's engineering belt concentrates demand for tight-tolerance silicon turned parts.
- Polycrystalline silicon blanks:Advances in high-purity feedstock availability are reducing material defect rates during high-speed machining, improving yield economics for optical component fabricators.
Market Restraints
- Polysilicon supply concentration:Downstream turners remain dependent on a narrow base of integrated polysilicon-to-wafer producers, creating input cost volatility when semiconductor fabs divert material allocation.
- Tool wear rates:Monocrystalline silicon's abrasive properties accelerate diamond insert degradation, elevating consumable costs per machined part above alternative ceramic substrates.
- REACH substance restrictions:Registration requirements for novel machining fluids extend formulation approval timelines, freezing chemistry innovation cycles for European fabricators.
Strategic Opportunities
- Defense contractor long-bore insulators:Horizontal turner manufacturers can penetrate gravity-stable workholding niches where few competitors maintain certified capacity.
- Lights-out production mandates:Automation integration for circuit board fabrication lines creates white space for turner OEMs offering predictive maintenance subscriptions tied to uptime guarantees.
- Japan's METI dual carbon goals:Energy-efficient machining center incentives align with domestic semiconductor equipment makers seeking lower-carbon supply chains.
Industry Challenges
- CNC programming specialization:Shortage of operators trained in crystal orientation compensation algorithms limits throughput scaling for shops serving aerospace thermal management programs.
- RoHS certification timelines:Decorative and custom parts exporters face extended documentation cycles when substantiating material compliance for European electronics supply chains.
- Silica dust containment capex:OSHA lockout-tagout and EPA hazardous waste compliance are redirecting capital toward enclosed machining centers rather than capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicon Turners Market |
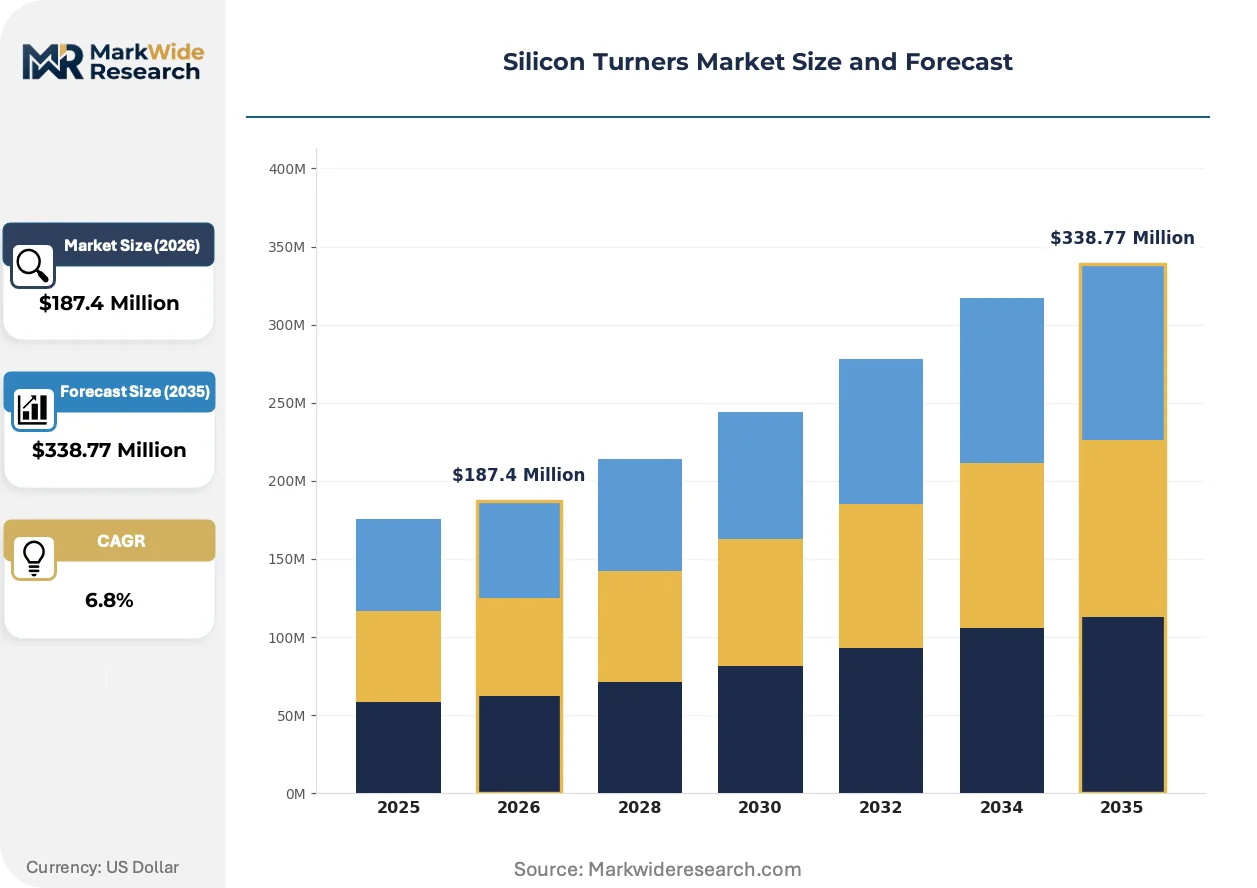
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CNC Lathes, Manual Lathes, Multi-Spindle Turners, Horizontal Turners Technology: Hybrid Technology, Electric Machines, Pneumatic Systems, Automation Solutions End User: Aerospace Manufacturers, Electronics Producers, Automotive Suppliers, Defense Contractors Application: Precision Components, Decorative Items, Circuit Board Fabrication, Custom Parts |
| Companies Covered | Dow, Wacker Chemie AG, Shin-Etsu Chemical Co. Ltd, Elkem ASA, Momentive, Evonik Industries AG, BASF SE, Kaneka Corporation, CHT Germany GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicon Turners Market Evolving Landscape
Precision machining workflows are converging with materials science and automation architecture, compressing the traditional boundaries between feedstock preparation, toolpath optimization, and post-process verification.
Hybrid diamond-coated carbide inserts are unifying the wear resistance of polycrystalline diamond with the fracture toughness of cemented carbide substrates. Aerospace thermal management suppliers are adopting these inserts at accelerating rates to machine silicon without thermal cracking. This convergence is unifying previously separate tooling supply chains into single-source procurement relationships.
The EU's F-Gas Regulation and REACH compliance framework are forcing coolant chemistry reformulation across German and French fabrication clusters. Industrial consequence includes mandatory phase-out of fluorinated greenhouse gases in conventional machining fluids. Optical component specialists in Stuttgart are responding fastest, securing early-mover certification for water-based alternatives.
Buyer consolidation among aerospace prime contractors is compressing supplier qualification cycles from 18 months to sub-12 month windows. Tier-2 fabricators are replacing discrete purchase orders with multi-year master service agreements bundling volume commitments with predictive maintenance. This pattern is most visible in Germany's precision engineering corridor, where automotive and electronics procurement teams are merging vendor pools.
Silicon Turners Market Segmentation
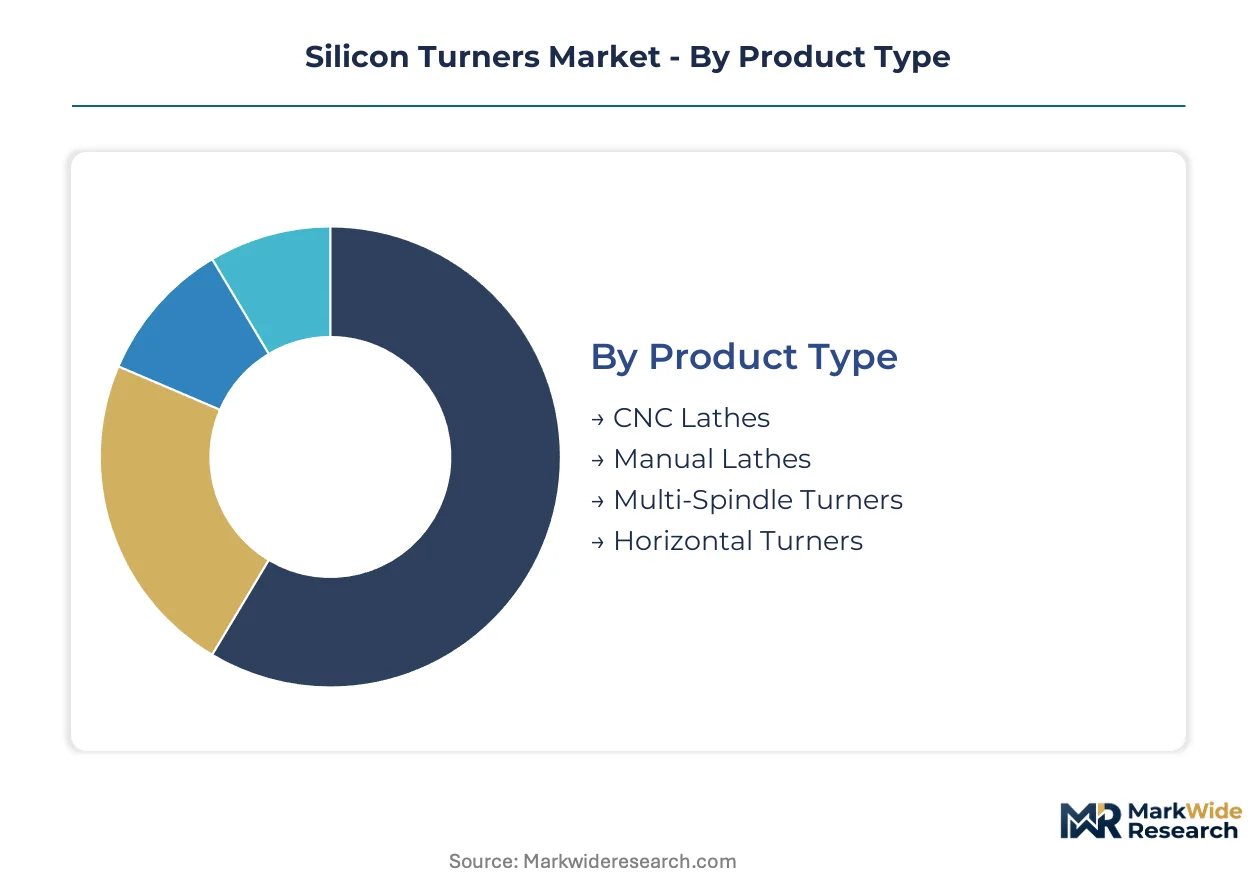
Equipment upgrade cycles and replacement timelines vary sharply across silicon turning installations. Fabricators weigh retrofit economics against full replacement when expanding precision component capacity. Segmentation reveals where capital deployment concentrates and which technology lanes attract fresh investment.
Product Type:
Replacement-cycle timing diverges across installed base vintages, with aerospace and defense procurement teams driving faster refresh rates than general fabrication shops.
- CNC Lathes:Computer-numerical control systems dominate active installed capacity through repeatability guarantees demanded by Stuttgart-area automotive suppliers and Aachen electronics producers. Aerospace manufacturers consolidating thermal management procurement specify these units for material traceability compliance.
- Horizontal Turners:Gravity-stable workholding configurations command premium positioning in defense contractor supply chains producing long-bore silicon insulators. German precision engineering clusters source these for optical component fabrication requiring sub-micron surface finishes.
- Multi-Spindle Turners:Parallel machining heads reduce cycle times for high-volume electronics producers in circuit board fabrication lines.
- Manual Lathes:Limited to prototype shops and training facilities; declining share as lights-out production mandates spread.
CNC Lathes sits at the top of the volume ranking, with Horizontal Turners climbing the fastest on defense procurement acceleration.
Technology:
Cost-tier stratification separates premium automation integrations from baseline pneumatic and electric configurations serving price-sensitive fabricators.
- Automation Solutions:Robotic workpiece handling and in-process measurement systems enable unattended operation for circuit board fabrication lines pursuing lights-out production. Japan's METI energy-efficiency incentives accelerate adoption among domestic semiconductor equipment makers.
- Hybrid Technology:Combined electric-pneumatic actuation balances precision positioning with rapid traverse speeds for optical component specialists. Stuttgart fabricators lead deployment as REACH-compliant coolant chemistry reformulation demands enclosed machining centers.
- Electric Machines:Direct-drive spindles reduce energy consumption; favored by automotive suppliers meeting Scope 3 emissions targets.
- Pneumatic Systems:Legacy installations persist in low-margin decorative item production; limited growth trajectory.
Automation Solutions holds the largest installed base, while Hybrid Technology gains share fastest among precision engineering corridors reformulating coolant chemistries.
End User:
Customer-type concentration shapes equipment specification requirements, with certified suppliers capturing multi-year master service agreements from consolidating primes.
- Aerospace Manufacturers:Thermal management system procurement drives demand for tight-tolerance silicon turned parts with full material traceability documentation. Qualification timelines compressing from eighteen months to sub-twelve months favor incumbent turners with established process certification.
- Electronics Producers:Circuit board fabrication lines require lights-out compatible turning centers with predictive maintenance integration. Germany's Stuttgart-Aachen corridor concentrates procurement through merged automotive-electronics vendor pools.
- Defense Contractors:Long-bore insulator specifications mandate horizontal turner capabilities with gravity-stable workholding; limited certified capacity creates supply bottlenecks.
- Automotive Suppliers:Precision engineering clusters around Stuttgart source silicon components for electric vehicle thermal management systems.
Aerospace Manufacturers represents the largest revenue concentration, with Electronics Producers expanding most quickly on automation integration mandates.
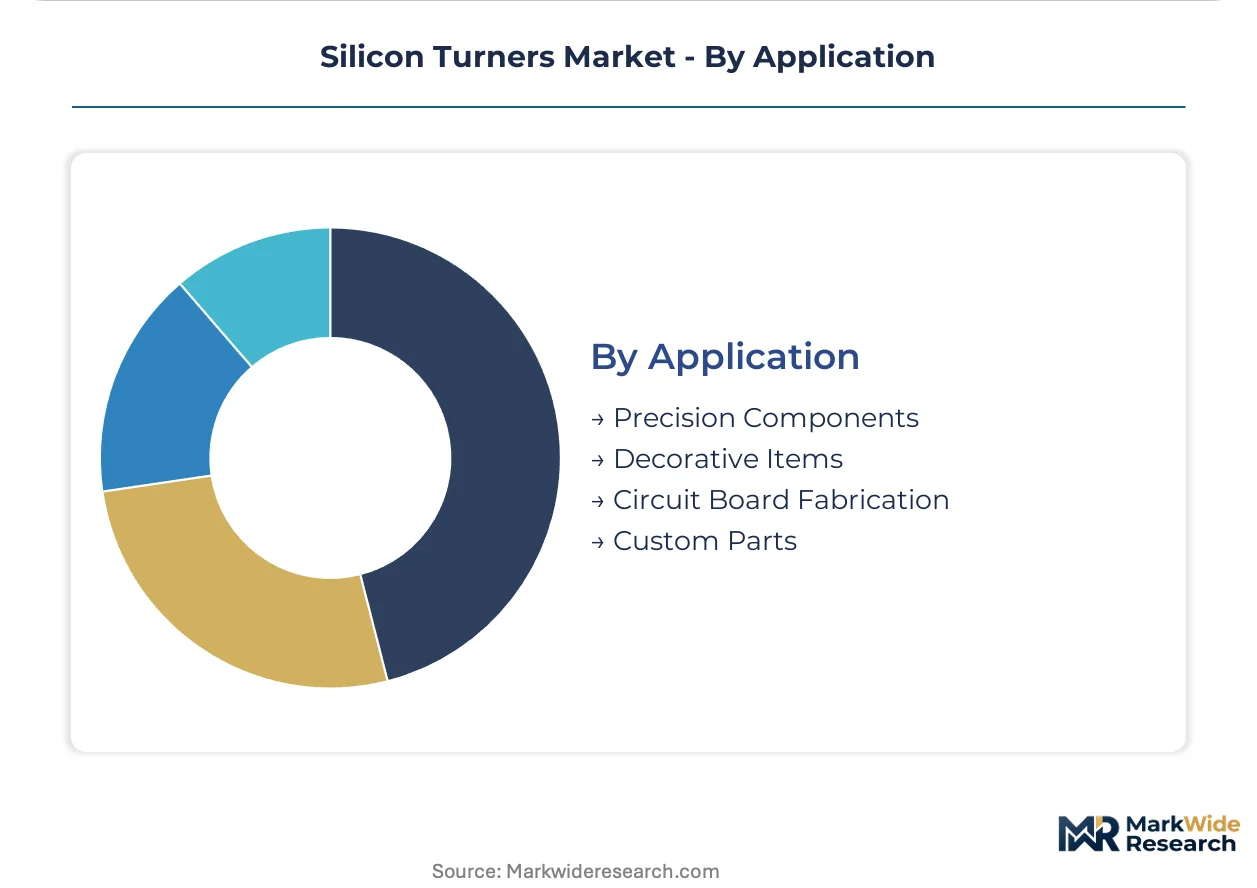
Application:
Margin structure varies across application lanes, with precision components commanding premium pricing against commoditized decorative output.
- Precision Components:Sub-micron surface finish requirements and ±2 micrometer dimensional tolerances for semiconductor and optical applications sustain premium pricing. Aerospace thermal management programs and Stuttgart-area automotive suppliers drive specification intensity.
- Circuit Board Fabrication:High-volume production of silicon substrates for electronic interconnects favors automated turning centers with predictive maintenance subscriptions. Electronics producers in Germany's engineering belt consolidate procurement through multi-year agreements.
- Custom Parts:Low-volume, high-mix output serves research institutions and prototype development; RoHS certification timelines constrain European export competitiveness.
- Decorative Items:Minimal technical specifications; price competition from alternative materials limits silicon penetration.
Precision Components captures the highest margin tier, while Circuit Board Fabrication scales fastest on lights-out production mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates precision engineering demand while the United States drives aerospace procurement consolidation, creating divergent equipment specification requirements across Atlantic supply chains.
United States
Aerospace manufacturers consolidating thermal management procurement compress supplier qualification timelines to sub-twelve months. OSHA lockout-tagout standards and EPA hazardous waste rules redirect capital toward enclosed machining centers. The defense contractor supply chain around Huntsville, Alabama and San Diego, California generates concentrated demand for long-bore silicon insulators requiring gravity-stable workholding.
Germany
Automotive suppliers and electronics producers in the Stuttgart-Aachen precision engineering corridor drive tight-tolerance silicon turned part specifications. The EU's F-Gas Regulation and REACH compliance requirements mandate cleaner machining chemistries, accelerating coolant reformulation. Stuttgart-based optical component specialists secure early-mover certification for water-based alternatives ahead of French and Italian competitors.
Japan
Domestic semiconductor equipment makers pursue lower-carbon supply chains aligned with METI dual carbon goals. Energy-efficient machining center incentives accelerate adoption of direct-drive spindle configurations. The Chubu region around Nagoya concentrates precision component fabricators serving Toyota and Denso thermal management programs.
China
Polycrystalline silicon blank availability advances reduce material defect rates during high-speed machining for optical component fabricators. MIIT industrial upgrading programs prioritize CNC localization in precision engineering. The Yangtze River Delta clusters electronics producers consolidating vendor pools for circuit board fabrication lines.
South Korea
Electronics producers mandate lights-out production compatibility for circuit board fabrication equipment procurement. MFDS industrial safety standards govern silica dust containment in precision machining operations. The Seoul Capital Area concentrates automation-integrated turning center demand from Samsung and SK Hynix supply chains.
Silicon Turners Market Competitive Landscape
Top-tier vendors anchor integrated polysilicon-to-wafer capabilities, while mid-tier fabricators compete on specialized crystal orientation control and regional logistics proximity. The vendor base stratifies across materials science conglomerates, precision chemical specialists, and dedicated silicon processors. Three archetypes dominate: upstream feedstock controllers, downstream machining technology licensors, and hybrid material-equipment integrators. Competitive moves concentrate on backward integration into high-purity blank supply and predictive maintenance subscription bundling.
Among materials science conglomerates, Dow and Wacker Chemie AG exemplify upstream feedstock control archetypes, while Shin-Etsu Chemical Co. Ltd occupies a position within the specialized crystal orientation tier. These three entities represent the dominant competitive anchors against which downstream turners benchmark material sourcing strategies and process certification standards.
| Leading Market Players |
|---|
| Dow |
| Wacker Chemie AG |
| Shin-Etsu Chemical Co. Ltd |
| Elkem ASA |
| Momentive |
| Evonik Industries AG |
| BASF SE |
| Kaneka Corporation |
| CHT Germany GmbH |
| Others |
Value Network & Pricing Analysis
Captive integration into high-purity silicon blank supply anchors both procurement security and pricing power for downstream turners, with Wacker Chemie AG and Shin-Etsu Chemical Co. Ltd leveraging upstream control to stabilize input costs while tier-2 fabricators absorb volatility from semiconductor fab diversion.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for polycrystalline silicon blanks, compressing margins for European fabricators dependent on German and Japanese feedstock. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-certified suppliers from automotive-tier producers and decorative-item commoditizers. Cost compression in the economy tier intensifies because Chinese blank availability reduces material defect rates. Defense contractors exhibit least price sensitivity due to gravity-stable workholding requirements, while decorative-item producers face maximum substitution pressure from alternative ceramics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from consolidating aerospace primes, bypassing traditional distributor markups for thermal management procurement. Geographic supply concentrates in Germany, Japan, and China, with polysilicon-to-wafer capabilities anchoring regional clusters. Downstream turners draw from high-purity blanks, hybrid diamond-coated carbide inserts, and REACH-compliant coolant formulations. Single-source vulnerability persists around integrated polysilicon producers when semiconductor fabs redirect material allocation. Distribution runs through certified supplier networks for defense and aerospace tiers, with spot-market flexibility serving prototype shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion hinges on predictive maintenance subscription bundling and premium-tier certification investments that separate qualified suppliers from commoditized competitors.
For Market Incumbents: Deepen backward integration into high-purity blank supply to offset semiconductor fab diversion risk, while securing early-mover REACH certification for water-based coolant alternatives ahead of French and Italian competitors. Lock in multi-year master service agreements with Stuttgart-Aachen automotive suppliers before qualification timelines compress further. Priority levers include crystal orientation control R&D and enclosed machining center capacity adds. For New Entrants and Emerging Players: Launch via predictive maintenance subscription models targeting mid-tier electronics producers in South Korea's Seoul Capital Area, where lights-out production mandates outpace local automation integration capabilities. White-space targets include defense contractor long-bore insulator niches with limited certified horizontal turner capacity, and Japan's METI-incentivized energy-efficient machining centers serving Toyota thermal management programs. For Investors and Strategic Acquirers: Roll-up economics work for regional precision fabricators with captive coolant reformulation expertise because EU F-Gas Regulation compliance creates stranded asset risk for uncertified competitors. Long-term viability favors targets with aerospace process certification and Stuttgart corridor logistics proximity. The signal to watch is qualification timeline compression below twelve months, which accelerates incumbent switching-cost advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon Supply | Wacker Chemie AG's captive blank production insulates downstream turners from semiconductor fab diversion. |
| Predictive Maintenance Subscription Launch | CNC lathe OEMs bundle uptime guarantees with multi-year electronics producer agreements in Germany. |
| REACH-Compliant Coolant Reformulation | Stuttgart optical specialists secure first-mover certification for water-based alternatives ahead of competitors. |
| Horizontal Turner Capacity Expansion | Defense contractor long-bore insulator demand outstrips certified gravity-stable workholding supply. |
| Energy-Efficient Machining Center Deployment | Japan's METI incentives accelerate direct-drive spindle adoption for lower-carbon semiconductor equipment chains. |
Research Methodology
Coverage spans Germany, Japan, the United States, China, and South Korea, with primary inputs from each combining structured interviews with plant engineers at precision fabrication facilities, procurement leads at aerospace and electronics OEMs, aftermarket service heads, and technical R&D directors at coolant and tooling suppliers. Secondary validation draws from SEC 10-K filings, EU ECHA REACH registration databases, Japan METI industrial policy disclosures, and customs trade data for polysilicon and precision machinery. Bottom-up equipment installation counts and top-down end-use demand estimates triangulate market sizing.
Granularity-level modeling disaggregates volume and value across product type, technology tier, end-user industry, and application, with additional dimensioning by regional regulatory cluster and certification status. CAGRs derive from fitted growth curves against historical replacement cycles and projected procurement consolidation patterns. Industry-specific forecast inputs include aerospace thermal management program ramp schedules, EU F-Gas Regulation phase-out timelines, and Japan METI dual carbon incentive uptake rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden polysilicon supply disruption or accelerated REACH substance restriction expansion. Periodic stress-testing of base assumptions is recommended, particularly around semiconductor fab material diversion scenarios and defense procurement budget volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Manufacturing
Malaysia and Thailand Precession Cleaning for Electronic Market
Semiconductor Manufacturing
Solder Paste Market
Semiconductor Manufacturing
Semiconductor and Electronic Parts Manufacturing Market
Semiconductor Manufacturing
PCB Photoresist Market
Semiconductor Manufacturing
Middle East and Africa Cell Manufacturing Market
Semiconductor Manufacturing
Global Overall EUV Lithography Market
Semiconductor Manufacturing
Stencil Lithography Market
Semiconductor Manufacturing
Photoresist Stripper Market
Semiconductor Manufacturing
Global Wafer Cutting Fluids Market
Semiconductor Manufacturing
Battery Manufacturing Machines Market
Semiconductor Manufacturing
High Purity Process Systems for Semiconductor Market
Semiconductor Manufacturing
United States Photoresist and Photoresist Ancillaries Market
Semiconductor Manufacturing
Medical Component Manufacturing Market
Semiconductor Manufacturing
Electronic Manufacturing Services (EMS) Market
Semiconductor Manufacturing
China Electronic Design Automation (EDA) Tools Market
Semiconductor Manufacturing
Thin Film Semiconductor Deposition Market