
 Nanoimprint Lithography System Market | 2026-2036
Nanoimprint Lithography System Market Size, Share, and Industry Trends Forecast 2026-2036
Nanoimprint Lithography System Market Foresight
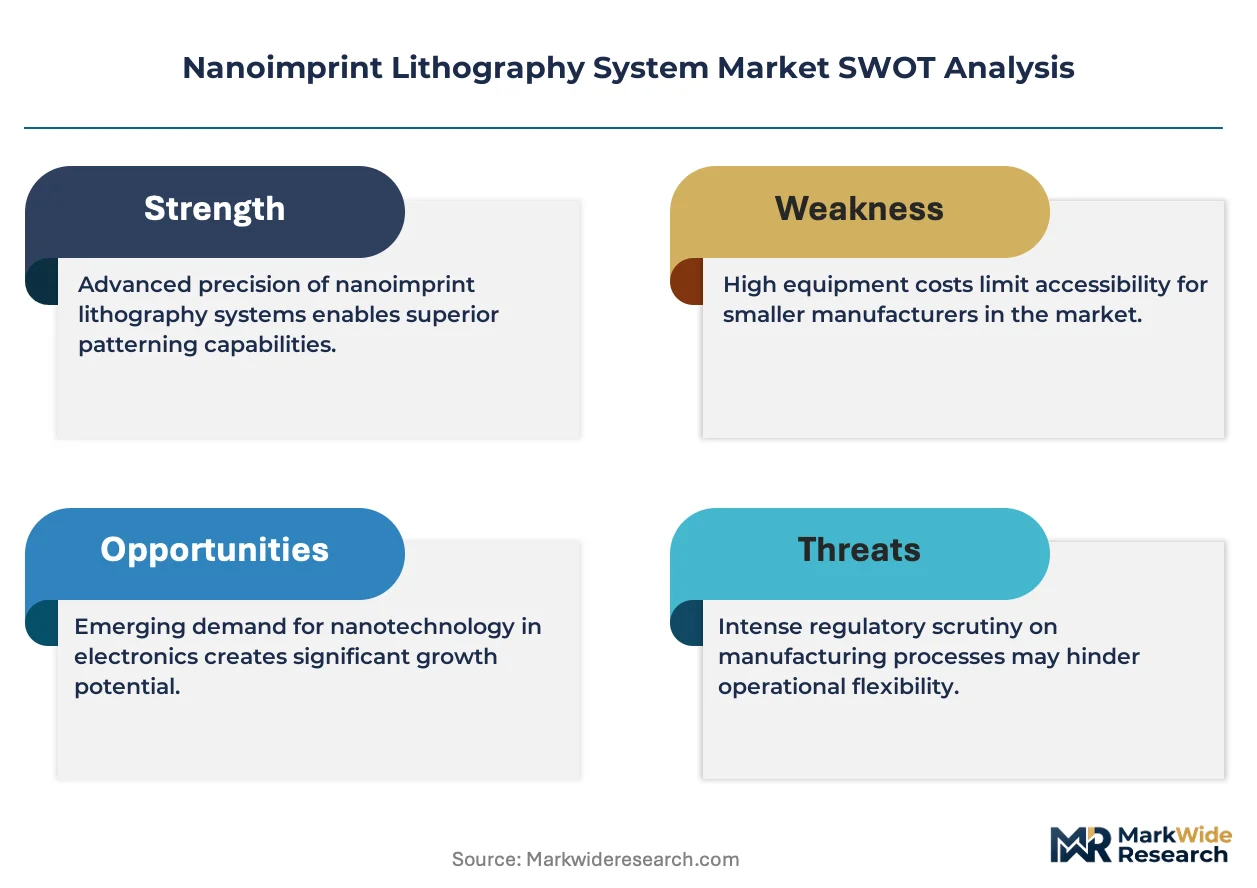
Equipment leasing and pay-per-use financing is tilting competitive access toward mid-tier semiconductor manufacturers previously locked out of lithography capital cycles. Canon Inc. leverages its established optics heritage to anchor mask-based system deployments across Asian foundries. EV Group (EVG) sustains R&D intensity in step-and-flash architectures that compete for advanced packaging nodes. SUSS MicroTec SE dominates European research institution procurement through specialized service contracts.
A nanoimprint lithography system mechanically presses a patterned mold into a resist-coated substrate, achieving resolution below 10nm through physical deformation rather than optical diffraction, with throughput parameters measured in wafers per hour and overlay accuracy in single-digit nanometers. Mask-based systems occupy the highest margin tier serving logic and memory fabs requiring sub-7nm fidelity. Roll-to-roll configurations extend into photonics and flexible sensor substrates where substrate format flexibility outweighs absolute resolution demands. Soft mold approaches lead academic lab adoption due to lower barrier-to-entry tooling costs.
Japan's METI subsidizes domestic lithography ecosystem development, while South Korea's MFDS oversees medical device qualification pathways that shape biomedicine application standards. REACH compliance in Europe restricts perfluorinated compound usage in resist formulations, forcing reformulation investments. Stakeholders must monitor which regulatory jurisdiction certifies nanoimprint equivalence to optical lithography for automotive-grade semiconductor reliability standards.
Market Dynamics
Extreme ultraviolet lithography cost escalation and throughput ceilings are forcing logic and memory fabs to diversify patterning strategies, accelerating nanoimprint adoption for sub-10nm layers previously reserved for optical systems.
Growth Catalysts
- Sub-7nm Node Demand:Logic manufacturers require alternative patterning for critical layers as EUV multipatterning costs escalate. Nanoimprint delivers single-exposure resolution at reduced process complexity.
- METI Lithography Resilience Programs:Japan's Ministry of Economy, Trade and Industry directs public funding toward domestic nanoimprint commercialization, accelerating equipment qualification timelines at domestic foundries.
- Advanced Packaging Proliferation:High-density interconnect requirements for chiplets and 3D stacking create addressable demand for step-and-flash systems serving redistribution layer patterning.
Market Restraints
- Master Template Supply Concentration:Electron-beam lithography systems for mold fabrication concentrate among Japanese and European equipment suppliers, creating single-source vulnerability for high-resolution master production.
- Perfluorinated Compound Restrictions:ECHA REACH compliance mandates reformulation of fluorinated release agents and resists, forcing multi-year qualification cycles for replacement chemistries.
- Optical Lithography Substitution:Continued EUV throughput improvements and high-NA system deployments threaten nanoimprint's cost advantage at intermediate nodes between 7nm and 14nm.
Strategic Opportunities
- Photonics and Optical Interconnects:Silicon photonics foundries require sub-100nm grating structures where nanoimprint's pattern fidelity exceeds optical limits at lower capital intensity than EUV.
- Biomedical Microfluidics:MFDS qualification pathways for nanoimprint-patterned diagnostic substrates open regulated revenue streams distinct from semiconductor capital cycles.
- Equipment-as-a-Service Models:Pay-per-wafer financing structures lower barrier-to-entry for mid-tier foundries and research consortia previously excluded from lithography ownership.
Industry Challenges
- Process Integration Complexity:Nanoimprint introduction requires reconfiguration of established cleanroom workflows, resist coating tracks, and metrology protocols optimized for optical exposure systems.
- Defect Inspection Standardization:Absence of unified protocols for mold defect classification and wafer-level yield attribution complicates customer acceptance criteria and equipment vendor liability frameworks.
- Cross-Contamination Protocols:Physical contact between mold and substrate introduces particle management requirements foreign to non-contact lithography, demanding modified facility infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanoimprint Lithography System Market |
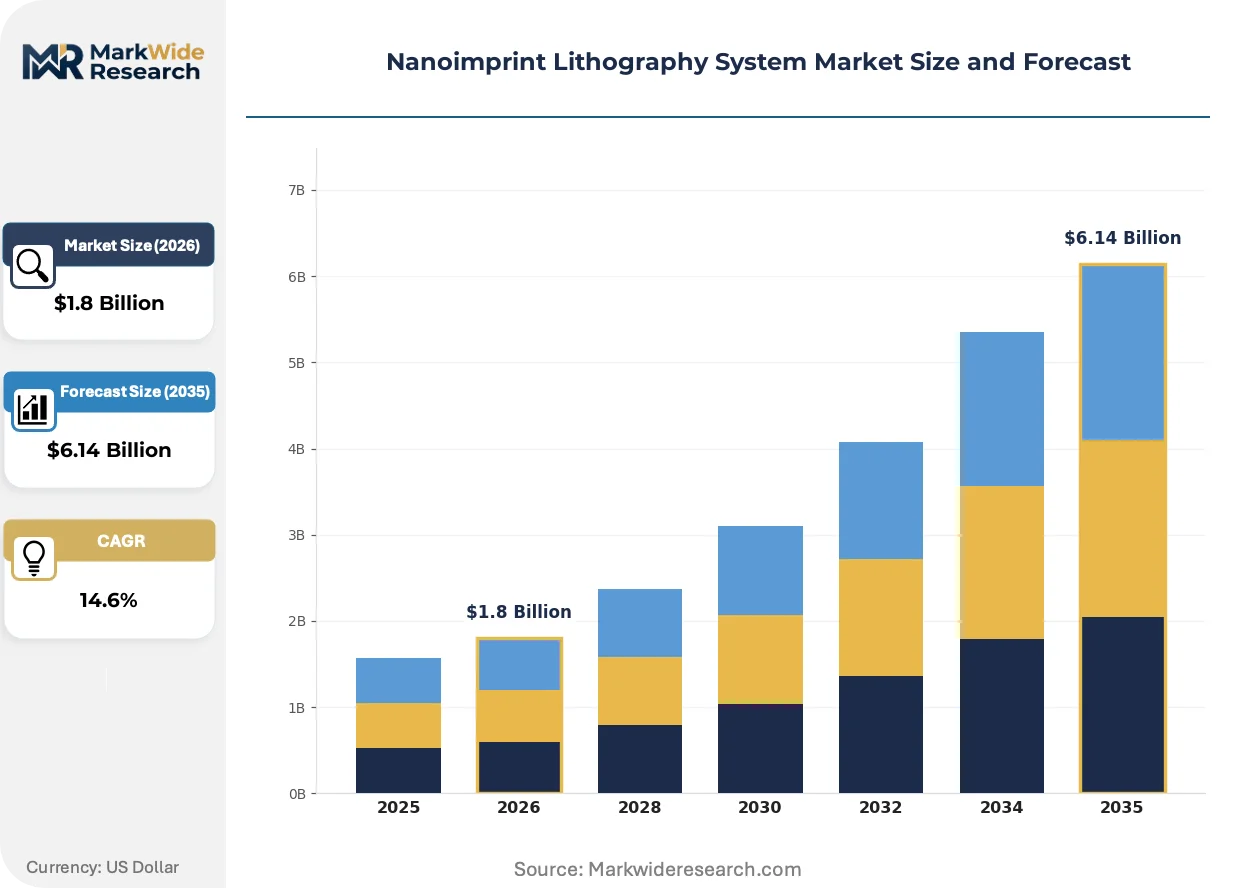
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mask-based, Roll-to-Roll, Step and Flash, Soft Mold Application: Microelectronics, Photonics, Sensors, Biomedicine End User: Semiconductor Manufacturers, Research Institutions, Medical Device Firms, Academic Labs Delivery Mode: On-Premises, Cloud-Based, Hybrid, License-Based |
| Companies Covered | SUSS MicroTec SE, Obducat AB, EV Group (EVG), Stensborg A/S, AMO GmbH, Canon Inc., NIL TECHNOLOGY, Germanlitho, Nanonex, Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanoimprint Lithography System Market Shifts & Advancements
Patterning economics are restructuring as physical-contact lithography competes for layers previously dominated by optical diffraction, with equipment architecture and service models adapting to divergent end-use requirements.
Step-and-flash imprint lithography is hybridizing with directed self-assembly chemistries to extend resolution below 5nm for next-generation memory arrays. SK Hynix and Micron Technology pilot lines are validating combined process flows for 3D NAND string stacking. The convergence compresses effective pitch multiplication without proportional capital escalation.
REACH restrictions on perfluorinated substances are forcing resist and release agent reformulations across European-qualified supply chains. ECHA substance evaluation timelines extend qualification windows for replacement chemistries by 18-24 months. German and French research consortia are accelerating bio-based alternative development to preempt regulatory discontinuities.
Mid-tier foundries and academic institutions are consolidating purchasing power through multi-party equipment leases and shared service contracts. Canon and EV Group have established regional service hubs in Taiwan and South Korea to support distributed ownership models. The shift concentrates aftermarket revenue with original equipment manufacturers while fragmenting upfront capital deployment.
Nanoimprint Lithography System Market Segmentation
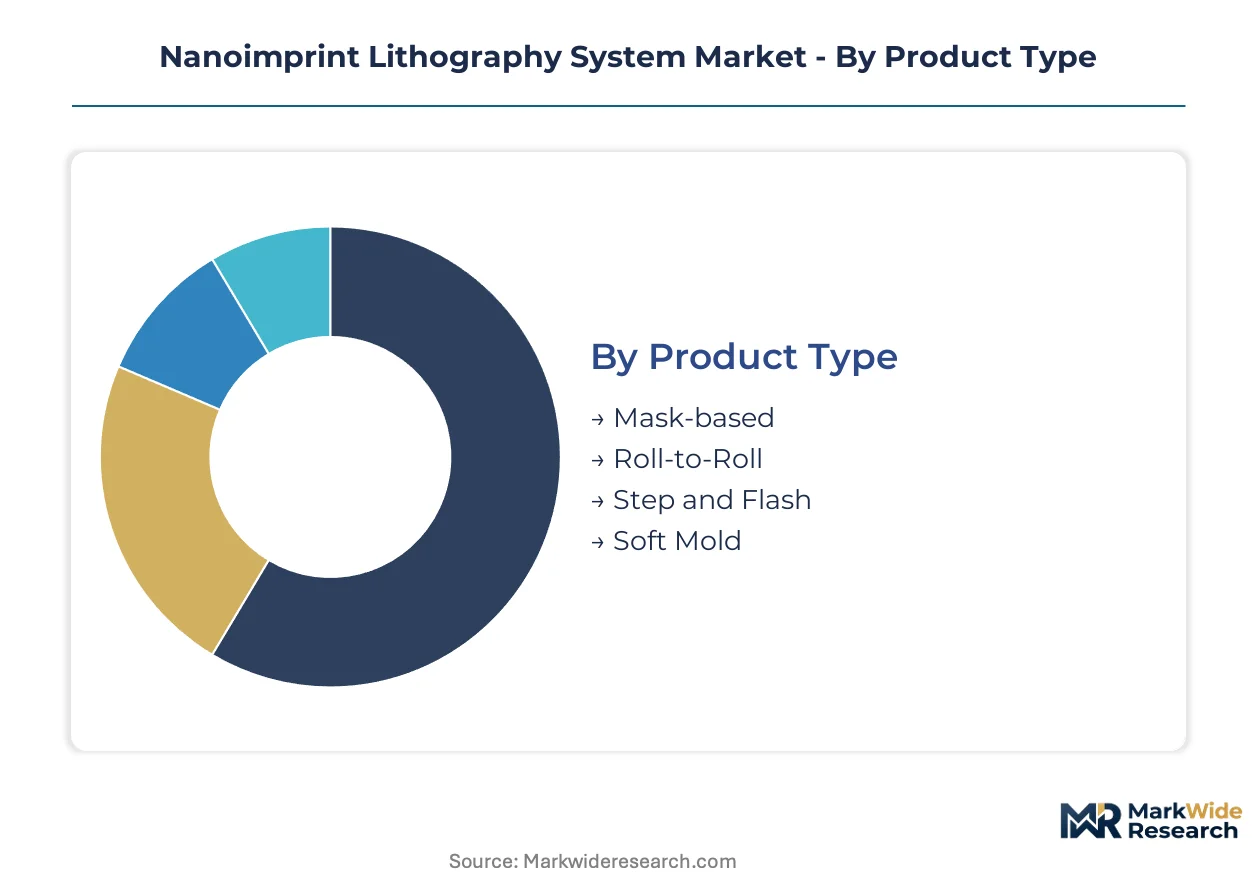
Segmentation in nanoimprint lithography reveals how equipment architecture, application requirements, and procurement models diverge across semiconductor fabrication, research, and emerging biomedical domains. Each dimension carries distinct margin profiles and qualification barriers that shape vendor strategy and customer access patterns.
Product Type:
Cost tier stratification separates mask-based systems commanding premium pricing from roll-to-roll configurations serving volume-flexible substrates.
- Mask-based:These systems mechanically press rigid quartz molds into resist-coated wafers, achieving sub-7nm resolution through physical deformation. Logic and memory fabs in Taiwan and South Korea concentrate procurement here as EUV multipatterning costs escalate for critical layers.
- Step and Flash:UV-curable resist dispensing between mold and substrate enables high-throughput patterning for advanced packaging redistribution layers. SK Hynix and Micron Technology pilot lines validate combined flows with directed self-assembly for 3D NAND string stacking.
- Roll-to-Roll:Continuous substrate feeding suits flexible photonics and sensor substrates where format flexibility outweighs absolute resolution.
- Soft Mold:Elastomeric PDMS molds lower barrier-to-entry tooling costs, anchoring academic lab adoption across European research consortia.
Mask-based systems command the established base. The steepest expansion runs through step-and-flash architectures.
Application:
Application maturity separates semiconductor-proven microelectronics from biomedicine's emerging regulatory pathways.
- Microelectronics:Logic and memory fabrication drives absolute equipment volume, with sub-10nm patterning requirements accelerating as EUV throughput ceilings force diversification. Taiwan's foundry clusters anchor demand concentration.
- Photonics:Silicon photonics foundries require sub-100nm grating structures where nanoimprint fidelity exceeds optical limits. German and French research consortia accelerate deployment for optical interconnects.
- Sensors:Flexible pressure and gas sensing substrates leverage roll-to-roll configurations for cost-scalable production.
- Biomedicine:MFDS qualification pathways in South Korea and FDA-equivalent frameworks elsewhere shape diagnostic substrate standards, opening regulated revenue streams distinct from semiconductor capital cycles.
Microelectronics absorbs the dominant equipment share. Biomedicine is climbing the fastest as regulatory pathways mature.
End User:
Customer type determines capital deployment scale, from billion-dollar fab budgets to grant-funded academic installations.
- Semiconductor Manufacturers:Logic and memory fabs in East Asia drive mask-based system procurement with qualification timelines measured in quarters, not years.
- Research Institutions:European consortia dominate specialized service contracts, with SUSS MicroTec SE anchoring regional procurement through dedicated support infrastructure.
- Academic Labs:Soft mold approaches concentrate here due to constrained capital budgets and exploratory patterning requirements.
- Medical Device Firms:South Korea's MFDS and Japan's PMDA pathways shape qualification investments for diagnostic substrate commercialization.
Semiconductor manufacturers anchor absolute demand. Medical device firms are gaining share fastest as regulatory clarity emerges.
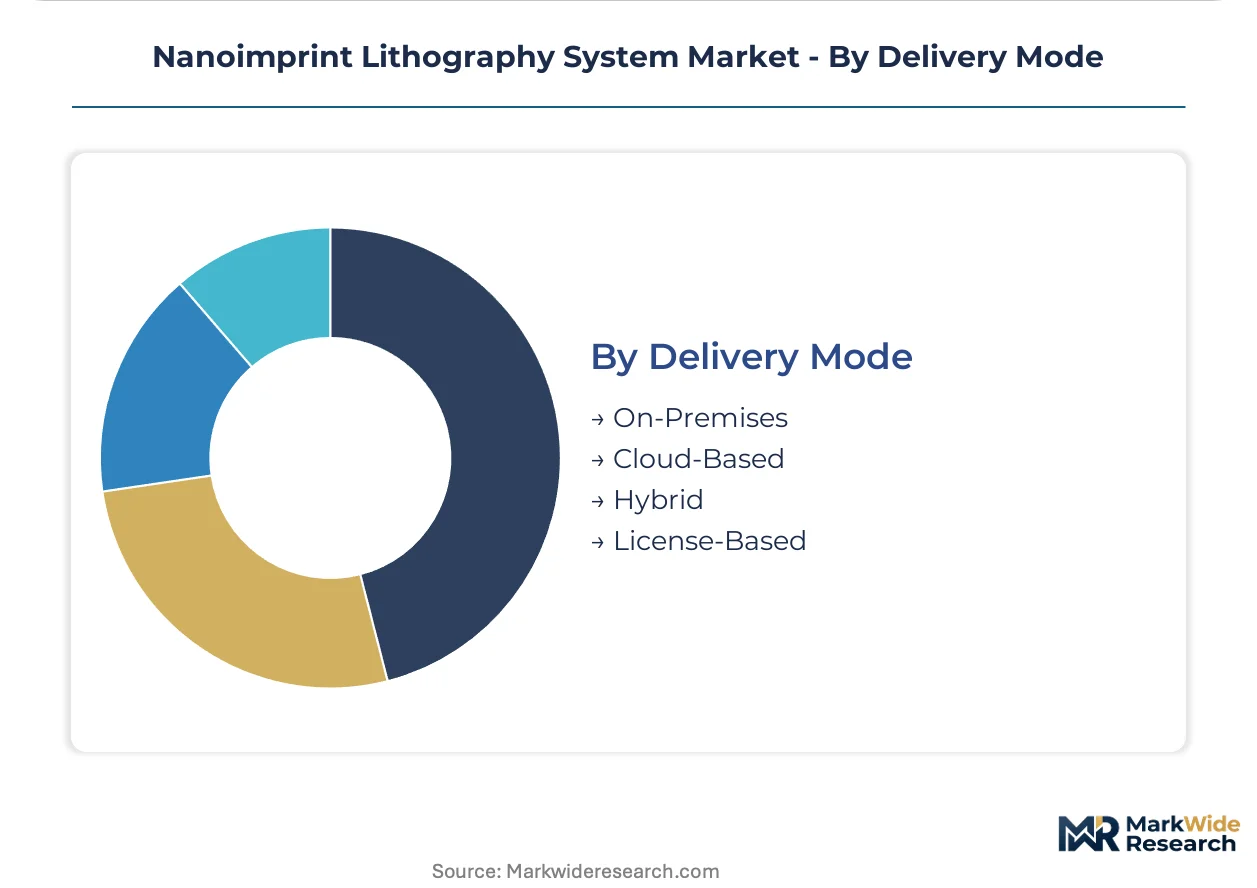
Delivery Mode:
Procurement structure separates upfront ownership from distributed access models reshaping competitive entry barriers.
- On-Premises:Traditional capital purchase dominates high-volume fabs requiring dedicated throughput and proprietary process control.
- Hybrid:Combined ownership and service contracts allow mid-tier foundries to access advanced tooling without full capital commitment.
- License-Based:Software and process IP licensing enables equipment manufacturers to capture recurring revenue beyond hardware margins.
- Cloud-Based:Remote process monitoring and predictive maintenance subscriptions concentrate among distributed research consortia and smaller fabrication facilities.
On-premises deployment commands the established base. Hybrid arrangements are expanding most quickly as mid-tier foundries consolidate purchasing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI's lithography resilience programs redirect public capital toward domestic nanoimprint commercialization, accelerating equipment qualification timelines at Japanese foundries. Taiwan and South Korea concentrate mask-based system procurement as EUV multipatterning costs escalate for sub-7nm layers.
Taiwan
Logic foundries drive mask-based system deployment as EUV throughput ceilings force patterning diversification for critical layers. The National Development Council coordinates semiconductor supply chain security investments alongside METI-aligned technology partnerships. Hsinchu Science Park anchors equipment qualification activity for sub-10nm production nodes.
South Korea
Memory manufacturers pilot step-and-flash hybridization with directed self-assembly for 3D NAND string stacking applications. MFDS oversees qualification pathways for nanoimprint-patterned diagnostic substrates, opening regulated biomedical revenue streams. Seoul Capital Area foundries concentrate capital expenditure for advanced packaging redistribution layer patterning.
Japan
Domestic equipment vendors leverage METI-funded lithography ecosystem development to accelerate mask-based system commercialization timelines. PMDA and METI coordinate on medical device substrate standards that shape biomedicine application specifications. Kyushu and Tohoku manufacturing clusters integrate nanoimprint tooling for photonics and sensor production.
Germany
ECHA REACH compliance mandates perfluorinated compound reformulation across resist and release agent supply chains, extending qualification windows for replacement chemistries. German research consortia accelerate bio-based alternative development to preempt regulatory discontinuities. Dresden and Munich clusters anchor silicon photonics foundry deployment for sub-100nm grating structures.
United States
Silicon photonics foundries require nanoimprint fidelity for optical interconnect applications where capital intensity constraints limit EUV adoption. FDA-equivalent frameworks shape diagnostic substrate qualification investments for biomedical microfluidics commercialization. Greater Boston and Pacific Northwest research hubs concentrate soft mold tooling adoption for exploratory patterning requirements.
Nanoimprint Lithography System Market Competitive Landscape
On the supply side, the industry is bifurcated between precision optics heritage players and specialized lithography equipment fabricators serving divergent end-use requirements. The vendor base separates into three strategic archetypes: mask-based system specialists commanding premium pricing for logic and memory fabs, step-and-flash architects targeting advanced packaging nodes, and roll-to-roll configurators addressing flexible substrate formats. Dominant competitive moves include geographic service hub expansion and multi-party equipment lease structuring to capture aftermarket revenue while fragmenting upfront capital deployment.
Among European equipment fabricators, SUSS MicroTec SE and AMO GmbH occupy positions within the research institution service tier, while EV Group exemplifies the step-and-flash architecture specialist archetype competing for advanced packaging applications. Canon Inc. represents the precision optics heritage anchor, leveraging established technical capabilities to secure mask-based system deployments across Asian foundry clusters. These three companies collectively illustrate how vendor strategy diverges across equipment architecture, geographic focus, and customer segment specialization.
| Leading Market Players |
|---|
| SUSS MicroTec SE |
| Obducat AB |
| EV Group (EVG) |
| Stensborg A/S |
| AMO GmbH |
| Canon Inc. |
| NIL TECHNOLOGY |
| Germanlitho |
| Nanonex, Corp. |
| Others |
Supply & Pricing Matrix
Single-source dependency on Japanese and European electron-beam lithography systems for master template fabrication determines both pricing tier spreads and supply chain shape, compressing margins for mask-based system vendors while amplifying procurement leverage for foundries with qualification timelines measured in quarters.
Pricing Analysis
Certification level (ISO/CE/FDA-grade) creates the primary spread between premium mask-based systems and economy-tier soft mold configurations. Three-tier pricing structure across premium, standard, and economy levels reflects equipment architecture complexity, with mask-based deployments bundling multi-year service contracts. Cost compression in the standard tier is intensifying because mid-tier foundries consolidate purchasing power through multi-party leases. Research institutions exhibit highest price sensitivity due to grant-funded capital constraints, while logic fabs in Taiwan and South Korea demonstrate lowest sensitivity given EUV multipatterning cost escalation.
Supply Chain Analysis
Tariff exposure between Japan and the United States dominates supply chain risk calculations for equipment vendors serving dual-region qualification pathways. Master template fabrication concentrates in Japan and Germany, while resist formulation draws from specialized chemical suppliers in France and the Netherlands. Single-source vulnerability in electron-beam lithography systems for mold production creates chokepoint exposure. Distribution runs through regional service hubs in Taiwan and South Korea that Canon and EV Group have established to support hybrid ownership models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among East Asian foundry clusters as equipment procurement consolidates through multi-party lease structures, fragmenting upfront capital deployment while capturing aftermarket revenue with original equipment manufacturers.
For Market Incumbents: Entrench mask-based system deployments through backward integration into master template fabrication capabilities, preempting single-source vulnerability in electron-beam lithography supply. Deepen service contract penetration with regional hub expansion in Hsinchu and Seoul Capital Area clusters. Canon and EV Group must defend against step-and-flash substitution in advanced packaging nodes by accelerating directed self-assembly hybridization timelines.
For New Entrants and Emerging Players: Establish a beachhead in biomedical microfluidics applications where MFDS and FDA-equivalent qualification pathways create regulatory moats distinct from semiconductor capital cycles. Target soft mold tooling for European research consortia constrained by grant-funded budgets. A pay-per-wafer financing go-to-market angle lowers barrier-to-entry for mid-tier foundries previously excluded from lithography ownership.
For Investors and Strategic Acquirers: The market sits at a technology-validation phase that favors equipment-as-a-service archetypes with recurring revenue visibility. Long-term viability over a 5-10 year window rests on nanoimprint achieving equivalence certification to optical lithography for automotive-grade semiconductor reliability standards. Acquisition targets should demonstrate regional service hub infrastructure or specialized resist formulation capabilities. The signal to watch is ECHA REACH substance evaluation timelines for perfluorinated compound replacements, which could extend qualification windows by 18-24 months and reshape competitive positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Regional Service Hub Expansion | Canon and EV Group's Taiwan and South Korea hubs capture aftermarket revenue from distributed ownership models. |
| Directed Self-Assembly Hybridization | SK Hynix and Micron pilot lines validate combined process flows that compress pitch multiplication without proportional capital escalation. |
| Perfluorinated Compound Reformulation | German and French research consortia accelerate bio-based alternatives to preempt ECHA REACH regulatory discontinuities. |
| Equipment-as-a-Service Deployment | Pay-per-wafer financing structures fragment upfront capital deployment while concentrating recurring revenue with equipment vendors. |
| Biomedical Qualification Pathway Investment | MFDS and PMDA coordination on diagnostic substrate standards opens regulated revenue streams distinct from semiconductor cycles. |
Research Methodology
Initial hypotheses were tested against primary input from semiconductor manufacturing executives, equipment procurement leads at foundries, resist formulation chemists, and regional service operations managers, and refined through secondary validation against SEC equipment vendor filings, METI subsidy program disclosures, ECHA substance evaluation databases, and foundry capital expenditure announcements. Bottom-up equipment shipment tracking and top-down fab capacity modeling were triangulated to reconcile volume estimates.
Demand-supply balance dynamics across the analysis window were modeled through segmentation by equipment architecture, application maturity, and procurement structure, with CAGRs derived from equipment shipment trajectories and foundry capital intensity ratios. Industry-specific forecast inputs included EUV multipatterning cost escalation curves and regulatory qualification timeline assumptions for perfluorinated compound replacements.
Stress conditions across electron-beam lithography system availability, REACH substance evaluation delays, and EUV throughput improvements were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding equipment qualification timelines and foundry capital deployment patterns. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Thin Film Deposition Equipment Market
Semiconductor Equipment
Semiconductor Laser Equipment Market
Semiconductor Equipment
Laser Annealing System Market
Semiconductor Equipment
Europe Semiconductor Etch Equipment Market
Semiconductor Equipment
Slide Processing System Market
Semiconductor Equipment
Sample Preparation Equipment Market
Semiconductor Equipment
Thin Wafer Processing and Dicing Equipment Market
Semiconductor Equipment
Semiconductor POD Cleaner Market
Semiconductor Equipment
Die Attach Equipment Market
Semiconductor Equipment
Dicing Equipment Market
Semiconductor Equipment
Global Capacitor Winding Machines Market
Semiconductor Equipment
I-Line Lithography Market
Semiconductor Equipment
Automatic Laser PCB Depaneling Machines Market
Semiconductor Equipment
Semiconductor Lithography Equipment Market
Semiconductor Equipment
Lithography Systems Market
Semiconductor Equipment
Photoresist for Semiconductor Market