
 Silicon Wafer Reclaim Market | 2026-2036
Silicon Wafer Reclaim Market Size, Share, and Industry Trends Forecast 2026-2036
Silicon Wafer Reclaim Market Analysis
Wafer reclaim services revenue is rewriting margin allocation across the silicon value chain. Nano Silicon Inc leverages in-house chemical mechanical polishing capabilities to control substrate recovery costs. Pure Wafer PLC anchors European supply through its UK-based reclaim facilities. Phoenix Silicon International Corporation specializes in high-volume processing for memory chip foundries.
Silicon wafer reclaim involves recovering used semiconductor substrates through stripping, polishing, and cleaning to restore surface flatness within sub-micron tolerances for non-critical applications. The process extends wafer lifecycle from single-use disposal to multiple reclaim cycles, reducing virgin polysilicon consumption in test and dummy wafer programs. Polished wafers dominate volume throughput due to mature CMP process economics and broad compatibility across node generations. Prime grade reclaim commands premium positioning as advanced packaging and MEMS applications tolerate tighter specifications. Chemical mechanical polishing leads processing method adoption where surface planarity requirements exceed plasma etching capabilities.
EPA hazardous waste rules in the United States and REACH chemical restrictions in Europe elevate compliance costs for reclaim chemistry disposal and recovery. China's MEE enforces wastewater discharge limits that favor closed-loop reclaim operations over open-loop virgin wafer production. Taiwan's central environmental regulator imposes hazardous substance tracking on cross-border wafer movements. Stakeholders must monitor regulatory divergence between jurisdictions as carbon border adjustments reshape substrate sourcing economics.
Market Dynamics
Semiconductor foundries are consolidating wafer reclaim procurement around captive chemical mechanical polishing capabilities to offset virgin silicon price volatility and meet Taiwan EPA hazardous substance tracking mandates.
Growth Catalysts
- MEE Wastewater Limits:China's Ministry of Ecology and Environment enforces discharge caps that elevate closed-loop reclaim economics above virgin wafer production for memory fabrication facilities.
- Test Wafer Demand:Advanced packaging yield validation programs in Taiwan's foundry cluster multiply reclaim cycles per substrate through multi-project wafer runs.
- Dual Carbon Goals:Beijing's carbon intensity targets pressure semiconductor manufacturers to document polysilicon consumption reductions via reclaim adoption.
Market Restraints
- Input Concentration:Virgin polysilicon supply from Xinjiang and Inner Mongolia concentrates pricing power with six major metallurgical-grade silicon producers.
- Technical Ceiling:Sub-micron surface flatness degradation limits reclaim cycles to 3-5 iterations before edge-chipping renders substrates unusable for 300mm applications.
- REACH Chemical Friction:ECHA registration requirements for reclaim chemistry imports add 18-24 month compliance timelines for European reclaim service expansion.
Strategic Opportunities
- MEMS Sensor Applications:Automotive pressure and inertial sensor fabs tolerate relaxed surface specifications, opening prime-grade reclaim penetration in Bosch and Denso supply chains.
- India PLI Scheme:Production-linked incentives for semiconductor fabrication attract reclaim service localization to Gujarat and Karnataka greenfield sites.
- Photovoltaic Feedstock Bridge:Downgraded reclaim wafers supply solar ingot pulling operations, creating arbitrage between semiconductor and energy silicon value chains.
Industry Challenges
- CMP Technician Scarcity:Chemical mechanical polishing process engineers command 40% salary premiums in Hsinchu and Yongin, constraining reclaim facility expansion timelines.
- Cross-Border Waste Classification:Taiwan's central environmental regulator and South Korea's Ministry of Environment apply divergent hazardous waste codes to spent reclaim chemistry, complicating multi-country service networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicon Wafer Reclaim Market |
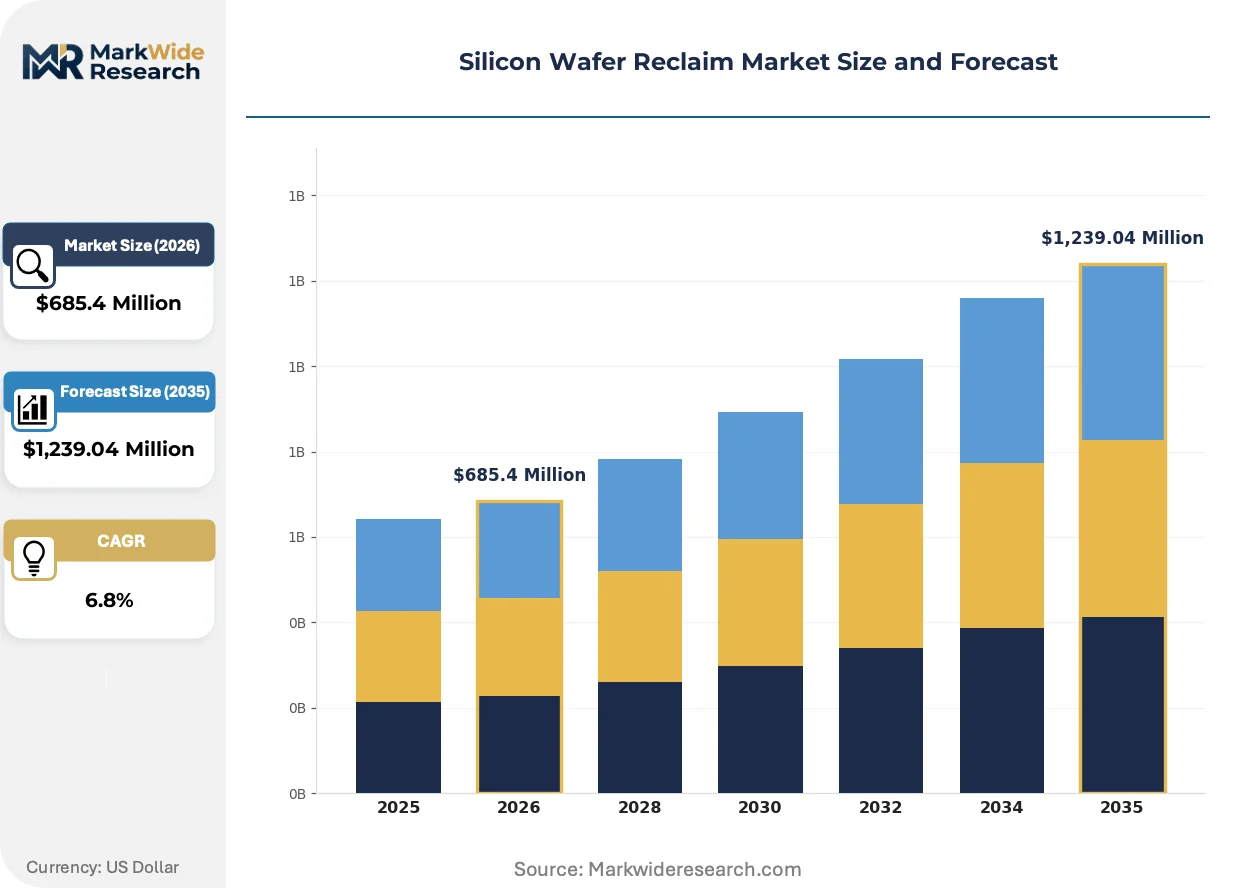
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Sided Wafers, Double-Sided Wafers, Polished Wafers, Epitaxial Wafers End User: Semiconductor Manufacturers, Solar Cell Producers, Research Institutions, Electronics Companies Processing Method: Chemical Mechanical Polishing, Plasma Etching, Laser Cleaning, Thermal Oxidation Quality Grade: Prime Grade, Test Grade, Recycled Grade, Specialty Grade |
| Companies Covered | Nano Silicon Inc, Silicon Valley Microelectronics, Silicon Quest International, Pure Wafer PLC, Noel Technologies, Phoenix Silicon International Corporation, Rockwood Wafer Reclaim, WRS Materials, Global Silicon Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicon Wafer Reclaim Market Emerging Trajectories
Plasma-assisted stripping chemistries and automated surface metrology are compressing reclaim cycle times while expanding addressable substrate conditions beyond traditional polishing limits.
Atomic layer etching for residue removal is rendering obsolete conventional wet-bath stripping for 14nm and below dummy wafer programs. Samsung and TSMC process engineering teams have qualified the technique for high-volume memory test wafer reclaim. The shift is rendering obsolete legacy multi-tank wet processing lines at independent reclaim facilities.
REACH authorization list expansion to perfluorinated compounds restricts etchant chemistry portfolios available to European reclaim operators. German and French reclaim facilities face reformulation costs exceeding €2 million per site for alternative stripping agents. Memory chip foundries with European packaging operations are accelerating qualification of fluorine-free reclaim streams to preempt supply disruption.
Consolidated procurement desks at Taiwan Semiconductor Manufacturing and SK Hynix now mandate vendor-managed inventory for reclaim wafer buffer stocks. Long-term reclaim service agreements with 24-month pricing floors displace spot-market purchasing. The model concentrates volume with vertically integrated reclaim specialists possessing in-house polishing and cleaning capabilities.
Silicon Wafer Reclaim Market Segmentation
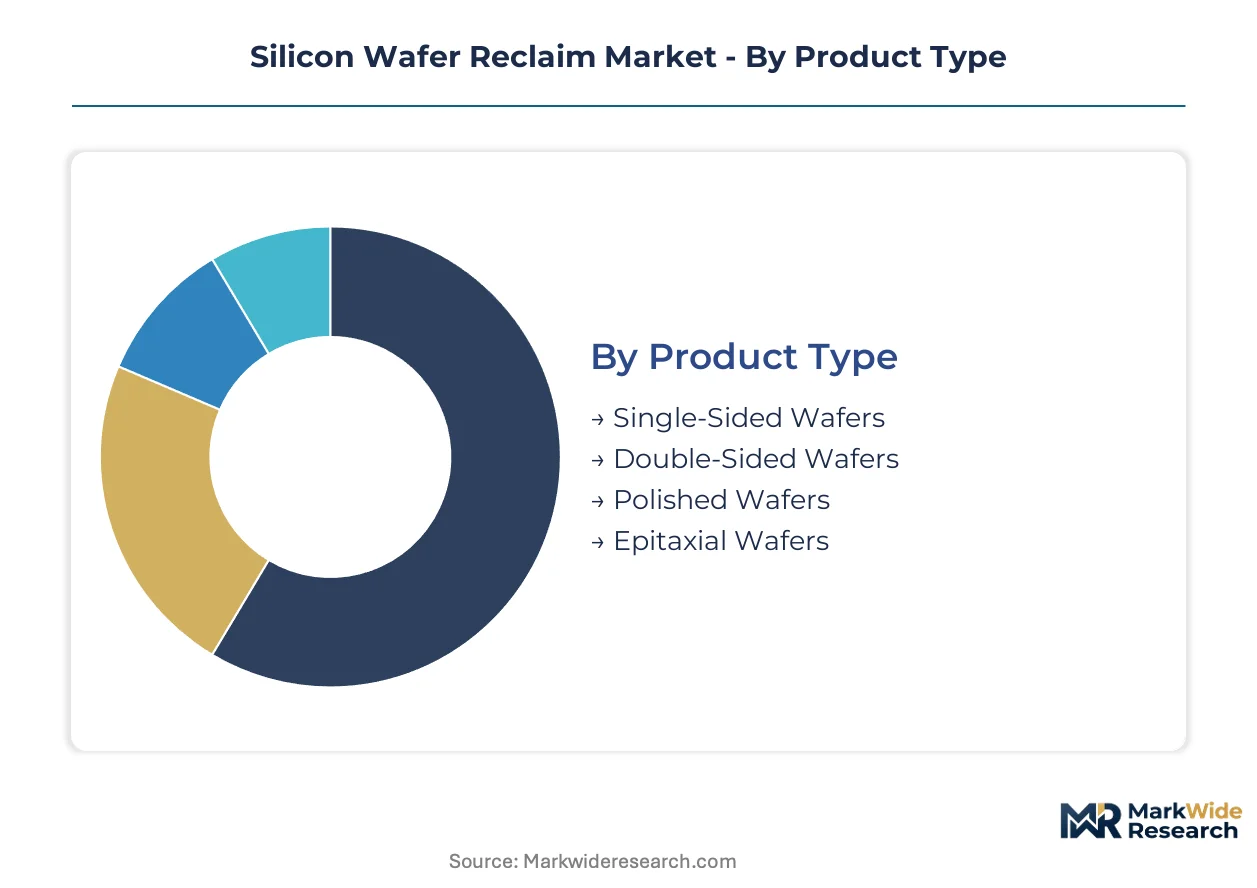
Segmentation in silicon wafer reclaim exposes how service intensity and technical specifications fragment procurement economics. Reclaim providers calibrate equipment configurations and chemistry portfolios against distinct substrate conditions and end-use tolerances.
Product Type:
After-sales service intensity varies sharply across wafer geometries, with double-sided configurations demanding specialized metrology support and edge-profile restoration protocols.
- Polished Wafers:Chemical mechanical polishing restores surface flatness within sub-micron tolerances through sequential abrasive slurry applications. Taiwan's foundry cluster drives volume through multi-cycle test wafer programs at TSMC and UMC facilities.
- Epitaxial Wafers:These substrates retain crystalline seed layers that enable high-temperature reclaim for power semiconductor applications. Demand concentrates in Germany's automotive silicon carbide supply chain where Bosch and Infineon qualify reclaimed epi-wafers for MOSFET test runs.
- Single-Sided Wafers:One active surface reduces processing complexity for memory foundry dummy applications.
- Double-Sided Wafers:Symmetrical polishing requirements elevate equipment utilization rates and technician labor intensity.
Polished wafers hold the largest share; momentum sits with epitaxial wafers.
End User:
Customer sophistication tiers separate semiconductor fabs with captive reclaim capabilities from outsourced procurement models.
- Semiconductor Manufacturers:Integrated device foundries and memory producers operate the most intensive reclaim programs. Samsung's Pyeongtaek campus and Micron's Singapore facility run 24-hour reclaim cycles to buffer virgin wafer price volatility.
- Solar Cell Producers:Downgraded semiconductor reclaim wafers supply photovoltaic ingot pulling operations. China's LONGi and JA Solar source degraded substrates from semiconductor reclaim streams to bridge polysilicon cost gaps.
- Research Institutions:Low-volume, high-mix procurement favors spot-market reclaim with flexible specification windows.
- Electronics Companies:MEMS and sensor fabs tolerate relaxed flatness tolerances for non-critical process development.
Semiconductor manufacturers dominate procurement volume; solar cell producers are expanding most quickly.
Processing Method:
Capital equipment differentiation separates high-throughput polishing operations from precision etching boutiques.
- Chemical Mechanical Polishing:Abrasive slurry systems dominate 300mm reclaim throughput where surface planarity requirements exceed plasma capabilities. Applied Materials and Ebara equipment installations concentrate in Taiwan and South Korea.
- Plasma Etching:Dry stripping removes metallization residues without wet chemistry disposal burdens. Samsung qualified plasma-assisted reclaim for 14nm dummy wafer programs, displacing legacy wet-bath lines.
- Laser Cleaning:Pulsed ablation targets localized contamination for specialty grade recovery.
- Thermal Oxidation:High-temperature oxide stripping serves niche epitaxial reclaim applications.
Chemical mechanical polishing commands installed capacity; plasma etching shows the steepest expansion trajectory.
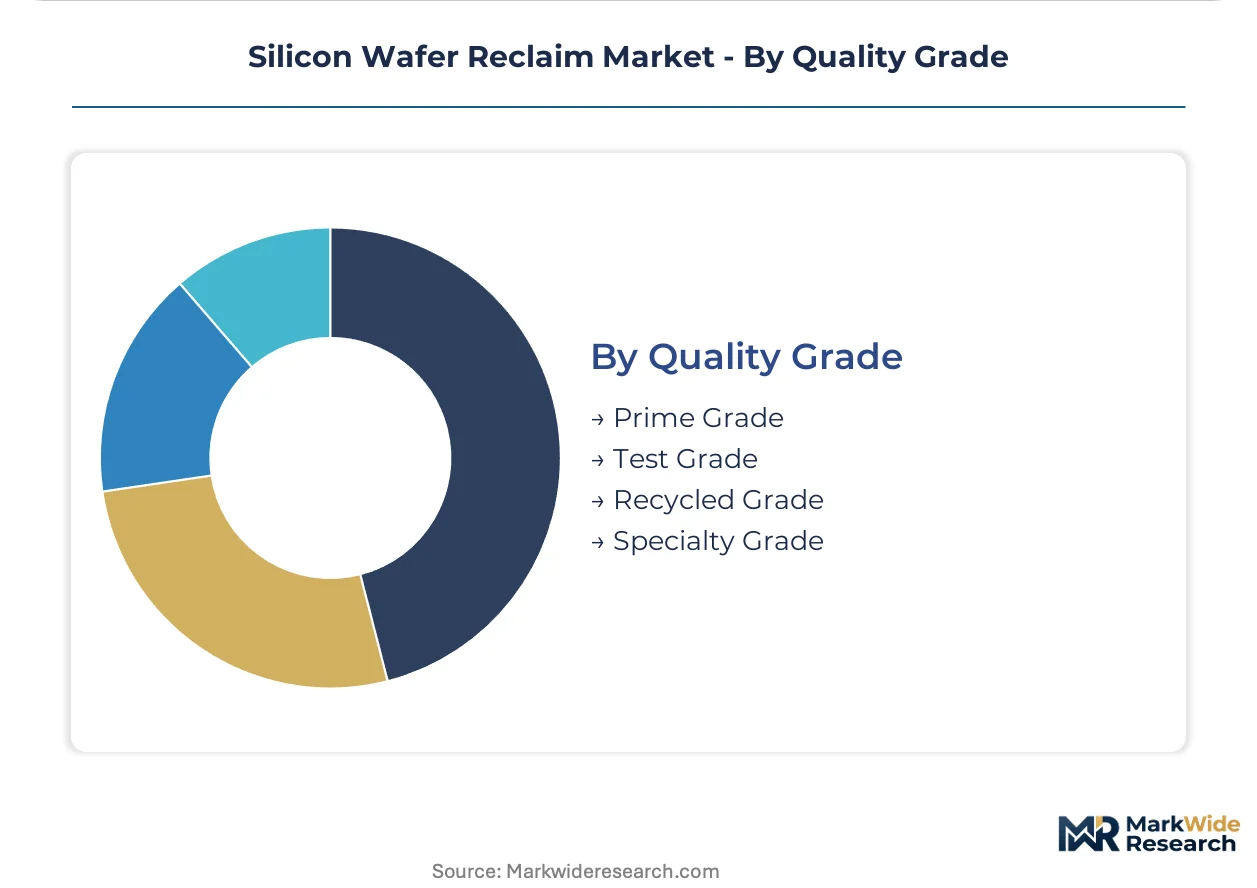
Quality Grade:
Certification tiers stratify pricing power and customer switching costs across reclaim specifications.
- Prime Grade:Tightest flatness and particle specifications qualify substrates for advanced packaging and MEMS production. Taiwan's ASE Group and Amkor Technology mandate prime-grade reclaim for flip-chip bumping process development.
- Test Grade:Intermediate specifications serve yield learning and equipment qualification cycles. Foundries in Hsinchu and Yongin consume test-grade reclaim for new node ramp preparation.
- Recycled Grade:Degraded specifications supply solar feedstock and non-semiconductor applications.
- Specialty Grade:Custom tolerances address RF, power, or sensor-specific substrate requirements.
Test grade holds the largest share; prime grade is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in South Korea and Taiwan absorb virgin wafer price swings with captive reclaim operations, while European and North American fabs outsource procurement and face steeper cost pass-through.
China
Memory fabrication facilities in Xi'an and Wuxi deploy closed-loop reclaim systems to meet MEE wastewater discharge limits. Beijing's dual carbon goals pressure semiconductor manufacturers to document polysilicon consumption reductions. The Yangtze River Delta cluster concentrates reclaim service demand from SMIC and Hua Hong facilities.
Taiwan
TSMC and UMC foundries run multi-cycle test wafer programs that multiply reclaim throughput per substrate. Taiwan's central environmental regulator imposes hazardous substance tracking on cross-border wafer movements. Hsinchu Science Park anchors the densest concentration of captive CMP reclaim capabilities globally.
South Korea
Samsung's Pyeongtaek campus and SK Hynix's Yongin facilities operate 24-hour reclaim cycles to buffer virgin silicon price volatility. The Ministry of Environment applies divergent hazardous waste codes to spent reclaim chemistry compared with Taiwan regulators. Yongin and Icheon form the core memory fabrication belt driving polished wafer reclaim volume.
United States
Integrated device manufacturers in Arizona and Texas qualify prime-grade reclaim for advanced packaging process development. EPA hazardous waste rules elevate compliance costs for reclaim chemistry disposal and recovery. Greater Phoenix and Austin metro areas concentrate demand from Intel and Texas Instruments fabrication sites.
Germany
Bosch and Infineon qualify reclaimed epitaxial wafers for silicon carbide MOSFET test runs in automotive power semiconductor supply chains. REACH authorization list expansion to perfluorinated compounds restricts etchant chemistry portfolios available to European reclaim operators. Saxony's Dresden cluster anchors automotive silicon carbide reclaim demand.
Silicon Wafer Reclaim Market Vendor Landscape
Capability concentration sits with vertically integrated specialists controlling in-house CMP and stripping operations; scale advantage sits with high-volume processors serving memory foundry procurement desks. The market structure tiers around three archetypes: captive reclaim operations at major foundries, independent full-service reclaimers, and niche plasma-etching boutiques. Consolidation pressures intensify as vendor-managed inventory agreements displace spot-market purchasing. Geographic expansion and chemistry portfolio diversification represent the dominant competitive moves.
Within the independent full-service tier, Pure Wafer PLC and Phoenix Silicon International Corporation exemplify scale-driven positioning, while Nano Silicon Inc occupies a capability-specialist position. These three entities represent distinct geographic and technical anchoring points across the reclaim value chain.
| Leading Market Players |
|---|
| Nano Silicon Inc |
| Silicon Valley Microelectronics |
| Silicon Quest International |
| Pure Wafer PLC |
| Noel Technologies |
| Phoenix Silicon International Corporation |
| Rockwood Wafer Reclaim |
| WRS Materials |
| Global Silicon Technologies, Inc. |
| Others |
Supply Flow & Price Mechanics
Shanghai-to-Kaohsiung container freight corridors transmit virgin polysilicon price volatility directly into reclaim service rate cards, compressing margins for independent processors while amplifying cost pass-through leverage for vertically integrated foundry captives. This logistics cost dynamic binds supply concentration in East Asian metallurgical-grade silicon hubs to downstream price differentiation between prime-grade reclaim and degraded solar feedstock tiers.
Pricing Analysis
After-sales service revenue from multi-cycle reclaim programs and vendor-managed inventory contracts drives lifetime value capture beyond transactional wafer sales. Three-tier pricing structure across prime, test, and recycled grades separates semiconductor manufacturers from solar cell producers and research institutions by specification tolerance and volume commitment. Cost compression in test-grade reclaim is intensifying because TSMC and SK Hynix procurement desks consolidate volume around 24-month pricing floors with integrated service providers. Solar cell producers exhibit highest price sensitivity due to polysilicon arbitrage economics, while advanced packaging foundries show lowest sensitivity given yield-critical substrate requirements.
Supply Chain Analysis
Extended payment terms from memory foundry procurement desks and supply-chain finance facilities anchored in Hsinchu and Yongin banking networks favor reclaim specialists with balance-sheet depth over independent operators. Virgin polysilicon supply concentrates in China, South Korea, and Germany, with reclaim service networks drawing from Taiwan, South Korea, and the United States for captive CMP capacity. The supply chain rests on abrasive slurry chemistries, precision polishing equipment, and high-purity cleaning agents as critical inputs. Single-source vulnerability in perfluorinated etchant chemistry due to REACH authorization restrictions threatens European reclaim facility operations. Distribution runs through direct vendor-managed inventory agreements at major foundry campuses, displacing spot-market spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon wafer reclaim operates as a substitution defense against virgin polysilicon price volatility and carbon-intensity documentation requirements, with incumbent reclaim specialists navigating displacement risk from atomic layer etching qualification at leading memory foundries.
For Market Incumbents: Harden captive chemical mechanical polishing capabilities through technician training investments in Hsinchu and Yongin to offset salary premium pressures. Deepen backward integration into abrasive slurry formulation to secure chemistry supply against REACH perfluorinated compound restrictions. Atomic layer etching adoption at Samsung and TSMC threatens wet-bath reclaim line obsolescence. For New Entrants and Emerging Players: Pursue MEMS sensor applications in Bosch and Denso supply chains where relaxed surface specifications enable prime-grade reclaim penetration with lower technical barriers. Target India's Gujarat and Karnataka greenfield sites under PLI scheme incentives for semiconductor fabrication localization. Lead with fluorine-free reclaim chemistry qualification to preempt European supply disruption. For Investors and Strategic Acquirers: Independent full-service reclaimers with in-house CMP and plasma etching capabilities present acquisition targets with durable vendor-managed inventory lock-in at TSMC and SK Hynix. Long-term viability hinges on carbon border adjustment mechanics and polysilicon traceability requirements tightening across the analysis window. Watch for atomic layer etching adoption rates at memory foundries as inflection indicator for wet-processing line asset values.| Strategic Initiative | Industry Significance |
|---|---|
| Captive CMP Capacity Expansion | Hsinchu and Yongin technician scarcity commands salary premiums that constrain facility ramp timelines. |
| Fluorine-Free Chemistry Qualification | REACH perfluorinated compound restrictions threaten German and French reclaim facility operations. |
| Vendor-Managed Inventory Agreements | TSMC and SK Hynix procurement desks now mandate buffer stock management with 24-month pricing floors. |
| India PLI Localization | Gujarat and Karnataka greenfield sites attract reclaim service investment for semiconductor fabrication incentives. |
| Atomic Layer Etching Adoption | Samsung qualification for 14nm dummy wafer programs displaces legacy wet-bath processing lines. |
Methodological Framework
Desk research of SEC filings from semiconductor equipment manufacturers, EPA hazardous waste rulemaking dockets, and Taiwan EPA regulatory notices preceded structured interviews with reclaim facility operations managers, foundry procurement directors, and chemical mechanical polishing process engineers. Secondary validation drew from customs trade data for polysilicon and wafer movements, ECHA REACH authorization lists, and China MEE wastewater discharge enforcement records. Bottom-up capacity utilization estimates triangulated against top-down virgin wafer consumption forecasts.
Assumptions held fixed include regulatory enforcement intensity at current levels and memory foundry capital expenditure plans; variables tested include carbon border adjustment implementation timing and atomic layer etching adoption curves. The analytical framework modeled segmentation across product type, end user, processing method, and quality grade dimensions over the projection horizon. CAGRs derived from wafer consumption intensity per fab, reclaim cycle economics, and substitution elasticity between virgin and reclaimed substrates. Forecast inputs incorporated polysilicon price volatility regimes and dual carbon goal compliance documentation requirements.
Sensitivities concentrate around REACH perfluorinated compound authorization timeline shifts and Taiwan-South Korea hazardous waste code harmonization outcomes. Forecasts reflect documented assumptions regarding memory foundry test wafer demand intensity and solar feedstock arbitrage viability. Macroeconomic contraction in semiconductor capital expenditure, regulatory divergence in cross-border wafer movement classification, or breakthrough displacement of CMP by atomic layer etching would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Manufacturing
High Purity Process Systems for Semiconductor Market
Semiconductor Manufacturing
Photoresist and Photoresist Ancillaries Market
Semiconductor Manufacturing
Global Overall EUV Lithography Market
Semiconductor Manufacturing
China Electronic Design Automation (EDA) Tools Market
Semiconductor Manufacturing
Photoresist Stripper Market
Semiconductor Manufacturing
Europe Photoresist and Photoresist Ancillaries Market
Semiconductor Manufacturing
IC CMP Slurries and Pads Market
Semiconductor Manufacturing
Medical Component Manufacturing Market
Semiconductor Manufacturing
Solar Laser Drilling Market
Semiconductor Manufacturing
Chip Melting Furnace Market
Semiconductor Manufacturing
United States Photoresist and Photoresist Ancillaries Market
Semiconductor Manufacturing
Middle East and Africa Cell Manufacturing Market
Semiconductor Manufacturing
Stencil Lithography Market
Semiconductor Manufacturing
Semiconductor Bonding Machine Market
Semiconductor Manufacturing
Advanced Process Control Market
Semiconductor Manufacturing
Battery Manufacturing Machines Market