
 Battery Manufacturing Machines Market | 2026-2036
Battery Manufacturing Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Manufacturing Machines Market Outlook
Solid-state electrolyte deposition is rewriting the equipment specifications for next-generation cell assembly. Lead Intelligent Equipment Co., Ltd. leverages its position in precision coating systems to serve lithium-ion expansion lines across Asia. Dürr Group anchors European demand through its integrated drying and formation equipment for large-scale gigafactories. Manz AG specializes in laser welding and testing modules that compete on throughput speed for automotive OEM contracts.
Battery manufacturing machines encompass the automated systems, precision tools, and process equipment used to fabricate electrochemical cells, including electrode coating systems operating at speeds exceeding 80 meters per minute and dry-room assembly environments maintained below 1% relative humidity. These machines enable mass production of cells with consistent energy density, cycle life, and safety profiles for transportation and grid storage applications. Coating machines command the largest capital allocation in new facilities due to the criticality of uniform cathode and anode layer deposition for cell performance. Welding tools represent the fastest-growing product category as cylindrical and prismatic formats shift toward laser-based tab bonding to reduce internal resistance. Solid-state technology is drawing disproportionate R&D investment despite lithium-ion's current dominance, since dry electrode processing requires fundamentally different equipment architectures.
The EU Green Deal and F-Gas Regulation constrain solvent-based coating processes in European facilities, pushing equipment buyers toward aqueous binder systems and closed-loop recovery designs. EPA emissions standards in the United States limit volatile organic compound releases from electrode drying stages, compelling manufacturers to upgrade thermal oxidizer integrations. China's MIIT enforces GB standards for battery cell quality consistency, which directly dictates the metrology and testing instrumentation that domestic equipment suppliers must embed. Stakeholders must weigh regional regulatory divergence against platform standardization when selecting machine configurations for multi-continent deployment strategies.
Market Dynamics
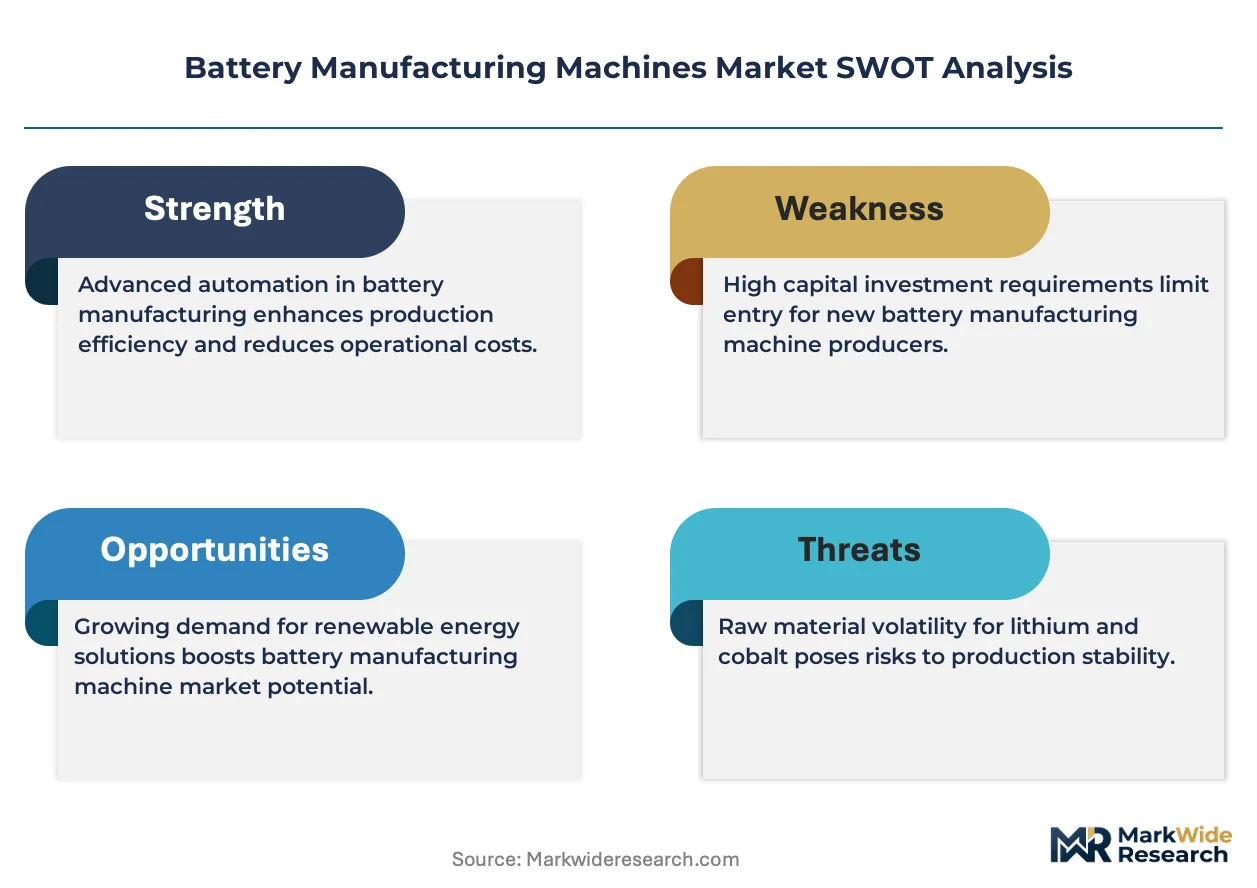
Solid-state electrolyte deposition is forcing equipment manufacturers to abandon wet-coating architectures entirely. Dry electrode processing demands new precision tooling that existing lithium-ion lines cannot retrofit, creating a bifurcation between incumbent suppliers and next-generation specialists.
Growth Catalysts
- EU Green Deal battery passport mandates:Traceability requirements are compelling gigafactory operators to upgrade metrology and testing modules for full lifecycle documentation.
- Automotive OEM captive production:Vertical integration into cell manufacturing is pulling precision coating and laser welding equipment directly into vehicle assembly supply chains.
- Dry electrode processing:Solid-state cell architectures are eliminating solvent recovery systems and accelerating capital redeployment toward powder compaction and calendering machinery.
Market Restraints
- Capital intensity of dry-room infrastructure:Humidity control below 1% relative humidity requires continuous energy input that constrains facility siting near renewable power sources.
- Equipment supplier concentration in Asia:Precision coating system manufacturing clusters in China and South Korea create geographic vulnerability for European and North American facility planners.
- Technical limitation in solid-state interface engineering:Ceramic-electrolyte to electrode bonding remains unproven at gigafactory throughput speeds, delaying equipment standardization.
Strategic Opportunities
- Underpenetrated North American electrode coating:Domestic cathode and anode production capacity lags cell assembly, creating demand for integrated coating-calendering lines in Michigan and Tennessee.
- Regulatory tailwind from US IRA domestic content credits:Equipment localization incentives are attracting European and Asian machinery suppliers to establish US assembly operations.
- Technology convergence of laser welding and inline inspection:Combined tab bonding and defect detection modules are reducing footprint requirements for cylindrical cell lines serving power tool and e-mobility applications.
Industry Challenges
- Electrochemical process engineering talent scarcity:Equipment manufacturers compete with cell producers for specialists who understand both coating rheology and solid-state ion transport.
- Certification timeline compression:UL and CE marking for new laser welding configurations must parallel rather than follow cell chemistry validation, stretching quality assurance resources.
- Legacy wet-coating asset stranding:Existing solvent-based electrode lines face accelerated depreciation as aqueous binder and dry electrode routes achieve performance parity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Manufacturing Machines Market |
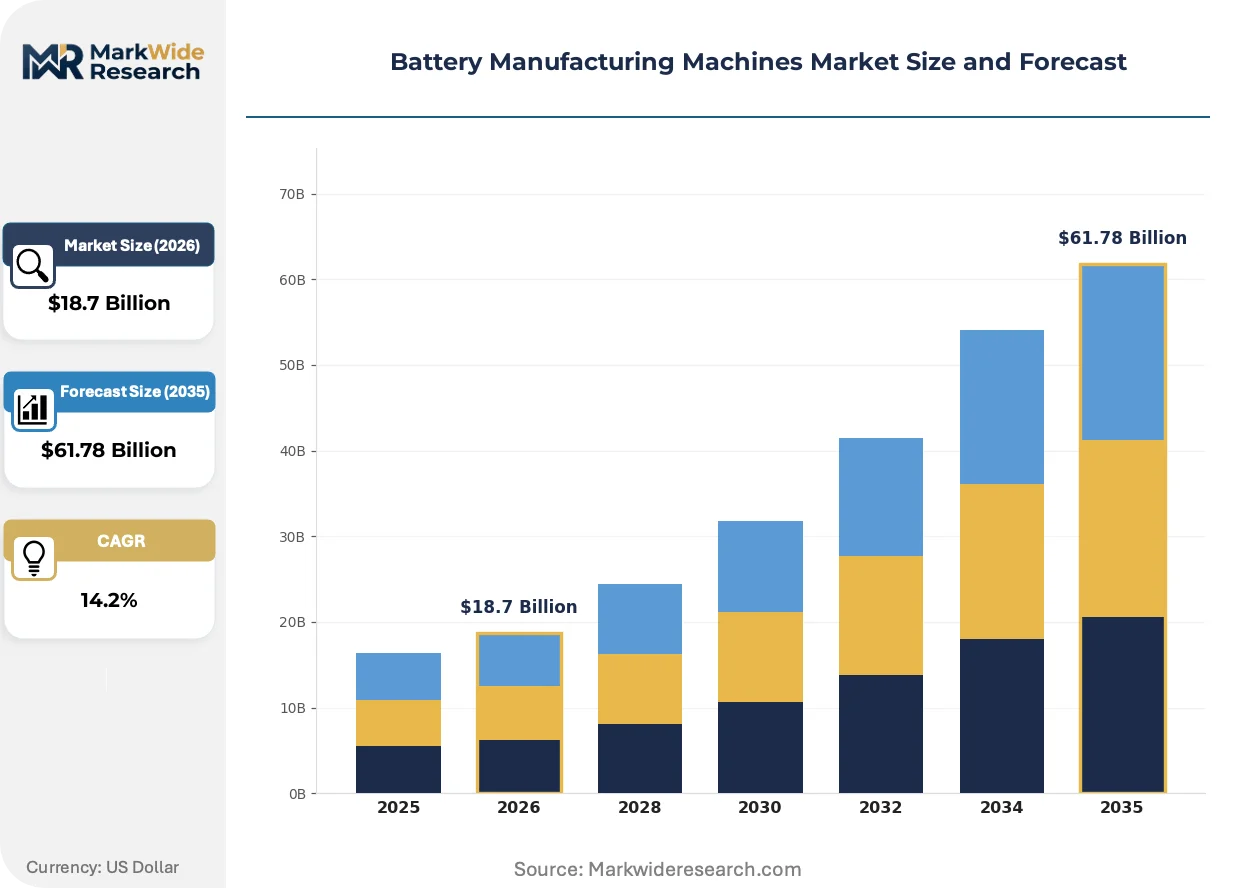
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Assembly Equipment, Testing Instruments, Coating Machines, Welding Tools Technology: Lithium-Ion, Nickel-Metal Hydride, Solid-State, Lead-Acid Application: Electric Vehicles, Consumer Electronics, Energy Storage Systems, Industrial Use End User: Aerospace, Automotive OEMs, Energy Providers, Manufacturers |
| Companies Covered | Lead Intelligent Equipment Co., Ltd., Hitachi High-Tech Corporation, Dürr Group, Yinghe Technology Co., Ltd., ANDRITZ Schuler GmbH, Manz AG, Bühler Group, Nordson Corporation, IPG Photonics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Manufacturing Machines Market Strategic Shifts
Digital twin integration is compressing equipment commissioning timelines from months to weeks. Virtual commissioning platforms allow coating line calibration without physical electrode material consumption, reducing startup waste and accelerating production ramp.
Digital twin platforms for electrode coating lines are virtualizing the entire calibration sequence before physical material touches the rollers. Automotive OEMs deploying these systems in German and Hungarian gigafactories report 40% reduction in startup scrap rates. The technology is virtualizing supplier-customer relationships by enabling remote acceptance testing that eliminates international travel for equipment sign-off.
EPA emissions standards for volatile organic compounds are forcing thermal oxidizer retrofits on existing electrode drying stages. Equipment buyers must integrate regenerative thermal oxidation or catalytic recovery systems to maintain operating permits. California and Texas facilities face the strictest enforcement, driving demand for closed-loop solvent recovery designs that European suppliers pioneered under F-Gas Regulation constraints.
Power purchase agreement structures are reshaping how equipment vendors price energy-intensive machinery. Buyers now demand guaranteed consumption benchmarks for coating ovens and dry-room HVAC systems, transferring operational cost risk to manufacturers. This contracting innovation is most advanced in Nordic markets where renewable electricity pricing volatility has compressed negotiation cycles for gigafactory equipment tenders.
Battery Manufacturing Machines Market Segmentation
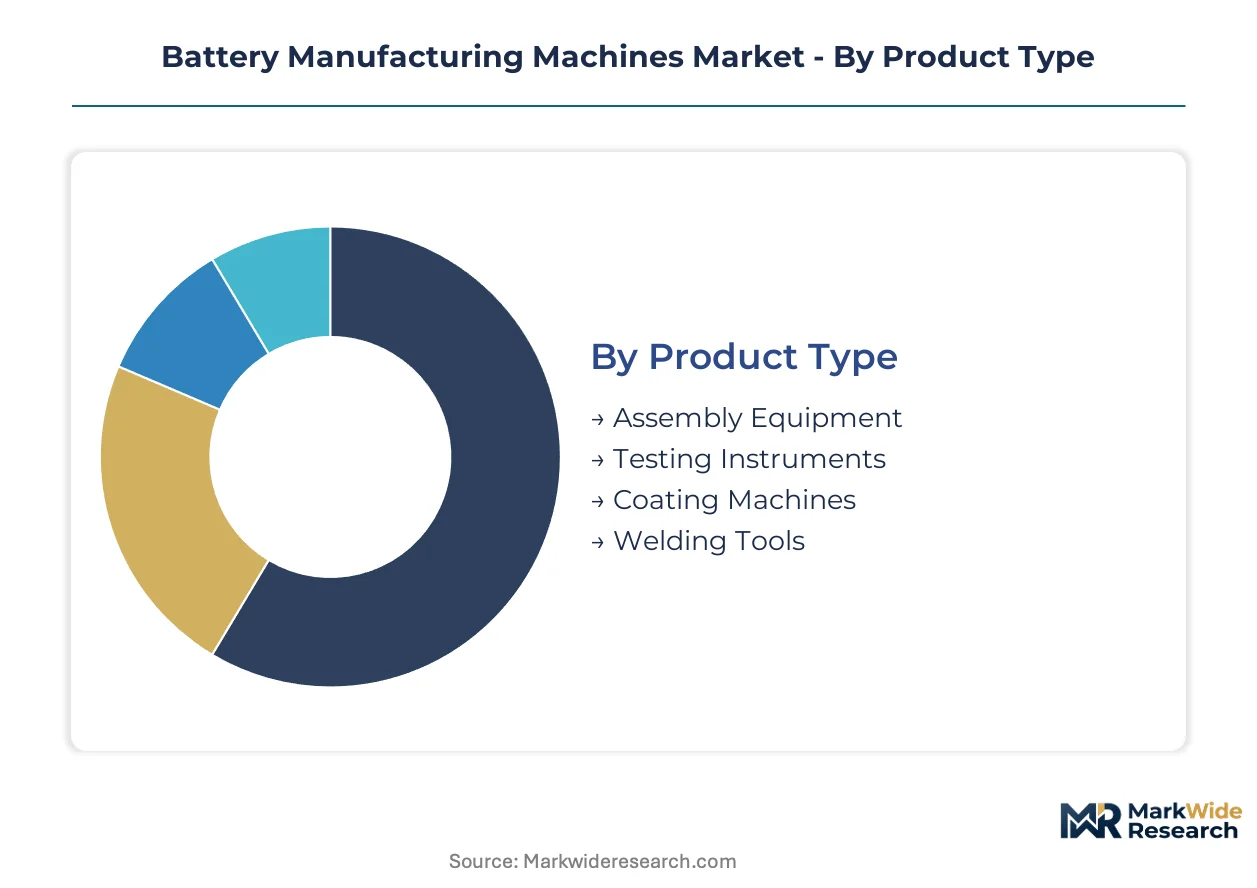
Equipment segmentation in battery manufacturing machines determines capital allocation cycles and technology refresh rates. Cycle time variations between coating systems and testing instruments create divergent replacement schedules that reshape supplier revenue predictability across the forecast window.
Product Type:
Cycle times vary dramatically across equipment categories, with coating machines requiring multi-year depreciation schedules while welding tools face compressed replacement windows from format shifts.
- Coating Machines:Electrode coating systems deposit cathode and anode slurries onto metal foils at speeds exceeding 80 meters per minute with thickness tolerances below 2 micrometers. Demand concentrates in Germany where CATL and Northvolt gigafactories require uniform layer deposition for high-energy-density cells, though EU F-Gas Regulation constraints on solvent recovery systems are extending procurement cycles for aqueous binder configurations.
- Welding Tools:Laser-based tab bonding equipment joins current collectors to electrode terminals with precision below 0.1 millimeters for cylindrical and prismatic formats. Automotive OEM captive production lines in Hungary and Sweden are pulling fiber laser configurations directly into vehicle assembly supply chains as cylindrical cell demand accelerates for power tool and e-mobility applications.
- Assembly Equipment:Cell stacking and electrolyte filling systems operate in dry-room environments below 1% relative humidity.
- Testing Instruments:Inline metrology modules verify dimensional consistency and electrochemical performance before formation cycling.
Coating machines anchor the volume base while welding tools gain share at the steepest rate.
Technology:
Cost tiers separate mature chemistry equipment from next-generation architectures requiring fundamentally different capital deployment.
- Lithium-Ion:Wet-coating electrode processing dominates current installed capacity with established supply chains for solvent-based slurry systems. Gigafactory operators in China and South Korea continue expanding lithium-ion lines despite dry electrode processing emergence, as GB standards from MIIT enforce quality consistency requirements that favor proven equipment configurations.
- Solid-State:Dry electrode processing and ceramic electrolyte deposition demand entirely new powder compaction, calendering, and interface engineering equipment that incumbent wet-coating suppliers cannot retrofit. R&D investment concentrates in Japan and Germany where METI and national research programs fund pilot line validation, though ceramic-electrolyte to electrode bonding remains unproven at production throughput speeds.
- Nickel-Metal Hydride:Mature equipment serves hybrid vehicle auxiliary power and stationary backup applications with stable but declining capital allocation.
- Lead-Acid:Grid-scale storage and automotive starter battery production utilizes established paste mixing and formation equipment with minimal technology refresh.
Lithium-ion equipment commands the dominant cost tier while solid-state architectures attract the steepest expansion trajectory in forward capital plans.
Application:
Customer type segmentation reveals divergent procurement authority structures between integrated OEMs and merchant cell suppliers.
- Electric Vehicles:Battery pack assembly for passenger cars, commercial trucks, and two-wheelers requires high-throughput coating and laser welding lines. Vertical integration by automotive OEMs into cell manufacturing is pulling precision equipment directly into vehicle assembly supply chains, with German and Hungarian facilities leading European capacity expansion.
- Energy Storage Systems:Grid-scale and residential battery production emphasizes cycle life consistency over energy density, favoring formation and aging equipment with extended test protocols. US IRA domestic content credits are accelerating demand for integrated coating-calendering lines in Michigan and Tennessee where cathode and anode production capacity lags cell assembly.
- Consumer Electronics:Cylindrical and pouch cell formats for smartphones, laptops, and power tools prioritize compact footprint and rapid format changeover.
- Industrial Use:Forklift, marine, and stationary power applications utilize robust equipment configurations with lower automation levels.
Electric vehicle applications anchor procurement volume while energy storage systems climb the fastest on policy-driven manufacturing reshoring.
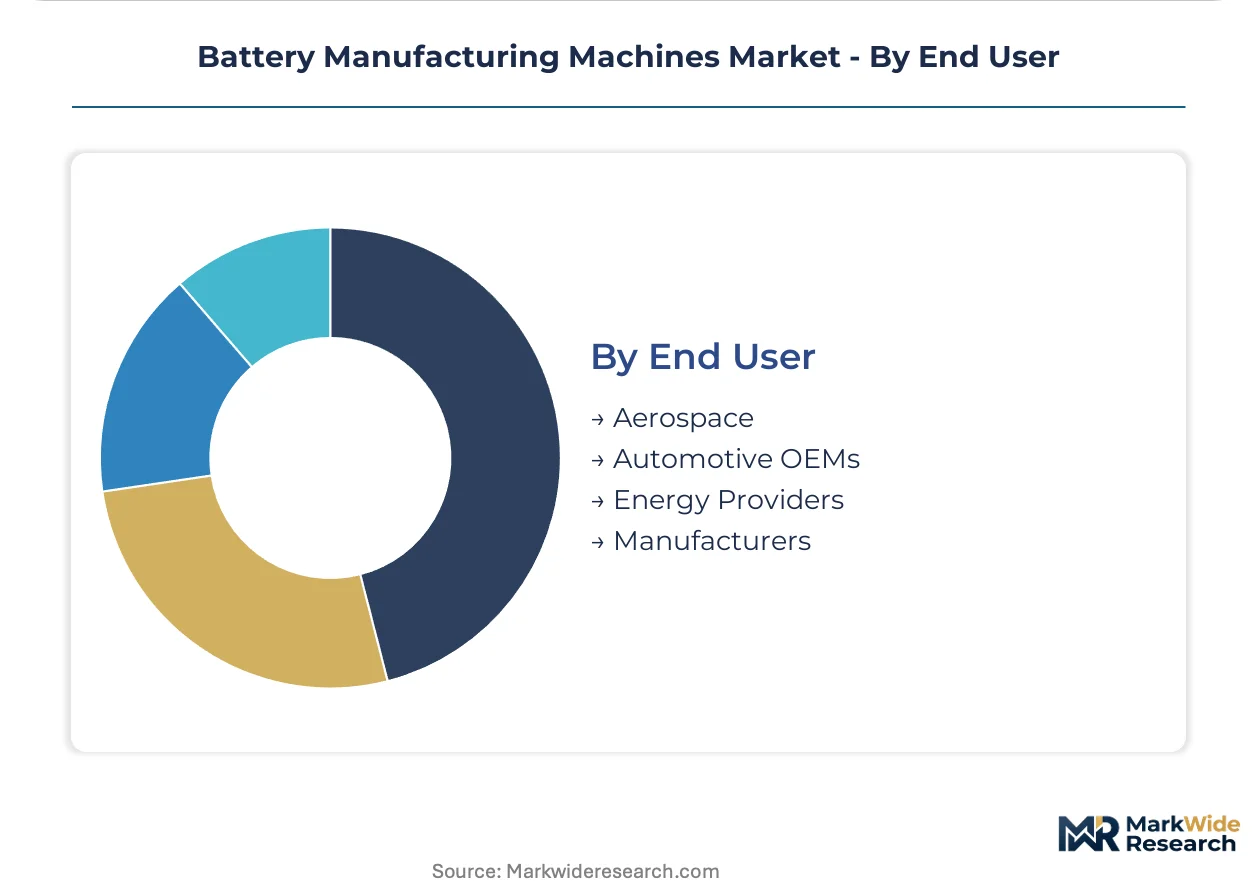
End User:
Supply concentration patterns vary sharply between aerospace certification requirements and automotive scale economics.
- Automotive OEMs:Captive cell production lines integrate coating, welding, and formation equipment directly into vehicle manufacturing campuses. EPA emissions standards for volatile organic compounds compel thermal oxidizer retrofits on electrode drying stages, with California and Texas facilities facing strictest enforcement.
- Energy Providers:Utility-scale battery manufacturing emphasizes formation and testing equipment for grid-connected storage systems with 20-year service life requirements.
- Manufacturers:Merchant cell producers serving multiple end-markets require flexible equipment platforms with rapid format reconfiguration capabilities.
- Aerospace:Aviation battery production demands specialized equipment for extreme reliability certification with low-volume, high-mix production characteristics.
Automotive OEMs concentrate the largest equipment procurement budgets while energy providers expand most quickly on grid storage deployment timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gigafactory operators concentrate procurement authority in three buyer archetypes: automotive OEMs with captive production, merchant cell producers serving multiple end-markets, and energy storage integrators. Geographic distribution of these archetypes determines regional equipment demand patterns.
Germany
Automotive OEM captive production lines dominate equipment procurement, with Volkswagen and BMW integrating cell manufacturing into vehicle assembly campuses. EU Green Deal battery passport mandates compel metrology upgrades for full lifecycle traceability. CATL and Northvolt facilities in Thuringia and Schleswig-Holstein anchor European coating machine demand.
United States
Domestic cathode and anode production capacity lags cell assembly, creating demand for integrated coating-calendering lines. EPA emissions standards for volatile organic compounds force thermal oxidizer retrofits on electrode drying stages. Michigan and Tennessee facilities lead capacity expansion as IRA domestic content credits attract machinery suppliers.
China
MIIT enforces GB standards for battery cell quality consistency, dictating metrology and testing instrumentation requirements. Precision coating system manufacturing clusters concentrate equipment supplier capacity. Zhengzhou and Shenzhen production bases serve lithium-ion expansion lines across Asia.
South Korea
LG Energy Solution and Samsung SDI vertical integration drives laser welding and formation equipment demand. MFDS-equivalent quality enforcement shapes testing protocol standardization. Gyeonggi-do and Ulsan industrial complexes concentrate electrode coating and cell assembly capacity.
Japan
METI-funded pilot lines validate solid-state ceramic-electrolyte deposition equipment. Dry electrode processing R&D concentrates in Nagoya and Osaka manufacturing clusters. Equipment suppliers serve domestic automotive OEMs transitioning from lithium-ion to next-generation cell architectures.
Battery Manufacturing Machines Market Competitive Environment
Channel-controlling players compete with product-specialist players for procurement relationships with gigafactory operators and automotive OEMs. The market structures around three tiers: integrated equipment platforms, precision subsystem specialists, and regional fabrication houses. Strategic moves concentrate on technology licensing partnerships and geographic expansion through local assembly operations.
Among German-based fabricators, Dürr Group and Manz AG occupy positions in the European precision equipment tier. Lead Intelligent Equipment Co., Ltd. represents the Asian coating system specialist archetype. These three companies exemplify how regional supplier clusters align with local regulatory requirements and customer procurement patterns.
| Leading Market Players |
|---|
| Lead Intelligent Equipment Co., Ltd. |
| Hitachi High-Tech Corporation |
| Dürr Group |
| Yinghe Technology Co., Ltd. |
| ANDRITZ Schuler GmbH |
| Manz AG |
| Bühler Group |
| Nordson Corporation |
| IPG Photonics Corporation |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese precision coating system manufacturing is compressing margins for European and North American equipment buyers while concentrating supplier bargaining power in Asia. Utilization rates below 70% at Shenzhen and Zhengzhou production bases are forcing extended payment terms and aggressive indexation clauses into contracts, reshaping how automotive OEMs and gigafactory operators negotiate equipment procurement.
Pricing Analysis
Cost-plus contracts with steel and rare-earth magnet indexation dominate equipment procurement for coating machines and laser welding systems. Three-tier pricing structure across premium, standard, and economy levels separates UL-certified configurations from CE-marked and uncertified alternatives, with certification grade driving 15-25% price spreads. Cost compression in standard-tier aqueous binder coating lines is intensifying because European F-Gas Regulation compliance adds thermal oxidizer bundling requirements. Merchant cell producers exhibit highest price sensitivity due to capital constraint cycles, while automotive OEM captive lines prioritize throughput guarantees over unit cost.
Supply Chain Analysis
Extended payment terms stretching to 180 days and supply-chain finance facilities anchored by Chinese state-backed credit are restructuring working capital flows for precision coating system procurement. Manufacturing clusters concentrate in China, South Korea, and Germany, with powder compaction tooling drawing from Japanese ceramic machining expertise and German precision engineering. Supply chain risk centers on single-source vulnerability for high-speed coating rollers and fiber laser resonators sourced exclusively from Asian suppliers. Distribution runs through direct OEM relationships for automotive captive lines and integrator channels for merchant cell producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrochemical process engineering talent scarcity is constraining equipment manufacturer expansion and creating acquisition premiums for teams with solid-state interface expertise. The gap between wet-coating legacy capabilities and dry electrode processing requirements is widening faster than training pipelines can fill.
For Market Incumbents: Build switching-cost moats through embedded digital twin platforms that virtualize commissioning and lock in recurring calibration service revenue. Defend against Asian coating system specialists by securing exclusive laser welding partnerships with automotive OEMs expanding into Hungary and Sweden. Add capacity in Tennessee and Michigan to capture IRA domestic content credit demand before European competitors establish local assembly. For New Entrants and Emerging Players: Pursue white-space opportunities in solid-state ceramic-electrolyte deposition equipment where incumbent wet-coating suppliers cannot retrofit existing architectures. Target North American electrode coating-calendering integration where cathode and anode production capacity lags cell assembly. Enter through technology licensing partnerships with METI-funded Japanese pilot lines to validate equipment before commercial scale. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision subsystem specialists with embedded metrology and testing modules serving battery passport traceability mandates. Long-term viability favors equipment suppliers with demonstrated solid-state pilot line validation and established relationships with automotive OEMs transitioning cell production in-house. Watch ceramic-electrolyte to electrode bonding throughput speeds as the inflection signal for equipment standardization and capital deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Dry Electrode Processing Equipment Development | Eliminates solvent recovery systems and attracts solid-state R&D funding from METI and EU programs. |
| Digital Twin Platform Integration | Compresses commissioning timelines and creates recurring service revenue from German gigafactory operators. |
| North American Assembly Localization | Captures IRA domestic content credits and reduces tariff exposure for precision coating system sales. |
| Laser Welding-Metrology Convergence | Reduces footprint for cylindrical cell lines serving power tool and e-mobility applications in Hungary. |
| Aqueous Binder System Certification | Meets EU F-Gas Regulation constraints and extends procurement cycles for European coating machine buyers. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with equipment procurement directors at automotive OEMs, gigafactory operations executives, precision coating system engineers, and laser welding specialists; and secondary validation through SEC filings, EU battery passport regulatory filings, MIIT GB standard documentation, and customs trade data for coating machine imports. Bottom-up equipment shipment tallies by product category and top-down gigafactory capital expenditure tracking were triangulated against supplier revenue disclosures.
Forecast inputs considered electrode coating speed evolution, dry-room infrastructure deployment cycles, and solid-state pilot line validation timelines across the projection horizon. Segmentation dimensions modeled include product type, technology chemistry, application end-use, and regional regulatory cluster. CAGRs were derived from equipment shipment trajectories and capital intensity ratios applied to announced gigafactory capacity builds. Industry-specific inputs incorporated F-Gas Regulation compliance cost pass-through and IRA domestic content credit eligibility thresholds.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed equipment suppliers or accelerated solid-state commercialization by Japanese automotive OEMs would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Manufacturing
Thin Film Semiconductor Deposition Market
Semiconductor Manufacturing
Malaysia and Thailand Precession Cleaning for Electronic Market
Semiconductor Manufacturing
Chip Melting Furnace Market
Semiconductor Manufacturing
Semiconductor and Circuit Manufacturing Market
Semiconductor Manufacturing
Advanced Process Control Market
Semiconductor Manufacturing
Global Wafer Cutting Fluids Market
Semiconductor Manufacturing
Semiconductor Bonding Machine Market
Semiconductor Manufacturing
Global EUV Lithography Market
Semiconductor Manufacturing
PCB Photoresist Market
Semiconductor Manufacturing
Silicon Wafer Reclaim Market
Semiconductor Manufacturing
Global Overall EUV Lithography Market
Semiconductor Manufacturing
High Purity Process Systems for Semiconductor Market
Semiconductor Manufacturing
Photoresist Stripper Market
Semiconductor Manufacturing
Electronic Manufacturing Services (EMS) Market
Semiconductor Manufacturing
Silicon Turners Market
Semiconductor Manufacturing
Surface Mount Technology (SMT) Market