
 Semiconductor Bonding Machine Market | 2026-2036
Semiconductor Bonding Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Bonding Machine Market Analytics
Automotive module packaging is collapsing as the dominant buyer archetype while advanced packaging for AI accelerators gains share. Tokyo Electron leverages its etch-and-deposition ecosystem to cross-sell bonding solutions into HBM fabs. BE Semiconductor Industries NV anchors its position through precision die-attach systems for heterogeneous integration. Kulicke & Soffa competes aggressively in thermocompression bonding for chiplet architectures.
A semiconductor bonding machine joins dies, wires, or packages to substrates using thermal, ultrasonic, laser, or induction energy with placement accuracy below 5 microns at throughputs exceeding 10,000 units per hour. Wire bonding retains the largest installed base but flip chip bonding captures the fastest growth as 2.5D and 3D packaging proliferate. Thermal bonding dominates legacy applications while laser bonding expands in MEMS and photonics where heat sensitivity constrains process windows.
China's MIIT enforces domestic equipment procurement quotas through its GB standards and dual carbon goals, restricting foreign bonding machine access. The EU Chips Act and CE marking under MDR require traceable calibration protocols for medical device semiconductor bonding. Japan's METI coordinates JIS standards with METI-funded consortia to preserve equipment export competitiveness. Stakeholders must monitor which qualification regimes their customers' fabs must satisfy before committing to regional service footprints.
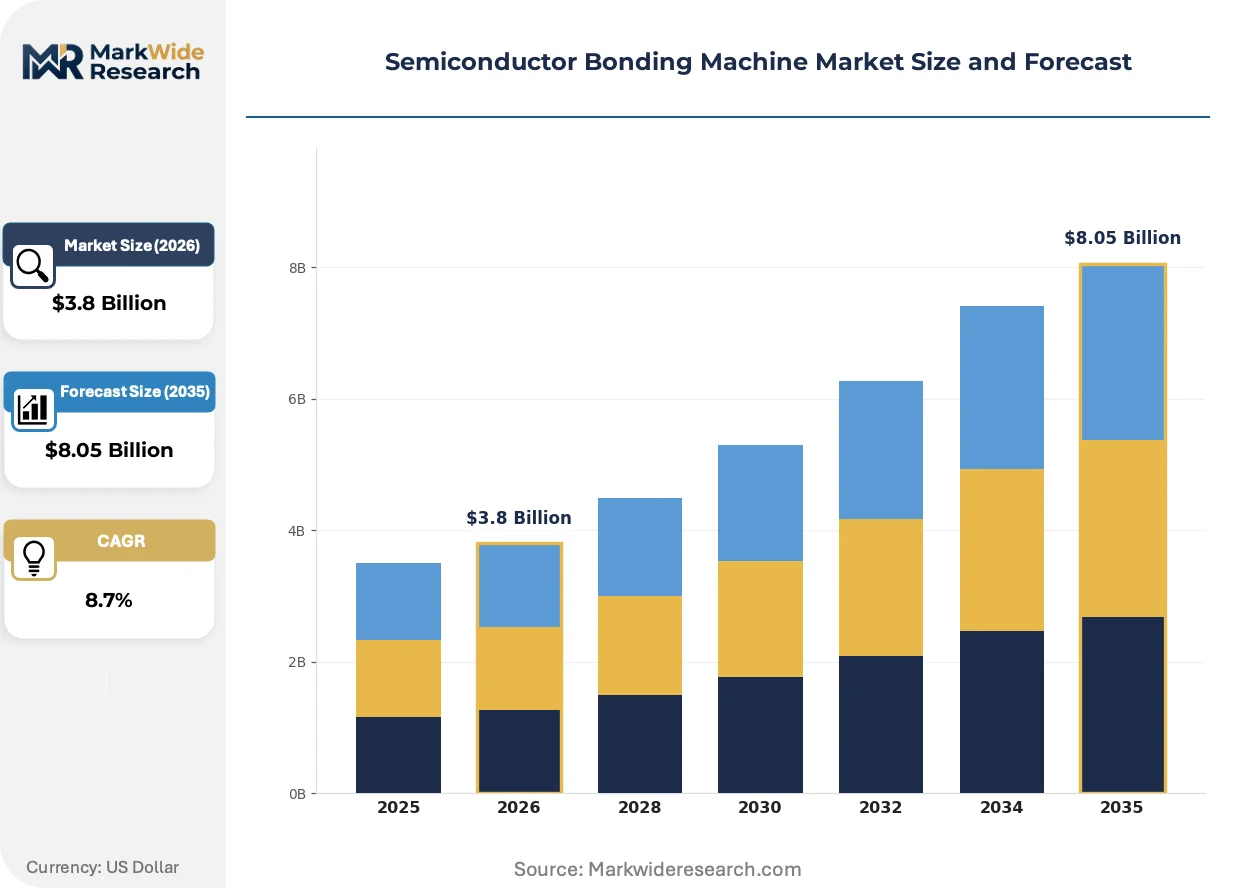
Market Dynamics
Advanced packaging architectures for AI accelerators are compressing legacy wire bonding volumes while thermocompression and hybrid bonding systems absorb disproportionate capital allocation across HBM fabs.
Growth Catalysts
- MIIT domestic procurement quotas:China's GB standards mandate local equipment sourcing, redirecting bonding machine demand toward qualified domestic suppliers.
- Heterogeneous integration:Chiplet architectures require precision die-attach systems for 2.5D and 3D stacking, expanding bonding equipment specifications.
- Pyeongtaek-Hwaseong corridor expansion:Samsung and SK Hynix are scaling HBM and 3D NAND capacity, concentrating equipment orders in South Korea's semiconductor belt.
Market Restraints
- Precious metal input volatility:Gold and copper wire costs fluctuate with commodity markets, pressuring wire bonding gross margins.
- Sub-micron placement tolerance requirements:Hybrid bonding demands below 500-nanometer alignment accuracy, restricting supplier qualification to a narrow equipment base.
- Dual carbon compliance costs:China's MEE enforcement of energy-intensity standards raises operational expenses for bonding machine manufacturing.
Strategic Opportunities
- Photonics packaging white space:Silicon photonics modules for data centers require laser bonding systems that avoid thermal damage to optical components.
- EU Chips Act capital access:European equipment makers can tap subsidies for bonding machine R&D targeting heterogeneous integration.
- MEMS sensor proliferation:Automotive and consumer MEMS devices need specialized bonding processes for fragile microstructures.
Industry Challenges
- Multi-physics simulation expertise gap:Bonding process optimization now requires coupled thermal-mechanical-electrical modeling capabilities that few field engineers possess.
- CE marking under MDR:Medical device semiconductor bonding equipment faces extended validation timelines for traceable calibration protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Bonding Machine Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Die Attach, Wire Bonding, Flip Chip, Package Bonding Technology: Thermal, Ultrasonic, Laser, Induction End User: Consumer Electronics, Automotive, Telecommunications, Medical Devices Installation: On-Site, Off-Site, Portable, Fixed |
| Companies Covered | EV Group, Tokyo Electron, BE Semiconductor Industries NV, Panasonic Holding Corporation, Shibaura Mechatronics Corporation, ASM Pacific Technology Ltd, Applied Materials, Fuji Corporation, Kulicke & Soffa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Bonding Machine Market Evolving Landscape
Thermocompression bonding heads are displacing conventional wire bonders in memory fabs, while regulatory compliance regimes fragment across major semiconductor geographies. Equipment vendors must architect modular platforms that adapt to divergent qualification standards.
Hybrid bonding technology is miniaturizing interconnect pitches below 10 micrometers for 3D NAND and HBM stacks. Memory manufacturers in South Korea and Taiwan are adopting these systems at accelerated replacement cycles. The shift is miniaturizing the addressable market for traditional wire bonders while expanding precision equipment TAM.
Japan's METI coordinates JIS standards with METI-funded consortia to preserve equipment export competitiveness. The framework mandates interoperability testing that adds six to nine months to equipment qualification. Bonding machine vendors targeting Japanese fabs must embed these protocols into their regional service footprints.
After-sales service unbundling is spreading as foundries negotiate predictive maintenance contracts separately from hardware procurement. Equipment OEMs are responding with sensor-embedded bonding heads that transmit vibration and thermal data to cloud analytics platforms. This pattern is most pronounced in Taiwan's foundry ecosystem where TSMC and UMC pressure vendors for uptime guarantees.
Semiconductor Bonding Machine Market Segmentation
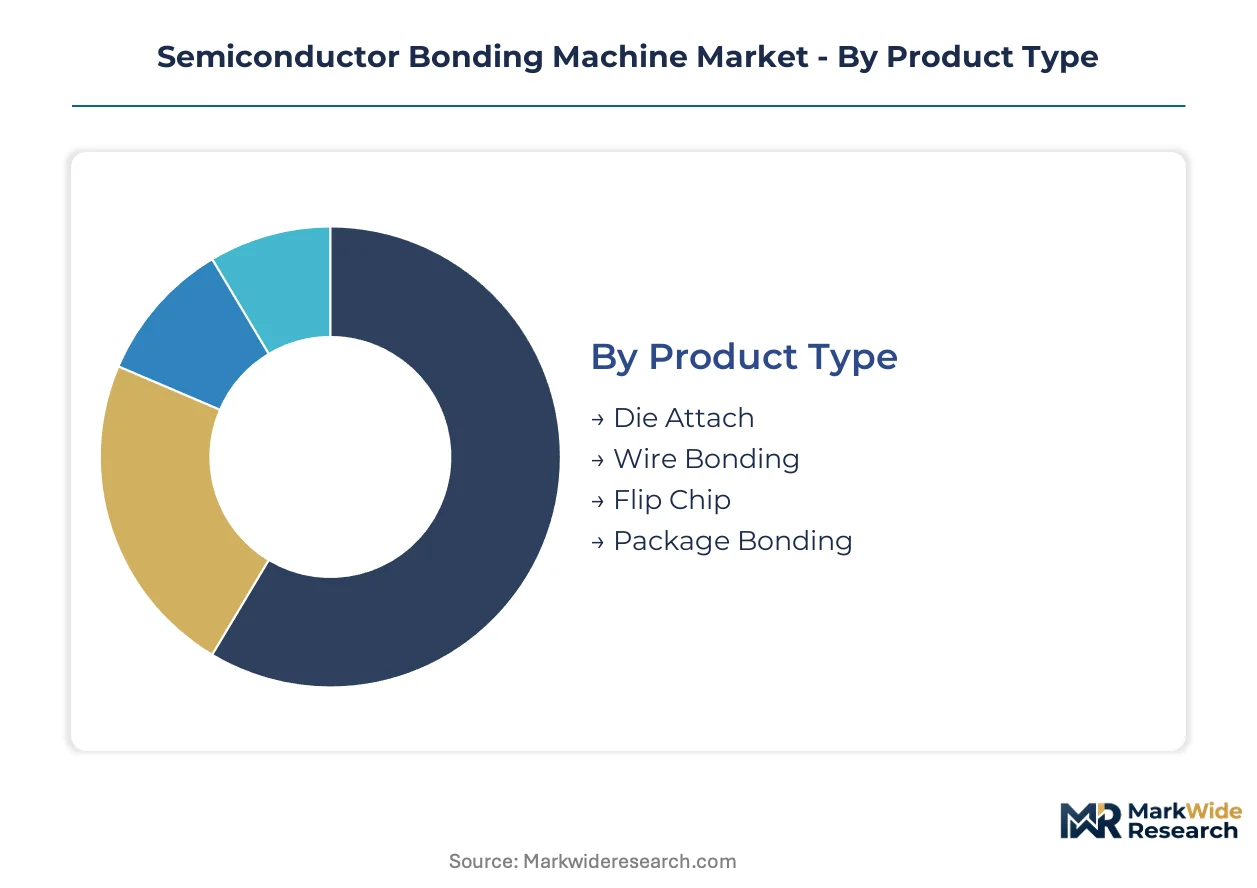
Semiconductor bonding machine procurement splits across four dimensions that determine equipment specifications and supplier qualification paths. Product type and technology choices dictate capital allocation priorities, while end-user verticals and installation modes shape regional service footprints and aftermarket revenue streams.
Product Type:
Die attach systems face the strongest substitution pressure from hybrid bonding as memory fabs compress interconnect pitches below 10 micrometers.
- Die Attach:Precision placement systems bond bare dies to substrates with placement accuracy below 5 microns. Samsung and SK Hynix in South Korea's Pyeongtaek-Hwaseong corridor are absorbing disproportionate volumes for HBM and 3D NAND stacks, though hybrid bonding is eroding share in leading-edge memory fabs.
- Wire Bonding:Gold and copper wire interconnect systems retain the largest installed base across legacy packaging facilities. Automotive module packaging in Germany and Japan continues specifying wire bonders for cost-sensitive power devices, yet advanced packaging for AI accelerators is compressing new equipment orders.
- Flip Chip:Solder bump and copper pillar systems enable high-density interconnects for heterogeneous integration. TSMC and UMC in Taiwan are driving replacement cycles as chiplet architectures proliferate.
- Package Bonding:System-in-package and module-level assembly equipment serves fan-out wafer-level packaging lines. China's OSATs are expanding capacity under MIIT domestic procurement quotas.
Wire bonding anchors the volume base while die attach gains share at the steepest rate.
Technology:
Cost tiers separate legacy thermal systems from premium laser platforms that command 3-4x capital intensity per bonding head.
- Thermal:Convection and conduction heating systems dominate legacy wire bonding and die attach applications. China's packaging houses favor thermal platforms for cost efficiency under dual carbon compliance cost pressures.
- Ultrasonic:Vibration-assisted bonding enables low-temperature interconnects for copper wire and ribbon applications. South Korean memory fabs specify ultrasonic systems for HBM stack assembly to minimize thermal stress on fragile TSV structures.
- Laser:Selective heating systems avoid bulk substrate thermal loading, critical for MEMS and silicon photonics packaging. Data center photonics modules in the United States and Germany are expanding addressable demand.
- Induction:Rapid localized heating suits high-throughput power device packaging. Automotive IGBT module lines in Japan and Germany specify induction bonding for throughput exceeding 10,000 units per hour.
Thermal technology anchors the volume base while laser systems climb the fastest on photonics packaging demand.
End User:
Application requirements fragment equipment specifications across verticals with divergent tolerance and traceability demands.
- Consumer Electronics:Smartphone and wearable packaging drives high-volume, cost-optimized wire bonding and flip chip demand. China's OSAT ecosystem concentrates procurement under MIIT GB standards compliance requirements.
- Automotive:Power module and sensor packaging specifies wire bonding with extended temperature range validation. Germany's KBA and Japan's METI coordinate qualification protocols that extend equipment validation timelines.
- Telecommunications:Base station and optical transceiver modules demand precision die attach for heterogeneous integration. South Korea's telecommunications infrastructure expansion is concentrating orders in the Pyeongtaek-Hwaseong corridor.
- Medical Devices:Implantable and diagnostic equipment requires CE marking under MDR with traceable calibration protocols. European and United States fabs face extended validation timelines that restrict supplier qualification.
Consumer electronics anchors the volume base while medical devices expand most quickly on diagnostic semiconductor proliferation.
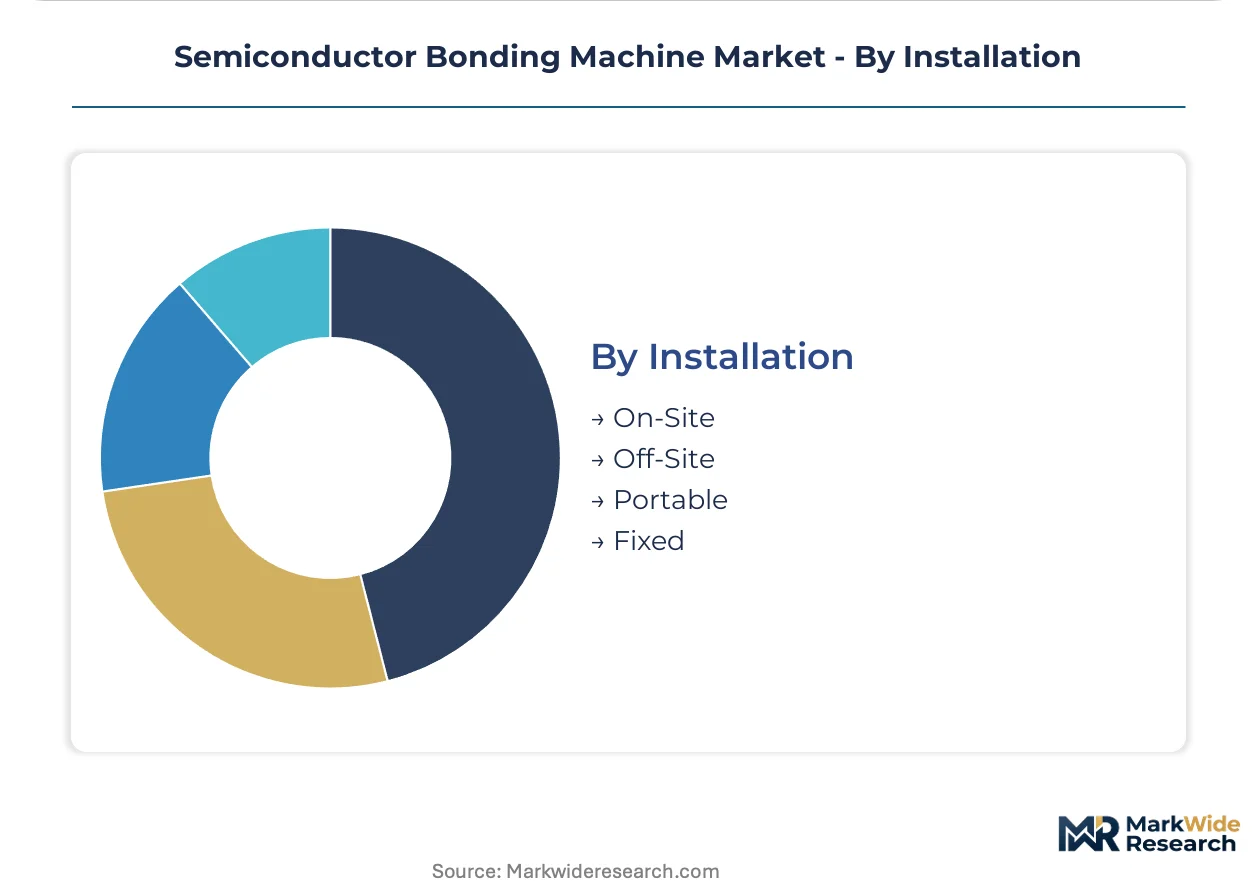
Installation:
Customer type splits between captive fabs demanding fixed installations and OSATs requiring operational flexibility.
- On-Site:Permanent integration within cleanroom facilities characterizes leading-edge memory and logic fabs. Samsung and TSMC specify on-site installation with predictive maintenance contracts unbundled from hardware procurement.
- Off-Site:Equipment housed at vendor or third-party facilities serves qualification and small-batch production needs. European equipment makers are expanding off-site service footprints under EU Chips Act capital access.
- Portable:Modular systems enable rapid redeployment across packaging lines for product mix flexibility. China's OSATs favor portable configurations to adapt to volatile demand patterns.
- Fixed:Dedicated production lines with minimal reconfiguration capability suit high-volume, stable product ramps. Automotive module packaging facilities in Germany and Japan specify fixed installations for process consistency.
Fixed installation anchors the volume base while portable configurations gain share fastest on OSAT operational flexibility demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese and South Korean equipment manufacturers export precision bonding systems to memory fabs across Taiwan and the United States, creating a concentrated trade corridor that channels capital equipment toward heterogeneous integration lines. This flow pattern shapes regional demand concentration and qualification requirements.
South Korea
Samsung and SK Hynix are scaling HBM and 3D NAND capacity in the Pyeongtaek-Hwaseong corridor, absorbing disproportionate volumes of thermocompression and hybrid bonding systems. The country's MFDS coordinates equipment qualification with export control frameworks. Memory manufacturers in Gyeonggi Province are replacing wire bonders at accelerated cycles for chiplet architectures.
Japan
Tokyo Electron and Shibaura Mechatronics anchor domestic supply chains for etch-deposition-bonding integration. METI coordinates JIS standards with METI-funded consortia, adding six to nine months to equipment qualification timelines. Nagoya-based precision engineering clusters serve automotive power module packaging lines with extended temperature range validation.
China
MIIT enforces domestic equipment procurement quotas through GB standards and dual carbon goals, redirecting bonding machine demand toward qualified domestic suppliers. The MEE enforces energy-intensity standards that raise operational expenses for manufacturing. OSATs in the Yangtze River Delta and Pearl River Delta favor portable configurations to adapt to volatile demand patterns.
United States
Applied Materials and Kulicke & Soffa serve data center photonics modules and AI accelerator packaging lines with laser bonding systems. The FDA and EPA coordinate traceable calibration protocols for medical device and environmental compliance applications. Arizona and Texas fabs are expanding heterogeneous integration capacity under CHIPS Act capital access.
Germany
BE Semiconductor Industries NV and European equipment makers target automotive IGBT module lines with induction bonding systems exceeding 10,000 units per hour. The KBA coordinates qualification protocols with Japan's METI that extend equipment validation timelines. Bavarian power electronics clusters specify fixed installations for process consistency in high-volume ramps.
Semiconductor Bonding Machine Market Competitive Landscape
Player mix skews toward precision equipment specialists with deep integration into memory and logic fab ecosystems. Consolidation pressure concentrates around three to five dominant system houses controlling hybrid bonding and thermocompression platforms. Two strategic archetypes define positioning: integrated process equipment conglomerates spanning deposition-to-bonding workflows, and pure-play bonding specialists with modular platform architectures. Competitive moves center on cross-selling into HBM fabs and unbundling predictive maintenance contracts from hardware procurement.
Among the integrated equipment houses, Tokyo Electron leverages its etch-and-deposition ecosystem to cross-sell bonding solutions into HBM fabs. BE Semiconductor Industries NV anchors its position through precision die-attach systems for heterogeneous integration. Kulicke & Soffa occupies a position in thermocompression bonding for chiplet architectures. These three exemplify the tier of vendors capturing disproportionate capital allocation as advanced packaging displaces legacy wire bonding volumes.
| Leading Market Players |
|---|
| EV Group |
| Tokyo Electron |
| BE Semiconductor Industries NV |
| Panasonic Holding Corporation |
| Shibaura Mechatronics Corporation |
| ASM Pacific Technology Ltd |
| Applied Materials |
| Fuji Corporation |
| Kulicke & Soffa |
| Others |
Value Network & Pricing Analysis
Ninety-day lead times for precision motion control subsystems concentrate supplier leverage in Japan and Germany, compressing margin buffers for wire bonding equipment makers while amplifying pricing power for hybrid bonding specialists with captive component sourcing.
Pricing Analysis
Current-generation hybrid bonding platforms command three to four times the capital intensity of prior-generation wire bonders, while next-generation laser systems for photonics packaging sit at premium tiers above both. Pricing stratifies across premium, standard, and economy tiers based on placement accuracy specifications and after-sales service bundling. Cost compression in wire bonding is intensifying because gold and copper wire input volatility pressures gross margins. Automotive module packaging facilities in Germany and Japan exhibit the highest price sensitivity due to extended validation timelines, while HBM fabs in South Korea show the least sensitivity given throughput-critical process requirements.
Supply Chain Analysis
Japan and South Korea anchor precision motion control and ceramic component fabrication, while Germany feeds specialized induction heating systems into automotive power module lines. The supply chain draws from high-purity aluminum oxide ceramics, rare-earth magnetic alloys, and sub-micron linear encoder scales. Single-source vulnerability concentrates in precision air-bearing spindle assemblies sourced from Nagoya engineering clusters. Distribution runs through direct OEM relationships with memory and logic fabs, bypassing traditional equipment distributor networks for qualification-critical installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as Samsung and SK Hynix consolidate HBM equipment procurement decisions in South Korea's Pyeongtaek-Hwaseong corridor, shifting negotiation leverage toward foundry-scale memory manufacturers and away from fragmented OSATs.
For Market Incumbents: Compound defensive positioning through backward integration into precision motion control subsystems and predictive maintenance service unbundling. Hybrid bonding technology substitution threatens wire bonding incumbents with accelerated replacement cycles. Certification investment in MIIT GB standards compliance secures access to China's domestic procurement quotas. For New Entrants and Emerging Players: Lead with laser bonding platforms targeting silicon photonics packaging white space in United States and German data center markets. Photonics module assembly lines remain underpenetrated by established wire bonding vendors. Direct engagement with photonics foundries in Arizona and Bavaria offers the clearest go-to-market path outside memory fab procurement concentration. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because equipment qualification barriers and R&D scale requirements favor three to five dominant system houses controlling hybrid bonding and thermocompression platforms. Acquisition targets should display modular platform architectures adaptable to divergent regional qualification standards. Monitor MIIT domestic procurement quota enforcement intensity as the signal for foreign equipment access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Service Unbundling | TSMC and UMC pressure vendors for uptime guarantees through sensor-embedded bonding heads. |
| Hybrid Bonding Platform Development | Samsung and SK Hynix drive accelerated replacement cycles for sub-10-micrometer interconnect pitches. |
| MIIT GB Standards Certification Investment | China's domestic procurement quotas redirect demand toward qualified local and foreign suppliers. |
| Laser Bonding System Commercialization | Silicon photonics modules in Arizona and Bavaria require selective heating to avoid optical component damage. |
| Precision Motion Control Backward Integration | Tokyo Electron leverages etch-deposition ecosystem to cross-sell bonding solutions into HBM fabs. |
Research Methodology
A spread of perspectives from fab operations directors, equipment procurement managers, precision engineering R&D leads, and aftermarket service heads converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC filings, customs equipment import records, METI-funded consortium disclosures, and MIIT GB standards documentation. Bottom-up equipment shipment tallies triangulated against top-down capital expenditure disclosures from Samsung, SK Hynix, TSMC, and UMC.
Segmentation dimensions modeled include bonding technology type, product platform generation, end-user vertical application, installation configuration, and regional qualification regime. CAGRs were derived from equipment replacement cycle analysis and capacity expansion announcements tracked across the projection horizon. Forecast inputs incorporated HBM stack layer count roadmaps, chiplet architecture adoption curves, and photonics packaging penetration rates in data center infrastructure.
The analysis sits within stated boundaries; outcomes outside sustained memory capital expenditure levels or abrupt regulatory restriction shifts would require recalibration. Forecasts reflect assumptions about heterogeneous integration adoption, dual carbon compliance cost trajectories, and export control framework stability. Recalibration cycles align with material shifts in MIIT procurement enforcement, EU Chips Act subsidy disbursement, and memory fab capacity announcement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Manufacturing
Europe Photoresist and Photoresist Ancillaries Market
Semiconductor Manufacturing
IC CMP Slurries and Pads Market
Semiconductor Manufacturing
Chip Melting Furnace Market
Semiconductor Manufacturing
Malaysia and Thailand Precession Cleaning for Electronic Market
Semiconductor Manufacturing
Silicon Turners Market
Semiconductor Manufacturing
Battery Manufacturing Machines Market
Semiconductor Manufacturing
Semiconductor and Circuit Manufacturing Market
Semiconductor Manufacturing
Semiconductor Polishing Pads Market
Semiconductor Manufacturing
Photomask Market
Semiconductor Manufacturing
Global EUV Lithography Market
Semiconductor Manufacturing
Semiconductor and Electronic Parts Manufacturing Market
Semiconductor Manufacturing
United States Photoresist and Photoresist Ancillaries Market
Semiconductor Manufacturing
Global Overall EUV Lithography Market
Semiconductor Manufacturing
Electronic Manufacturing Services (EMS) Market
Semiconductor Manufacturing
Medical Component Manufacturing Market
Semiconductor Manufacturing
Photoresist Stripper Market