
 High Purity Process Systems for Semiconductor Market | 2026-2036
High Purity Process Systems for Semiconductor Market Size, Share, and Industry Trends Forecast 2026-2036
High Purity Process Systems for Semiconductor Market Insights
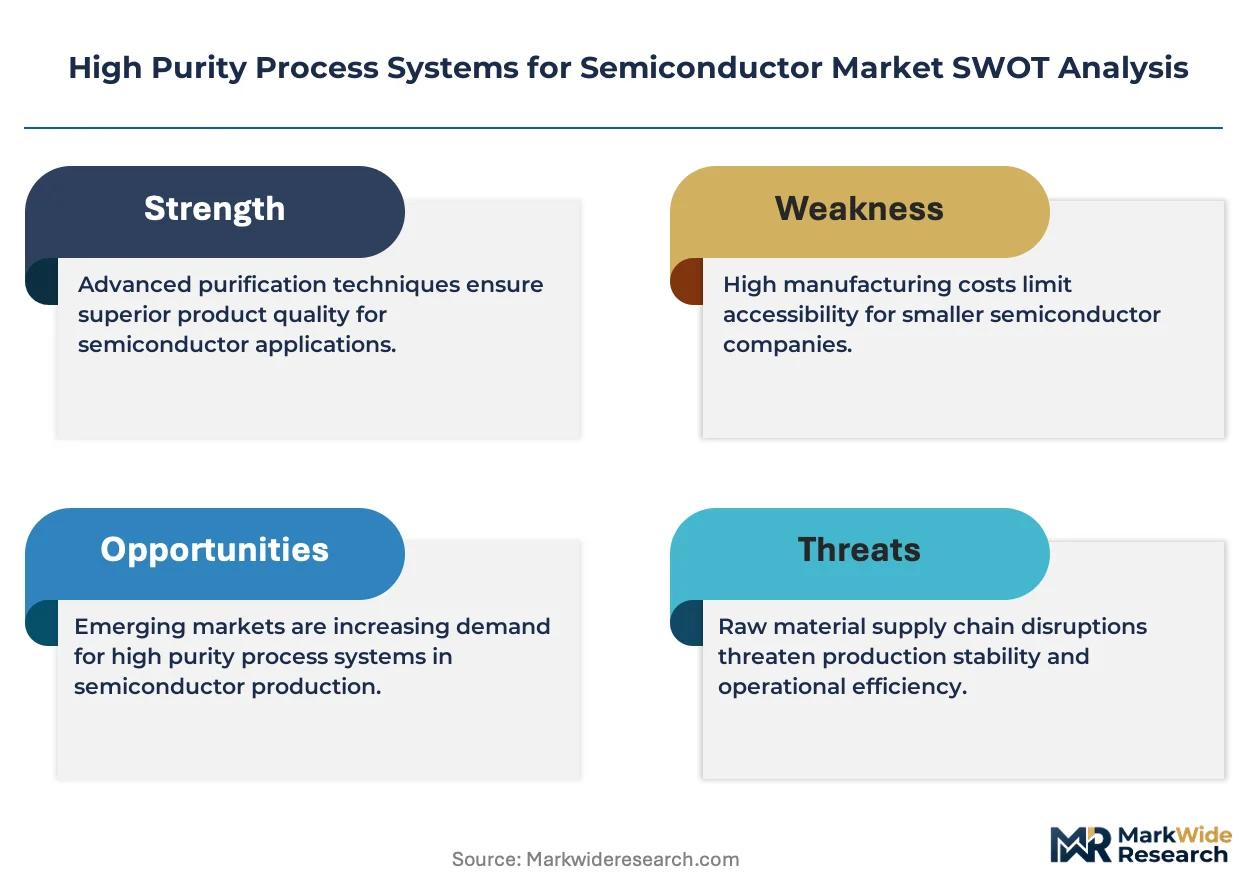
Foundry customer concentration is expanding as advanced node production consolidates among a handful of megafabs, pulling high-purity system procurement into larger, more technically demanding contracts. Kinetics Process Systems leverages its installed base across Korean and Taiwanese fabs to sustain recurring upgrade revenue. Entegris anchors its position through captive materials science expertise that extends into chemical delivery architecture. Swagelok competes on component standardization, dominating critical fitting and valve categories that underpin system integrity.
High purity process systems for semiconductor manufacturing encompass integrated fluid handling architectures designed to deliver chemicals, gases, and water at contamination levels measured in parts per trillion, with surface roughness specifications below 10 Ra microinches and electropolished 316L stainless steel construction. These systems prevent particle-induced yield loss during wafer fabrication, photolithography, and chemical mechanical planarization. Gas delivery systems command the deepest margin pools due to specialty gas complexity and safety enclosure requirements, while membrane filtration technology leads equipment attach rates as node shrinkage intensifies purity thresholds. Chemical delivery systems show the fastest structural growth trajectory, driven by escalating solvent volumes in multi-patterning schemes.
The EPA enforces stringent effluent and airborne emissions limits on semiconductor chemical processing, compelling fabs to deploy closed-loop purification modules and vapor recovery systems. Taiwan's Industrial Development Bureau coordinates local content requirements and technical standards that shape supplier qualification pathways for domestic foundry expansions. OSHA process safety management rules govern hazardous chemical inventory thresholds, directly influencing system automation and secondary containment specifications. Stakeholders must monitor how regulatory divergence between East Asian manufacturing hubs and Western environmental frameworks reshapes system design standardization and certification burdens.
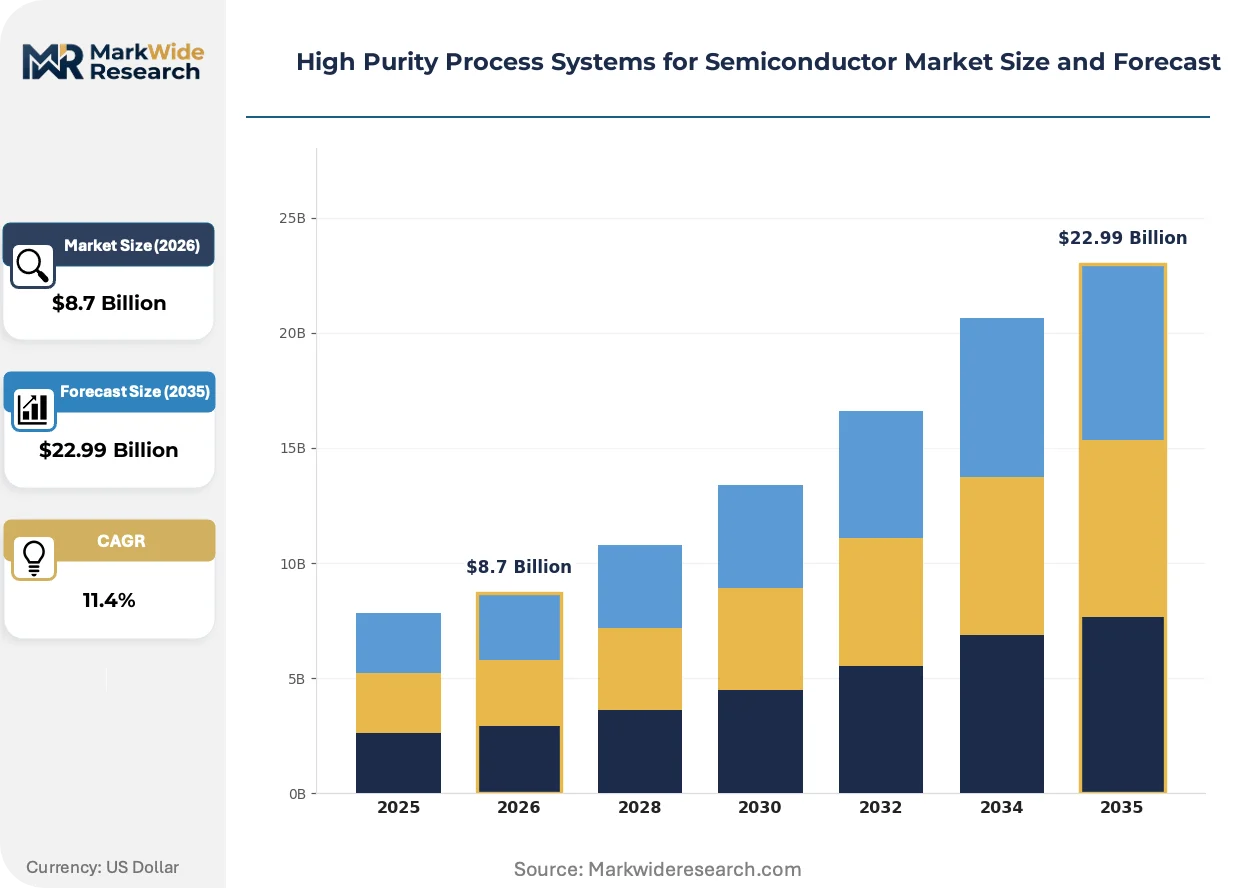
Market Dynamics
Sub-3nm node migration is compressing contamination tolerance thresholds from parts per billion to parts per trillion, forcing simultaneous upgrades across gas, chemical, and ultrapure water delivery architectures in advanced foundries.
Growth Catalysts
- EPA Effluent Guidelines:Tighter semiconductor manufacturing discharge limits in the United States mandate closed-loop chemical recovery systems, pulling forward replacement cycles for legacy open-loop infrastructure.
- Multi-patterning solvent volumes:EUV lithography limitations at sub-5nm nodes require quadruple and quintuple patterning sequences, multiplying chemical consumption per wafer pass.
- Taiwan cluster densification:Foundry capacity concentration in Hsinchu and Tainan Science Parks creates localized demand spikes that outpace equipment installation lead times.
Market Restraints
- 316L stainless steel supply concentration:Electropolished tubing and fitting feedstock production clusters in Japan and Germany, exposing procurement to single-source vulnerability.
- Specialty gas cylinder handling:OSHA Process Safety Management thresholds for toxic gas inventory trigger mandatory automation investments that add 15-25% to system capital cost.
- Fluoropolymer membrane lead times:PFA and PTFE filtration media face 26-40 week delivery windows, constraining system integrator throughput.
Strategic Opportunities
- India semiconductor incentive corridor:Gujarat and Karnataka fab subsidies under the PLI scheme create first-mover advantage for high-purity system qualification at greenfield sites.
- Hydrogen peroxide reclamation:Closed-loop purification modules for SC-1 and SC-2 cleaning chemistries reduce virgin chemical purchase by 30-40% at mature nodes.
- Digital twin integration:Real-time contamination monitoring converging with predictive maintenance software enables outcome-based service pricing for gas delivery infrastructure.
Industry Challenges
- Electropolishing technician scarcity:Surface finish certification for 10 Ra microinch specifications requires specialized welders and quality engineers with 5+ years fab experience.
- Legacy system interoperability:200mm and 300mm fab retrofits demand custom manifold bridging to connect new high-purity skids with existing facility chemical distribution headers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Purity Process Systems for Semiconductor Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultra-Pure Water Systems, Gas Delivery Systems, Chemical Delivery Systems, Filtration Units, Purification Modules Technology: Membrane Filtration, Ion Exchange, Vacuum Ultraviolet Oxidation, Liquid Chromatography, Electro-Deionization Application: Wafer Fabrication, Photolithography, Chemical Mechanical Planarization, Thin Film Deposition, Etching Processes End User: Foundries, Integrated Device Manufacturers, Outsourced Assembly Providers, Equipment Manufacturers, Specialized Test Facilities |
| Companies Covered | Kinetics Process Systems, Marketech International Corp., Morimatsu, PNC Technology Group, Shanghai GenTech, Swagelok, Parker Hannifin, Entegris, SMC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Purity Process Systems for Semiconductor Market Trends and Innovations
Point-of-use purification architectures are displacing centralized bulk distribution models, fragmenting system design authority from major integrators toward component specialists and fab engineering teams.
Modular gas panel assemblies with embedded mass flow controllers and pressure transducers are decentralizing specialty gas delivery from centralized bulk gas yards to individual process tool connections. Advanced logic foundries in Taiwan and South Korea are specifying these plug-and-play subsystems for 40% of new tool hookups. This architecture compresses installation timelines from 12 weeks to 4 weeks while reducing leak-test failure rates by decentralizing connection points across smaller, factory-tested modules.
REACH F-Gas Regulation amendments are phasing down sulfur hexafluoride and perfluorocarbon use in etch and chamber clean processes, forcing gas delivery system redesigns for fluorine-based alternatives. Equipment suppliers must recertify wetted materials compatibility for NF3 and F2/N2 mixtures. European memory manufacturers are accelerating this transition ahead of the 2030 phase-down deadlines, creating specification divergence from Asian foundry standards.
Lifecycle service contracts are unbundling from initial equipment purchase, with foundries negotiating separate multi-year agreements for filter replacement, calibration, and regulatory compliance documentation. Korean megafabs are leading this shift, separating capex and opex procurement decisions. This bifurcation pressures system integrators to build captive service organizations or cede recurring revenue to third-party maintenance specialists.
High Purity Process Systems for Semiconductor Market Segmentation
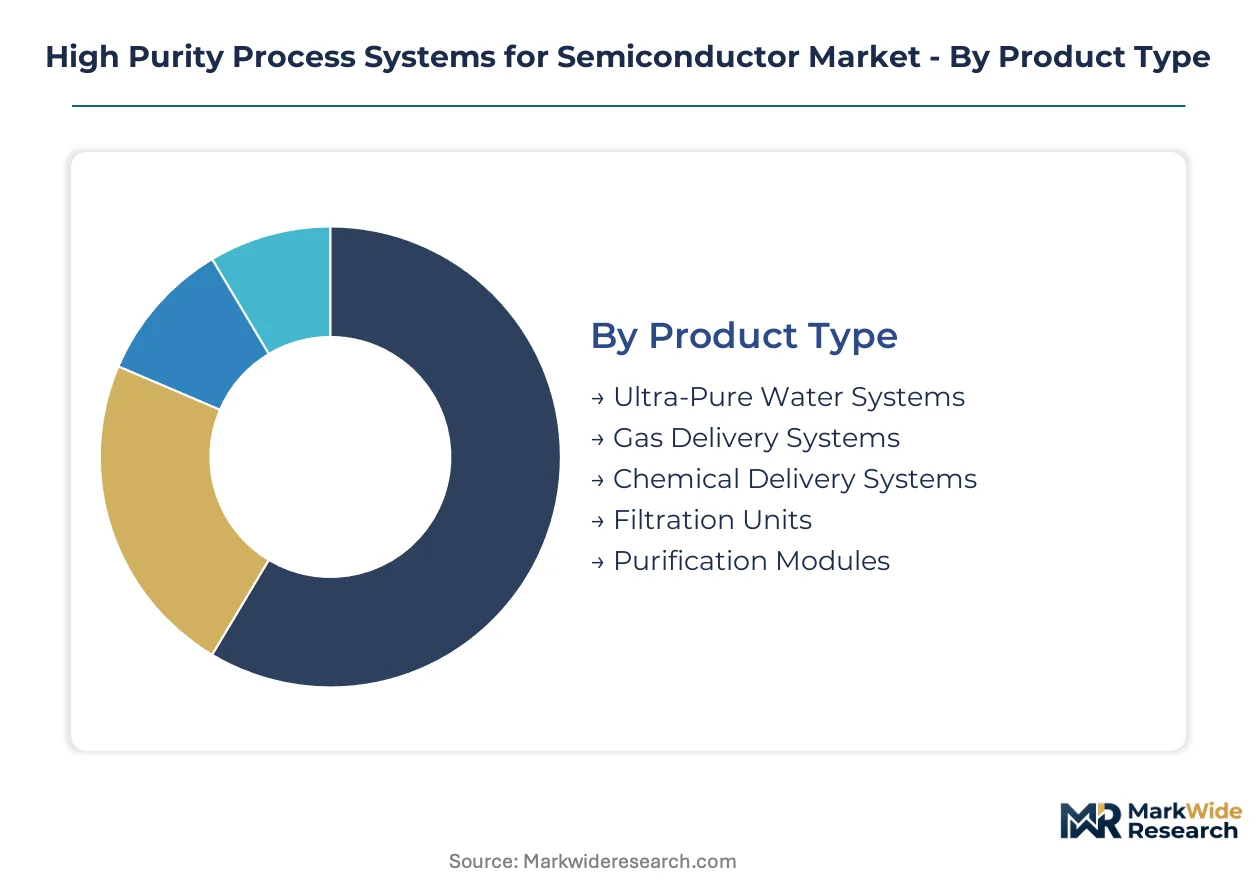
High purity process system procurement fragments across multiple technical and commercial dimensions, with product architecture and contamination control methodology determining qualification pathways and margin structures. Each segmentation axis reveals distinct competitive dynamics, from the capital intensity of gas delivery infrastructure to the service intensity of filtration consumables.
Product Type:
Volume concentrates in water and chemical handling infrastructure, while premium margins pool in gas delivery and point-of-use purification where safety enclosures and materials science expertise create defensive positions.
- Gas Delivery Systems:These architectures manage specialty gases at sub-atmospheric pressures through electropolished 316L stainless steel manifolds with redundant containment. Taiwan's advanced logic foundries specify these for 40% of new tool hookups as sub-3nm nodes tighten particulate specifications. The deepest margin pools in this segment reflect fluorine-based gas handling complexity and NF3 compatibility recertification burdens under REACH F-Gas amendments.
- Chemical Delivery Systems:Solvent distribution skids with secondary containment and automated valve manifolds handle escalating volumes from multi-patterning schemes. Korean megafabs are scaling quadruple and quintuple patterning sequences that multiply chemical consumption per wafer pass, pulling demand toward modular architectures with faster installation timelines.
- Ultra-Pure Water Systems:Multi-stage purification trains producing 18.2 MΩ·cm resistivity water for wafer cleaning and rinsing operations.
- Filtration Units:PFA and PTFE membrane housings for particle removal at 0.003 μm ratings, constrained by 26-40 week media lead times.
- Purification Modules:Closed-loop recovery systems for hydrogen peroxide reclamation in SC-1 and SC-2 cleaning chemistries.
Today's leader: Gas Delivery Systems. Tomorrow's challenger: Chemical Delivery Systems.
Technology:
Membrane-based approaches dominate installed capacity, while advanced oxidation and electro-chemical methods are gaining specification at leading-edge nodes where legacy ion exchange reaches purity limits.
- Membrane Filtration:Cross-flow ultrafiltration and reverse osmosis membranes remove dissolved organics and colloidal silica from process fluids. This technology leads equipment attach rates as node shrinkage intensifies purity thresholds, with Taiwanese foundries specifying tighter pore ratings for each process node migration.
- Vacuum Ultraviolet Oxidation:Low-pressure mercury lamps generating 185 nm and 254 nm wavelengths photolyze trace organics and chlorine species without chemical addition. Advanced logic fabs in South Korea are deploying these upstream of final polishing loops to reduce ion exchange resin consumption and extend regeneration cycles.
- Ion Exchange:Mixed-bed and separate-bed resin vessels for cation and anion removal in ultrapure water production.
- Electro-Deionization:Continuous electrodeionization cells combining ion exchange membranes with electrical regeneration, eliminating acid and caustic handling.
- Liquid Chromatography:High-performance separation for trace metal analysis and process chemistry validation in specialty gas certification.
Membrane Filtration anchors current procurement volumes. Vacuum Ultraviolet Oxidation is climbing the fastest as resin cost and waste discharge regulations tighten.
Application:
Wafer fabrication commands the largest equipment footprint, while photolithography and planarization drive the most stringent contamination specifications due to pattern fidelity requirements.
- Wafer Fabrication:Bulk chemical and gas distribution serving diffusion, oxidation, and implant process bays across 300mm and emerging 450mm formats. This application absorbs the broadest system integration scope, from bulk chemical storage to point-of-use purification, with Korean megafabs consolidating procurement into fewer, larger contracts.
- Photolithography:Ultrapure water and specialty gas delivery for resist coating, exposure, and developing operations at sub-5nm resolution. Taiwan's Hsinchu Science Park cluster concentrates demand here, where particle-induced defects translate directly to yield loss at $15,000+ wafer values.
- Chemical Mechanical Planarization:Slurry distribution and post-CMP cleaning chemistry handling for dielectric and metal layer polishing.
- Thin Film Deposition:Precursor gas delivery for atomic layer deposition and chemical vapor deposition chambers.
- Etching Processes:Halogen-based gas handling for plasma and wet etch operations, subject to EPA effluent guidelines and OSHA Process Safety Management thresholds.
Wafer Fabrication captures the widest system scope. Photolithography is gaining specification intensity fastest as EUV multi-patterning proliferates.
End User:
Foundry concentration is restructuring procurement authority, with IDMs and outsourced assembly providers following technical specifications set by Taiwan and Korean megafabs.
- Foundries:Pure-play contract manufacturers operating at 5nm and below, including TSMC, Samsung Foundry, and Intel Foundry Services. These end users are unbundling lifecycle service contracts from initial equipment purchase, separating capex and opex procurement decisions and pressuring integrators to build captive service organizations.
- Integrated Device Manufacturers:Vertically integrated semiconductor producers with captive fabrication for memory and logic products. IDMs in the United States face EPA semiconductor manufacturing discharge limits that mandate closed-loop chemical recovery systems, pulling forward replacement cycles for legacy open-loop infrastructure.
- Outsourced Assembly Providers:OSATs handling packaging and test operations with lower purity requirements than front-end fabrication.
- Equipment Manufacturers:Lam Research, Applied Materials, and Tokyo Electron specifying gas panel subsystems for tool integration.
- Specialized Test Facilities:Reliability and failure analysis labs requiring high-purity chemistry for destructive and non-destructive testing protocols.
Foundries set the technical pace. Integrated Device Manufacturers are expanding fastest as Intel and Samsung accelerate captive capacity additions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States fabs face stricter EPA effluent mandates than their Taiwanese counterparts, yet both markets are scaling sub-3nm capacity that demands synchronized upgrades across gas, chemical, and ultrapure water infrastructure.
United States
Intel Foundry Services and emerging domestic foundries are expanding Arizona and Ohio fabrication campuses. EPA semiconductor manufacturing discharge limits under the Clean Water Act mandate closed-loop chemical recovery systems that pull forward replacement cycles for legacy open-loop infrastructure. Phoenix and Columbus metro areas concentrate equipment procurement timelines as construction outpaces qualified installer availability.
Taiwan
TSMC and United Microelectronics Corporation are densifying capacity in Hsinchu and Tainan Science Parks. Taiwan's Industrial Development Bureau coordinates local content requirements and technical standards that shape supplier qualification pathways for domestic foundry expansions. Kaohsiung's emerging advanced packaging cluster is generating secondary demand for high-purity chemical delivery retrofitting.
South Korea
Samsung Foundry and SK Hynix are accelerating Pyeongtaek and Yongin campus expansions for 2nm-class production. Korean megafabs are unbundling lifecycle service contracts from initial equipment purchase, separating capex and opex procurement decisions. Seoul Capital Area foundry concentration is compressing installation lead times below 16 weeks for qualified system integrators.
Japan
Tokyo Electron and Shin-Etsu Chemical are expanding domestic 300mm silicon wafer and equipment component production. METI's semiconductor supply chain resilience subsidies under the Economic Security Promotion Act are redirecting capital toward domestic high-purity tubing and fitting fabrication. Kyushu's Kumamoto prefecture is attracting TSMC-Japan joint venture fabs that import Taiwanese technical specifications.
China
SMIC and Hua Hong Semiconductor are expanding mature-node capacity in Shanghai and Wuxi despite advanced lithography equipment restrictions. MIIT domestic substitution mandates are accelerating qualification of local high-purity system component suppliers. Yangtze River Delta cluster concentration is creating specification divergence between import-dependent and domestic-sourced infrastructure.
High Purity Process Systems for Semiconductor Market Competitive Landscape
East Asian producers anchor one tier; North American and European specialists hold defensive positions in component categories and materials science integration. The vendor base stratifies across three tiers: integrated system architects, component standardization leaders, and regional installation specialists. Strategic archetypes include captive materials science extenders, modular subsystem disaggregators, and service revenue unbundlers. M&A activity concentrates on filtration media and electropolishing capability acquisition; geographic expansion targets Indian and Southeast Asian greenfield qualifications.
Within the integrated system tier, Kinetics Process Systems and Entegris exemplify divergent approaches to customer captivity. Kinetics leverages its installed base across Korean and Taiwanese fabs to sustain recurring upgrade revenue through proximity-based service organizations. Entegris anchors its positioning through captive materials science expertise that extends into chemical delivery architecture rather than pure equipment fabrication. Among component specialists, Swagelok occupies a position defined by fitting and valve standardization that underpins system integrity across multiple integrator supply chains. These three companies represent the competitive spectrum from geographic embedding to technical specification control.
| Leading Market Players |
|---|
| Kinetics Process Systems |
| Marketech International Corp. |
| Morimatsu |
| PNC Technology Group |
| Shanghai GenTech |
| Swagelok |
| Parker Hannifin |
| Entegris |
| SMC Corporation |
| Others |
Pricing and Supply Chain Analysis
Captive electropolishing capacity in Japanese and German specialty metals mills anchors both supply security and pricing power for high-purity system integrators, creating tiered procurement structures where fabs with long-term offtake agreements secure preferential 316L stainless steel allocation while spot buyers absorb volatility.
Pricing Analysis
Capacity additions in South Korea and Taiwan are reshaping price floors for gas delivery systems as Samsung Foundry and TSMC consolidate procurement into fewer, larger contracts. Three-tier pricing structure across premium, standard, and economy levels separates foundry-grade specifications from IDM retrofits and mature-node expansions. Cost compression in chemical delivery skids is intensifying because modular architectures reduce installation labor content. IDMs in the United States show highest price sensitivity due to EPA-mandated closed-loop upgrades that strain capital budgets, while Taiwanese megafabs prioritize specification compliance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Japanese electropolished tubing producers and German precision fitting manufacturers, exposing system integrators to 26-40 week delivery windows for critical feedstock. Raw material flows draw from nickel ore processing in Indonesia, chromium refining in South Africa, and fluoropolymer resin production in the United States. Tariff exposure on 316L stainless steel semis imported into Taiwan and South Korea elevates landed costs for non-captive fabricators. Distribution runs through qualified system integrators with fab-proximity service organizations, bypassing traditional industrial distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as sub-3nm node migration forces simultaneous upgrades across gas, chemical, and ultrapure water delivery architectures, shifting procurement authority toward specification-intensive contracts that reward materials science expertise over equipment fabrication scale.
For Market Incumbents: Extend captive service organizations into predictive maintenance platforms before third-party specialists capture recurring revenue streams. Deepen backward integration into PFA membrane media production to insulate margins from 26-40 week fluoropolymer lead times. Secure electropolishing technician pipelines through apprenticeship partnerships with Korean and Taiwanese technical institutes.
For New Entrants and Emerging Players: Enter via hydrogen peroxide reclamation modules for mature-node fabs seeking 30-40% virgin chemical cost reduction, a segment where incumbent chemical delivery specialists lack dedicated purification expertise. Target India's Gujarat and Karnataka greenfield sites under PLI scheme subsidies, where first-mover qualification creates multi-year procurement lock-in. Lead with digital twin integration for real-time contamination monitoring as a differentiated service layer.
For Investors and Strategic Acquirers: Roll-up economics work for regional installation specialists with fab-proximity service density because Korean megafabs are unbundling lifecycle contracts from initial equipment purchase, fragmenting incumbent service monopolies. Five-to-ten year viability hinges on capturing recurring filter replacement and calibration revenue rather than one-time system sales. Watch for REACH F-Gas recertification burdens accelerating NF3-compatible gas panel demand as the inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Media | Captive PFA membrane production insulates margins from 26-40 week supplier lead times. |
| Digital Twin Platform Development | Real-time contamination monitoring enables outcome-based service pricing for gas delivery infrastructure. |
| Electropolishing Technician Apprenticeships | Pipeline development addresses 5+ year certification scarcity constraining 10 Ra microinch surface finish capacity. |
| India Greenfield Site Qualification | First-mover positioning under PLI scheme subsidies creates procurement lock-in at emerging Gujarat and Karnataka fabs. |
| Closed-Loop Chemical Recovery Module Launch | EPA effluent guidelines mandate upgrades that pull forward replacement cycles for legacy open-loop infrastructure. |
Research Methodology
Multiple input streams — primary interviews with fab engineering directors and high-purity system procurement managers, secondary validation through SEMI equipment market databases and EPA semiconductor manufacturing discharge filings, and customs trade data on 316L stainless steel and fluoropolymer imports — were reconciled to construct bottom-up and top-down triangulations. Conversations with gas delivery subsystem specialists, chemical handling safety officers, and point-of-use filtration integrators provided qualification pathway and installation timeline ground-truthing.
Historical capacity expansion patterns were cross-referenced against panel input from equipment procurement executives at TSMC, Samsung Foundry, and Intel Foundry Services to anchor projection assumptions across the analysis window. Segmentation dimensions modeled include product architecture, contamination control technology, wafer fabrication application, and end-user procurement authority structure. CAGRs were derived from node migration intensity, regulatory compliance cost trajectories, and materials science capability scarcity.
Inputs from foundry capital expenditure disclosures and science park construction permits were available through the study window; gaps in proprietary chemical consumption per wafer metrics introduce uncertainty bands around chemical delivery system attach rate assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Manufacturing
Solar Laser Drilling Market
Semiconductor Manufacturing
Global Overall EUV Lithography Market
Semiconductor Manufacturing
Global Wafer Cutting Fluids Market
Semiconductor Manufacturing
Stencil Lithography Market
Semiconductor Manufacturing
Chip Melting Furnace Market
Semiconductor Manufacturing
Photomask Market
Semiconductor Manufacturing
China Electronic Design Automation (EDA) Tools Market
Semiconductor Manufacturing
Advanced Process Control Market
Semiconductor Manufacturing
PCB Photoresist Market
Semiconductor Manufacturing
Europe Electronic Manufacturing Services Market
Semiconductor Manufacturing
Malaysia and Thailand Precession Cleaning for Electronic Market
Semiconductor Manufacturing
Photoresist and Photoresist Ancillaries Market
Semiconductor Manufacturing
Medical Component Manufacturing Market
Semiconductor Manufacturing
Electronic Manufacturing Services (EMS) Market
Semiconductor Manufacturing
Semiconductor Bonding Machine Market
Semiconductor Manufacturing
EUV Lithography Service Market