
 Semiconductor and Electronic Parts Manufacturing Market | 2026-2036
Semiconductor and Electronic Parts Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor and Electronic Parts Manufacturing Market Analytics
Modular chiplet packaging is hardening as the dominant product-configuration choice for advanced processors, letting buyers mix compute, memory, and I/O dies from different process nodes. Taiwan Semiconductor Manufacturing Co. Ltd. leverages its CoWoS and InFO platforms to anchor high-performance packaging demand. Samsung Electronics Co. Ltd. competes through its X-Cube 3D stacking technology, while Intel Corp. extends its Foveros direct bonding approach to regain manufacturing leadership.
Semiconductor and electronic parts manufacturing encompasses the fabrication of integrated circuits, discrete devices, sensors, and optoelectronic components on silicon, gallium arsenide, and emerging wide-bandgap substrates such as silicon carbide, with feature sizes now reaching angstrom-scale precision for logic and memory functions. The primary purpose spans computation, signal processing, power management, and sensing across virtually all electronic systems. Integrated circuits command the largest value pool, while sensors represent the fastest-expanding segment as IoT and automotive electrification multiply sensing nodes. Analog and mixed-signal technologies sustain higher margins than commodity digital logic, reflecting longer product lifecycles and specialized design expertise.
The EPA governs hazardous chemical discharge from fabrication facilities in the United States, while REACH restricts substance use across European supply chains, and China's MEE enforces wastewater and emissions standards for domestic foundries. These frameworks elevate compliance costs but also create market access barriers that favor scaled manufacturers with dedicated environmental, health, and safety infrastructure. Stakeholders must monitor how diverging substance restrictions and carbon-border adjustments reshape sourcing decisions and capital allocation across the value chain.
Market Dynamics
Modular chiplet architectures are fragmenting monolithic processor design, forcing foundries to compete on advanced packaging yield rather than node density alone. This structural shift redistributes value from pure-play logic fabrication toward heterogeneous integration capabilities.
Growth Catalysts
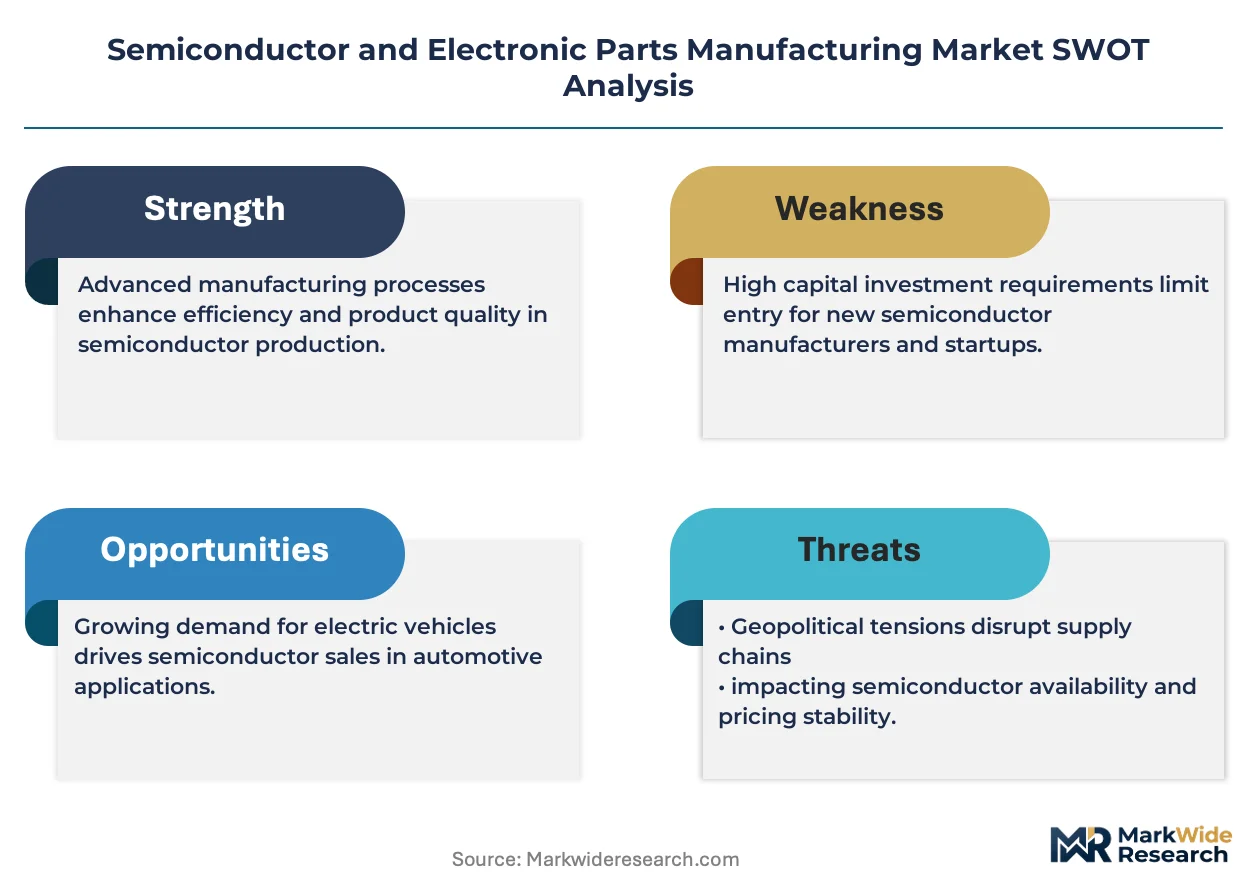
- EU Chips Act capital allocation:The framework redirects public and private investment toward domestic EU fabrication capacity, reducing import dependency for automotive and industrial chips.
- Electric vehicle power electronics:Silicon carbide substrates for traction inverters and onboard chargers are pulling wide-bandgap capacity expansion across multiple foundry networks.
- Advanced packaging demand:High-bandwidth memory integration with logic dies through 2.5D and 3D stacking is consuming disproportionate backend capacity in Taiwan and South Korea.
Market Restraints
- Extreme ultraviolet lithography cost structure:ASML's monopoly on EUV tools concentrates capital intensity among three viable purchasers, elevating breakeven volume thresholds for leading-edge nodes.
- Neon and palladium supply concentration:Ukrainian and Russian sourcing of high-purity noble gases and catalyst metals exposes lithography and plating operations to geopolitical disruption.
- REACH substance restrictions:The European framework limits per- and polyfluoroalkyl substance use in etching and cleaning chemistries, forcing process requalification across EU-serving supply chains.
Strategic Opportunities
- India's semiconductor PLI scheme:The production-linked incentive program is attracting display driver and mature-node logic assembly to Gujarat and Tamil Nadu.
- Photonics-electronics convergence:Silicon photonics integration with CMOS logic is opening optical interconnect markets for data center and telecommunications equipment.
- Direct-to-OEM component sourcing:Automotive and aerospace buyers are establishing qualified supplier programs that bypass traditional distribution tiers for critical chips.
Industry Challenges
- Process engineer scarcity:The specialized knowledge required for atomic-layer deposition and selective epitaxy outstrips university pipeline output in the United States, Germany, and Japan.
- Cleanroom construction timelines:Multi-year facility qualification cycles for ISO Class 1 environments delay capacity response to demand surges in logic and memory segments.
- IP fragmentation in chiplet interfaces:Proprietary die-to-die communication standards from Intel, AMD, and UCIe consortium members complicate multi-vendor integration roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor and Electronic Parts Manufacturing Market |
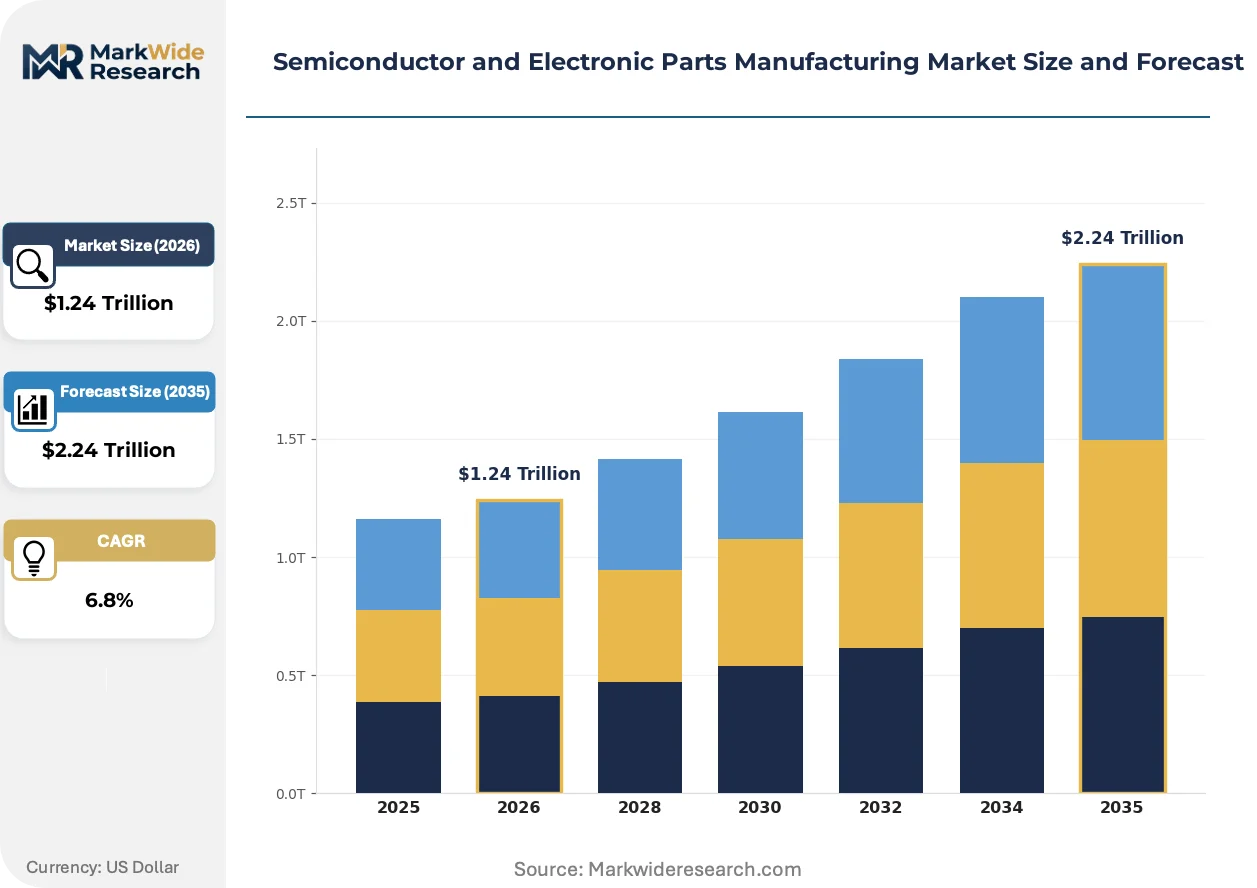
| Market Size in 2026 | $1.24 Trillion |
| Market Size in 2035 | $2.24 Trillion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Discrete Semiconductors, Integrated Circuits, Sensors, Optoelectronics Technology: Analog, Digital, Mixed-Signal, RF End User: Consumer Electronics, Automotive Components, Industrial Applications, Telecommunications Packaging Type: Through-Hole, Surface Mount, Chip-On-Board, Ball Grid Array |
| Companies Covered | Taiwan Semiconductor Manufacturing Co. Ltd., Samsung Electronics Co. Ltd., Intel Corp., SK Hynix Inc., Micron Technology Inc., Qualcomm Technologies Inc., Broadcom Inc., Texas Instruments Inc., Nvidia Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor and Electronic Parts Manufacturing Market Evolving Landscape
Silicon photonics and heterogeneous integration are compressing traditional boundaries between electrical and optical signal processing. These shifts demand new metrology, packaging, and thermal management capabilities across the value chain.
Gallium nitride power semiconductors are converging with silicon carbide in electric vehicle onboard chargers and DC-DC converters. Tier 1 automotive suppliers are dual-sourcing both wide-bandgap technologies to optimize cost-performance tradeoffs across vehicle classes. This convergence is compressing the addressable market for silicon-based insulated-gate bipolar transistors in traction applications.
China's MEE wastewater discharge standards are tightening effluent limits for fluoride and heavy metal content from wafer fabrication facilities. Domestic foundries in Shanghai and Beijing are retrofitting abatement systems to maintain operating permits. Memory and logic producers serving export markets face parallel compliance burdens from REACH substance restrictions in Europe.
Automotive OEMs are consolidating semiconductor procurement under direct long-term supply agreements rather than tiered supplier arrangements. Volkswagen, Toyota, and Ford have established dedicated chip sourcing offices in Taiwan and South Korea. This pattern is most visible in battery electric vehicle programs where power electronics content per vehicle exceeds internal combustion platforms by substantial margins.
Semiconductor and Electronic Parts Manufacturing Market Segmentation
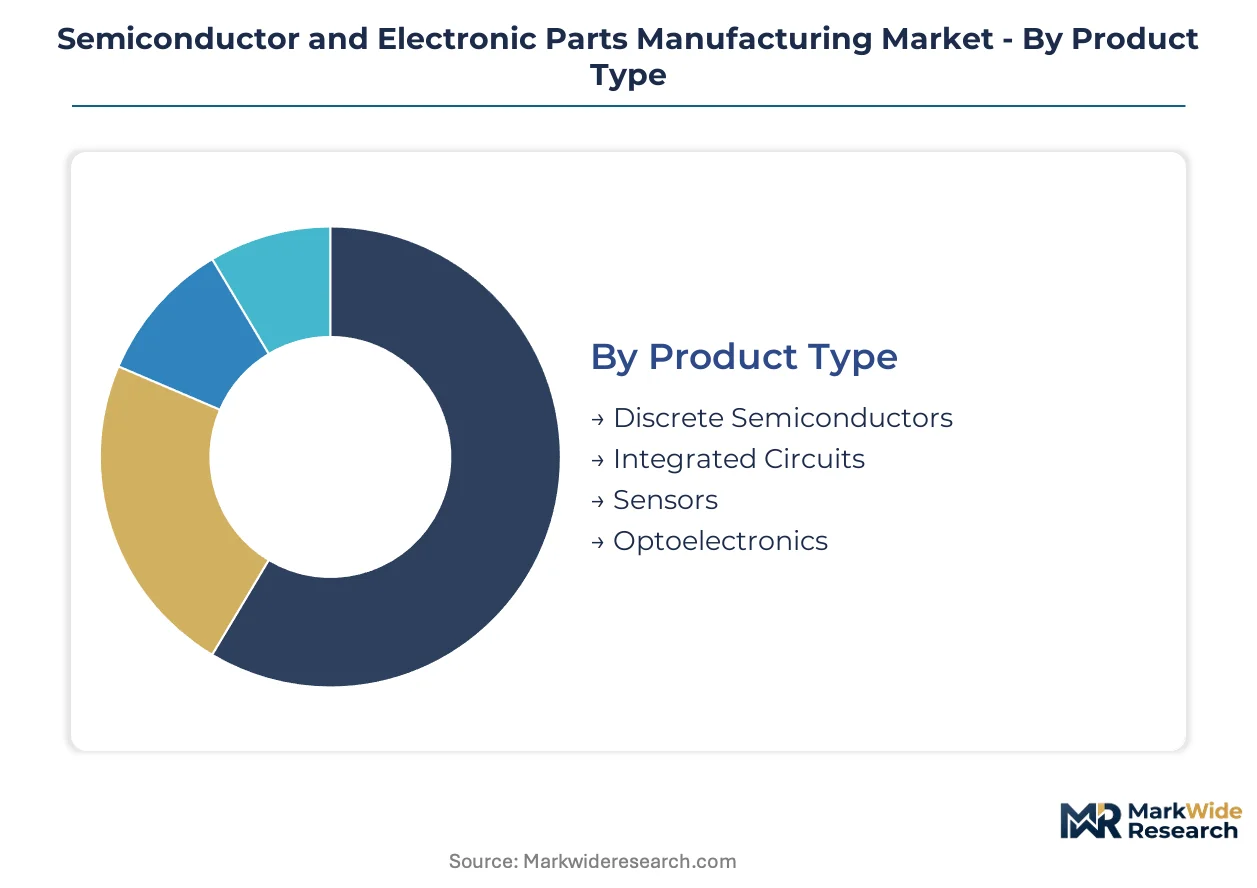
Semiconductor and electronic parts manufacturing fragments across multiple technical and commercial dimensions. Each segmentation axis reveals distinct capital requirements, margin structures, and competitive dynamics that shape supplier positioning and buyer procurement strategies.
Product Type:
Integrated circuits demand the heaviest upfront investment, with leading-edge fabrication facilities requiring multi-billion dollar commitments for EUV lithography and cleanroom infrastructure.
- Integrated Circuits:Logic and memory dies fabricated at nanometer-scale precision serve as the computational backbone for servers, smartphones, and data center infrastructure. Taiwan and South Korea foundries concentrate leading-edge capacity, while automotive-grade mature nodes face allocation constraints from consumer electronics demand.
- Sensors:MEMS accelerometers, pressure transducers, and environmental monitors integrate mechanical and electronic functions on silicon substrates. Electric vehicle battery management systems and industrial IoT deployments in Germany and Japan are pulling capacity from Bosch, STMicroelectronics, and TDK fabrication lines.
- Discrete Semiconductors:Individual transistors, diodes, and rectifiers handle power switching and signal conditioning at lower integration levels.
- Optoelectronics:LEDs, laser diodes, and photodetectors convert between electrical and optical signals for communications and sensing applications.
Integrated circuits absorb the bulk of installed capacity; sensors are expanding most quickly.
Technology:
Analog and mixed-signal segments sustain higher margins through longer product lifecycles and specialized design expertise that resists commoditization.
- Mixed-Signal:Circuits combining analog sensing with digital processing enable power management ICs and audio codecs for mobile devices. Automotive 48V mild-hybrid systems and USB-C power delivery controllers in US and European designs are pulling capacity from Texas Instruments and Analog Devices fabrication networks.
- Analog:Continuous signal processing for power conversion, amplification, and filtering operates across voltage and frequency ranges. Industrial motor drives and solar inverters in China and India are consuming operational amplifier and voltage regulator output from ON Semiconductor and Infineon production lines.
- Digital:Binary logic for computation and storage scales through process node advancement.
- RF:Radio frequency circuits for wireless communications operate at gigahertz frequencies.
Mixed-signal commands premium pricing; RF is climbing the fastest on 5G infrastructure and automotive radar demand.
End User:
Automotive components impose the most stringent qualification requirements, with AEC-Q100 stress testing and ISO 26262 functional safety certification creating multi-year supplier approval timelines.
- Automotive Components:Power electronics, sensor arrays, and domain controllers for electric and autonomous vehicles. Battery electric vehicle platforms from Volkswagen, Toyota, and Ford are sourcing silicon carbide MOSFETs and gate drivers directly from Taiwan and South Korea foundries, bypassing traditional tiered distribution.
- Consumer Electronics:Smartphones, laptops, and wearables drive volume demand for advanced logic and memory. Apple's procurement in Taiwan and Qualcomm's foundry commitments in South Korea are concentrating leading-edge capacity allocation for mobile application processors.
- Industrial Applications:Factory automation, robotics, and process control systems.
- Telecommunications:Baseband processors, optical transceivers, and network infrastructure equipment.
Consumer electronics absorbs the bulk of leading-edge wafer starts; automotive components are expanding most quickly.
Packaging Type:
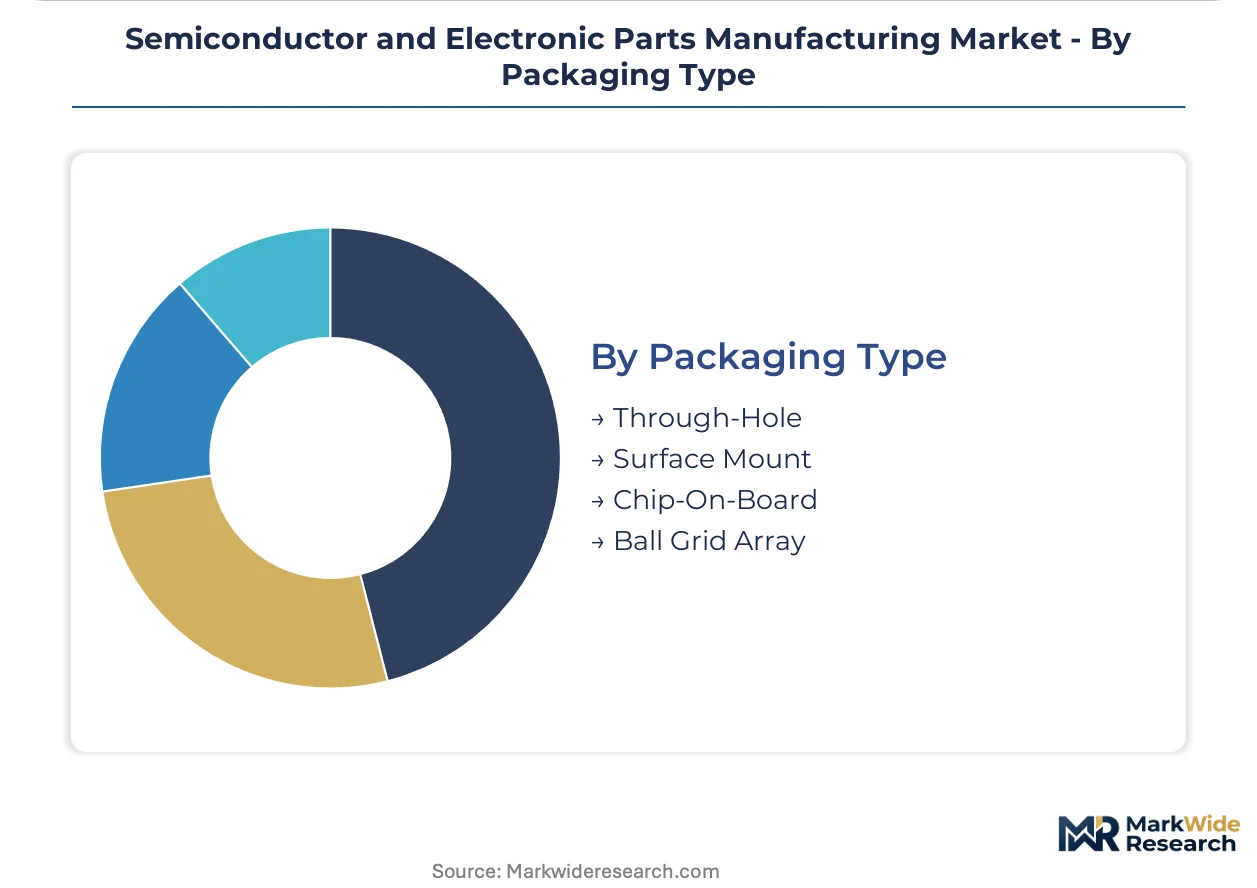
Advanced packaging formats concentrate value-add in Taiwan and South Korea backend facilities, where 2.5D and 3D integration commands premium pricing over traditional leadframe assembly.
- Ball Grid Array:High-density interconnect with solder spheres beneath the package enables processor and FPGA mounting. AI accelerator chips from NVIDIA and AMD are consuming CoWoS capacity at TSMC, while Intel's Foveros technology competes for high-bandwidth memory integration.
- Surface Mount:Leadless or short-lead components attach directly to PCB pads for automated assembly. Consumer electronics manufacturing in Vietnam and Mexico is pulling QFN and QFP capacity from ASE and Amkor facilities.
- Through-Hole:Wire leads pass through PCB holes for mechanical stability in high-stress environments.
- Chip-On-Board:Bare die attach with wire bonding for space-constrained applications.
Ball grid array captures the highest value per unit; surface mount is expanding most quickly on electronics manufacturing migration to Southeast Asia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in East Asian foundry clusters while consumption spreads across automotive and electronics assembly networks in Germany, the United States, and India. This geographic split shapes capital flows, regulatory exposure, and supply chain vulnerability patterns.
United States
CHIPS Act subsidies are pulling advanced logic and memory fabrication toward Arizona, Texas, and New York. The EPA enforces hazardous chemical discharge limits from new fabrication facilities. Intel's expansion in Hillsboro, Oregon and Chandler, Arizona exemplifies domestic capacity rebuilding for leading-edge nodes.
Germany
Automotive OEMs in Stuttgart and Munich are sourcing silicon carbide power semiconductors directly from foundries, bypassing traditional distribution tiers. REACH substance restrictions limit per- and polyfluoroalkyl substance use in etching chemistries. Dresden's Saxony cluster hosts Infineon and GlobalFoundries facilities serving European automotive demand.
China
Domestic foundries in Shanghai and Beijing are expanding mature-node capacity for automotive and industrial applications. The MEE enforces tightening wastewater discharge standards for fluoride and heavy metal content. Yangtze Memory Technologies and SMIC anchor fabrication investment in the Yangtze River Delta and Beijing-Tianjin-Hebei corridor.
South Korea
High-bandwidth memory integration with AI accelerators is consuming disproportionate backend packaging capacity. The MFDS regulates occupational chemical exposure in cleanroom environments. Samsung Electronics and SK Hynix dominate DRAM and NAND output from the Seoul Capital Area and Busan-Ulsan regions.
India
Production-linked incentive schemes are attracting display driver and mature-node logic assembly to Gujarat and Tamil Nadu. The BIS mandates certification for electronic components entering domestic supply chains. Tata Electronics and CG Power are establishing fabrication and assembly presence in Dholera, Gujarat and Hosur, Tamil Nadu.
Semiconductor and Electronic Parts Manufacturing Market Competitive Landscape
The competitive structure tilts toward scale-driven foundry operators with disproportionate capital access. Three to five players command leading-edge logic and memory capacity, while specialized analog and power semiconductor fabricators occupy defensible niche positions. Strategic archetypes span pure-play foundries, integrated device manufacturers, and fabless design houses. Capacity expansion and advanced packaging yield competition constitute the dominant competitive moves.
Among East Asian pure-play foundries, Taiwan Semiconductor Manufacturing Co. Ltd. and Samsung Electronics Co. Ltd. exemplify the scale-driven archetype through their dominance of leading-edge node output and advanced packaging platforms. Intel Corp. occupies a distinctive position as an integrated device manufacturer attempting to regain process leadership while maintaining captive design capabilities.
| Leading Market Players |
|---|
| Taiwan Semiconductor Manufacturing Co. Ltd. |
| Samsung Electronics Co. Ltd. |
| Intel Corp. |
| SK Hynix Inc. |
| Micron Technology Inc. |
| Qualcomm Technologies Inc. |
| Broadcom Inc. |
| Texas Instruments Inc. |
| Nvidia Corp. |
| Others |
Value Network & Pricing Analysis
Automotive OEMs' direct long-term supply agreements for silicon carbide power semiconductors are compressing traditional distribution markups and forcing foundries to absorb qualification costs upfront. This procurement shift elevates contract-based pricing over spot transactions while concentrating negotiation leverage with vehicle manufacturers in Germany, Japan, and the United States.
Pricing Analysis
Cost-down pressure on mature-node automotive chips accelerates because foundries must offset AEC-Q100 qualification expenses across lower unit volumes than consumer electronics. Three-tier pricing structure across automotive-grade, industrial-grade, and commercial-grade certification levels separates qualified from unqualified supply. Pricing pressure stems from automotive OEMs consolidating procurement offices in Taiwan and South Korea. Consumer electronics buyers exhibit highest price sensitivity on commodity memory and display drivers, while aerospace and defense programs show lowest sensitivity due to traceability mandates.
Supply Chain Analysis
Extreme ultraviolet lithography equipment supply rests on ASML's Dutch manufacturing facilities, creating single-source dependency for leading-edge node capacity. Photoresist and high-purity neon sourcing concentrates in Japan, Ukraine, and Russia, exposing lithography operations to geopolitical disruption. Fluorinated etching chemistries face REACH substance restrictions across European-serving supply chains. Distribution runs through direct foundry-OEM contracts for automotive power electronics, while consumer electronics flows through tiered distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chiplet-based heterogeneous integration is displacing monolithic processor architectures, creating transition-phase winners among advanced packaging specialists and losers among pure-play logic fabricators without backend capabilities.
For Market Incumbents: Extend CoWoS and InFO platform investments to capture high-bandwidth memory integration demand from AI accelerator designers. Consolidate process engineering talent through university partnerships in Arizona, Dresden, and Hsinchu to counter specialist scarcity. Defend against Intel's Foveros and Samsung's X-Cube competition by locking multi-year capacity commitments with NVIDIA and AMD. For New Entrants and Emerging Players: Direct-to-OEM component sourcing channels offer lowest barrier entry for automotive-qualified silicon carbide device suppliers bypassing traditional tiered distribution. Target India's PLI-backed mature-node assembly in Gujarat and Tamil Nadu where land and labor costs undercut East Asian backend facilities. Lead with photonics-electronics convergence applications for data center optical interconnects, a segment lacking established incumbent dominance. For Investors and Strategic Acquirers: The window for entry favors analog and mixed-signal specialists with captive fab capacity and automotive certification pipelines. Long-term viability hinges on exposure to electrification and autonomous vehicle content growth rather than consumer electronics cyclicality. Watch EU Chips Act capital allocation velocity as inflection signal for European fabrication capacity returns.| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Packaging Capacity Expansion | TSMC's CoWoS investments capture NVIDIA and AMD high-bandwidth memory integration demand. |
| Wide-Bandgap Substrate Backward Integration | ST Microelectronics' silicon carbide wafer sourcing from Swedish suppliers secures traction inverter supply. |
| Automotive Qualification Pipeline Investment | Infineon's Dresden AEC-Q100 certification capacity serves Volkswagen and BMW direct procurement programs. |
| Photonics-Electronics Convergence R&D | Intel's silicon photonics integration opens data center optical interconnect markets beyond electrical signaling limits. |
| Geographic Manufacturing Footprint Diversification | Intel's Arizona and Ohio fabs reduce concentration risk in Taiwan and South Korea foundry clusters. |
Research Methodology
Independent corroboration across foundry operations executives, automotive Tier 1 procurement directors, and semiconductor equipment engineers underwrites the qualitative findings in this study. Primary interviews with cleanroom construction specialists and analog design house technical leads combined with secondary validation from SEC 10-K filings, SEMI equipment shipment data, and EU Chips Act implementation trackers. Bottom-up wafer start estimates and top-down electronics systems content analysis triangulate market sizing across the value chain.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, technology node, packaging format, end-use industry, and regional production cluster. CAGRs derive from fitted growth curves calibrated to capital expenditure announcements and capacity ramp schedules. Industry-specific forecast inputs incorporate EUV tool delivery backlogs and automotive platform electrification roadmaps.
Inputs from foundry utilization reports and equipment order backlogs were available through the study window; gaps in proprietary yield data and customer concentration metrics introduce uncertainty bands around leading-edge node revenue splits. Forecasts reflect assumptions on geopolitical stability in East Asian shipping lanes and REACH substance restriction implementation timelines. A small set of triggers—neon supply disruption, EUV tool delivery delays, and automotive demand cyclicality—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Manufacturing
Semiconductor Bonding Machine Market
Semiconductor Manufacturing
Medical Component Manufacturing Market
Semiconductor Manufacturing
Surface Mount Technology (SMT) Market
Semiconductor Manufacturing
EUV Lithography Service Market
Semiconductor Manufacturing
Electronic Manufacturing Services (EMS) Market
Semiconductor Manufacturing
Europe Electronic Manufacturing Services Market
Semiconductor Manufacturing
Europe Photoresist and Photoresist Ancillaries Market
Semiconductor Manufacturing
Solar Laser Drilling Market
Semiconductor Manufacturing
Chip Melting Furnace Market
Semiconductor Manufacturing
United States Photoresist and Photoresist Ancillaries Market
Semiconductor Manufacturing
Stencil Lithography Market
Semiconductor Manufacturing
Malaysia and Thailand Precession Cleaning for Electronic Market
Semiconductor Manufacturing
Middle East and Africa Cell Manufacturing Market
Semiconductor Manufacturing
Semiconductor Polishing Pads Market
Semiconductor Manufacturing
Solder Paste Market
Semiconductor Manufacturing
Global EUV Lithography Market