
 North America Next Generation Storage Market | 2026-2036
North America Next Generation Storage Market Size, Share, and Industry Trends Forecast 2026-2036
North America Next Generation Storage Market Analytics
Hyperscale cloud operators is bifurcating demand away from conventional enterprise buyers in the North America Next Generation Storage Market. Dell Technologies leverages vertical integration across server and storage hardware to control supply chain costs for large-scale deployments. Pure Storage differentiates through software-defined flash architectures that reduce data center footprint and power consumption. IBM Corporation anchors its position in government and regulated verticals through encryption-certified storage systems.
Next Generation Storage encompasses solid-state, software-defined, and cloud-integrated data retention systems engineered for sub-millisecond latency, petabyte-scale density, and automated tiering across flash, disk, and object storage layers. NVMe over Fabrics and computational storage architectures enable real-time analytics pipelines by processing data closer to physical media, eliminating host CPU bottlenecks. Flash Storage commands premium pricing in financial services and autonomous vehicle development workflows where throughput requirements exceed SATA capabilities. Object Storage extends into healthcare imaging and media archives as unstructured data volumes outpace block and file growth, while Hybrid Storage configurations retain relevance in mid-market manufacturing where legacy application compatibility constrains all-flash migration.
The US Federal Energy Regulatory Commission and Canada's Office of the Privacy Commissioner shape deployment architectures through grid reliability mandates and cross-border data sovereignty requirements, respectively. EPA Energy Star certification and California's Title 24 building efficiency standards increasingly filter storage procurement specifications, favoring vendors with verified power consumption metrics. Stakeholders must weigh the capital intensity of in-house NVMe fabric deployment against consumption-based cloud storage economics as workload portability becomes a strategic priority.
Market Dynamics
Hyperscale cloud operators and AI training clusters are consolidating procurement power, forcing storage vendors to reconfigure product roadmaps around petabyte-scale density and sub-millisecond latency rather than traditional enterprise feature sets.
Growth Catalysts
- US Inflation Reduction Act clean energy incentives:Tax credits for renewable-powered data center infrastructure accelerate all-flash array deployments in hyperscale facilities across Virginia and Texas.
- NVMe over Fabrics protocol maturation:This interconnect technology eliminates host CPU bottlenecks for real-time analytics pipelines in financial services and autonomous vehicle development workflows.
- Northern Virginia's Data Center Alley concentration:Dominion Energy's renewable power commitments attract sustainability-driven storage procurement from cloud operators seeking carbon-neutral operations.
Market Restraints
- NAND flash supply concentration:Fabrication capacity concentrates in South Korea and Taiwan, exposing procurement timelines to geopolitical disruption and foundry allocation decisions.
- Legacy application compatibility constraints:Mid-market manufacturing and healthcare IT systems require SATA interfaces that throttle all-flash migration and extend hybrid storage relevance.
- FERC grid reliability mandates:Federal Energy Regulatory Commission requirements for backup power systems add capital overhead to storage deployments in regulated utilities and critical infrastructure.
Strategic Opportunities
- Canada cross-border data sovereignty:The Office of the Privacy Commissioner's data localization requirements create demand for Canadian-located object storage in healthcare imaging and government archives.
- Computational storage convergence:Processing-in-memory architectures combined with NVMe fabrics enable edge analytics for smart manufacturing and autonomous logistics.
- California Title 24 building efficiency standards:Mandatory energy disclosure for data center equipment creates preference pull for vendors with verified EPA Energy Star power consumption metrics.
Industry Challenges
- NAND fabrication process engineering talent scarcity:Advanced node development requires specialized lithography and materials science expertise concentrated at a handful of research institutions.
- Multi-generational interface integration complexity:Storage systems must simultaneously support NVMe, SAS, and SATA protocols for heterogeneous enterprise environments.
- Encryption certification timelines:FIPS 140-2 validation for government and regulated verticals extends product launch cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Next Generation Storage Market |
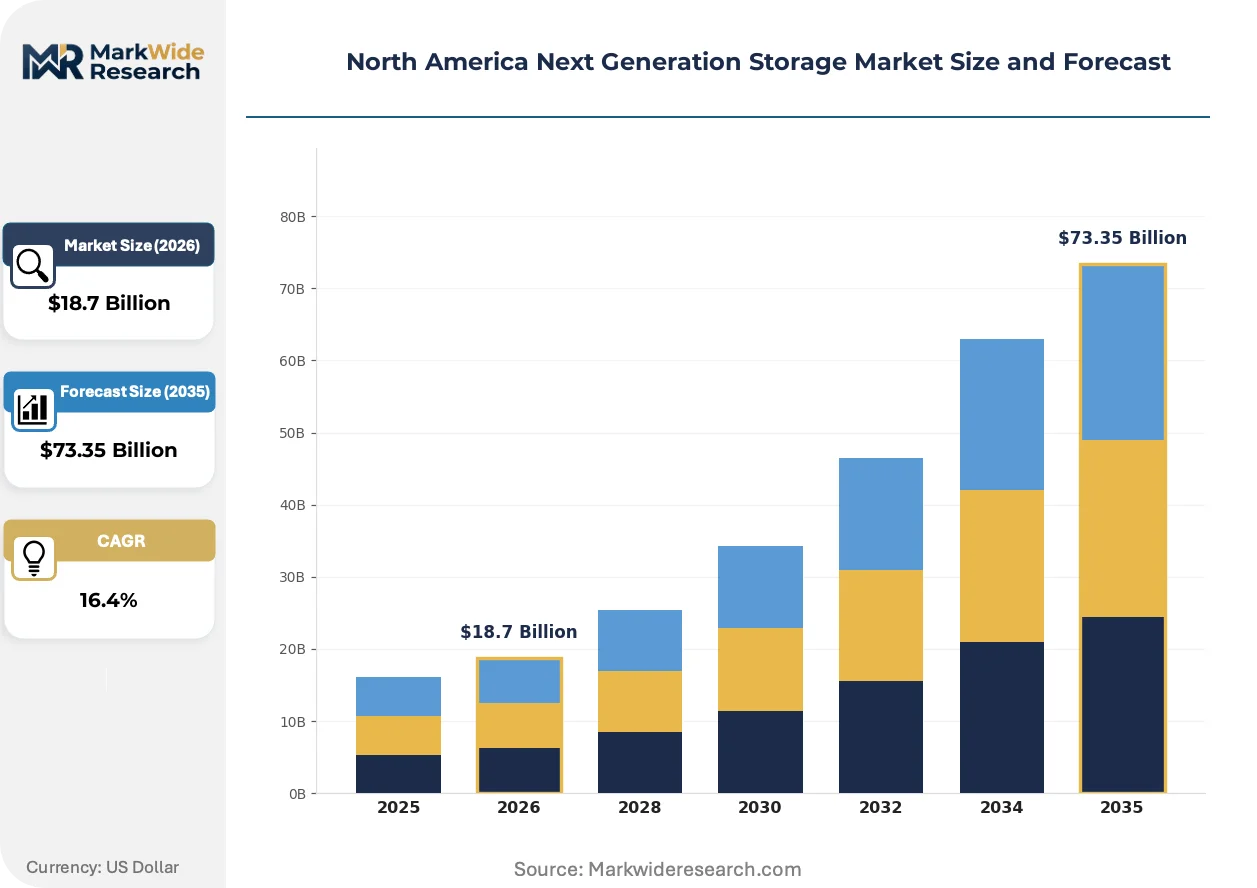
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flash Storage, Disk Storage, Cloud Storage, Hybrid Storage Technology: SDD, NVMe, SATA, Object Storage End User: Enterprises, Government, Healthcare, Education Application: Data Backup, Disaster Recovery, Data Archiving, Big Data Analytics |
| Companies Covered | Dell Technologies, Hewlett Packard Enterprise, NetApp, IBM Corporation, Pure Storage, Hitachi Vantara, Micron Technology, Toshiba Corporation, DataDirect Networks, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Next Generation Storage Market Evolving Landscape
Storage architectures are fragmenting into two distinct optimization paths: extreme performance for AI training clusters and extreme efficiency for archival workloads, with the middle tier contracting.
Computational storage drives is bifurcating the market between analytics-optimized and capacity-optimized procurement. Hyperscale operators deploy these processing-capable devices for training pipeline acceleration. Traditional enterprise buyers face compressed mid-tier options as vendors discontinue general-purpose arrays.
EPA Energy Star certification and California Title 24 standards are hardening into procurement gatekeepers. Data center operators now require verified power consumption metrics before vendor qualification. Financial services and healthcare verticals in California and New York lead this specification shift.
Consumption-based cloud storage economics are compressing capital purchase cycles for mid-market buyers. Monthly billing models displace three-year depreciation schedules in manufacturing and professional services. This pattern concentrates in the US Midwest and Southeast where legacy on-premise infrastructure remains prevalent.
North America Next Generation Storage Market Segmentation
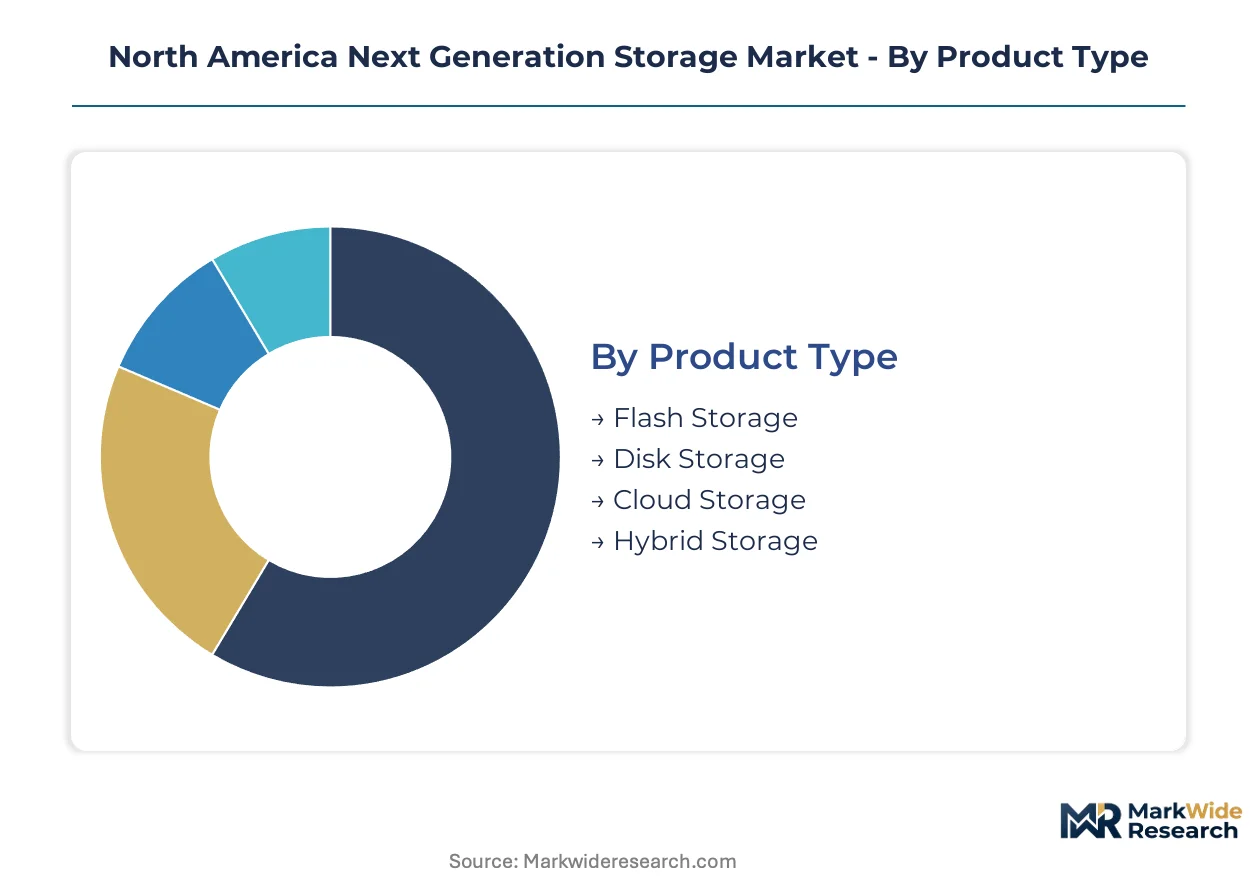
Storage procurement in North America fragments across performance tiers, interface protocols, and compliance requirements. Each segmentation dimension carries distinct substitution pressures that reshape vendor positioning and customer migration patterns.
Product Type:
Flash Storage faces the most intense substitution pressure as NVMe-over-Fabrics and computational storage architectures displace traditional SAS-based arrays.
- Flash Storage:All-flash arrays built on NAND and emerging SCM media deliver sub-millisecond latency for AI training clusters in Northern Virginia and financial trading floors. Dominion Energy's renewable power commitments in Data Center Alley accelerate sustainability-driven flash procurement from hyperscale operators.
- Cloud Storage:Consumption-based object and block services compress capital purchase cycles for mid-market manufacturing and professional services across the US Midwest. Monthly billing models displace three-year depreciation schedules where legacy on-premise infrastructure remains prevalent.
- Disk Storage:HDD-based systems retain relevance in cold archive tiers where petabyte-scale density outweighs latency requirements.
- Hybrid Storage:Flash-disk combinations serve healthcare IT and manufacturing environments constrained by SATA interface compatibility.
Flash Storage anchors the volume base while Cloud Storage gains share at the steepest rate.
Technology:
Cost stratification separates enterprise-grade interconnects from commodity interfaces, with protocol choice directly determining deployment economics.
- NVMe:PCIe-based flash protocols eliminate host CPU bottlenecks for real-time analytics pipelines in autonomous vehicle development and high-frequency trading. FERC grid reliability mandates add backup power overhead to NVMe fabric deployments in regulated utilities.
- Object Storage:Flat-namespace architectures scale into petabyte ranges for healthcare imaging archives and media content repositories. Canada's Office of the Privacy Commissioner data localization requirements drive Canadian-located object storage demand.
- SDD:Software-defined storage abstracts hardware dependencies for multi-cloud data mobility.
- SATA:Legacy interface protocols throttle all-flash migration in mid-market manufacturing with constrained refresh budgets.
NVMe commands premium positioning while Object Storage scales most rapidly in unstructured data workloads.
End User:
Customer type determines procurement authority, with hyperscale cloud operators consolidating purchasing power away from fragmented enterprise buyers.
- Enterprises:Fortune 500 corporations deploy petabyte-scale NVMe fabrics for ERP consolidation and customer analytics. US Inflation Reduction Act clean energy incentives accelerate all-flash array deployments in Texas and Virginia facilities.
- Government:Federal and state agencies require FIPS 140-2 encryption certification, extending product validation cycles. Procurement concentrates in defense and intelligence verticals with air-gapped security requirements.
- Healthcare:HIPAA-compliant storage supports electronic health record systems and diagnostic imaging archives.
- Education:University research clusters demand high-throughput storage for scientific computing workloads.
Enterprises dominate absolute spending while Government procurement carries the longest sales cycles.
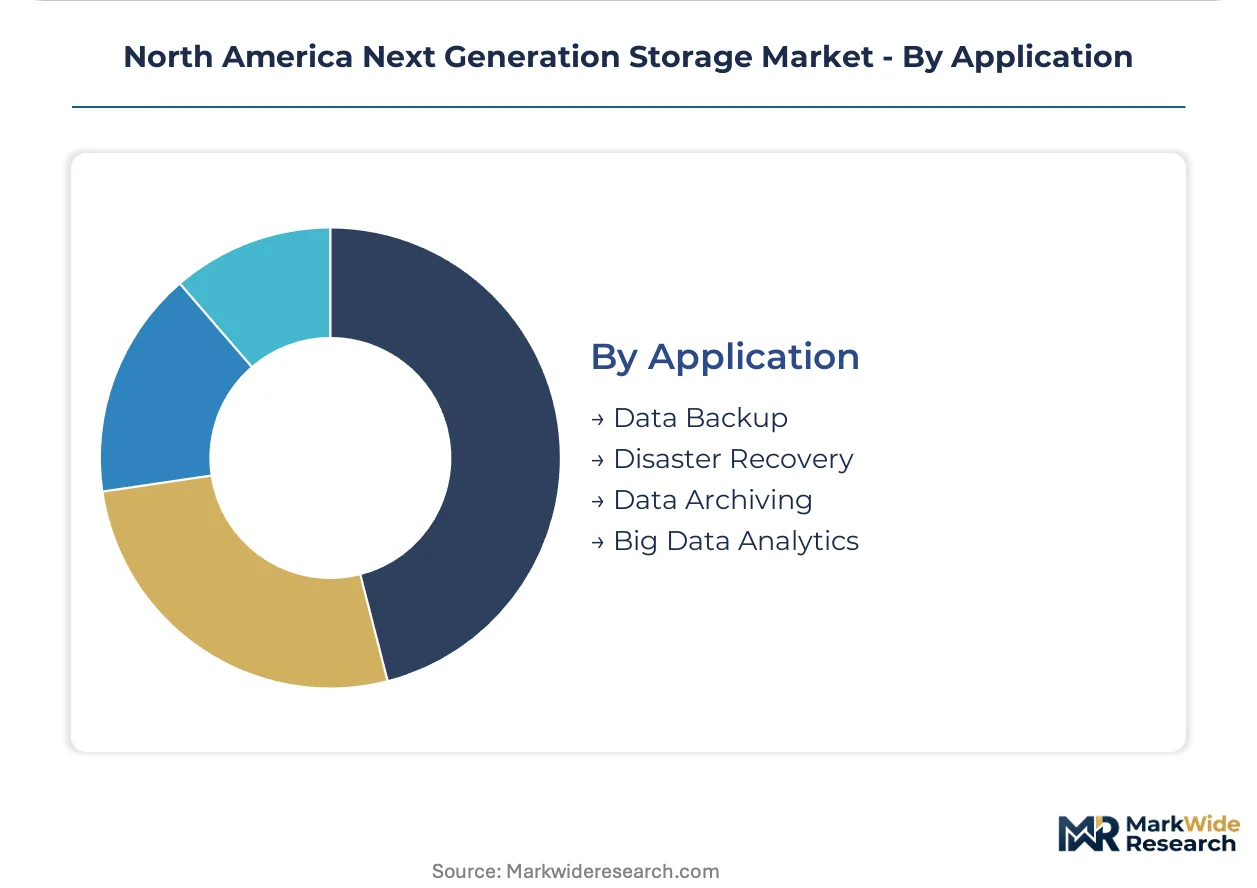
Application:
Workload characteristics dictate architecture choice, with latency-sensitive pipelines diverging from capacity-optimized tiers.
- Big Data Analytics:Real-time inference and model training workloads require NVMe-over-Fabrics and computational storage convergence. Smart manufacturing and autonomous logistics in the US Southeast drive edge analytics procurement.
- Disaster Recovery:Synchronous replication between geographically separated facilities demands sub-5ms latency for RPO compliance. Financial services in New York and California lead specification shifts toward verified EPA Energy Star power metrics.
- Data Backup:Immutable snapshot architectures protect against ransomware in healthcare and government verticals.
- Data Archiving:WORM-compliant object storage satisfies SEC retention requirements for financial records.
Big Data Analytics captures the steepest investment growth while Disaster Recovery maintains the most rigid compliance thresholds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada exports storage hardware components and specialized memory modules to United States hyperscale operators concentrated in Northern Virginia and Texas data center corridors. Cross-border supply chains integrate Canadian fabrication with American assembly and deployment infrastructure.
United States
Hyperscale cloud operators in Northern Virginia's Data Center Alley and Texas hyperscale campuses drive petabyte-scale flash procurement. FERC grid reliability mandates require backup power systems for storage deployments in regulated utilities. Dominion Energy's renewable power commitments in Virginia accelerate sustainability-driven storage procurement from carbon-neutral-seeking operators.
Canada
The Office of the Privacy Commissioner's data localization requirements create demand for Canadian-located object storage in healthcare imaging and government archives. Health Canada regulates medical device data retention standards for diagnostic imaging systems. Toronto and Montreal host growing data center clusters serving provincial healthcare networks and federal archival requirements.
Mexico
Nearshoring manufacturing investments in Nuevo León and Bajío Region generate demand for edge storage in smart factory deployments. Mexico's Federal Law on Protection of Personal Data mandates local data residency for financial services. Querétaro and Guadalajara emerging as data center hubs serving Latin American cloud expansion.
North America Next Generation Storage Market Competitive Landscape
Player mix skews toward vertically integrated infrastructure conglomerates and specialized flash array vendors. Market structure concentrates procurement power among hyperscale operators, forcing tiered supplier relationships. Strategic archetypes include full-stack server-storage integrators, software-defined pure-plays, and memory semiconductor specialists. Competitive moves center on backward integration into NAND supply and strategic partnerships for NVMe fabric deployment.
Within the vertically integrated tier, Dell Technologies and Hewlett Packard Enterprise exemplify full-stack infrastructure providers controlling hardware supply chains. Pure Storage occupies a position representing software-defined flash specialists. IBM Corporation anchors the encryption-certified segment serving government and regulated verticals with validated security architectures.
| Leading Market Players |
|---|
| Dell Technologies |
| Hewlett Packard Enterprise |
| NetApp |
| IBM Corporation |
| Pure Storage |
| Hitachi Vantara |
| Micron Technology |
| Toshiba Corporation |
| DataDirect Networks |
| Others |
Value Network & Pricing Analysis
EPA Energy Star certification gates both supplier qualification and price stratification in North American storage procurement, compressing margins for uncertified vendors while enabling verified manufacturers to command sustainability premiums from hyperscale operators in Virginia and Texas.
Pricing Analysis
Current-generation NVMe-over-Fabrics arrays command substantial premiums against prior-generation SAS flash and next-generation computational storage prototypes still in qualification. Pricing stratifies across premium, standard, and economy tiers based on FIPS 140-2 certification status and volume scale commitments. Cost compression in mid-tier hybrid configurations is intensifying because hyperscale direct procurement is bypassing traditional channel markups. Mid-market manufacturing buyers exhibit highest price sensitivity due to constrained refresh budgets, while financial services trading floors show lowest sensitivity given latency-driven performance requirements.
Supply Chain Analysis
Inventory lead times for advanced NAND modules stretch considerably when foundry allocation decisions in South Korea and Taiwan prioritize smartphone and PC OEM contracts over enterprise storage demand. Component sourcing draws from South Korean memory fabrication, Taiwanese controller silicon, and Malaysian assembly operations. Single-source vulnerability concentrates in EUV lithography equipment held by Dutch and Japanese suppliers. Distribution runs through direct OEM relationships with hyperscale operators alongside value-added reseller networks serving fragmented enterprise accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Next Generation Storage Market is entering a cyclical recovery phase as hyperscale capital expenditure cycles rebound from prior-year contraction, with AI training cluster buildouts serving as the primary cyclical driver accelerating procurement velocity through 2035.
For Market Incumbents: Consolidate procurement relationships with Dominion Energy-served data center developments in Northern Virginia to lock in renewable-powered deployment commitments ahead of competitor qualification. Deepen backward integration into NAND supply through strategic foundry partnerships, insulating against South Korean and Taiwanese fabrication allocation volatility. Prioritize FIPS 140-2 certification maintenance to defend government and regulated vertical positions against encryption-certified challengers.
For New Entrants and Emerging Players: FIPS 140-2 fast-track programs offer accelerated path into federal and defense procurement cycles where validation timelines traditionally exclude unproven vendors. Target Canadian healthcare imaging archives constrained by Office of the Privacy Commissioner data localization mandates, where incumbent presence remains underdeveloped. Pursue edge analytics partnerships with smart manufacturing deployments in the US Southeast as beachhead for NVMe fabric credibility.
For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate parent companies seeking to divest non-core storage divisions amid portfolio rationalization pressures. Long-term viability hinges on software-defined architecture transitions rather than hardware-dependent revenue models. Monitor hyperscale capital expenditure disclosure patterns as inflection indicator for procurement cycle timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into NAND Supply | Captive wafer supply from South Korean foundries secures allocation priority during fabrication constraints. |
| NVMe Fabric Deployment Partnership | Direct hyperscale operator relationships in Texas bypass traditional channel economics and accelerate revenue recognition. |
| FIPS 140-2 Certification Investment | Federal procurement eligibility extends product lifecycles in defense and intelligence verticals with air-gapped requirements. |
| Canadian Data Center Localization | Toronto and Montreal facilities satisfy Health Canada medical device data retention standards for provincial networks. |
| Computational Storage Convergence | Processing-in-memory architectures capture edge analytics demand from autonomous logistics in the US Southeast. |
Research Methodology
A standing panel of hyperscale infrastructure procurement directors, enterprise storage architects, NAND supply chain managers, and federal IT acquisition officers provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, hyperscaler capex disclosures, FERC grid reliability reports, and EPA Energy Star certification databases. Bottom-up deployment modeling triangulated against top-down market sizing across technology generations and end-user verticals.
Consistency checks validated volume and value outputs against external benchmarks including foundry utilization reports and data center power consumption disclosures. The analytical framework modeled segmentation across storage media type, interface protocol, deployment scale tier, compliance certification status, and regional regulatory cluster throughout the projection horizon. CAGRs were derived from installation base growth rates and technology substitution curves, with specific inputs including Dominion Energy renewable power commitment timelines and FIPS validation cycle durations.
Decision-makers should treat outputs as directional under assumptions of continued hyperscale capital expenditure growth and stable NAND supply chain configuration; material deviation in either factor would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Data Center Ssds Market
Data Storage
China Solid-State Drive Market
Data Storage
Storage Virtualization Market
Data Storage
Non-Volatile Memory Express (Nvme) Market
Data Storage
Digital Recording System Market
Data Storage
All Flash Storage Market
Data Storage
Taiwan Data Center Storage Market
Data Storage
Serial (SPI) NOR Flash Market
Data Storage
Asia-Pacific Data Center Storage Market
Data Storage
Transparent Caching Market
Data Storage
Tape Storage Market
Data Storage
Distributed Storage System Market
Data Storage
Portable Storage Device Control Software Market
Data Storage
Middle East Data Center Storage Market
Data Storage
Blu-Ray Optical Disk Market
Data Storage
Electrochromic Storage Devices Market