
 Asia Pacific Integrated Circuit (IC) Market | 2026-2036
Asia Pacific Integrated Circuit (IC) Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Integrated Circuit (IC) Market Insights
Multi-source wafer supply contracts is consolidating around dominant foundry operators in East Asia. TSMC anchors advanced logic production through its Taiwan-based megafabs. Samsung Electronics leverages captive memory and logic capacity to compete across DRAM, NAND, and custom ASIC segments. SK Hynix sustains leadership in high-bandwidth memory architectures critical to AI accelerator cards.
An integrated circuit is a miniaturized electronic circuit comprising transistors, resistors, and capacitors fabricated on a semiconductor substrate, typically silicon, using photolithography and etching processes with node geometries now reaching three nanometers. These devices perform computation, signal processing, and power management functions across virtually all electronic systems. Digital ICs command the largest revenue pool, while mixed-signal ICs capture expanding margin share as automotive sensor fusion and 5G baseband integration intensify. Power ICs occupy a structurally defensive position given electrification trends in transportation and industrial motor drives.
Japan's METI semiconductor revitalization framework, South Korea's K-Chips Act, and China's MIIT domestic production mandates collectively reshape investment incentives and technology transfer rules across the region. REACH-aligned substance restrictions and emerging EU-style supply chain due diligence standards are elevating compliance costs for materials sourcing. Stakeholders must monitor which regulatory jurisdiction ultimately sets the de facto standard for export controls and carbon disclosure in semiconductor manufacturing.
Market Dynamics
Foundry capacity concentration in Taiwan and South Korea is redrawing competitive boundaries across the Asia Pacific IC landscape, as advanced node production becomes captive to a handful of megafab operators and their equipment supplier ecosystems.
Growth Catalysts
- Automotive sensor fusion architectures:Electric vehicle platforms in China and Japan are embedding mixed-signal ICs for battery management and lidar processing, pulling wafer starts toward automotive-qualified process nodes.
- MIIT dual carbon mandates:China's Ministry of Industry and Information Technology directives on domestic chip production and energy efficiency are redirecting state capital into 12-inch wafer fabs and advanced packaging facilities.
- High-bandwidth memory integration:AI accelerator cards deployed in South Korean and Singaporean data centers are consuming HBM3E stacks, sustaining foundry utilization rates for memory-logic heterogeneous integration.
Market Restraints
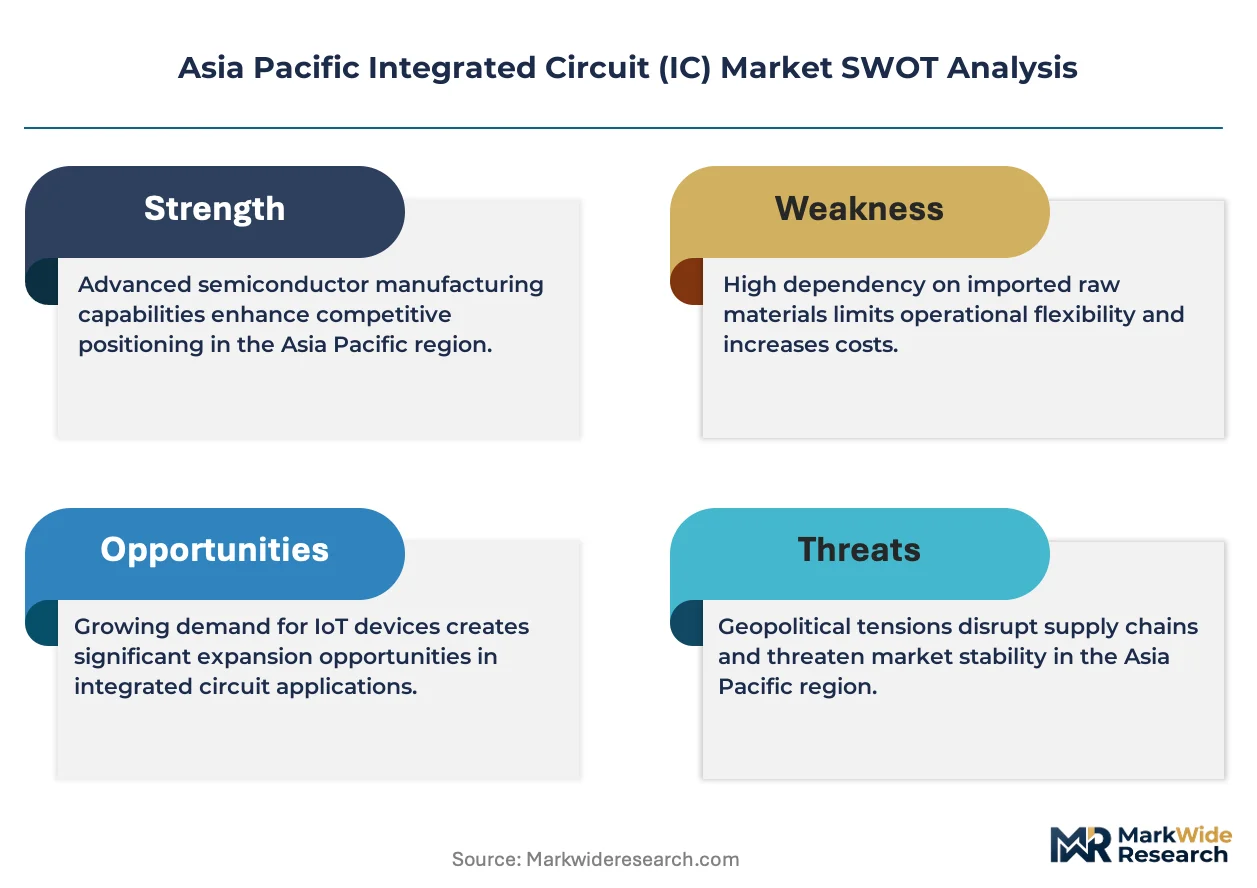
- Extreme ultraviolet lithography dependency:ASML equipment lead times and Dutch export licensing bottlenecks constrain 3nm and 2nm ramp schedules for Taiwan-based logic foundries.
- Fluorinated gas supply concentration:Japan and South Korea control critical etching gas production for advanced nodes, exposing downstream fabs to input cost volatility and supply disruption risks.
- Silicon carbide substrate scarcity:Power IC manufacturers face structural shortages in 150mm and 200mm SiC wafers, limiting capacity expansion for automotive traction inverter modules.
Strategic Opportunities
- Vietnam and Malaysia packaging expansion:ASEAN governments are offering land and tax incentives for advanced packaging and test facilities, attracting OSAT investment away from traditional China-Taiwan corridors.
- Chiplets and 3D stacking standards:Universal Chiplet Interconnect Express and proprietary foundry interfaces are converging, enabling fabless designers to mix IP blocks across process nodes.
- METI semiconductor revitalization subsidies:Japan's Ministry of Economy, Trade and Industry funding for legacy node capacity and materials independence creates captive supply options for automotive and industrial IC buyers.
Industry Challenges
- Process engineering talent scarcity:Taiwan and South Korea face acute shortages of experienced lithography and yield enhancement engineers, compressing fab ramp timelines and inflating compensation costs.
- Multi-jurisdictional export control compliance:Navigating US BIS entity list restrictions, Japanese METI licensing requirements, and Chinese SAMR data localization rules simultaneously complicates cross-border technology transfers.
- Legacy node equipment obsolescence:Secondhand 200mm tool availability is collapsing as IDMs retire older fabs, stranding automotive and industrial IC designers on mature processes with rising maintenance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Integrated Circuit (IC) Market |
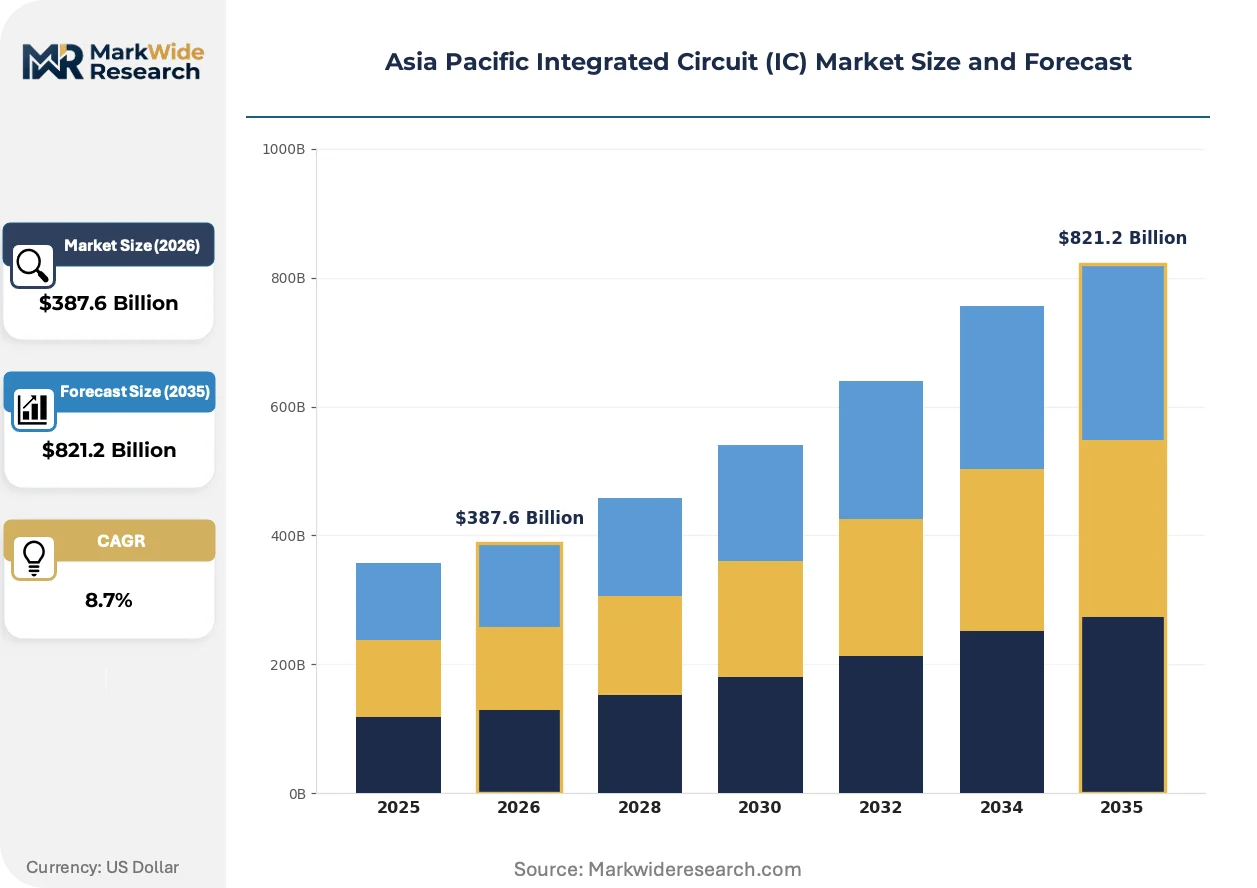
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $821.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog ICs, Digital ICs, Mixed-signal ICs, Power ICs End User: Telecommunications, Consumer Electronics, Automotive, Industrial Electronics Technology: CMOS, BiCMOS, GaAs, SiGe Application: Embedded Systems, Communications, Power Management, Signal Processing |
| Companies Covered | MediaTek, NXP Semiconductors, Taiwan Semiconductor Manufacturing Company (TSMC), STMicroelectronics, Infineon Technologies, Samsung Electronics, Renesas Electronics Corporation, Texas Instruments, SK Hynix, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Integrated Circuit (IC) Market Trends and Innovations
Photolithography and materials science advances are compressing transistor geometries while packaging innovations are displacing traditional Moore's Law scaling as the primary performance lever for compute-intensive applications.
Gate-all-around transistor architectures are consolidating process leadership at the 2nm node, replacing finFET structures to improve electrostatic control and reduce power leakage. Samsung and TSMC are qualifying these designs for high-performance computing and smartphone SoC production. The shift is consolidating capital expenditure into a shrinking pool of equipment suppliers capable of supporting atomic-layer deposition and high-NA EUV patterning.
Japan's METI semiconductor materials independence framework is accelerating domestic production of photoresists, high-purity hydrogen fluoride, and silicon wafers previously sourced from consolidated overseas suppliers. The policy mandates 50% domestic sourcing targets for critical materials by 2030. Automotive and industrial IC segments are responding by qualifying Japanese-origin substrates and chemicals ahead of potential supply disruptions.
Long-term supply agreements are displacing spot-market wafer purchases as OEM procurement departments confront foundry allocation constraints. Automotive electronics divisions at Japanese and Korean tier-1 suppliers are locking three-to-five-year capacity reservations directly with Taiwan-based foundries. This pattern is most visible in power management IC and MCU categories where automotive qualification cycles exceed standard consumer product lifecycles.
Asia Pacific Integrated Circuit (IC) Market Segmentation
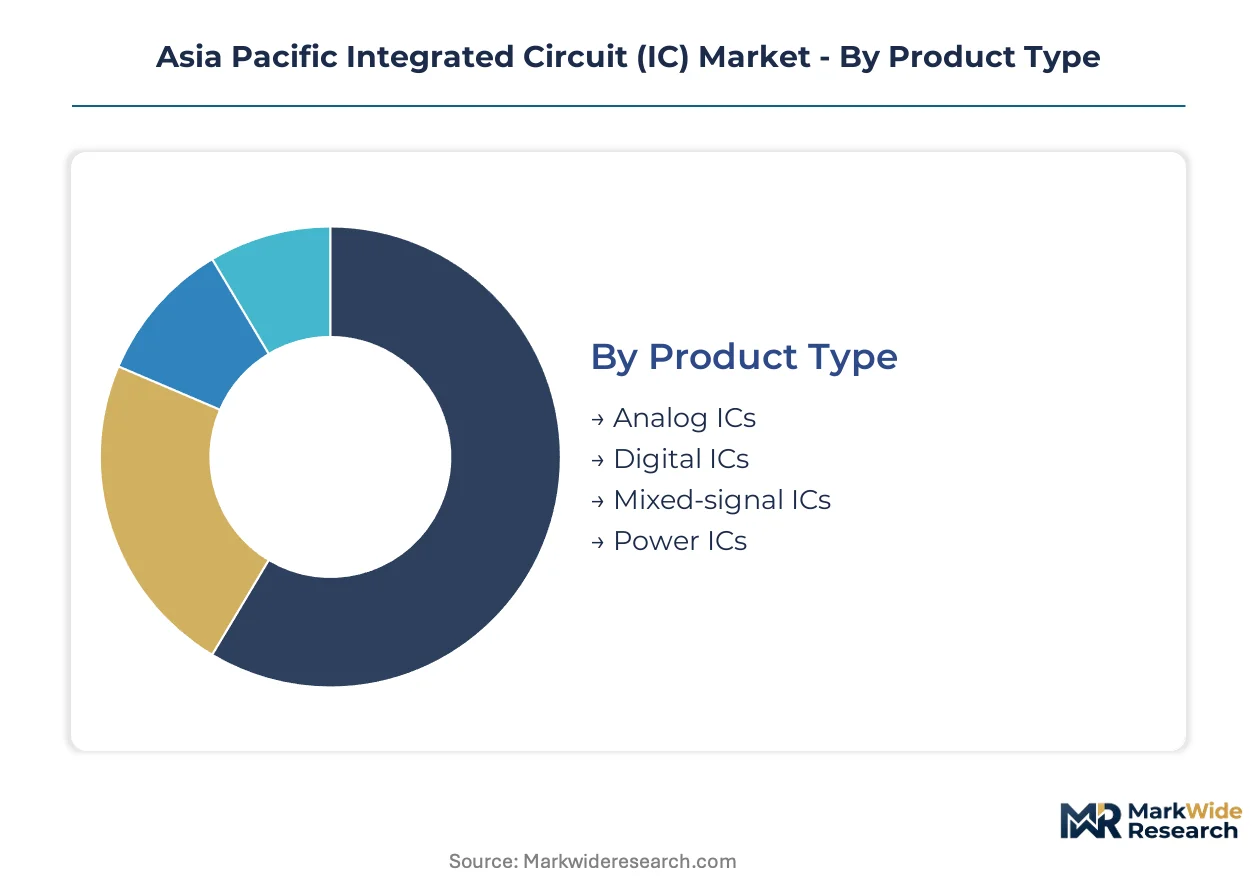
IC procurement decisions across the Asia Pacific region hinge on process node availability, automotive qualification cycles, and foundry allocation constraints. Buyers weight performance-per-watt against supply security as advanced logic and memory production concentrates in Taiwan and South Korea.
Product Type:
Cost tier determines procurement channel selection, with premium nodes commanding direct foundry relationships and mature processes flowing through distribution.
- Digital ICs:Logic devices fabricated at 3nm to 7nm nodes serve high-performance computing and smartphone SoC applications. Taiwan-based foundries anchor supply for Chinese and South Korean OEMs amid MIIT self-sufficiency mandates and Samsung captive capacity expansion.
- Mixed-signal ICs:Devices integrating analog and digital functions on single die support automotive sensor fusion and 5G baseband integration. Japanese tier-1 suppliers are locking long-term capacity reservations for radar and lidar processing chips as EV platforms proliferate.
- Analog ICs:Continuous signal processing components for voltage regulation and data conversion.
- Power ICs:Electrification applications in traction inverters and charging infrastructure.
Volume sits with Digital ICs; growth tilts toward Mixed-signal ICs.
End User:
Application maturity shapes supplier qualification requirements and contract duration.
- Automotive:Battery management systems and ADAS domains demand AEC-Q100 grade silicon with zero-defect traceability. Chinese EV manufacturers are pulling wafer starts toward 28nm and 40nm automotive-qualified nodes as domestic production scales.
- Telecommunications:Baseband processors and RF front-end modules for 5G infrastructure deployment. South Korean network equipment vendors are qualifying HBM3E-integrated accelerators for edge data centers.
- Consumer Electronics:Smartphone and wearable SoCs with annual refresh cycles.
- Industrial Electronics:Motor drives and factory automation controllers.
Volume sits with Consumer Electronics; expansion tilts most steeply toward Automotive.
Technology:
Process geometry and substrate material dictate capital intensity and equipment supplier dependency.
- CMOS:Dominant planar and finFET processes for logic and memory fabrication at nodes from 3nm to 180nm. TSMC and Samsung are qualifying gate-all-around architectures at 2nm to improve electrostatic control for Taiwan and South Korean flagship device production.
- BiCMOS:Bipolar-CMOS integration for high-frequency analog and RF applications. Japanese foundries are expanding BiCMOS capacity for automotive radar and satellite communication chipsets under METI revitalization subsidies.
- GaAs:Gallium arsenide substrates for millimeter-wave and optoelectronic devices.
- SiGe:Silicon-germanium heterojunction processes for cost-sensitive RF transceivers.
Volume sits with CMOS; growth tilts toward BiCMOS.
Application:
System architecture complexity determines packaging technology selection and heterogeneous integration requirements.
- Embedded Systems:Microcontrollers and SoCs for real-time control in automotive and industrial domains. Chinese domestic foundries are expanding 40nm and 55nm MCU capacity to reduce import dependency under MIIT chip mandates.
- Power Management:Voltage regulators and battery charging ICs for mobile and electrified transport. Japanese power semiconductor IDMs are vertically integrating into silicon carbide substrate supply to secure automotive traction inverter sockets.
- Communications:Wired and wireless transceiver architectures.
- Signal Processing:Audio, video, and sensor data conversion.
Volume sits with Embedded Systems; expansion tilts most steeply toward Power Management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon feedstock from Inner Mongolia and polysilicon refining clusters in Xinjiang anchor the Asia Pacific IC supply base. Wafer fabrication concentrates in Taiwan and South Korea, while ASEAN packaging corridors absorb overflow capacity from traditional China-Taiwan routes.
China
Electric vehicle battery management systems and 5G base station deployments are pulling wafer starts toward 28nm automotive-qualified nodes. MIIT dual carbon mandates and chip self-sufficiency directives are redirecting state capital into 12-inch fabs in Shanghai and Xi'an. Yangtze Memory Technologies anchors 3D NAND production in Wuhan under national import substitution programs.
Taiwan
High-performance computing accelerators and smartphone SoCs sustain foundry utilization at leading-edge nodes. The National Development Council coordinates water and power allocation for Hsinchu Science Park expansion amid drought risks. Tainan's Southern Taiwan Science Park hosts TSMC's 3nm megafab ramp, concentrating EUV lithography capacity for regional fabless customers.
South Korea
AI training clusters and HBM3E-integrated accelerators are driving memory-logic heterogeneous integration demand. The K-Chips Act subsidizes domestic materials sourcing and packaging R&D through 2030. Pyeongtaek's semiconductor complex anchors Samsung and SK Hynix expansion, while Yongin emerges as a dedicated foundry cluster under government-backed infrastructure.
Japan
Automotive radar chipsets and industrial motor drive controllers are sustaining BiCMOS and legacy node demand. METI semiconductor revitalization subsidies target 50% domestic materials sourcing by 2030. Kyushu's Silicon Island hosts Renesas and Kioxia fabs, with Kumamoto attracting TSMC-Japan Advanced Semiconductor Manufacturing joint venture investment for 22/28nm capacity.
Vietnam
Advanced packaging and test facility investments are absorbing OSAT migration from China-Taiwan corridors. The Ministry of Planning and Investment offers land and tax incentives for semiconductor assembly operations. Bac Ninh and Ho Chi Minh City industrial zones host Intel and Amkor expansion, positioning the country as a backend alternative amid geopolitical supply chain restructuring.
Asia Pacific Integrated Circuit (IC) Market Competitive Landscape
Global majors compete with regional champions across foundry capacity allocation and advanced packaging technology. The market structures around three tiers: captive IDMs with in-house logic and memory, pure-play foundries serving fabless designers, and memory specialists dominating HBM architectures. Strategic moves concentrate on long-term supply agreements with automotive OEMs and government-subsidized capacity expansion in Japan and ASEAN corridors.
Among Taiwan-based pure-play foundries, Taiwan Semiconductor Manufacturing Company anchors advanced logic production through its captive megafab network. Samsung Electronics exemplifies the integrated IDM archetype, spanning DRAM, NAND, and custom logic segments from South Korean manufacturing bases. SK Hynix occupies a specialist position in high-bandwidth memory architectures, supplying AI accelerator integration demand across regional data center deployments.
| Leading Market Players |
|---|
| MediaTek |
| NXP Semiconductors |
| Taiwan Semiconductor Manufacturing Company (TSMC) |
| STMicroelectronics |
| Infineon Technologies |
| Samsung Electronics |
| Renesas Electronics Corporation |
| Texas Instruments |
| SK Hynix |
| Others |
Pricing and Supply Chain Analysis
Gate-all-around transistor qualification at the 2nm node is compressing cost curves for Taiwan and South Korean foundries while simultaneously concentrating capital expenditure among atomic-layer deposition equipment suppliers. This technology transition redraws pricing power toward fabs with EUV lithography access, leaving mature-node producers exposed to rising maintenance costs and stranded capacity.
Pricing Analysis
Long-term capacity reservations bundle automotive qualification cycles, yield guarantees, and priority wafer allocation into multi-year contracts that Japanese tier-1 suppliers increasingly favor over spot-market purchases. Price differentiation rests on process node maturity and AEC-Q100 certification grade, with 28nm automotive-qualified silicon commanding premiums over consumer-grade equivalents. Cost compression in mature nodes intensifies as secondhand 200mm tool availability collapses and IDMs retire older fabs. Automotive electronics divisions exhibit highest price sensitivity due to zero-defect traceability requirements, while AI accelerator card manufacturers prioritize performance-per-watt over unit economics.
Supply Chain Analysis
Experienced lithography and yield enhancement engineer shortages in Taiwan and South Korea are compressing fab ramp timelines and inflating compensation costs for critical process engineering roles. Wafer fabrication concentrates in Taiwan and South Korea, with advanced packaging capacity expanding into Vietnam and Malaysia under ASEAN government incentives. Raw material dependencies center on photoresists, high-purity hydrogen fluoride, and silicon carbide substrates from Japanese and South Korean suppliers. Single-source vulnerability in EUV lithography equipment from Dutch suppliers exposes foundry expansion schedules to export licensing bottlenecks. Distribution runs through direct foundry relationships for premium nodes and authorized distribution for mature-process consumer ICs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific IC market participants face a vertical-integration race where captive control over silicon carbide substrates, advanced packaging capacity, and photoresist supply determines margin sustainability. Foundry operators and IDMs alike are pursuing backward integration into materials and forward integration into module assembly.
For Market Incumbents: Deepen captive silicon carbide substrate supply through joint ventures with Japanese materials suppliers, securing automotive traction inverter sockets ahead of structural wafer shortages. Expand 22/28nm capacity in Kumamoto and Yongin to capture METI and K-Chips Act subsidies while defending against Chinese domestic foundry expansion under MIIT mandates. Prioritize long-term supply agreements with Korean and Japanese automotive tier-1s to lock utilization rates through cyclical downturns. For New Entrants and Emerging Players: Launch via advanced packaging specialization in Bac Ninh and Ho Chi Minh City industrial zones, leveraging Vietnamese land and tax incentives to capture OSAT migration from China-Taiwan corridors. Target heterogeneous integration services for AI accelerator cards as the most penetrable segment, where HBM3E stacking demand outstrips qualified supplier capacity. Pursue Universal Chiplet Interconnect Express certification to enable fabless designers to mix IP blocks across process nodes without captive foundry relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty materials and equipment suppliers serving gate-all-around node transitions. Five-to-ten year viability hinges on exposure to automotive electrification and AI infrastructure buildouts rather than consumer smartphone cycles. Target acquisition archetypes include Japanese photoresist and high-purity chemical producers with METI semiconductor revitalization subsidy eligibility. Watch ASML equipment lead times and Dutch export licensing decisions as the critical inflection indicator for foundry capacity expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Substrates | Japanese power semiconductor IDMs secure automotive traction inverter supply chains against 150mm and 200mm wafer scarcity. |
| Long-term Foundry Capacity Reservations | Automotive electronics divisions at Korean tier-1s lock three-to-five-year allocations for MCU and power management IC categories. |
| Advanced Packaging Facility Expansion | Intel and Amkor investments in Bac Ninh position Vietnam as a backend alternative amid geopolitical supply chain restructuring. |
| Gate-all-around Node Qualification | TSMC and Samsung consolidate process leadership at 2nm, displacing finFET architectures for high-performance computing applications. |
| Domestic Materials Sourcing Mandates | METI's 50% domestic sourcing targets by 2030 accelerate Japanese production of photoresists and high-purity hydrogen fluoride. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with foundry operations executives, fabless design house CTOs, automotive tier-1 procurement directors, and semiconductor equipment supplier account managers. SEC 10-K disclosures, MIIT production statistics, METI subsidy announcements, and Taiwan National Development Council water allocation records provided demand-side and policy validation. Bottom-up wafer start projections and top-down semiconductor consumption estimates were triangulated to reconcile volume and value outputs.
Data-stream reconciliation across foundry utilization rates, capital expenditure disclosures, and end-use shipment data informed the analytical framework. Segmentation dimensions modeled include product type, end user, process technology, and application complexity across the projection horizon. CAGRs were derived from fitted growth curves incorporating equipment lead times, automotive qualification cycle durations, and government subsidy disbursement schedules. Forecast inputs specifically incorporated EUV lithography capacity constraints and fluorinated gas supply concentration risks.
ASML export licensing decisions, drought-induced water allocation restrictions in Hsinchu Science Park, and MIIT dual carbon mandate enforcement intensity are the dominant revision risks to foundry expansion assumptions. Forecasts reflect documented assumptions regarding equipment supplier lead times, automotive platform electrification rates, and government subsidy continuity. Material deviation in any named trigger warrants pause and re-evaluation of capacity utilization and pricing trajectory assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Analog IC Market
IC (Integrated Circuits)
Bluetooth IC Market
IC (Integrated Circuits)
Global Analog Integrated Circuit (IC) Market
IC (Integrated Circuits)
Lithium Battery Charger Ics Market
IC (Integrated Circuits)
United States Integrated Circuits Market
IC (Integrated Circuits)
PFC Control IC Market
IC (Integrated Circuits)
China Analog IC Market
IC (Integrated Circuits)
United States Logic Integrated Circuits Market
IC (Integrated Circuits)
Reset Integrated Circuit (IC) Market
IC (Integrated Circuits)
APAC Analog IC Market
IC (Integrated Circuits)
United States Analog Integrated Circuits Market
IC (Integrated Circuits)
Taiwan Integrated Circuits Market
IC (Integrated Circuits)
Ultra Large Scale Ics Market
IC (Integrated Circuits)
Europe Integrated Circuits Market
IC (Integrated Circuits)
Automotive Special Purpose Logic IC Market
IC (Integrated Circuits)
Mixed-Signal Microcontroller Market