
 Semiconductor Silicon Material Market | 2026-2036
Semiconductor Silicon Material Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Silicon Material Market Insights
Photolithography technician shortages across advanced fabs is bifurcating output between leading-edge nodes and trailing-edge supply. Shin-Etsu Chemical leverages captive polysilicon refining to sustain wafer-grade silicon dominance in Japan. Hemlock Semiconductor anchors North American supply through integrated chlorosilane-to-epitaxial-grade production in Michigan. SUMCO Corporation competes on 300mm monocrystalline ingot scale for logic and memory customers.
Semiconductor silicon material comprises ultrapure silicon refined to electronic-grade specifications, typically achieving impurity levels below one part per billion through Siemens process distillation and Czochralski crystal growth, serving as the foundational substrate for transistor fabrication. Polycrystalline feedstock remains the volume anchor, while monocrystalline wafers command the dominant value share due to exacting crystallographic orientation requirements for EUV lithography compatibility. Hyperpure silicon for power semiconductors is expanding fastest as silicon carbide hybrid modules penetrate automotive traction inverters. Application demand from integrated circuits holds the largest margin pool, whereas solar cell silicon faces pricing pressure from thin-film alternatives.
Japan's METI enforces JIS standards for semiconductor material traceability, while REACH and RoHS in Europe restrict hazardous dopants in silicon wafer manufacturing, reshaping chemistries for epitaxial deposition. The EPA in the United States monitors fluorinated gas emissions from polysilicon purification, adding compliance cost layers to domestic production. Stakeholders must track how divergent carbon-border adjustment mechanisms across these jurisdictions will reroute polysilicon trade flows and localize ingot pulling capacity.
Market Dynamics
Photolithography technician shortages across advanced fabs are bifurcating output between leading-edge nodes and trailing-edge supply, compressing availability for mature-node automotive and industrial chips while EUV-capable facilities absorb scarce talent pools.
Growth Catalysts
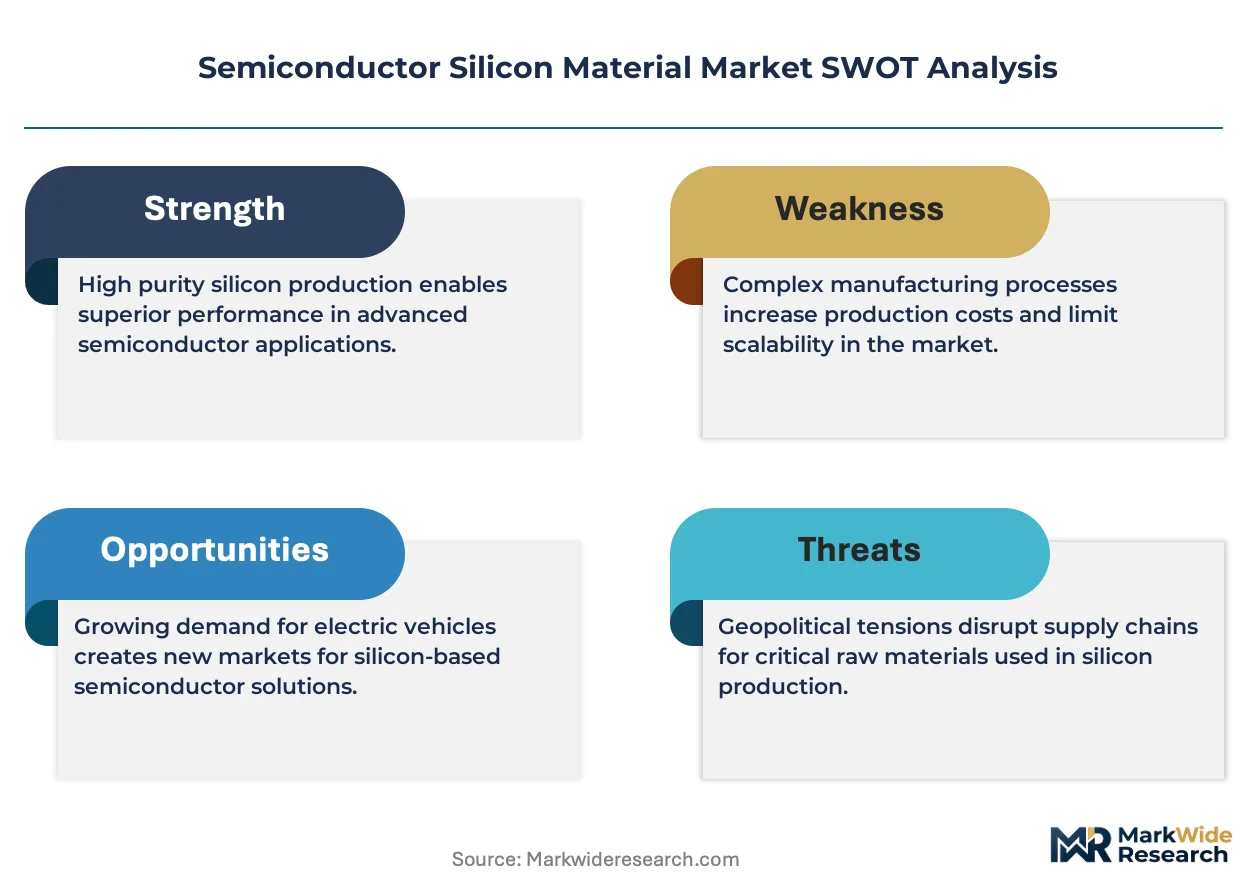
- EU F-Gas Regulation:Phase-down mandates for hydrofluorocarbons in polysilicon purification are accelerating investment in closed-loop chlorosilane recovery systems across European feedstock facilities.
- Electric vehicle powertrain modules:Silicon carbide hybrid inverters for 800V architectures are pulling hyperpure silicon demand from traction semiconductor suppliers at triple the rate of conventional automotive electronics.
- East Asian fabrication clusters:Concentrated ingot pulling capacity across Japan, South Korea, and Taiwan is creating localized supply security that attracts downstream wafer investments.
Market Restraints
- Metallurgical-grade silicon price volatility:Ferrosilicon alloy competition and energy cost spikes in Chinese smelting regions transmit directly to polysilicon feedstock economics.
- Chlorosilane supply concentration:Three integrated producers control trichlorosilane and silicon tetrachloride refining for semiconductor-grade specifications, creating single-source vulnerability for merchant epitaxial buyers.
- Thin-film photovoltaic substitution:Cadmium telluride and perovskite tandem cells are capturing utility-scale solar deployments that previously anchored polysilicon volume.
Strategic Opportunities
- India's semiconductor PLI scheme:Subsidies for compound semiconductors and silicon photonics are attracting polysilicon merchants to establish ingot pulling operations near emerging fab sites.
- Silicon photonics convergence:Co-packaged optical interconnects for AI clusters are creating new specification tiers for silicon-on-insulator substrates with crystallographic tolerances tighter than logic wafers.
- Carbon-border adjustment mechanisms:Embedded emissions accounting for imported polysilicon is incentivizing EU and US captive production with renewable-powered chlorosilane distillation.
Industry Challenges
- Czochralski crystal growth expertise:Decades of tacit knowledge in thermal gradient control and dislocation engineering is retiring faster than apprenticeship pipelines can replenish across Japanese and German equipment vendors.
- EUV mask blank certification timelines:Defect density specifications below 0.003 per square centimeter for pellicle-grade substrates are extending qualification cycles to 18-24 months for new ingot suppliers.
- Legacy 200mm fab equipment integration:Retrofitting monocrystalline pulling furnaces for silicon carbide seed compatibility requires complete thermal zone redesigns that disrupt running production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Silicon Material Market |
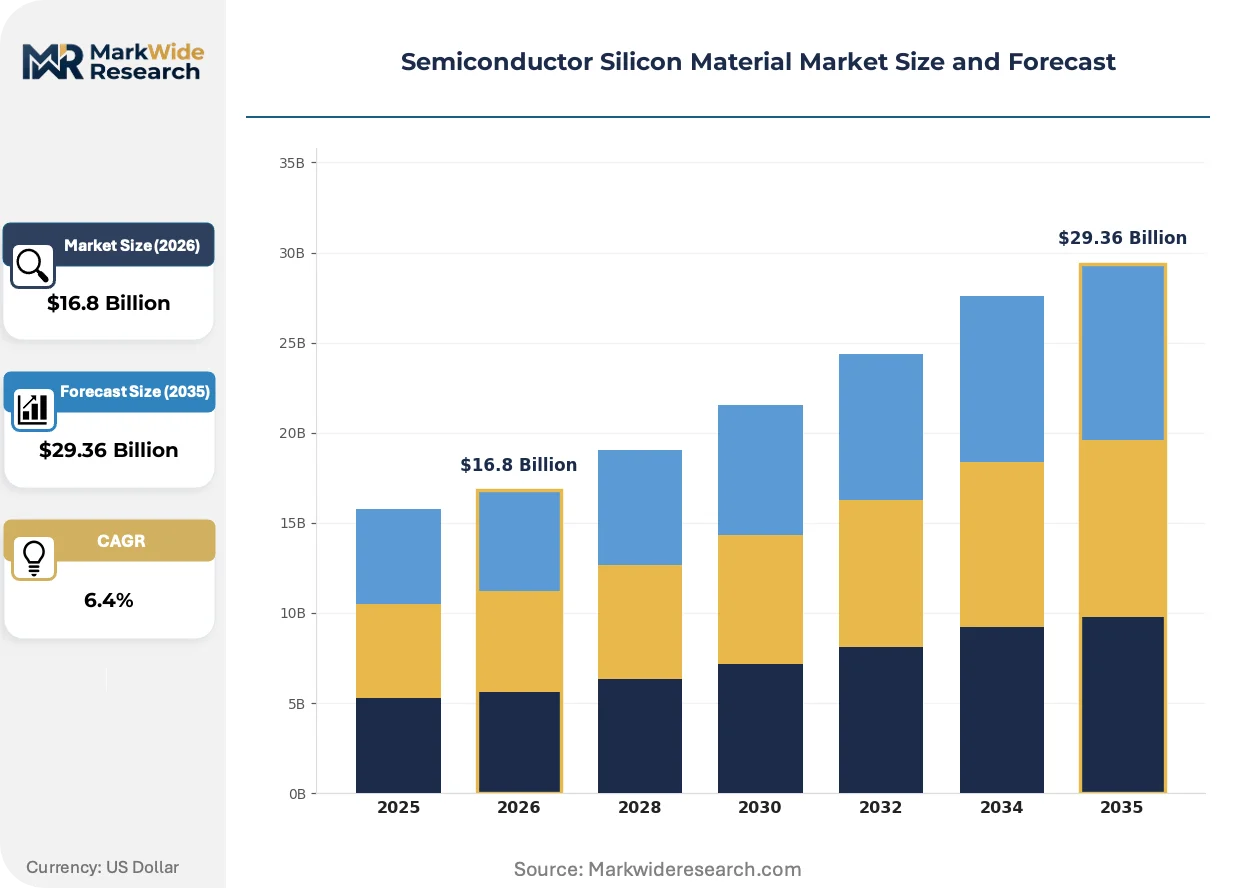
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $29.36 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Amorphous, Hyperpure Application: Integrated Circuits, Solar Cells, LED, Sensors End User: Electronics Industry, Renewable Energy, Telecommunication, Automotive Sales Channel: Direct Sales, Distributors, Online Retail, Technical Representatives |
| Companies Covered | Shin-Etsu Chemical Co., Ltd., Hemlock Semiconductor, SUMCO Corporation, GlobalWafers Co., Ltd., Siltronic AG, SK Siltron Co., Ltd., Soitec S.A., Okmetic Oyj, Wafer Works Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Silicon Material Market Trends and Innovations
Continuous casting methods for solar-grade polysilicon are migrating upward into semiconductor feedstock preparation, challenging the Siemens process dominance that has defined electronic-grade refining for four decades.
Direct solidification techniques using directional solidification furnaces are displacing traditional Czochralski ingots for power semiconductor substrates where minority carrier lifetime requirements are less stringent than logic applications. Onsemi and Infineon have qualified cast silicon for 1.7kV IGBT modules. The structural compression is forcing Czochralski specialists to defend margin pools at 150mm and 200mm diameters where casting cannot yet achieve crystallographic uniformity.
Japan's METI has revised JIS H 0610 standards to mandate blockchain-based material traceability from polysilicon chunk to polished wafer, effective for government procurement contracts. The industrial consequence is a two-tier compliance structure where integrated producers with captive refining gain audit efficiency while merchant wafer vendors face documentation cost premiums. Logic and memory fabs in Yokkaichi and Hiroshima are requiring full chain-of-custody certification from Q3 2025, compressing supplier qualification windows.
Automotive tier-one semiconductor buyers are consolidating silicon wafer procurement through centralized commodity desks rather than fab-level purchasing, compressing supplier negotiation leverage. Bosch and Continental have established dedicated materials sourcing teams in Dresden and Tokyo that bypass traditional distributor relationships for 300mm epitaxial contracts. The geographic concentration of this shift is most visible in German automotive electronics clusters where just-in-sequence wafer delivery is replacing quarterly blanket orders.
Semiconductor Silicon Material Market Segmentation
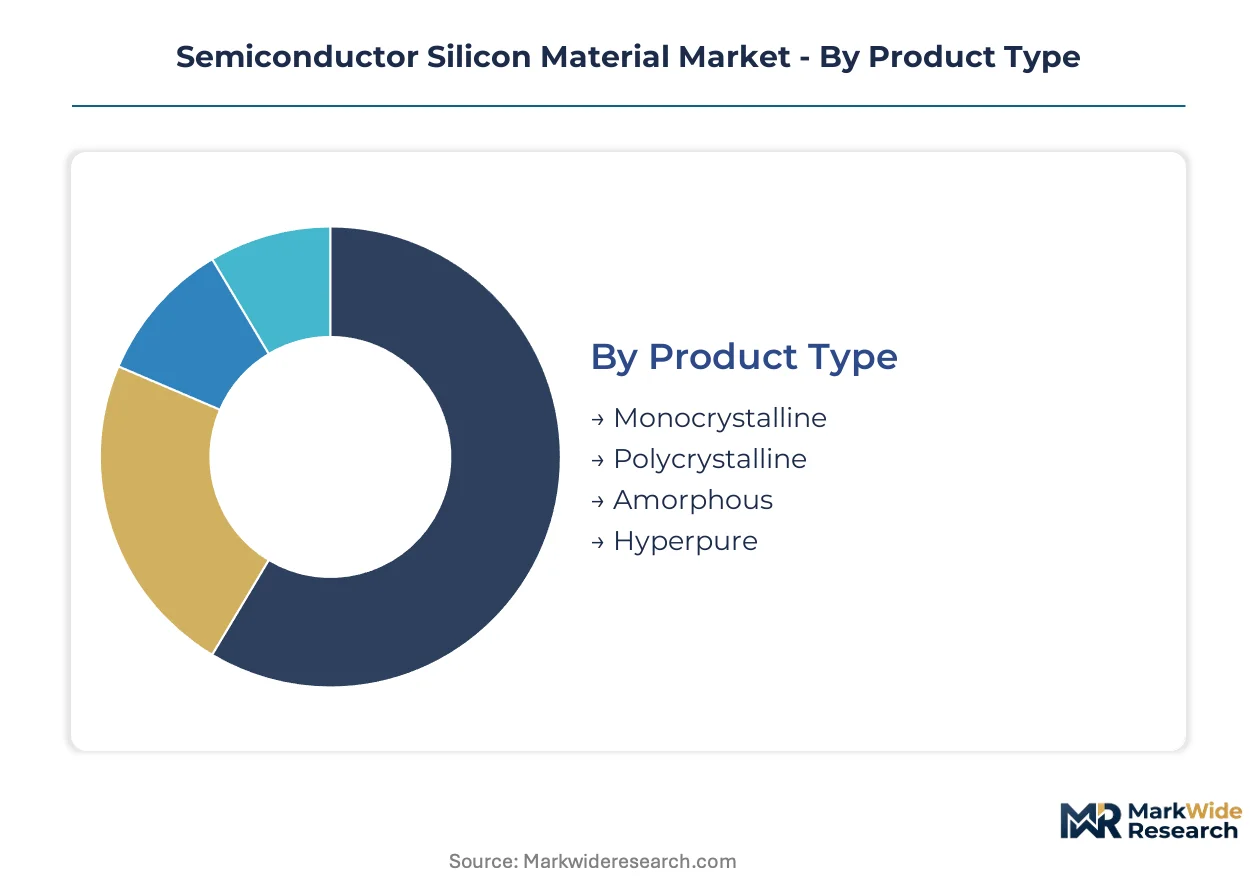
Semiconductor silicon material exhibits distinct demand patterns across product grades, with purity specifications and crystallographic properties determining geographic sourcing strategies and customer qualification timelines. Understanding how these segments intersect with end-use requirements reveals where procurement power concentrates and where new entrants face technical barriers.
Product Type:
Monocrystalline and polycrystalline silicon dominate export flows from East Asian refining clusters, while hyperpure grades remain largely captive to integrated producers serving domestic automotive and power semiconductor customers.
- Monocrystalline:Electronic-grade silicon refined through Czochralski crystal growth achieves impurity levels below one part per billion, with 300mm ingot demand concentrating in Yokkaichi and Hsinchu fabrication clusters serving logic and memory EUV lithography requirements. Japan's METI traceability mandates from Q3 2025 are compressing qualification windows for merchant suppliers lacking captive polysilicon refining.
- Hyperpure:Silicon carbide hybrid power modules for 800V electric vehicle traction inverters are pulling demand from specialized chlorosilane distillation facilities at triple the rate of conventional automotive electronics, with Hemlock Semiconductor's Michigan complex anchoring North American supply security.
- Polycrystalline:Siemens-process feedstock remains the volume anchor for solar and semiconductor applications, though continuous casting methods are challenging four-decade refining dominance.
- Amorphous:Thin-film transistor backplanes for display applications require hydrogenated deposition specifications distinct from crystalline grades.
Monocrystalline holds the largest share; momentum sits with hyperpure as silicon carbide penetration accelerates.
Application:
Margin pools vary sharply across applications, with integrated circuit substrates commanding premium pricing tied to EUV mask blank certification timelines while solar cell silicon faces thin-film substitution pressure.
- Integrated Circuits:Logic and memory fabs in Hiroshima and Dresden require 18-24 month qualification cycles for new ingot suppliers due to defect density specifications below 0.003 per square centimeter for pellicle-grade substrates, consolidating procurement through captive refining arrangements.
- Solar Cells:Cadmium telluride and perovskite tandem cells are capturing utility-scale deployments that previously anchored polysilicon volume, transmitting pricing pressure upstream to metallurgical-grade feedstock economics.
- LED:Sapphire substrate alternatives have compressed silicon-based epitaxial demand to niche visible-spectrum applications.
- Sensors:MEMS fabs in Bosch's Dresden cluster source 150mm silicon-on-insulator wafers through centralized commodity desks bypassing traditional distributor relationships.
Integrated circuits capture the dominant margin pool; solar cells face the steepest pricing compression.
End User:
Automotive procurement centralization is reshaping supplier relationships, with tier-one semiconductor buyers consolidating silicon wafer sourcing through dedicated materials teams rather than fab-level purchasing.
- Electronics Industry:Logic and memory fabs concentrate 300mm epitaxial procurement in East Asian clusters where ingot pulling capacity creates localized supply security.
- Automotive:Bosch and Continental have established centralized sourcing teams in Dresden and Tokyo that negotiate just-in-sequence wafer delivery replacing quarterly blanket orders.
- Renewable Energy:Utility-scale solar deployments are shifting toward thin-film alternatives, reducing polysilicon volume anchoring.
- Telecommunication:Silicon photonics for AI cluster interconnects is creating new specification tiers with crystallographic tolerances tighter than logic wafers.
Electronics industry retains the largest procurement volume; automotive exhibits the fastest sourcing centralization.
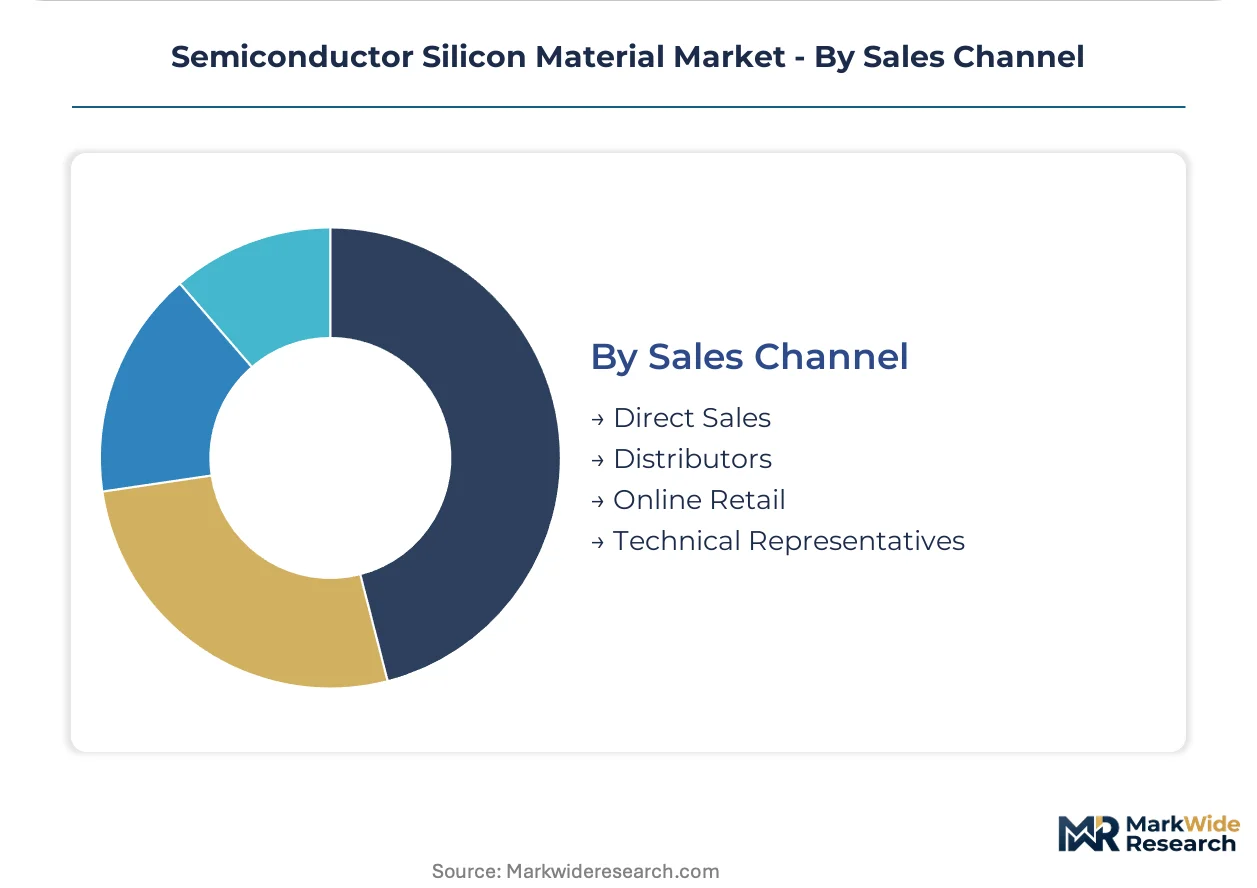
Sales Channel:
Channel structure reflects customer scale and technical complexity, with direct sales dominating high-volume epitaxial contracts while technical representatives serve qualification-intensive new product introductions.
- Direct Sales:Automotive tier-one buyers and large fabs negotiate 300mm contracts through centralized commodity desks, compressing distributor leverage.
- Technical Representatives:New ingot suppliers rely on field engineering support to navigate 18-24 month EUV mask blank certification timelines.
- Distributors:Merchant wafer vendors face documentation cost premiums under Japan's blockchain traceability mandates.
- Online Retail:Limited to standard-grade polysilicon feedstock and consumables for research quantities.
Direct sales command the highest contract value; technical representatives enable the most complex qualification pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI in Japan enforces JIS H 0610 standards that mandate blockchain-based material traceability from polysilicon chunk to polished wafer, creating compliance tiers that favor integrated producers with captive refining capabilities across East Asian fabrication clusters.
Japan
Logic and memory fabs in Yokkaichi and Hiroshima drive 300mm monocrystalline demand for EUV lithography compatibility. METI's revised traceability standards effective Q3 2025 compress supplier qualification windows to 18-24 months for pellicle-grade substrates. Shin-Etsu Chemical leverages captive polysilicon refining in Gunma Prefecture to sustain wafer-grade silicon dominance.
China
Dual carbon goals and MEE emissions monitoring are tightening feedstock and process standards for polysilicon purification facilities. Metallurgical-grade silicon price volatility from ferrosilicon alloy competition transmits directly to electronic-grade feedstock economics. Yangtze River Delta fabrication clusters in Shanghai and Wuxi concentrate ingot pulling capacity that attracts downstream wafer investments.
South Korea
Silicon carbide hybrid power modules for 800V electric vehicle architectures pull hyperpure silicon demand from automotive semiconductor suppliers. MFDS oversight of hazardous dopants in wafer manufacturing reshapes chemistries for epitaxial deposition. Pyeongtaek and Giheung fabrication complexes anchor memory and logic production requiring defect density specifications below 0.003 per square centimeter.
United States
EPA monitoring of fluorinated gas emissions from polysilicon purification adds compliance cost layers to domestic production. Carbon-border adjustment mechanisms incentivize captive production with renewable-powered chlorosilane distillation. Hemlock Semiconductor's Michigan complex anchors North American supply security through integrated chlorosilane-to-epitaxial-grade production.
Germany
Bosch and Continental have established centralized materials sourcing teams in Dresden that negotiate just-in-sequence wafer delivery replacing quarterly blanket orders. REACH and RoHS restrictions on hazardous dopants reshape silicon wafer manufacturing chemistries for epitaxial deposition. Saxony's automotive electronics clusters drive procurement centralization for 300mm epitaxial contracts.
Semiconductor Silicon Material Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in semiconductor silicon material supply. Three producers control trichlorosilane and silicon tetrachloride refining for semiconductor-grade specifications, creating single-source vulnerability for merchant epitaxial buyers. Strategic archetypes include captive refiners with backward integration into polysilicon, merchant wafer specialists dependent on external feedstock, and compound semiconductor substrate diversifiers. Competitive moves center on capacity expansion for 300mm monocrystalline ingots and strategic partnerships for silicon carbide seed compatibility.
Among Japanese integrated producers, Shin-Etsu Chemical Co., Ltd. and SUMCO Corporation exemplify the captive-refiner archetype with in-house polysilicon capabilities. Hemlock Semiconductor occupies a position representing North American supply security through geographically concentrated chlorosilane-to-epitaxial-grade production. These three anchors demonstrate how backward integration into feedstock refining creates audit efficiency under emerging traceability mandates while merchant competitors face documentation cost premiums.
| Leading Market Players |
|---|
| Shin-Etsu Chemical Co., Ltd. |
| Hemlock Semiconductor |
| SUMCO Corporation |
| GlobalWafers Co., Ltd. |
| Siltronic AG |
| SK Siltron Co., Ltd. |
| Soitec S.A. |
| Okmetic Oyj |
| Wafer Works Corporation |
| Others |
Pricing and Supply Chain Analysis
300mm ingot pulling economies in Yokkaichi and Hsinchu fabrication clusters compress unit costs through thermal zone utilization rates above 85%, establishing price floors that merchant wafer vendors cannot match without captive polysilicon refining. This scale concentration simultaneously concentrates procurement leverage among logic and memory fabs while forcing smaller players toward 150mm and 200mm specialty tiers where casting methods challenge Czochralski dominance.
Pricing Analysis
Geographic price spreads between East Asian fabrication clusters and North American merchant markets exceed 15% for 300mm epitaxial contracts, reflecting localized supply security premiums. Three-tier pricing structure across EUV-grade, automotive-qualified, and solar-feedstock tiers differentiates by certification level and defect density specifications. Cost compression in solar-grade polysilicon is intensifying because cadmium telluride and perovskite tandem cells capture utility-scale deployments. Automotive tier-one buyers exhibit lowest price sensitivity due to just-in-sequence delivery requirements, while solar cell manufacturers face acute margin pressure from thin-film substitution.
Supply Chain Analysis
Inbound logistics costs from chlorosilane refining facilities in Michigan and Tennessee to epitaxial deposition centers in Texas and Arizona fluctuate with container availability across Pacific trade lanes. Supply concentrates in Japan, South Korea, and Taiwan for monocrystalline ingot pulling, while Germany and the United States anchor hyperpure silicon for automotive power modules. Raw material dependencies rest on metallurgical-grade silicon from Chinese smelting regions, trichlorosilane from integrated chlorosilane producers, and high-purity quartz crucibles for Czochralski growth. Single-source vulnerability in semiconductor-grade chlorosilane refining creates structural risk for merchant epitaxial buyers. Distribution runs through direct sales contracts for high-volume automotive and logic fab customers, with technical representatives serving qualification-intensive new product introductions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-based material traceability services represent a faster-expanding recurring revenue layer than hardware margins, as Japan's METI mandates and EU carbon-border adjustment mechanisms force documentation premiums upon merchant wafer vendors lacking captive refining.
For Market Incumbents: Secure backward integration into polysilicon refining to sustain audit efficiency under emerging traceability mandates, while adding silicon carbide seed compatibility to 200mm furnace fleets before casting methods capture power semiconductor substrate share. Threat from continuous casting techniques in solar-grade migration upward demands capacity defense at 150mm diameters where crystallographic uniformity still favors Czochralski expertise. For New Entrants and Emerging Players: EUV mask blank certification fast-tracks through partnerships with established Japanese equipment vendors offer the most penetrable pathway, targeting India's semiconductor PLI scheme for ingot pulling operations near emerging fab sites. White-space exists in silicon photonics substrates for AI cluster interconnects, where crystallographic tolerances exceed logic wafer specifications. Go-to-market angle centers on co-packaged optical interconnect qualification support for hyperscaler data center buildouts. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compound semiconductor substrate diversifiers with silicon carbide hybrid module exposure over pure-play silicon merchants facing casting displacement. Long-term viability across the projection horizon hinges on renewable-powered chlorosilane distillation assets that satisfy EU and US carbon-border adjustment mechanisms. Acquisition target archetype: integrated producers with captive polysilicon and established automotive qualification pipelines. Signal to watch: qualification cycle compression below 18 months for pellicle-grade substrates indicating ingot supply tightness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon Refining | Captive chlorosilane distillation eliminates documentation cost premiums under Japan's METI blockchain mandates. |
| Silicon Carbide Seed Compatibility Retrofit | 200mm furnace thermal zone redesigns defend power semiconductor substrate share against directional solidification casting. |
| Renewable-Powered Chlorosilane Distillation | EU carbon-border adjustment mechanisms incentivize low-embedded-emissions production for automotive epitaxial contracts. |
| EUV Mask Blank Certification Fast-Track | 18-24 month qualification cycles compress supplier windows for merchant ingot vendors seeking logic fab entry. |
| Silicon Photonics Substrate Qualification | Co-packaged optical interconnects for AI clusters demand crystallographic tolerances tighter than conventional logic wafers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across photolithography technicians, epitaxial deposition engineers, automotive semiconductor procurement leads, and polysilicon plant managers. Primary interviews combined with secondary validation from SEC filings of listed wafer vendors, EPA fluorinated gas emission disclosures, METI JIS standard revisions, and EU F-Gas Regulation implementation guidance. Bottom-up triangulation across ingot pulling capacity utilization rates and top-down cross-check against semiconductor capital expenditure disclosures anchored volume estimates.
Across the analysis window, the analytical framework modeled product type segmentation by monocrystalline, hyperpure, polycrystalline, and amorphous grades; application segmentation across integrated circuits, solar cells, LEDs, and sensors; and end-user segmentation spanning electronics industry, automotive, renewable energy, and telecommunication. CAGRs derived from capacity expansion announcements, qualification timeline compression rates, and substitution elasticity estimates for silicon carbide hybrid power modules. Industry-specific forecast inputs included EUV lithography node migration schedules and electric vehicle 800V architecture penetration curves.
Underlying assumptions cover sustained chlorosilane supply concentration, stable metallurgical-grade silicon feedstock economics, and gradual casting method penetration into power semiconductor substrates, with deviation risk concentrated in regulatory acceleration of carbon-border adjustments or breakthrough perovskite tandem cell efficiency gains. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Titanium Diboride Market
Semiconductor Material
Hafnium Market
Semiconductor Material
Global Thermal Paste Market
Semiconductor Material
DCB and AMB Substrate Market
Semiconductor Material
Sapphire Substrate Market
Semiconductor Material
Semiconductor Grade PTFE Market
Semiconductor Material
Asia-Pacific Silicone Market
Semiconductor Material
Quartz Market
Semiconductor Material
Silicon Germanium Material Market
Semiconductor Material
Europe Silicone Market
Semiconductor Material
5G Substrate Materials Market
Semiconductor Material
Middle East Silicon Carbide (Sic) Market
Semiconductor Material
Polymethylhydrosiloxane Market
Semiconductor Material
PP Capacitor Films Market
Semiconductor Material
Global Silicone Market
Semiconductor Material
Cadmium Telluride Market