
 Surface Mount Technology (SMT) Market | 2026-2036
Surface Mount Technology (SMT) Market Size, Share, and Industry Trends Forecast 2026-2036
Surface Mount Technology (SMT) Market Insights
China is fragmenting as contract manufacturers and domestic equipment vendors expand SMT capacity across the Yangtze River Delta and Pearl River Delta clusters. Yamaha Motor Co. Ltd. leverages its precision motion control heritage to dominate high-speed placement systems for smartphone PCB production. ASMPT Limited anchors its position through deep software integration between placement, inspection, and material logistics modules. Fuji Corporation differentiates via laser soldering specialization for miniaturized automotive sensor packages.
Surface Mount Technology refers to an electronics assembly method where components mount directly onto printed circuit board surfaces rather than through drilled holes, utilizing solder paste deposition, automated component placement, and controlled thermal reflow to achieve interconnect densities exceeding 200 components per square centimeter in consumer devices. The technology serves the core purpose of enabling miniaturized, high-reliability electronic assemblies for mass production. PCB Assemblies command the largest value share as the integrated system-level output that absorbs placement, soldering, and inspection equipment across production lines. Active Components represent the fastest-growing equipment demand segment as advanced packaging formats like flip-chip and wafer-level chip scale packages require higher-precision placement platforms. Reflow technology leads process equipment value due to its dominance in high-volume consumer electronics, while Laser Soldering captures expanding share in medical device and aerospace applications demanding localized thermal control.
RoHS restrictions on lead content and REACH substance authorization requirements in Europe shape solder material formulations and flux chemistry portfolios across the supply chain. The EPA oversees hazardous waste classification for spent solder dross and flux residues in US manufacturing facilities, while China's GB standards and MIIT directives enforce domestic equipment certification and energy efficiency benchmarks for imported SMT lines. Stakeholders must monitor how evolving semiconductor packaging roadmaps toward heterogeneous integration reshape placement accuracy requirements and equipment replacement cycles.
Market Dynamics
Component miniaturization thresholds below 0.3mm pitch are forcing placement equipment refresh cycles while heterogeneous integration roadmaps from semiconductor packaging consortia redefine accuracy benchmarks across automotive and medical device production lines.
Growth Catalysts
- Electric vehicle powertrain controllers:Automotive electronics manufacturers are expanding SMT adoption for battery management systems and inverter modules, with Tier 1 suppliers scaling dedicated high-volume lines for EV platforms.
- REACH substance authorization:Europe's tightening material purity standards for solder alloys and flux chemistries are accelerating compliant formulation development and creating specification premiums for certified suppliers.
- Yangtze River Delta PCB clusters:Domestic equipment vendors and contract manufacturers in China are concentrating high-volume SMT capacity for 5G infrastructure and consumer electronics export fulfillment.
Market Restraints
- Silver and tin price volatility:Solder alloy feedstock costs fluctuate with commodity metal markets, compressing margin visibility for EMS providers on fixed-price assembly contracts.
- High-speed placement equipment oligopoly:Precision motion control platforms for sub-0.4mm component handling depend on a concentrated supplier base in Japan and Germany, creating procurement bottlenecks during capacity ramps.
- RoHS lead-content thresholds:Exemptions for high-reliability aerospace and defense applications are narrowing, forcing costly alloy substitutions in legacy product lines without equivalent thermal fatigue performance.
Strategic Opportunities
- Laser soldering for medical devices:Localized thermal control requirements in implantable electronics and diagnostic equipment are opening premium equipment segments beyond traditional reflow dominance.
- Wafer-level chip scale packaging:Flip-chip and advanced packaging formats are demanding higher-precision placement platforms with sub-10-micron accuracy, expanding addressable equipment value per line.
- Software-integrated production modules:Deep integration between placement, inspection, and material logistics systems is creating recurring revenue streams through predictive maintenance and yield optimization subscriptions.
Industry Challenges
- Multi-physics simulation expertise:Thermal management and warpage prediction for complex PCB assemblies require scarce cross-disciplinary engineering capabilities spanning materials science and computational modeling.
- GB standards certification timelines:China's MIIT directives for domestic equipment certification and energy efficiency benchmarks impose extended validation periods for imported SMT line deployments.
- Legacy through-hole integration:Mixed-technology assemblies combining surface mount and conventional components complicate process optimization and defect traceability in automotive safety-critical applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surface Mount Technology (SMT) Market |
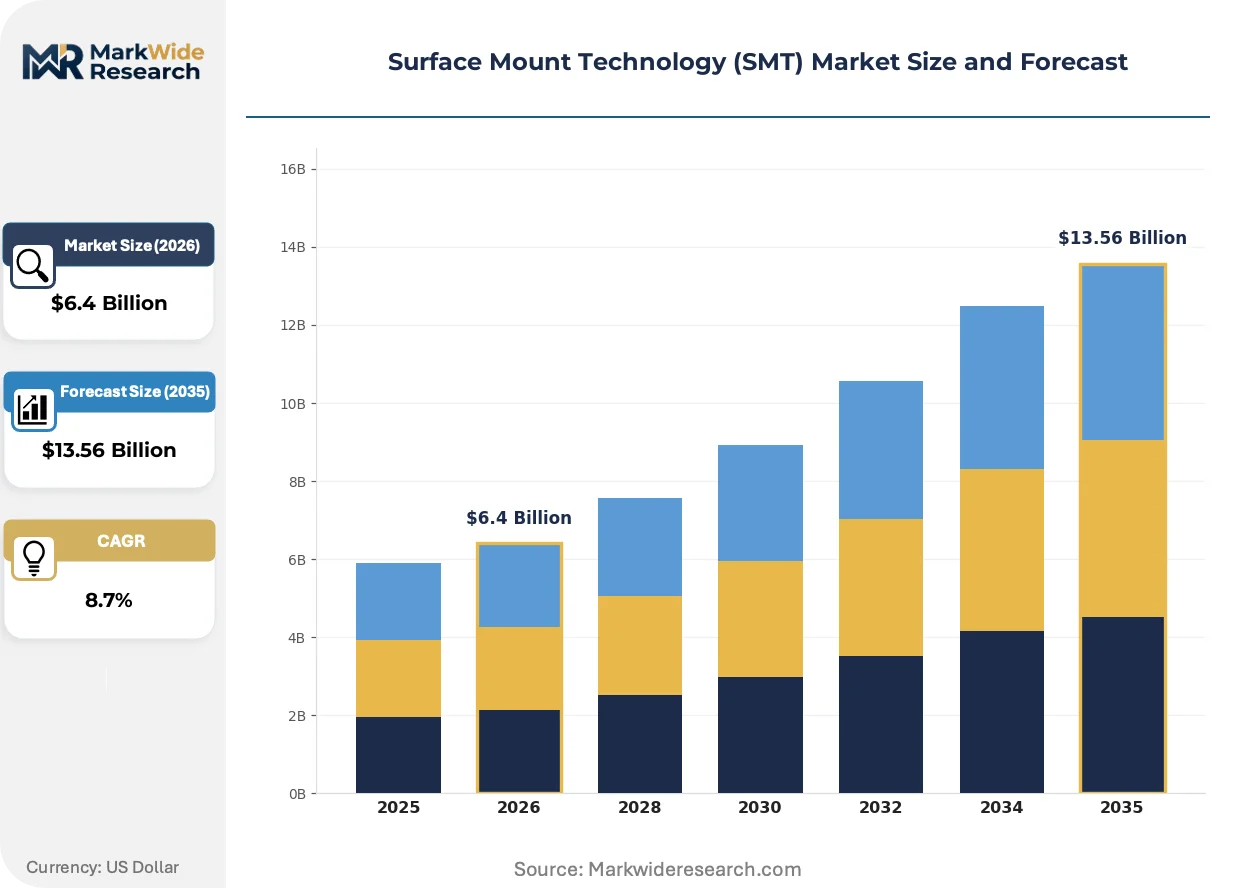
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $13.56 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PCB Assemblies, Passive Components, Active Components, Connectors Technology: Reflow, Wave Soldering, Laser Soldering, Manual Soldering End User: Consumer Electronics, Automotive, Industrial Equipment, Telecommunications Application: Mobile Devices, Home Appliances, Medical Devices, Aerospace |
| Companies Covered | Yamaha Motor Co. Ltd., ASM Assembly Systems GmbH & Co. KG, ASMPT Limited, Mycronic AB, Juki Corporation, Fuji Corporation, Nordson Corporation, Hanwha Precision Machinery Co., Ltd., Panasonic Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surface Mount Technology (SMT) Market Trends and Innovations
Placement accuracy requirements are compressing equipment replacement cycles while thermal process control technologies fragment across end-use reliability tiers. Software-defined production orchestration is emerging as the primary differentiation vector.
Miniaturized component formats below 01005 imperial case size are collapsing the distinction between semiconductor packaging and board-level assembly. Medical device manufacturers and smartphone PCB producers are adopting these formats fastest. The technology is collapsing traditional equipment category boundaries as placement platforms must now handle both bare die and packaged components interchangeably.
REACH Annex XIV substance authorization procedures are restricting flux activator chemistries and solder alloy additives across European manufacturing. Formulation houses are accelerating halogen-free and low-residue flux development to maintain market access. Automotive sensor packaging and EV battery management modules face the tightest compliance timelines, with OEMs dual-sourcing qualified materials to mitigate authorization uncertainty.
Consolidated procurement of SMT line equipment is displacing point-solution purchasing as EMS providers seek unified vendor accountability for throughput and yield metrics. Tier 1 contract manufacturers in China and Taiwan are bundling placement, inspection, and reflow platforms under multi-year performance contracts. This concentration is most visible in 5G infrastructure PCB production, where single-source vendor relationships reduce qualification overhead for high-mix, high-volume programs.
Surface Mount Technology (SMT) Market Segmentation
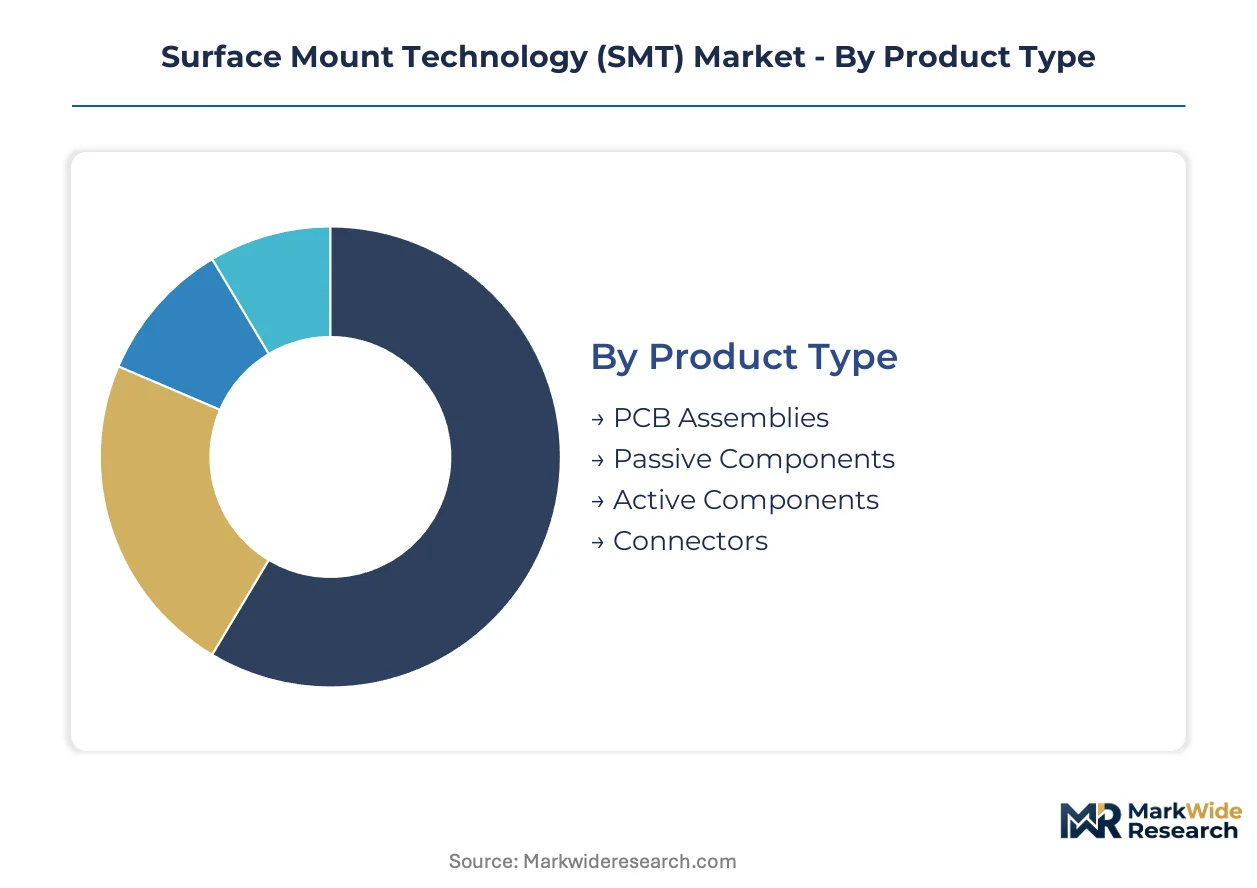
SMT market segmentation reveals how equipment and material demand fragments across reliability tiers, thermal process requirements, and miniaturization thresholds. Understanding these splits exposes where capital expenditure concentrates and which technology transitions command premium pricing.
Product Type:
Cost tier differentiation separates integrated system outputs from discrete component supply, with value capture varying dramatically across the assembly stack.
- PCB Assemblies:Integrated system-level output absorbing placement, soldering, and inspection equipment across complete production lines. Automotive Tier 1 suppliers in Germany and Japan scale dedicated high-volume lines for EV powertrain controllers, absorbing the largest equipment capex per square meter of factory floor.
- Active Components:Advanced packaging formats including flip-chip and wafer-level chip scale packages demanding sub-10-micron placement accuracy. Medical device manufacturers in Switzerland and Massachusetts are expanding fastest as implantable electronics require higher-precision platforms for miniaturized sensor integration.
- Passive Components:Capacitors, resistors, and inductors in 01005 and smaller case sizes for high-density consumer PCB layouts.
- Connectors:High-reliability interconnects for automotive and aerospace applications with specialized coplanarity requirements.
PCB Assemblies holds installed capacity. Active Components is rotating up the share rankings.
Technology:
Application thermal requirements fragment process equipment selection across reliability tiers, from consumer electronics to implantable medical devices.
- Reflow:Dominant thermal process utilizing forced convection ovens for high-volume consumer electronics with precise temperature profiling across multiple zones. China's Yangtze River Delta PCB clusters deploy the most reflow capacity for 5G infrastructure and smartphone export fulfillment.
- Laser Soldering:Localized thermal control for heat-sensitive components and miniaturized automotive sensor packages. Swiss and German medical device manufacturers are expanding fastest for implantable electronics where reflow thermal exposure risks component damage.
- Wave Soldering:Through-hole and mixed-technology assemblies for industrial equipment with legacy component integration.
- Manual Soldering:Low-volume prototyping and repair operations with limited automation applicability.
Reflow commands the equipment installed base. Laser Soldering is climbing the fastest.
End User:
Volume concentration and margin structure vary sharply across customer industries, with automotive and telecommunications demanding divergent equipment specifications.
- Consumer Electronics:Smartphone, tablet, and wearable PCB production requiring highest placement speeds and smallest component handling. Contract manufacturers in Shenzhen and Dongguan absorb the most high-speed placement equipment for Apple and Android device fulfillment.
- Automotive:Battery management systems, inverter modules, and ADAS sensor packaging with stringent thermal cycling reliability. Tier 1 suppliers in Stuttgart, Toyota City, and Detroit are scaling dedicated EV lines with automotive-grade placement accuracy.
- Industrial Equipment:Motor drives, power supplies, and control systems with extended product lifecycles and mixed-technology requirements.
- Telecommunications:5G base station and optical networking hardware with high-layer-count PCB complexity.
Consumer Electronics holds installed capacity. Automotive is gaining share fastest.
Application:
Maturity and certification requirements segment demand across medical, aerospace, and consumer use cases with radically different qualification timelines.
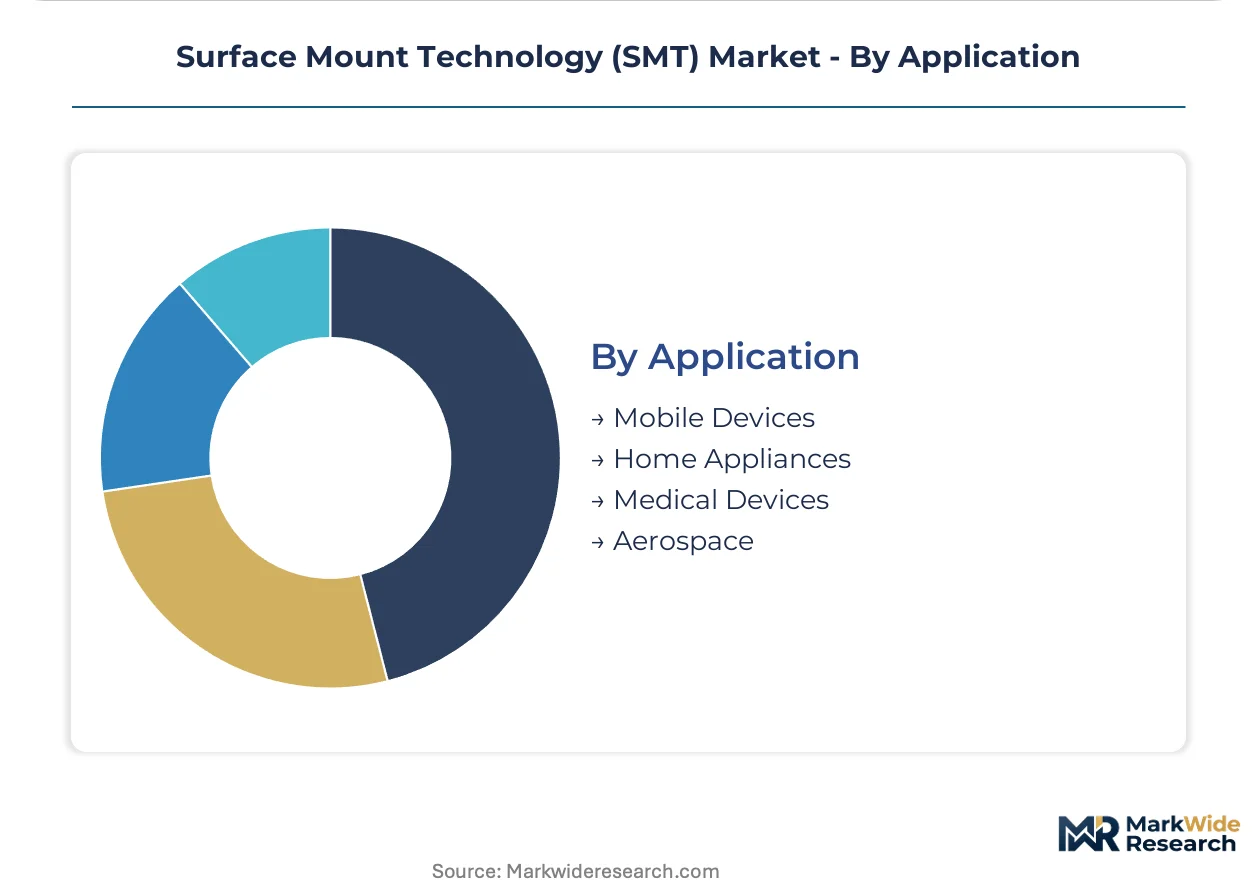
- Mobile Devices:Smartphone and tablet PCBs with highest component density and shortest product refresh cycles. EMS providers in Taiwan and Vietnam run the most placement lines for flagship device launches.
- Medical Devices:Diagnostic equipment and implantable electronics requiring FDA, EMA, and NMPA compliance with extensive validation documentation. Manufacturers in Minneapolis and Frankfurt are expanding laser soldering capacity fastest for localized thermal control.
- Home Appliances:White goods control boards with cost-optimized placement and extended reliability requirements.
- Aerospace:Avionics and satellite hardware with IPC Class 3 reliability and narrow RoHS exemption windows for high-reliability alloys.
Mobile Devices holds installed capacity. Medical Devices is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai-Ningbo port complex underwrites China's dominance in SMT equipment import and PCB export throughput, while the Rhine-Main corridor anchors European high-precision assembly demand.
China
MIIT directives enforce GB standards certification and energy efficiency benchmarks for imported SMT lines. The Yangtze River Delta clusters in Suzhou and Wuxi concentrate high-volume placement capacity for 5G infrastructure boards. Domestic equipment vendors and contract manufacturers scale dedicated lines for consumer electronics export fulfillment.
Germany
Automotive Tier 1 suppliers in Stuttgart scale dedicated EV powertrain controller lines with automotive-grade placement accuracy. REACH Annex XIV substance authorization restricts flux activator chemistries and solder alloy additives across manufacturing. The Baden-Württemberg industrial corridor hosts precision equipment integration facilities serving European EMS providers.
United States
EPA hazardous waste classification for spent solder dross shapes facility compliance costs in domestic manufacturing. The EPA oversees flux residue handling protocols across SMT production sites. Greater Boston medical device manufacturers expand laser soldering capacity for implantable electronics requiring localized thermal control.
Japan
METI industrial technology roadmaps guide placement accuracy benchmarks for sub-0.4mm component handling. The Chubu region around Nagoya anchors precision motion control equipment production for smartphone PCB lines. Domestic vendors leverage heritage in robotics and automation to supply high-speed placement platforms.
South Korea
Seoul Capital Area contract manufacturers absorb high-speed placement equipment for flagship smartphone launches. MFDS medical device regulations align with FDA and EMA standards for diagnostic equipment validation. The Busan-Ulsan corridor concentrates PCB fabrication for telecommunications and consumer electronics exports.
Surface Mount Technology (SMT) Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in placement, inspection, and thermal process modules. The vendor base concentrates around precision motion control platforms with sub-10-micron accuracy capabilities. Three archetypes dominate: high-speed placement specialists, software-integrated production module providers, and laser soldering equipment innovators. Consolidated procurement patterns favor multi-year performance contracts bundling complete SMT lines, while technology licensing agreements accelerate access to emerging packaging formats.
Among Japanese precision equipment manufacturers, Yamaha Motor Co. Ltd. and Fuji Corporation exemplify the high-speed placement archetype with heritage in motion control systems. ASMPT Limited anchors the software-integrated tier through deep module connectivity between placement, inspection, and material logistics. These three entities represent distinct competitive positioning vectors within a market where unified vendor accountability displaces point-solution purchasing.
| Leading Market Players |
|---|
| Yamaha Motor Co. Ltd. |
| ASM Assembly Systems GmbH & Co. KG |
| ASMPT Limited |
| Mycronic AB |
| Juki Corporation |
| Fuji Corporation |
| Nordson Corporation |
| Hanwha Precision Machinery Co., Ltd. |
| Panasonic Holdings Corporation |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in China's Yangtze River Delta SMT equipment fabrication clusters is compressing margin visibility for placement system vendors while simultaneously granting EMS providers procurement leverage on multi-year performance contracts. This utilization dynamic feeds back into supplier pricing posture, forcing Japanese and German precision equipment manufacturers to bundle software subscriptions and predictive maintenance modules to defend realized pricing.
Pricing Analysis
REACH Annex XIV substance authorization dictates the pricing tier structure across European SMT material supply, separating halogen-free certified flux formulations from standard-grade chemistries. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with automotive Tier 1 suppliers absorbing the least price sensitivity due to qualification lock-in. Cost compression in economy-tier solder alloys is intensifying because silver and tin feedstock volatility erodes fixed-price contract viability. Contract manufacturers in Vietnam and Mexico exhibit the highest price sensitivity, prioritizing equipment with lowest capital expenditure per placement line.
Supply Chain Analysis
Extended payment terms from EMS consolidators in Taiwan and South Korea are reshaping supplier working capital requirements across Japanese precision motion control vendors. Geographic supply concentration centers on Japan, Germany, and China for high-speed placement platforms, while solder alloy feedstock draws from Indonesian tin smelters and Peruvian silver mining operations. Single-source vulnerability in sub-10-micron accuracy linear motor assemblies creates procurement bottlenecks during capacity ramps for heterogeneous integration roadmaps. Distribution runs through direct vendor-to-EMS relationships with limited intermediary channel presence, reflecting the technical complexity of line integration services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SMT equipment procurement is shifting toward platform-economics logic as software-defined production orchestration displaces point-solution purchasing, with unified vendor accountability becoming the dominant interoperability standard across Tier 1 contract manufacturers.
For Market Incumbents: Harden software integration moats between placement, inspection, and material logistics modules to defend against modular challengers offering best-of-breed point solutions. Deepen backward integration into machine vision subsystems to capture margin leakage from third-party inspection component suppliers. Priority investment in predictive maintenance algorithm development preserves recurring revenue streams as hardware commoditization accelerates.
For New Entrants and Emerging Players: Establish a beachhead in laser soldering equipment for medical device manufacturers, where localized thermal control requirements create specification premiums beyond reflow dominance. Target Swiss and German implantable electronics producers with sub-5-micron accuracy platforms, as these customers prioritize technical performance over total cost of ownership. Go-to-market leverage through partnerships with existing flux formulation houses accelerates qualification timelines.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across wafer-level chip scale packaging placement platforms as sub-10-micron accuracy requirements demand precision motion control engineering talent scarcity. Long-term viability favors vendors with installed base scale sufficient to amortize software development costs across multi-year subscription contracts. Acquisition target archetype: mid-tier placement equipment specialists with dormant automotive certification pipelines. Signal to monitor: MIIT directive enforcement intensity affecting imported SMT line deployment timelines in China.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Integrated Production Module Development | Deep connectivity between placement, inspection, and logistics creates recurring revenue streams through yield optimization subscriptions. |
| Laser Soldering Capacity Expansion | Swiss and German medical device manufacturers absorb localized thermal control platforms fastest for implantable electronics production. |
| REACH-Compliant Formulation Investment | Halogen-free flux development preserves European market access as Annex XIV authorization procedures tighten. |
| Automotive-Grade Certification Pipeline | Tier 1 suppliers in Stuttgart and Toyota City scale dedicated EV powertrain controller lines with stringent reliability requirements. |
| Precision Motion Control Talent Acquisition | Sub-0.4mm component handling capabilities concentrate in Japanese and German engineering clusters with limited supply elasticity. |
Research Methodology
A spread of perspectives from SMT equipment procurement directors, EMS operations executives, semiconductor packaging engineers, and flux formulation chemists converged on the working assumptions underpinning this analysis. Primary interviews with placement platform vendors and contract manufacturing site managers combined with secondary validation from METI industrial technology roadmaps, EPA hazardous waste classification protocols, and REACH Annex XIV substance authorization databases. Bottom-up equipment shipment tracking and top-down PCB assembly value analysis provided triangulation across modeling approaches.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation dimensions spanning product type, thermal process technology, end-use industry vertical, and miniaturization threshold tier. CAGRs derived from equipment replacement cycle velocity and semiconductor packaging roadmap transitions, incorporating heterogeneous integration adoption curves and automotive electrification content-per-vehicle expansion as industry-specific forecast inputs.
Sensitivities concentrate around silver and tin commodity price volatility, MIIT certification timeline extensions for imported SMT lines, and RoHS exemption narrowing for high-reliability aerospace alloys. Forecasts reflect documented assumptions regarding equipment accuracy requirement compression and software subscription attach rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Manufacturing
PCB Photoresist Market
Semiconductor Manufacturing
Europe Electronic Manufacturing Services Market
Semiconductor Manufacturing
Advanced Process Control Market
Semiconductor Manufacturing
Semiconductor and Electronic Parts Manufacturing Market
Semiconductor Manufacturing
EUV Lithography Service Market
Semiconductor Manufacturing
Global Overall EUV Lithography Market
Semiconductor Manufacturing
Semiconductor and Circuit Manufacturing Market
Semiconductor Manufacturing
Global Wafer Cutting Fluids Market
Semiconductor Manufacturing
Semiconductor Polishing Pads Market
Semiconductor Manufacturing
Photoresist Stripper Market
Semiconductor Manufacturing
Semiconductor Bonding Machine Market
Semiconductor Manufacturing
Europe Photoresist and Photoresist Ancillaries Market
Semiconductor Manufacturing
Photoresist and Photoresist Ancillaries Market
Semiconductor Manufacturing
Battery Manufacturing Machines Market
Semiconductor Manufacturing
Middle East and Africa Cell Manufacturing Market
Semiconductor Manufacturing
Thin Film Semiconductor Deposition Market