
 Transparent Cache Market | 2026-2036
Transparent Cache Market Size, Share, and Industry Trends Forecast 2026-2036
Transparent Cache Market Outlook
The gap between enterprise-grade transparent cache tiers and commodity edge caching is realigning around latency guarantees and programmable control planes. Cisco Systems leverages its carrier router integration to anchor premium deployments in tier-one networks. Akamai Technologies competes through its distributed edge fabric, while Cloudflare differentiates on serverless compute co-location with cache nodes.
Transparent cache refers to network-resident storage systems that intercept content requests without client-side configuration, typically operating at Layer 4-7 with sub-50 millisecond response targets to reduce origin server load and backbone congestion. In-memory caches and distributed caches command the deepest margin pools due to DRAM cost structures and cluster orchestration complexity. Cloud-based and hybrid deployments are expanding fastest as enterprises migrate from rigid on-premises appliances toward API-managed edge footprints.
FCC net neutrality provisions and EU GDPR data-localization requirements shape where cache nodes may legally reside and what traffic metadata operators may retain. ISO 27001 and IEC 62351-4 standards govern information security management and network protocol protections for cached content integrity. Stakeholders must weigh sovereign data rules against latency optimization when selecting multi-cloud cache topologies.

Market Dynamics
Telecommunications operators are deploying transparent cache nodes deeper into metro networks to absorb 4K and 8K video traffic surges without expanding backbone capacity. This structural shift toward edge-distributed storage is compressing procurement cycles and rewiring vendor selection criteria around latency service-level agreements rather than capital cost alone.
Growth Catalysts
- FCC Net Neutrality Framework:Open Internet rules in the United States prevent paid prioritization, compelling ISPs to deploy transparent caching as a traffic management tool that improves user experience without violating non-discrimination principles.
- Edge Computing Infrastructure Buildout:5G network densification requires sub-50 millisecond response guarantees that only distributed transparent cache architectures can deliver for video and IoT data streams.
- Germany Core Network Modernization:Deutsche Telekom and Vodafone are upgrading national backbones, creating concentrated demand for carrier-grade cache appliances integrated with existing routing infrastructure.
Market Restraints
- DRAM Cost Volatility:In-memory cache tiers depend on semiconductor memory pricing, which fluctuates with foundry capacity allocation and creates margin compression for appliance vendors.
- GDPR Data Localization Mandates:EU requirements restrict where traffic metadata may reside, forcing operators to fragment cache node placement and increasing operational complexity across member states.
- Cloud CDN Substitution:Hyperscale content delivery networks offer managed caching as-a-service, diverting enterprise budgets from dedicated transparent cache hardware procurement.
Strategic Opportunities
- India Broadband Expansion:TRAI-mandated fiber-to-the-home targets and the PLI scheme for telecom equipment create a greenfield market for cost-optimized cache deployments in tier-2 and tier-3 cities.
- Serverless Compute Co-location:Transparent cache nodes that integrate edge function execution attract cloud-native application developers seeking low-latency compute without origin round-trips.
- ISO 27001 Certification Differentiation:Information security management certification is becoming a procurement gate for financial services and healthcare network operators, favoring vendors with established compliance frameworks.
Industry Challenges
- Legacy Router Integration Complexity:Transparent cache deployment requires protocol-level coordination with existing carrier routing infrastructure, extending implementation timelines and demanding specialized network engineering expertise.
- IEC 62351-4 Compliance Burden:Power system communication protocol security standards impose cryptographic and authentication requirements that increase software development costs for utility-facing cache vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transparent Cache Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: In-Memory Caches, Distributed Caches, Web Caches, Object Caches Deployment: On-Premises, Cloud-Based, Hybrid, Multi-Cloud End User: IT Services, E-Commerce, Telecommunications, Financial Services Industry Vertical: Healthcare, Retail, Media, Government |
| Companies Covered | Cisco Systems, Akamai Technologies, Google, Nokia Corporation, Huawei Technologies, Ericsson, Cloudflare, Microsoft, Fortinet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transparent Cache Market Strategic Shifts
Programmable control planes and AI-driven cache prefetching are redefining how network operators balance storage efficiency against real-time latency guarantees. These developments are compressing the traditional boundary between hardware appliances and software-defined edge infrastructure.
Software-defined cache orchestration is converging with Kubernetes-native service meshes to enable policy-driven content placement across distributed node clusters. Tier-one mobile operators in South Korea and Japan are piloting these architectures for augmented reality streaming. This convergence is collapsing the distinction between cache management and containerized application deployment, forcing traditional appliance vendors to rearchitect around cloud-native control interfaces.
The EU AI Act's risk classification framework is imposing algorithmic transparency requirements on automated cache optimization systems that use machine learning for content prediction. Operators deploying predictive prefetching must now document training data provenance and decision logic for high-stakes use cases. Financial services networks in Frankfurt and Amsterdam are responding by segregating AI-driven cache tiers from standard rule-based systems to limit compliance scope.
Enterprise procurement teams are consolidating vendor relationships around integrated edge platforms that bundle transparent caching with security and observability functions. This pattern is displacing standalone cache appliance purchases in North American and European enterprise accounts. Manufacturing and logistics verticals with distributed facility networks are driving this consolidation, preferring single-source accountability for edge infrastructure performance.
Transparent Cache Market Segmentation

Transparent cache procurement decisions split sharply across memory architecture, infrastructure ownership, and compliance-sensitive verticals. Each segmentation axis carries distinct margin profiles and vendor qualification barriers that reshape competitive positioning.
Product Type:
Supply concentration tilts toward DRAM-dependent tiers where foundry allocation cycles dictate vendor margins and delivery timelines.
- In-Memory Caches:These systems store frequently accessed content in volatile DRAM arrays to guarantee sub-millisecond response times for latency-critical applications. Deutsche Telekom and Vodafone deployments in Germany favor this tier for core network modernization, though DRAM cost volatility compresses appliance vendor profitability.
- Distributed Caches:Clustered node architectures span multiple geographic locations with automated data replication and failure recovery. South Korean and Japanese mobile operators pilot these for augmented reality streaming, where Kubernetes-native orchestration collapses the boundary between cache management and containerized deployment.
- Web Caches:HTTP-specific interception systems optimize static content delivery for web applications without client reconfiguration.
- Object Caches:Key-value storage engines handle unstructured data blobs for cloud-native application backends.
Today's leader: In-Memory Caches. Tomorrow's challenger: Distributed Caches.
Deployment:
Cost tier stratification separates capital-intensive appliance ownership from operational expenditure models favored by cloud-native enterprises.
- Cloud-Based:Fully managed cache services eliminate hardware procurement and shift operational burden to hyperscale providers. GDPR data localization mandates fragment node placement across EU member states, forcing operators to architect multi-region compliance topologies that increase complexity.
- Hybrid:Split architectures retain sensitive data on premises while bursting peak loads to public cloud infrastructure. Financial services networks in Frankfurt and Amsterdam segregate AI-driven cache tiers from standard rule-based systems to limit EU AI Act compliance scope.
- On-Premises:Dedicated hardware appliances satisfy sovereign data requirements and deterministic performance guarantees.
- Multi-Cloud:Portability frameworks prevent vendor lock-in by abstracting cache operations across competing cloud platforms.
Cloud-Based deployments currently dominate new procurement. Hybrid architectures are climbing the fastest as regulated industries seek compliance flexibility.
End User:
Application intensity varies dramatically across sectors, with video traffic surges and real-time transaction volumes driving divergent technical specifications.
- Telecommunications:Carrier-grade deployments absorb 4K and 8K video traffic surges through metro-distributed nodes without backbone expansion. FCC net neutrality rules in the United States compel ISPs to adopt transparent caching as a non-discriminatory traffic management tool.
- Financial Services:ISO 27001 certification gates procurement for institutions handling payment card and securities transaction data. Frankfurt-based operators face EU AI Act algorithmic transparency requirements for machine-learning-driven prefetching systems.
- IT Services:Managed service providers bundle caching with broader infrastructure outsourcing contracts.
- E-Commerce:Peak-load handling for flash sales and seasonal demand spikes drives elastic capacity requirements.
Telecommunications commands the deepest deployment expertise. Financial Services represents the steepest expansion trajectory as compliance mandates proliferate.
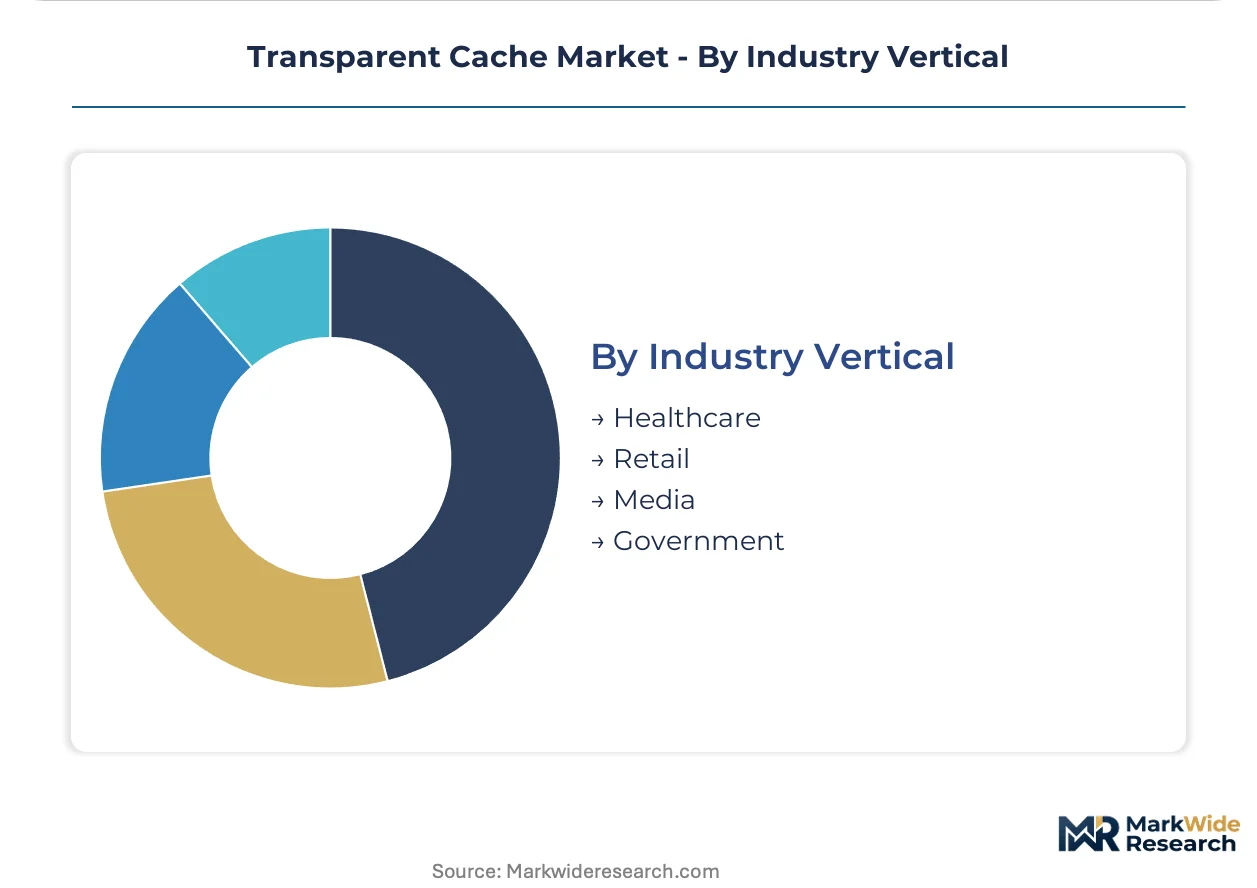
Industry Vertical:
Customer maturity separates early adopters with established edge infrastructure from laggards still migrating off legacy content delivery architectures.
- Media:Streaming platforms and broadcast networks demand the most aggressive latency guarantees for live event delivery. Manufacturing and logistics verticals with distributed facility networks are consolidating vendor relationships around integrated edge platforms that bundle caching with security functions.
- Government:Sovereign data requirements and classified network isolation create captive demand for on-premises appliances with IEC 62351-4 cryptographic compliance for utility-facing deployments.
- Healthcare:HIPAA and GDPR intersection imposes strict audit trails on cached patient data access patterns.
- Retail:Omnichannel inventory synchronization and personalized recommendation engines drive real-time data requirements.
Media verticals currently absorb the highest cache node density per revenue dollar. Government procurement is gaining share fastest as national security frameworks mandate domestic data residency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Network engineering talent pools in Germany, the United States, Japan, India, and South Korea anchor transparent cache deployment expertise across carrier and enterprise verticals.
United States
Telecommunications operators deploy metro-distributed cache nodes to absorb 4K and 8K video traffic without backbone expansion. FCC net neutrality rules prevent paid prioritization, compelling ISPs to adopt transparent caching as a non-discriminatory traffic management tool. Dallas-Fort Worth and Atlanta host concentrated carrier infrastructure engineering clusters where Verizon and AT&T operate network operations centers.
Germany
Deutsche Telekom and Vodafone drive core network modernization with carrier-grade cache appliances integrated into existing routing infrastructure. GDPR data localization mandates restrict where traffic metadata may reside, fragmenting cache node placement across EU member states. Frankfurt anchors financial services network engineering expertise where operators segregate AI-driven cache tiers to limit EU AI Act compliance scope.
Japan
Mobile operators pilot Kubernetes-native cache orchestration for augmented reality streaming applications requiring sub-50 millisecond response guarantees. METI industrial policy supports 5G network densification investments that depend on distributed transparent cache architectures. Tokyo and Osaka metropolitan areas concentrate vendor engineering resources for edge infrastructure deployment.
India
TRAI-mandated fiber-to-the-home targets and the PLI scheme for telecom equipment create greenfield demand for cost-optimized cache deployments in tier-2 and tier-3 cities. BIS certification requirements govern equipment interoperability for domestic network infrastructure. Bangalore and Hyderabad anchor systems integration expertise for carrier network modernization programs.
South Korea
KT Corporation and SK Telecom deploy edge-distributed storage to support 5G network densification and real-time video services. National broadband policy emphasizes ultra-low latency infrastructure for cloud gaming and industrial IoT applications. Seoul Capital Area concentrates semiconductor memory engineering talent critical for in-memory cache tier development.
Transparent Cache Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the transparent cache market, with semiconductor memory foundry investments separating DRAM-dependent appliance vendors from software-defined orchestration specialists. The vendor base stratifies between integrated networking conglomerates and pure-play edge infrastructure developers. Three archetypes dominate: carrier-router-integrated suppliers, distributed edge fabric operators, and cloud-native platform developers. Competitive moves center on strategic partnerships with telecommunications operators and portfolio diversification into serverless compute co-location.
Within the carrier-router-integrated tier, Cisco Systems and Nokia Corporation exemplify established networking infrastructure suppliers. Among cloud-native platform developers, Cloudflare occupies a position representing the convergence of transparent caching with edge function execution. These anchors illustrate how vendor selection criteria increasingly prioritize latency service-level agreements over capital cost alone, with ISO 27001 certification becoming a procurement gate for regulated industries.
| Leading Market Players |
|---|
| Cisco Systems |
| Akamai Technologies |
| Nokia Corporation |
| Huawei Technologies |
| Ericsson |
| Cloudflare |
| Microsoft |
| Fortinet |
| Others |
Value Chain & Pricing Dynamics
The performance gap between carrier-grade in-memory cache appliances and commodity edge caching nodes manifests in divergent pricing architectures and sourcing strategies. Premium tiers command three-to-five-fold unit economics over standard web cache appliances, reflecting DRAM cost structures and ISO 27001 certification overhead that reshape supplier qualification criteria across procurement teams.
Pricing Analysis
Bundled managed cache services separate from unbundled hardware-only procurement across enterprise accounts. Three-tier pricing structure across premium, standard, and economy levels stratifies by latency guarantee tiers and security certification bundles. Cost compression in commodity edge tiers intensifies because hyperscale CDN providers absorb price-sensitive volume. Telecommunications operators show least price sensitivity due to backbone cost avoidance calculus, while mid-market IT services buyers migrate fastest to SaaS-tiered consumption models.
Supply Chain Analysis
Dual-sourcing requirements from Deutsche Telekom and Vodafone mandate multi-supplier qualification for DRAM modules and cryptographic accelerators. Foundry capacity in South Korea, Taiwan, and the United States anchors semiconductor memory supply. Cache appliance assembly draws from China, Mexico, and Germany for chassis fabrication and power supply integration. Single-source vulnerability concentrates in advanced DRAM packaging nodes. Distribution runs through carrier-direct procurement channels and systems integrator partnerships for enterprise verticals.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where procurement teams prioritize latency service-level agreements over capital cost minimization. The shift toward sub-50 millisecond response guarantees for 5G video and augmented reality workloads elevates premium-tier vendor selection criteria.
For Market Incumbents: To counter hyperscale CDN substitution, anchor carrier-router integration capabilities through Nokia Corporation and Ericsson partnership ecosystems. Deepen backward integration into DRAM supply chains through foundry allocation agreements with Samsung and SK Hynix. ISO 27001 certification maintenance serves as the priority procurement gate for financial services verticals.
For New Entrants and Emerging Players: Kubernetes-native cache orchestration offers the most penetrable wedge against legacy appliance incumbents. Target India's tier-2 and tier-3 city broadband expansion under TRAI fiber-to-the-home mandates. Serverless compute co-location with cache nodes provides the decisive go-to-market angle for cloud-native developer adoption.
For Investors and Strategic Acquirers: Consolidation pressure builds where GDPR data localization mandates fragment operational scale across EU member states. Five-to-ten year viability favors vendors with established compliance frameworks and carrier-grade routing integration. Acquisition target archetypes include pure-play edge orchestration specialists with Kubernetes-native control planes. The signal to watch is carrier capex disclosure shifts toward metro-distributed infrastructure versus backbone expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Serverless Compute Co-location | Edge function execution attracts cloud-native developers seeking origin bypass architectures. |
| ISO 27001 Certification Investment | Information security management gates procurement for Frankfurt financial services networks. |
| Carrier Router Integration Partnership | Protocol-level coordination with Cisco Systems and Nokia anchors tier-one network deployments. |
| India Market Entry | PLI scheme incentives and TRAI fiber targets create greenfield demand in tier-2 cities. |
| AI-Driven Prefetching Development | EU AI Act compliance documentation separates rule-based from machine-learning cache tiers. |
Study Parameters
Bottom-up telecommunications operator deployment modeling reconciled against top-down semiconductor foundry capacity tracking forms the analytical core. Primary interviews with network engineering directors, carrier procurement officers, edge infrastructure architects, and compliance officers at Deutsche Telekom, Vodafone, Verizon, and KT Corporation cross-validated against secondary sources including FCC net neutrality filings, ETSI standardization documents, SEC 10-K infrastructure capex disclosures, and TRAI regulatory circulars.
Historical trendline analysis of carrier cache node shipments and DRAM content per appliance informed projection frameworks across the analysis window. Segmentation dimensions modeled include memory architecture tier, deployment model, end-user vertical, and regional regulatory cluster. CAGRs derived from slope analysis of infrastructure investment cycles and video traffic growth elasticities. Forecast inputs incorporated 5G network densification timelines and EU AI Act implementation schedules.
The model holds under stable FCC net neutrality enforcement and continued DRAM foundry capacity expansion; deviation in semiconductor trade policy or sovereign data rule fragmentation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
SSD Controller Market
Data Storage
Enterprise Storage System Market
Data Storage
APAC Next Generation Storage Market
Data Storage
Multiprotocol Storage Market
Data Storage
North America SSD Caching Market
Data Storage
Solid State Drive (SSD) Market
Data Storage
Portable Storage Device Control Software Market
Data Storage
Non-Volatile Memory Express (Nvme) Market
Data Storage
Hybrid Flash Storage Market
Data Storage
Enterprise Flash Storage Market
Data Storage
Global Personal and Entry Level Storage (PELS) Market
Data Storage
Asia Pacific Transparent Caching Market
Data Storage
Storage Class Memory Market
Data Storage
Archival Grade Blu-Ray Discs Market
Data Storage
APAC SSD Caching Market
Data Storage
Tape Storage Market