
 Germanium Semiconductor Market | 2026-2036
Germanium Semiconductor Market Size, Share, and Industry Trends Forecast 2026-2036
Germanium Semiconductor Market Analytics
Silicon carbide is realigning power electronics economics, yet germanium retains irreplaceable advantages in infrared optoelectronics and high-frequency analog devices. Umicore N.V. leverages integrated refining capabilities from zinc smelting byproduct recovery to secure feedstock independence. Yunnan Chihong Zinc & Germanium Co., Ltd. anchors Chinese domestic supply through captive zinc-germanium ore processing. Teck Resources Limited competes via polymetallic mine output in British Columbia that yields germanium concentrate as a co-product.
Germanium semiconductors comprise single-crystal substrates or epitaxial layers with a bandgap of approximately 0.67 eV, enabling efficient photodetection in the near-infrared spectrum from 800 to 1800 nanometers; foundries deploy these properties in fiber-optic receivers and thermal imaging sensors. Photodetectors dominate current revenue as datacenter interconnects and LiDAR modules multiply die requirements. Optoelectronics technology leads growth velocity because silicon-germanium heterostructures enable faster transceivers than pure silicon alternatives. Power electronics applications in automotive traction inverters remain nascent due to cost barriers but attract developmental investment.
China's Ministry of Commerce export licensing for germanium metal shapes international procurement patterns, while REACH registration requirements in Europe constrain chemical processing pathways for refined material. The U.S. Defense Logistics Agency maintains strategic stockpile protocols that buffer military supply chains against geopolitical disruption. Stakeholders must monitor export permit backlogs and alternative refining investments in Canada and Belgium to assess supply security through the forecast horizon.
Market Dynamics
China's export licensing regime for germanium metal is concentrating supply control in state-affiliated refiners while forcing non-domestic wafer fabricators to secure alternative feedstock pathways through Canadian and Belgian polymetallic operations.
Growth Catalysts
- Datacenter interconnect buildouts:Cloud infrastructure operators are expanding fiber-optic receiver deployments that rely on germanium photodetectors for near-infrared signal conversion at 800-1800 nanometer wavelengths.
- REACH registration pathways:European chemical processing frameworks are streamlining refined material certification for compound semiconductor foundries operating under ECHA compliance protocols.
- Automotive LiDAR module proliferation:Tier-1 suppliers are scaling thermal imaging sensor die orders to meet OEM requirements for advanced driver-assistance systems in premium vehicle segments.
Market Restraints
- Feedstock concentration in zinc smelting byproduct recovery:Primary germanium extraction remains tethered to polymetallic mine economics, creating supply inelasticity when zinc prices compress.
- Technical substitution in power electronics:Silicon carbide traction inverters are capturing automotive electrification investment despite germanium's theoretical efficiency advantages at lower bandgaps.
- Export permit backlog friction:China's Ministry of Commerce licensing delays are extending procurement lead times for Taiwanese and South Korean foundry clusters dependent on metal shapes.
Strategic Opportunities
- Defense stockpile protocols:The U.S. Defense Logistics Agency maintains strategic buffer mechanisms that create preferential offtake channels for military-grade substrate specifications.
- Silicon-germanium heterostructure convergence:Foundry integration of SiGe epitaxy with CMOS lines is enabling faster transceiver architectures than pure silicon alternatives in telecom infrastructure.
- Belgian refining capacity expansion:Umicore's integrated zinc-germanium recovery operations offer non-Chinese feedstock security for European optoelectronics manufacturers.
Industry Challenges
- Crystal growth technician scarcity:Czochralski puller operation and dislocation-free boule production require specialized expertise concentrated in legacy semiconductor manufacturing regions.
- Epitaxial reactor capex intensity:MOCVD and MBE tool installation for germanium-on-silicon layer deposition demands significant capital commitment from mid-scale foundry operators.
- Dual-use export classification complexity:Infrared optical systems fall under multilateral regime controls, extending compliance timelines for satellite communications substrate shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germanium Semiconductor Market |
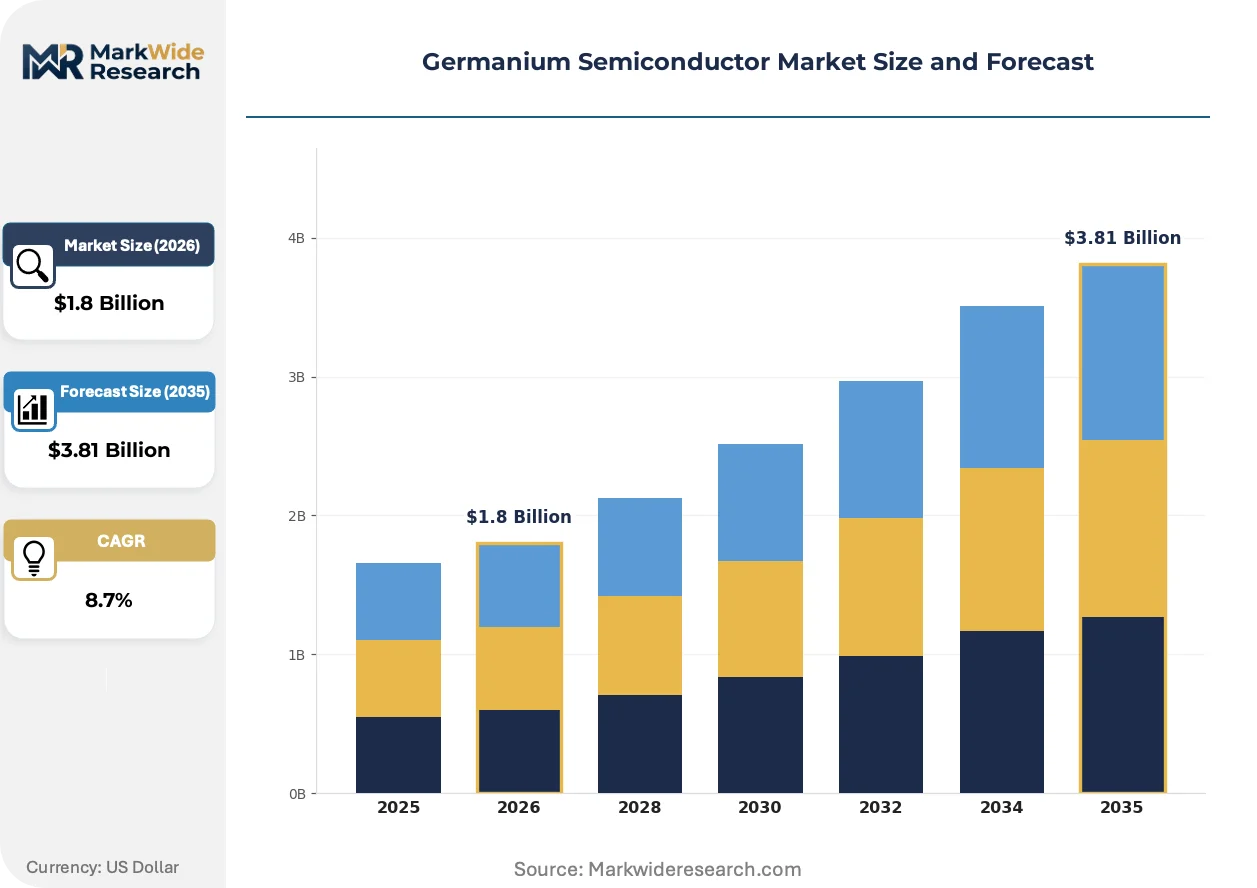
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transistors, Diodes, Photodetectors, Integrated Circuits Application: Telecommunications, Consumer Electronics, Automotive, Aerospace End User: OEMs, Research Institutions, Government Agencies, Utility Companies Technology: MEMS, Power Electronics, Optoelectronics, Quantum Dots |
| Companies Covered | Teck Resources Limited, 5N Plus Inc., Umicore N.V., AXT, Inc., PPM Pure Metals GmbH, Yunnan Chihong Zinc & Germanium Co., Ltd., Indium Corporation, American Elements, China Germanium Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germanium Semiconductor Market Evolving Landscape
Process integration and supply security imperatives are reshaping how germanium semiconductors move from refined metal to packaged die, with heterostructure engineering and regulatory adaptation driving competitive differentiation.
Silicon-germanium heterostructure technology is integrating germanium channels into CMOS-compatible process flows to achieve hole mobility advantages over pure silicon. Datacenter transceiver manufacturers are adopting these architectures for 400G and 800G optical interconnects. The technology is integrating photodetection and electronic signal processing functions onto unified substrates, compressing module footprint and assembly cost structures.
REACH chemical registration requirements in Europe are constraining refined material processing pathways for non-EU feedstock sources. ECHA compliance documentation now mandates full supply chain substance disclosure for germanium compounds used in semiconductor fabrication. German substrate refiners and Belgian chemical processors are investing in registration dossier completion to maintain market access for infrared optical grade material.
Buyer concentration in East Asian foundry clusters is compressing procurement negotiation cycles and favoring long-term offtake agreements over spot market transactions. Taiwanese and South Korean compound semiconductor facilities are consolidating supplier qualification lists to dual-source from Chinese licensed exporters and Canadian polymetallic concentrate producers. This pattern is most visible in photodetector die supply chains serving datacenter and automotive LiDAR end-uses.
Germanium Semiconductor Market Segmentation
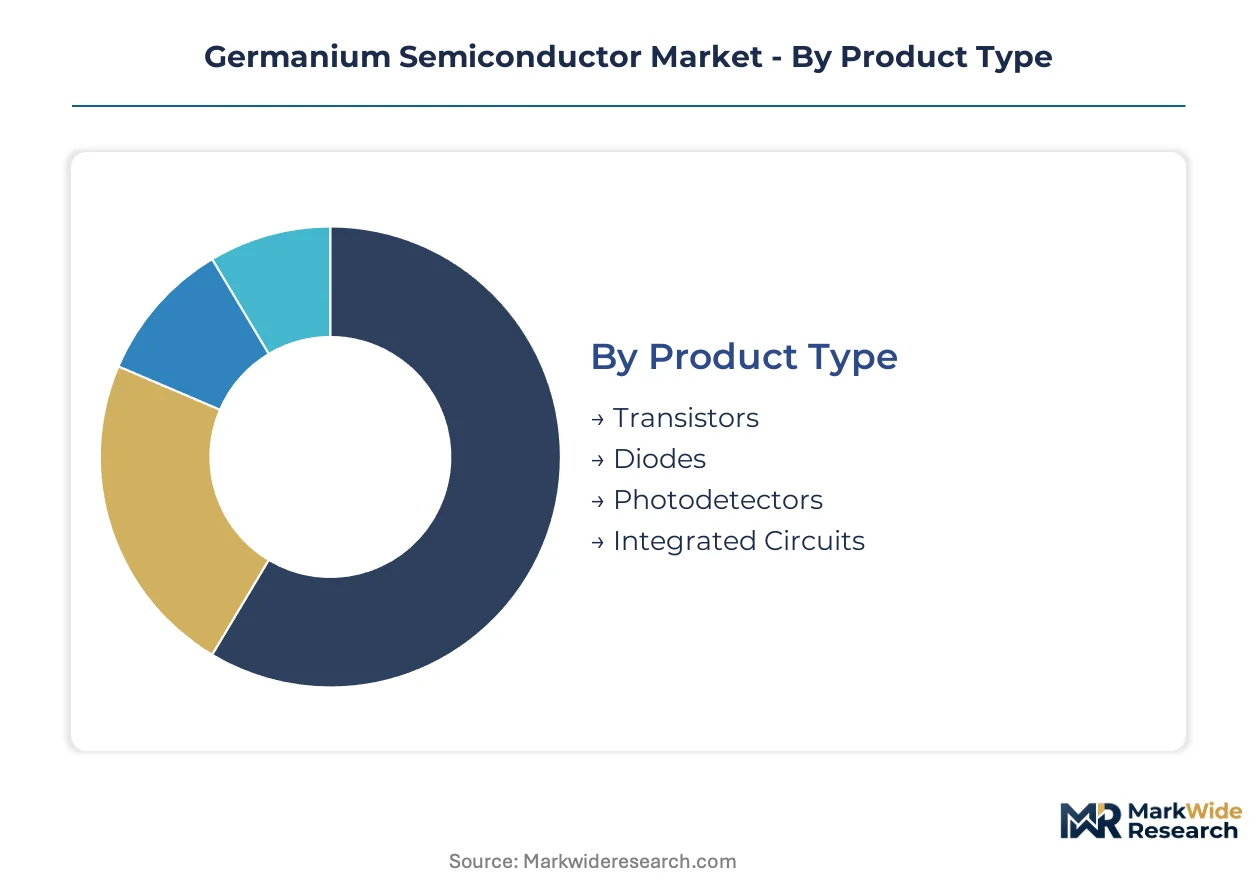
Germanium semiconductor applications span discrete devices through complex heterostructures, with each product category commanding distinct manufacturing protocols and end-use specifications. Understanding these segment boundaries clarifies where foundry investments concentrate versus where system-level integration dominates procurement decisions.
Product Type:
Discrete components serve standalone optical and analog functions, while integrated formats embed germanium functionality within broader silicon process flows.
- Photodetectors:These devices exploit germanium's 0.67 eV bandgap for efficient near-infrared conversion across 800-1800 nanometer wavelengths. Datacenter interconnect buildouts in Taiwan and South Korea are multiplying die orders for fiber-optic receiver modules.
- Integrated Circuits:Silicon-germanium heterostructures merge germanium channels with CMOS-compatible fabrication, enabling hole mobility advantages in 400G and 800G telecom transceivers. Foundry integration of SiGe epitaxy compresses module footprint while unifying photodetection with signal processing.
- Transistors:High-frequency analog devices leverage germanium's electron mobility for RF amplification in satellite communications ground stations.
- Diodes:Power rectification components target specialized aerospace applications where temperature stability exceeds silicon limits.
Photodetectors lead volumes today; integrated circuits are gaining share fastest.
Application:
End-use concentration varies sharply by deployment maturity, with infrastructure-scale applications commanding longer qualification cycles than consumer-facing formats.
- Telecommunications:Fiber-optic backbone expansion and 5G fronthaul architectures drive substrate demand for high-speed optical interconnects. Taiwanese compound semiconductor foundries are scaling epitaxial reactor capacity to meet transceiver module requirements.
- Automotive:LiDAR thermal imaging sensors for advanced driver-assistance systems are multiplying die orders from tier-1 suppliers serving premium vehicle OEMs.
- Aerospace:Satellite communications manufacturers are expanding germanium substrate procurement for infrared optical systems under multilateral export control protocols.
- Consumer Electronics:Niche applications in spectroscopic sensing and specialized imaging remain volume-constrained by cost structures.
Telecommunications commands the largest revenue base; automotive applications are expanding most quickly.
End User:
Procurement authority concentrates in entities with captive system integration capabilities or direct access to defense funding streams.
- OEMs:Tier-1 automotive suppliers and telecommunications equipment manufacturers dominate commercial offtake through long-term supply agreements with foundry clusters.
- Government Agencies:The U.S. Defense Logistics Agency maintains strategic stockpile protocols that buffer military supply chains against geopolitical disruption in refined metal access.
- Research Institutions:University and national laboratory demand centers on experimental quantum dot and heterostructure development.
- Utility Companies:Fiber-optic grid monitoring systems represent an emerging procurement channel for photodetector modules.
OEMs anchor current demand; government agencies provide the most stable procurement commitments.
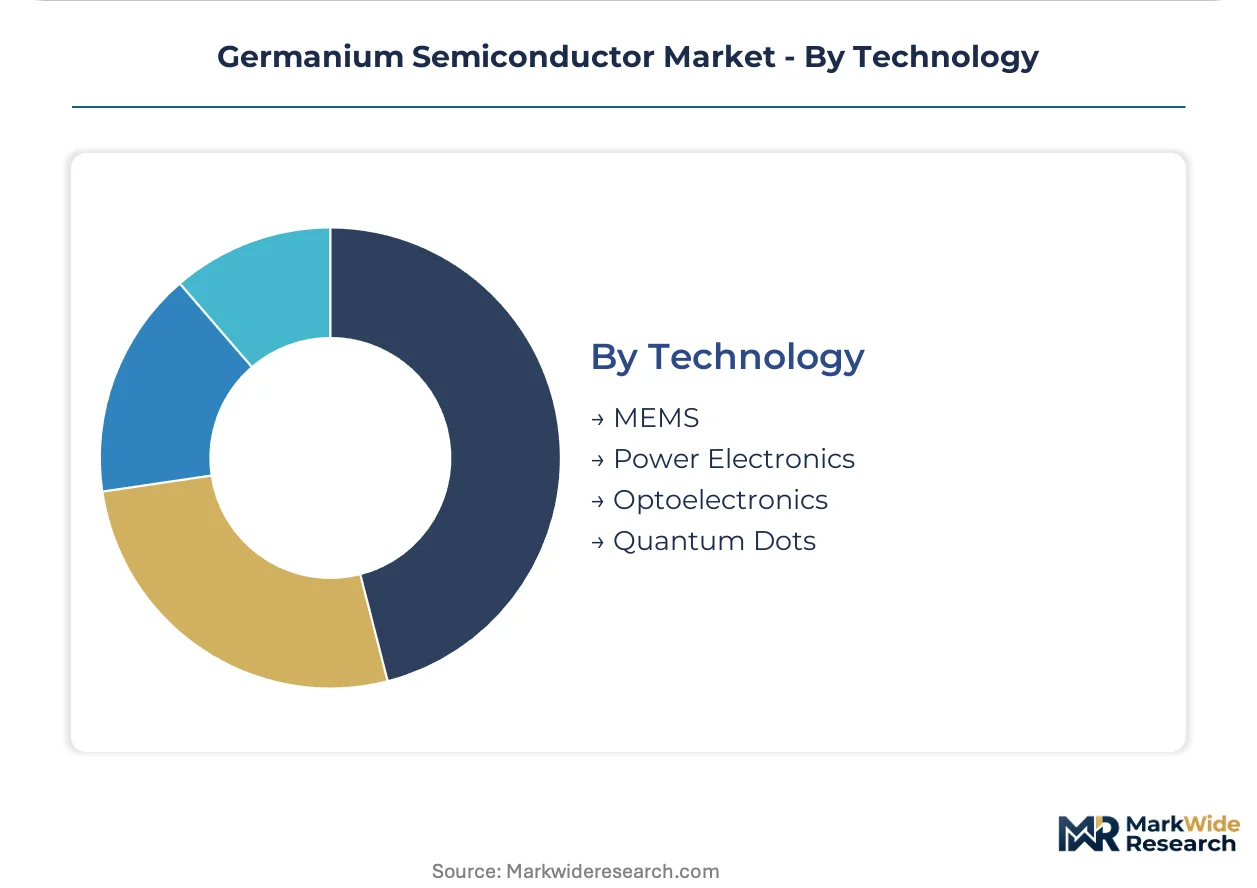
Technology:
Process maturity diverges sharply between established optical formats and developmental quantum architectures.
- Optoelectronics:Near-infrared photodetection and silicon-germanium heterostructure transceivers represent the commercial core, with ECHA REACH registration requirements now constraining European refined material processing pathways.
- Power Electronics:Automotive traction inverter applications remain nascent due to silicon carbide competition, though developmental investment continues for specialized thermal management scenarios.
- MEMS:Micro-electromechanical systems incorporating germanium layers target specialized pressure and thermal sensors for aerospace environments.
- Quantum Dots:Experimental quantum confinement structures for next-generation photonic computing remain confined to research institution procurement.
Optoelectronics generates the dominant revenue stream; quantum dots are climbing the fastest on a percentage basis from minimal base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian foundry clusters in Taiwan and South Korea concentrate germanium substrate demand for photodetector and silicon-germanium heterostructure production. China's export licensing regime is redirecting procurement flows toward Canadian and Belgian polymetallic concentrate sources. Regulatory adaptation across multiple jurisdictions is reshaping refined material access for compound semiconductor fabricators.
China
Domestic wafer fabricators secure preferential access to state-licensed refined metal from Yunnan Chihong Zinc & Germanium's captive ore processing operations. The Ministry of Commerce export licensing requirements for germanium metal shapes constrain international availability and extend procurement lead times for non-domestic buyers. Yangtze River Delta foundry clusters are scaling compound semiconductor capacity fastest, absorbing captive domestic supply for infrared optical systems.
Taiwan
Compound semiconductor foundries are multiplying photodetector die orders to serve datacenter interconnect and telecom transceiver module demand. The island's trade regulator monitors export permit backlogs from mainland China that threaten feedstock security for wafer fabrication. Hsinchu Science Park facilities are consolidating supplier qualification lists to dual-source from Chinese licensed exporters and Canadian polymetallic concentrate producers.
South Korea
Memory and logic chip conglomerates are expanding silicon-germanium epitaxial reactor capacity for 400G and 800G optical interconnect applications. The Korea Trade-Investment Promotion Agency facilitates alternative feedstock pathway development with Canadian mining operations to bypass Chinese supply concentration. Seoul-Pangyo corridor fabs are negotiating long-term offtake agreements rather than spot market transactions to secure substrate supply.
United States
The Defense Logistics Agency maintains strategic stockpile protocols that buffer military supply chains against geopolitical disruption in refined metal access. FDA and FCC regulatory frameworks govern infrared optical system deployment in medical imaging and telecommunications infrastructure respectively. Arizona and Texas semiconductor manufacturing corridors attract developmental investment for silicon-germanium heterostructure integration with CMOS process flows.
Belgium
Umicore N.V.'s integrated zinc-germanium recovery operations offer non-Chinese feedstock security for European optoelectronics manufacturers. ECHA REACH registration requirements constrain refined material processing pathways and mandate full supply chain substance disclosure for germanium compounds. Antwerp refining facilities are investing in registration dossier completion to maintain market access for infrared optical grade material serving telecom and aerospace end-uses.
Germanium Semiconductor Market Competitive Landscape
Global majors compete with regional champions across feedstock security and refining integration dimensions. The vendor base organizes around three tiers: polymetallic mining conglomerates with co-product recovery capabilities, integrated zinc smelters leveraging byproduct extraction, and specialized semiconductor material refiners. Strategic archetypes include upstream-integrated miners, midstream chemical processors, and downstream substrate fabricators. Dominant competitive moves encompass backward integration into captive ore supply and capacity expansion in non-Chinese refining jurisdictions.
Among polymetallic mining specialists, Teck Resources Limited and 5N Plus Inc. exemplify the upstream-integrated archetype with co-product germanium concentrate output from base metal operations. Umicore N.V. occupies a distinctive position as a European-integrated zinc-germanium recovery operator with REACH-compliant refining pathways. These three entities represent alternative feedstock security options for East Asian foundry clusters seeking to diversify beyond Chinese state-licensed supply channels.
| Leading Market Players |
|---|
| Teck Resources Limited |
| 5N Plus Inc. |
| Umicore N.V. |
| AXT, Inc. |
| PPM Pure Metals GmbH |
| Yunnan Chihong Zinc & Germanium Co., Ltd. |
| Indium Corporation |
| American Elements |
| China Germanium Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Silicon-germanium heterostructure integration into CMOS process flows is compressing module footprints while simultaneously concentrating cost economics in East Asian foundry clusters with captive epitaxial reactor capacity. This technology transition rewards scale operators with pricing power over mid-scale competitors lacking unified photodetection-signal processing capabilities.
Pricing Analysis
Input-cost pass-through from zinc smelting byproduct recovery dominates pricing dynamics, with polymetallic mine economics tethering germanium concentrate costs to base metal price cycles. Three-tier pricing structure across infrared optical grade, semiconductor substrate grade, and industrial feedstock grade separates defense-qualified specifications from commercial photodetector die. Cost compression in standard-grade material is intensifying because Chinese export licensing delays are forcing Taiwanese and South Korean foundries to absorb premium sourcing from Canadian polymetallic operations. OEMs in automotive LiDAR applications exhibit highest price sensitivity due to silicon carbide substitution threats, while defense agencies maintain lowest sensitivity through strategic stockpile buffers.
Supply Chain Analysis
China's Ministry of Commerce export licensing requirements are reshaping sourcing patterns by mandating domestic-content verification for state-affiliated refiners while restricting metal shape availability to licensed exporters. Geographic supply concentration centers on China, Canada, and Belgium as primary refined metal sources, with feedstock drawing from zinc-germanium ore processing in Yunnan province and polymetallic concentrate from British Columbia. Raw material dependencies rest on zinc smelting byproduct recovery, sulfuric acid leaching capacity, and Czochralski crystal growth equipment. Single-source vulnerability from Chinese state-controlled supply creates structural risk for non-domestic wafer fabricators. Distribution runs through long-term offtake agreements rather than spot markets, with East Asian foundry clusters consolidating dual-source qualification lists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where ECHA REACH registration milestones and Chinese export licensing protocols are accelerating procurement consolidation among qualified suppliers with compliant refining pathways.
For Market Incumbents: Deepen backward integration into captive zinc-germanium ore supply through polymetallic mining partnerships in Canada and Belgium to offset Chinese export permit backlog friction. Expand epitaxial reactor capacity in Taiwan and South Korea to capture silicon-germanium heterostructure demand from 400G and 800G transceiver manufacturers. Threat from silicon carbide traction inverters demands defensive certification investment in infrared optical grade specifications for defense stockpile protocols. For New Entrants and Emerging Players: Enter via automotive LiDAR module supply chains where tier-1 suppliers are multiplying thermal imaging sensor die orders with less entrenched incumbent relationships. Target Belgian refining jurisdiction for REACH-compliant material processing serving European optoelectronics manufacturers. Go-to-market angle should emphasize dual-source qualification status for Taiwanese foundry clusters seeking non-Chinese feedstock security. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale substrate fabricators lacking integrated refining capabilities but possessing qualified foundry relationships with East Asian compound semiconductor clusters. Long-term viability hinges on securing alternative feedstock pathways before Chinese licensing restrictions tighten further. Acquisition target archetype: European or North American refiners with zinc-germanium recovery operations and pending ECHA registration dossier completion. Signal to watch is backlog duration in Chinese Ministry of Commerce export permit queues as inflection indicator for supply security premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymetallic Mining | Teck Resources and Umicore operations in Canada and Belgium secure non-Chinese concentrate supply for wafer fabricators. |
| Epitaxial Reactor Capacity Expansion | Hsinchu Science Park and Seoul-Pangyo corridor fabs capture silicon-germanium heterostructure demand from telecom infrastructure. |
| REACH Registration Dossier Completion | Antwerp refining facilities maintain European market access for infrared optical grade germanium compounds under ECHA protocols. |
| Dual-Source Supplier Qualification | Taiwanese foundries consolidate procurement lists to blend Chinese licensed exports with Canadian polymetallic concentrate. |
| Defense Stockpile Protocol Alignment | U.S. Defense Logistics Agency preferential offtake channels buffer military substrate supply against geopolitical disruption. |
Research Methodology
Multiple input streams — primary interviews with compound semiconductor foundry procurement managers, epitaxial reactor equipment specialists, and zinc smelter operations directors; secondary validation through SEC 10-K filings, customs trade databases, and ECHA registration dossiers; plus defense stockpile disclosure documents — were reconciled through bottom-up and top-down triangulation. Supply chain mapping incorporated conversations with crystal growth technicians and infrared optical system manufacturers.
Data-stream reconciliation across product type segmentation, application end-uses, technology maturity tiers, and regional regulatory clusters shaped the analytical framework over the projection horizon. Modeled dimensions spanned photodetector versus integrated circuit formats, telecommunications versus automotive applications, and optoelectronics versus power electronics technology pathways. CAGRs were derived from elasticity modeling of datacenter interconnect buildouts and LiDAR module proliferation against feedstock supply constraints.
Inputs from Chinese Ministry of Commerce licensing disclosures and ECHA substance registration databases were available through the study window; gaps in real-time export permit queue data introduce uncertainty bands around procurement lead time assumptions. Forecasts reflect documented assumptions regarding silicon-germanium heterostructure adoption curves and zinc price correlation effects. Epitaxial reactor capex cycles and crystal growth technician scarcity present revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductors
Smartphone Battery Market
Semiconductors
Indium Phosphide Compound Semiconductor Market
Semiconductors
North America Semiconductor Market
Semiconductors
Europe Semiconductor Diode Market
Semiconductors
East Asia Automotive Semiconductors Market
Semiconductors
Europe Semiconductor Market
Semiconductors
Semiconductor Target Market
Semiconductors
ASEAN Semiconductor Market
Semiconductors
Wide Bandgap Semiconductors Market
Semiconductors
India Semiconductor Market
Semiconductors
United States Discrete Semiconductors Market
Semiconductors
Global Semiconductor Silicon Intellectual Property Market
Semiconductors
China Semiconductor Market
Semiconductors
Digital Semiconductors Market
Semiconductors
Europe Discrete Semiconductor Market
Semiconductors
IV-IV Compound Semiconductor Market