
 Global Copper Indium Gallium Selenide (CIGS) Solar Cells Market | 2026-2036
Global Copper Indium Gallium Selenide (CIGS) Solar Cells Market Size, Share, and Industry Trends Forecast 2026-2036
Global Copper Indium Gallium Selenide (CIGS) Solar Cells Market Intelligence
The module supply chain is fragmenting as regional distributors lose exclusivity to direct OEM relationships and specialized engineering-procurement-construction consortia. Solar Frontier leverages its integrated sputtering and selenization lines in Japan to sustain captive output for domestic utility-scale tenders. Avancis competes through co-evaporation expertise on rigid glass substrates for commercial rooftop segments across European markets.
Copper Indium Gallium Selenide solar cells are thin-film photovoltaic devices fabricated by depositing a p-type CIGS absorber layer, typically one to two micrometers thick, onto molybdenum-coated substrates via co-evaporation or sputtering followed by selenization; their primary purpose is converting sunlight to electricity at higher theoretical efficiencies than conventional cadmium telluride thin-film alternatives while tolerating partial shading and high-temperature operation. Flexible product types are gaining share in building-integrated applications where weight constraints and curvature compatibility override the cost premiums of rigid glass-glass architectures. Vacuum deposition technology dominates current manufacturing scale, though electroplating approaches are attracting R&D investment for indium reduction and process energy savings.
The EU Green Deal and F-Gas Regulation are reshaping manufacturing location decisions by restricting fluorinated greenhouse gases used in CIGS module encapsulation, while India's BIS certification mandates and PLI scheme for solar manufacturing are conditioning market access for imported thin-film equipment. Japan's METI feed-in tariff revisions and FIT-to-FIP transition are compressing project returns and forcing technology suppliers to demonstrate bankability under merchant price exposure. Stakeholders must monitor how national content requirements and carbon border adjustments redistribute competitive advantage across CIGS supply chain nodes before committing to capacity expansion.
Market Dynamics
The CIGS solar cell market is being restructured by the collision between rigid glass-glass cost structures and flexible polymer substrate demand from building-integrated photovoltaic architects who prioritize curvature tolerance over module efficiency.
Growth Catalysts
- EU Green Deal efficiency mandates:The framework's tightening carbon budgets for building stock renovation are accelerating specification of lightweight CIGS laminates for facade retrofits where structural load limits exclude crystalline silicon.
- Japan's FIT-to-FIP transition:Merchant electricity price exposure is forcing project developers to favor high-temperature coefficient performance, a technical strength of sputtered CIGS absorbers in rooftop installations.
- Electroplating R&D clusters:Process energy reductions and indium consumption cuts from aqueous deposition routes are attracting equipment investment at national renewable energy laboratories.
Market Restraints
- Indium supply concentration:Primary extraction from zinc mining concentrates in Chinese smelting complexes creates price volatility exposure for sputtering target manufacturers.
- F-Gas Regulation encapsulation restrictions:The EU's phasedown of fluorinated greenhouse gases used in barrier film lamination is forcing reformulation of flexible module edge seals.
- Cadmium telluride efficiency competition:First Solar's manufacturing scale and bankability track record constrain CIGS penetration in utility-scale procurement auctions.
Strategic Opportunities
- India BIS certification pathway:Domestic manufacturing incentives under the PLI scheme create localization opportunities for foreign thin-film equipment suppliers meeting the Bureau of Indian Standards module testing protocols.
- Automotive integrated photovoltaics:Curved glass compatibility and partial shading tolerance position CIGS for roof and glazing integration in electric vehicle programs.
- Sputtering-selenization convergence:Hybrid process flows combining vacuum deposition precision with rapid thermal processing throughput are emerging at pilot lines in Germany and Japan.
Industry Challenges
- Selenization reactor engineering talent:The specialized knowledge base for sulfur incorporation and grain boundary passivation is concentrated among retired researchers from national laboratory programs.
- Module bankability certification timelines:IEC 61215 and IEC 61646 testing sequences for flexible substrates require 12-18 month validation cycles that delay project financing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Copper Indium Gallium Selenide (CIGS) Solar Cells Market |
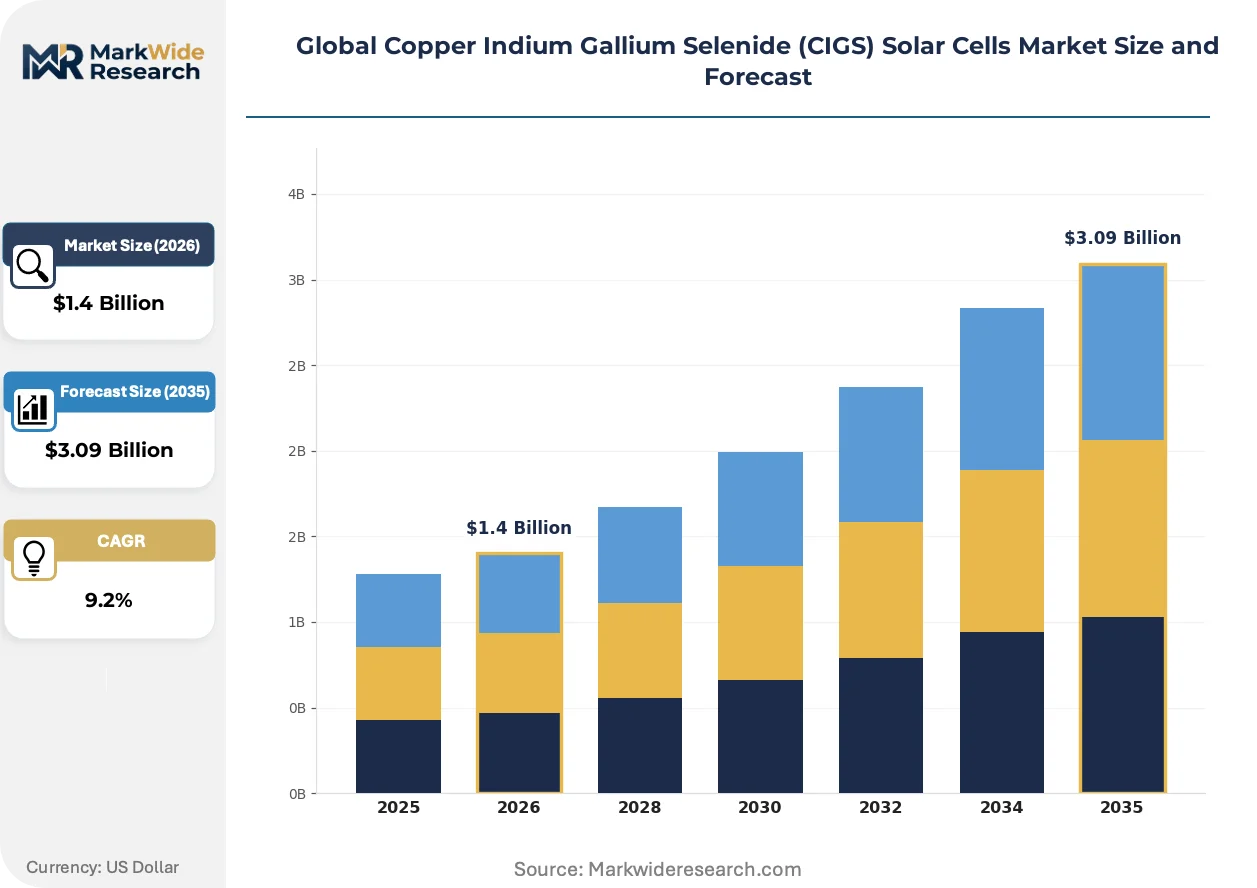
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $3.09 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monolithic, Flexible, Rigid, Tandem Technology: Thin-Film, Vacuum Deposition, Electroplating, Sputtering Application: Residential Installations, Commercial Operations, Military Systems, Remote Power Solutions End User: Utility-Scale Plants, Telecom Providers, Off-Grid Users, Research Institutions |
| Companies Covered | Oxford PV, Avancis, Solar Frontier, Jinko Solar, Manz AG, Ascent Solar Technologies, SoloPower Systems, Midsummer, Hanergy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Copper Indium Gallium Selenide (CIGS) Solar Cells Market Strategic Shifts & Innovations
Process instrumentation and substrate handling systems are being reengineered around continuous roll-to-roll deposition architectures that challenge batch vacuum chamber dominance.
Advanced process control software is digitizing selenization temperature profiling and sulfur gradient management across meter-width substrates. Equipment suppliers in Germany are retrofitting legacy batch lines with real-time spectral reflectance monitoring. This capability is compressing yield variation and enabling predictive maintenance contracts that displace fixed-price service agreements.
The EU F-Gas Regulation is prohibiting hydrofluorocarbon blowing agents in encapsulant foams and barrier film adhesives used in flexible CIGS modules. Manufacturers are qualifying silicone-based alternatives that sacrifice some moisture ingress resistance. European building-integrated photovoltaic distributors are stockpiling grandfathered inventory while awaiting re-certification of reformulated laminates.
Architects and facade engineers are unbundling module supply from engineering-procurement-construction contracts to direct OEM relationships. Specialized consortiums are displacing regional distributors who previously held exclusive territory agreements. Germany's utility-scale tendering authorities are witnessing this channel compression most acutely in commercial rooftop segments above 750 kilowatts.
Global Copper Indium Gallium Selenide (CIGS) Solar Cells Market Segmentation
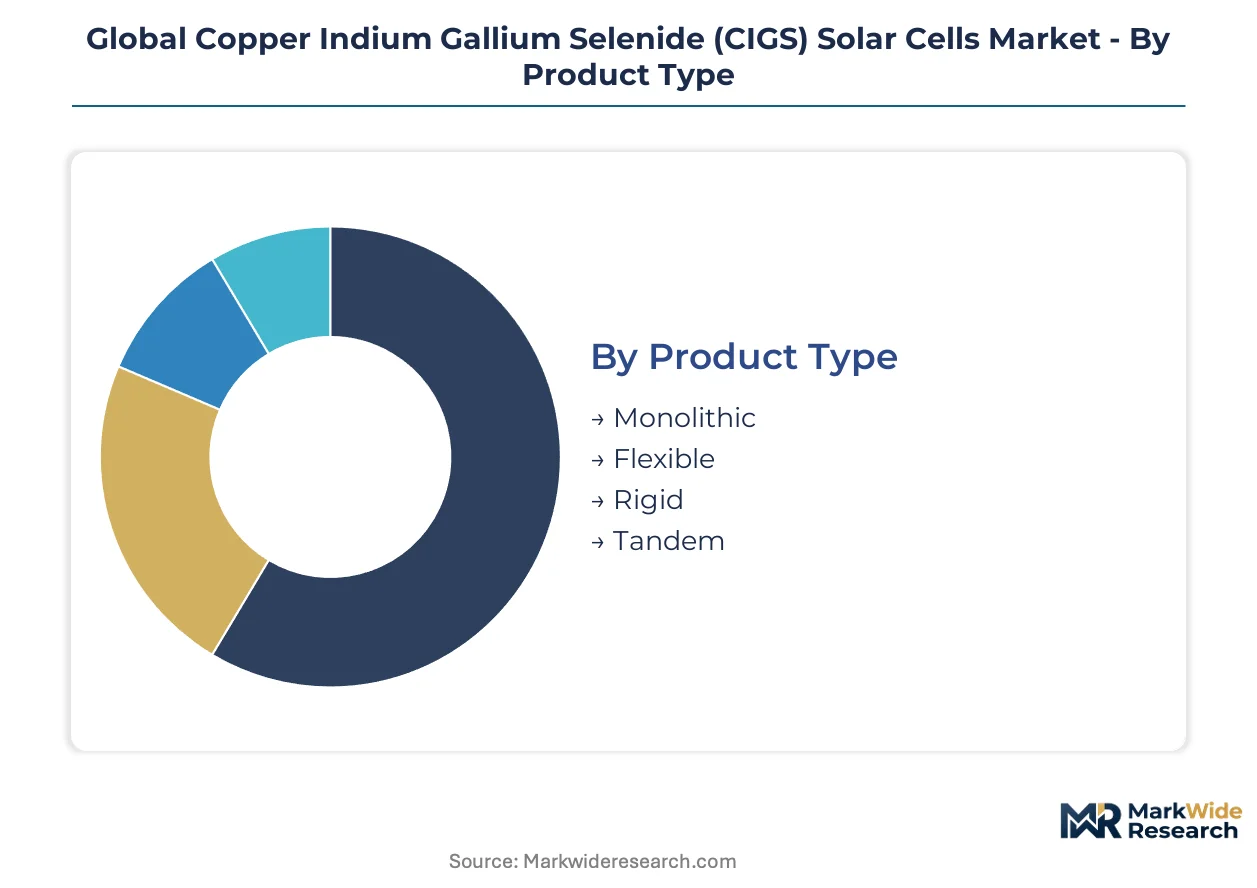
CIGS solar cell manufacturers configure production lines around substrate rigidity and deposition physics, with each segment demanding distinct capital equipment and qualification timelines. Procurement cycles vary dramatically across these boundaries, from rapid-turn flexible laminate orders for building-integrated projects to multi-year validation programs for utility-scale rigid glass contracts.
Product Type:
Flexible modules turn inventory fastest in European building-integrated photovoltaic channels, while monolithic architectures tie up working capital through extended IEC certification sequences.
- Monolithic:Integrated cell-interconnect designs eliminate soldered stringing by patterning molybdenum back contacts and transparent conductive oxides through photolithographic scribing. Utility-scale plants in Germany specify these for megawatt-scale rooftop installations where labor cost reduction outweighs efficiency penalties from dead area losses.
- Flexible:Polyimide or stainless steel substrates enable curvature radii below 500 millimeters and weights under three kilograms per square meter. Japanese automotive glazing programs and German facade retrofit consortia concentrate procurement here, accepting the moisture ingress risks that barrier film engineering must mitigate.
- Rigid:Glass-glass laminates with tempered front sheets and soda-lime rear barriers dominate commercial operations requiring 25-year performance warranties.
- Tandem:Perovskite-CIGS dual-junction stacks push theoretical efficiencies beyond single-junction Shockley-Queisser limits, though selenization thermal budgets complicate top-cell processing compatibility.
Monolithic dominates installed base. Flexible is where expansion concentrates.
Technology:
Cost tiers separate batch vacuum processes from continuous roll-to-roll alternatives, with electroplating attracting capital at the pilot scale for indium reduction.
- Thin-Film:The foundational category encompasses all CIGS architectures distinguished from wafered crystalline silicon by direct absorber deposition onto foreign substrates. Residential installations in Japan favor these for partial shading tolerance on complex roof geometries.
- Vacuum Deposition:Co-evaporation of copper, indium, gallium, and selenium from elemental sources enables precise composition grading through the absorber depth. Solar Frontier's integrated lines in Japan sustain captive output for domestic FIT-to-FIP transition projects.
- Electroplating:Aqueous precursor deposition followed by thermal selenization cuts process energy and indium consumption by half relative to vacuum routes. National renewable energy laboratories in Germany and the United States are scaling pilot lines.
- Sputtering:Magnetron deposition of metallic precursors onto molybdenum-coated substrates precedes rapid thermal processing in hydrogen selenide atmosphere. Avancis employs this for rigid glass modules in European commercial rooftop segments.
Vacuum deposition anchors current manufacturing scale. Electroplating is climbing the fastest.
Application:
Volume concentrates in commercial operations above 750 kilowatts, while margin structures favor military systems with their qualification premiums and long-term supply agreements.
- Residential Installations:Distributed rooftop systems below 20 kilowatts benefit from CIGS temperature coefficient advantages over crystalline silicon in high-irradiance climates. Indian PLI scheme incentives are conditioning technology selection for domestic content compliance.
- Commercial Operations:Flat-roof and facade-integrated systems from 100 kilowatts to 5 megawatts constitute the primary revenue pool. German engineering-procurement-construction consortia are unbundling module supply from installation contracts in this bracket.
- Military Systems:Ruggedized flexible modules for forward operating bases prioritize logistics portability over levelized cost of electricity. Procurement runs through specialized defense contractors with ITAR-controlled supply chains.
- Remote Power Solutions:Off-grid telecommunications and rural electrification in sub-Saharan markets deploy lightweight CIGS for helicopter-transportable microgrids.
Commercial operations dominate installed base. Residential installations are gaining share fastest.
End User:
Customer type determines financing structure and technical specification depth, from merchant price-exposed utility tenders to grant-funded research collaborations.
- Utility-Scale Plants:Centralized generation assets above 5 megawatts procure through competitive auctions with bankability requirements that disadvantage unproven flexible module suppliers. Japan's FIT-to-FIP transition is compressing returns and forcing technology demonstrations under merchant exposure.
- Telecom Providers:Mobile network operators specify remote power for off-grid base stations, with CIGS partial shading tolerance outperforming crystalline silicon in antenna-shadowed configurations.
- Off-Grid Users:Rural households and agricultural operations outside distribution network coverage prioritize module portability and shade tolerance over efficiency maximization.
- Research Institutions:National laboratories and university consortia purchase small-lot specialty modules for process development and tandem cell architecture validation.
Utility-scale plants dominate installed base. Telecom providers are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands pricing power in building-integrated procurement while India squeezes import margins through domestic content mandates. Japanese manufacturers capture premium positioning via captive sputtering capacity. Chinese indium smelters anchor raw material cost structures.
Germany
Utility-scale tenders above 750 kilowatts specify flexible CIGS laminates for facade retrofits where structural load limits exclude crystalline silicon. The EU Green Deal and F-Gas Regulation restrict fluorinated encapsulants, forcing silicone-based barrier reformulation. Engineering-procurement-construction consortia in Berlin and Munich are unbundling module supply from installation contracts.
Japan
Domestic FIT-to-FIP transition compresses project returns and forces technology demonstrations under merchant price exposure. METI feed-in tariff revisions prioritize high-temperature coefficient performance where sputtered CIGS absorbers outperform alternatives. Manufacturing clusters in Miyazaki Prefecture sustain integrated sputtering and selenization lines for captive utility-scale output.
India
BIS certification mandates and PLI scheme incentives condition market access for imported thin-film equipment. The Central Electricity Authority tightens efficiency benchmarks for solar imports through domestic content requirements. Tamil Nadu and Gujarat host emerging electroplating pilot lines seeking indium reduction and process energy savings.
United States
National renewable energy laboratories in Colorado and California scale electroplating R&D for aqueous precursor deposition. The Inflation Reduction Act production tax credits attract equipment investment for domestic thin-film manufacturing. Defense contractors in the Southwest procure ruggedized flexible modules for forward operating base logistics.
China
Primary indium extraction from zinc mining concentrates in Yunnan and Hunan smelting complexes creates price volatility exposure for global sputtering target manufacturers. Dual carbon goals accelerate renewable energy deployment targets without specific CIGS technology preference. Equipment makers in Jiangsu province retrofit legacy batch lines with real-time spectral reflectance monitoring.
Global Copper Indium Gallium Selenide (CIGS) Solar Cells Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in deposition equipment and precursor materials. The vendor base separates into three tiers: integrated module manufacturers with captive process lines, equipment suppliers licensing turnkey production systems, and materials specialists in sputtering targets and barrier films. Strategic moves concentrate on hybrid sputtering-selenization convergence and geographic licensing partnerships to bypass capital-intensive capacity builds.
Among Japanese integrated manufacturers, Solar Frontier anchors the captive production archetype with domestic sputtering capacity. German equipment specialists Manz AG and Avancis occupy positions in the vacuum deposition technology tier, representing European precision engineering in co-evaporation and sputtering-selenization systems. Ascent Solar Technologies exemplifies the flexible substrate specialization archetype targeting building-integrated and defense applications.
| Leading Market Players |
|---|
| Oxford PV |
| Avancis |
| Solar Frontier |
| Jinko Solar |
| Manz AG |
| Ascent Solar Technologies |
| SoloPower Systems |
| Midsummer |
| Hanergy |
| Others |
Cost & Logistics Intelligence
Undercapacity in Japanese sputtering-selenization lines is tightening supply discipline and emboldening domestic manufacturers to hold pricing premiums against European flexible laminate imports. This utilization dynamic concentrates pricing power with integrated producers while forcing project developers in Germany and India to accept longer lead times or absorb cost pass-throughs on indium-bearing precursors.
Pricing Analysis
Configured-to-order pricing for custom-curvature flexible modules commands spreads of 15-25% above standard rigid glass-glass baselines. Three-tier pricing structure across premium, standard, and economy levels segments by IEC certification grade and barrier film warranty duration. Cost compression in standard-grade rigid modules is intensifying because Chinese indium smelters are restricting spot market releases. Utility-scale EPC consortia exhibit highest price sensitivity, while defense contractors accept premiums for ITAR-controlled supply chains.
Supply Chain Analysis
Contract manufacturing concentrates with Solar Frontier's captive Miyazaki lines, Manz AG's German equipment-licensing network, and emerging electroplating pilot capacity at NREL facilities. Primary indium extraction draws from Chinese zinc smelting complexes in Yunnan and Hunan, with secondary recovery from Korean electronics waste streams. Single-source vulnerability in hydrogen selenide precursor supply creates exposure to transport regulation shifts. Distribution runs through direct OEM relationships that displace regional distributor exclusivity in European BIPV channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CIGS solar cell market represents a high-growth disruption as electroplating R&D achieves indium reduction breakthroughs and EU F-Gas Regulation forces encapsulant reformulation. These concurrent inflections are redistributing competitive advantage toward aqueous deposition specialists and silicone-barrier engineers.
For Market Incumbents: Insulate captive sputtering capacity through backward integration into indium sputtering target production, neutralizing Chinese smelter price volatility. Accelerate certification investment for IEC 61215 flexible substrate sequences to defend against electroplating entrants in German commercial rooftop procurement. Prioritize hybrid sputtering-selenization convergence R&D to maintain throughput advantages over batch vacuum alternatives. For New Entrants and Emerging Players: Pursue automotive integrated photovoltaics as the most penetrable white-space target, where curvature tolerance requirements and partial shading performance outweigh efficiency maximization. Target Indian PLI scheme incentives through BIS certification compliance for domestic electroplating capacity. Anchor go-to-market strategy on indium reduction narratives that resonate with EU Green Deal carbon budgeting mandates. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across electroplating pilot lines as aqueous deposition eliminates vacuum chamber infrastructure requirements. Long-term viability favors equipment suppliers licensing turnkey production systems over capital-intensive module manufacturing. Acquisition target archetype: German or Japanese deposition equipment specialists with hybrid process IP. Monitor indium price volatility indices and F-Gas Regulation enforcement timelines as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Electroplating Process Scale-Up | Aqueous precursor deposition at NREL and German labs cuts indium consumption and process energy versus vacuum routes. |
| Silicone Barrier Film Certification | EU F-Gas Regulation prohibition of hydrofluorocarbon encapsulants forces reformulation of flexible module edge seals. |
| Direct OEM Channel Development | Engineering-procurement-construction consortia in Germany unbundle module supply from installation contracts above 750 kilowatts. |
| Hybrid Sputtering-Selenization Convergence | Pilot lines in Japan and Germany combine vacuum deposition precision with rapid thermal processing throughput gains. |
| Indium Recovery and Recycling Investment | Secondary extraction from Korean electronics waste streams diversifies supply beyond Chinese zinc smelting concentration. |
Research Approach
A standing panel of thin-film equipment engineers, utility procurement officers, EPC project developers, and national laboratory R&D directors provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from IEC certification databases, METI feed-in tariff filings, EU F-Gas Regulation implementation guidance, and Indian BIS testing protocols. Bottom-up module shipment estimates triangulated against top-down renewable energy auction capacity allocations.
Scenario-bracketing framed demand projections across the analysis window, with high-case assumptions for electroplating commercialization and low-case constraints from indium supply disruption. Segmentation dimensions modeled include substrate rigidity, deposition technology, application scale, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating technology substitution elasticities and policy incentive phase-out schedules. Forecast inputs encompassed selenization reactor throughput benchmarks and barrier film moisture ingress test results.
Macroeconomic conditions sit as an overlay; deviation in zinc mining output, merchant electricity price volatility, or carbon border adjustment implementation would shift the trajectory. Forecasts reflect documented assumptions regarding electroplating scale-up timelines and F-Gas Regulation grandfathering periods. Quarterly review of indium spot pricing, IEC certification queue lengths, and EU building renovation fund disbursements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductors
IV-IV Compound Semiconductor Market
Semiconductors
Wide Bandgap Semiconductors Market
Semiconductors
Europe Discrete Semiconductor Market
Semiconductors
Semiconductor Market
Semiconductors
East Asia Automotive Semiconductors Market
Semiconductors
Semiconductor IP Market
Semiconductors
Global Computer Microchip Market
Semiconductors
India Semiconductor Market
Semiconductors
Global Organic Semiconductor Market
Semiconductors
Digital Semiconductors Market
Semiconductors
North America Semiconductor Market
Semiconductors
Semiconductor in Military and Aerospace Market
Semiconductors
Semiconductor Intellectual Property Market
Semiconductors
Asia-Pacific Semiconductor Market
Semiconductors
Resistive RAM Market
Semiconductors
Germanium Semiconductor Market