
 Inkjet Printing Market | 2026-2036
Inkjet Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Inkjet Printing Market Outlook
East Asian printhead foundries and precision nozzle manufacturers is pivoting toward higher-resolution thermal and piezoelectric architectures for industrial throughput. HP Inc. leverages its page-wide array technology to dominate high-speed commercial document streams. Canon Inc. anchors the professional photo and fine-art segment with pigment-ink archival systems. Seiko Epson Corporation specializes in precision micro-piezo heads that sustain textile and direct-to-garment growth.
Inkjet printing deposits liquid ink droplets through thermally actuated or piezoelectrically driven nozzles onto substrates at resolutions typically exceeding 300 dpi, with UV-curable and water-based formulations enabling adhesion to porous paper, plastics, textiles, and ceramics. Drop-on-Demand architectures now lead unit shipments across packaging and signage because they eliminate continuous recirculation systems and reduce ink waste. UV Inkjet commands premium positioning in industrial decoration and 3D printing applications where instant curing enables multi-layer build and non-porous substrate compatibility.
The EPA regulates volatile organic compound emissions from solvent-based inkjet operations in the United States, while REACH governs chemical registration and hazard classification for inks sold across Europe. Japan's METI enforces energy-efficiency standards on production-scale printing equipment that shape R&D priorities for hardware OEMs. Stakeholders must monitor how food-contact material approvals from EFSA and the FDA constrain pigment and photoinitiator selection in packaging inks.
Market Dynamics
Water-based and UV-curable ink chemistries are displacing solvent formulations as REACH chemical restrictions and FDA food-contact material rules tighten pigment and photoinitiator selection across packaging applications.
Growth Catalysts
- Short-run corrugated demand:Packaging converters in Germany and Japan are installing single-pass inkjet systems to capture just-in-time production economics that flexographic presses cannot match.
- REACH chemical registration:European hazard classification rules are accelerating formulator investment in aqueous binder systems and LED-UV photoinitiators with lower migration risk.
- Direct-to-garment textile printing:Precision micro-piezo heads now sustain cotton and polyester pretreatment workflows that previously required screen-based color separation.
Market Restraints
- Piezoelectric printhead supply concentration:Precision nozzle manufacturing clusters in East Asian foundries create single-source vulnerability for industrial press OEMs outside the region.
- Pigment dispersion input volatility:Specialty carbon black and organic colorant supply chains face periodic disruption from petroleum feedstock price swings.
- UV ink adhesion limitations:Low-surface-energy polyolefin substrates in flexible food packaging require corona or plasma pretreatment, adding capital and throughput friction.
Strategic Opportunities
- Ceramic tile decoration:Drop-on-Demand UV inkjet is penetrating glazed surface printing in Italy and Spain where rotary screen labor costs are accelerating replacement cycles.
- India packaging SME segment:Compact single-pass corrugated printers address the country's fragmented converter base that lacks capital for flexographic cylinder investments.
- ISO 14001 environmental management:Certification-driven procurement by multinational CPG brands favors ink suppliers with verified lifecycle assessment documentation.
Industry Challenges
- Color management specialist scarcity:ICC profile creation and substrate-specific ink limiting require expertise that vocational programs have not scaled to match hardware deployment.
- Legacy RIP software integration:Prepress workflows built around offset or flexo color separation demand middleware development that delays inkjet press commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inkjet Printing Market |
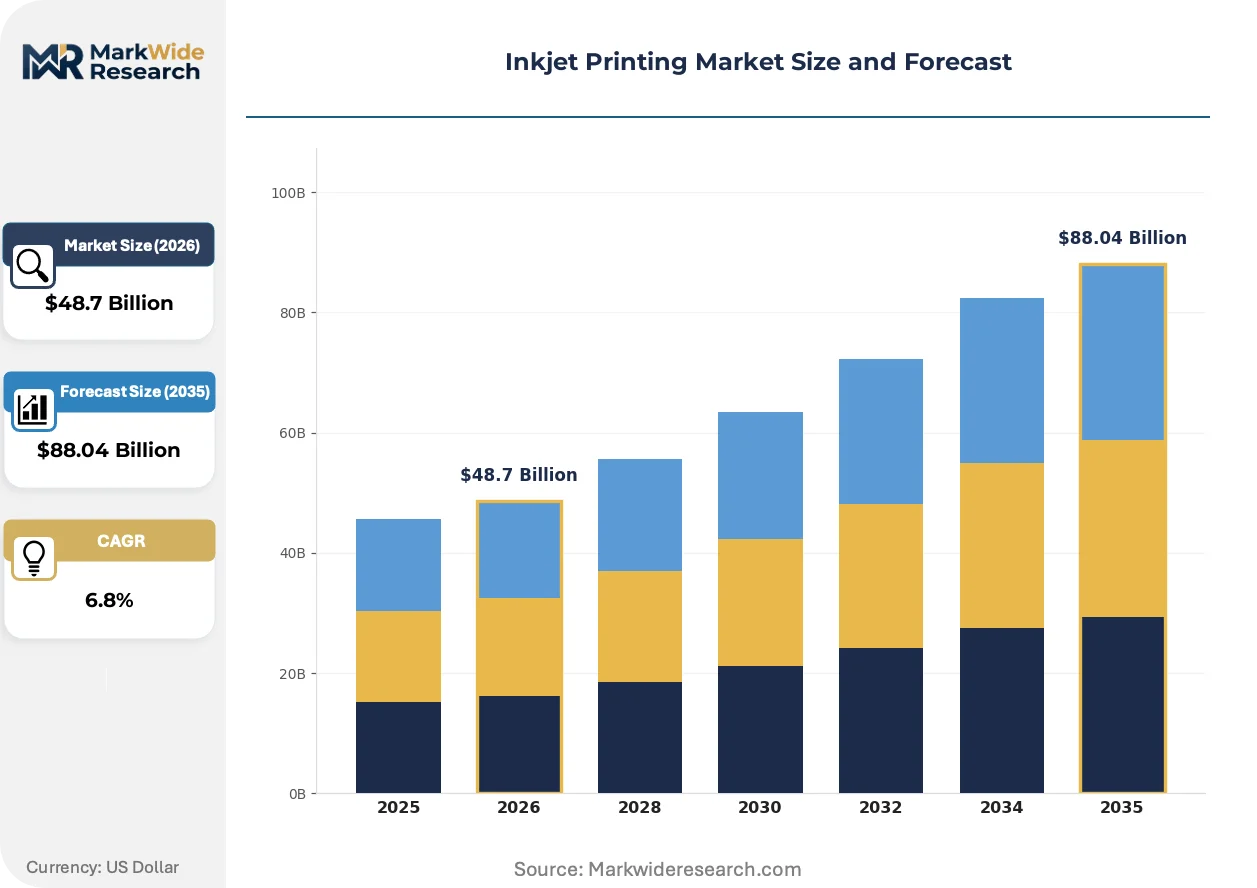
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Inkjet, Drop-on-Demand, Thermal Inkjet, UV Inkjet End User: Commercial Printing, Packaging, Textile, Signage Technology: Inkjet, Printer, Print Head, Imaging Application: Labeling, Decoration, Photo Printing, 3D Printing |
| Companies Covered | Canon Inc., Mimaki Engineering Co., Ltd., HP Inc., Mutoh Holdings Co., Ltd., Electronics For Imaging (EFI), Sun Chemical, DuPont, INX International, Seiko Epson Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inkjet Printing Market Strategic Shifts
Hardware architectures and ink chemistries are converging to address substrate versatility demands that previously required dedicated press lines for each material category.
Single-pass page-wide array technology is integrating fixed printbar configurations that eliminate carriage motion mechanics. Commercial document print shops in the United States are adopting these systems to compress turnaround times on variable-data direct mail. The architecture is integrating high-speed production economics previously exclusive to offset lithography into mid-volume operations.
EPA volatile organic compound emission limits are tightening solvent-based inkjet operational permits in industrial decoration facilities. Print service providers face capital allocation decisions between thermal oxidizer installation and aqueous/UV chemistry conversion. Metal decorating and 3D additive manufacturing segments are most affected, with equipment finance structures now favoring LED-UV curing retrofits.
Brand owners are consolidating ink supply contracts around lifecycle assessment transparency rather than unit cost alone. Beverage and personal care packaging buyers in Germany and Japan are unbundling historical chemical supplier relationships to audit carbon footprint per printed unit. This pattern is most visible in premium cosmetic folding carton procurement where ESG disclosure requirements penetrate tier-two converter selection criteria.
Inkjet Printing Market Segmentation
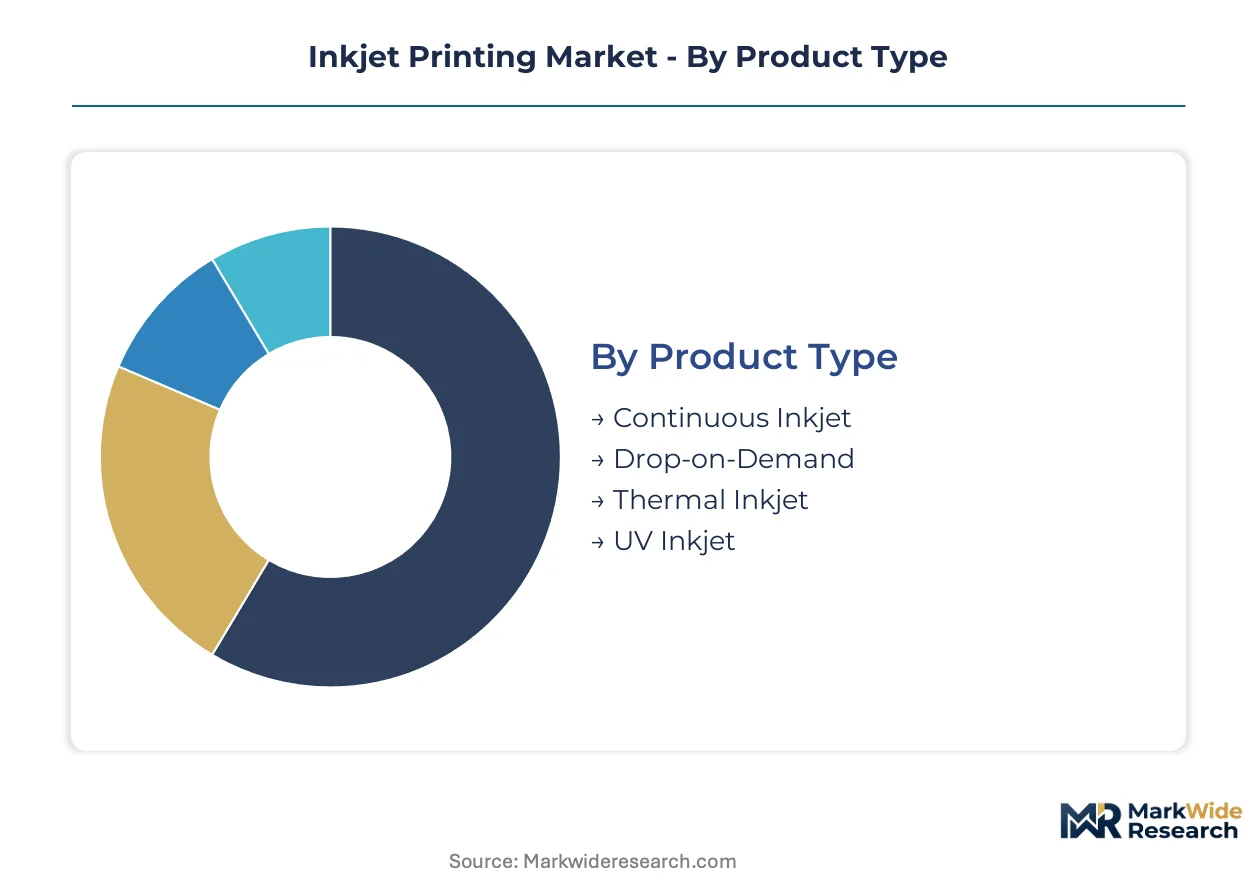
Segmentation in inkjet printing reveals how capital deployment, regulatory exposure, and substrate versatility split demand across hardware architectures and ink chemistries. Each dimension exposes different margin structures and vendor concentration patterns.
Product Type:
Capital intensity varies sharply across these architectures, with UV-curable and continuous recirculation systems demanding the heaviest upfront investment in curing infrastructure and fluid management.
- Continuous Inkjet:Recirculating ink systems maintain droplet velocity through pressurized nozzles, enabling high-speed coding on porous and non-porous surfaces alike. Beverage and pharmaceutical packaging lines in Germany deploy these systems for lot-number serialization under traceability mandates. Capital requirements concentrate in pump infrastructure and solvent recovery equipment.
- Drop-on-Demand:Piezoelectric or thermal actuators eject individual droplets without continuous flow, eliminating recirculation losses. Corrugated converters across Japan favor this architecture for short-run flexibility that flexographic cylinders cannot match. Lower fluid-handling complexity reduces maintenance staffing versus continuous systems.
- Thermal Inkjet:Resistive heating elements vaporize ink to propel droplets, limiting compatible chemistries to water-based formulations with precise boiling-point characteristics. Document production centers in the United States deploy page-wide thermal arrays for variable-data direct mail at throughput speeds rivaling offset.
- UV Inkjet:Photoinitiator-laden inks polymerize instantly under LED or mercury-arc exposure, enabling multi-layer deposition on glass, metal, and ceramics. Industrial decoration facilities in Italy and Spain adopt these systems for ceramic tile glazing where rotary screen labor costs accelerate replacement cycles. Curing equipment adds substantial capital burden alongside the print engine itself.
Drop-on-Demand absorbs the bulk of installed capacity; UV Inkjet is expanding most quickly.
End User:
Application maturity determines which segments command premium pricing versus commodity competition.
- Commercial Printing:Transactional documents, direct mail, and book-on-demand production dominate volume. HP's page-wide array installations in the United States compress turnaround times for variable-data workflows that offset cannot address profitably.
- Packaging:Folding cartons, corrugated containers, and flexible films require food-contact-compliant ink chemistries. REACH restrictions and FDA migration limits are pushing European and North American converters toward aqueous binder systems and low-migration photoinitiators.
- Textile:Direct-to-garment and roll-to-roll fabric printing demand pretreatment workflows for cotton and polyester. Precision micro-piezo heads from Seiko Epson sustain growth in this segment by enabling photographic color reproduction without screen-based separation.
- Signage:Wide-format display graphics and vehicle wraps utilize solvent, eco-solvent, and UV formulations on vinyl and rigid substrates. EPA volatile organic compound limits are tightening operational permits for solvent-based operations in industrial decoration facilities.
Commercial Printing retains the deepest installed base; Packaging is climbing the fastest as brand owners consolidate supply contracts around lifecycle assessment transparency.
Technology:
Supply concentration patterns differ markedly between consumables, hardware, and precision components.
- Ink:Formulations span aqueous, solvent, UV-curable, and oil-based chemistries, each with distinct pigment dispersion requirements. Specialty carbon black and organic colorant supply chains face periodic disruption from petroleum feedstock volatility.
- Printer:Complete press systems integrate transport, curing, and color management subsystems. Single-pass page-wide configurations eliminate carriage motion mechanics, compressing turnaround times for mid-volume operations.
- Print Head:Precision nozzle manufacturing clusters in East Asian foundries create single-source vulnerability for industrial press OEMs outside the region. Thermal and piezoelectric architectures each demand distinct microfabrication expertise.
- Imaging:Raster image processor software and ICC profile creation tools bridge design files to device-specific color output. Legacy prepress workflows built around offset or flexo separation demand middleware development that delays inkjet press commissioning timelines.
Printer systems absorb the bulk of installed capacity; Print Head is gaining share fastest as resolution and durability specifications tighten.
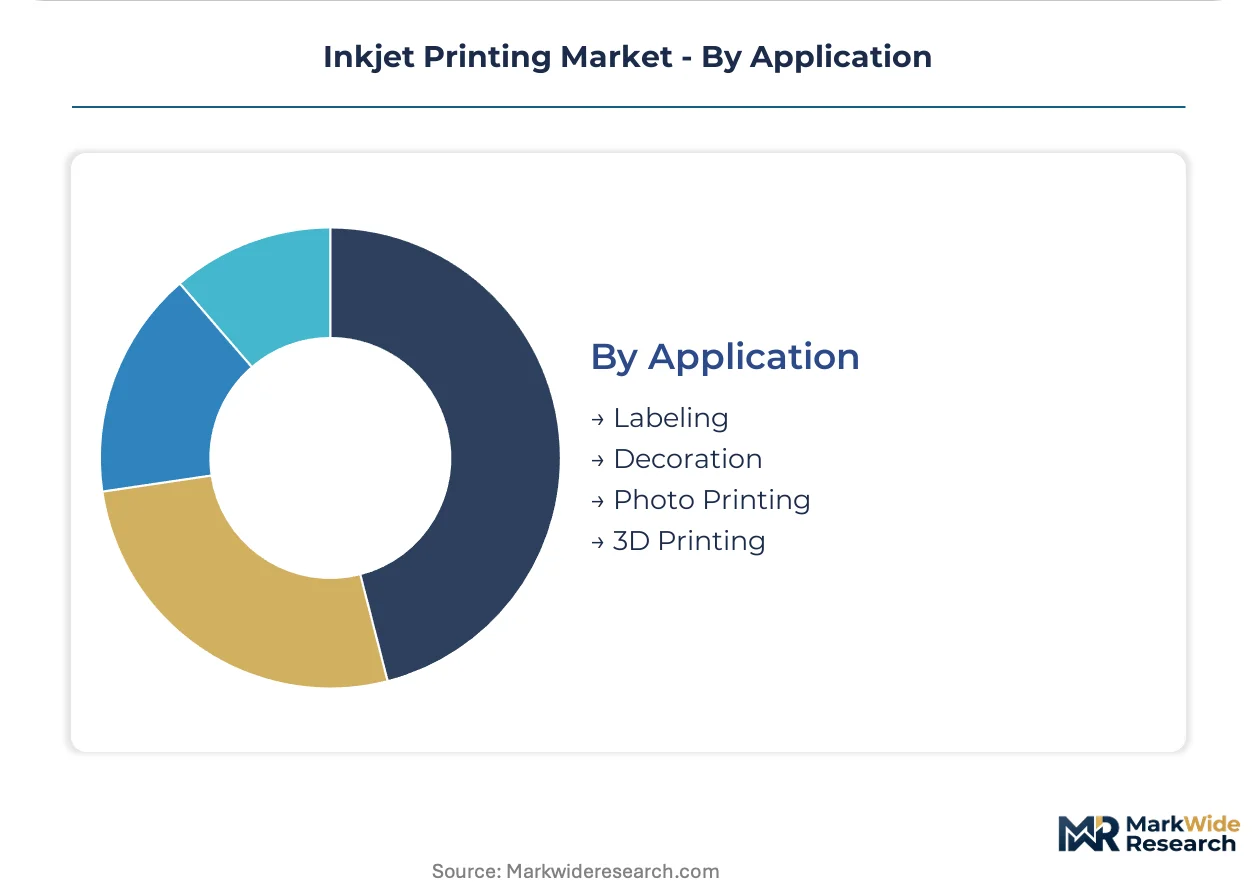
Application:
Functional requirements separate segments by adhesion chemistry, curing speed, and dimensional precision.
- Labeling:Pressure-sensitive and shrink-sleeve applications demand food-contact-compliant formulations with low migration risk. Beverage and personal care packaging buyers in Germany audit carbon footprint per printed unit.
- Decoration:Industrial goods, consumer electronics, and automotive interiors require durable graphics on curved or textured surfaces. UV inkjet penetrates glazed ceramic printing where rotary screen labor costs accelerate replacement cycles.
- Photo Printing:Archival pigment-ink systems target professional photographers and fine-art reproduction. Canon anchors this segment with color permanence ratings exceeding traditional silver-halide output.
- 3D Printing:Material jetting deposits photocurable resins layer-by-layer to build functional prototypes and end-use parts. Multi-material capability and support-structure removal complexity distinguish this application from planar graphics.
Labeling retains the deepest installed base; 3D Printing shows the steepest expansion trajectory as additive manufacturing penetrates production rather than prototyping alone.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Piezoelectric printhead foundries in Kyushu and thermal nozzle manufacturing clusters in Shenzhen anchor regional supply chains. Ink formulation expertise concentrates near chemical processing hubs in Ludwigshafen and Houston. Press OEMs locate final assembly near packaging converter density in Düsseldorf and Chicago.
United States
Commercial document print shops in Chicago and Dallas deploy page-wide thermal arrays for variable-data direct mail at throughput speeds rivaling offset. EPA volatile organic compound emission limits tighten solvent-based operational permits in industrial decoration facilities. HP Inc. leverages its page-wide array technology to dominate high-speed commercial document streams from its Palo Alto engineering base.
Germany
Packaging converters in Düsseldorf and Hamburg install single-pass inkjet systems to capture just-in-time production economics that flexographic presses cannot match. REACH chemical registration and hazard classification rules accelerate formulator investment in aqueous binder systems and LED-UV photoinitiators with lower migration risk. Heidelberg and Munich host precision engineering clusters where press OEMs integrate transport and curing subsystems.
Japan
Precision micro-piezo head manufacturing sustains textile and direct-to-garment growth from foundries in Kyushu and Nagoya. METI enforces energy-efficiency standards on production-scale printing equipment that shape R&D priorities for hardware OEMs. Seiko Epson Corporation anchors the professional photo and fine-art segment with pigment-ink archival systems from its Suwa engineering headquarters.
China
Drop-on-Demand architecture manufacturing scales in Shenzhen and Dongguan to serve corrugated converters across the Pearl River Delta. GB standards and MIIT industrial policy shape equipment certification timelines for both domestic and export markets. Zhengzhou and Chengdu packaging SME clusters adopt compact single-pass corrugated printers that address fragmented converter capital constraints.
Italy
UV inkjet penetrates glazed ceramic tile printing in Sassuolo and Modena where rotary screen labor costs accelerate replacement cycles. EFSA food-contact material approvals constrain pigment and photoinitiator selection in packaging inks exported across the European Union. Bologna and Milan host industrial decoration equipment integrators specializing in multi-layer build applications.
Inkjet Printing Market Competitive Environment
Global majors compete with regional champions across hardware architecture, ink chemistry, and precision component supply. The vendor base stratifies between integrated systems houses, specialty chemical formulators, and precision nozzle foundries. Three archetypes dominate: diversified technology conglomerates with page-wide array portfolios, precision micro-piezo specialists serving textile and photo segments, and chemical formulators with UV-curable expertise. Competitive moves concentrate on strategic partnerships between press OEMs and ink suppliers, plus capacity expansion in East Asian printhead foundries.
Among diversified technology conglomerates, Canon Inc. and HP Inc. occupy positions spanning commercial document and professional photo segments. Seiko Epson Corporation exemplifies the precision micro-piezo specialist archetype with concentrated expertise in textile and direct-to-garment applications. These three anchors demonstrate how hardware-ink integration strategies separate premium-tier positioning from commodity competition.
| Leading Market Players |
|---|
| Canon Inc. |
| Mimaki Engineering Co., Ltd. |
| HP Inc. |
| Mutoh Holdings Co., Ltd. |
| Electronics For Imaging (EFI) |
| Sun Chemical |
| DuPont |
| INX International |
| Seiko Epson Corporation |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between REACH-compliant aqueous formulations and commodity solvent chemistries manifests in both unit pricing and raw material sourcing configurations. Premium ink suppliers command 30-40% spreads over commodity tiers by bundling EFSA migration documentation and ISO 14001 lifecycle transparency into supply contracts, while converters in Germany and Japan absorb these premiums to secure brand-owner procurement eligibility.
Pricing Analysis
Extended warranty and printhead refurbishment bundling separates premium-tier press OEMs from unbundled equipment vendors in competitive tenders. Three-tier pricing structure across premium, standard, and economy levels tracks LED-UV curing integration, food-contact certification status, and geographic service density. Cost compression in mid-tier aqueous formulations is intensifying because East Asian foundries are scaling piezoelectric nozzle output. SME packaging converters in India and China exhibit highest price sensitivity, while multinational CPG brands in Germany prioritize total cost of ownership over unit ink pricing.
Supply Chain Analysis
Remanufactured printhead flows from Kyushu and Shenzhen refurbishment centers back into secondary equipment markets, extending nozzle lifecycles and compressing replacement part pricing. Precision microfabrication clusters in Japan, South Korea, and Taiwan anchor global piezoelectric actuator supply. Specialty carbon black and organic photoinitiator feedstocks draw from petroleum processing hubs in Germany and the United States. Single-source vulnerability concentrates in East Asian nozzle foundries. Distribution runs through authorized OEM service networks and independent aftermarket channels serving converter clusters in Düsseldorf, Chicago, and the Pearl River Delta.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Piezoelectric printhead foundry capacity constraints are propping equipment pricing power, as lead times for industrial-grade nozzles stretch procurement timelines for press OEMs outside East Asia.
For Market Incumbents: Anticipate margin compression from emerging Chinese press OEMs by deepening captive ink formulation capabilities in Ludwigshafen and Houston chemical hubs. Accelerate LED-UV curing R&D to preempt EPA emission enforcement tightening on solvent-based operations. Vertical integration into precision nozzle microfabrication reduces single-source exposure from Kyushu suppliers.
For New Entrants and Emerging Players: Launch via compact single-pass corrugated printer distribution targeting India's fragmented SME converter base, where flexographic cylinder capital barriers exclude incumbent competition. White-space concentration sits in ceramic tile decoration aftermarket services across Italy's Sassuolo cluster, where rotary screen replacement cycles accelerate hardware refresh demand. Direct-to-garment pretreatment workflow bundling offers lowest customer acquisition friction.
For Investors and Strategic Acquirers: Re-rating potential sits with UV-curable ink formulators given REACH chemical registration tightening and brand-owner ESG disclosure requirements. Long-term viability favors suppliers with verified lifecycle assessment documentation and backward integration into photoinitiator synthesis. Monitor EFSA and FDA food-contact material approval timelines as inflection signals for packaging ink margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photoinitiator Synthesis | Captive supply of LED-UV curing components insulates margin from petroleum feedstock volatility affecting specialty carbon black. |
| Single-Pass Page-Wide Array Launch | Elimination of carriage motion mechanics compresses turnaround times for mid-volume commercial document shops in Chicago and Dallas. |
| ISO 14001 Environmental Certification | Verified lifecycle assessment documentation unlocks multinational CPG brand procurement contracts in Germany and Japan. |
| Regional Printhead Foundry Expansion | Kyushu and Shenzhen capacity additions reduce single-source vulnerability for industrial press OEMs serving European converters. |
| Direct-to-Garment Pretreatment Workflow Bundle | Integrated cotton and polyester preparation sustains textile segment growth against screen-based color separation alternatives. |
Study Parameters
Multi-period observation of press installation rates, ink formulation patent filings, and regulatory enforcement patterns anchored the trend analysis, supplemented by interviews with packaging converter operations directors, ink formulator R&D leads, printhead manufacturing engineers, and brand-owner procurement managers. Secondary validation drew from ECHA REACH registration databases, EPA emission permit disclosures, METI energy-efficiency filings, and SEC equipment manufacturer 10-K reports. Bottom-up triangulation across regional converter surveys and top-down reconciliation against chemical industry production data ensured consistency.
Segment-weighting approaches distributed value estimates across hardware architecture, ink chemistry, end-use application, and geographic demand clusters. CAGRs were derived from installed base replacement cycles, capacity expansion announcements, and regulatory phase-in timelines. Industry-specific forecast inputs incorporated UV-curable ink adhesion performance on low-surface-energy substrates and piezoelectric nozzle durability specifications for textile pretreatment workflows.
Feedstock price volatility, regulatory approval delays at EFSA and FDA, and East Asian foundry supply disruptions are the dominant revision risks to projection assumptions. Practitioners should monitor photoinitiator raw material spot markets, food-contact material rulemaking calendars, and Kyushu manufacturing output reports for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printers
Nanographic Printing Market
Printers
Mobile Printer Market
Printers
Global Printer Market
Printers
A3 and A4 Multi-Function Printer Market
Printers
NCR Printers Market
Printers
Ink Tank Printer Market
Printers
Retail Printers and Consumables Market
Printers
Global Thermal Printing Market
Printers
Thermal Inkjet Printer Market
Printers
Copier, MFP and Printer Market
Printers
Aerosol Printing and Graphics Market
Printers
Global Ticket Printers Production Market
Printers
Electrophotographic Printing Market
Printers
Mobile Photo Printer Market
Printers
Global Thermal Inkjet Print-Heads Market
Printers
Dot Matrix Printer Market