
 South Korea Discrete Semiconductors Market | 2026-2036
South Korea Discrete Semiconductors Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Discrete Semiconductors Market Insights
Automotive electrification is hardening demand for discrete semiconductors across South Korea's supplier base. Infineon Technologies AG leverages its SiC module expertise to anchor contracts with domestic EV platforms. Rohm Co., Ltd. sustains vertical integration from substrate to module, competing on cost structure against fabless rivals. Samsung-backed ecosystem players dominate legacy silicon packaging while navigating gallium nitride qualification cycles.
Discrete semiconductors are individual, non-integrated circuit electronic components—diodes, transistors, thyristors, and rectifiers—fabricated through epitaxial growth, ion implantation, and metallization processes, typically rated from milliwatts to kilowatts for switching, rectification, and power conversion tasks. Silicon carbide technology leads in thermal performance and efficiency gains for traction inverters, while gallium nitride occupies fast-switching consumer adapter segments where form factor shrinks matter most. Diodes retain volume dominance in industrial rectification, though transistor revenue pools deepen in automotive IGBT and MOSFET modules.
MFDS semiconductor-grade material standards, K-Semiconductor Belt infrastructure directives, and METI-aligned export control frameworks shape product qualification timelines and fab equipment access. These regulations force domestic producers toward JIS-equivalent reliability certifications and restrict certain compound semiconductor deposition tool imports. Stakeholders must weigh captive SiC substrate investment against foundry partnership models as wafer supply tightens.
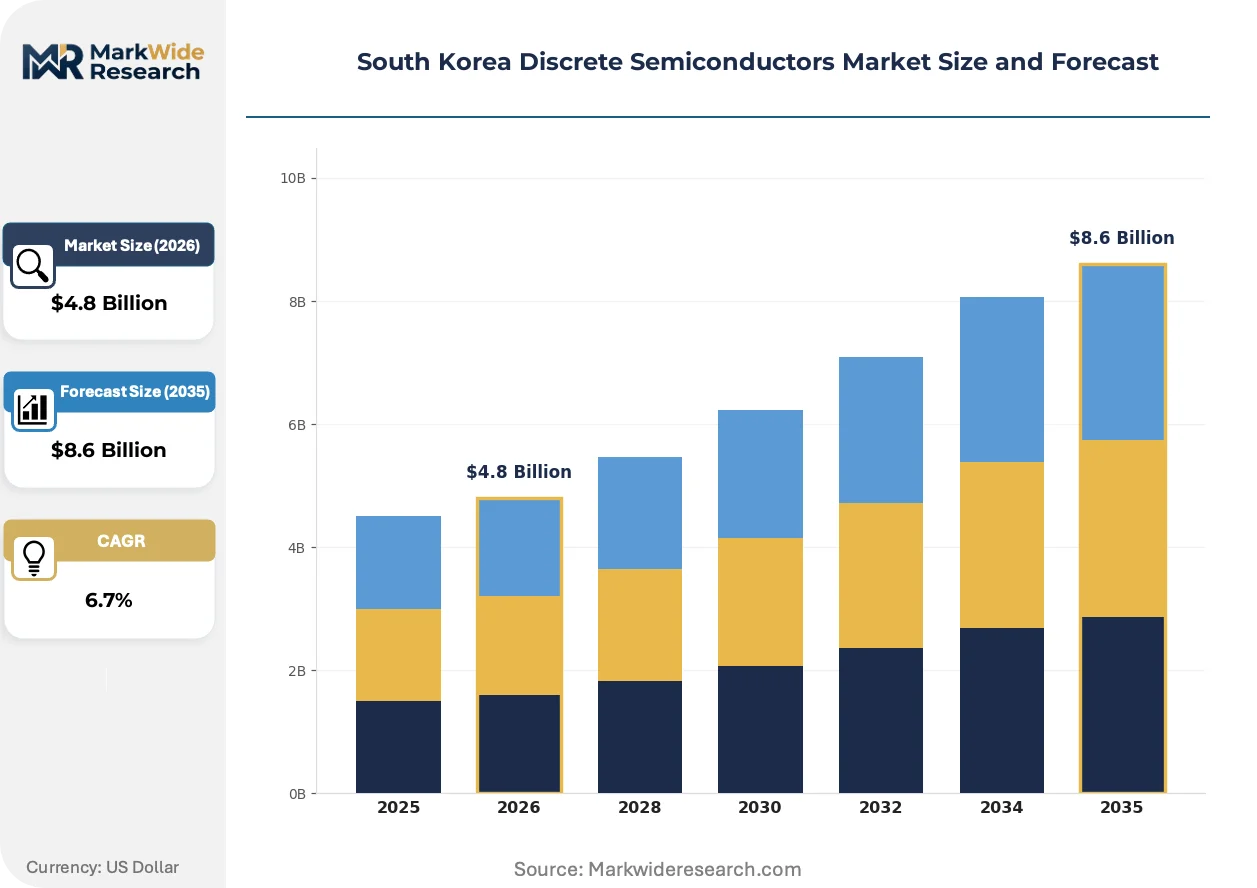
Market Dynamics
Silicon carbide substrate shortages are forcing South Korean power module makers into long-term wafer supply contracts while K-Semiconductor Belt subsidies accelerate domestic epitaxial capacity buildout.
Growth Catalysts
- MFDS semiconductor-grade material standards:These certification requirements are accelerating qualification timelines for domestic SiC device producers serving medical and automotive power electronics.
- Electric vehicle powertrain electrification:Traction inverter demand is pulling 650V-1200V MOSFET and diode volumes from Seoul-based packaging houses into Hyundai-Kia supply chains.
- Pyeongtaek cluster concentration:Foundry and advanced packaging co-location is reducing logistics costs for fabless GaN designers qualifying consumer adapter reference designs.
Market Restraints
- 6-inch SiC substrate cost volatility:Wolfspeed and II-VI supply concentration limits price negotiation leverage for Korean module assemblers.
- METI-aligned export control friction:Japanese deposition tool licensing delays are extending compound semiconductor fab equipment lead times by 8-14 months.
- Silicon IGBT substitution ceiling:Cost-sensitive industrial motor drives below 400V continue specifying mature trench-gate silicon despite SiC efficiency advantages.
Strategic Opportunities
- Gwangju region underpenetration:Secondary packaging and test capacity expansion outside Seoul-Pyeongtaek corridors offers land cost arbitrage for mid-volume diode producers.
- Renewable energy inverter demand:Utility-scale solar and onshore wind installations are specifying 1700V SiC modules for string inverter architectures.
- K-Semiconductor Belt R&D tax credits:These incentives subsidize 30-40% of compound semiconductor pilot line capex for qualified domestic applicants.
Industry Challenges
- Compound semiconductor process engineer scarcity:Epitaxial growth and ion implantation specialists command 2.5x silicon fab equivalent salaries, constraining SiC line ramp schedules.
- JIS-equivalent reliability certification timelines:Automotive AEC-Q101 qualification cycles extend 18-24 months, delaying revenue recognition for new discrete product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Discrete Semiconductors Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diodes, Transistors, Thyristors, Rectifiers End User: Consumer Electronics, Automotive, Telecommunications, Industrial Applications Technology: Silicon, Gallium Nitride, Silicon Carbide, Compound Semiconductors Packaging Type: TO-220, TO-247, SMD, Power Modules |
| Companies Covered | Vishay Intertechnology Inc., STMicroelectronics NV, Infineon Technologies AG, Onsemi, Rohm Co., Ltd., Renesas Electronics Corp., Diodes Incorporated, Nexperia BV, Littelfuse Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Discrete Semiconductors Market Trends and Innovations
Discrete semiconductor architecture is converging around system-in-package integration while regulatory pressure on efficiency standards accelerates wide-bandgap material substitution across power conversion applications.
Silicon carbide MOSFETs with integrated Schottky diodes are unifying switching and rectification functions in single-die configurations. Automotive inverter designers at domestic EV platforms are specifying these co-packaged devices for 800V architectures. This unification is compressing module component counts by 30-40% while forcing legacy silicon suppliers into joint development agreements with SiC substrate specialists.
K-Semiconductor Belt infrastructure directives are mandating domestic wafer fab equipment procurement quotas for subsidized projects. These localization requirements are redirecting capex toward Korean-built ion implanters and epitaxial reactors. Compound semiconductor startups in Seoul and Suwon are restructuring supply agreements to satisfy MFDS domestic content verification.
Power module procurement is consolidating around direct foundry relationships rather than distributor intermediation. Industrial inverter OEMs are negotiating multi-year die supply agreements with Samsung-backed packaging houses. This disintermediation is most visible in Pyeongtaek, where tier-one automotive suppliers have established on-site engineering liaison offices.
South Korea Discrete Semiconductors Market Segmentation
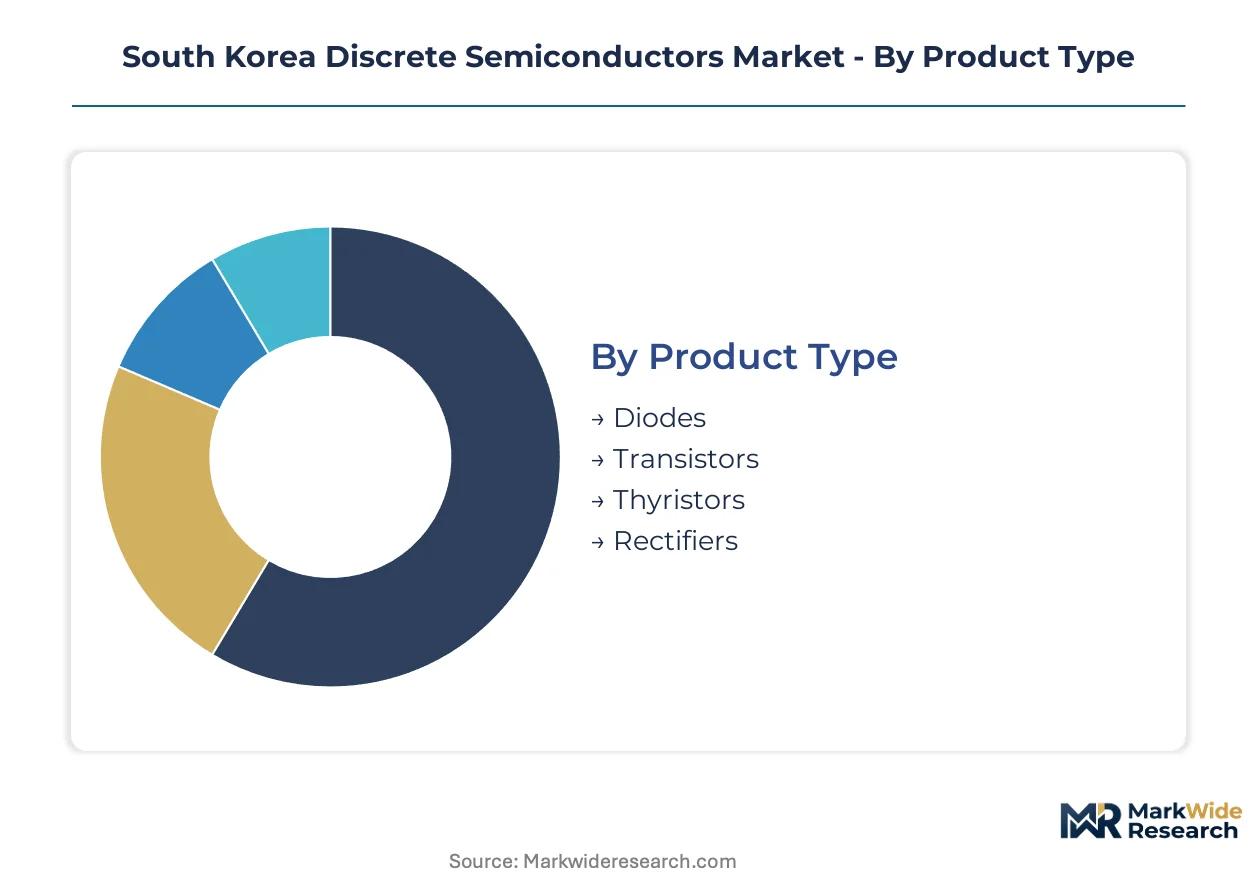
Discrete semiconductor segmentation in South Korea reveals distinct integration patterns across power conversion applications. Product architecture determines whether devices operate as standalone components or embed within larger system-in-package configurations.
Product Type:
Integration depth varies sharply across this category, with some segments serving as discrete building blocks while others merge into compound module assemblies.
- Diodes:Unipolar rectification devices fabricated through epitaxial growth on silicon or SiC substrates, rated from milliwatts to kilowatts. Industrial motor drives across Gwangju manufacturing corridors specify these for AC-DC conversion, though silicon IGBT substitution ceilings constrain premium pricing power.
- Transistors:Bipolar and field-effect switching elements including MOSFETs and IGBTs, processed through ion implantation and metallization sequences. Hyundai-Kia traction inverter procurement is pulling 650V-1200V MOSFET volumes from Seoul-based packaging houses at accelerating rates.
- Thyristors:Four-layer semiconductor switches for high-power phase control applications. Legacy industrial equipment in Busan heavy manufacturing zones maintains steady demand for these mature devices.
- Rectifiers:Bridge and full-wave configurations integrating multiple diode junctions. Renewable energy inverter OEMs specify 1700V variants for utility-scale solar installations.
Diodes lead volumes today; transistors are gaining share fastest.
End User:
Application cost tiers stratify procurement patterns, with automotive and industrial segments commanding premium qualification standards while consumer electronics optimize for unit economics.
- Consumer Electronics:Fast-switching GaN adapters and mobile power management ICs dominate this price-sensitive tier. Pyeongtaek cluster fabless designers qualify reference designs for smartphone OEMs under compressed margin constraints.
- Automotive:AEC-Q101-qualified power modules for 800V traction architectures. MFDS semiconductor-grade material standards are accelerating qualification timelines for domestic SiC device producers serving this segment.
- Telecommunications:Base station power supplies and RF amplification subsystems. 5G infrastructure deployment in Seoul metropolitan corridors sustains demand for high-reliability discretes.
- Industrial Applications:Motor drives, welding equipment, and uninterruptible power supplies. Cost-sensitive specifications below 400V continue specifying mature trench-gate silicon despite SiC efficiency advantages.
Industrial applications anchor current revenue; automotive delivers the steepest expansion trajectory.
Technology:
Material maturity curves determine supply concentration, with silicon maintaining broadest availability while wide-bandgap alternatives face substrate bottlenecks.
- Silicon:Mature trench-gate IGBTs and super-junction MOSFETs dominate below-400V applications. Samsung-backed ecosystem players control legacy packaging capacity for this established technology base.
- Gallium Nitride:Heteroepitaxial devices on silicon substrates for sub-100kHz switching frequencies. Consumer adapter form factor requirements in Suwon design centers favor this technology's fast-switching characteristics.
- Silicon Carbide:Homoepitaxial MOSFETs and Schottky diodes on 4H-SiC substrates for 650V-1700V ranges. Wolfspeed and II-VI supply concentration limits Korean module assembler price negotiation leverage.
- Compound Semiconductors:GaAs and InP devices for RF and optoelectronic applications. METI-aligned export control friction extends deposition tool lead times for domestic fab projects.
Silicon retains volume dominance; silicon carbide is climbing the fastest.
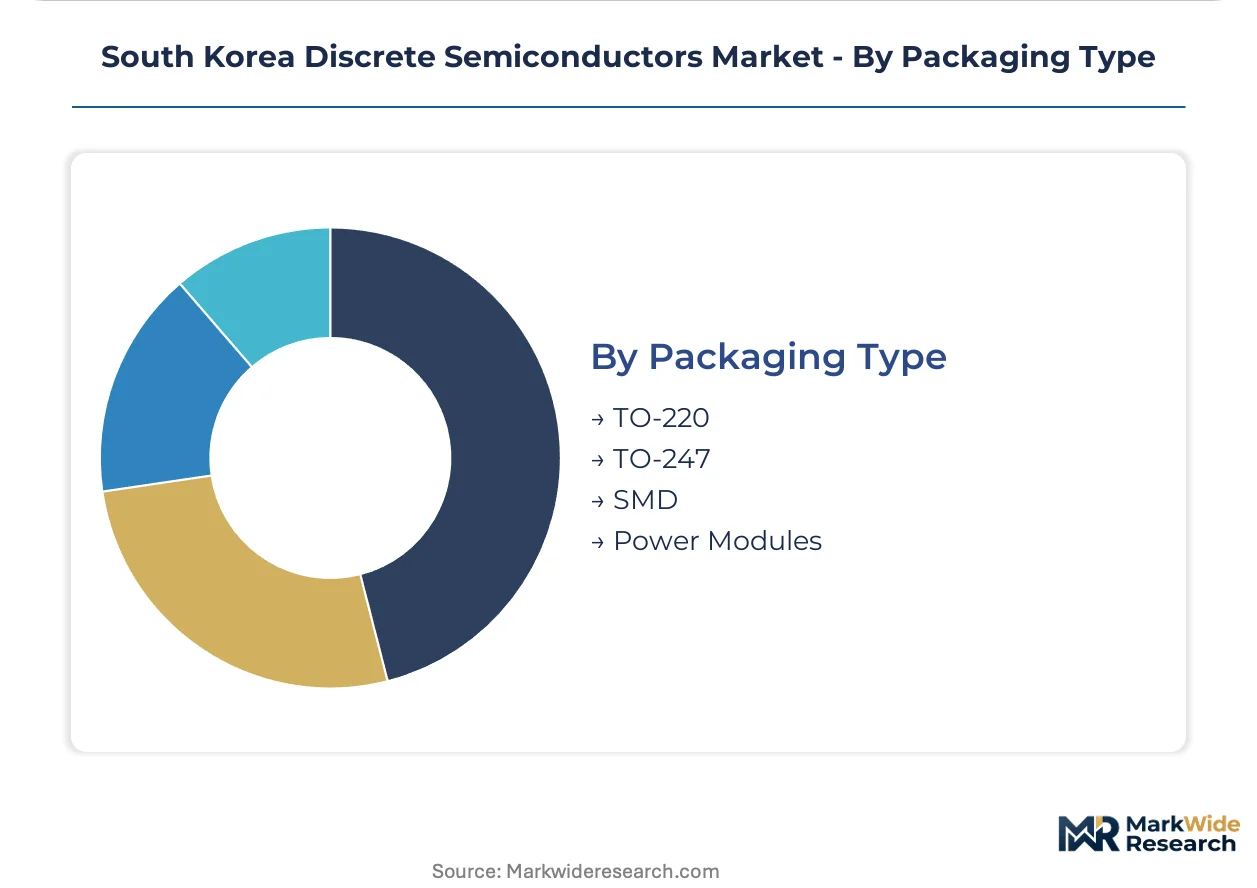
Packaging Type:
Customer procurement scale determines packaging selection, with high-volume automotive programs favoring modules while fragmented industrial buyers specify discrete leaded packages.
- TO-220:Through-hole plastic packages for low-to-medium power applications. Legacy industrial equipment refurbishment sustains demand across Daegu manufacturing zones.
- TO-247:Isolated metal tab packages for higher thermal dissipation requirements. Motor drive OEMs specify these for 600V-1200V IGBT implementations.
- SMD:Surface-mount devices for high-density PCB assemblies in consumer electronics. Pyeongtaek advanced packaging co-location reduces logistics costs for fabless designers.
- Power Modules:Multi-die integrated assemblies with direct bonded copper substrates and encapsulation. Tier-one automotive suppliers have established on-site engineering liaison offices for these high-value configurations.
TO-220 and TO-247 lead unit shipments; power modules capture the fastest value growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Seoul Capital Area concentrates South Korea's discrete semiconductor demand through its dominance of EV powertrain engineering and advanced packaging infrastructure.
Seoul Capital Area
Hyundai-Kia traction inverter procurement and 5G base station power supply manufacturing anchor demand for 650V-1200V MOSFETs. MFDS semiconductor-grade material standards accelerate qualification timelines for domestic producers serving automotive and medical power electronics. Samsung-backed ecosystem players in Suwon and Pyeongtaek dominate legacy silicon packaging while navigating gallium nitride qualification cycles.
Busan-Ulsan
Heavy manufacturing zones sustain steady demand for mature thyristors in legacy industrial equipment and shipbuilding motor drives. The country's national industrial standards body enforces JIS-equivalent reliability certifications that extend product qualification cycles. Ulsan petrochemical complexes specify high-power rectifiers for process automation systems.
Daegu-Gyeongbuk
Industrial motor drive OEMs below 400V continue specifying cost-sensitive trench-gate silicon IGBTs despite SiC efficiency advantages. K-Semiconductor Belt subsidies redirect capital expenditure toward Korean-built ion implanters and epitaxial reactors. Daegu manufacturing zones maintain refurbishment demand for TO-220 packaged devices in legacy equipment.
Daejeon-Sejong
Compound semiconductor startups cluster around government research institutes pursuing SiC epitaxial growth capabilities. K-Semiconductor Belt R&D tax credits subsidize 30-40% of pilot line capital expenditure for qualified domestic applicants. Sejong administrative city hosts engineering liaison offices coordinating between fabless designers and foundry partners.
Gwangju-Honam
Secondary packaging and test capacity expansion offers land cost arbitrage for mid-volume diode producers outside Seoul-Pyeongtaek corridors. Renewable energy inverter demand for utility-scale solar installations specifies 1700V SiC modules. Gwangju region remains underpenetrated relative to northern industrial clusters, attracting cost-focused industrial discrete producers.
South Korea Discrete Semiconductors Market Competitive Landscape
Capacity expansion dominates the current landscape as substrate shortages force long-term wafer supply contracting. The vendor base organizes around three tiers: integrated device manufacturers with captive SiC substrate access, fabless designers reliant on foundry partnerships, and packaging specialists serving industrial legacy demand. Strategic archetypes include vertical integrators controlling epitaxial growth through module assembly, foundry-dependent designers optimizing fast-switching consumer adapters, and scale-driven legacy silicon suppliers. Competitive moves concentrate on backward integration into substrate supply and multi-year die supply agreements that disintermediate distributor channels.
Among diversified multinational suppliers, Infineon Technologies AG and STMicroelectronics NV exemplify the integrated device manufacturer archetype with broad power semiconductor portfolios. Rohm Co., Ltd. occupies a distinct position representing Japanese vertical integration from substrate production through module assembly. These three anchors demonstrate how geographic origin and corporate structure shape competitive positioning across SiC and legacy silicon technology tiers.
| Leading Market Players |
|---|
| Vishay Intertechnology Inc. |
| STMicroelectronics NV |
| Infineon Technologies AG |
| Onsemi |
| Rohm Co., Ltd. |
| Renesas Electronics Corp. |
| Diodes Incorporated |
| Nexperia BV |
| Littelfuse Inc. |
| Others |
Pricing and Supply Chain Analysis
Tier-one automotive suppliers negotiating multi-year die supply agreements with Seoul-based packaging houses dictate contract-based long-term offtake pricing across South Korea's discrete semiconductor market. Hyundai-Kia traction inverter procurement volumes compress distributor margins while accelerating direct foundry relationships that disintermediate traditional channel markups.
Pricing Analysis
Distributor margin compression now runs through the 650V-1200V MOSFET tier as tier-one automotive suppliers negotiate direct die supply agreements with Samsung-backed packaging houses. Three-tier pricing structure across AEC-Q101-certified premium, industrial-grade standard, and consumer-economy levels separates automotive qualification timelines from cost-sensitive adapter segments. Cost compression in legacy silicon IGBTs below 400V intensifies because industrial motor drive OEMs resist SiC premiums despite efficiency advantages. Consumer electronics adapters exhibit highest price sensitivity; automotive power modules show lowest sensitivity due to AEC-Q101 certification barriers.
Supply Chain Analysis
Epitaxial growth and ion implantation specialist scarcity in Seoul and Pyeongtaek clusters extends equipment lead times and inflates talent acquisition costs for SiC line ramps. Substrate supply concentrates in the United States and Japan; packaging capacity centers on South Korea and Taiwan. Wolfspeed and II-VI wafer output constrains Korean module assembler feedstock access. Single-source vulnerability in 6-inch SiC substrate supply creates procurement risk for domestic power module makers. Distribution runs through direct foundry relationships rather than distributor intermediation for high-volume automotive programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's discrete semiconductor market offers margin expansion through SiC substrate backward integration and premium-tier AEC-Q101 certification capture. K-Semiconductor Belt subsidies offset pilot line capital intensity while automotive electrification hardens long-term contract pricing.
For Market Incumbents: Extend captive SiC substrate supply through long-term wafer offtake agreements with Wolfspeed and II-VI to secure feedstock against fabless rivals. Infineon Technologies AG and STMicroelectronics NV demonstrate how integrated device manufacturer structures defend position against Rohm Co., Ltd.'s vertical cost structure. Accelerate JIS-equivalent reliability certification investment to compress 18-24 month AEC-Q101 qualification cycles and capture Hyundai-Kia platform wins before emerging entrants qualify. For New Entrants and Emerging Players: Enter via Gwangju region packaging and test capacity expansion where land cost arbitrage supports mid-volume diode production outside Seoul-Pyeongtaek corridor concentration. The 1700V SiC module segment for utility-scale solar inverters remains underpenetrated by domestic suppliers despite renewable energy procurement growth. Partner with Daejeon-Sejong government research institutes for epitaxial growth technology transfer under K-Semiconductor Belt R&D tax credit programs. For Investors and Strategic Acquirers: Integrated device manufacturers with captive SiC substrate access are the most active acquirer in this space, seeking packaging specialists to complete vertical stacks. Five-to-ten year viability hinges on compound semiconductor process engineer pipeline development and domestic wafer fab equipment localization quotas. Monitor METI-aligned export control friction on Japanese deposition tools as inflection indicator for Korean fab equipment lead time compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Substrate Supply | Long-term wafer offtake agreements with Wolfspeed secure Hyundai-Kia platform feedstock against fabless rivals. |
| AEC-Q101 Certification Acceleration | Compressed qualification timelines capture automotive power module revenue before emerging entrants qualify. |
| Gwangju Region Capacity Expansion | Secondary packaging and test facilities exploit land cost arbitrage outside Seoul-Pyeongtaek corridor concentration. |
| K-Semiconductor Belt R&D Tax Credit Utilization | Subsidized pilot line capital expenditure reduces compound semiconductor startup barrier to entry. |
| Direct Foundry Relationship Establishment | Disintermediated die supply agreements with tier-one automotive suppliers compress distributor margins. |
Research Methodology
Bottom-up automotive and industrial end-use modeling reconciled against top-down SiC substrate and packaging capacity tracking forms the analytical core of this study. Primary interviews with traction inverter procurement managers at Hyundai-Kia, power module packaging engineers in Pyeongtaek, compound semiconductor process specialists at Daejeon research institutes, and industrial motor drive OEMs in Daegu combined with secondary validation from MFDS semiconductor-grade material standard filings, K-Semiconductor Belt infrastructure directive disclosures, METI export control notifications, and Korean customs trade data. Top-down and bottom-up triangulation reconciles supply-side capacity announcements against demand-side platform procurement schedules.
Input-output matrices map SiC wafer supply concentration against automotive inverter demand pull across product type, end user, technology, and packaging type segmentation dimensions. CAGRs derive from normalized growth rate convergence across the projection horizon. Industry-specific forecast inputs include K-Semiconductor Belt subsidy disbursement schedules and AEC-Q101 qualification pipeline visibility.
Inputs from Hyundai-Kia procurement disclosures and MFDS certification databases were available through the study window; gaps in Wolfspeed and II-VI wafer pricing transparency introduce uncertainty bands around substrate cost assumptions. Forecasts reflect documented assumptions about SiC substrate supply expansion and automotive electrification penetration rates. Practitioners should monitor METI deposition tool licensing delays and K-Semiconductor Belt domestic content verification enforcement for early signals of supply chain constraint severity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductors
Resistive RAM Market
Semiconductors
Semiconductor Target Market
Semiconductors
Europe Semiconductor Diode Market
Semiconductors
Global Computer Microchip Market
Semiconductors
China Semiconductor Market
Semiconductors
Wide Bandgap Semiconductors Market
Semiconductors
Digital Semiconductors Market
Semiconductors
Europe Discrete Semiconductor Market
Semiconductors
Semiconductor IP Market
Semiconductors
Organic Electronics Market
Semiconductors
Semiconductor Intellectual Property Market
Semiconductors
Analog Semiconductor Market
Semiconductors
Japan Discrete Semiconductors Market
Semiconductors
Global FD-SOI Wafers Market
Semiconductors
Semiconductor Market
Semiconductors
Global Organic Semiconductor Market