
 Global FD-SOI Wafers Market | 2026-2036
Global FD-SOI Wafers Market Size, Share, and Industry Trends Forecast 2026-2036
Global FD-SOI Wafers Market Analysis
The capital-intensity divergence between thin-film epitaxy specialists and volume wafer foundries is unwinding competitive stability across the FD-SOI supply base. Soitec leverages its proprietary Smart Cut technology to dominate 300mm engineered substrate supply for advanced nodes. GlobalFoundries anchors differentiated manufacturing by integrating FD-SOI into its 22FDX platform across multiple fabs. STMicroelectronics sustains dual-source flexibility by operating captive wafer qualification programs alongside merchant supply agreements.
FD-SOI wafers consist of a thin silicon layer over a buried oxide insulator, typically ranging from 7nm to 12nm in active silicon thickness, manufactured through layer-transfer bonding and precision grinding to enable sub-threshold voltage operation with reduced leakage current. Their primary purpose centers on delivering power-efficient logic for battery-dependent and thermally constrained devices. Twelve-inch wafers command the dominant revenue share given node migration toward larger diameters for automotive and telecom chips. Thin wafer variants represent the fastest-growing product category as backside illumination and 3D stacking architectures proliferate in smart sensor modules. Low-power processors generate the deepest margin pools among applications, particularly where edge AI inference demands sub-watt operation.
REACH substance restrictions from ECHA govern precursor chemicals in European wafer fabrication, while FDA oversight applies to FD-SOI components entering diagnostic and wearable medical devices in the United States. Japan's METI coordinates national semiconductor strategy through JIS standards alignment for substrate dimensional tolerances. China's NMPA and GB standards increasingly shape import qualification protocols for foreign-sourced wafers deployed in domestic telecom infrastructure. Stakeholders must monitor regulatory divergence on substrate traceability requirements as geopolitical fragmentation of semiconductor supply chains intensifies qualification burden.
Market Dynamics
Automotive electrification is compressing qualification cycles for power-efficient substrates as OEMs redesign inverter and battery management architectures around sub-threshold silicon operation.
Growth Catalysts
- EU REACH substance restrictions:Tightening purity mandates on precursor chemicals are accelerating substrate traceability investments across French and German supply chains.
- Edge AI inference modules:Sub-watt processor requirements in smart sensors are pulling thin-film FD-SOI into industrial automation and wearable health monitors.
- 12-inch wafer migration:Node advancement toward larger diameters is consolidating process equipment demand in automotive and telecom chip fabrication.
Market Restraints
- Epitaxial silicon input costs:Volatility in high-purity silane and disilane pricing squeezes margin structures for thin-film specialists without captive gas supply.
- Grenoble cluster concentration:Layer-transfer bonding capacity concentrates in a single French metropolitan region, exposing buyers to localized disruption risk.
- Bulk CMOS substitution:Mature-node planar silicon retains cost advantage in non-critical power applications below 28nm equivalent performance.
Strategic Opportunities
- Japan METI semiconductor strategy:National JIS alignment programs for substrate dimensional tolerances create qualification pathways for foreign wafer suppliers into Japanese automotive fabs.
- Backside illumination convergence:FD-SOI stacking with image sensor die is opening smart camera module sockets in autonomous vehicle perception systems.
- China NMPA import protocols:Evolving GB standards for telecom infrastructure wafers reward early compliance investment with preferential vendor status.
Industry Challenges
- Bond-and-etchback process engineering:The specialized skill pool for precision grinding and hydrogen implantation is thinning as veteran technicians exit without sufficient apprenticeship pipelines.
- Multi-regulatory qualification burden:Simultaneous FDA device clearance and ECHA substance registration stretches compliance timelines for medical-wafer product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global FD-SOI Wafers Market |
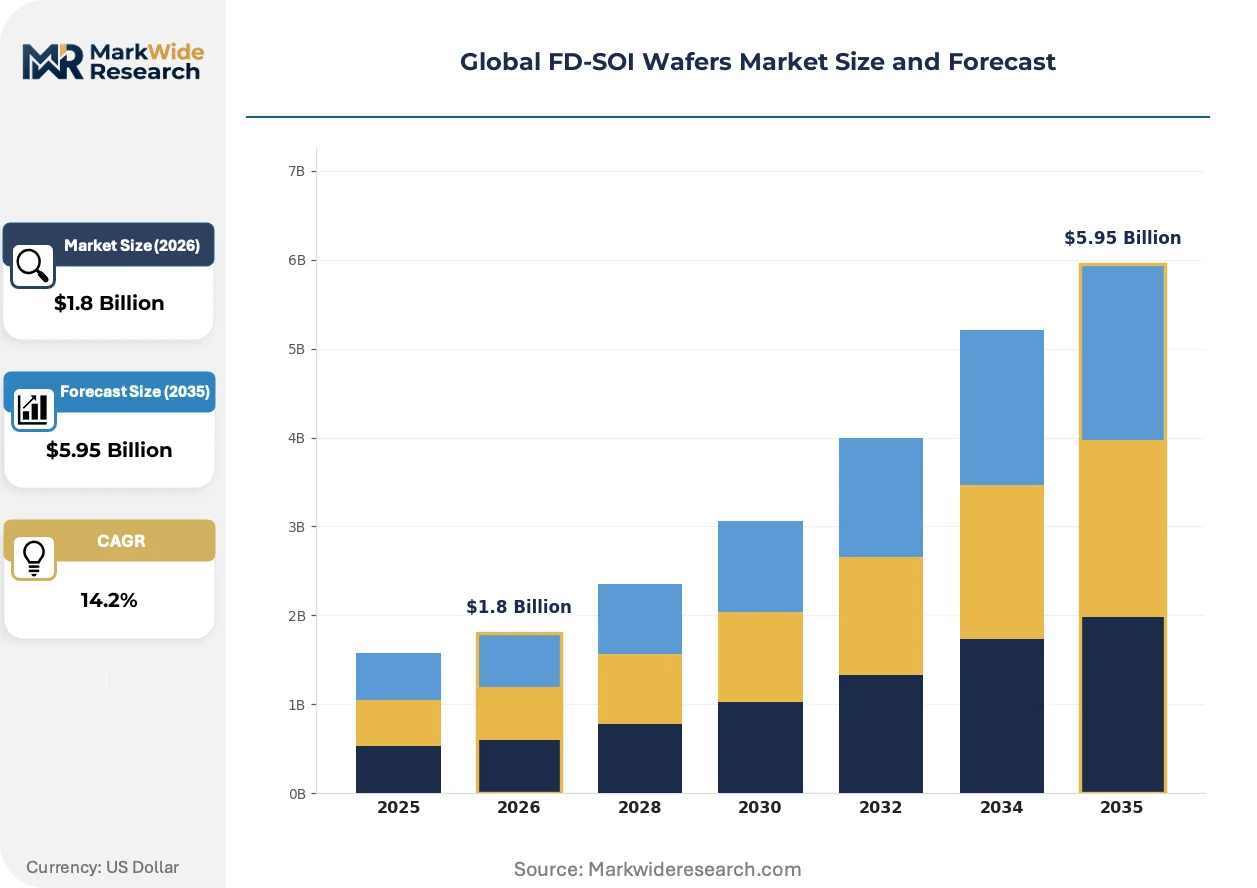
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 8-Inch, 12-Inch, Thin Wafer, Ultra-Thin Wafer Application: RFIDs, Smart Sensors, Low-Power Processors, Power Amplifiers End User: Consumer Electronics, Automotive Electronics, Telecommunications, Industrial Automation Delivery Mode: Direct Sales, Online Sales, Distributors, Resellers |
| Companies Covered | SUMCO Corporation, GlobalFoundries, Soitec, Shanghai Simgui Technology, Okmetic, Shin-Etsu Chemical, STMicroelectronics, NXP Semiconductors, GlobalWafers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global FD-SOI Wafers Market Emerging Trajectories
Wafer-level engineering is pivoting from planar scaling toward three-dimensional integration, with layer-transfer bonding and precision thinning displacing conventional epitaxy as the dominant cost-reduction pathway.
Ultrathin active silicon layers—approaching 7nm thickness—are displacing thicker epitaxial alternatives in battery-dependent edge devices. Automotive tier-one suppliers are qualifying these variants for electric vehicle subsystems requiring sub-milliwatt standby operation. This displacement is compressing the addressable market for bulk silicon-on-insulator alternatives above 20nm active thickness.
ECHA REACH candidate list expansion is tightening disclosure requirements for boron and phosphorus dopants in European wafer fabrication. Substrate suppliers must now document full chemical provenance back to mined quartz. Medical device wafer categories face the steepest compliance cost escalation as FDA 21 CFR Part 820 quality system overlap with EU MDR substance documentation.
Long-term supply agreements are supplanting spot-market wafer purchasing among automotive semiconductor divisions. Tier-one chipmakers are locking multi-year substrate volumes directly with engineered-wafer specialists, bypassing traditional distributor intermediaries. This concentration is most pronounced in German and French automotive supply chains where just-in-time inverter production demands buffer-stock elimination.
Global FD-SOI Wafers Market Segmentation
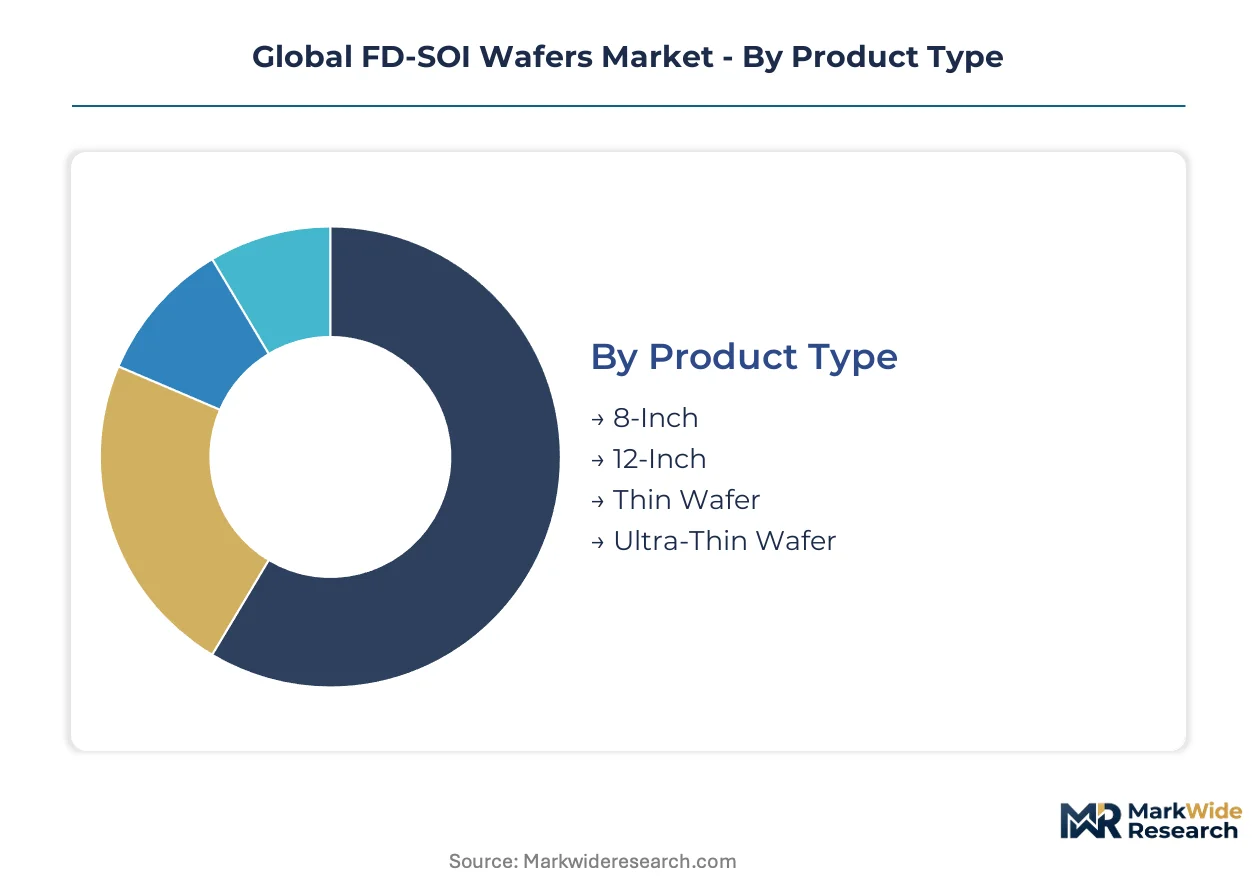
FD-SOI wafer demand fragments across diameter specifications, application power envelopes, and end-user qualification rigor. Margin capture varies sharply by substrate thickness and automotive certification status.
Product Type:
Twelve-inch wafers concentrate the deepest margin pools given node migration toward larger diameters for automotive and telecom chips. Thin wafer variants command premium pricing as backside illumination and 3D stacking architectures proliferate.
- 8-Inch:Mature-diameter substrates serve legacy RF and mixed-signal designs where foundry equipment amortization favors smaller formats. Demand concentrates in Japanese automotive fabs running established node portfolios.
- 12-Inch:Dominant-diameter engineered substrates enable 22nm and below FD-SOI nodes with full-field lithography economics. Automotive inverter and battery management chip qualification cycles are compressing around this format in German and French supply chains.
- Thin Wafer:Active silicon layers below 100 micrometers enable backside illumination integration and thermal stacking for smart sensor modules. Edge AI inference demand in industrial automation is pulling this category fastest.
- Ultra-Thin Wafer:Sub-50 micrometer substrates approaching 7nm active silicon thickness deliver sub-milliwatt standby operation for wearable health monitors.
Twelve-inch holds installed capacity. Thin wafer is rotating up the share rankings.
Application:
Power efficiency requirements stratify application value, with sub-watt edge inference commanding steepest substrate premiums. RF performance specifications create secondary margin tiers.
- RFIDs:Passive tag chips exploit FD-SOI's low leakage for extended read-range without battery power. Logistics and retail inventory tracking in China and the United States drive volume.
- Smart Sensors:Environmental and motion sensing modules integrate FD-SOI die with MEMS structures for battery-constrained IoT endpoints. Automotive cabin monitoring and industrial predictive maintenance are concentrating demand in Germany and Japan.
- Low-Power Processors:Sub-threshold voltage operation enables always-on voice recognition and image classification at milliwatt budgets. Edge AI inference in wearable health monitors generates the deepest margin pools.
- Power Amplifiers:RF front-end modules leverage FD-SOI's linearity and power-added efficiency for 5G sub-6GHz transmission. Smartphone and small-cell infrastructure procurement in South Korea and the United States shapes specifications.
Low-power processors anchor current revenue. Smart sensors are climbing the fastest.
End User:
Automotive qualification timelines stretch 18-24 months, concentrating procurement power among tier-one chipmakers with captive substrate agreements. Consumer electronics volumes run higher but with compressed margins.
- Consumer Electronics:Smartphone and wearable OEMs prioritize die-size efficiency and standby power reduction. Apple and Samsung supplier ecosystems in Taiwan and South Korea set thickness tolerances.
- Automotive Electronics:Electric vehicle inverter and battery management systems demand AEC-Q100 qualified substrates with full traceability documentation. German and French OEM direct sourcing agreements are bypassing traditional distribution.
- Telecommunications:5G baseband and RF transceiver chips require low-noise substrate performance for millimeter-wave operation. Infrastructure deployment in China and the United States drives diameter migration.
- Industrial Automation:Motor control and predictive maintenance modules combine FD-SOI logic with power discretes. Japanese and German factory automation OEMs specify extended temperature ranges.
Automotive electronics holds installed capacity. Industrial automation is rotating up the share rankings.
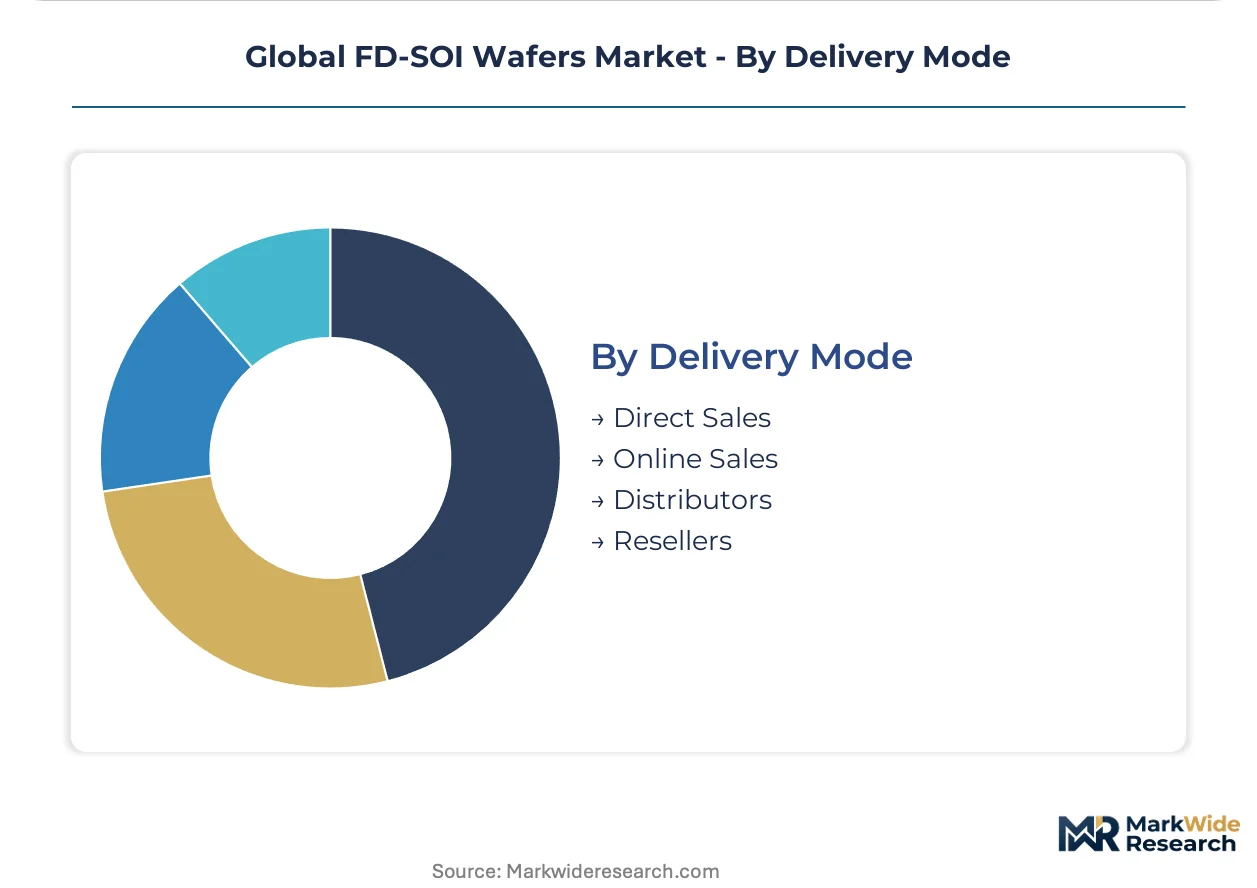
Delivery Mode:
Direct engagement with engineered-wafer specialists is displacing spot-market purchasing as automotive buffer-stock requirements tighten. Digital procurement channels remain underdeveloped for qualified substrate categories.
- Direct Sales:Multi-year volume agreements between Soitec and GlobalFoundries, STMicroelectronics, and tier-one IDMs lock capacity and eliminate intermediary margin. French and German automotive supply chains concentrate this mode.
- Online Sales:E-procurement platforms serve prototype and research-volume requirements with limited qualification documentation. University and startup access to thin-film samples runs through specialized distributors.
- Distributors:Arrow and Avnet maintain inventory positions for 8-inch legacy formats where qualification burden is lighter. Regional warehousing in Singapore and the Netherlands covers Asian and European demand.
- Resellers:Secondary market channels move excess inventory from canceled automotive programs with discounted traceability packages.
Direct sales holds installed capacity. Distributors are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in engineered substrates tilt heavily toward net-import dependence across major semiconductor-consuming economies, with only France and Japan maintaining structural wafer surpluses. Trade deficits concentrate in automotive and telecommunications sectors where domestic fabrication capacity lags substrate requirements.
France
Electric vehicle inverter demand from Renault and Stellantis pulls 300mm FD-SOI volumes through Soitec's captive agreements. ECHA REACH substance restrictions govern boron and phosphorus dopant documentation across Grenoble cluster fabrication sites. The Isère department anchors layer-transfer bonding capacity with hydrogen implantation facilities supplying GlobalFoundries and STMicroelectronics qualification programs.
Germany
Bosch and Infineon battery management chip designs compress substrate qualification cycles toward 18-month automotive timelines. KBA type-approval processes for electric powertrains extend traceability requirements to mined quartz provenance. Dresden's Saxony cluster concentrates back-end thinning operations for 12-inch wafers destined for Bavarian automotive fabs.
United States
FDA 21 CFR Part 820 quality system overlap with EU MDR documentation stretches medical-wafer compliance timelines for wearable diagnostic devices. EPA precursor chemical oversight applies to silane and disilane imports for thin-film epitaxy operations. Arizona's Phoenix metro hosts GlobalFoundries 22FDX fabrication with direct substrate offtake from French engineered-wafer specialists.
Japan
METI semiconductor strategy coordinates JIS standards alignment for substrate dimensional tolerances in Toyota and Honda supplier ecosystems. Sub-threshold voltage operation requirements in industrial automation modules pull ultrathin wafer categories. Kyushu's Kumamoto prefecture hosts back-end processing facilities serving Renesas mixed-signal qualification programs.
China
NMPA GB standards for telecom infrastructure wafers impose import qualification protocols on foreign-sourced substrates deployed in 5G baseband chips. MIIT domestic semiconductor targets accelerate local 300mm SOI pilot lines in Shanghai and Beijing. Yangtze River Delta packaging houses concentrate 3D stacking integration for smart sensor modules using thinned die.
Global FD-SOI Wafers Market Vendor Landscape
Concentration sits with engineered-substrate specialists possessing proprietary layer-transfer intellectual property. Three archetypes populate the supply base: thin-film epitaxy houses controlling hydrogen implantation and precision grinding, foundry-integrated merchants securing captive volume agreements, and diversified chemical conglomerates with backward integration into high-purity silane production. Competitive moves center on multi-year direct sales contracts eliminating distributor intermediaries, and geographic diversification of bonding capacity to reduce Grenoble cluster exposure.
Among substrate specialists, Soitec and GlobalFoundries exemplify the foundry-integrated archetype through technology licensing and volume commitment structures. Shin-Etsu Chemical occupies a position representing chemical conglomerate backward integration into precursor supply. These three anchors demonstrate how competitive positioning stratifies between proprietary bonding technology holders, captive demand aggregators, and upstream material integrators.
| Leading Market Players |
|---|
| SUMCO Corporation |
| GlobalFoundries |
| Soitec |
| Shanghai Simgui Technology |
| Okmetic |
| Shin-Etsu Chemical |
| STMicroelectronics |
| NXP Semiconductors |
| GlobalWafers |
| Others |
Supply Flow & Price Mechanics
ECHA REACH substance restrictions gate both substrate qualification and price differentiation simultaneously, forcing buyers to absorb compliance premiums for full dopant traceability while suppliers tier offerings by documentation depth. Automotive OEMs purchasing AEC-Q100 certified wafers face steeper pricing than consumer electronics buyers accepting lighter qualification packages, yet both segments confront cost compression as high-purity silane supply tightens.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure, with German and French automotive chipmakers locking multi-year volumes directly with engineered-wafer specialists. Price differentiation hinges on certification grade—AEC-Q100 automotive qualification commands substantial premiums over industrial-grade alternatives—and volume scale, where tier-one IDMs extract favorable terms through captive agreements. Cost compression in thin-film epitaxy tiers is intensifying because high-purity silane and disilane input volatility squeezes margin structures. Consumer electronics buyers exhibit highest price sensitivity, prioritizing die-size efficiency over substrate provenance, while medical device OEMs accepting FDA-EU MDR dual documentation show lowest sensitivity.
Supply Chain Analysis
France and Japan anchor wafer fabrication through Soitec's Grenoble cluster and Shin-Etsu's Kumamoto facilities, with the United States hosting back-end processing at GlobalFoundries' Arizona fab. Raw material dependencies draw from high-purity quartz mining, silane gas production, and hydrogen implantation equipment manufacturing. Single-source vulnerability concentrates in layer-transfer bonding capacity, where Grenoble's metropolitan region houses irreplaceable Smart Cut technology infrastructure. Distribution runs through direct sales agreements eliminating intermediary margin, with spot-market channels serving only prototype and research volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as edge AI inference demand splinters substrate requirements across power envelopes and thickness specifications, creating specialized niches beyond incumbent scale advantages. Automotive electrification compressing qualification cycles rewards agile specialists over volume generalists.
For Market Incumbents: Consolidate through backward integration into high-purity silane production to escape precursor cost volatility, and expand bonding capacity outside Grenoble to mitigate geographic concentration risk. Bulk CMOS substitution at mature nodes threatens margin pools in non-critical power applications, making captive gas supply and regional capacity diversification essential defensive levers.
For New Entrants and Emerging Players: Differentiate on ultrathin wafer categories below 50 micrometers, where edge AI inference demand outpaces incumbent capacity allocation. Industrial automation in Japan and Germany represents the most penetrable geography, with sub-threshold voltage specifications still fluid. A qualification-fast go-to-market angle—compressing AEC-Q100 timelines through pre-certified process templates—unlocks automotive sockets.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with dormant substrate bonding assets and stranded hydrogen implantation capacity. Long-term viability centers on structural supply deficit for 300mm engineered substrates through the mid-2030s as automotive and telecom demand compounds. Watch for ECHA REACH candidate list expansion signals as inflection indicators, as each dopant disclosure requirement reshapes competitive cost structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Locks multi-year wafer volumes between Soitec and GlobalFoundries, eliminating spot-market exposure. |
| Backward Integration | Captures high-purity silane production to insulate margin from precursor chemical volatility. |
| Geographic Capacity Expansion | Reduces Grenoble cluster concentration risk by replicating layer-transfer bonding outside France. |
| Certification Investment | Accelerates AEC-Q100 and FDA-EU MDR dual qualification to capture medical-wafer premium tiers. |
| Platform Integration | Bonds FD-SOI die with image sensor modules for autonomous vehicle perception systems. |
Methodological Framework
Operator-level perspectives from wafer fabrication engineers, automotive semiconductor procurement leads, thin-film epitaxy specialists, and regulatory compliance officers anchored the qualitative base. Primary interviews combined with secondary validation from ECHA REACH filings, METI JIS standard documentation, FDA 21 CFR Part 820 quality system records, and SEC disclosures from publicly traded substrate suppliers. Bottom-up and top-down triangulation cross-checked capacity utilization assumptions against import-export trade flows and foundry capex announcements.
Sensitivity analysis framed volume and value outputs across the analysis window, modeling segmentation dimensions including wafer diameter, active silicon thickness, application power envelope, end-user qualification rigor, and regional regulatory cluster. CAGRs derived from trend extrapolation of automotive inverter adoption curves, edge AI module deployment rates, and telecom infrastructure buildout schedules. Forecast inputs incorporated silane pricing volatility bands and layer-transfer bonding capacity expansion timelines.
Forecasts assume regulatory continuity in ECHA REACH, FDA 21 CFR Part 820, and METI JIS alignment programs; material policy shifts would require re-modeling. Specific risks include REACH candidate list expansion accelerating compliance cost escalation, and geopolitical fragmentation of semiconductor supply chains intensifying qualification burden. Recalibration cycles align with material shifts in automotive electrification adoption, edge AI inference deployment, and precursor chemical supply dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductors
Europe Discrete Semiconductor Market
Semiconductors
Semiconductor Target Market
Semiconductors
Global Copper Indium Gallium Selenide (CIGS) Solar Cells Market
Semiconductors
Global Organic Semiconductor Market
Semiconductors
Asia Pacific Flash Memory Market
Semiconductors
Digital Semiconductors Market
Semiconductors
Analog Semiconductor Market
Semiconductors
Semiconductor Market
Semiconductors
Semiconductor in Military and Aerospace Market
Semiconductors
Global Computer Microchip Market
Semiconductors
Europe Semiconductor Diode Market
Semiconductors
Asia-Pacific Semiconductor Market
Semiconductors
Organic Electronics Market
Semiconductors
North America Semiconductor Market
Semiconductors
Germanium Semiconductor Market
Semiconductors
China Semiconductor Market