
 High Bay Lighting Market | 2026-2036
High Bay Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
High Bay Lighting Market Intelligence
A shift toward multi-source procurement for integrated controls is decoupling the luminaire purchase from the software and sensor ecosystem. This allows facility managers to mix and match best-in-class components. Signify N.V. leverages its extensive portfolio to offer complete, networked lighting systems. Eaton Corporation competes on industrial-grade durability and integration with complex building management platforms, while Acuity Brands positions itself with a broad range of smart lighting and control solutions.
High bay lighting encompasses luminaires engineered for spaces with ceiling heights over 20 feet, often requiring outputs exceeding 15,000 lumens. These fixtures are essential for ensuring safe and productive conditions in large-volume environments like warehouses and manufacturing facilities. The transition from legacy sources like metal halide to LED products represents the dominant product-level shift. Within applications, warehouses and manufacturing facilities constitute the largest segments, while wireless controls and daylight harvesting technologies represent the fastest-growing technology additions.
Regulatory frameworks like the EU's Ecodesign Directive and the DesignLights Consortium (DLC) standards in the United States mandate stringent energy efficiency and performance benchmarks, effectively barring older technologies from the market. In China, national GB standards for industrial lighting enforce specific safety and quality levels, which influences market access. The key decision for suppliers now involves balancing hardware performance with the development of software-based lighting-as-a-service models.
Market Dynamics
The central force shaping the market is the regulatory-driven obsolescence of legacy lighting technologies. Mandates like the EU's Ecodesign Directive and performance benchmarks from the DesignLights Consortium in the United States are accelerating the compulsory switch to energy-efficient LED systems.
Growth Catalysts
- E-Commerce Logistics Expansion:The build-out of massive fulfillment and distribution centers, particularly in North America and China, creates sustained, large-scale demand for new high bay installations to ensure operational safety and productivity.
- Government Efficiency Mandates:Policies such as the EU's Ecodesign for Sustainable Products Regulation compel facility owners to retrofit older, inefficient metal halide and fluorescent systems, directly stimulating replacement sales cycles.
- Wireless Control Integration:The adoption of IoT-enabled wireless controls and sensors allows for advanced energy management strategies like daylight harvesting and occupancy sensing, adding significant value beyond basic illumination and justifying upgrade investments.
Market Restraints
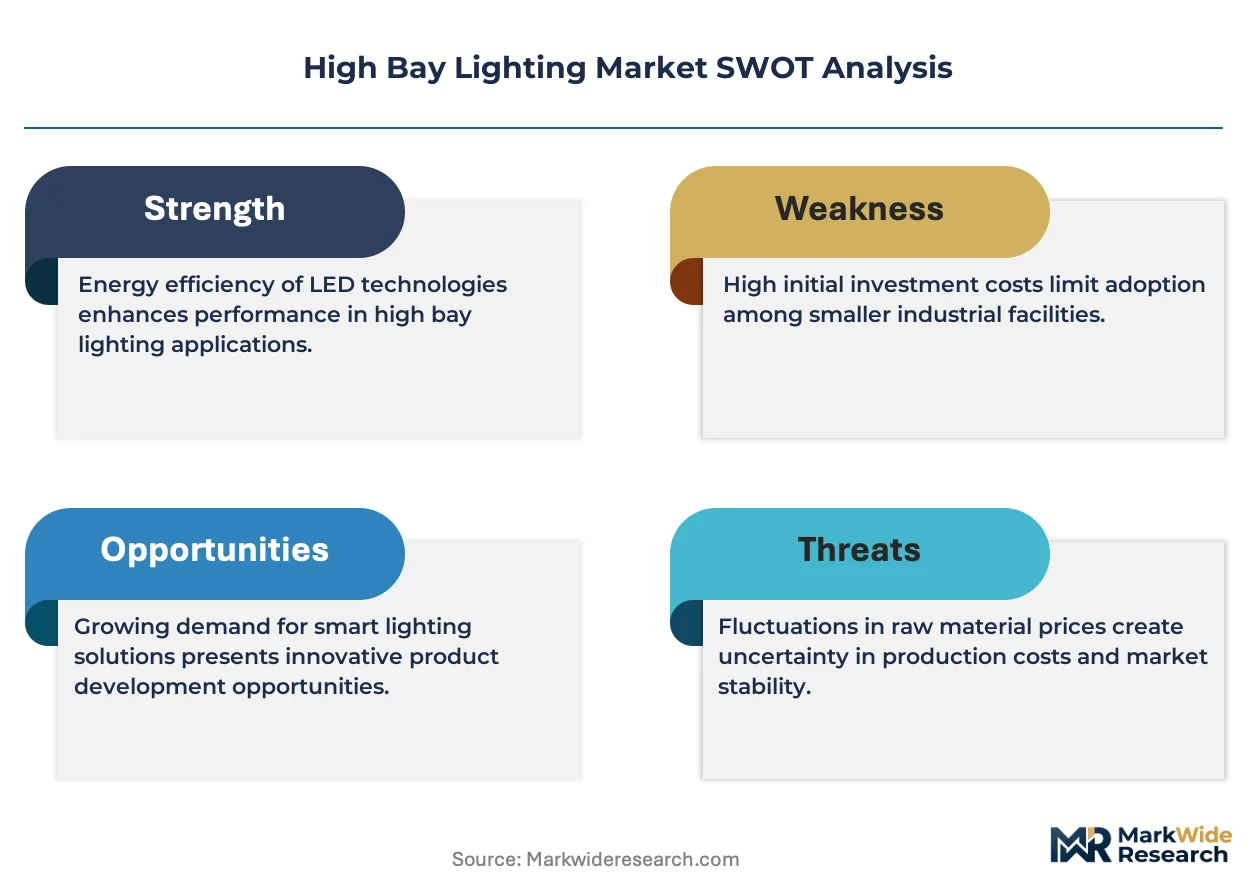
- High Initial Capital Outlay:The upfront cost of advanced LED high bay systems, especially those with integrated smart controls and sensors, remains a significant barrier for small and medium-sized enterprises with limited capital budgets.
- Supply Chain Concentration:A heavy reliance on East Asian countries for critical components like LED chips and drivers exposes the market to geopolitical risks, trade policy fluctuations, and potential supply chain disruptions.
- Integration Complexity:Ensuring seamless interoperability between luminaires, sensors, and control software from different vendors can be technically challenging, often requiring specialized expertise that many facility management teams lack.
Strategic Opportunities
- Lighting-as-a-Service (LaaS) Models:Offering subscription-based models that bundle hardware, software, and maintenance into a single operational expense can bypass customer capex hurdles and create long-term, recurring revenue streams for suppliers.
- Specialized Application Development:There is an opportunity to engineer and certify high-performance luminaires for niche, high-value applications such as food processing facilities, hazardous locations, and extreme temperature cold storage warehouses.
- Emerging Market Industrialization:Rapid industrial growth in regions like Southeast Asia and Latin America presents a significant greenfield opportunity for high bay lighting as new manufacturing plants and warehouses are constructed.
Industry Challenges
- System Interoperability:The absence of a single, universally adopted communication standard for networked lighting controls creates fragmentation, leading to vendor lock-in concerns and complicating integration with broader building management systems.
- Navigating Certification Pathways:The process of securing and maintaining compliance with multiple, evolving regional standards like DLC in the US and GB standards in China is costly and time-consuming for manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Bay Lighting Market |
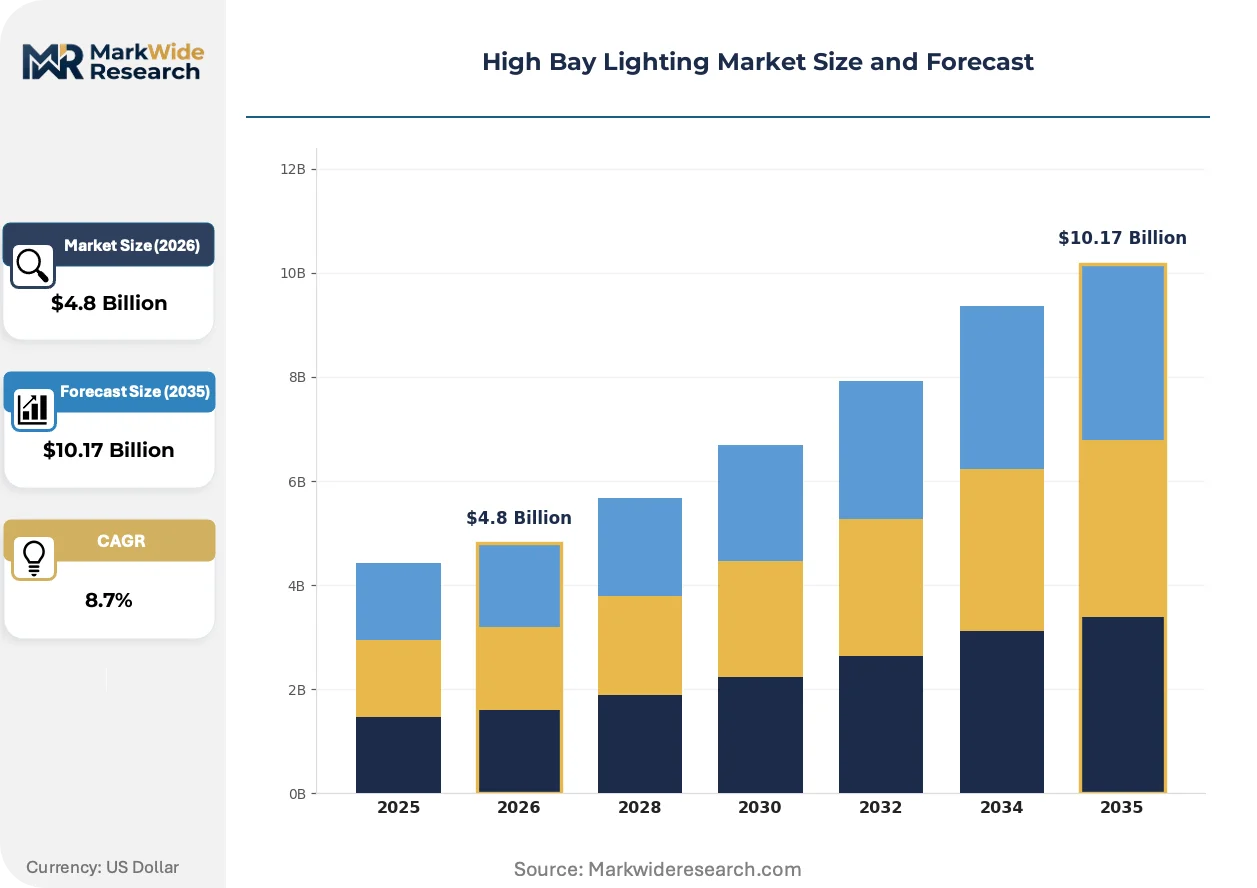
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Metal Halide, Fluorescent, High-Pressure Sodium, Induction Technology: Wireless Controls, Photocell Sensors, Motion Detectors, Dimming Systems, Daylight Harvesting Application: Warehouses, Manufacturing Facilities, Sports Complexes, Convention Centers, Aircraft Hangars End User: Logistics Providers, Industrial Plants, Educational Institutes, Government Buildings, Event Venues |
| Companies Covered | Signify N.V., Acuity Brands, ams OSRAM AG, Eaton Corporation, Cree Lighting, Hubbell Lighting, LEDVANCE, Dialight, Panasonic Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Bay Lighting Market Strategic Shifts & Innovations
A fundamental shift is underway, transforming high bay lighting from a static hardware asset into a dynamic, data-generating infrastructure. This evolution is driven by the convergence of efficient solid-state lighting with networked intelligence, creating new value propositions for industrial facility operators.
Integrated sensors and controls are a defining product evolution. These components, embedded directly within the luminaire, provide capabilities for occupancy detection, daylight harvesting, and environmental monitoring. Large-scale logistics and manufacturing operators are the primary adopters, seeking granular control over energy consumption. The luminaire itself is absorbing functions previously managed by disparate building automation systems, simplifying deployment and unlocking facility-level data analytics.
Regulatory frameworks are increasingly focused on system-level performance, not just fixture efficiency. The DesignLights Consortium (DLC) in the United States, for instance, has established stringent technical requirements for Networked Lighting Controls (NLC) that include cybersecurity and energy monitoring. This forces manufacturers to validate the performance of their entire system to qualify for utility rebates. Consequently, products targeting the North American market must now demonstrate sophisticated control capabilities.
A move toward multi-source procurement for integrated systems is altering purchasing behavior. Facility managers are increasingly unbundling the hardware purchase from the control software and sensor ecosystem, allowing them to select best-in-class components from multiple vendors. This trend of component unbundling is most visible within sophisticated logistics and manufacturing operations across Europe and North America, where system flexibility and avoiding proprietary lock-in are paramount.
High Bay Lighting Market Segmentation
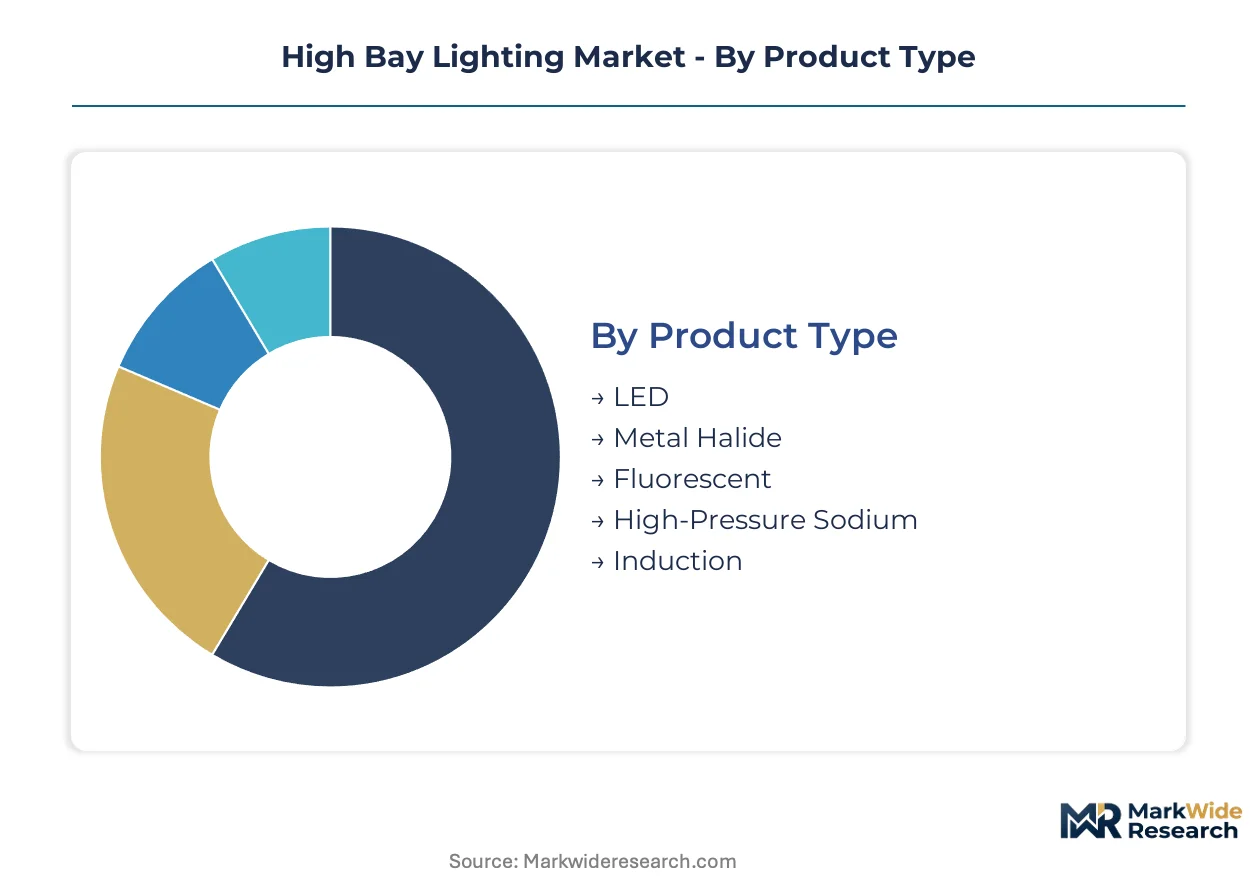
The High Bay Lighting Market's segmentation provides a detailed view of product evolution, technological integration, and diverse end-use applications. This granular breakdown helps identify specific demand drivers and strategic opportunities across various industry verticals. Understanding these distinctions is crucial for suppliers to tailor product development and market penetration strategies effectively.
Product Type:
The High Bay Lighting Market's product segmentation highlights the ongoing transition from older, less efficient technologies to modern solutions, driven by energy mandates and performance demands.
- LED:These solid-state lighting fixtures offer superior energy efficiency, extended operational lifespan, and precise light control. Demand concentrates in new warehouse builds and retrofit projects across North America, driven by energy efficiency incentives and DLC standards.
- Metal Halide:Traditional high-intensity discharge lamps provide strong light output but consume significantly more energy and have shorter lifespans than LEDs. Many facilities in Europe are actively replacing these legacy systems due to the EU's Ecodesign Directive.
- Fluorescent:Linear fluorescent lamps, particularly T5 and T8, offer moderate efficiency but are being phased out in many industrial settings due to lower lumen output and mercury content.
- High-Pressure Sodium:Known for their long life and yellow-orange light, these lamps are primarily found in older industrial and outdoor applications where color rendering is not critical.
- Induction:These lamps offer long life and good color rendering, but their higher initial cost and specialized ballast requirements limit widespread adoption compared to LEDs.
LED sits at the top of the volume ranking, with Induction representing the fastest-growing trajectory.
Technology:
Technology segmentation reveals how advanced control systems are enhancing the functionality and efficiency of high bay installations, moving beyond basic illumination to integrated intelligence.
- Wireless Controls:These systems enable remote management and automation of lighting fixtures, using protocols like Zigbee or Bluetooth Mesh. Large logistics hubs in China are adopting wireless controls for centralized energy management and operational flexibility.
- Daylight Harvesting:Sensors detect ambient natural light levels and automatically adjust artificial lighting output to maintain desired illumination, optimizing energy use. This technology sees strong uptake in facilities with skylights or large windows across Western Europe.
- Photocell Sensors:These devices detect ambient light and switch luminaires on or off based on preset thresholds, primarily for outdoor or perimeter high bay applications.
- Motion Detectors:Occupancy and vacancy sensors automatically turn lights on when movement is detected and off after a period of inactivity, reducing energy waste in intermittently used areas.
- Dimming Systems:These allow for adjustable light output, providing flexibility to match lighting levels to specific tasks or times of day, enhancing visual comfort and energy savings.
Wireless Controls gain significant traction, while Daylight Harvesting demonstrates strong adoption in new constructions.
Application:
Application analysis delineates the diverse environments where high bay lighting is critical for operational safety and productivity, each with unique performance requirements.
- Warehouses:These large-volume storage facilities require uniform, high-lumen illumination to ensure safe navigation, inventory management, and operational efficiency. E-commerce expansion in the United States drives continuous demand for new installations and upgrades.
- Manufacturing Facilities:Production environments demand robust, high-output lighting that can withstand harsh conditions and provide adequate visibility for intricate tasks and machinery operation. German automotive plants prioritize durable, high-CRI high bay systems for quality control.
- Sports Complexes:High bay lighting in these venues must provide broad, even illumination for athletic performance and spectator visibility, often requiring specialized optics to minimize glare.
- Convention Centers:Large exhibition halls and event spaces utilize high bay systems for adaptable lighting that can accommodate various events, often integrating with sophisticated control systems.
- Aircraft Hangars:These expansive structures need powerful, uniform lighting for aircraft maintenance and inspection, often requiring fixtures resistant to dust and vibration.
Warehouses dominate the application landscape, with Manufacturing Facilities maintaining consistent, large-scale demand.
End User:
End-user segments illustrate the varied institutional and commercial entities driving demand for specialized high bay lighting solutions, each with distinct procurement priorities.
- Logistics Providers:Companies managing vast distribution and fulfillment centers require efficient, smart high bay lighting to support 24/7 operations and reduce energy costs. Amazon and other e-commerce giants are key drivers of this segment's growth in North America.
- Industrial Plants:Heavy and light manufacturing operations depend on durable, high-performance high bay lighting for worker safety, productivity, and adherence to regulatory standards. Factories in India are investing in LED high bays to meet national energy efficiency goals.
- Educational Institutes:University gymnasiums, auditoriums, and vocational training centers use high bay lighting, balancing energy efficiency with visual comfort for occupants.
- Government Buildings:Public works facilities, maintenance depots, and large municipal storage areas require reliable and energy-compliant high bay lighting solutions.
- Event Venues:Arenas, exhibition halls, and concert venues utilize high bay lighting for general illumination, often integrated with dynamic lighting systems for various events.
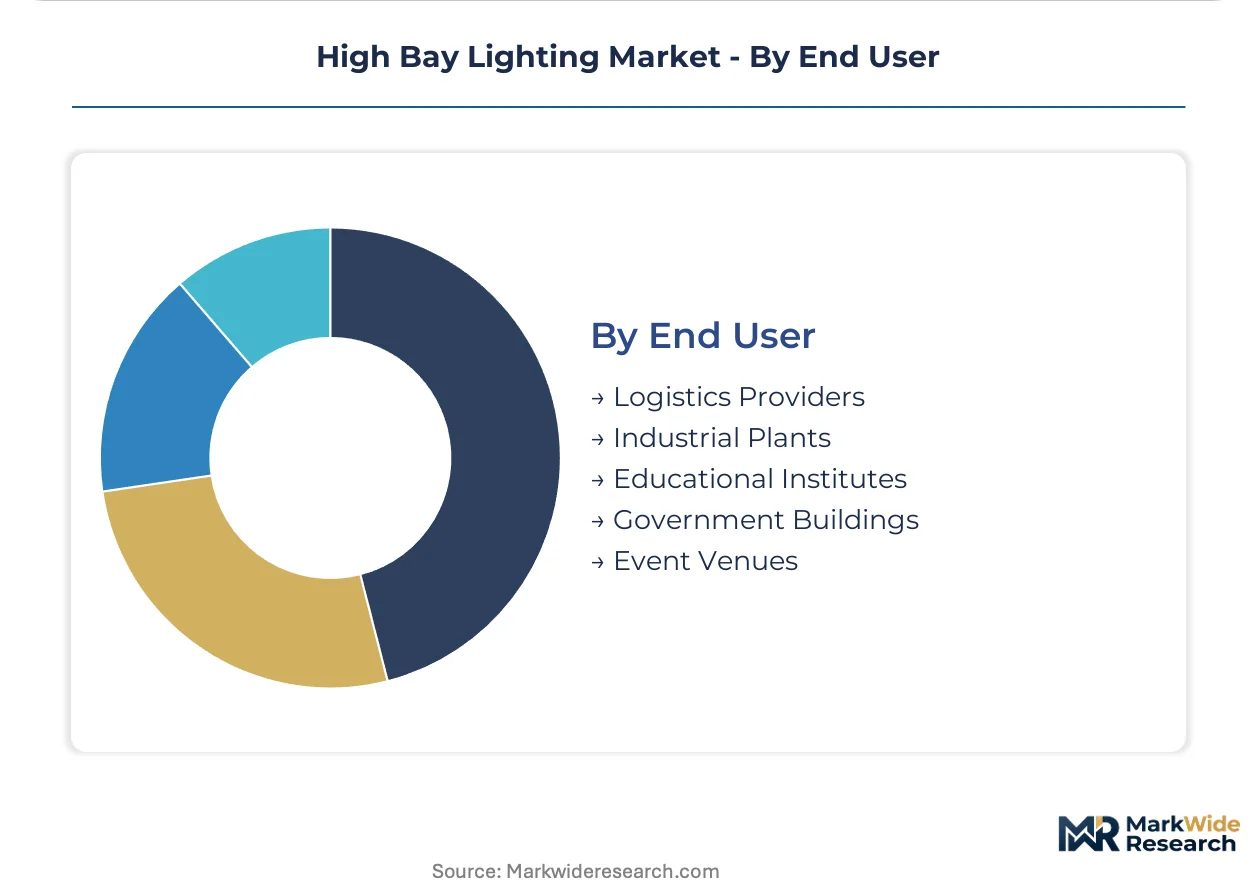
Logistics Providers are the largest end-user segment, while Industrial Plants exhibit a steady procurement cycle.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's expansive manufacturing and logistics hubs drive significant demand for high bay lighting. The global market benefits from ongoing infrastructure development and stringent energy efficiency mandates. Facilities worldwide are upgrading to advanced LED systems to enhance operational safety and reduce energy consumption.
China
Demand for high bay lighting stems from its vast manufacturing and logistics sectors. National GB standards for industrial lighting enforce specific safety and quality levels. Large logistics hubs across the Yangtze River Delta are rapidly adopting wireless controls for energy management.
United States
E-commerce logistics expansion fuels continuous demand for new high bay installations and upgrades. The DesignLights Consortium (DLC) standards mandate stringent energy efficiency benchmarks for systems. Massive fulfillment centers in states like California and Texas require uniform, high-lumen illumination.
Germany
Manufacturing facilities, especially in the automotive sector, require robust high-output lighting. The EU's Ecodesign Directive compels facilities to retrofit older, less efficient systems. German automotive plants in Bavaria prioritize durable, high-CRI high bay systems for quality control.
India
Industrial plants are investing in advanced LED high bays to meet national energy efficiency goals. Government policies support the transition to more sustainable lighting solutions across industrial sectors. Factories in Maharashtra are upgrading to enhance worker safety and productivity.
Japan
The manufacturing sector drives consistent demand for reliable high bay lighting solutions. JIS standards ensure specific quality and performance levels for industrial fixtures. Automated warehouses in the Kanto region are integrating smart lighting systems for operational efficiency.
High Bay Lighting Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue integrated software and service models. The high bay lighting market exhibits a tiered structure, with a mix of large diversified conglomerates and specialized lighting manufacturers. Strategic archetypes include hardware-focused suppliers emphasizing industrial-grade durability, smart control system integrators offering advanced energy management, and service-centric providers bundling hardware and software. Dominant competitive moves involve portfolio diversification into control solutions and strategic partnerships for software development.
On the premium-tier vector, Signify N.V. exemplifies companies leveraging extensive portfolios to offer complete, networked lighting systems across various industrial applications. Acuity Brands occupies a position among those providing a broad range of smart lighting and control solutions, emphasizing advanced functionality and user experience. Eaton Corporation represents suppliers competing on industrial-grade durability and seamless integration with complex building management platforms, catering to demanding industrial environments. These entities anchor the market through comprehensive offerings, established distribution channels, and continuous innovation in control technologies, influencing overall market direction.
| Leading Market Players |
|---|
| Signify N.V. |
| Acuity Brands |
| ams OSRAM AG |
| Eaton Corporation |
| Cree Lighting |
| Hubbell Lighting |
| LEDVANCE |
| Dialight |
| Panasonic Holdings |
Cost & Logistics Intelligence
LED chip pricing, a key commodity benchmark, drives initial hardware costs, which then cascade through various product tiers in the high bay lighting market, influencing final system pricing.
Pricing Analysis
Input-cost pass-through influences high bay lighting pricing across all tiers. Pricing stratifies across performance tiers, with advanced networked lighting controls commanding higher premiums. Price differentiation stems from certification levels like DLC standards, integrated smart features, and after-sales service bundles. Pricing softness reflects component commoditization in basic LED fixtures, particularly for standard products. Small and medium-sized enterprises (SMEs) exhibit the highest price sensitivity due to upfront capital outlay constraints, while large logistics providers prioritize long-term operational savings.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke patterns characterize the high bay lighting supply chain. Geographic supply concentration centers on East Asian countries like China for critical components such as LED chips and drivers. The market relies heavily on optical components and control modules sourced from a concentrated global base. Geopolitical risks and trade policy fluctuations represent a structural supply chain risk. Distribution runs through a mix of direct sales to large industrial clients and extensive networks of electrical distributors and system integrators for broader market reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The High Bay Lighting Market presents a compelling margin-expansion story, driven by the premium-tier shift towards integrated smart lighting systems and Lighting-as-a-Service (LaaS) models.
For Market Incumbents: Hedge against commoditization by deepening vertical integration into control software development. Diversify portfolios to offer complete, networked lighting systems that leverage existing customer relationships. Invest in R&D for AI-driven analytics to enhance system value beyond basic illumination. Secure critical component supply chains to mitigate geopolitical risks and ensure production stability against emerging entrants.
For New Entrants and Emerging Players: Enter via specialized application development, targeting niche high-value environments such as cold storage or hazardous locations. Focus on a software-first approach, offering Lighting-as-a-Service models to overcome customer capex hurdles. The most penetrable segment involves small and medium-sized enterprises seeking energy efficiency without significant upfront investment. Prioritize value-added services like predictive maintenance and energy performance guarantees.
For Investors and Strategic Acquirers: Consolidation pressure builds where market fragmentation hinders scale efficiencies and R&D investment. Long-term viability rests on the sustained demand from industrial modernization and energy efficiency mandates across a 5-10 year window. Target acquisition archetypes include specialized software firms with expertise in IoT lighting controls or regional system integrators with strong customer bases. The adoption rate of open communication standards for lighting controls serves as a key inflection indicator to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification into Control Solutions | Expands revenue streams and locks in customers with advanced energy management capabilities. |
| Strategic Partnerships for Software Development | Accelerates innovation in smart lighting platforms and reduces time-to-market for new features. |
| Green Manufacturing Transition | Enhances brand reputation and meets evolving regulatory demands for sustainable production practices. |
| Direct-to-Consumer LaaS Model Launch | Bypasses traditional distribution channels and captures recurring revenue from operational expenses. |
| Geographic Expansion into Emerging Markets | Taps into greenfield opportunities from new industrialization in Southeast Asia and Latin America. |
Research Approach
Bottom-up application modeling reconciled against top-down supplier tracking forms the analytical core for this high bay lighting market study. Primary interviews with facility managers, procurement officers, lighting engineers, and system integrators provided qualitative insights. Secondary validation drew from regulatory filings such as DLC standards, industry association reports, and patent databases to ensure data integrity.
An input-output matrix frames the forecast framework, projecting market evolution across various dimensions. Key segmentation dimensions modeled include product type, technology, application, end-user, and geographic region, alongside control system sophistication. Compound Annual Growth Rates (CAGRs) were derived from historical trends, projected technology adoption rates, and regulatory impact assessments across the modeling period. E-commerce logistics expansion rates and industrial manufacturing output served as critical forecast inputs.
Inputs from industry reports and regulatory databases were available through the study window; gaps in emerging technology adoption rates introduce uncertainty bands. Forecasts reflect assumptions regarding economic stability and geopolitical conditions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Connected Lighting Platform Market
Lighting
Indicator Lights Market
Lighting
Lighting Fixture Market
Lighting
Eye-Illuminating Gadgets Market
Lighting
Lighting As a Service (Laas) Market
Lighting
Explosion Proof Lighting Market
Lighting
Smart Lighting Market
Lighting
Circadian Lighting Market
Lighting
Lighting Market
Lighting
Ultraviolet Lamps Market
Lighting
Global Lamps Market
Lighting
India Lighting Market
Lighting
Tritium Light Source Market
Lighting
Softbox Lighting Kit Market
Lighting
Solid-State Lighting Source Market
Lighting
Solar Spotlights Market